

Balance Sheet Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Balance Sheet Management Software Market Insights
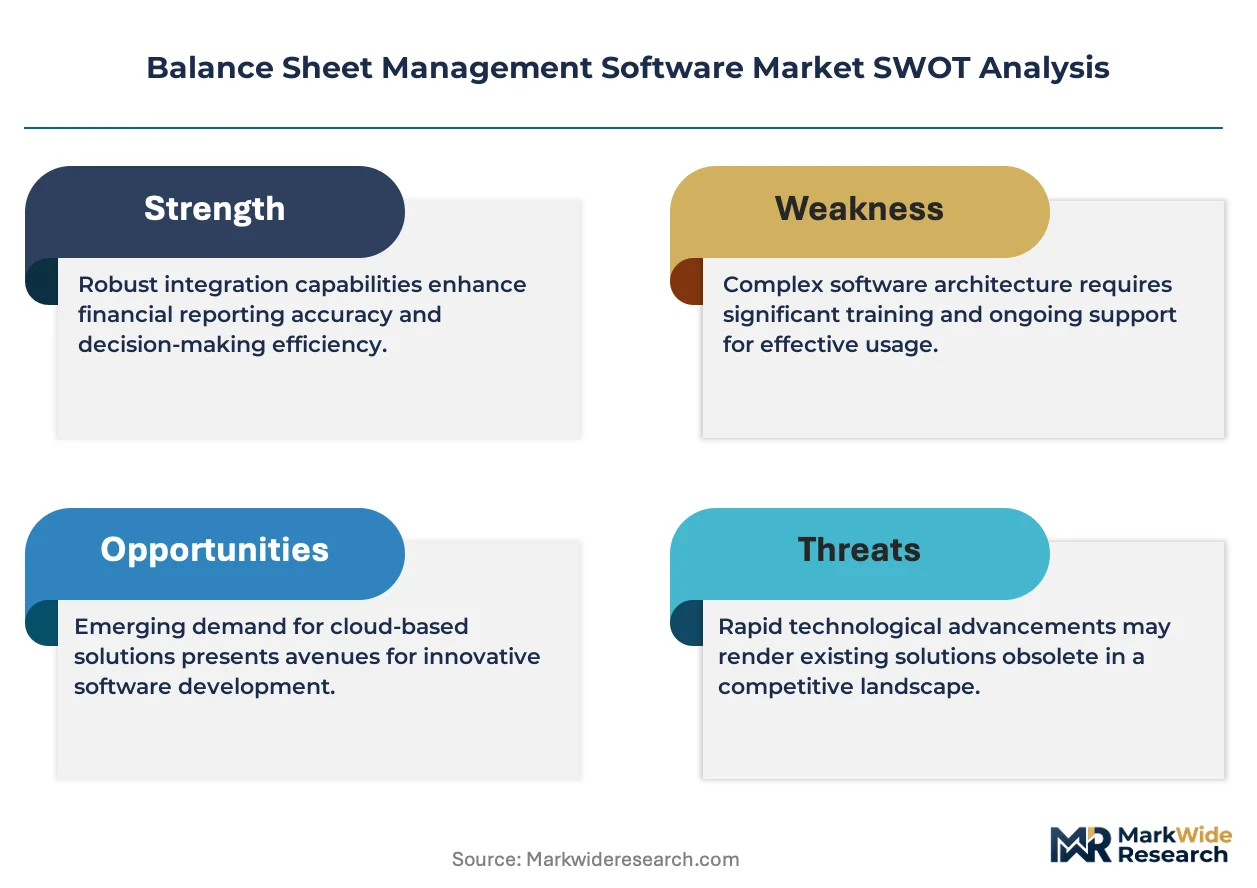
Enterprise-grade automation is redrawing competitive boundaries in balance sheet management software. Oracle leverages its database heritage to anchor large-bank implementations across complex asset-liability portfolios. SAP competes through deep ERP integration that sustains cross-functional data flows between treasury and accounting systems. Moody’s differentiates via embedded risk analytics that positions its platform for institutions prioritizing credit-sensitive balance sheet oversight.
Balance sheet management software comprises integrated systems for financial data aggregation, ratio calculation, scenario modeling, and regulatory reporting across institutional asset and liability positions. These platforms typically process real-time general ledger feeds, apply GAAP or IFRS accounting rules, and generate standardized disclosures for supervisory review. Cloud-based deployment leads solution uptake as banks retire legacy on-premises infrastructure, while regulatory compliance modules command premium pricing due to mandatory reporting obligations. The subscription-based pricing model now dominates new customer acquisition, displacing perpetual licenses among mid-tier institutions seeking operational flexibility.
US banking regulators including the Federal Reserve and OCC mandate granular liquidity coverage ratio disclosures that shape software procurement timelines. The European Banking Authority’s CRD VI implementation timeline and EBA stress test templates create parallel compliance-driven demand across EU member states. Stakeholders must weigh vendor roadmaps for generative AI integration against the operational risk of entrusting automated narrative generation to systems still awaiting supervisory guidance.

Market Dynamics
Cloud-native architecture is compressing deployment cycles for balance sheet management platforms, forcing incumbent vendors to rearchitect legacy codebases while challenger firms exploit API-first modularity to capture mid-tier bank contracts.
Growth Catalysts
- Basel III Endgame Implementation:US Federal Reserve liquidity coverage ratio mandates compel tier-one banks to replace spreadsheet-based reporting with automated compliance engines. Procurement timelines compress as supervisory deadlines approach.
- Real-time Payment Infrastructure:Instant settlement systems across the United Kingdom, Brazil, and India generate continuous cash-flow data streams. Banks require dynamic balance sheet modeling to manage intraday liquidity positions.
- Generative AI Integration:Large language models embedded in scenario analysis modules accelerate stress test documentation. Early adopters in Scandinavian banking consortia report reduced analyst hours for regulatory narrative generation.
Market Restraints
- Specialized Talent Scarcity:Quantitative developers fluent in both regulatory accounting and machine learning command compensation premiums exceeding standard IT budgets. Regional banking associations struggle to fill implementation roles.
- Data Sovereignty Requirements:China's Cybersecurity Law and Russia's data localization mandates fragment cloud deployment architectures. Vendors must maintain separate infrastructure instances, elevating operational complexity.
- Core Banking System Entrenchment:Decades-old mainframe environments at Japanese megabanks resist API integration. Middleware costs for legacy connectivity often exceed software licensing fees.
Strategic Opportunities
- Southeast Asian Digital Banks:Neobank licenses in Indonesia, Philippines, and Vietnam create greenfield procurement opportunities. These institutions skip on-premises infrastructure entirely, favoring SaaS-native platforms.
- Climate Risk Stress Testing:European Central Bank climate scenario mandates extend balance sheet modeling to carbon-intensive loan portfolios. Vendors embedding physical risk geospatial data capture premium positioning.
- Embedded Finance Partnerships:Non-bank lenders integrating banking-as-a-service require lightweight balance sheet visibility tools. API-only product tiers address this adjacent demand without full enterprise implementation.
Industry Challenges
- Model Risk Management Validation:US OCC guidance on algorithmic decision-making demands independent validation of AI-generated forecasts. Banks face extended implementation timelines while establishing internal model governance committees.
- Multi-jurisdictional Reporting Fragmentation:Divergent GAAP, IFRS, and local statutory accounting standards force costly customization. Vendors maintain parallel code branches, degrading upgrade velocity.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Balance Sheet Management Software Market Trends and Innovations
Computational methods and supervisory frameworks are converging to redefine how financial institutions simulate balance sheet behavior under stress. Three developments dominate vendor roadmaps and procurement criteria.
Graph database technology is miniaturizing the latency between raw transaction ingestion and ratio computation. Tier-two US regional banks now deploy subgraph analytics for real-time liquidity monitoring, compressing what required overnight batch processing into sub-minute dashboards. This capability is miniaturizing the competitive gap between capital-rich institutions and mid-market competitors.
The EU's Digital Operational Resilience Act imposes strict continuity requirements on critical financial software providers. Vendors must demonstrate geographic redundancy and incident response protocols to maintain bank eligibility. Continental European institutions are prioritizing DORA-certified platforms in renewal decisions, accelerating consolidation among compliant suppliers.
Subscription fatigue among treasury departments is fragmenting procurement authority. Functional buyers now evaluate modular point solutions against enterprise suites, with Netherlands-based cooperative banks leading unbundling experiments. This pattern spreads through Nordic banking associations before reaching Southern European conservatism.
Balance Sheet Management Software Market Segmentation
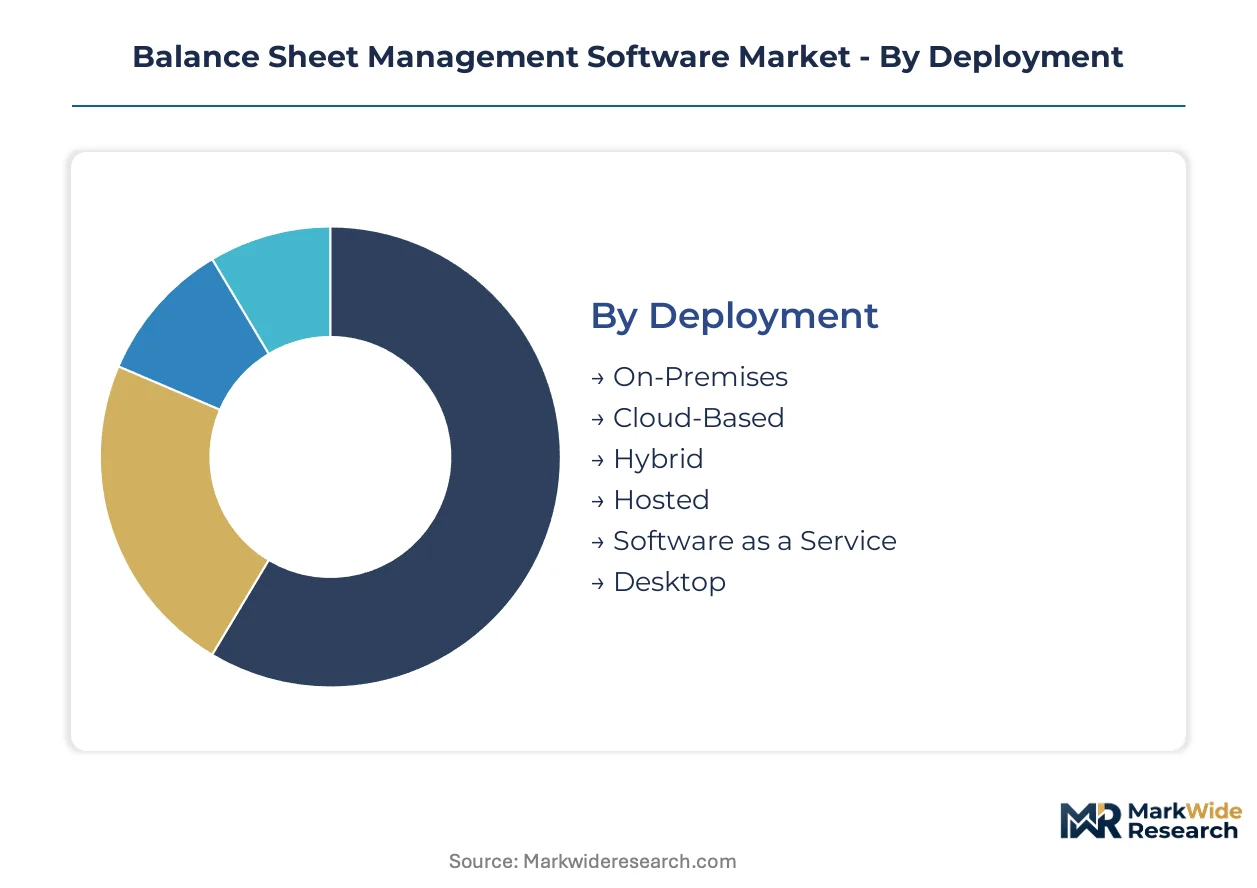
Segmentation in balance sheet management software reveals how procurement authority is fragmenting across treasury, risk, and IT functions. Deployment architecture and pricing model choices increasingly determine vendor shortlists before functional capabilities enter evaluation.
Deployment:
Cloud-native substitutes are displacing legacy infrastructure fastest among mid-tier institutions with compressed implementation timelines.
- Cloud-Based:Multi-tenant architectures eliminate hardware procurement cycles and enable automatic regulatory template updates. Demand concentrates in Scandinavian cooperative banks replacing spreadsheet-based liquidity monitoring with real-time dashboards ahead of ECB deadlines.
- Software as a Service:Pre-configured modules reduce implementation to weeks rather than quarters, with API-first vendors capturing greenfield digital bank contracts in Indonesia and Vietnam.
- On-Premises:Air-gapped environments persist at Japanese megabanks with decades-old core banking dependencies and strict data residency policies.
- Hybrid:Sensitive asset data remains on-premises while regulatory reporting leverages cloud compute bursts during stress test windows.
- Hosted:Single-tenant managed services appeal to UK building societies seeking vendor accountability without shared infrastructure risks.
- Desktop:Survives only in shadow IT scenarios at small credit unions with under $500 million in assets.
Cloud-Based retains volume leadership; Software as a Service holds the steepest expansion curve.
Solution:
Functional bundling is splintering as treasury departments unbundle enterprise suites into best-of-breed point solutions.
- Regulatory Compliance:Automated Basel III and CRD VI reporting engines command premium pricing due to mandatory filing obligations and supervisory audit trails. German Landesbanks prioritize embedded EBA stress test templates over broader ALM functionality.
- Risk Management:Integrated credit, market, and operational risk analytics require quantitative developer teams that smaller institutions cannot staff. Demand clusters at US regional banks facing OCC model risk management validation requirements.
- Asset Liability Management:Duration gap and net interest income simulation remain core to treasury function software evaluations.
- Liquidity Forecasting:Intraday cash-flow modeling gains urgency with instant payment system adoption across Brazil and India.
- Capital Planning:CCAR and Pillar II buffer calculations drive procurement at US and EU systemically important banks.
- Cash Flow Analysis:Working capital visibility tools extend into non-bank corporate treasury departments.
Regulatory Compliance captures the largest revenue pool; Risk Management is climbing the fastest as AI-powered scenario analytics mature.
End User Industry:
Customer-type concentration follows regulatory intensity rather than institutional size.
- Commercial Banks:Tier-one institutions run parallel vendor evaluations for regulatory engines and ALM platforms, often selecting different suppliers. US money center banks face compressed Federal Reserve liquidity coverage ratio implementation timelines.
- Investment Firms:Broker-dealers require intraday position valuation and margin requirement calculations that differ fundamentally from banking book analytics. Prime brokerage units at US bulge-bracket firms drive specialized procurement.
- Insurance Companies:Solvency II and LDTI accounting standards create distinct liability modeling requirements separate from banking regulations.
- Credit Unions:NCUA examination priorities and limited IT budgets favor lightweight SaaS solutions over enterprise implementations.
- Private Equity Firms:Portfolio company aggregation and covenant monitoring requirements differ from regulated depositories.
- Leasing Companies:Residual value risk and equipment finance cash flows demand specialized asset-side modeling.
Commercial Banks retain volume leadership; Investment Firms hold the steepest expansion curve.
Pricing Model:
Contract structure is shifting from capital expenditure to operational expenditure alignment.
- Subscription-Based:Annual recurring revenue models dominate new customer acquisition, with mid-tier institutions prioritizing cash flow predictability over ownership. Netherlands-based cooperative banking associations lead unbundling experiments that separate module subscriptions from core platform fees.
- Usage-Based:Stress test computation bursts and regulatory filing volumes determine costs, appealing to seasonal reporting patterns at specialized lenders.
- Perpetual License:Survives only in long-tail maintenance contracts at Japanese and German institutions with conservative capital allocation committees.
- Tiered Pricing:User count and data volume bands create upgrade friction that vendors exploit for expansion revenue.
- Enterprise License:Unlimited deployment rights across banking groups with complex subsidiary structures.
- Freemium:Limited-functionality tiers attract credit unions and community banks for initial evaluation before conversion to paid modules.
Subscription-Based retains volume leadership; Usage-Based holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based vendors export balance sheet management platforms to European and Asian banking institutions confronting Basel III endgame deadlines. Cross-border procurement flows concentrate through London, Frankfurt, and Singapore financial centers.
United States
Federal Reserve liquidity coverage ratio mandates compress procurement timelines at money center banks. The OCC's model risk management guidance forces institutions to validate automated forecasting engines. New York and Charlotte banking clusters drive enterprise contract volumes for cloud-native regulatory reporting suites.
Germany
Landesbanks prioritize EBA stress test template automation over broader ALM functionality. CRD VI implementation timelines create parallel compliance-driven demand across cooperative banking associations. Frankfurt's financial district anchors vendor development centers serving EU regulatory complexity.
United Kingdom
Building societies seek vendor accountability through single-tenant hosted services rather than shared cloud infrastructure. The Bank of England's climate biennial exploratory scenario extends balance sheet modeling to carbon-intensive portfolios. London fintech clusters incubate API-first challengers targeting real-time payment infrastructure.
Japan
Megabank mainframe entrenchment resists API integration, elevating middleware costs above software licensing fees. METI data localization policies fragment deployment architectures for foreign vendors. Tokyo banking headquarters maintain conservative capital allocation committees favoring perpetual license structures.
Singapore
Neobank licenses across Southeast Asia create greenfield procurement opportunities skipping on-premises infrastructure entirely. MAS digital banking frameworks mandate operational resilience standards for critical software providers. The city-state's financial hub hosts regional headquarters for SaaS-native platform vendors.
Balance Sheet Management Software Market Competitive Landscape
Listed leaders compete with private specialists across compliance automation depth. The vendor base stratifies between database heritage giants, ERP-integrated platforms, and risk analytics specialists. Three archetypes dominate: infrastructure incumbents leveraging legacy data architectures, cloud-native challengers exploiting API modularity, and embedded risk specialists positioning through supervisory relationships. M&A activity concentrates on regulatory template libraries and climate risk geospatial capabilities.
Within the infrastructure tier, Oracle and SAP anchor large-bank implementations through database and ERP integration respectively. Moody’s occupies a distinct position embedding credit-sensitive analytics for institutions prioritizing risk oversight. FIS represents the scale-driven archetype serving tier-one institutions with complex subsidiary structures across multiple jurisdictions.
| Leading Market Players |
|---|
| FIS |
| Moody's |
| Oracle |
| SAP |
| Finastra |
| Kyriba |
| HighRadius |
| Jedox |
| Lucanet |
| Others |
Pricing and Supply Chain Analysis
Fixed-cost amortization across multi-tenant cloud architectures compresses marginal delivery costs for SaaS-native vendors, concentrating pricing power among scale leaders while forcing smaller providers toward modular point-solution positioning. This scale dynamic elevates procurement sophistication at mid-tier banks, which now negotiate module-level subscriptions rather than accepting bundled enterprise suites.
Pricing Analysis
Legacy perpetual-license pricing persists at Japanese megabanks with conservative capital committees, while subscription tiers dominate new customer acquisition across North American and European institutions. Three-tier pricing structure across premium regulatory-compliance bundles, standard ALM functionality, and economy SaaS entry points reflects certification depth and API integration complexity. Cost compression in the economy tier intensifies as API-first challengers from London and Singapore undercut incumbent maintenance fees. Credit unions and community banks under $500 million in assets exhibit highest price sensitivity, whereas tier-one money center banks prioritize regulatory audit trail completeness over license cost.
Supply Chain Analysis
Just-in-time deployment preferences dominate among Southeast Asian digital banks, while strategic stockpiling of regulatory template libraries characterizes vendor preparation for ECB and Federal Reserve deadline clusters. Software development concentrates in the United States, United Kingdom, and Singapore, with implementation services drawing from India and Poland. Intellectual property dependencies rest on graph database engines from California, stress-test computation frameworks from Germany, and cloud infrastructure from hyperscalers. Single-source vulnerability around Basel III template updates poses structural risk. Distribution runs through systems integrators and direct vendor relationships with treasury departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates formidable defensive moats in balance sheet management software, as switching costs escalate with each integrated general ledger feed and validated stress-test workflow.
For Market Incumbents: Fortify API ecosystem control through deeper core banking system partnerships, particularly at Japanese megabanks where middleware replacement cycles open consolidation opportunities. Invest in climate risk geospatial data capabilities ahead of ECB scenario mandates. Cloud-native challenger erosion in the mid-tier segment demands rapid rearchitecture of legacy codebases to preserve renewal rates. For New Entrants and Emerging Players: Lead with embedded finance partnerships targeting non-bank lenders requiring lightweight balance sheet visibility without full enterprise implementation. Indonesia, Philippines, and Vietnam neobank licenses offer the most penetrable geography, skipping on-premises infrastructure entirely. API-only product tiers with rapid deployment cycles address procurement authority fragmentation among Netherlands cooperative banking associations. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among SaaS-native platforms with pre-configured regulatory modules, suggesting superior long-term viability across the analysis window. Target acquisition archetypes include climate risk geospatial specialists and stress-test template library owners. Watch for inflection when DORA certification requirements accelerate continental European vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Template Library Acquisition | Accelerates Federal Reserve and ECB compliance deadline positioning for tier-one bank procurement. |
| Climate Risk Geospatial Partnership | Captures ECB climate scenario mandate premium through physical risk data integration. |
| API-First Platform Launch | Addresses Southeast Asian digital bank greenfield demand with weeks-not-quarters deployment. |
| Core Banking Middleware Integration | Unlocks Japanese megabank contracts where legacy entrenchment resists cloud migration. |
| DORA Certification Investment | Maintains continental European bank eligibility under strict operational resilience standards. |
Research Methodology
The analysis maps cloud-native deployment architectures, regulatory compliance modules, and risk analytics engines, each validated through treasury officers, risk management directors, and IT procurement leads at commercial banks and investment firms. Primary interview findings triangulate against SEC 10-K filings, EBA stress test disclosure templates, and Federal Reserve regulatory guidance documents. Bottom-up contract value aggregation and top-down market sizing cross-validate volume estimates.
Consistency checks against external benchmarks confirm analytical framework outputs across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution functionality, end-user institution type, and pricing model structure. CAGRs derive from regression analysis of historical procurement velocity and regulatory deadline clustering. Forecast inputs incorporate cloud migration timelines at tier-two US regional banks and instant payment infrastructure adoption across Brazil and India.
Forecasts assume regulatory continuity in US Federal Reserve and European Banking Authority regimes; material policy shifts would require re-modeling. Revision becomes warranted when Basel III implementation timelines compress or generative AI supervisory guidance disrupts automation roadmaps.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.