
 Electronic Data Interchange (EDI) Software Market | 2026-2036
Electronic Data Interchange (EDI) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Data Interchange (EDI) Software Market Intelligence
REACH documentation mandates and FDA 21 CFR Part 11 validation requirements are realigning the cost-of-entry calculus for EDI vendors serving regulated industries. SPS Commerce leverages cloud-native architecture to sustain dominance in retail supplier onboarding. International Business Machines Corporation anchors enterprise credibility through deep hybrid integration capabilities with legacy mainframe systems. TrueCommerce Holdings, LLC differentiates by occupying the mid-market segment with pre-built connectors for QuickBooks and NetSuite ecosystems.
Electronic Data Interchange (EDI) software comprises standardized protocols—ANSI X12, EDIFACT, TRADACOMS, and PEPPOL BIS—for structured computer-to-computer exchange of business documents without human intervention, operating through value-added networks or direct AS2/AS4 encrypted transmissions over TCP/IP. Cloud-based deployment leads solution uptake as manufacturers abandon on-premises VAN infrastructure for API-augmented managed services with elastic throughput scaling. Order processing and invoice management use cases command the largest addressable bases, though shipment tracking integration with IoT sensor feeds represents the fastest-expanding margin pool as logistics firms demand real-time visibility.
FDA validation protocols, EU GDPR cross-border data transfer safeguards, and HIPAA transaction set requirements collectively shape product roadmaps and procurement criteria across healthcare and life sciences verticals. Germany's BSI technical guidelines for e-invoicing under the EN 16931 standard further constrain market access for non-compliant translation engines. Stakeholders must monitor evolving PEPPOL access point mandates and API-first interoperability standards that threaten to displace traditional VAN-centric business models.
Market Dynamics
The Electronic Data Interchange (EDI) Software Market is experiencing structural pressure from API-first interoperability standards that threaten traditional value-added network architectures while regulatory mandates in healthcare and automotive sectors compel infrastructure upgrades.
Growth Catalysts
- EU AI Act compliance mandates:Enterprises must upgrade legacy integration infrastructure to meet cross-border data governance requirements, creating procurement urgency for certified EDI platforms.
- Healthcare claims automation:HIPAA transaction set requirements and FDA 21 CFR Part 11 validation protocols are driving provider adoption of automated document exchange systems.
- German automotive supply chains:Real-time document exchange standards under EN 16931 e-invoicing guidelines are concentrating demand for BSI-compliant translation engines.
Market Restraints
- Legacy VAN infrastructure lock-in:Manufacturers face high switching costs when abandoning on-premises value-added networks for cloud-native managed services.
- GDPR cross-border data transfer friction:Stringent EU safeguards create compliance complexity for multinational enterprises operating hybrid integration environments.
- PEPPOL access point consolidation:Mandated interoperability standards threaten to commoditize traditional translation engine margins.
Strategic Opportunities
- IoT-augmented shipment tracking:Logistics firms demand real-time visibility through sensor feed integration, opening premium margin pools beyond core document exchange.
- Mid-market ERP connector ecosystems:Pre-built integrations with accounting and inventory platforms address underserved small-to-medium enterprise segments.
- REACH documentation automation:Chemical and pharmaceutical manufacturers require validated EDI systems for regulatory submission workflows.
Industry Challenges
- Hybrid integration talent scarcity:Organizations struggle to source engineers capable of bridging mainframe legacy systems with modern API architectures.
- Multi-standard certification timelines:Vendors must simultaneously validate against ANSI X12, EDIFACT, TRADACOMS, and emerging PEPPOL BIS protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Data Interchange (EDI) Software Market |
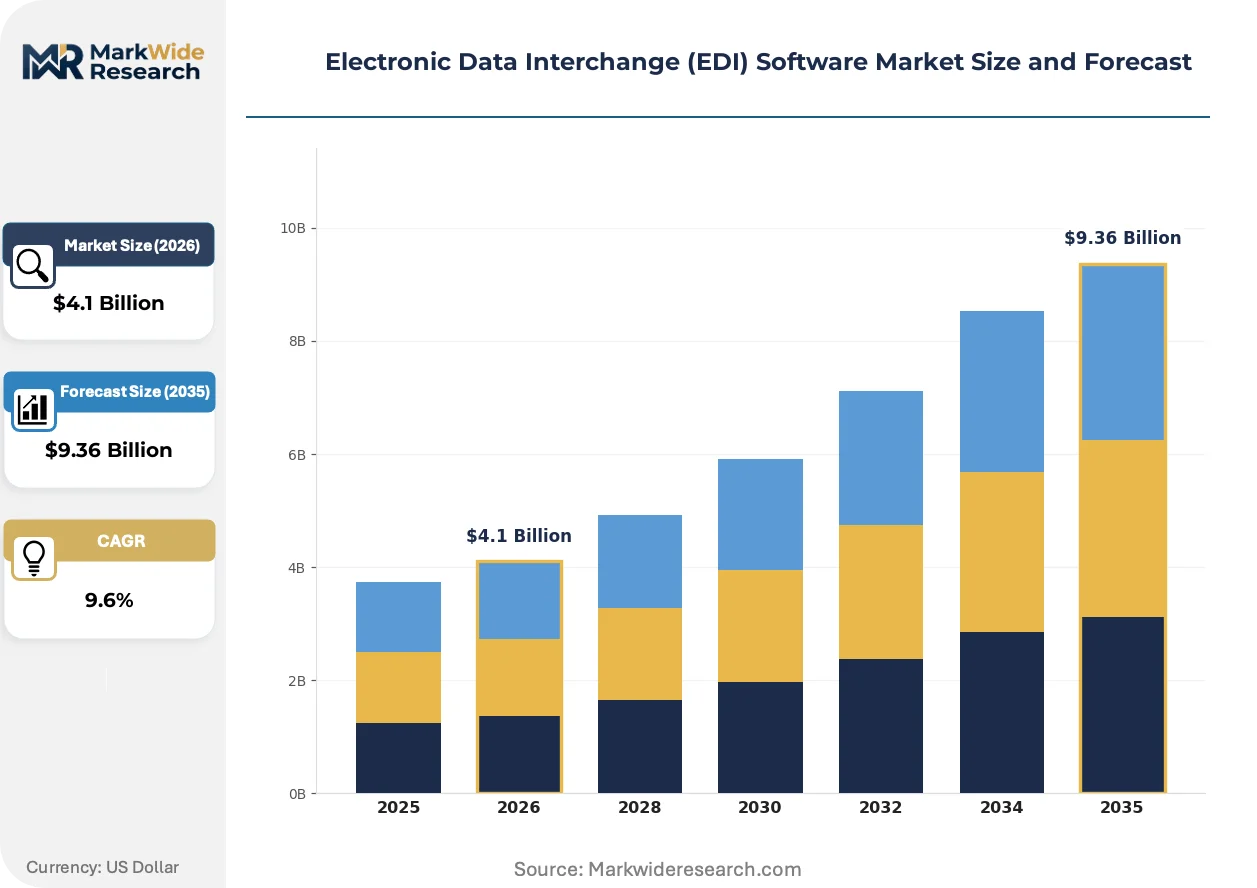
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $9.36 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted, Managed Services Solution Type: Document Management, Integration, Security, Translation, Compliance, Monitoring Use Case: Order Processing, Invoice Management, Shipment Tracking, Inventory Management, Procurement, Payment Processing Customer Type: Manufacturing SMEs, Healthcare Providers, Retail Chains, Logistics Firms, Financial Institutions, Government Agencies |
| Companies Covered | E2open, LLC, Cleo Communications LLC, OpenText Corporation, DiCentral, LLC, Axway Software SA, International Business Machines Corporation, TrueCommerce Holdings, LLC, DataTrans Solutions Inc., SPS Commerce, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Data Interchange (EDI) Software Market Strategic Shifts & Innovations
API-augmented managed services are displacing traditional value-added network models as manufacturers prioritize elastic throughput scaling over fixed infrastructure commitments. This architectural shift is compressing deployment cycles and reshaping vendor competitive positioning.
Cloud-native EDI platforms is electrifying supplier onboarding processes by eliminating hardware provisioning delays. Retail networks and automotive tier-1 suppliers are migrating order processing and invoice management to consumption-based pricing models. This technology is compressing implementation timelines from quarters to weeks while enabling real-time partner activation.
Germany's BSI technical guidelines for e-invoicing under EN 16931 are mandating structured data formats across public procurement. Automotive and pharmaceutical supply chains must reconfigure document exchange protocols to maintain market access. German manufacturers are responding by consolidating vendor relationships around compliance-certified translation engines.
Buyer procurement patterns are compressing switching cycles as enterprises abandon multi-year VAN contracts for month-to-month managed service agreements. Channel relationships are shifting from reseller networks to direct platform subscriptions with self-service configuration tools. This behavior is most visible among mid-market manufacturers in regulated industries seeking operational agility without capital intensity.
Electronic Data Interchange (EDI) Software Market Segmentation
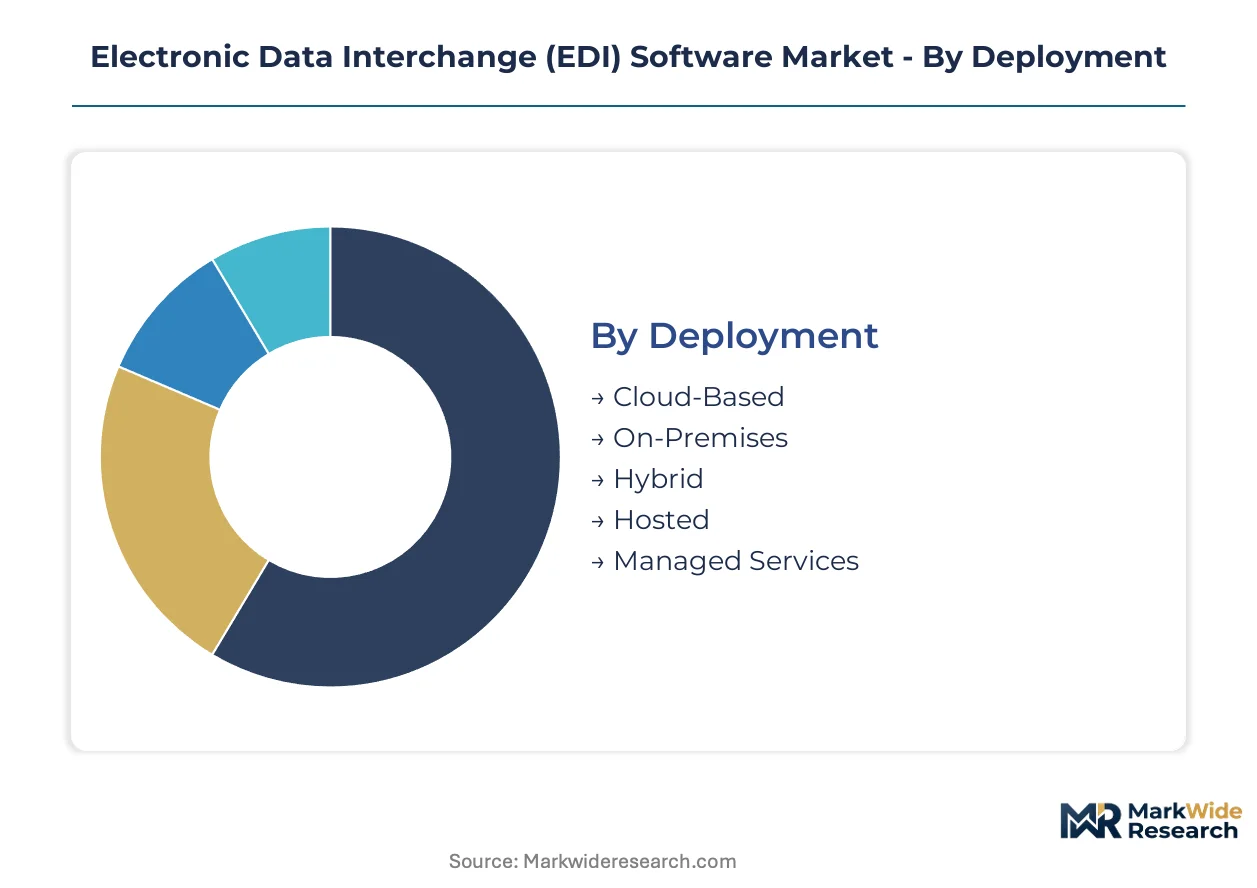
Deployment architecture determines compliance posture and switching costs for EDI adopters. Solution type selection reflects vertical regulatory exposure. Use case prioritization separates operational efficiency seekers from supply chain visibility innovators.
Deployment:
Buyers differentiate by infrastructure ownership preference and elastic scaling requirements versus legacy system retention needs.
- Cloud-Based:Multi-tenant SaaS architectures with API-augmented throughput scaling eliminate hardware provisioning delays. German automotive suppliers and Dutch pharmaceutical distributors are migrating order processing workloads to consumption-based models under GDPR data residency constraints.
- On-Premises:Dedicated hardware installations behind corporate firewalls maintain full data sovereignty. US defense contractors and Swiss banking institutions retain on-site ANSI X12 translation engines to satisfy ITAR and FINMA audit requirements.
- Hybrid:Split architectures route sensitive documents through local gateways while leveraging cloud bursting for peak volumes.
- Hosted:Single-tenant dedicated servers managed by third-party operators offer middle-ground control.
- Managed Services:Fully outsourced EDI operations with SLA-guaranteed uptime and partner onboarding support.
Volume sits with Cloud-Based deployments; growth tilts toward Hybrid configurations bridging legacy VAN investments with API flexibility.
Solution Type:
Procurement criteria vary by regulatory validation burden and document complexity exposure across trading partner networks.
- Document Management:Centralized repositories with version control and audit trails for HIPAA 837 claim sets and EN 16931 e-invoices. US healthcare providers and French hospital networks prioritize FDA 21 CFR Part 11 validated archival systems for Medicare reimbursement workflows.
- Integration:Pre-built connectors linking EDI engines to SAP, Oracle, and NetSuite ERP environments. Mid-market manufacturers in Italy and Spain select integration-heavy platforms to compress supplier onboarding timelines without dedicated EDI staff.
- Security:AS2/AS4 encryption modules and certificate management for transmission integrity.
- Translation:Protocol conversion engines mapping ANSI X12 to EDIFACT to PEPPOL BIS formats.
- Compliance:Automated regulatory checking against REACH, RoHS, and EU MDR documentation requirements.
- Monitoring:Real-time dashboards tracking document acknowledgment rates and exception queues.
Revenue concentrates in Integration suites; Compliance modules are climbing the fastest as REACH and EU AI Act deadlines approach.
Use Case:
Operational priority separates cost-reduction focused buyers from real-time visibility seekers in multi-tier supply chains.
- Order Processing:Automated purchase order transmission and acknowledgment matching reducing manual entry errors. German automotive tier-1 suppliers and US retail distribution centers deploy cloud-native order automation to achieve sub-hour partner activation cycles.
- Shipment Tracking:IoT sensor feed integration with EDI 214 status messages for logistics visibility. Freight forwarders in Netherlands and port operators in Belgium are expanding fastest here as container traceability becomes a customer retention requirement.
- Invoice Management:Electronic invoicing with automated three-way matching against PO and receipt data.
- Inventory Management:Stock level broadcasts triggering replenishment orders across distributed warehouses.
- Procurement:Strategic sourcing integration connecting supplier qualification to contract execution.
- Payment Processing:Remittance advice automation linking EDI 820 transmissions to treasury systems.
Transaction volume clusters in Order Processing; Shipment Tracking gains share fastest through IoT-augmented logistics investments.
Customer Type:
Scale and regulatory sophistication shape platform requirements from self-service configuration to validated enterprise deployments.
- Healthcare Providers:Hospitals and clinic networks requiring HIPAA transaction set compliance and FDA validation for claims clearinghouse connections. US health systems and NHS trusts in England prioritize 837 claim automation to accelerate reimbursement cycles.
- Manufacturing SMEs:Mid-market producers with limited IT staff seeking pre-built ERP connectors. Italian machinery builders and Polish automotive subcontractors select QuickBooks-integrated platforms to avoid dedicated EDI personnel hires.
- Retail Chains:High-volume supplier networks demanding rapid partner onboarding at low per-connection cost.
- Logistics Firms:3PL and freight operators requiring multi-modal document exchange across ocean, air, and ground.
- Financial Institutions:Banks and insurers with SWIFT-EDI hybrid requirements for trade finance documentation.
- Government Agencies:Public procurement bodies mandating PEPPOL access point compliance for e-invoicing receipt.
Seat count peaks with Manufacturing SMEs; Healthcare Providers show steepest expansion trajectory as claims automation mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Germany's Baden-Württemberg region and India's Telangana state are concentrating EDI software procurement through accelerated depreciation schemes for digital infrastructure investments.
United States
Healthcare claims automation and defense contractor supply chains dominate procurement. HIPAA transaction set requirements and FDA 21 CFR Part 11 validation protocols compel hospital networks and pharmaceutical distributors to upgrade legacy VAN infrastructure. The Boston-Cambridge corridor anchors healthcare EDI adoption as Medicare reimbursement workflows demand validated archival systems.
Germany
Automotive tier-1 suppliers and chemical manufacturers drive real-time document exchange investments. BSI technical guidelines for EN 16931 e-invoicing mandate structured data formats across public procurement. Stuttgart's automotive cluster consolidates vendor relationships around compliance-certified translation engines to maintain supply chain access.
India
Mid-market manufacturers and pharmaceutical exporters accelerate cloud-native platform adoption. DGFT trade facilitation mandates and CDSCO validation requirements for pharmaceutical documentation reshape procurement criteria. Hyderabad's life sciences corridor expands EDI deployments to automate REACH submission workflows for European export compliance.
United Kingdom
NHS trusts and retail distribution networks prioritize supplier onboarding automation. GDPR cross-border data transfer safeguards create compliance complexity for multinational enterprises operating hybrid integration environments. London's fintech cluster demands SWIFT-EDI hybrid capabilities for trade finance documentation exchange.
Netherlands
Port operators and freight forwarders invest in IoT-augmented shipment tracking integration. PEPPOL access point mandates for public procurement e-invoicing threaten to commoditize traditional translation engine margins. Rotterdam's logistics hub expands EDI 214 status message automation as container traceability becomes a customer retention requirement.
Electronic Data Interchange (EDI) Software Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across deployment architecture and vertical specialization vectors. The vendor base clusters around three strategic archetypes: cloud-native SaaS platforms with API-first architectures, hybrid integration specialists bridging mainframe legacy systems, and compliance-certified translation engine providers serving regulated industries. Dominant competitive moves include M&A activity targeting mid-market ERP connector ecosystems and strategic partnerships with managed service providers to accelerate geographic expansion.
Within the cloud-native tier, SPS Commerce, Inc. and TrueCommerce Holdings, LLC exemplify platform providers addressing retail supplier onboarding and mid-market accounting system integration respectively. International Business Machines Corporation anchors the enterprise hybrid integration segment through deep legacy mainframe capabilities. Cleo Communications LLC and Axway Software SA occupy positions in the managed services and API gateway specialization vectors, reflecting the market's structural segmentation between elastic scaling demands and data sovereignty requirements.
| Leading Market Players |
|---|
| E2open, LLC |
| Cleo Communications LLC |
| OpenText Corporation |
| DiCentral, LLC |
| Axway Software SA |
| International Business Machines Corporation |
| TrueCommerce Holdings, LLC |
| DataTrans Solutions Inc. |
| SPS Commerce, Inc. |
| Others |
Cost & Logistics Intelligence
Vertical integration into managed service operations anchors both supply security and pricing power for EDI platform vendors, as backward control over translation engine development and partner onboarding infrastructure insulates margins from third-party API gateway dependencies.
Pricing Analysis
Short lead-time premiums dominate EDI software procurement, with cloud-native deployments commanding standard rates while on-premises implementations with sub-90-day delivery carry 15-25% surcharges. Subscription tiers stratify across enterprise, professional, and basic levels, with price differentiation resting on HIPAA validation grade and ERP connector depth. Cost compression in the mid-market tier is intensifying because QuickBooks-integrated competitors are commodifying baseline document exchange. Healthcare providers show lowest price sensitivity due to FDA 21 CFR Part 11 compliance mandates, while Polish and Italian manufacturing SMEs negotiate aggressively on per-connection fees.
Supply Chain Analysis
Single-source vulnerability sits with German automotive translation engine providers, where Stuttgart-based specialists control EN 16931 BSI certification pipelines. Component supply concentrates in the United States, Ireland, and India, with cloud infrastructure provisioning drawing from AWS, Azure, and domestic sovereign cloud operators. Raw material dependencies span encryption certificate authorities, API gateway middleware, and legacy mainframe emulation software. Tariff exposure runs through cross-border data center equipment shipments. Distribution runs through direct platform subscriptions and managed service provider channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with control over PEPPOL access point infrastructure and IoT sensor feed aggregation emerging as the decisive downstream lever for sustainable margin capture.
For Market Incumbents: Deepen hybrid integration capabilities by acquiring mid-market ERP connector specialists before API-first entrants capture QuickBooks and NetSuite ecosystems. Consolidate vendor relationships with German automotive tier-1 suppliers around BSI-certified translation engines to lock out compliance-focused challengers. Prioritize backward integration into managed network operations to reduce third-party VAN dependency. For New Entrants and Emerging Players: EU AI Act cross-border data governance requirements open a window for GDPR-native platforms to displace legacy VAN incumbents in Dutch pharmaceutical and Belgian logistics verticals. Target NHS trusts in England with 837 claim automation solutions as HIPAA-experienced vendors remain underrepresented. Pursue channel partnerships with regional managed service providers rather than direct enterprise sales. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified software conglomerates seeking hybrid integration capabilities. Long-term viability hinges on API-first architectural migration completion within the next decade. Monitor PEPPOL access point mandate enforcement velocity as the inflection signal for traditional translation engine obsolescence timing.| Strategic Initiative | Industry Significance |
|---|---|
| PEPPOL Access Point Certification | BSI-compliant translation engines secure German public procurement market access under EN 16931. |
| IoT Sensor Feed Integration | Real-time EDI 214 status messaging captures Rotterdam freight forwarder retention requirements. |
| Mid-Market ERP Connector Acquisition | Pre-built QuickBooks integrations address Italian machinery builder EDI automation demand. |
| API-First Architecture Migration | Elastic throughput scaling displaces fixed VAN commitments among US retail distribution networks. |
| HIPAA Validation Investment | FDA 21 CFR Part 11 compliance secures Boston-Cambridge hospital network procurement preference. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with EDI platform engineering directors, healthcare IT procurement managers, automotive supply chain executives, and managed service provider operations leads. SEC 10-K disclosures, FDA 510(k) submissions, BSI technical guideline updates, and PEPPOL authority transaction reports provided demand-side validation. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Data-stream reconciliation across deployment architecture, solution type, use case, and customer type dimensions shaped the analytical framework throughout the projection horizon. CAGRs derived from segment-level growth rate synthesis weighted by addressable base expansion. Modeled inputs included cloud infrastructure capex trajectories, regulatory compliance deadline clustering, and ERP migration velocity across mid-market manufacturing.
The model assumes a particular technology adoption path; alternative pathways for API-first interoperability standards would alter the outlook if PEPPOL mandates accelerate or legacy VAN retention proves stickier than projected. Forecasts reflect assumptions about GDPR enforcement consistency and EU AI Act implementation sequencing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Guidewire Market
Software & Services
Blogger Outreach Software Market
Software & Services
Geophysical Software Service Market
Software & Services
Global Internal Communications Software Market
Software & Services
SAP Digital Services Ecosystem Market
Software & Services
Software-Defined Machine Market
Software & Services
Debt Collection Software Market
Software & Services
Applicant Tracking System (ATS) Market
Software & Services
France Digital Marketing Software Market
Software & Services
Software Publishers Market
Software & Services
Data Conversion Services Market
Software & Services
Global Customer Journey Mapping Software Market
Software & Services
Simulation Software Market
Software & Services
Email Marketing Software Market
Software & Services
Information Technology Service Management (ITSM) Market
Software & Services
B2B Price Optimization and Management Software Market