
 Italy Data Center Storage Market | 2026-2036
Italy Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Data Center Storage Market Insights
Project finance and sale-leaseback structures for hyperscale facilities is tilting competitive dynamics toward capital-light operators. Dell Technologies leverages its integrated server-storage portfolio to anchor enterprise refresh cycles across northern Italy. Pure Storage specializes in all-flash arrays that sustain premium positioning among latency-sensitive workloads. Huawei Technologies navigates procurement constraints through localized assembly partnerships that extend its reach into mid-tier service providers.
Italy data center storage encompasses electromechanical and solid-state systems engineered for persistent data retention, with SSD arrays achieving sequential read speeds exceeding 7,000 MB/s via NVMe interfaces and HDD clusters delivering cost-optimized capacity above 20 TB per spindle. These systems serve as the foundational infrastructure for enterprise virtualization, backup archives, and real-time analytics platforms. NVMe-based flash deployments are capturing the fastest expansion as latency requirements tighten for AI inference workloads, while hybrid deployments spanning on-premise and cloud retain the largest installed base among risk-averse financial institutions. Tape storage persists as a mature, cost-isolated tier for long-term regulatory archives where retrieval frequency remains minimal.
Italy's data center storage sector operates under the EU AI Act's risk-based data governance tiers, supplemented by AGID (Agenzia per l'Italia Digitale) guidelines on public-sector cloud qualification and national cybersecurity perimeter requirements administered by ACN (Agenzia per la Cybersicurezza Nazionale). These frameworks mandate encryption standards, residency protocols, and supply-chain vetting that elevate procurement complexity for foreign equipment vendors. Stakeholders must monitor how forthcoming EU Data Act portability rules reshape storage architecture decisions across multi-cloud environments.
Market Dynamics
NVMe flash penetration is compressing refresh cycles across Italian enterprise storage estates, forcing incumbents to defend installed base relationships while hyperscalers scale direct procurement of commodity-class arrays. This technology displacement is redrawing vendor competitive boundaries from performance specifications toward data services integration.
Growth Catalysts
- EU AI Act risk-tier mandates:High-risk AI system operators must maintain immutable audit logs with guaranteed residency, compelling storage architecture upgrades that satisfy AGID cloud qualification protocols.
- Milan metropolitan concentration:Hyperscaler facility clustering in Lombardy generates localized demand for petabyte-scale object storage supporting real-time analytics pipelines.
- Financial services virtualization:Italian banks are consolidating branch infrastructure onto software-defined storage to support omnichannel digital banking workloads.
Market Restraints
- NAND flash supply concentration:Korean and Taiwanese foundry dominance exposes Italian buyers to input cost volatility and allocation constraints during demand surges.
- ACN cybersecurity perimeter vetting:Foreign equipment vendors face extended certification timelines that delay procurement decisions for critical national infrastructure operators.
- Tape archive persistence:Long-term regulatory retention requirements sustain mature storage tier demand, limiting all-flash array addressable share in compliance-heavy verticals.
Strategic Opportunities
- Southern Italy latency arbitrage:Underdeveloped data center density in Sicily and Apulia offers greenfield deployment potential for edge storage serving Mediterranean submarine cable terminations.
- EU Data Act portability rules:Forthcoming multi-cloud data mobility mandates will stimulate investment in software-defined storage with native cross-platform replication capabilities.
- AI inference edge deployment:Converged NVMe-compute nodes are penetrating manufacturing and logistics facilities for real-time quality control and predictive maintenance.
Industry Challenges
- Storage administrator skill scarcity:Specialized expertise in software-defined and container-native storage architectures remains concentrated in northern industrial districts, constraining nationwide deployment velocity.
- Legacy SAN integration friction:Fibre Channel estates in established financial institutions resist seamless migration to NVMe-over-TCP architectures without substantial re-cabling investment.
- AGID-ACN dual compliance timelines:Public-sector cloud qualification and national cybersecurity perimeter requirements operate on misaligned review schedules, extending procurement cycles for state-affiliated operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Data Center Storage Market |
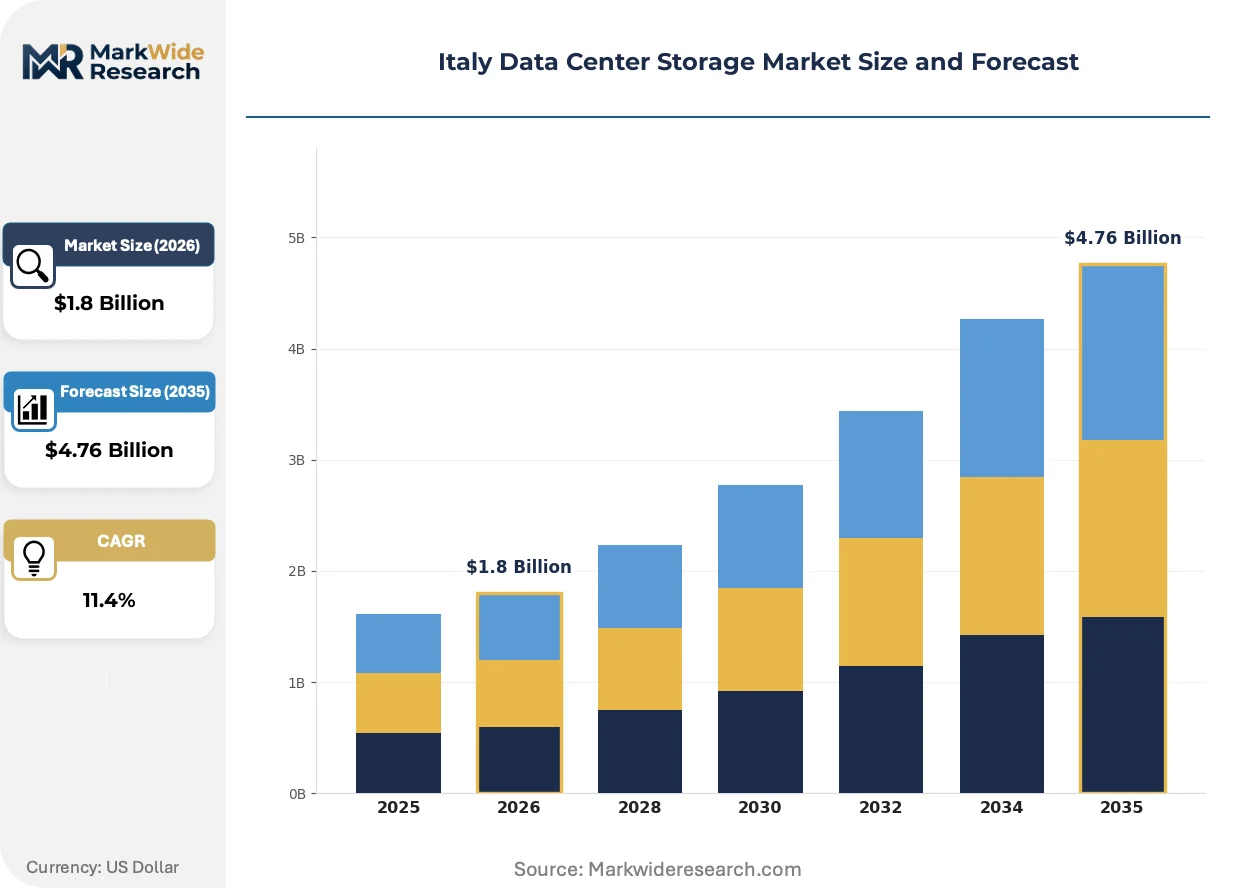
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDD, SSD, Hybrid Storage, Tape Storage Deployment: On-Premise, Cloud, Hybrid, Edge End User: Enterprise, SMEs, Government, Service Providers Technology: NVMe, SATA, SAS, Fibre Channel |
| Companies Covered | NetApp, Hitachi Vantara, Dell Technologies, Pure Storage, Seagate Technology, Hewlett Packard Enterprise, Huawei Technologies, Lenovo Group, IBM Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Data Center Storage Market Trends and Innovations
Computational storage architectures are collapsing data movement bottlenecks that previously constrained analytics throughput. Italian operators are re-evaluating total cost of ownership models as processing capabilities migrate from host servers into drive-level controllers.
NVMe-based computational storage drives are embedding ARM processing cores directly within solid-state devices to execute data reduction and encryption operations at the media interface. Telecom operators in Lombardy are piloting these arrays for subscriber analytics workloads that previously saturated host CPU resources. This architecture is digitizing traditional storage controller functions and compressing the hardware layers between application and persistent media.
ACN-administered national cybersecurity perimeter requirements are mandating supply-chain provenance documentation and encryption certification for all storage equipment deployed in critical infrastructure facilities. Hardware vendors must maintain Italian-registered legal entities and localized technical support capabilities to satisfy procurement pre-qualification. Financial services operators in Milan are responding by consolidating vendor relationships toward domestic system integrators with established ACN accreditation.
Consumption-based financing models are displacing capital-intensive storage procurement among mid-market enterprises with irregular capacity growth patterns. Managed service providers in Turin and Bologna are offering metered all-flash capacity with bundled data protection services that transfer refresh risk from customer balance sheets. This shift is most visible among professional services firms and regional healthcare networks seeking to align storage expenditure with actual utilization trajectories.
Italy Data Center Storage Market Segmentation
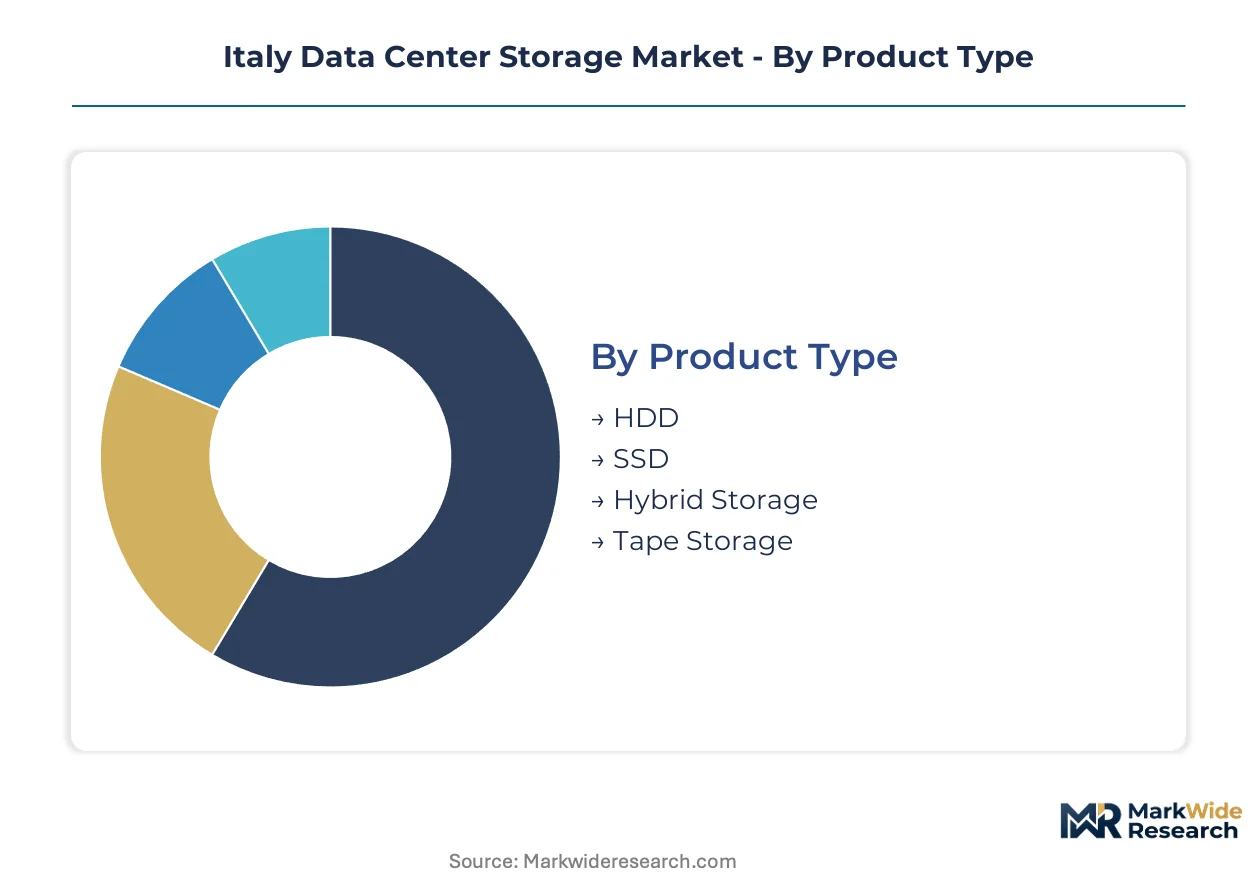
Storage architecture decisions in Italy trace divergent paths across workload latency requirements, data sovereignty mandates, and infrastructure refresh cycles. Each segmentation dimension reveals how procurement patterns split between risk-averse incumbents and cloud-native operators.
Product Type:
Workloads range from millisecond-sensitive transaction processing to decade-scale regulatory archiving, dictating radically different media economics.
- HDD:Electromechanical spindles deliver sequential throughput above 250 MB/s with per-terabyte costs minimized through helium-sealed 20+ TB densities. Milan-based hyperscalers deploy HDD clusters for warm object storage supporting analytics pipelines where access frequency remains moderate.
- SSD:NAND-based arrays achieve sub-100 microsecond latency via NVMe interfaces, capturing premium positioning among Lombardy financial institutions running real-time fraud detection workloads.
- Hybrid Storage:Automated tiering combines flash front-ends with HDD back-ends, serving Turin manufacturing firms balancing performance and capacity constraints.
- Tape Storage:LTO-9 cartridges provide isolated air-gap protection for AGID-mandated public-sector archives with 30-year retention horizons.
Established volume favors HDD; emerging adoption favors SSD.
Deployment:
Infrastructure location determines compliance exposure and latency boundaries across the Italian peninsula.
- On-Premise:ACN cybersecurity perimeter requirements anchor sensitive workloads in certified facilities with localized encryption key management.
- Cloud:AGID-qualified hyperscaler regions in Lombardy serve public-sector tenants with guaranteed residency and sovereign controls.
- Hybrid:Policy-driven data placement splits active datasets between colocated flash and cloud object tiers, expanding most quickly among Bologna professional services firms seeking utilization-aligned expenditure.
- Edge:Converged NVMe-compute nodes deploy to Sicilian logistics hubs for real-time quality control with submarine cable backhaul.
Hybrid architectures are gaining share fastest as compliance complexity fragments workload placement.
End User:
Procurement sophistication varies sharply across organizational scale and regulatory exposure.
- Enterprise:Northern Italian banks and insurers maintain dedicated storage engineering teams managing Fibre Channel SAN estates with five-year depreciation schedules.
- SMEs:Consumption-based financing from Turin managed service providers transfers refresh risk and eliminates capital intensity for irregular growth patterns.
- Government:ACN vetting timelines and AGID cloud qualification extend procurement cycles for state-affiliated operators.
- Service Providers:Multi-tenant infrastructure demands software-defined storage with native cross-platform replication anticipating EU Data Act portability mandates.
Enterprise installed base sustains incumbent relationships; service provider expansion drives architectural innovation.
Technology:
Interface selection locks in performance ceilings and integration complexity for the deployment lifecycle.
- NVMe:PCIe-attached flash bypasses legacy controller bottlenecks, climbing the fastest among AI inference workloads in Lombardy data centers.
- SATA:Cost-optimized NAND and HDD connectivity persists in secondary tier applications where bandwidth requirements remain modest.
- SAS:Dual-ported drives sustain mission-critical availability for Rome healthcare networks running 24/7 diagnostic imaging.
- Fibre Channel:Established 32 Gb/s fabrics resist displacement in Milan financial institutions despite re-cabling friction for NVMe-over-TCP migration.
Fibre Channel defends legacy footprint; NVMe commands new investment priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's data center storage sector operates as a net importer of specialized NAND flash and high-density HDD components, with domestic demand outstripping local manufacturing capacity. The national market draws equipment from Asian foundry centers and European assembly facilities, creating procurement dependencies that shape regional investment patterns.
Lombardy
Milan anchors the peninsula's storage demand through hyperscaler clustering and financial services density. AGID cloud qualification protocols govern public-sector procurement from Lombardy-based facilities. The metropolitan zone hosts concentrated deployments of NVMe arrays serving real-time fraud detection workloads for banking headquarters.
Piedmont
Turin manufacturing networks generate edge storage demand for industrial IoT and quality control systems. ACN cybersecurity perimeter requirements extend certification timelines for equipment deployed in critical infrastructure. The region's automotive supply chain is piloting converged NVMe-compute nodes for predictive maintenance applications.
Emilia-Romagna
Bologna professional services firms are expanding hybrid cloud storage architectures to align expenditure with utilization trajectories. EU AI Act risk-tier mandates compel architecture upgrades for high-risk system operators in the region. Managed service providers here are scaling consumption-based financing models for mid-market enterprises.
Lazio
Rome healthcare networks sustain demand for dual-ported SAS storage supporting 24/7 diagnostic imaging availability. National cybersecurity perimeter vetting from ACN concentrates procurement decisions among accredited domestic system integrators. Public-sector cloud qualification timelines extend deployment cycles for state-affiliated hospital operators.
Sicily
Southern latency arbitrage opportunities are emerging around Mediterranean submarine cable terminations in Palermo and Catania. AGID guidelines on data residency influence edge storage placement decisions for logistics operators. Greenfield data center development remains underdeveloped relative to northern density, offering expansion potential for regional service providers.
Italy Data Center Storage Market Competitive Landscape
On the supply side, the industry is consolidating around integrated infrastructure portfolios and specialized flash architectures. Tier-one vendors defend enterprise relationships through server-storage bundling, while pure-play flash specialists capture premium positioning in latency-sensitive verticals. Two strategic archetypes dominate: diversified technology conglomerates with broad infrastructure portfolios, and focused storage specialists with all-flash expertise. Competitive moves center on localized assembly partnerships to navigate procurement constraints, and consumption-based financing models that transfer refresh risk to service providers.
Within the diversified infrastructure tier, Dell Technologies and Hewlett Packard Enterprise exemplify integrated server-storage portfolios that anchor enterprise refresh cycles. Pure Storage occupies a specialist position representing all-flash array architectures for performance-critical workloads. Huawei Technologies sits within a partnership-dependent archetype, leveraging localized assembly arrangements to extend reach into mid-tier service providers despite extended ACN certification timelines.
| Leading Market Players |
|---|
| NetApp |
| Hitachi Vantara |
| Dell Technologies |
| Pure Storage |
| Seagate Technology |
| Hewlett Packard Enterprise |
| Huawei Technologies |
| Lenovo Group |
| IBM Corporation |
| Others |
Pricing and Supply Chain Analysis
Milan's hyperscaler clustering concentrates procurement volume among Lombardy-based financial institutions and cloud operators, compressing vendor margins through consolidated purchasing power while amplifying price sensitivity for commodity-class HDD arrays.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with NVMe flash arrays commanding substantial premiums based on latency certification and AGID compliance documentation. Price differentiation hinges on ACN cybersecurity perimeter accreditation and bundled data protection services. Cost compression in mid-market HDD tiers is intensifying because Korean foundry allocation constraints are squeezing NAND flash availability. Regional healthcare networks exhibit the highest price sensitivity, while Milan-headquartered banks prioritize performance guarantees over unit economics.
Supply Chain Analysis
Upstream NAND flash wafers and high-density HDD components draw from South Korea, Taiwan, and Japan, with helium-sealed spindle mechanisms resting on precision manufacturing concentrated in Southeast Asian assembly facilities. Raw material dependencies span silicon substrates, rare earth magnets, and specialized controller semiconductors. Single-source vulnerability around Korean foundry output exposes Italian buyers to allocation rationing during demand surges. Distribution runs through accredited domestic system integrators with established ACN pre-qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
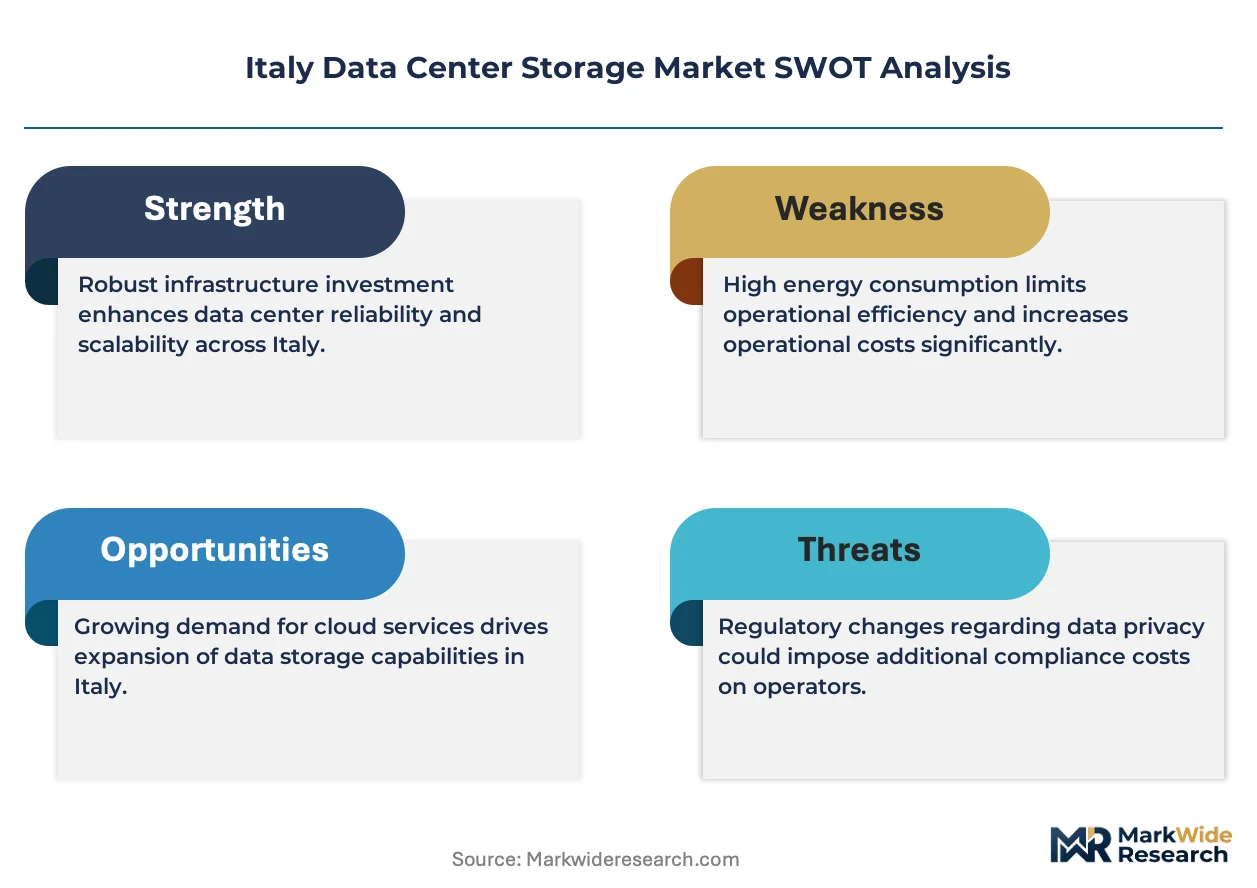
Italy's data center storage sector sits at a platform-economics inflection where software-defined architectures and cross-cloud interoperability are displacing proprietary hardware lock-in, reshaping how vendors capture value across the stack.
For Market Incumbents: Pre-empt NVMe-over-TCP displacement by accelerating Fibre Channel migration programs for Milan financial institutions before re-cabling friction hardens legacy SAN commitments. Deepen vertical integration into localized assembly partnerships that satisfy ACN supply-chain provenance requirements, compressing certification timelines for critical infrastructure bids.
For New Entrants and Emerging Players: Southern Italy's underdeveloped data center density in Sicily and Apulia represents the most penetrable entry point for edge storage serving Mediterranean submarine cable terminations with minimal incumbent saturation. AGID-ACN dual compliance service bundles offer a differentiated go-to-market angle for public-sector cloud qualification.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because consumption-based financing models are transferring refresh risk to service providers and concentrating procurement relationships among capital-light operators. Acquisition targets should display software-defined storage expertise with native cross-platform replication capabilities. The signal to watch is EU Data Act portability rule finalization timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Consumption-Based Financing Launch | Turin managed service providers are transferring refresh risk from mid-market enterprise balance sheets. |
| Localized Assembly Partnership | Huawei Technologies navigates ACN vetting timelines through Italian-registered legal entities with technical support. |
| NVMe-over-TCP Architecture Migration | Milan banks reduce re-cabling investment while preserving sub-100 microsecond latency for fraud detection. |
| Edge Storage Deployment | Sicilian logistics hubs deploy converged NVMe-compute nodes for real-time quality control with cable backhaul. |
| ACN Cybersecurity Accreditation | Domestic system integrators consolidate procurement relationships toward accredited vendors with provenance documentation. |
Research Methodology
The analysis maps HDD, SSD, hybrid, and tape storage architectures, each validated through primary interviews with data center infrastructure directors, storage engineering leads at Lombardy financial institutions, ACN certification officers, and AGID cloud qualification specialists. Secondary validation drew from ACN cybersecurity perimeter guidelines, AGID public-sector procurement databases, EU AI Act risk-tier documentation, and hyperscaler capex disclosures. Bottom-up capacity deployment estimates and top-down market sizing were triangulated to anchor projections.
Assumptions held fixed include ACN vetting timeline durations and AGID qualification protocols, while NAND flash foundry allocation and EU Data Act implementation timing were varied across scenarios. The forecast framework spans product type, deployment model, end-user scale, and interface technology dimensions throughout the projection horizon. CAGRs were derived from segment-level capacity expansion trajectories and refresh cycle compression rates, with AI inference workload penetration and financial services virtualization intensity serving as primary demand inputs.
Stress conditions across NAND supply concentration, ACN certification backlog duration, and hyperscaler facility commissioning delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions that may require revision if regulatory timelines shift or supply chain disruptions materialize. Cross-checking against AGID public-sector procurement award data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Netherlands Data Center Storage Market
Storage Solutions
Brazil Data Center Storage Market
Storage Solutions
Philippines Data Center Storage Market
Storage Solutions
Storage Software Market
Storage Solutions
Global All-Flash Array Market
Storage Solutions
Data Backup and Recovery Market
Storage Solutions
Disk Based Data Fabric Market
Storage Solutions
UK Data Center Storage Market
Storage Solutions
Stand Alone Cloud Storage Market
Storage Solutions
Vietnam Data Center Storage Market
Storage Solutions
Austria Data Center Storage Market
Storage Solutions
Virtual Machine Backup and Recovery Market
Storage Solutions
Mexico Data Center Storage Market
Storage Solutions
Global in Memory Data Grid Market
Storage Solutions
Global Cloud Object Storage Market
Storage Solutions
Global Ethernet Storage Fabric Market