
 Patent Management Software Market | 2026-2036
Patent Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Patent Management Software Market Outlook
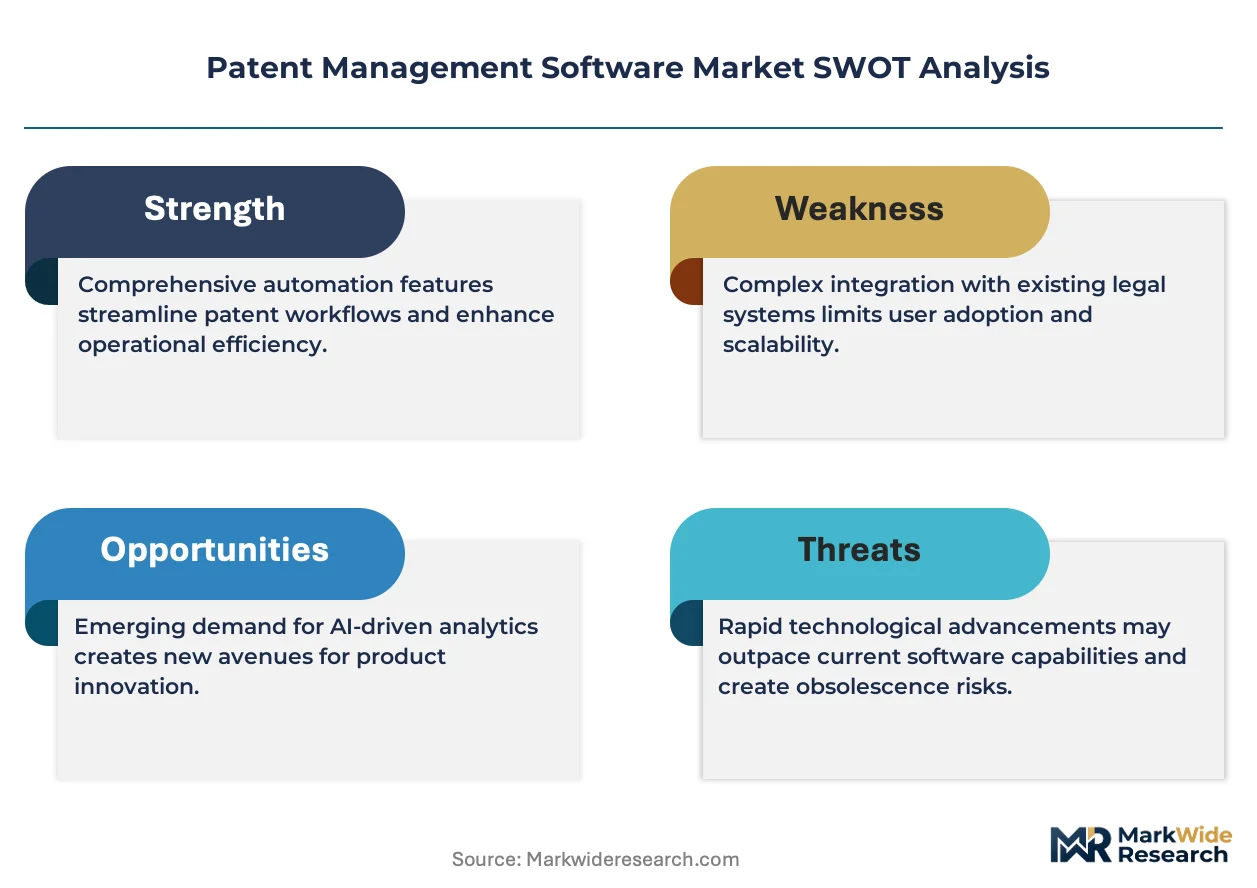
Subscription-based analytics tiers is restructuring how patent management platforms capture recurring revenue. Anaqua leverages deep integration with prosecution workflows to anchor enterprise accounts across diversified technology portfolios. CPA Global competes through extensive geographic coverage and renewal management automation. PatSnap differentiates by embedding machine learning into prior art search and competitive intelligence modules.
Patent management software comprises digital platforms that track filing deadlines, monitor maintenance fees, analyze portfolio strength, and automate correspondence with patent offices through structured data interfaces. These systems process bibliographic metadata, claim language, and legal status events to reduce administrative risk and support strategic IP decision-making. Cloud-based deployments now lead functionality expansion as law firms and corporations prioritize remote access and API connectivity. IP Portfolio Management segments command the deepest margin pools due to multi-module bundling and long implementation cycles. Analytics Tools represent the fastest-growing functionality area as buyers demand predictive litigation risk scoring and technology landscape mapping.
The USPTO electronic filing mandates and the European Patent Office's evolving data exchange protocols shape platform interoperability requirements. ISO 27001 certification and GDPR-compliant data residency controls determine vendor eligibility for cross-border corporate deployments. Stakeholders must monitor how generative AI integration changes examiner search practices and whether patent offices formalize machine-readable disclosure standards.
Market Dynamics
Generative AI integration is compressing prior art search cycles and forcing incumbent platforms to rearchitect their analytics engines around large language model pipelines. USPTO examiner workflows and corporate IP department staffing models are both recalibrating around these capabilities.
Growth Catalysts
- USPTO Electronic Filing Mandates:Complete transition to digital prosecution interfaces compels law firms to upgrade legacy docketing infrastructure. Platform vendors capture replacement revenue as paper-based workflows phase out.
- Semiconductor Patent Surge:Chip architecture disputes and R&D tax credit optimization drive technology companies toward automated portfolio analytics. Complex claim mapping requirements favor sophisticated software deployments.
- GDPR-Compliant Data Residency:Cross-border corporate IP departments require region-locked cloud instances. Vendors with EU and Asia-Pacific data center certifications unlock enterprise procurement pipelines.
Market Restraints
- Specialized Talent Scarcity:Patent informatics professionals with both legal domain knowledge and machine learning engineering skills command premium compensation. Hiring friction slows vendor R&D velocity.
- Legacy System Entrenchment:Large law firms operate decades-old custom docketing databases with deep workflow integration. Migration costs and partner resistance extend sales cycles.
- Input Cost Concentration:Cloud compute and API access for AI-powered prior art search concentrate with hyperscale providers. Vendor margin pressure intensifies as inference costs scale with usage.
Strategic Opportunities
- India Manufacturing IP Expansion:Production-linked incentive schemes accelerate domestic R&D filings. Local patent agent networks seek affordable cloud-native management tools.
- EU AI Act Compliance Layer:Mandatory documentation standards for AI-generated patent applications create demand for audit-trail modules. First movers capture regulatory technology budgets.
- API-First Ecosystem Integration:Direct connectivity with enterprise ERP and litigation finance platforms replaces siloed deployments. Channel partnerships with legal tech marketplaces open mid-market access.
Industry Challenges
- Interoperability Fragmentation:National patent offices maintain incompatible data exchange formats. Vendors absorb ongoing engineering costs to maintain multi-jurisdiction filing connectivity.
- Validation Timeline Compression:ISO 27001 and SOC 2 certification cycles stretch 12-18 months. Enterprise procurement gates delay revenue recognition for emerging vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patent Management Software Market |
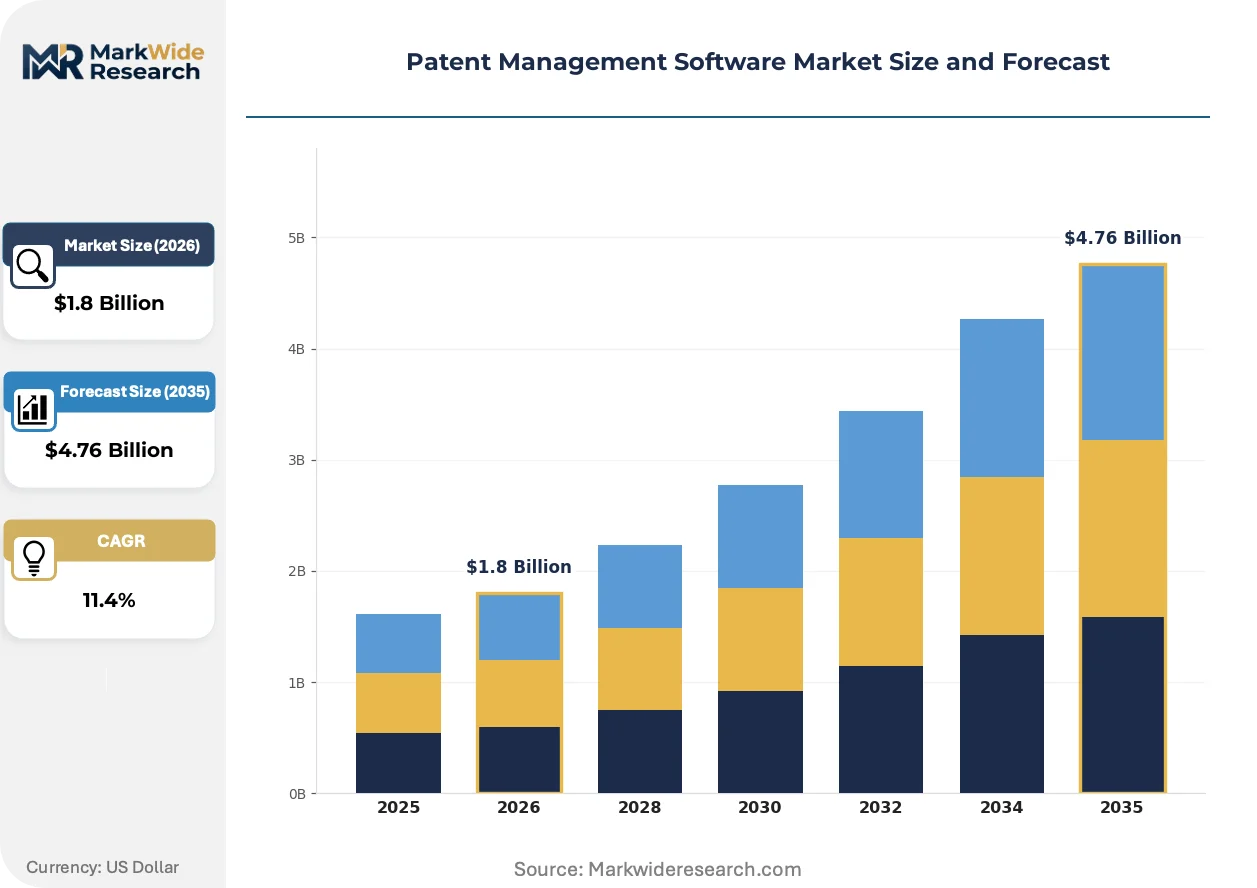
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Online Platforms, Integration Tools, Mobile Applications Deployment: Cloud-Based, On-Premises, Hybrid Solutions, SaaS End User: Law Firms, Corporations, R&D Institutions, IP Consultancies Functionality: IP Portfolio Management, Filing Tracking, Renewal Notifications, Analytics Tools |
| Companies Covered | Anaqua, CPA Global, PatSnap, Questel, IPfolio, Clarivate FoundationIP, Innography, MaxVal, LexisNexis PatentSight, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patent Management Software Market Strategic Shifts
Natural language processing capabilities are collapsing the distinction between patent search and strategic intelligence functions. Platform architectures now prioritize semantic understanding over keyword indexing.
Large language model fine-tuning on patent claim corpora is rewriting how prior art relevance scoring operates. Fortune 500 IP departments and specialized litigation boutiques are deploying these systems for invalidity and freedom-to-operate analyses. The technology is compressing research timelines from weeks to hours while elevating strategic counsel roles over manual document review.
The USPTO's AI-assisted examination pilot and corresponding examiner training protocols are reshaping prosecution strategy. Patent applicants now anticipate algorithmic prior art retrieval and front-load specification detail. Pharmaceutical and biotechnology filings show the most pronounced adjustment, with claim construction evolving to satisfy both human and machine reviewers.
Corporate legal departments are unbundling analytics subscriptions from full-platform implementations. Procurement teams negotiate standalone competitive intelligence modules while retaining incumbent docketing providers. This pattern is most visible among mid-cap technology companies in the United States, where CFO oversight of legal spend has intensified post-2022.
Patent Management Software Market Segmentation
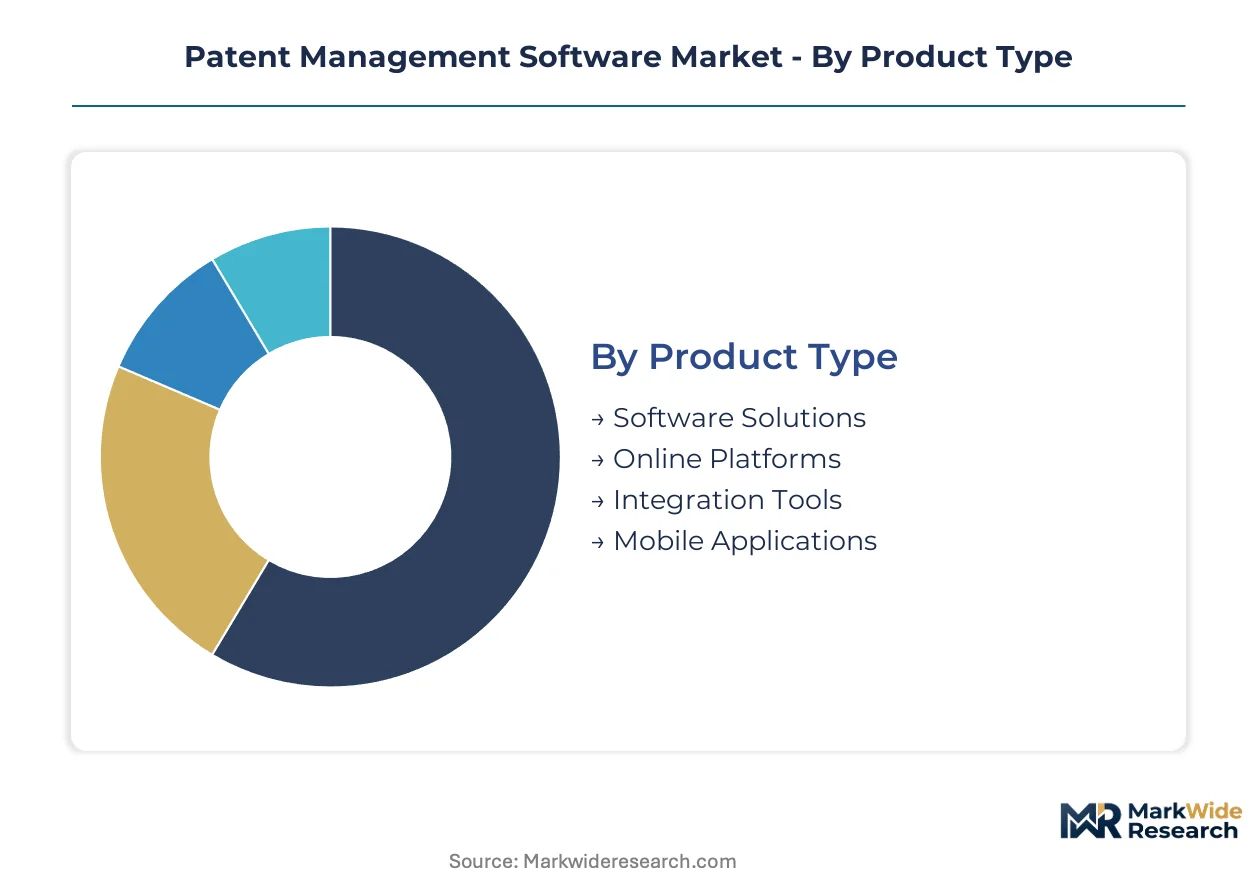
Patent management software segmentation reveals how capital allocation and technical requirements diverge across buyer types. Cloud infrastructure investments, compliance certification costs, and integration complexity create distinct tiering that shapes vendor go-to-market strategies and pricing architectures.
Product Type:
Capital intensity concentrates in integration layers and enterprise software stacks rather than surface-level applications.
- Software Solutions:Comprehensive desktop and server-based platforms handle docketing, document generation, and USPTO electronic filing interfaces. Fortune 500 legal departments in the United States drive demand for these systems as they replace legacy paper-based prosecution workflows. Most installed capacity flows through Software Solutions. Expansion is steepest in Online Platforms.
- Online Platforms:Browser-accessible systems deliver real-time collaboration across distributed IP teams and external counsel networks. Mid-market technology corporations in semiconductor and pharmaceutical sectors favor these deployments for remote claim drafting and examiner response preparation.
- Integration Tools:API middleware and ERP connectors synchronize patent data with corporate financial and R&D systems.
- Mobile Applications:Smartphone-optimized interfaces provide deadline alerts and document review for traveling attorneys.
Software Solutions absorb the majority of enterprise procurement budgets. Online Platforms are climbing the fastest as cloud-native architectures displace on-premises licensing.
Deployment:
Technical debt and data sovereignty requirements fragment buyer preferences across infrastructure models.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server maintenance burdens and enable automatic feature updates. GDPR-compliant EU data centers and US FedRAMP authorization unlock procurement at cross-border pharmaceutical and defense contractors. Cloud-Based deployments command the deepest margin pools due to subscription scalability and reduced implementation friction. SaaS is gaining share fastest among new buyers.
- SaaS:Subscription-native platforms with usage-based tiers attract mid-market IP consultancies and boutique law firms seeking predictable operational expenditure.
- On-Premises:Air-gapped installations serve government laboratories and classified R&D facilities with mandatory physical data control.
- Hybrid Solutions:Split architectures keep sensitive claim language on local servers while pushing docketing alerts to cloud instances.
Cloud-Based installations dominate new contract volume. Hybrid Solutions are expanding most quickly as regulated industries navigate compliance complexity.
End User:
Procurement sophistication and module bundling appetite vary sharply across organizational buyer types.
- Corporations:In-house IP departments at technology and life sciences companies purchase integrated platforms spanning portfolio analytics, competitive intelligence, and maintenance fee optimization. United States-based semiconductor firms drive premium deployments with complex multi-jurisdiction filing requirements. Corporations represent the largest addressable spend pool. IP Consultancies are expanding most quickly.
- Law Firms:Am Law 200 practices and specialized boutiques prioritize docketing accuracy and USPTO deadline compliance above advanced analytics.
- R&D Institutions:University technology transfer offices and national laboratories seek affordable solutions for provisional filing tracking and licensee monitoring.
- IP Consultancies:Independent advisors and patent agent networks demand lightweight, per-matter pricing without long-term enterprise commitments.
Corporations generate the highest average contract values. IP Consultancies are climbing the fastest as fractional IP management services proliferate.
Functionality:
Feature depth and implementation complexity create distinct margin tiers across software modules.
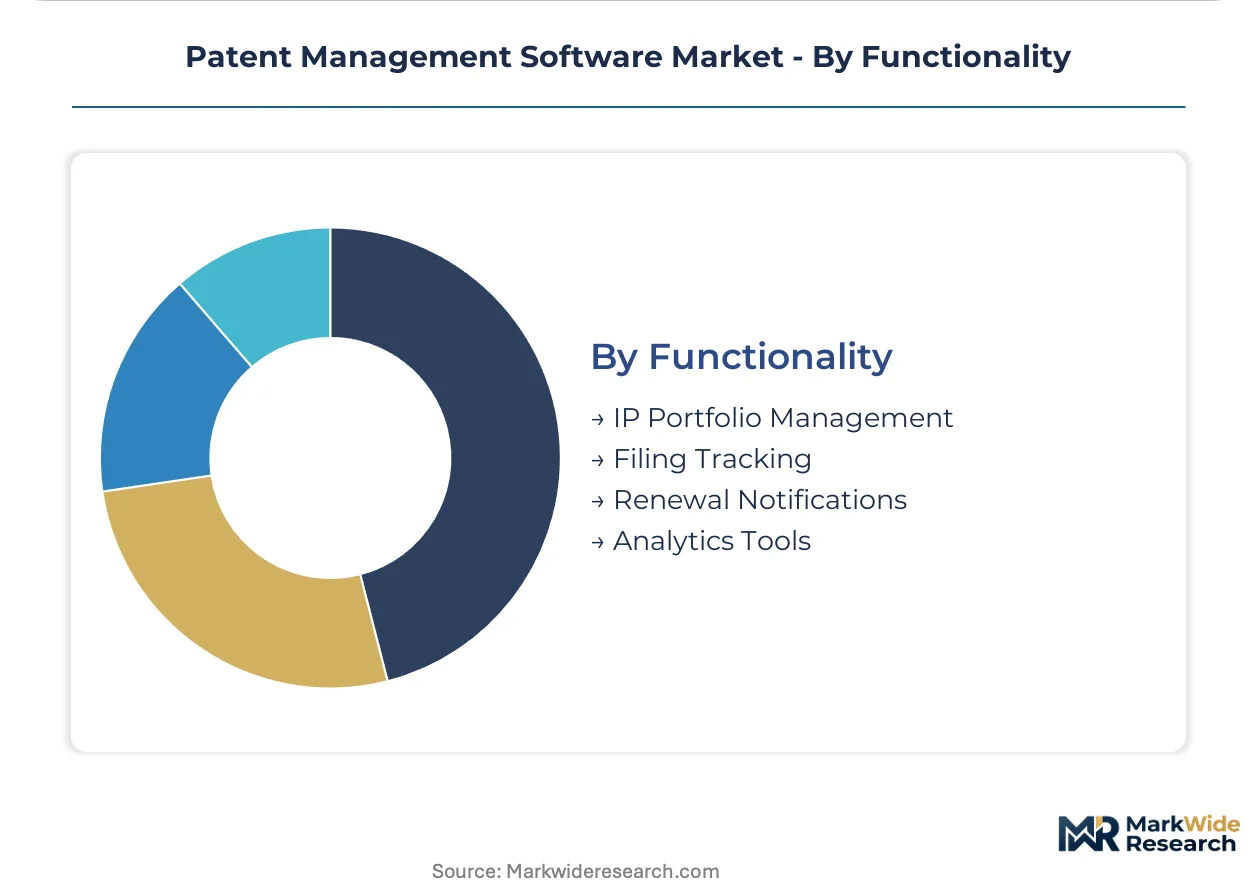
- IP Portfolio Management:Multi-module suites combine docketing, spend analysis, and strategic planning dashboards for enterprise patent estates. Pharmaceutical companies in the United States leverage these systems to map therapeutic area coverage and identify pruning candidates for maintenance fee reduction. IP Portfolio Management commands the steepest pricing premiums and longest sales cycles. Analytics Tools are expanding most quickly.
- Analytics Tools:Machine learning-powered prior art search, litigation risk scoring, and technology landscape mapping compress research timelines from weeks to hours.
- Filing Tracking:Deadline monitoring and prosecution milestone alerts form the baseline functionality for all buyer segments.
- Renewal Notifications:Automated maintenance fee deadline management prevents inadvertent patent lapses due to administrative oversight.
IP Portfolio Management anchors the largest contract values. Analytics Tools are gaining share fastest as generative AI integration reshapes buyer expectations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States captures the deepest patent management software procurement budgets, while Germany's export-oriented manufacturing base generates comparable per-capita platform adoption intensity. Japan's semiconductor patent surge and India's production-linked incentive expansion create divergent growth trajectories across the Pacific corridor.
United States
Fortune 500 legal departments in technology and life sciences sectors anchor enterprise platform deployments, with semiconductor firms driving premium multi-jurisdiction implementations. USPTO electronic filing mandates compel law firm infrastructure upgrades, accelerating replacement cycles for legacy docketing systems. The Greater Boston and San Francisco Bay Area clusters concentrate boutique IP practices adopting AI-assisted prior art search modules.
Germany
Industrial machinery and automotive patent portfolios demand sophisticated claim mapping and freedom-to-operate analytics from Mittelstand engineering firms. EPO data exchange protocol compliance shapes vendor selection criteria for cross-border corporate IP departments. The Munich and Stuttgart metropolitan regions host dense concentrations of patent attorney networks transitioning to cloud-native management tools.
China
Domestic R&D filing volume expansion and NMPA regulatory data requirements propel state-owned pharmaceutical enterprises toward integrated portfolio platforms. MIIT standards for electronic patent documentation accelerate government laboratory procurement of air-gapped installation systems. The Yangtze River Delta and Pearl River Delta technology corridors concentrate independent patent agent networks seeking affordable SaaS docketing solutions.
Japan
Semiconductor equipment manufacturers and materials science conglomerates deploy predictive litigation risk scoring for complex cross-licensing negotiations. METI intellectual property strategy guidelines incentivize corporate IP department automation investments. The Tokyo-Osaka corridor anchors specialized litigation boutiques adopting machine learning-powered invalidity analysis modules.
India
Production-linked incentive schemes for electronics and pharmaceutical manufacturing accelerate domestic patent filing growth among contract research organizations. BIS certification requirements for software procurement shape vendor eligibility for public sector R&D institutions. The Bengaluru and Hyderabad technology clusters concentrate mid-market IP consultancies seeking per-matter pricing without long-term enterprise commitments.
Patent Management Software Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with enterprise legal departments favoring integrated platform suites while boutique practices prioritize modular subscription tiers. The vendor base concentrates around three strategic archetypes: prosecution workflow specialists, analytics-native disruptors, and geographic coverage incumbents. M&A activity targets machine learning engineering talent and ISO 27001-certified data center infrastructure. Portfolio diversification moves emphasize API-first ecosystem integration over standalone feature expansion.
Within the enterprise platform tier, Anaqua, CPA Global, and PatSnap occupy positions reflecting distinct competitive positioning vectors. Anaqua exemplifies deep prosecution workflow integration for diversified technology portfolios. CPA Global represents extensive geographic coverage and renewal management automation capabilities. PatSnap anchors the analytics-native archetype through machine learning embedding in prior art search and competitive intelligence functions.
| Leading Market Players |
|---|
| Anaqua |
| CPA Global |
| PatSnap |
| Questel |
| IPfolio |
| Clarivate FoundationIP |
| Innography |
| MaxVal |
| LexisNexis PatentSight |
| Others |
Value Chain & Pricing Dynamics
Captive cloud infrastructure development in hyperscale data centers anchors vendor cost positions and pricing power in patent management software. Vendors with owned server deployments in the United States, Germany, and Singapore command margin advantages over competitors renting compute from third-party providers, while procurement teams at Fortune 500 legal departments exploit this supplier stratification during enterprise SaaS negotiations.
Pricing Analysis
Capacity additions in Ireland and Singapore are reshaping price floors for GDPR-compliant cloud instances serving European corporate IP departments. Three-tier pricing structure across premium, standard, and economy levels segments buyer archetypes, with ISO 27001 certification and FedRAMP authorization driving premium tier qualification. Cost compression in standard tiers is intensifying because hyperscale API access fees for AI-powered prior art search scale with usage volume. Mid-market technology companies exhibit the highest price sensitivity, while defense contractors and pharmaceutical firms show inelastic demand for air-gapped premium deployments.
Supply Chain Analysis
Dual-sourcing requirements from enterprise procurement teams mandate multi-supplier qualification for both cloud compute and machine learning engineering talent. Supply concentration rests on the United States, Ireland, and Singapore for certified data center infrastructure, while specialized patent informatics professionals draw from India, Poland, and Romania. Single-source vulnerability in large language model API providers creates contingency planning overhead for analytics-native vendors. Distribution runs through direct enterprise sales teams and legal technology marketplaces serving boutique IP practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patent management software constitutes a late-cycle quality story as corporate legal departments shift procurement criteria toward predictive litigation risk scoring and generative AI integration. This demand migration favors vendors with certified infrastructure and machine learning engineering depth over legacy docketing providers.
For Market Incumbents: Hedge against margin erosion in commoditized docketing modules by deepening ISO 27001-certified data center footprints in the Asia-Pacific region. Acquire machine learning engineering teams with patent claim corpus fine-tuning experience to defend analytics subscription renewal rates against specialized AI-native entrants. For New Entrants and Emerging Players: Capture white-space opportunity in India's production-linked incentive-driven patent filing surge among contract research organizations. Target per-matter pricing models for IP consultancies in Bengaluru and Hyderabad seeking lightweight cloud-native tools without enterprise implementation cycles. For Investors and Strategic Acquirers: Roll-up economics work for analytics-native specialists because corporate procurement teams are unbundling competitive intelligence subscriptions from incumbent docketing platforms. Monitor USPTO examiner training protocol updates as the inflection signal for generative AI adoption velocity across prosecution workflows.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API connectivity with ERP systems anchors enterprise renewal rates at Fortune 500 legal departments. |
| Acquisition of Specialist Firm | Machine learning engineering teams with patent corpus expertise compress product development timelines. |
| Geographic Expansion | EU data center certification unlocks GDPR-compliant procurement at cross-border pharmaceutical firms. |
| Strategic Partnership | Legal technology marketplace alliances open mid-market access for per-matter pricing tiers. |
| Product Launch | Audit-trail modules for EU AI Act compliance capture regulatory technology budgets ahead of mandates. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with IP portfolio directors, legal technology procurement officers, patent informatics specialists, and cloud infrastructure architects with secondary validation against USPTO electronic filing statistics, EPO data exchange protocol documentation, hyperscaler capex disclosures, and enterprise software procurement databases. Bottom-up deployment counts and top-down market sizing triangulated volume estimates across the analysis window.
Comparable-period anchoring tied projection assumptions to historical adoption curves for cloud-based legal technology and electronic filing mandate compliance cycles. Segmentation modeling incorporated deployment model, organization size, vertical industry, integration complexity, and regional data residency requirements. CAGRs derived from fitted growth curves applied to validated baseline estimates, with inputs including examiner workflow automation timelines and corporate R&D tax credit optimization patterns.
Generative AI integration delays, patent office machine-readable disclosure standard revisions, and hyperscale API pricing volatility are the dominant revision risks to forecast assumptions. Deviation in USPTO examiner training protocol rollout speed would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Architecture Design Software Market
Software & Services
Global Travel and Expense Management Software Market
Software & Services
Game Development Software Market
Software & Services
Weather Forecast Software Market
Software & Services
Sales Gamification Software Market
Software & Services
Programming Language Market
Software & Services
Royalty Management Software and Services Market
Software & Services
Architecture, Engineering, and Construction (AEC) Software Market
Software & Services
Drone Mapping Software Market
Software & Services
US Enterprise Legal Management Software Market
Software & Services
Sales Platforms Software Market
Software & Services
Online Project Management Software Market
Software & Services
Attendance Management Software Market
Software & Services
Global Project Software Market
Software & Services
HACCP Software Market
Software & Services
Mining Software Market