
 Japan Data Center Networking Market | 2026-2036
Japan Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Data Center Networking Market Insights
Cloud service providers is bifurcating the buyer landscape away from traditional enterprise IT departments as hyperscale operators command larger procurement volumes and custom silicon requirements. Arista Networks dominates high-performance spine-leaf architectures for these facilities, while Cisco Systems anchors its position through integrated security and automation stacks. NEC Corporation differentiates via domestic manufacturing and compliance with Japan-specific operational standards.
Data center networking encompasses the switching, routing, and interconnect fabric that enables server-to-server and facility-to-internet communication, typically operating at 100Gbps to 400Gbps per port with sub-microsecond latency targets for financial and AI workloads. Switches capture the largest margin pool as port densities rise to support GPU clusters, while InfiniBand gains share in high-performance computing installations where bandwidth outranks cost efficiency. Ethernet sustains its volume leadership across cloud and enterprise deployments through backward compatibility and broad vendor support.
METI enforces energy efficiency benchmarks through its Data Center Energy Efficiency Guidelines, while JIS standards govern physical infrastructure resilience against seismic events. The Ministry of Internal Affairs and Communications coordinates spectrum policy for wireless backup links and edge facility connectivity. Stakeholders must weigh the capital intensity of 800G-ready switching against the operational risk of stranding 400G assets before depreciation cycles complete.
Market Dynamics
Hyperscale cloud operators are compressing procurement cycles and demanding custom silicon configurations, forcing incumbent vendors to rearchitect supply chains around GPU-optimized switching fabrics rather than general-purpose enterprise gear.
Growth Catalysts
- AI Training Clusters:Domestic financial institutions and pharmaceutical firms are deploying dedicated GPU interconnects for quantitative modeling and molecular simulation workloads, requiring 400Gbps spine-leaf fabrics.
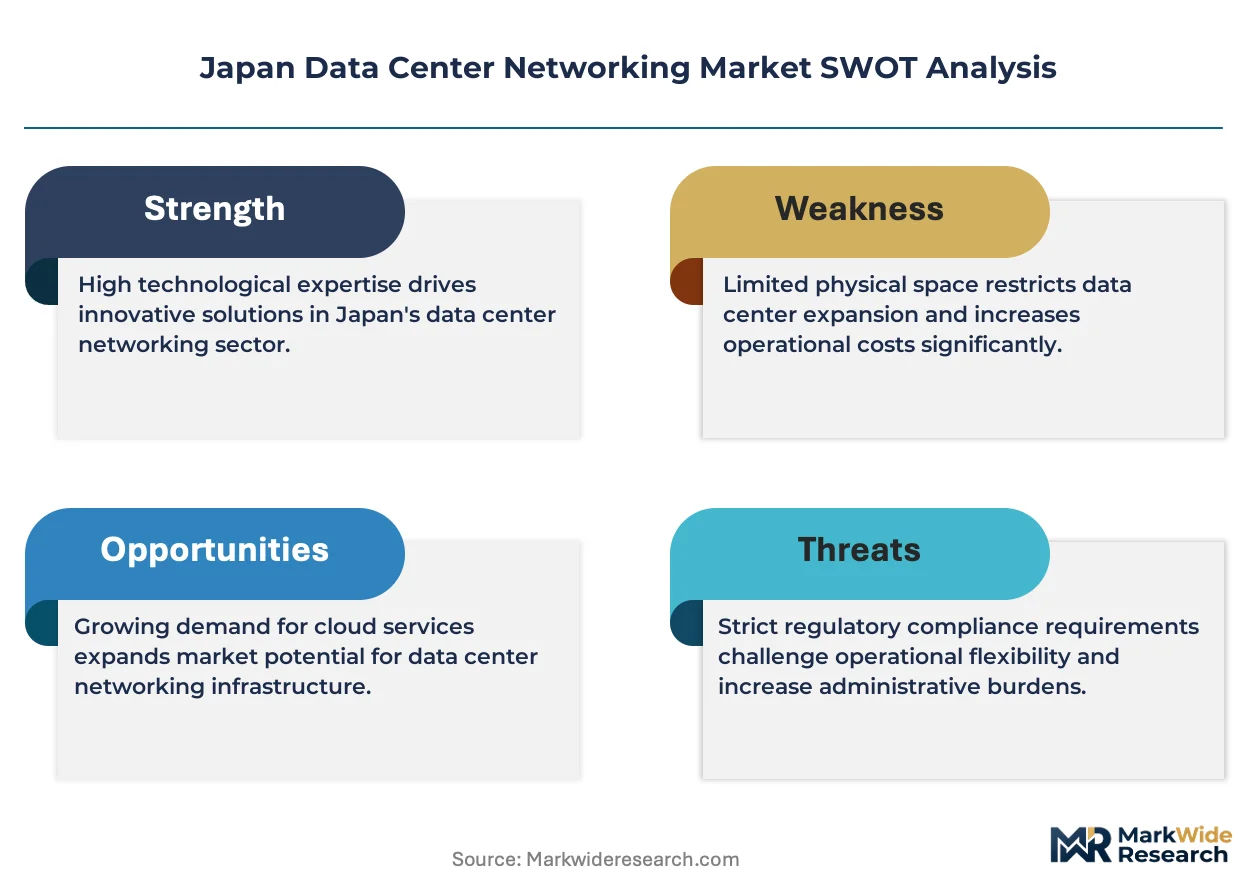
- METI Efficiency Mandates:The ministry's Data Center Energy Efficiency Guidelines create procurement preference for liquid-cooled networking equipment, accelerating refresh cycles in legacy Tokyo facilities.
- Submarine Cable Landings:New fiber optic terminus points in Chiba and Kanagawa prefectures are pulling hyperscale investment toward Greater Tokyo, concentrating demand for high-density interconnect hardware.
Market Restraints
- Silicon Supply Concentration:Advanced switching ASICs depend on single-source foundry capacity in Taiwan, exposing Japanese operators to geopolitical transit risk and allocation constraints.
- Power Grid Saturation:TEPCO's eastern Japan network faces capacity reservation limits, capping facility expansion in the primary demand cluster regardless of capital availability.
- Copper Interconnect Persistence:Legacy enterprise data centers retain 10Gbps copper DAC cabling, creating technical debt that slows full-fiber upgrades and fragments procurement volumes.
Strategic Opportunities
- Osaka-Kobe Corridor:Western Japan's secondary fiber hub remains underserved by hyperscale presence, offering first-mover positioning for edge networking infrastructure.
- Co-Packaged Optics Convergence:Integration of silicon photonics with switch ASICs enables 800Gbps port economics, collapsing power-per-bit metrics for AI training fabrics.
- JIS Seismic Certification:Compliance with earthquake resilience standards opens export pathways to other Pacific Rim markets with similar structural requirements.
Industry Challenges
- Optical Engineering Talent:Coherent DSP and silicon photonics design capabilities concentrate in a handful of domestic research institutes, constraining product development velocity.
- Multi-Vendor Orchestration:Hyperscale operators demand unified control planes across switching hardware from disparate suppliers, forcing complex API harmonization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Data Center Networking Market |
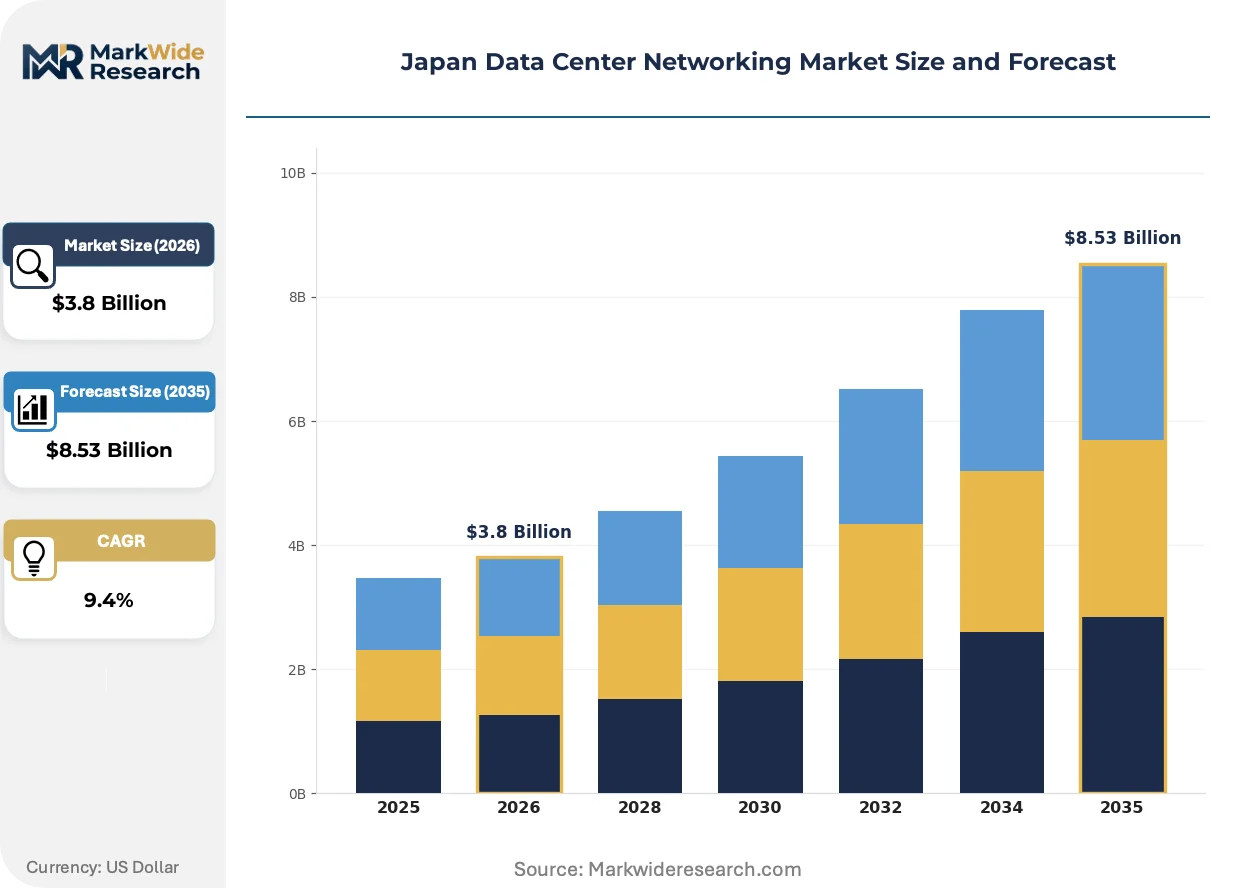
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Firewalls, Network Adapters End User: Telecommunications, Cloud Service Providers, Enterprises, Government Agencies Technology: Ethernet, InfiniBand, Fibre Channel, Wireless Installation: On-premises, Cloud-based, Hybrid, Managed Services |
| Companies Covered | Cisco Systems Inc, Arista Networks Inc, Huawei Technologies Co Ltd, VMware Inc, H3C Technologies Co Ltd, NEC Corporation, Dell Technologies Inc, Extreme Networks Inc, Hewlett Packard Enterprise Development LP, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Data Center Networking Market Trends and Innovations
Networking architectures are fragmenting into workload-optimized designs as AI traffic patterns diverge from traditional enterprise flows, compelling vendors to abandon one-size-fits-all platform strategies.
Disaggregated chassis designs are decomposing monolithic switch hardware into modular subsystems. Hyperscale operators in Saitama and Chiba prefectures are adopting these architectures to mix-and-match merchant silicon with custom forwarding engines. This decomposition is compressing hardware refresh intervals from five-year cycles to eighteen-month increments as individual subsystems upgrade independently.
METI's 2024 revision to Data Center Energy Efficiency Guidelines tightens PUE reporting requirements and mandates liquid cooling readiness for new facilities above 10MW capacity. The regulation forces incumbent operators in central Tokyo to retrofit existing plants rather than pursue greenfield construction. Colocation providers are responding by consolidating smaller facilities into certified hyperscale campuses in peripheral prefectures.
Consumption patterns among Japanese enterprises are fragmenting procurement authority. Central IT departments retain governance over security policy while line-of-business units gain direct contracting power for cloud-adjacent networking gear. This bifurcation is most visible in Osaka's manufacturing sector, where factory automation teams now source industrial Ethernet switches independently of corporate network architects, creating parallel vendor engagement channels.
Japan Data Center Networking Market Segmentation
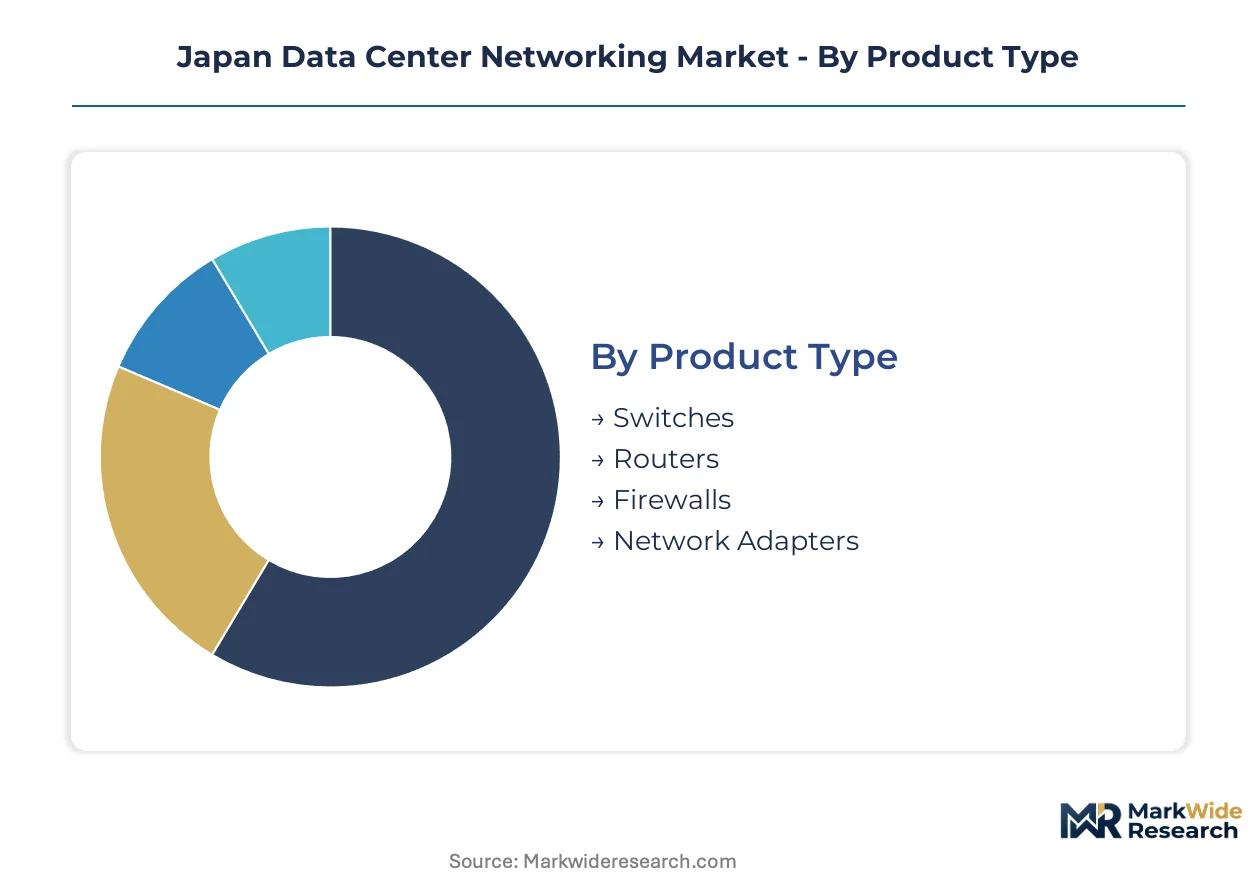
Segmentation in Japan's data center networking market reveals how procurement authority is fragmenting across buyer types and deployment models. Understanding these divisions exposes where vendor margins concentrate and where refresh cycles accelerate under METI efficiency mandates.
Product Type:
Margin pools concentrate in switching hardware where port density premiums and custom silicon configurations command pricing power from hyperscale operators.
- Switches:Spine-leaf architectures dominate hyperscale deployments, with 400Gbps port densities now standard for GPU cluster interconnects. Financial institutions in Tokyo's Otemachi district drive demand for sub-microsecond latency variants. Arista Networks and Cisco Systems capture premium positioning through merchant silicon differentiation and integrated automation stacks.
- Routers:Border gateway infrastructure handles facility-to-internet traffic at submarine cable landing points in Chiba and Kanagawa. Cloud service providers demand terabit-scale forwarding capacity with programmable pipeline architectures for traffic engineering flexibility.
- Firewalls:East-west microsegmentation requirements are displacing perimeter-only security models in multi-tenant colocation facilities.
- Network Adapters:SmartNICs with onboard DPUs are gaining traction for computational offloading in AI training clusters.
The dominant share belongs to Switches, while Network Adapters are closing the gap fastest as computational offload requirements reshape server connectivity.
End User:
Volume concentration tracks capital deployment cycles, with cloud service providers compressing procurement timelines through direct silicon sourcing relationships.
- Cloud Service Providers:Hyperscale operators in Saitama and Chiba prefectures command custom switch configurations with eighteen-month refresh intervals. These buyers disaggregate hardware procurement from software licensing, forcing incumbent vendors to unbundle traditional enterprise bundles.
- Telecommunications:NTT and KDDI operate carrier-neutral facilities requiring interoperability certification across multi-vendor environments. Their procurement emphasizes JIS-compliant physical infrastructure for seismic resilience.
- Enterprises:Manufacturing and pharmaceutical firms in Osaka deploy hybrid architectures balancing on-premises control with burst capacity to cloud.
- Government Agencies:METI and MIC procurement guidelines prioritize energy efficiency ratings and domestic supply chain provenance.
Cloud Service Providers command the largest procurement volumes, though Government Agencies are expanding fastest under digital sovereignty initiatives.
Technology:
Application requirements dictate protocol selection, with bandwidth-density tradeoffs separating AI training fabrics from general-purpose enterprise traffic.
- Ethernet:IEEE 802.3 standards sustain volume leadership through backward compatibility and broad vendor interoperability. Cloud and enterprise deployments standardize on 100Gbps to 400Gbps per port with migration paths to 800Gbps coherent optics.
- InfiniBand:NVIDIA's interconnect technology dominates high-performance computing installations where bandwidth outranks cost efficiency. RDMA capabilities enable GPU memory pooling across server nodes for molecular simulation workloads.
- Fibre Channel:Storage area networks persist in legacy financial services infrastructure with 32Gbps and 64Gbps generations.
- Wireless:5G private networks and Wi-Fi 6E provide backup connectivity and edge facility access in seismic-resilient architectures.
Ethernet maintains the installed base majority, while InfiniBand is expanding most quickly alongside domestic AI cluster deployment.
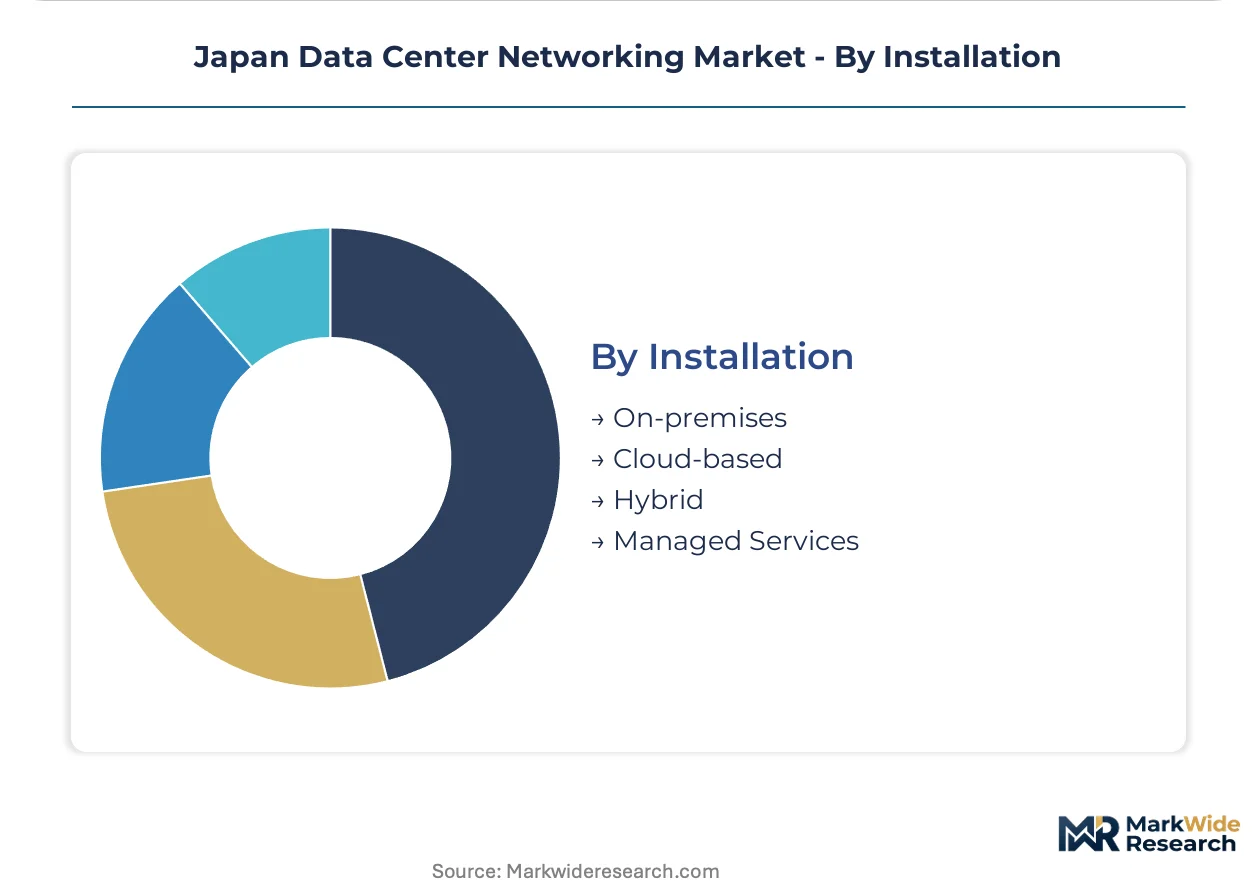
Installation:
Operational model selection reflects capital availability and core competency boundaries, with hybrid architectures emerging as the dominant compromise.
- Hybrid:Workload portability between on-premises and cloud infrastructure demands consistent networking abstractions. Japanese enterprises favor this model to retain data sovereignty while accessing hyperscale burst capacity.
- On-premises:Financial exchanges and defense-adjacent facilities require air-gapped infrastructure with dedicated physical security perimeters.
- Cloud-based:Software-defined networking overlays enable rapid provisioning without hardware procurement cycles.
- Managed Services:Colocation providers offer network operations center staffing for operators lacking internal optical engineering expertise.
Hybrid deployments hold the leading position, with Managed Services climbing fastest as talent constraints push operational outsourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pacific Crossing-1 and Japan-US Cable Network landings at Chiba and Kanagawa prefectures anchor Greater Tokyo's position as East Asia's primary interconnection hub. These submarine fiber termini concentrate hyperscale facility investment along the eastern seaboard. METI's efficiency mandates are redistributing capacity toward peripheral prefectures with available power grid headroom.
Kanto/Tokyo
Financial exchanges in Otemachi and Marunouchi drive sub-microsecond latency requirements for spine-leaf switching fabrics. METI's 2024 Data Center Energy Efficiency Guidelines tighten PUE reporting thresholds above 10MW capacity. Legacy facilities in central Tokyo face retrofit pressure as TEPCO's grid saturation blocks new power reservations in core wards.
Kansai/Osaka
Manufacturing automation teams in Osaka's factory belt now source industrial Ethernet switches independently of corporate IT departments. The Ministry of Internal Affairs and Communications coordinates 5G private network spectrum for edge facility connectivity. Kansai Electric's more favorable capacity allocation is attracting colocation consolidation from Tokyo-constrained operators.
Chubu/Nagoya
Automotive OEM headquarters in Aichi prefecture generate hybrid cloud networking demand for R&D simulation workloads. JIS seismic resilience standards govern physical infrastructure certification for supplier-adjacent data halls. Toyota City and surrounding industrial corridors are emerging as secondary fiber hub candidates.
Kyushu
Fukuoka's undersea cable connections to Busan and Shanghai position the prefecture for cross-border latency-sensitive applications. Local government incentive packages target disaster recovery facility operators seeking geographic separation from Tokyo seismic risk. Saga and Nagasaki prefectures are evaluating renewable energy-powered campus sites.
Japan Data Center Networking Market Competitive Landscape
Concentration sits with merchant silicon specialists and integrated security-stack incumbents who command procurement relationships with hyperscale cloud operators. The vendor base organizes around three strategic archetypes: high-performance switching fabric designers, compliance-focused domestic manufacturers, and automation-integrated platform providers. Competitive dynamics revolve around custom ASIC configuration partnerships and liquid-cooled hardware certification under METI efficiency mandates. Incumbents defend position through eighteen-month refresh cycle alignment with GPU cluster deployment timelines.
Among US-based networking specialists, Cisco Systems Inc and Arista Networks Inc exemplify divergent positioning within the hyperscale procurement channel. Cisco Systems Inc anchors integrated security-automation bundles that appeal to enterprise IT departments retaining governance authority. Arista Networks Inc occupies a position as the reference architecture for cloud service provider spine-leaf deployments at 400Gbps density. NEC Corporation represents the domestic compliance archetype, leveraging JIS seismic certification and local manufacturing presence to secure government and telecommunications procurement. These three anchors illustrate how vendor selection bifurcates between global hyperscale standards and Japan-specific operational requirements.
| Leading Market Players |
|---|
| Cisco Systems Inc |
| Arista Networks Inc |
| Huawei Technologies Co Ltd |
| VMware Inc |
| H3C Technologies Co Ltd |
| NEC Corporation |
| Dell Technologies Inc |
| Extreme Networks Inc |
| Hewlett Packard Enterprise Development LP |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with Taiwan-based foundries lock in switch ASIC allocation while fixing unit costs for hyperscale procurement cycles. These arrangements shield Japanese operators from spot-market volatility in advanced silicon but embed price rigidity when merchant silicon alternatives emerge.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Arista Networks' merchant silicon configurations from Cisco Systems' integrated automation bundles and NEC Corporation's JIS-certified domestic manufacturing. Price differentiation rests on liquid-cooling readiness under METI guidelines and port density ratings for GPU cluster compatibility. Cost compression in standard-tier Ethernet switching is intensifying because cloud service providers disaggregate hardware from software licensing. Government agencies exhibit lowest price sensitivity due to digital sovereignty mandates, while Osaka manufacturing enterprises drive hardest bargain on industrial Ethernet volumes.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for advanced switching ASICs, while Japan retains captive production of optical transceiver components and seismic-resilient chassis assemblies. Raw material dependencies span silicon wafers, III-V compound semiconductors for coherent DSPs, and rare-earth elements for magnetics in power supplies. Single-source vulnerability concentrates in TSMC's 5nm and 3nm node capacity, exposing procurement timelines to geopolitical transit risk. Distribution runs through direct vendor relationships with hyperscale operators and tier-one systems integrators serving enterprise and government accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's data center networking market is accelerating through a structural inflection as METI's liquid-cooling mandates and AI training cluster deployments force eighteen-month hardware refresh cycles. This compression rewards vendors with supply chain agility and punishes asset-heavy incumbents locked into legacy manufacturing footprints.
For Market Incumbents: Consolidate procurement relationships with domestic cloud service providers through custom silicon co-development agreements that preempt merchant silicon substitution. Deepen backward integration into optical transceiver manufacturing to secure supply chain autonomy against Taiwan foundry allocation constraints. Prioritize JIS seismic certification refresh for peripheral prefecture facilities where TEPCO grid saturation redirects hyperscale investment.
For New Entrants and Emerging Players: Managed network operations for Osaka-Kobe manufacturing automation teams represents an underserved service layer where corporate IT departments retain governance but lack optical engineering depth. Target this segment through subscription-based NOC staffing that bundles hardware procurement with operational expertise. Position against NEC Corporation's premium domestic positioning with standardized API-first platforms that reduce multi-vendor orchestration complexity.
For Investors and Strategic Acquirers: Capital is best deployed toward merchant silicon specialists with established spine-leaf reference architectures at 400Gbps density and clear roadmaps to 800Gbps coherent optics. Long-term viability hinges on co-packaged optics convergence timelines and the ability to serve both hyperscale cloud operators and METI-compliant government procurement. Watch for inflection signals in Kansai Electric capacity allocation announcements that presage westward facility migration.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid-Cooling Hardware Certification | METI compliance unlocks procurement preference in Tokyo facilities above 10MW capacity. |
| Co-Packaged Optics Integration | Silicon photonics convergence collapses power-per-bit metrics for AI training fabrics. |
| Custom Silicon Partnership | GPU-optimized switching configurations secure eighteen-month refresh cycle alignment. |
| Osaka-Kobe Corridor Expansion | Western Japan's fiber hub offers first-mover positioning for edge networking infrastructure. |
| JIS Seismic Certification Export | Earthquake resilience standards open pathways to Pacific Rim markets with similar requirements. |
Research Methodology
A standing panel of hyperscale network architects, colocation facility operators, METI policy officers, and optical transceiver procurement managers provided ongoing calibration against market developments. Primary interview insights were cross-referenced with secondary validation from SEC filings of US-based networking vendors, Japanese customs data on optical component imports, METI Data Center Energy Efficiency Guidelines documentation, and TEPCO grid capacity reservation disclosures. Bottom-up demand modeling from individual facility expansion announcements was reconciled with top-down market sizing through triangulation across these independent sources.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across product type, end user archetype, protocol technology, and installation operational model, with additional dimensioning for liquid-cooling readiness certification. CAGRs were derived from fitted growth curves anchored to disclosed hyperscaler capex trajectories and METI regulatory implementation timelines. Forecast inputs incorporated GPU cluster deployment densities per rack and submarine cable landing capacity expansion schedules.
Forecasts assume regulatory continuity in METI efficiency mandates and JIS seismic standards; material policy shifts would require re-modeling of facility retrofit economics and procurement preference structures. Specific risks that could revise projections include Taiwan Strait logistics disruption, accelerated coherent optics substitution timelines, and TEPCO grid interconnection moratoria extension. Recalibration cycles align with material shifts in hyperscale capital deployment patterns and METI guideline revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Dedicated Internet Access Market
Data Center and Networking
Edge Server Market
Data Center and Networking
Virtual Data Optimizer Market
Data Center and Networking
Global Virtual Network Functions Market
Data Center and Networking
Australia Data Center Networking Market
Data Center and Networking
Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market
Data Center and Networking
Network Slicing Market
Data Center and Networking
Philippines Data Center Networking Market
Data Center and Networking
Dynamic Data Management System Market
Data Center and Networking
Belgium Data Center Networking Market
Data Center and Networking
Global Optical Communication and Networking Market
Data Center and Networking
Vietnam Data Center Networking Market
Data Center and Networking
Data Center Servers Market
Data Center and Networking
Global Data Warehouse Market
Data Center and Networking
Global Cloud Content Delivery Network Market
Data Center and Networking
Data Center Market