
 Online Lottery Software Market | 2026-2036
Online Lottery Software Market Size, Share, and Industry Trends Forecast 2026-2036
Online Lottery Software Market Insights
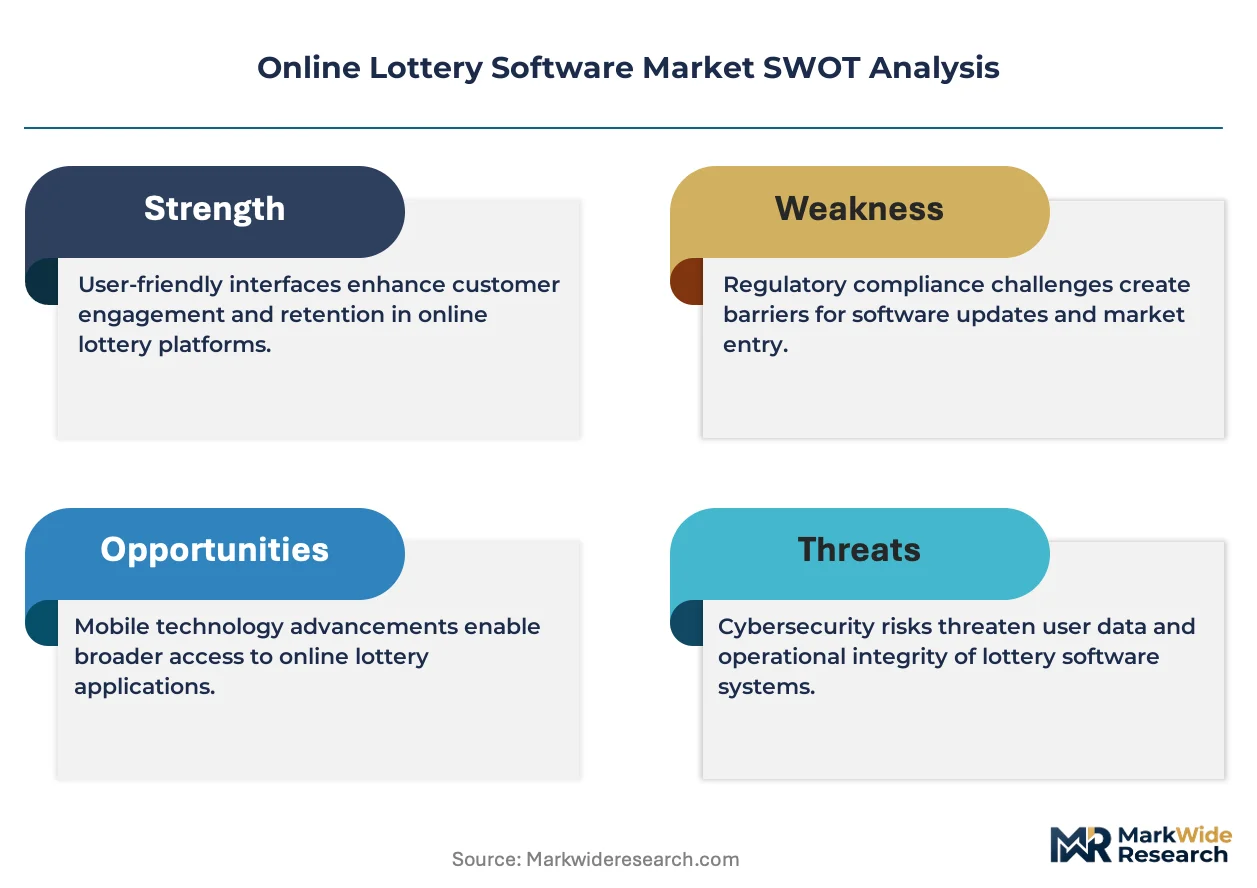
The capital-intensity divergence between platform-native developers and legacy hardware suppliers is bifurcating competitive dynamics across the sector. IGT leverages its installed base of retail lottery terminals to extend into hybrid digital-physical ecosystems. NeoGames specializes in turnkey iLottery solutions, anchoring its growth on cloud-native architectures that reduce upfront infrastructure burdens for state clients.
Online lottery software encompasses draw-management systems, random number generation engines, and player-account platforms engineered to process millions of concurrent transactions with sub-second latency and cryptographic audit trails. Its primary commercial purpose is to enable regulated lottery operators to sell tickets, manage prize pools, and verify winners through digitally secure channels. Cloud-based technology leads deployment preference among new entrants seeking elastic capacity without data center investment, while blockchain-based provable fairness mechanisms represent the fastest-growing sub-area as regulators in multiple jurisdictions demand transparent randomization. Draw-based lottery software retains the largest revenue pool due to recurring jackpot cycles, though instant lottery modules are capturing margin as impulse-play formats migrate from retail to mobile.
The United Kingdom Gambling Commission, state gaming authorities across the United States, and Brazil's federal lottery regulator MAPA shape market access through licensing tiers that mandate responsible gaming protocols and anti-money laundering integration. GDPR and emerging state privacy laws in California and Virginia impose data localization and consent-management requirements that increase platform engineering costs. Stakeholders must monitor regulatory divergence between permissive digital lottery frameworks and restrictive jurisdictions that block cross-border platform access.
Market Dynamics
The Online Lottery Software Market is experiencing a fundamental restructuring as state-level digital authorization protocols replace the legacy retail-terminal dependency that dominated lottery distribution for decades. This shift forces platform architects to rebuild core transaction engines around mobile-first architectures while maintaining cryptographic audit standards inherited from physical ticket systems.
Growth Catalysts
- Mobile-First Authorization Protocols:State gaming commissions in the United States are approving smartphone-based ticket purchases, eliminating the geographic friction of retail-only access. This expands addressable player bases beyond convenience-store catchment zones.
- GDPR-Driven Data Infrastructure Investment:European operators are rebuilding player-account platforms to satisfy consent-management and data-localization mandates. These compliance expenditures create durable switching costs that lock in platform providers.
- Cloud-Native Deployment Models:Elastic capacity provisioning allows lottery operators to absorb jackpot-driven traffic spikes without capital-intensive data center expansion. Brazilian federal lottery modernization is accelerating this adoption pattern.
Market Restraints
- Input Cost Concentration in Cryptographic Hardware:Hardware security module procurement for random number generation engines faces supply bottlenecks from specialized semiconductor foundries concentrated in East Asia.
- Regulatory Fragmentation Across State Lines:The United States lacks federal lottery legislation, forcing platform developers to maintain fifty-plus compliance variants. This multiplies engineering overhead without corresponding revenue scaling.
- Substitution Pressure from Skill-Based Gaming:Sports betting platforms and daily fantasy operators are capturing discretionary entertainment budgets from younger demographics, compressing the addressable market for pure chance-based lottery formats.
Strategic Opportunities
- Blockchain-Based Provable Fairness:Immutable randomization verification is displacing proprietary audit systems as regulators in multiple jurisdictions demand transparent draw mechanisms. This creates first-mover advantages for platforms with deployed cryptographic transparency layers.
- Instant Lottery Module Expansion:Impulse-play formats migrating from retail scratch tickets to mobile interfaces capture higher margin per transaction. Brazil's authorized digital channels represent the most concentrated deployment opportunity.
- Responsible Gaming Integration Mandates:The United Kingdom Gambling Commission's player-protection requirements are becoming template legislation elsewhere. Platforms with pre-built self-exclusion and spend-limit tooling gain accelerated licensing timelines.
Industry Challenges
- Cryptographic Engineering Talent Scarcity:The intersection of secure random number generation and high-throughput transaction processing requires specialized skill sets concentrated in financial technology hubs. Lottery operators compete with payment processors and cryptocurrency exchanges for this limited labor pool.
- Legacy Terminal Integration Complexity:Hybrid digital-physical ecosystems must synchronize decades-old retail terminal protocols with modern cloud architectures. State lottery operators with entrenched installed bases face extended migration timelines that delay full platform replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Lottery Software Market |
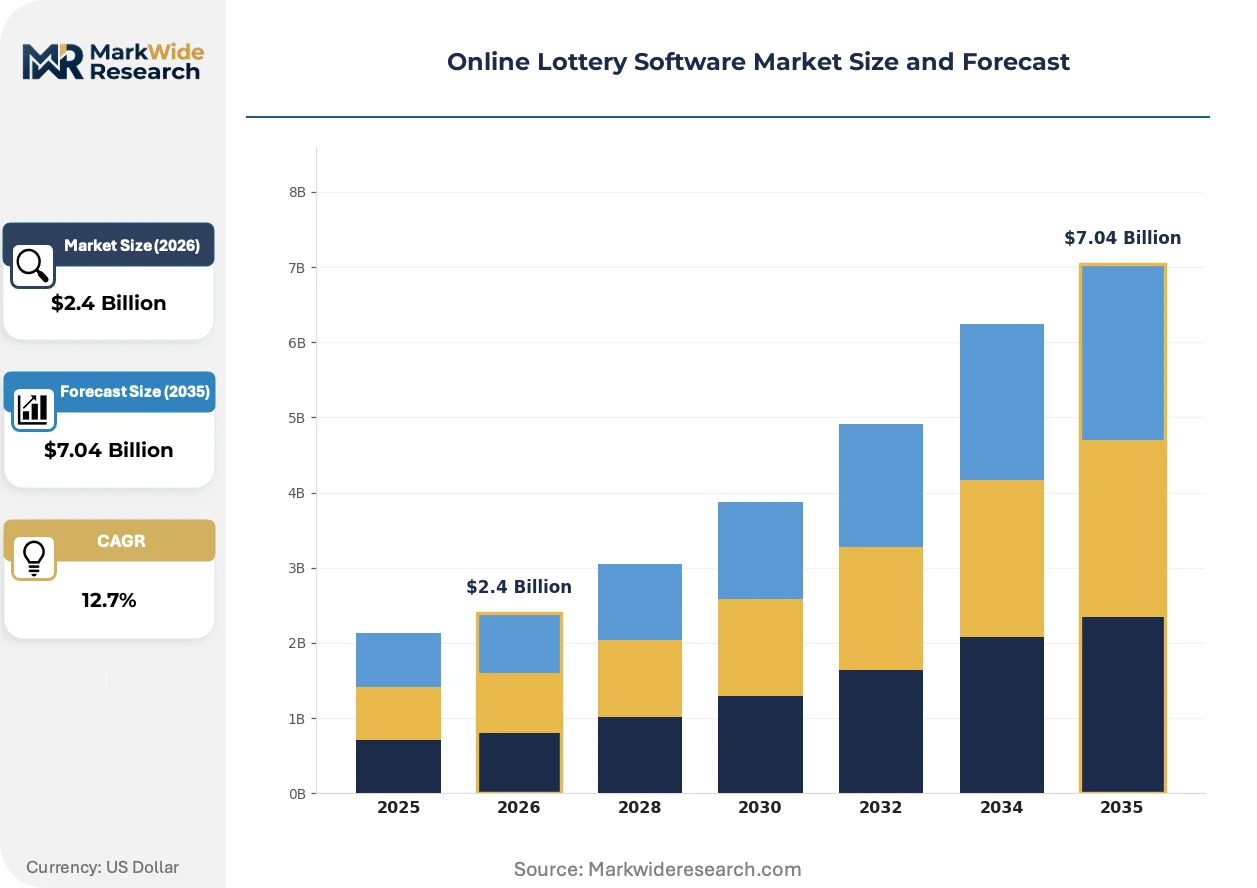
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.04 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Lottery, Draw-Based Lottery, Sports Betting, Online Scratch Cards End User: Lottery Operators, Governments, Gaming Platforms, Charitable Organizations Technology: Blockchain, Cloud-Based, Mobile Applications, Web-Based Platforms Distribution Channel: Online, Mobile, Retail, Affiliate Marketing |
| Companies Covered | IGT, Light & Wonder, NeoGames, INTRALOT, Playtech, Scientific Games, Aristocrat Interactive, Sportradar, Pollard Banknote, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Lottery Software Market Trends and Innovations
Architectural decomposition of monolithic lottery platforms is redistributing competitive advantage toward specialized component vendors and away from integrated system providers. This fragmentation enables faster innovation cycles but complicates accountability for end-to-end security.
Blockchain-based randomization verification is decomposing the traditional trust model that placed audit authority exclusively with state gaming commissions. Platform developers in Malta and Gibraltar are deploying these systems to satisfy emerging transparency mandates from Brazilian and European regulators. The technology is compressing procurement cycles as lottery operators bypass lengthy proprietary audit negotiations in favor of open-verification protocols.
The European Union's GDPR enforcement is mandating data-residency and erasure capabilities that legacy lottery databases were never engineered to accommodate. Platform providers are rebuilding player-account systems with region-specific data partitioning. Operators serving cross-border European player bases face the highest retrofit burden, with compliance timelines extending platform deployment schedules.
Impulse-driven purchasing behavior is migrating from retail convenience channels to smartphone interfaces, unbundling the location-locked distribution model that protected incumbents. Younger demographics in the United Kingdom and Scandinavia demonstrate this shift most visibly. Lottery operators are responding with micro-transaction instant formats that compress play cycles from weekly draws to seconds-based outcomes.
Online Lottery Software Market Segmentation
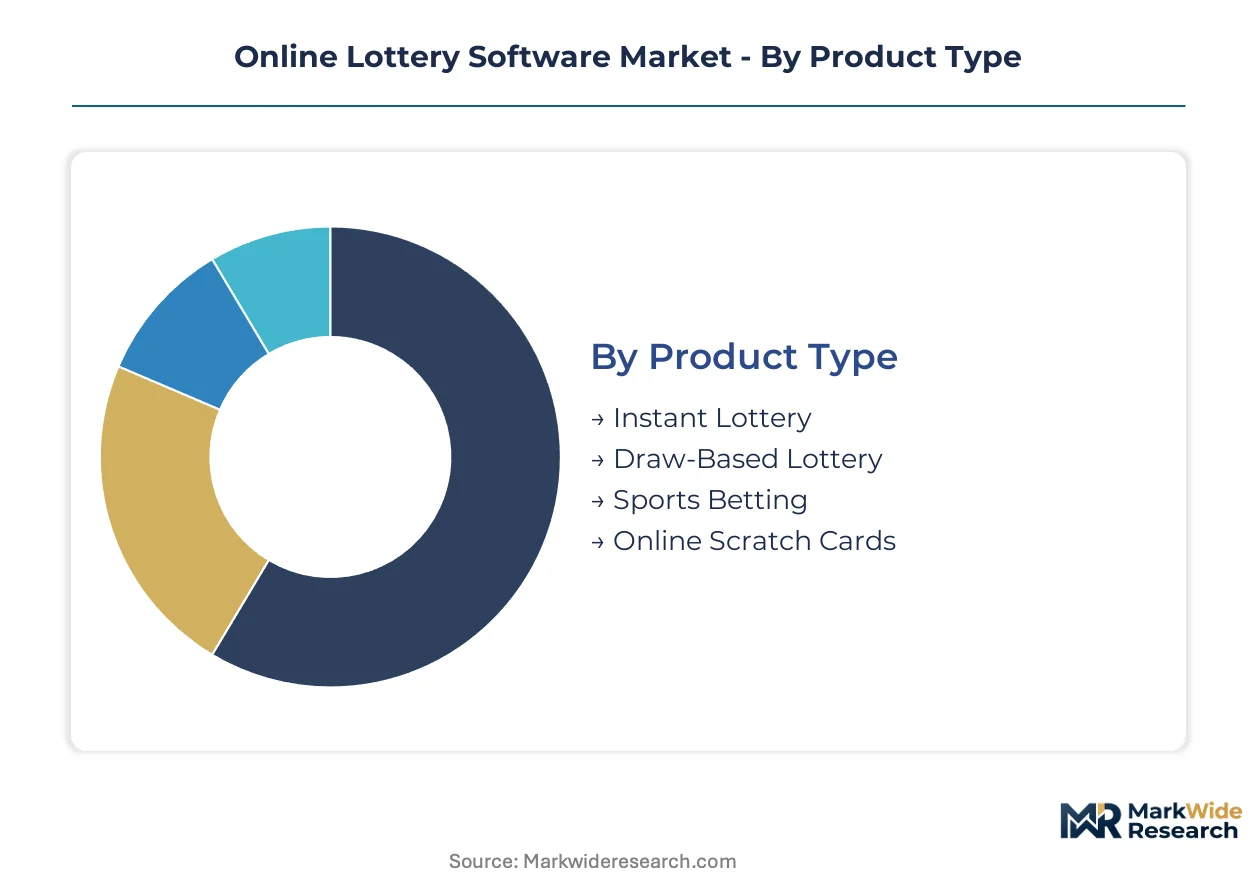
Segmentation in online lottery software reveals how platform architectures align with distinct regulatory environments and player behavior patterns. Each category exposes different cost structures, compliance burdens, and growth trajectories that shape provider strategy.
Product Type:
Geographic spread varies sharply across formats, with draw-based systems concentrated in mature state lottery markets while instant formats penetrate emerging digital jurisdictions.
- Draw-Based Lottery:Core systems manage recurring jackpot cycles with cryptographic random number generation and sub-second transaction processing. Demand clusters in the United States and Brazil where state and federal operators modernize legacy infrastructure. Regulatory audit requirements in these markets create durable vendor relationships.
- Instant Lottery:Mobile-first scratch and quick-play modules compress play cycles to seconds-based outcomes. Brazil's authorized digital channels and UK smartphone penetration drive fastest expansion here. Higher per-transaction margins attract platform investment.
- Instant Lottery:Mobile-first scratch and quick-play modules compress play cycles to seconds-based outcomes. Brazil's authorized digital channels and UK smartphone penetration drive fastest expansion here. Higher per-transaction margins attract platform investment.
- Sports Betting:Odds-engine integration with lottery platforms captures crossover player budgets. European operators lead deployment under UK Gambling Commission frameworks.
- Online Scratch Cards:Digital replication of physical ticket mechanics targets impulse players. Scandinavian markets show strongest adoption rates.
Draw-Based Lottery holds the largest share; momentum sits with Instant Lottery.
End User:
Customer type determines procurement scale and compliance complexity, with government direct contracts commanding longest sales cycles but highest lifetime value.
- Lottery Operators:State and regional lottery authorities require end-to-end platform integration with legacy terminal synchronization. GDPR and state gaming commission mandates in Europe and the United States dominate their vendor selection criteria.
- Governments:Federal and state entities prioritize transparent audit trails and responsible gaming integration. Brazil's MAPA modernization program represents the most concentrated government deployment opportunity.
- Gaming Platforms:Commercial operators seek white-label lottery modules to diversify beyond core casino offerings. Malta and Gibraltar licensing hubs concentrate their procurement activity.
- Charitable Organizations:Nonprofit lottery fundraisers operate under lighter regulatory tiers with simplified compliance requirements. UK and Irish markets support specialized platform variants.
Lottery Operators dominate procurement volume; Gaming Platforms show steepest expansion trajectory.
Technology:
Deployment architecture choices separate capital-intensive operators from lean entrants seeking elastic capacity without infrastructure ownership.
- Cloud-Based:Elastic provisioning allows operators to absorb jackpot-driven traffic spikes without data center investment. New entrants in Brazil and European markets favor this model for speed-to-market.
- Blockchain:Immutable randomization verification satisfies emerging transparency mandates from Brazilian and European regulators. Malta-based developers lead deployment of cryptographic transparency layers.
- Mobile Applications:Smartphone-first ticket purchasing eliminates geographic friction of retail-only access. US state commission approvals accelerate this channel's growth.
- Web-Based Platforms:Browser-accessible lottery portals retain relevance for desktop-centric player demographics and older installed base migrations.
Cloud-Based technology leads current deployment preference; Blockchain is climbing the fastest.
Distribution Channel:
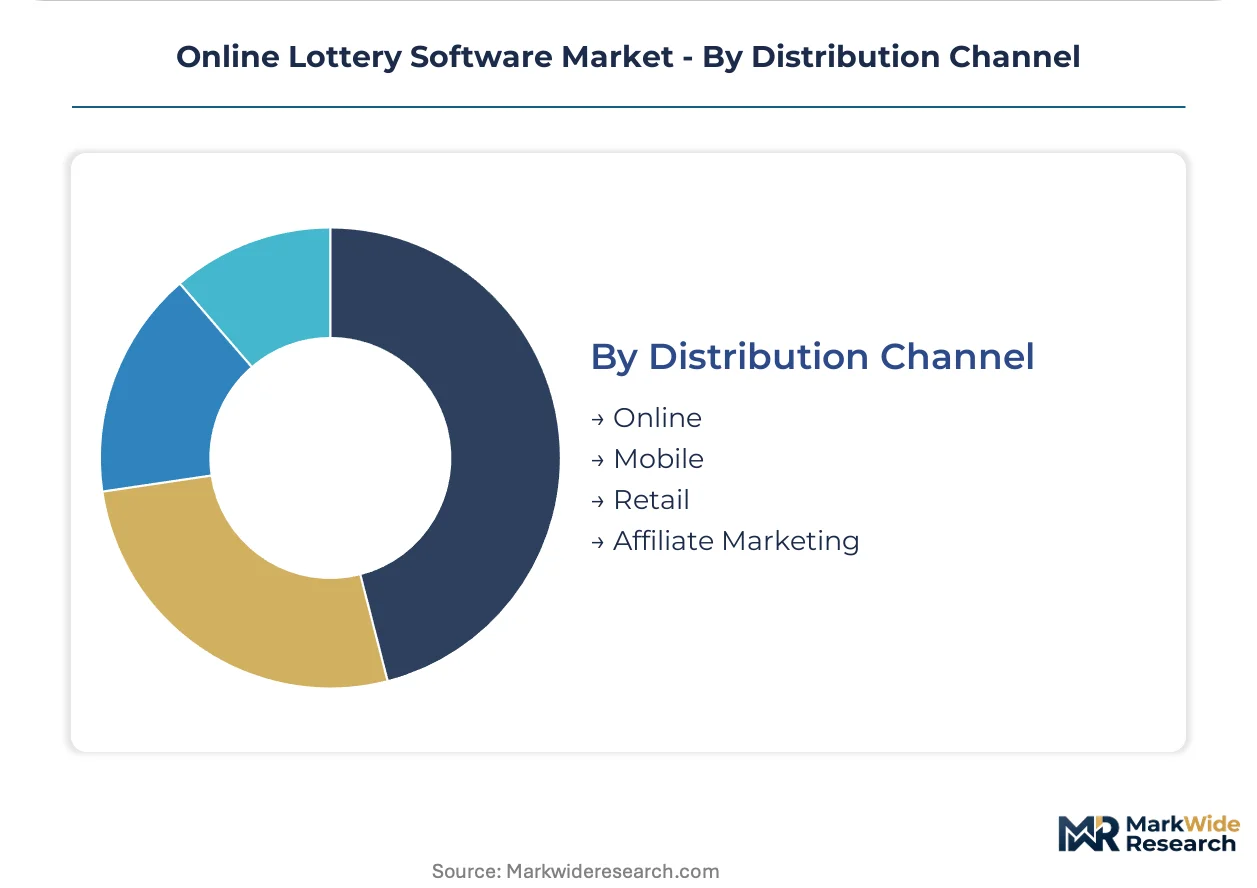
Channel strategy reflects the unbundling of location-locked retail protection as impulse purchasing migrates to digital interfaces.
- Mobile:Smartphone ticket sales expand addressable player bases beyond convenience-store catchment zones. US state gaming commission approvals and UK Gambling Commission mobile frameworks drive this channel's expansion.
- Online:Direct web platform access serves desktop players and integrated multi-product gaming sites. European operators with cross-border player bases invest heavily here.
- Retail:Physical terminal networks persist as hybrid ecosystems require synchronization with digital platforms. Legacy installed bases in mature markets slow full displacement.
- Affiliate Marketing:Third-party player acquisition channels concentrate in competitive jurisdictions with multiple licensed operators. UK and Scandinavian markets show highest affiliate penetration.
Online channels hold established volume; Mobile is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity diverges sharply across jurisdictions. Brazil's federal lottery modernization absorbs price premiums for compliance-heavy platforms, while European operators under GDPR pressure prioritize cost-efficient data infrastructure over feature expansion.
United States
State gaming commissions in New York, Illinois, and Michigan authorize smartphone ticket purchases, eliminating retail-only access friction. The lack of federal lottery legislation forces platform developers to maintain fifty-plus compliance variants. Lottery software clusters concentrate in Nevada's gaming technology corridor and New Jersey's Atlantic City digital gaming hub.
Brazil
Federal lottery modernization through MAPA accelerates authorized digital channel deployments across state operators. The country's national gaming regulator mandates transparent audit trails for all platform procurements. São Paulo anchors the largest concentration of lottery technology implementation, with Rio de Janeiro following for mobile-first instant lottery modules.
United Kingdom
The UK Gambling Commission's player-protection requirements template legislation for responsible gaming integration across European operators. GDPR consent-management and data-localization mandates increase platform engineering costs. London's fintech corridor hosts the densest cluster of lottery software developers serving cross-border European player bases.
Germany
State-level gaming authorities in Bavaria and North Rhine-Westphalia tighten compliance requirements for online lottery platforms. The country's federal data protection framework imposes additional localization constraints beyond baseline GDPR. Berlin's gaming technology ecosystem specializes in hybrid digital-physical lottery system integration.
Malta
Gibraltar and Malta licensing hubs concentrate procurement activity for commercial gaming platforms seeking white-label lottery modules. The Malta Gaming Authority's framework for blockchain-based provable fairness attracts transparency-focused developers. Platform developers here deploy cryptographic verification systems to satisfy emerging Brazilian and European regulatory mandates.
Online Lottery Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the sector. Platform-native developers with cloud-native architectures reduce upfront infrastructure burdens for state clients, while legacy hardware suppliers leverage installed retail terminal bases to extend into hybrid ecosystems. Three archetypes dominate: turnkey iLottery specialists, integrated gaming conglomerates with lottery divisions, and component vendors focused on random number generation engines. M&A activity concentrates on acquiring cryptographic engineering capabilities, while geographic expansion targets Brazil's federal modernization program and US state digital authorization waves.
Within the integrated gaming conglomerate tier, IGT and Scientific Games exemplify archetypes leveraging legacy retail infrastructure to anchor hybrid digital-physical positions. NeoGames occupies a specialist position as a turnkey iLottery provider with cloud-native deployment models. These three represent distinct competitive vectors: terminal-installed-base extension, full-platform integration, and elastic cloud-native delivery.
| Leading Market Players |
|---|
| IGT |
| Light & Wonder |
| NeoGames |
| INTRALOT |
| Playtech |
| Scientific Games |
| Aristocrat Interactive |
| Sportradar |
| Pollard Banknote |
| Others |
Pricing and Supply Chain Analysis
Cloud-native architecture substitution for legacy on-premise data center deployments simultaneously redistributes supply geography toward distributed engineering hubs and compresses upfront pricing economics for state lottery operators. This shift enables Brazilian and European entrants to bypass capital-intensive infrastructure commitments while forcing incumbent hardware suppliers to rebundle terminal-installed-base relationships into hybrid service contracts.
Pricing Analysis
Post-deployment support and cryptographic audit maintenance contracts drive lifetime value capture across platform tiers. SaaS-tiered subscription models dominate new procurements, with price differentiation resting on GDPR compliance certification grade and jackpot-scale elastic capacity guarantees. Pricing pressure stems from cloud-native entrants undercutting legacy infrastructure bundles. State lottery operators show highest price sensitivity; federal modernization programs in Brazil demonstrate lowest.
Supply Chain Analysis
Specialized semiconductor foundry capacity in Taiwan and South Korea underwrites hardware security module availability for random number generation engines. East Asian cryptographic chip fabrication, European data center infrastructure, and Brazilian systems integration services anchor upstream supply. Raw material dependencies span silicon wafers, HSM-grade processors, and quantum-resistant encryption components. Single-source vulnerability concentrates in advanced node semiconductor manufacturing. Distribution runs through direct government procurement channels and licensed platform vendor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent platform providers face substitution defense against cloud-native specialists and blockchain-verification entrants that disintermediate proprietary audit relationships. Sports betting and daily fantasy operators capture younger demographics, compressing pure lottery addressable markets.
For Market Incumbents: Shield terminal-installed-base revenue through hybrid digital-physical ecosystem bundling that synchronizes legacy retail protocols with mobile-first architectures. Accelerate cryptographic engineering hiring in Malta and Gibraltar to counter blockchain transparency competitors. Prioritize GDPR-compliant data infrastructure investments that create durable switching costs for European state clients.
For New Entrants and Emerging Players: Lead with instant lottery modules targeting Brazil's MAPA-authorized digital channels where federal modernization absorbs compliance-heavy platform premiums. Capture white-space in UK Gambling Commission jurisdictions by pre-building responsible gaming tooling that accelerates licensing timelines. Deploy cloud-native delivery models to undercut legacy infrastructure procurement cycles.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed iLottery specialists possessing turnkey cloud architectures but limited geographic footprint. Five-to-ten year viability hinges on regulatory divergence between permissive digital frameworks and restrictive cross-border blocks. Watch for blockchain-based provable fairness mandates crossing threshold adoption in Brazilian and European procurement specifications as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-Based Provable Fairness Deployment | Immutable verification layers satisfy MAPA and UK Gambling Commission transparency mandates ahead of competitors. |
| Cloud-Native Platform Integration | Elastic capacity provisioning eliminates data center capital burdens for Brazilian state lottery operators. |
| Responsible Gaming Tooling Pre-Build | Self-exclusion and spend-limit modules accelerate UK Gambling Commission licensing timelines versus retrofit approaches. |
| Hybrid Digital-Physical Ecosystem Extension | Retail terminal synchronization protects incumbent installed-base relationships against pure-cloud disintermediation. |
| Cryptographic Engineering Talent Acquisition | Secure random number generation expertise counters fintech and cryptocurrency exchange competition for limited labor pools. |
Research Methodology
Desk research of state gaming commission procurement filings, federal lottery modernization specifications, and GDPR enforcement precedents preceded structured interviews with lottery platform CTOs, state procurement officers, regulatory compliance leads, and cryptographic engineering directors. Primary fieldwork with Brazilian MAPA officials and UK Gambling Commission policy specialists cross-validated secondary data from SEC filings, customs records, and hyperscaler capex disclosures. Bottom-up transaction volume modeling and top-down regulatory adoption curves were triangulated.
Variance decomposition across deployment model, operator scale, jurisdictional regulatory cluster, and jackpot-cycle frequency shaped the analytical framework. CAGRs derived from segment-level adoption velocity and infrastructure replacement cycles. Cloud migration timelines and blockchain transparency mandate penetration served as lottery-specific forecast inputs throughout the projection horizon.
The analysis sits within stated boundaries; outcomes outside sustained state-level digital authorization waves or hardware security module supply normalization would require recalibration. Forecasts reflect assumptions regarding regulatory divergence persistence and cryptographic talent market tightness. Revision becomes warranted when blockchain-based provable fairness adoption crosses threshold procurement specifications in multiple jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Screen and Script Writing Software Market
Software & Services
Global Accreditation Management Software Market
Software & Services
Global Affiliate Software Market
Software & Services
Driver and Staff Management Software Market
Software & Services
Lead Management Software Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Graphical User Interface (GUI) Design Software Market
Software & Services
House Cleaning App Market
Software & Services
Voice to Text on Mobile Devices Market
Software & Services
Hydraulic Modeling Software Market
Software & Services
Solar Rooftop Design Software Market
Software & Services
Russian IT Software and Services Market
Software & Services
Global Demand Planning Software Market
Software & Services
Construction Software Market
Software & Services
Server Software Market
Software & Services
Automotive Operating Systems Market