
 Global Plumbing Software Market | 2026-2036
Global Plumbing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plumbing Software Market Foresight
North American SaaS infrastructure is expanding its capacity to serve trade-specific verticals. ServiceTitan leverages deep workflow integration for multi-location plumbing operations. Jobber anchors its position through strong mobile-first scheduling tools for independent contractors. simPRO competes aggressively in the Australian and UK markets with project-costing modules tailored to commercial plumbing.
Plumbing software encompasses digital platforms that manage scheduling, estimation, design, inventory, and customer relationships for plumbing contractors and trade professionals. Core functional parameters include real-time dispatch algorithms, CAD-compatible pipe-system design engines, and API connectivity to accounting systems like QuickBooks. Cloud-based deployment leads the technology dimension due to lower upfront costs and remote accessibility for field technicians. Project management and estimation tools command the strongest margin pools because they directly reduce labor overruns and material waste. Mobile applications represent the fastest-growing technology segment as smartphone-dependent field crews replace paper-based workflows.
FDA regulations for plumbing in food-processing facilities, EPA lead-and-copper rules, and EU Green Deal building-efficiency standards shape product compliance requirements across jurisdictions. These frameworks force software vendors to embed audit trails, material-certification tracking, and energy-performance reporting into their platforms. Stakeholders must monitor how evolving municipal water-quality mandates in the United States, Germany, and Australia will reshape feature roadmaps and certification requirements for plumbing software developers.
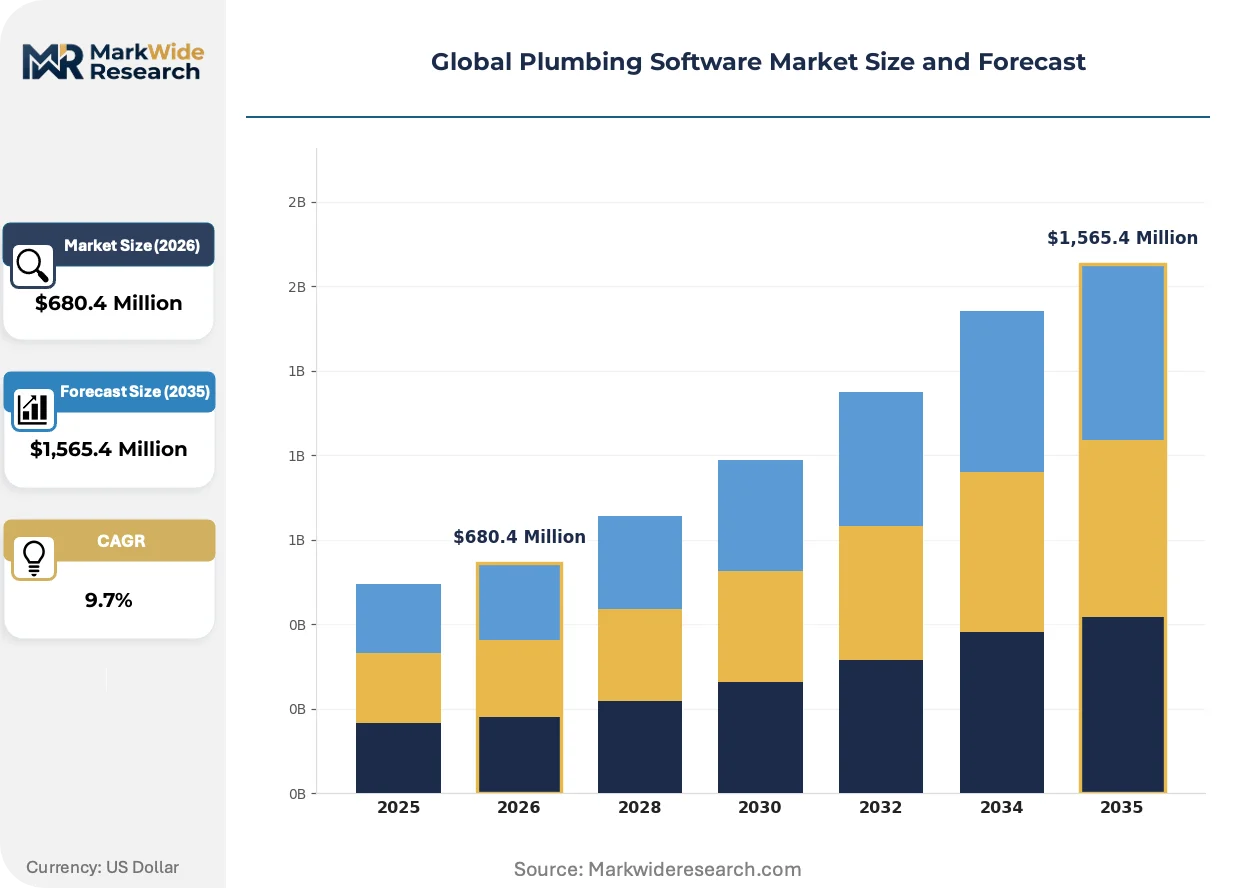
Market Dynamics
Cloud-based deployment architectures are compressing upfront capital barriers for small and mid-sized plumbing contractors, fundamentally restructuring how field-service automation penetrates trade-specific verticals previously locked out of enterprise-grade tooling.
Growth Catalysts
- EU Green Deal building-efficiency mandates:These frameworks force software vendors to embed energy-performance reporting and audit-trail functionality, creating compulsory upgrade cycles across European commercial plumbing operations.
- Mobile-first field workflows:Smartphone-dependent technician crews are replacing paper-based dispatch and invoicing, pulling cloud-based scheduling and real-time inventory lookup into standard operating procedure.
- Commercial contractor concentration:Multi-location plumbing operations in the United States, Germany, and Australia are consolidating vendor relationships around platforms with deep workflow integration and API connectivity to accounting systems.
Market Restraints
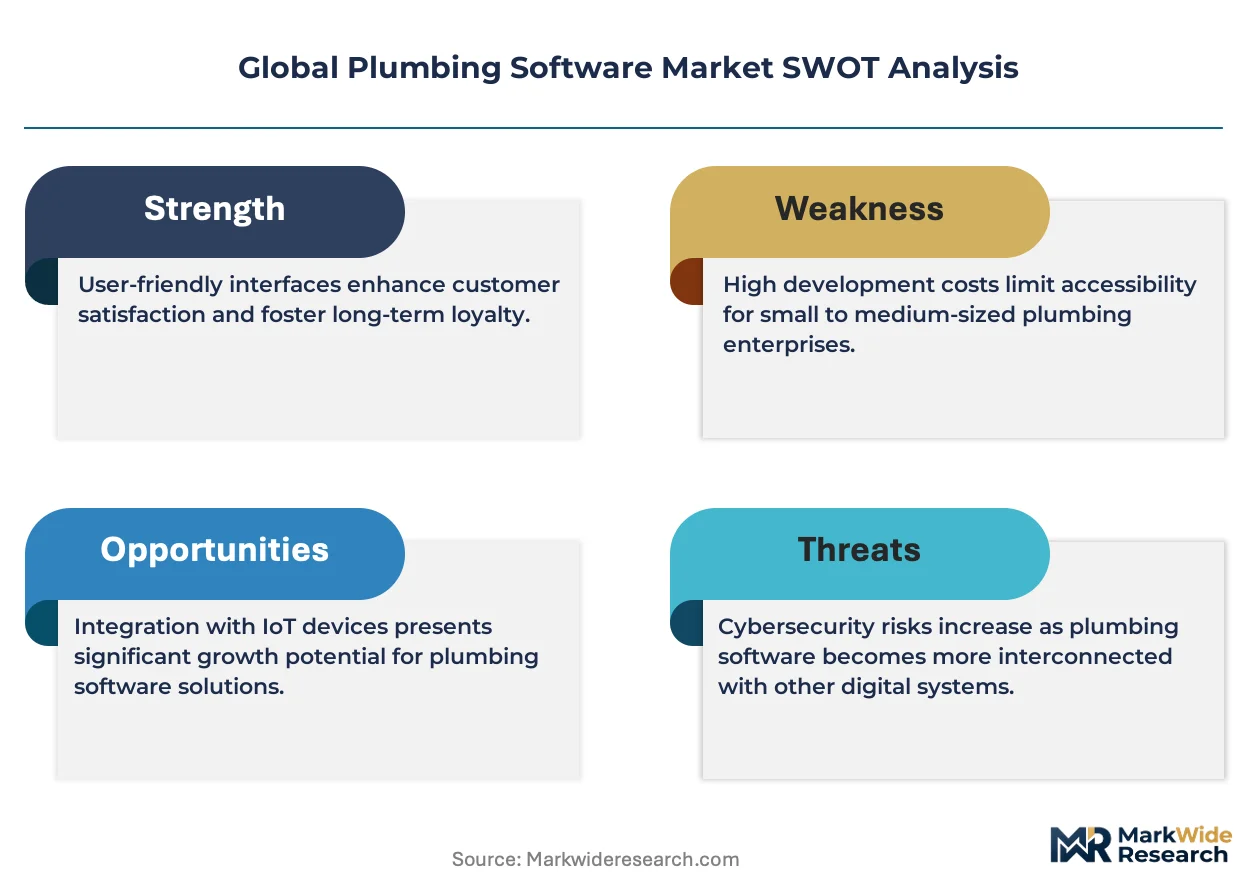
- Legacy system integration friction:Established contractors face substantial reconfiguration costs when migrating decades of customer records and job-history data from on-premise servers to cloud architectures.
- Technical talent scarcity:Field technicians with simultaneous plumbing certification and software literacy remain concentrated in urban labor markets, constraining rollout velocity in secondary and tertiary service territories.
- Data sovereignty fragmentation:Jurisdictional requirements around customer and job-site data storage create compliance complexity for vendors attempting unified platform delivery across multiple national markets.
Strategic Opportunities
- Underpenetrated mechanical contractor segments:HVAC and electrical trade contractors with overlapping customer bases represent adjacent expansion targets for plumbing-software vendors with modular product architectures.
- Predictive maintenance convergence:Integration of IoT sensor data from building management systems with plumbing dispatch platforms enables proactive service scheduling before catastrophic failures occur.
- German municipal water-quality mandates:Evolving local regulations around lead-and-copper monitoring create demand for specialized compliance modules that track material certification and generate audit-ready documentation.
Industry Challenges
- Technician onboarding velocity:Seasoned field crews with decades of paper-based habit formation require sustained training investment to achieve productive utilization of mobile application features.
- CAD compatibility certification:Pipe-system design engines must maintain interoperability with multiple proprietary file formats, forcing continuous engineering resources toward standards compliance rather than feature differentiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plumbing Software Market |
| Market Size in 2026 | $680.4 Million |
| Market Size in 2035 | $1,565.4 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Design Software, Project Management, Maintenance Tracking, Estimation Tools, Customer Relationship Management Technology: Cloud-Based, On-Premise, Mobile Applications, SaaS, Desktop Platforms Application: Residential Installations, Commercial Systems, Industrial Plumbing, Public Infrastructure, Educational Institutions End User: Independent Contractors, Plumbing Firms, Facility Managers, Construction Companies, Aftermarket Specialists |
| Companies Covered | ServiceTitan, Jobber, Housecall Pro, FieldEdge, Service Fusion, WorkWave Service, simPRO, Workiz, Payzerware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plumbing Software Market Shifts & Advancements
Artificial intelligence and machine learning architectures are penetrating field-service management at an accelerating clip, compressing the gap between diagnostic data capture and automated dispatch decisioning.
Unified field-service platforms are unifying historically siloed functions—scheduling, estimation, inventory, and customer relationship management—into single-pane-of-glass architectures. Mid-sized commercial contractors in Australia and the United Kingdom are adopting these integrated stacks fastest, consolidating vendor relationships that previously required three to four separate point solutions. This consolidation is unifying data flows across job lifecycle stages, enabling real-time margin visibility that paper-based workflows cannot replicate.
EPA lead-and-copper rule enforcement is intensifying documentation requirements for plumbing work in food-processing and municipal water infrastructure. Software vendors must now embed material-certification tracking and chain-of-custody logging as core platform features rather than optional add-ons. Commercial contractors serving FDA-regulated facilities face the steepest compliance burden, driving preference toward platforms with pre-built audit-trail templates.
Subscription-based pricing models are displacing perpetual-license structures across the contractor software landscape. Independent plumbing operators with irregular cash flows prefer monthly payments aligned to revenue cycles rather than large upfront capital outlays. This shift is most visible in the United States, where SaaS infrastructure maturity enables vendors to offer tiered functionality scaled to fleet size without custom implementation fees.
Global Plumbing Software Market Segmentation
Plumbing software segmentation reveals how functional specialization maps to contractor scale and job complexity. Vendors architect product portfolios around whether users operate as solo technicians or manage distributed commercial fleets.
Product Type:
Integration depth varies sharply across this category, with standalone estimation modules serving independent contractors while full-suite platforms embed design-to-invoicing workflows for multi-location operators.
- Design Software:CAD-compatible pipe-system engines generate material takeoffs and pressure calculations. Commercial contractors in Germany and Australia adopt these tools most aggressively, driven by EU Green Deal documentation requirements and municipal water-quality mandates.
- Project Management:Unified scheduling, crew dispatch, and milestone tracking compress job-cycle times. United States multi-location plumbing firms concentrate demand here, consolidating previously siloed point solutions into single-pane architectures.
- Maintenance Tracking:Recurring service contract management with automated renewal triggers.
- Estimation Tools:Labor and material costing modules with supplier price integration.
- Customer Relationship Management:Pipeline management and post-service follow-up automation.
Volume placements concentrate in Project Management; the faster expansion belongs to Design Software.
Technology:
Cost tier structures dominate purchasing decisions, with entry-level SaaS subscriptions capturing independent contractors and enterprise cloud deployments serving consolidated commercial operations.
- Cloud-Based:Browser-accessible platforms with automatic updates and remote data synchronization. Australian and United Kingdom plumbing contractors lead adoption, pulled by lower upfront capital barriers and field-crew smartphone penetration.
- Mobile Applications:Native iOS and Android tools for real-time dispatch, photo documentation, and digital invoicing. Independent contractors across all major markets adopt these fastest, replacing paper-based workflows entirely.
- SaaS:Subscription pricing aligned to contractor revenue cycles rather than perpetual licenses.
- On-Premise:Local server installations for contractors with strict data sovereignty requirements.
- Desktop Platforms:Legacy Windows-based systems with limited remote accessibility.
Deployment volume clusters in Cloud-Based architectures; Mobile Applications are climbing the fastest as field-crew smartphone dependency deepens.
Application:
Customer type and job-scale differentiation separate residential retrofit tools from commercial new-construction platforms with multi-trade coordination requirements.
- Commercial Systems:Multi-story building plumbing with fire-suppression integration and compliance documentation. United States and German markets anchor demand, shaped by FDA food-processing regulations and EPA lead-and-copper enforcement.
- Industrial Plumbing:Process piping for manufacturing facilities with material-certification tracking. Australian mining and resource infrastructure drives specialized module development.
- Residential Installations:Single-family and small multi-family fixture replacement and repair scheduling.
- Public Infrastructure:Municipal water-main maintenance with geographic information system integration.
- Educational Institutions:Campus-wide maintenance coordination across dispersed building portfolios.
Commercial Systems command the largest deployment base; Industrial Plumbing shows the steepest expansion trajectory as process-facility compliance burdens intensify.
End User:
Maturity and digital readiness separate legacy contractors migrating from paper systems from facility managers already embedded in enterprise software ecosystems.
- Plumbing Firms:Established multi-technician operations with recurring maintenance contract portfolios. German and Australian markets concentrate adoption, consolidating vendor relationships around API-connected accounting integration.
- Facility Managers:Building operators overseeing HVAC, electrical, and plumbing through unified work-order platforms. United States commercial real estate portfolios drive cross-trade platform consolidation.
- Independent Contractors:Solo operators prioritizing mobile-first scheduling and payment collection.
- Construction Companies:General contractors coordinating plumbing subcontractors through project-wide scheduling tools.
- Aftermarket Specialists:Parts distributors and warranty service providers with inventory-centric workflows.
Plumbing Firms represent the deepest installed base; Facility Managers are gaining share fastest as building-management system integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's SaaS infrastructure anchors software development for trade-specific verticals, while German engineering clusters and Australian mining corridors shape specialized compliance and industrial modules across the plumbing software value chain.
United States
Commercial plumbing contractors in Texas and Florida drive cloud-platform adoption for multi-location dispatch operations. EPA lead-and-copper rule enforcement compels material-certification tracking features in software procurement decisions. Greater Atlanta's facility management sector consolidates vendor relationships around API-connected accounting integration.
Germany
Municipal water-quality mandates in Bavaria and North Rhine-Westphalia accelerate digital compliance tool deployment among commercial contractors. EU Green Deal building-efficiency standards force energy-performance reporting functionality into core platform requirements. Stuttgart's industrial plumbing sector demands CAD-compatible pipe-system design engines with audit-trail capabilities.
Australia
Mining and resource infrastructure in Western Australia and Queensland generates specialized demand for industrial plumbing modules with material-certification tracking. Field-crew smartphone penetration pulls mobile-first scheduling tools into standard operating procedure across Sydney and Melbourne contractor bases. simPRO anchors regional competition through project-costing modules tailored to commercial operations.
United Kingdom
Mid-sized commercial contractors in Greater Manchester and the West Midlands adopt unified field-service platforms fastest, consolidating previously siloed point solutions. GDPR data sovereignty requirements create compliance complexity for vendors attempting unified platform delivery. London's facility management sector drives cross-trade platform consolidation with building-management system integration.
Canada
Independent contractors in Ontario and British Columbia prioritize mobile-first scheduling and payment collection tools with subscription-based pricing. Health Canada regulations for plumbing in food-processing facilities shape compliance module requirements. Toronto's commercial real estate portfolios generate demand for unified work-order platforms serving HVAC, electrical, and plumbing trades.
Global Plumbing Software Market Competitive Landscape
Global majors compete with regional champions across cloud-deployment architectures and mobile-first workflow integration, producing a tiered structure where deep vertical specialization separates premium positioning from scale-driven efficiency plays. The vendor base clusters around three strategic archetypes: full-suite platforms with API connectivity, mobile-native tools for independent contractors, and project-costing specialists for commercial operations. Dominant competitive moves include strategic partnerships with accounting software providers and geographic expansion through compliance module localization.
Within the full-suite platform tier, ServiceTitan and Jobber exemplify contrasting geographic anchoring and customer-scale specialization. ServiceTitan occupies a position serving multi-location plumbing operations with deep workflow integration across the United States. Jobber represents the mobile-first scheduling archetype, anchoring independent contractor segments through strong smartphone-native tools. Australian-based simPRO sits within the project-costing specialist tier, competing aggressively in commercial plumbing markets with localized compliance features.
| Leading Market Players |
|---|
| ServiceTitan |
| Jobber |
| Housecall Pro |
| FieldEdge |
| Service Fusion |
| WorkWave Service |
| simPRO |
| Workiz |
| Payzerware |
| Others |
Supply & Pricing Matrix
Commercial plumbing contractors in the United States, Germany, and Australia anchor procurement volume, compressing vendor pricing power around subscription-based SaaS tiers aligned to fleet size rather than perpetual licensing structures.
Pricing Analysis
Warranty and implementation support bundling separates premium-tier deployments from stripped-down entry offerings. Three-tier pricing structure across premium, standard, and economy levels tracks integration depth and API connectivity to accounting systems like QuickBooks. Cost compression in the economy tier intensifies because independent contractors prioritize mobile-first scheduling over design-engine modules. Small-scale independent operators exhibit the highest price sensitivity, while multi-location commercial fleets absorb premium pricing for unified field-service architectures.
Supply Chain Analysis
Cross-border data synchronization costs and cloud-hosting latency shape vendor margin structures across distributed deployment footprints. Software development concentrates in the United States, the United Kingdom, and Australia, with specialized compliance module engineering clustered in Germany. Platform engineering draws from SaaS infrastructure providers, mobile OS ecosystems, and CAD interoperability libraries. Single-source vulnerability in hyperscaler cloud hosting creates concentration risk for vendors serving data-sovereignty-sensitive jurisdictions. Distribution runs through direct sales teams for enterprise accounts and digital self-serve channels for independent contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical talent scarcity in secondary service territories props pricing for vendors with proven technician onboarding velocity, constraining supply expansion faster than demand growth.
For Market Incumbents: Deploy API ecosystem expansion to lock in multi-location plumbing operations before modular competitors fragment integration revenue. Deepen workflow integration with building-management systems to defend against facility-manager platform consolidation. Counter emerging mobile-native entrants through accelerated CAD compatibility certification investments that prolong incumbent switching costs.
For New Entrants and Emerging Players: AI-powered diagnostic dispatch algorithms offer the most penetrable wedge for unseating established scheduling incumbents. Target independent contractor segments in Ontario and British Columbia where subscription pricing preference outstrips vendor supply. Pursue white-label partnerships with plumbing parts distributors to bypass direct customer acquisition costs.
For Investors and Strategic Acquirers: The window for entry favors vertical SaaS consolidators with cross-trade expansion capability into HVAC and electrical adjacencies. Long-term viability hinges on platforms with embedded compliance module roadmaps responsive to evolving EPA and EU Green Deal mandates. Monitor German municipal water-quality enforcement intensity as the inflection signal for specialized audit-trail feature demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies scheduling, estimation, and inventory into single-pane architectures for multi-location contractors. |
| Compliance Module Localization | Embeds EPA lead-and-copper tracking and EU Green Deal energy reporting for jurisdiction-specific procurement. |
| Strategic Partnership | Links plumbing dispatch systems to QuickBooks and Xero accounting APIs to reduce contractor workflow friction. |
| Geographic Expansion | Establishes Australian and UK engineering presence to capture commercial project-costing module demand. |
| Acquisition of Specialist Firm | Absorbs IoT sensor integration capabilities for predictive maintenance convergence with building management systems. |
Research Methodology
Independent corroboration across primary interviews with plumbing firm operations directors, facility management technology officers, and SaaS platform product managers, combined with secondary validation of SEC filings, hyperscaler capex disclosures, and EU regulatory directive texts, underwrites the qualitative findings. Bottom-up triangulation against top-down market sizing anchors volume and value estimates.
Comparable-period anchoring to historical SaaS adoption curves in trade-specific verticals shapes the forecast window across the analysis window. Segmentation dimensions modeled include deployment architecture, contractor fleet size, application complexity, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to disclosed vendor subscriber counts and estimated average revenue per user benchmarks.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EPA enforcement or delayed EU Green Deal implementation timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Contract Abstraction Software Market
Software & Services
Talent Management Software Market
Software & Services
HPC Software Market
Software & Services
Smartphone OS Market
Software & Services
Global Custom Software Development Services Market
Software & Services
SMS Marketing Software Market
Software & Services
Japan IT Services Market
Software & Services
Ground Handling Software Market
Software & Services
Online Paint Editor App Market
Software & Services
Global Portal Software Market
Software & Services
Service Scheduling Software Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Global Salesforce Appexchange Tools Market
Software & Services
Spain HR Payroll Software Market
Software & Services
Cloud Communication Platform Software Market
Software & Services
Canada HR Payroll Software Market