
 Australia Data Center Cooling Market | 2026-2036
Australia Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Data Center Cooling Market Insights
The performance gap between premium liquid-cooled hyperscale installations and commodity air-cooled enterprise setups is consolidating around power density thresholds above 50 kW per rack. Vertiv Group Corp. leverages its precision cooling portfolio to dominate high-density deployments across Sydney and Melbourne corridors. Schneider Electric SE anchors the mid-market through integrated micro data center solutions with embedded thermal controls. Daikin Industries Limited competes on energy efficiency ratings, sustaining market position via inverter-driven compressor technology optimized for Australian climate zones.
Data center cooling encompasses engineered thermal management systems designed to dissipate heat generated by IT equipment, maintaining inlet temperatures between 18°C and 27°C per ASHRAE guidelines while optimizing power usage effectiveness ratios. Liquid cooling and immersion cooling segments are capturing the fastest growth as GPU-intensive AI workloads proliferate, with chilled beams retaining niche presence in legacy retrofit applications. Cloud service providers and telecommunications end users are driving deployment model shifts toward colocation and edge data centers, concentrating service type demand in installation and managed services as operators seek outsourced thermal optimization.
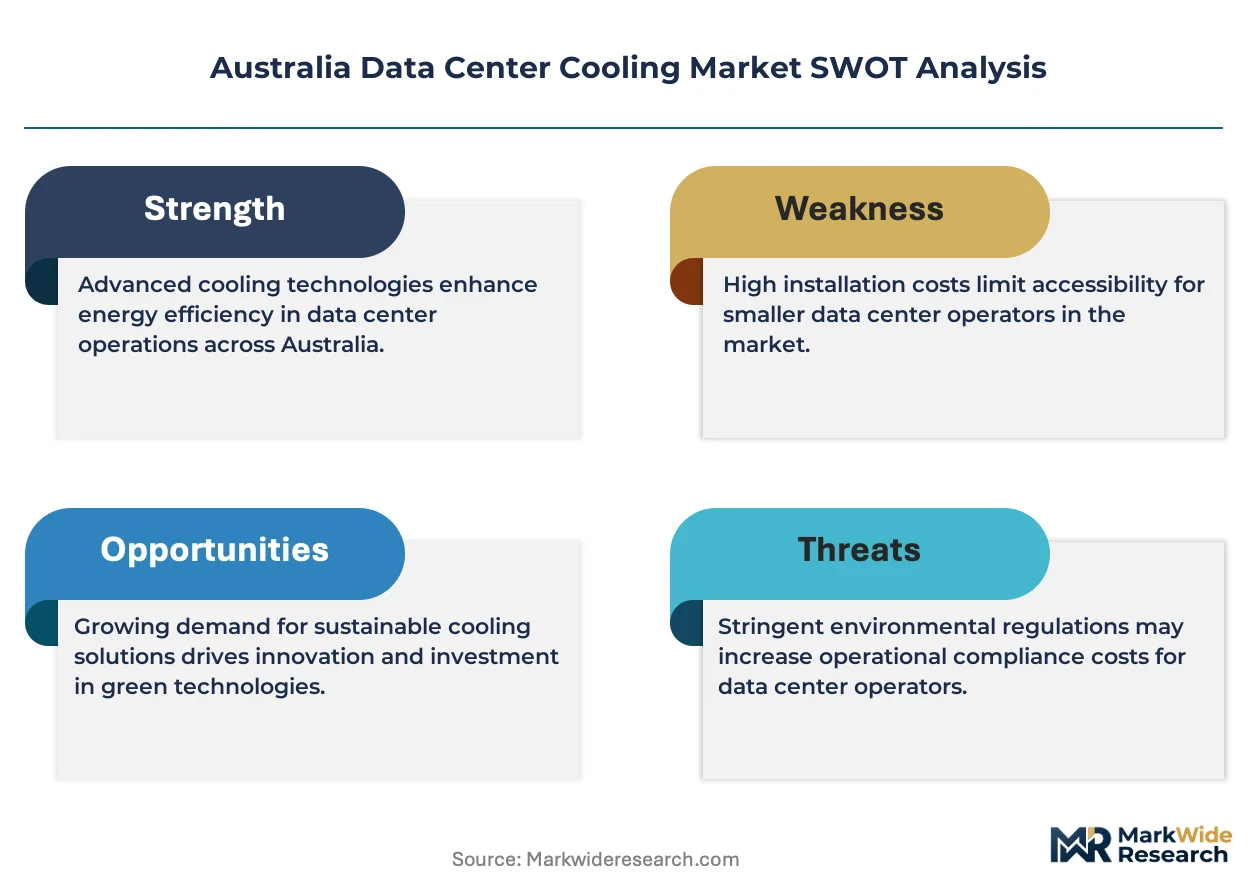
TGA refrigerant standards and Australian Building Codes Board energy efficiency mandates are tightening compliance requirements for cooling equipment deployed in Australian facilities, directly influencing product certification pathways and procurement specifications. NCC Section J provisions on building energy efficiency are accelerating demand for low-global-warming-potential refrigerants and heat recovery configurations. Stakeholders must monitor evolving NCC amendments and state-level planning regulations as thermal load densities climb, since compliance architecture will determine viable equipment categories before capital commitments crystallize.
Market Dynamics
GPU-intensive AI workloads are compressing power density thresholds across Australian facilities, forcing operators to abandon legacy air-cooled architectures before thermal limits breach ASHRAE guidelines.
Growth Catalysts
- Hyperscale Expansion:Cloud service providers are commissioning multi-megawatt facilities in Sydney and Melbourne corridors, creating immediate demand for precision thermal management systems.
- NCC Section J Amendments:The Australian Building Codes Board's tightening energy efficiency provisions are mandating heat recovery configurations and low-global-warming-potential refrigerants in new builds.
- Liquid Cooling Maturation:Direct-to-chip and immersion cooling technologies have crossed commercial viability thresholds for racks above 50 kW, displacing chilled beam retrofits in high-performance computing environments.
Market Restraints
- Copper and Aluminum Input Volatility:Heat exchanger fabrication depends on base metal prices that have fluctuated sharply, compressing margins for equipment manufacturers serving price-sensitive enterprise segments.
- Specialized Technician Scarcity:Installation and commissioning of advanced liquid cooling systems requires certified refrigeration mechanics with data center-specific training, creating bottleneck capacity in New South Wales and Victoria.
- TGA Refrigerant Compliance Timelines:Therapeutic Goods Administration certification pathways for alternative refrigerants extend procurement cycles by 8-14 months versus conventional hydrofluorocarbon systems.
Strategic Opportunities
- Queensland and Western Australia:These states remain underpenetrated relative to hyperscale concentration in Sydney and Melbourne, offering first-mover positioning as edge computing nodes proliferate.
- Integrated Heat Recovery:District heating tie-ins and thermal storage coupling are capturing policy support under state-level renewable energy targets, enabling new revenue streams from waste heat valorization.
- AI-Driven Predictive Maintenance:Machine learning algorithms trained on thermal telemetry are converging with building management systems to enable condition-based servicing contracts.
Industry Challenges
- Refrigeration Mechanic Certification:The Australian Refrigeration Council's licensing framework has not kept pace with immersion cooling and two-phase liquid system architectures, creating compliance ambiguity for contractors.
- Legacy Chiller Integration:Hybrid deployments combining new liquid cooling manifolds with existing chilled water infrastructure require custom engineering that extends project timelines and inflates commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Data Center Cooling Market |
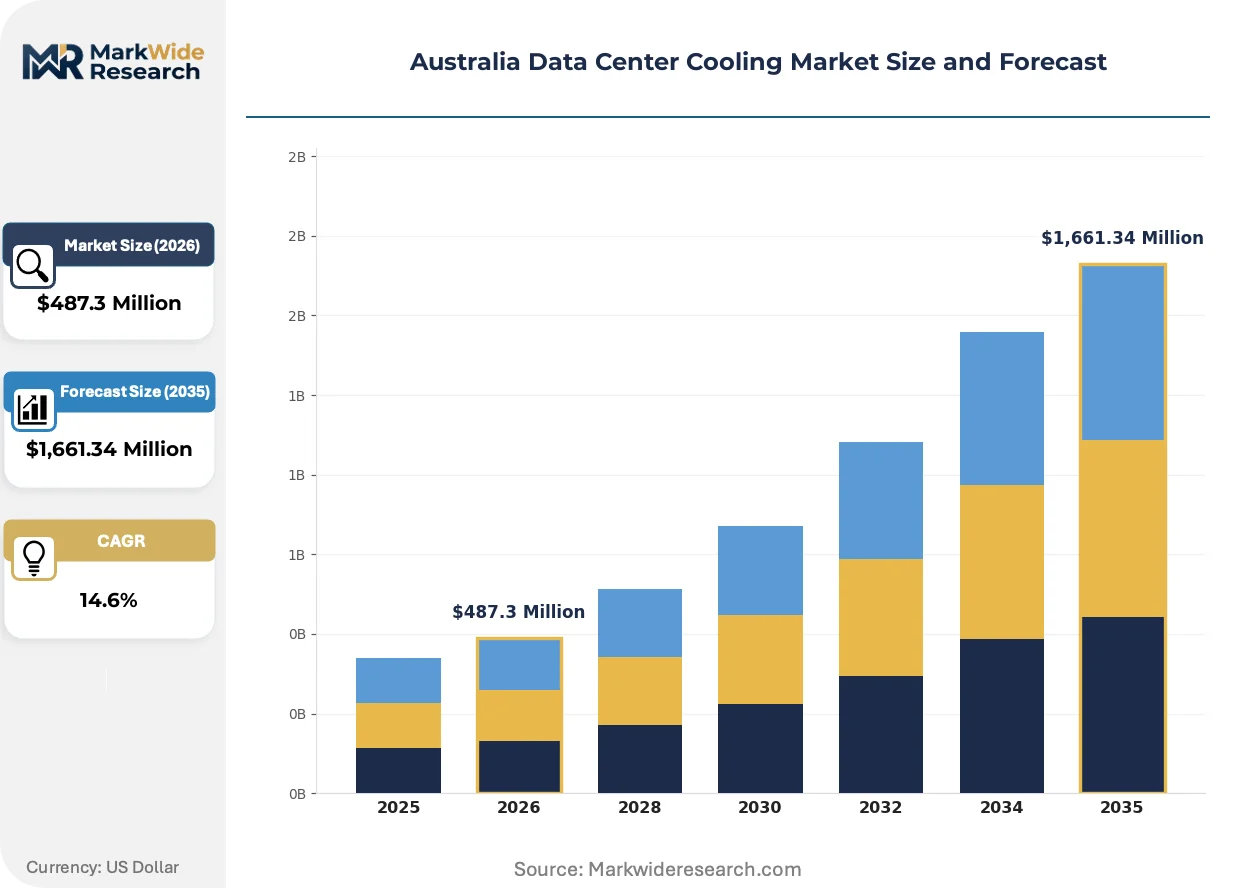
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Aired Cooling, Liquid Cooling, Immersion Cooling, Chilled Beams End User: Telecommunications, Cloud Service Providers, Enterprises, Government Deployment Model: On-Premise, Colocation, Edge Data Centers, Cloud Service Type: Maintenance Services, Installation Services, Consulting Services, Managed Services |
| Companies Covered | Vertiv Group Corp., Schneider Electric SE, Stulz GmbH, Rittal GmbH & Co. KG, Mitsubishi Electric Corporation, Johnson Controls Inc., Daikin Industries Limited, Trane Technologies Company LLC, Munters Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Data Center Cooling Market Trends and Innovations
Thermal management architectures are fragmenting across performance tiers as AI training clusters diverge from conventional enterprise workloads, creating parallel innovation tracks in the Australian market.
Direct-to-chip liquid cooling is modularizing around standardized quick-disconnect manifolds and skid-mounted pumping stations. Hyperscale operators in Sydney's Macquarie Park corridor are adopting factory-preconfigured cooling distribution units that slash on-site installation time. This standardization is modularizing procurement patterns, allowing operators to scale thermal capacity in 500 kW increments matched to GPU rack deployment waves.
TGA refrigerant standards and NCC Section J provisions are tightening in parallel, creating compound compliance burdens for equipment suppliers. The convergence of pharmaceutical-grade purity requirements with building energy efficiency mandates is disqualifying legacy compressor technologies from new facility tenders. Australian operators are responding by specifying inverter-driven systems with embedded refrigerant leak detection and automated reporting protocols.
Facility operators are unbundling thermal optimization from traditional mechanical maintenance contracts, creating discrete purchasing categories for energy performance guarantees. Colocation providers in Melbourne's Fishermans Bend precinct are contracting cooling-as-a-service arrangements where vendors assume inlet temperature risk. This reconfiguration is most visible among cloud-adjacent operators seeking to transfer capex exposure while locking in power usage effectiveness ratios below 1.3.
Australia Data Center Cooling Market Segmentation
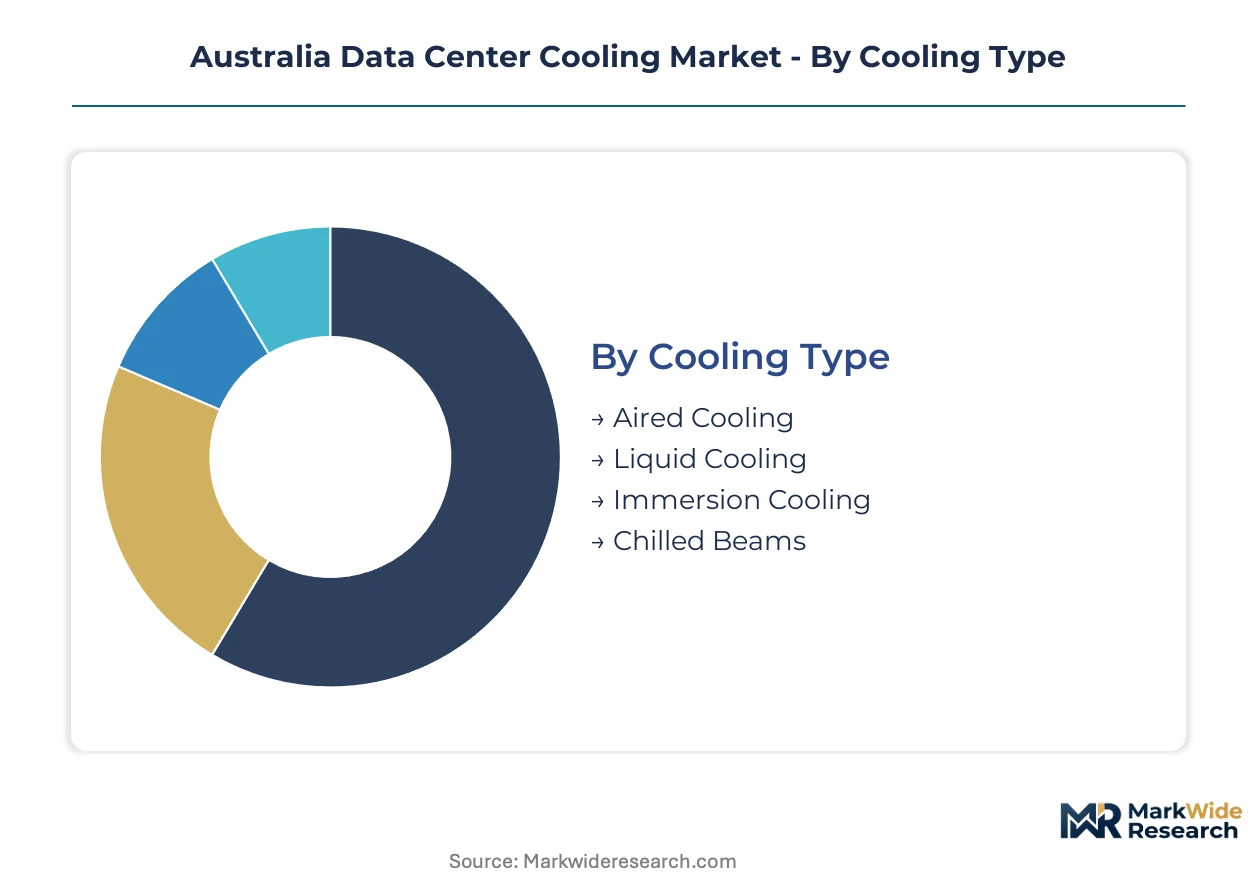
Thermal management procurement in Australian facilities fragments across four distinct dimensions, each carrying unique compliance burdens from TGA refrigerant certification to NCC Section J energy efficiency mandates. Equipment selection and service contracting decisions increasingly hinge on how specific segment combinations navigate these overlapping regulatory frameworks.
Cooling Type:
TGA refrigerant standards and NCC Section J provisions apply asymmetrically across cooling architectures, with liquid and immersion systems facing extended certification timelines while air-cooled units confront stricter efficiency thresholds.
- Liquid Cooling:Direct-to-chip and cold plate configurations circulate dielectric fluid through server-integrated cold plates, achieving thermal dissipation for racks exceeding 50 kW. Cloud service providers in Sydney's Macquarie Park corridor are standardizing around quick-disconnect manifold systems to compress installation windows. TGA certification for alternative refrigerants extends procurement cycles by 8-14 months versus conventional hydrofluorocarbon systems.
- Immersion Cooling:Two-phase and single-phase tanks submerge entire server assemblies in engineered dielectric fluids, eliminating air-side heat exchangers entirely. Hyperscale operators deploying GPU-intensive AI clusters in Melbourne's Fishermans Bend precinct are piloting factory-preconfigured skids to bypass on-site fabrication bottlenecks. Australian Refrigeration Council licensing frameworks have not kept pace with this architecture, creating compliance ambiguity for installation contractors.
- Air Cooling:Precision and computer room air handlers remain dominant in enterprise facilities below 30 kW per rack density, though NCC Section J efficiency mandates are disqualifying legacy compressor technologies from new builds.
- Chilled Beams:Passive and active beam configurations retain niche presence in legacy retrofit applications where existing chilled water infrastructure cannot accommodate liquid cooling manifold integration.
Liquid cooling sits at the top of the volume ranking, with immersion cooling climbing the fastest as GPU rack densities breach commercial viability thresholds.
End User:
Procurement sophistication varies sharply across end-user categories, with cloud service providers demanding power usage effectiveness guarantees while government tenders prioritize compliance documentation over performance metrics.
- Cloud Service Providers:Hyperscale operators commissioning multi-megawatt facilities in Sydney and Melbourne corridors specify embedded thermal controls with automated refrigerant leak detection and reporting protocols. These buyers are unbundling thermal optimization from mechanical maintenance, creating discrete purchasing categories for energy performance guarantees below 1.3 PUE.
- Telecommunications:Edge computing node proliferation across Queensland and Western Australia is driving demand for modular cooling distribution units scalable in 500 kW increments. Telstra and Optus infrastructure divisions are contracting cooling-as-a-service arrangements to transfer capex exposure.
- Enterprises:Mid-market buyers anchor demand for integrated micro data center solutions with embedded thermal controls, though price sensitivity constrains adoption of advanced liquid cooling architectures.
- Government:Commonwealth and state procurement frameworks emphasize NCC Section J compliance documentation and low-global-warming-potential refrigerant specifications over thermal performance optimization.
Cloud service providers command the largest procurement volumes, with telecommunications expanding most quickly as edge infrastructure proliferates beyond Sydney-Melbourne concentration.
Deployment Model:
Facility ownership structures determine whether thermal management is procured as capital equipment or operational service, with colocation and edge models accelerating outsourced thermal optimization.
- Colocation:Third-party facility operators in Melbourne's Fishermans Bend and Sydney's Macquarie Park are contracting vendors to assume inlet temperature risk through performance-guaranteed service agreements. This model concentrates demand for managed services and predictive maintenance contracts.
- Edge Data Centers:Distributed nodes across Queensland and Western Australia require skid-mounted cooling systems factory-preconfigured to minimize remote site commissioning complexity. Standardized quick-disconnect manifolds are modularizing procurement patterns.
- On-Premise:Enterprise-owned facilities retain legacy air-cooled architectures longer due to capital replacement cycles, though GPU workload adoption is forcing premature infrastructure obsolescence.
- Cloud:Hyperscale self-operated facilities drive standardization of cooling distribution units and automated refrigerant management systems across Sydney and Melbourne corridors.
Colocation claims the steepest expansion trajectory among deployment models, with edge data centers gaining share fastest as latency requirements push compute beyond metropolitan cores.
Service Type:
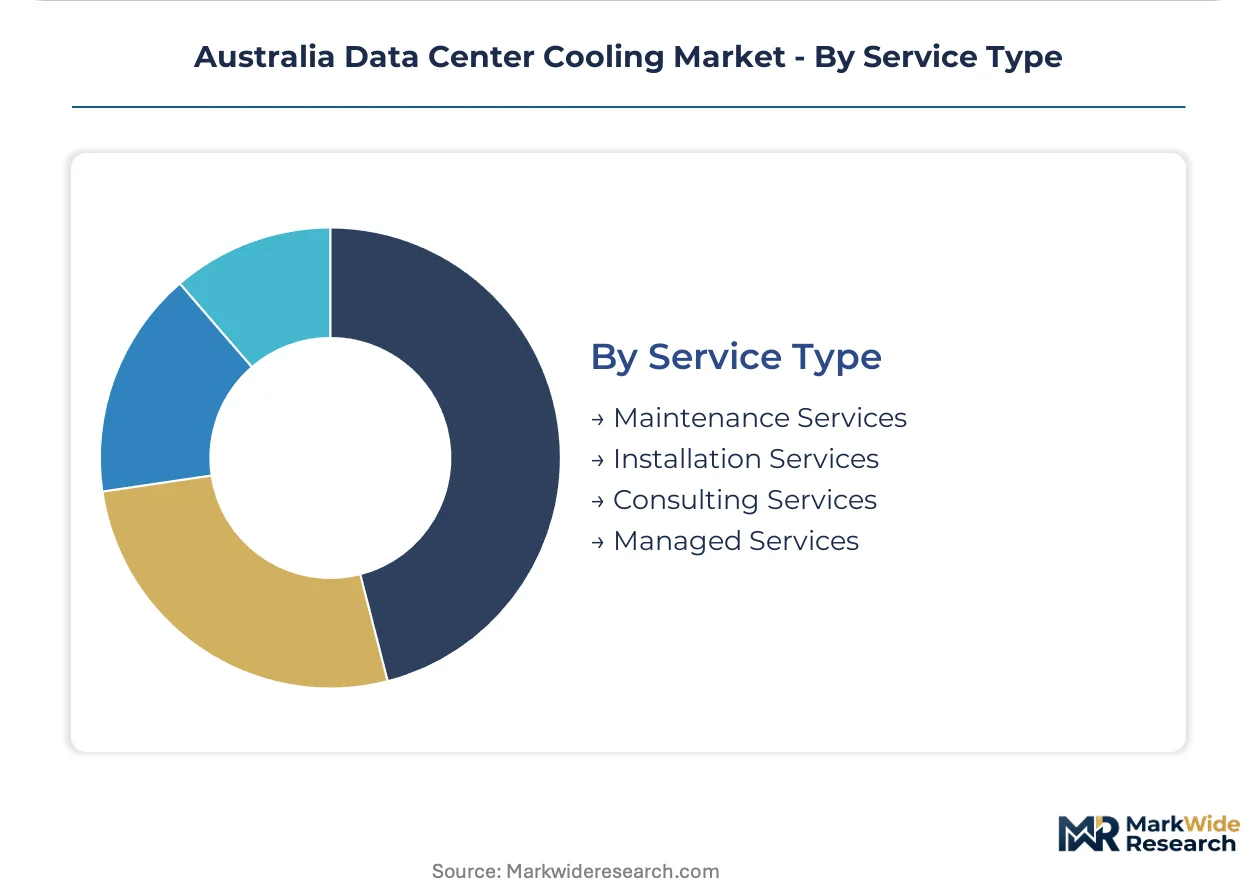
Service procurement patterns are reconfiguring around condition-based maintenance enabled by AI-driven thermal telemetry, though specialized technician scarcity in New South Wales and Victoria constrains installation and commissioning capacity.
- Managed Services:Vendors assume full thermal optimization responsibility including energy performance guarantees and refrigerant compliance reporting. Colocation providers are unbundling this from traditional mechanical maintenance contracts.
- Installation Services:Factory-preconfigured cooling distribution units are compressing on-site installation time, though certified refrigeration mechanics with data center-specific training remain bottlenecked in New South Wales and Victoria.
- Maintenance Services:Machine learning algorithms trained on thermal telemetry are converging with building management systems to enable predictive rather than scheduled servicing.
- Consulting Services:Hybrid deployment engineering combining liquid cooling manifolds with existing chilled water infrastructure requires custom thermal load analysis and compliance pathway navigation.
Managed services lead service-type procurement value, with installation services facing capacity constraints from specialized technician scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified refrigeration mechanics with data center-specific training concentrate disproportionately in New South Wales and Victoria, creating installation bottlenecks that constrain deployment velocity in secondary states. This workforce asymmetry shapes where hyperscale operators can commission advanced liquid cooling systems within contracted timelines.
New South Wales
Sydney's Macquarie Park corridor hosts the densest concentration of multi-megawatt hyperscale facilities, with cloud service providers standardizing around quick-disconnect manifold systems. TGA refrigerant certification requirements extend procurement cycles for alternative cooling fluids. The corridor's cooling distribution unit preconfiguration hubs are compressing on-site installation windows for GPU-intensive AI clusters.
Victoria
Melbourne's Fishermans Bend precinct is emerging as a colocation hub where vendors assume inlet temperature risk through performance-guaranteed service agreements. NCC Section J energy efficiency mandates are disqualifying legacy compressor technologies from new facility tenders. Operators here are piloting factory-preconfigured immersion cooling skids to bypass fabrication bottlenecks.
Queensland
Edge computing node proliferation across Brisbane and regional centers is driving demand for modular cooling systems scalable in 500 kW increments. State-level renewable energy targets are creating policy support for integrated heat recovery configurations. Telecommunications infrastructure divisions are contracting cooling-as-a-service arrangements to transfer capex exposure.
Western Australia
Perth's data center development lags Sydney-Melbourne concentration, offering first-mover positioning as latency requirements push compute beyond metropolitan cores. The Australian Building Codes Board's tightening provisions on building energy efficiency apply equally here, accelerating demand for low-global-warming-potential refrigerants. Remote site commissioning complexity favors skid-mounted systems with minimal on-site fabrication.
South Australia
Adelaide's smaller facility footprint concentrates enterprise and government procurement emphasizing NCC Section J compliance documentation over thermal performance optimization. The state's planning regulations are evolving as thermal load densities climb, requiring stakeholders to monitor amendments before capital commitments crystallize. Legacy air-cooled architectures persist longer here due to extended capital replacement cycles.
Australia Data Center Cooling Market Competitive Landscape
Top-tier vendors anchor precision thermal management for hyperscale deployments above 50 kW per rack, while mid-market specialists capture integrated micro data center demand through embedded control systems. The vendor base stratifies across three archetypes: precision cooling portfolio holders, energy efficiency rating competitors, and integrated infrastructure platform providers. Consolidation pressure is intensifying as GPU-intensive workloads force premature obsolescence of legacy air-cooled architectures. Dominant competitive moves include capacity expansion in Sydney and Melbourne corridors and strategic partnerships for factory-preconfigured skid delivery.
Among precision cooling specialists, Vertiv Group Corp. and Stulz GmbH exemplify the high-density deployment archetype, occupying positions where quick-disconnect manifold standardization is compressing installation timelines. Schneider Electric SE anchors the integrated infrastructure tier, representing the mid-market vector where embedded thermal controls converge with micro data center platforms. Daikin Industries Limited sits within the energy efficiency competitor set, with inverter-driven compressor technology optimized for Australian climate zones serving as its market positioning anchor. These three company structures illustrate how vendor differentiation is fragmenting across performance tiers as AI training clusters diverge from conventional enterprise workloads.
| Leading Market Players |
|---|
| Vertiv Group Corp. |
| Schneider Electric SE |
| Stulz GmbH |
| Rittal GmbH & Co. KG |
| Mitsubishi Electric Corporation |
| Johnson Controls Inc. |
| Daikin Industries Limited |
| Trane Technologies Company LLC |
| Munters Group |
| Others |
Pricing and Supply Chain Analysis
Captive manufacturing of precision cooling distribution units anchors supply positioning for hyperscale operators while compressing procurement cycles against third-party equipment sourcing. Vertiv Group Corp. and Schneider Electric SE leverage in-house fabrication of quick-disconnect manifolds and skid-mounted pumping stations to command pricing power in Sydney and Melbourne corridors, whereas mid-market buyers face cost premiums from outsourced thermal component assembly.
Pricing Analysis
Bundled cooling-as-a-service arrangements are displacing transactional equipment sales as colocation providers transfer capex exposure to vendors. Pricing stratifies across performance-guaranteed service tiers, with PUE commitments below 1.3 commanding substantial premiums over standard maintenance contracts. Cost compression in air-cooled enterprise segments stems from commodity compressor oversupply, while liquid cooling procurement faces upward pressure from TGA certification timelines. Government tenders exhibit highest price sensitivity due to compliance-documentation prioritization, whereas cloud service providers prioritize thermal performance guarantees over unit economics.
Supply Chain Analysis
TGA refrigerant certification and Australian Refrigeration Council licensing create qualification gating that extends procurement cycles for alternative cooling fluids. Heat exchanger fabrication draws from copper and aluminum supply chains concentrated in China, Chile, and Australia, with base metal price volatility transmitting directly to equipment margins. Single-source vulnerability persists for specialized dielectric fluids used in immersion cooling architectures. Distribution runs through factory-preconfiguration hubs in Sydney and Melbourne that compress on-site installation windows for GPU-intensive deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Queensland and Western Australia offer geographic-arbitrage positioning as installation cost differentials against New South Wales and Victoria widen due to certified technician scarcity in secondary states.
For Market Incumbents: Acquire specialized refrigeration mechanics with data center-specific training to bypass installation bottlenecks constraining deployment velocity. Incumbents should expand captive manufacturing capacity for quick-disconnect manifold systems to defend margin position against modular equipment competitors. GPU-intensive AI workload proliferation threatens premature obsolescence of legacy air-cooled portfolios; backward integration into dielectric fluid supply secures input cost control for immersion cooling scaling. For New Entrants and Emerging Players: Enter via cooling-as-a-service arrangements targeting telecommunications edge nodes across Queensland and Western Australia, where capex-transfer demand runs ahead of incumbent service capacity. The most penetrable white space sits in 500 kW modular cooling distribution units for remote site deployment. A direct go-to-market angle partners with Optus and Telstra infrastructure divisions on standardized skid configurations that minimize commissioning complexity. For Investors and Strategic Acquirers: Roll-up economics work for precision cooling specialists with TGA-certified refrigerant portfolios because certification timelines create defensible moats against commodity equipment competitors. Long-term viability hinges on exposure to liquid and immersion cooling architectures as power densities breach air-cooled thermal limits. The signal to watch is NCC Section J amendment velocity, which determines the rate of legacy equipment disqualification from new facility tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Factory-Preconfiguration Hub Expansion | Compresses on-site installation windows for Sydney and Melbourne hyperscale corridors. |
| TGA Alternative Refrigerant Certification | Unlocks procurement pathways for low-global-warming-potential cooling fluids in new builds. |
| Cooling-as-a-Service Platform Launch | Captures colocation demand for performance-guaranteed thermal optimization contracts. |
| Heat Recovery System Integration | Aligns with Queensland state renewable energy targets for waste heat valorization revenue. |
| AI-Driven Predictive Maintenance Deployment | Enables condition-based servicing contracts through thermal telemetry machine learning. |
Research Methodology
Coverage spans New South Wales, Victoria, Queensland, Western Australia, and South Australia, with primary inputs from each jurisdiction's facility operators and equipment vendors. The analysis combines structured interviews with data center engineering directors, refrigeration contractor licensing bodies, and colocation procurement leads with secondary validation from Australian Building Codes Board NCC amendments, TGA refrigerant registration databases, and state-level planning authority filings. Bottom-up equipment shipment tracking and top-down facility capacity announcements were triangulated to anchor volume estimates.
Rate-of-change decomposition separates installed base replacement demand from incremental capacity additions across the projection horizon. Segmentation dimensions modeled include cooling type, end-user category, deployment model, and service type, with state-level regulatory cluster as an additional geographic dimension. CAGRs were derived from logistic adoption curves fitted to liquid cooling penetration thresholds and hyperscale facility commissioning timelines. Forecast inputs incorporate GPU rack density trajectories and NCC Section J compliance phase-in assumptions.
Inputs from Australian Refrigeration Council licensing records and state planning authority approval databases were available through the study window; gaps in real-time facility commissioning data introduce uncertainty bands around near-term capacity estimates. Forecasts reflect assumptions on technician training pipeline expansion and alternative refrigerant certification velocity. A model refresh is warranted upon material change in NCC amendment schedules or TGA refrigerant approval pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Data Center Cooling Market
Data Center Cooling
Global Laptop Cooling Pads Market
Data Center Cooling
Nigeria Data Center Cooling Market
Data Center Cooling
Uk Data Center Cooling Market
Data Center Cooling
Japan Data Center Cooling Market
Data Center Cooling
Europe Data Center Cooling Market
Data Center Cooling
Adiabatic Dry Cooler Market
Data Center Cooling
Liquid Cooling Racks Market
Data Center Cooling
Mexico Data Center Cooling Market
Data Center Cooling
Italy Data Center Cooling Market
Data Center Cooling
Indonesia Study of Data Center Water Consumption Market
Data Center Cooling
Chile Data Center Cooling Market
Data Center Cooling
Denmark Data Center Cooling Market
Data Center Cooling
France Data Center Cooling Market
Data Center Cooling
Austria Data Center Cooling Market
Data Center Cooling
Saudi Arabia Data Center Cooling Market