
 Avionics Software Market | 2026-2036
Avionics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Avionics Software Market Insights
Market Context
OEM-direct procurement is tilting toward long-term software licensing agreements with embedded update commitments. Honeywell International Inc. leverages its integrated flight deck ecosystem to lock in recurring service revenue across commercial and military platforms. RTX Corporation anchors its position through classified defense avionics programs where security-cleared development teams create high switching costs. Thales Group competes on European sovereignty credentials, winning French and German military contracts that require domestic source code control.
Technical Definition and Segment Structure
Avionics software encompasses the embedded operating systems, application layers, and certification artifacts that govern aircraft flight control, navigation, communication, and surveillance functions, typically developed under DO-178C DAL A through D assurance levels for safety-critical execution. Flight Management System software commands the largest installed base and generates the steadiest maintenance revenue, while Surveillance Software and Mission Planning segments expand fastest as unmanned platforms multiply and sense-and-avoid mandates proliferate across civilian airspace. Deployment architecture shows a decisive shift from purely onboard systems toward hybrid models that synchronize airframe processors with ground control stations and edge-computing nodes, redistributing latency tolerance and cybersecurity exposure across the operational chain.
Regulatory Frame and Outlook
FAA DO-178C and EU EASA CS-25 software standards enforce rigorous verification matrices that stretch development timelines and elevate barrier costs for new entrants. China's NMPA-equivalent civil aviation regulator and India's DGCA are adopting harmonized certification pathways that open qualified foreign suppliers to their expanding airline fleets while demanding local code review facilities. Stakeholders must monitor how emerging AI-assisted flight functions trigger reinterpretation of existing assurance levels before committing multi-year development roadmaps.
Market Dynamics
FAA DO-178C and EU EASA CS-25 software standards are compressing development timelines while elevating certification costs, forcing OEMs to consolidate supplier relationships around proven verification track records.
Growth Catalysts
- Autonomous Flight Mandates:Sense-and-avoid requirements for unmanned aircraft systems in civilian airspace are expanding Surveillance Software procurement across commercial and defense platforms.
- FAA Certification Harmonization:India's DGCA and China's civil aviation regulator are adopting DO-178C-aligned pathways, opening qualified foreign suppliers to their expanding airline fleets.
- Digital Cockpit Retrofits:Narrow-body and wide-body fleet operators are replacing legacy analog systems with integrated flight deck software to reduce pilot workload and fuel burn.
Market Restraints
- Verification Cost Escalation:DO-178C DAL A certification artifacts require 50-100 lines of objective evidence per line of code, stretching development budgets for new entrants.
- Security-Cleared Labor Pool:Classified defense avionics programs depend on cleared software engineers concentrated in the United States, creating geographic supply constraints.
- Legacy Hardware Lock-In:Proprietary processor architectures in installed commercial fleets resist open-standard software ports, fragmenting upgrade pathways.
Strategic Opportunities
- Ground-Air Hybrid Architectures:Edge-computing nodes and ground control station synchronization are redistributing flight-critical functions, opening software licensing models beyond airframe-embedded delivery.
- AI-Assisted Flight Functions:Machine learning inference engines for predictive maintenance and trajectory optimization are triggering regulatory reinterpretation of existing assurance levels.
- European Sovereignty Procurement:French and German military contracts now require domestic source code control and local verification facilities, favoring suppliers with EU-based development centers.
Industry Challenges
- DO-178C Talent Scarcity:Verification engineers with DAL A through D certification experience command premium compensation, constraining program staffing velocity.
- Multi-Domain Integration Complexity:Flight Management System software must now synchronize with cybersecurity-hardened communication stacks and satellite navigation constellations, expanding test matrix scope.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Avionics Software Market |
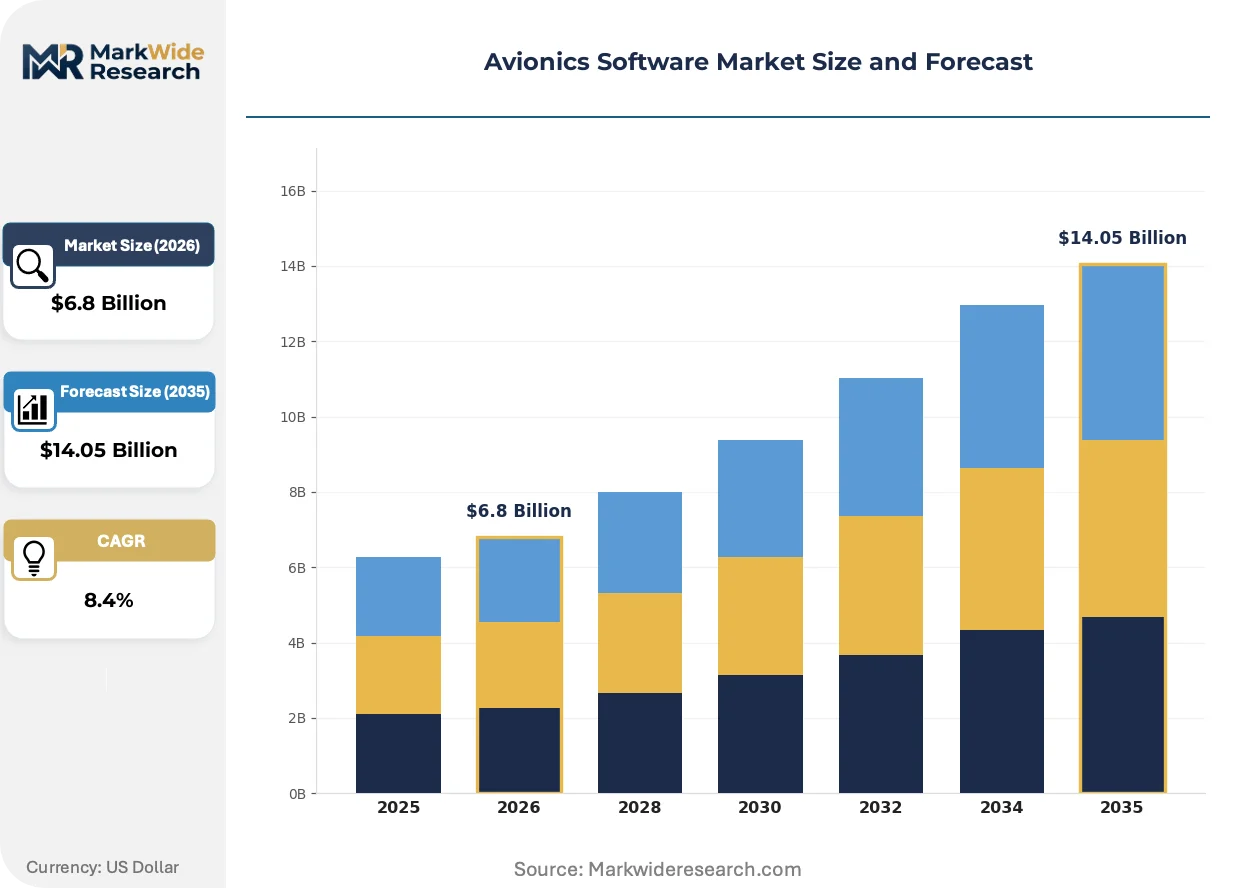
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Management System, Navigation Software, Communication Software, Surveillance Software, Mission Planning, Data Management Deployment: Onboard Systems, Ground Control Stations, Cloud-Based Solutions, Edge Computing Platforms, Hybrid Models Application: Commercial Aircraft, Military Aircraft, Unmanned Aerial Vehicles, Helicopters, Spacecraft End User: Airlines, Defense Contractors, UAV Operators, Space Agencies, Maintenance Providers |
| Companies Covered | Honeywell International Inc., RTX Corporation, Thales Group, L3Harris Technologies Inc., Garmin Ltd, BAE Systems, Safran SA, GE Aviation, Boeing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Avionics Software Market Trends and Innovations
Avionics software architecture is decoupling from monolithic airframe processors, redistributing computational load across ground networks and edge nodes while regulatory frameworks scramble to assure safety across distributed execution environments.
Model-based development environments are replacing hand-coded implementations for Flight Management System software. Commercial airlines and business jet OEMs are adopting automatic code generation from formal specifications to compress verification cycles. The practice is migrating from experimental programs into production line-fit and retrofit contracts, compressing supplier differentiation around tool chain expertise rather than raw coding capacity.
EU EASA is advancing interpretive guidance for AI-assisted flight functions under existing CS-25 software standards, creating provisional certification pathways for neural network-based trajectory prediction. European narrow-body operators are piloting these systems on revenue routes under restricted operational conditions. The segment most affected is single-aisle commercial transport, where airlines are demanding software update commitments that extend through 2040 fleet lifecycles.
Airlines are unbundling software maintenance from hardware service contracts, negotiating direct licensing agreements with avionics software vendors. This disintermediates traditional OEM aftermarket channels and shifts recurring revenue toward subscription-based update delivery. The pattern is most visible in the United States, where Delta, United, and American have established dedicated software procurement functions separate from airframe technical operations.
Avionics Software Market Segmentation
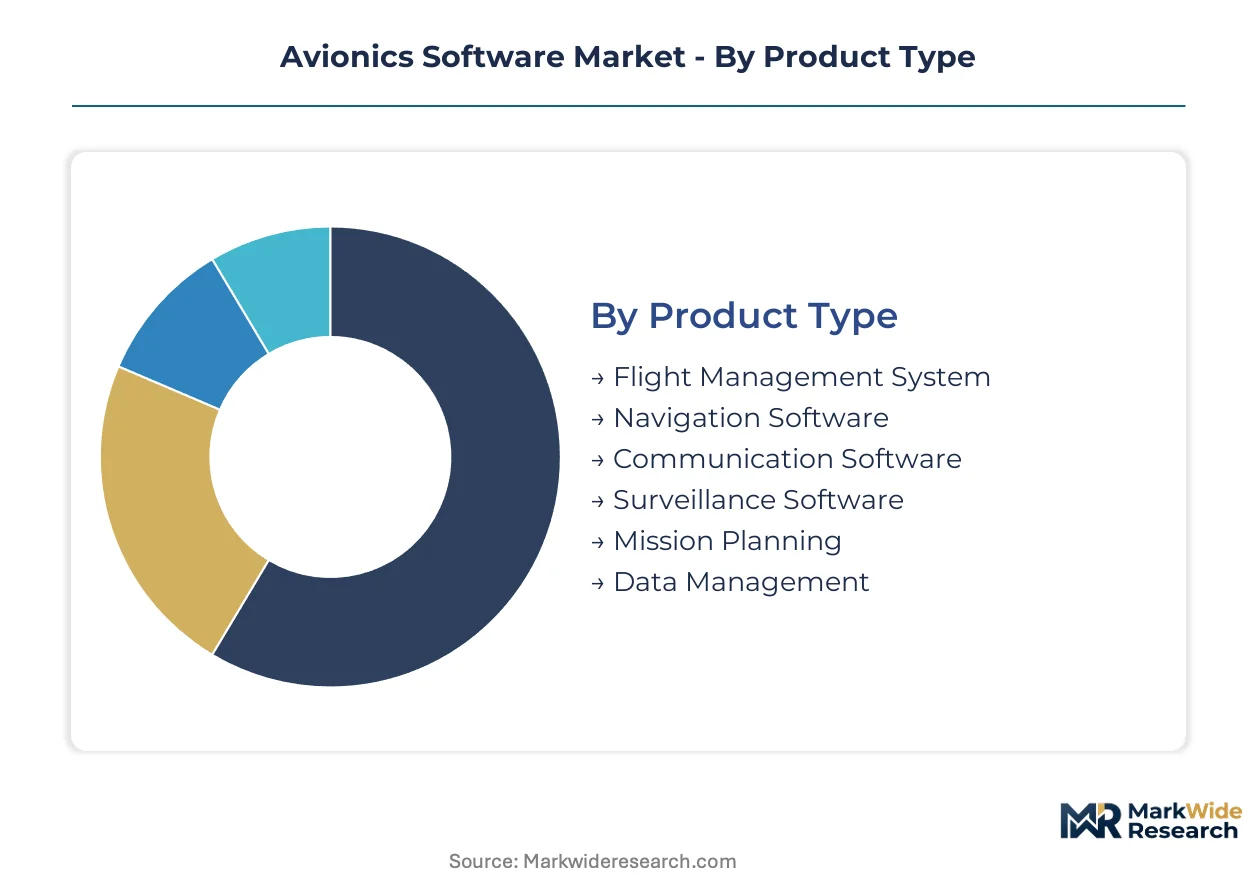
Avionics software procurement cycles vary dramatically by segment, with flight-critical systems demanding decade-long certification timelines while cloud-based deployments refresh annually. Understanding these velocity differentials shapes supplier resource allocation and R&D prioritization across the value chain.
Product Type:
Flight Management System software commands the longest replacement cycles due to airworthiness recertification requirements, while Surveillance Software and Mission Planning refresh most frequently as threat environments and sense-and-avoid mandates evolve.
- Flight Management System:Embedded operating systems governing trajectory computation, fuel optimization, and autopilot integration under DO-178C DAL A assurance levels. Commercial airlines in the United States anchor installed base maintenance, though DAL A verification artifacts stretch development budgets for new suppliers.
- Surveillance Software:Sense-and-avoid algorithms and traffic collision avoidance systems processing ADS-B and radar inputs. Unmanned Aerial Vehicle operators in civilian airspace drive procurement acceleration as FAA mandates expand beyond visual line-of-sight operations.
- Navigation Software:GPS/GNSS augmentation and inertial reference system interfaces.
- Communication Software:VHF datalink and satellite communication protocol stacks.
- Mission Planning:Route optimization and payload management for defense and unmanned platforms.
- Data Management:Flight data recording and predictive maintenance analytics engines.
Flight Management System anchors the volume base while Surveillance Software gains share at the steepest rate.
Deployment:
Cost tiering separates embedded airframe processors requiring hardware-software co-certification from ground-based alternatives that trade latency tolerance for deployment flexibility.
- Onboard Systems:Airframe-embedded processors executing flight-critical functions under real-time operating systems with deterministic latency guarantees. Boeing and Airbus production lines in the United States and France concentrate procurement, though proprietary architectures resist open-standard ports.
- Hybrid Models:Distributed architectures synchronizing onboard execution with ground-based computation for non-critical functions. European narrow-body operators pilot these configurations under EASA provisional guidance, redistributing cybersecurity exposure across operational chains.
- Ground Control Stations:Remote piloting interfaces for unmanned platforms.
- Cloud-Based Solutions:Fleet-wide analytics and software update distribution infrastructure.
- Edge Computing Platforms:Localized processing nodes reducing backhaul dependency.
Onboard Systems capture the premium pricing tier while Hybrid Models expand most quickly as regulatory frameworks accommodate distributed execution.
Application:
Customer maturity stratifies the market, with commercial aviation demanding exhaustive certification heritage and military programs tolerating higher technical risk for capability advantage.
- Commercial Aircraft:Integrated flight deck software for narrow-body and wide-body fleets replacing analog systems. United States airlines including Delta and United unbundle software procurement from hardware contracts, negotiating direct licensing with update commitments extending through fleet lifecycles.
- Unmanned Aerial Vehicles:Autonomous navigation and sense-and-avoid systems for civilian and defense platforms. FAA beyond-visual-line-of-sight rulemaking and EU U-space regulation expansion concentrate investment in detect-and-avoid algorithm development.
- Military Aircraft:Classified avionics suites with security-cleared development requirements.
- Helicopters:Rotorcraft-specific flight control and terrain awareness systems.
- Spacecraft:Guidance, navigation, and control software for launch vehicles and orbital platforms.
Commercial Aircraft generates the largest revenue pool while Unmanned Aerial Vehicles climb the fastest as airspace integration accelerates.
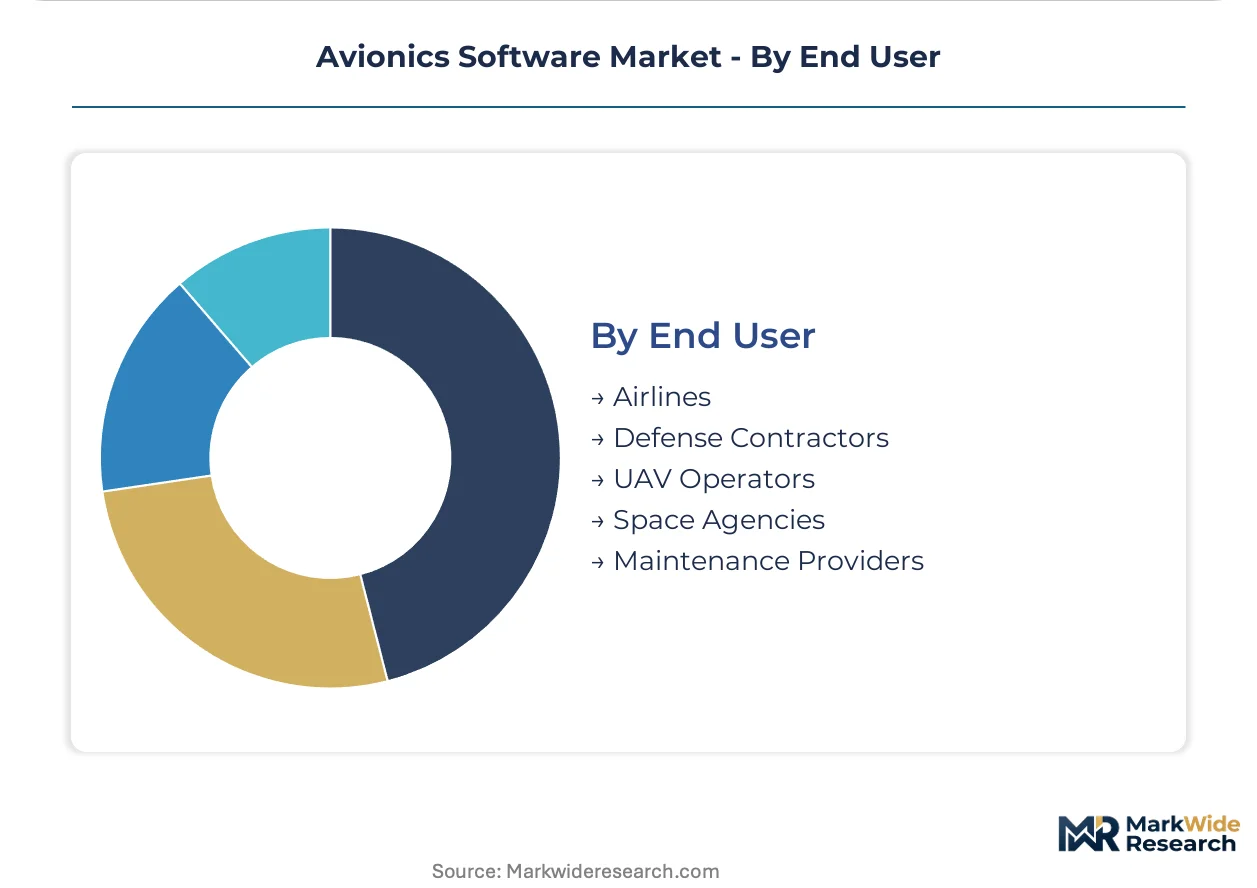
End User:
Procurement authority concentration varies sharply, with defense contractors exercising multi-year program control and maintenance providers fragmenting across distributed service networks.
- Defense Contractors:RTX Corporation and classified primes in the United States anchor procurement through security-cleared development teams. French and German military contracts now require domestic source code control, favoring suppliers with EU-based verification facilities.
- Airlines:Major carriers establishing dedicated software procurement functions separate from technical operations. United States network carriers lead this disintermediation trend, shifting recurring revenue toward subscription-based update delivery.
- UAV Operators:Commercial drone fleet managers and defense unmanned system integrators.
- Space Agencies:NASA and ESA procurement for crewed and uncrewed mission software.
- Maintenance Providers:Third-party repair stations managing legacy fleet software updates.
Defense Contractors dominate classified program value while Airlines reshape commercial aftermarket economics through direct vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA DO-178C certification mandates anchor procurement volumes in the United States, while EU EASA CS-25 standards and China's harmonized pathways reshape supplier access across major aviation economies.
United States
Boeing and defense primes concentrate avionics software procurement in the Seattle and Dallas-Fort Worth corridors. FAA DO-178C DAL A certification requirements create high switching costs for qualified suppliers. Security-cleared development teams in the Washington DC-Baltimore corridor dominate classified defense avionics programs.
France
Thales Group and Safran SA anchor domestic source code control requirements for military contracts. EU EASA CS-25 interpretive guidance for AI-assisted flight functions advances through Paris-based regulatory working groups. The Toulouse aerospace cluster concentrates narrow-body flight deck software integration for Airbus production lines.
Germany
German military procurement mandates domestic verification facilities and sovereign code review for avionics systems. EASA provisional certification pathways for hybrid ground-air architectures pilot through Munich and Hamburg engineering centers. The Bavarian aerospace corridor hosts specialized DO-178C verification tooling development.
China
China's civil aviation regulator adopts DO-178C-aligned certification pathways for qualified foreign suppliers. COMAC C919 production expansion drives flight management system software procurement in the Shanghai Yangtze River Delta cluster. Local code review facilities in Beijing and Xi'an process regulatory submissions for imported avionics systems.
India
DGCA harmonization with FAA certification standards opens qualified foreign suppliers to IndiGo and Air India fleet expansion. Software development centers in Bengaluru and Hyderabad supply verification engineering talent for global avionics programs. Indian carriers establish direct software licensing negotiations separate from airframe technical operations.
Avionics Software Market Competitive Landscape
Integrated flight deck ecosystem providers and classified defense specialists split the market between commercial aftermarket recurring revenue and security-cleared program capture. The supplier base concentrates around three strategic archetypes: vertically integrated aerospace conglomerates with captive software divisions, independent avionics software houses with certification heritage, and defense primes with cleared development infrastructure. Consolidation pressure intensifies as DO-178C verification cost escalation favors proven track records over new entrant innovation.
Among the integrated ecosystem tier, Honeywell International Inc. exemplifies the flight deck bundling archetype, while RTX Corporation represents the cleared-defense specialist position. Thales Group occupies the European sovereignty tier, anchoring contracts that mandate domestic source code control. These three patterns illustrate how certification barriers and procurement nationalism reshape competitive positioning across commercial and military segments.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| RTX Corporation |
| Thales Group |
| L3Harris Technologies Inc. |
| Garmin Ltd |
| BAE Systems |
| Safran SA |
| GE Aviation |
| Boeing Company |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on security-cleared verification engineers in the United States compresses both pricing tier spreads and supply chain geography, forcing buyers to absorb DAL A certification premiums or accept longer lead times from cleared-labor pools. FAA DO-178C artifact requirements amplify this structural constraint, embedding labor scarcity directly into cost structures across commercial and defense procurement channels.
Pricing Analysis
Configured-to-order pricing for DAL A flight-critical systems commands substantial premiums over standard DAL C/D configurations, with subscription-based licensing models now dominating commercial airline procurement. Price differentiation hinges on certification grade and vertical integration depth, with Honeywell and RTX leveraging captive verification teams to sustain margin structures. Pricing pressure stems from Indian and Chinese carriers negotiating direct vendor relationships that bypass traditional OEM aftermarket channels. Defense contractors exhibit lowest price sensitivity due to security-cleared labor scarcity, while regional airlines face acute cost compression.
Supply Chain Analysis
Specialized processor architectures and real-time operating system licenses feed from concentrated design centers in the United States, France, and Germany, with verification tooling development anchored in Bavarian and Dallas-Fort Worth engineering clusters. Raw material dependencies center on radiation-hardened semiconductors, deterministic memory modules, and aerospace-grade firmware repositories. Single-source vulnerability pervades security-cleared development teams concentrated in the Washington DC-Baltimore corridor. Distribution runs through OEM-direct channels for line-fit systems and airline procurement functions for retrofit and update services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Avionics software is shifting toward platform-economics dynamics as flight deck ecosystems integrate ground-air hybrid architectures and subscription-based update delivery, with interoperability mandates from EASA and FAA accelerating vendor consolidation around integrated stack providers.
For Market Incumbents: Harden verification capacity in security-cleared labor pools against emerging AI-assisted flight function entrants that threaten to bypass traditional DAL A certification pathways. Deepen backward integration into model-based development tooling to compress cycle times against automatic code generation competitors. Fortify European sovereignty credentials through domestic source code control facilities in France and Germany. For New Entrants and Emerging Players: Mid-tier commercial UAV operators in civilian airspace represent the most penetrable entry point, with sense-and-avoid algorithm development offering lower certification barriers than flight management systems. Indian DGCA-harmonized certification pathways open qualified foreign supplier access to IndiGo and Air India fleet expansion. Target ground-control-station software for hybrid architectures where latency tolerance permits non-DAL A development. For Investors and Strategic Acquirers: EASA interpretive guidance for AI-assisted flight functions under CS-25 standards reshapes the acquisition landscape toward verification-tooling specialists and neural-network safety-assurance firms. Long-term viability favors suppliers with demonstrated DAL A track records across multiple regulatory jurisdictions. Monitor FAA beyond-visual-line-of-sight rulemaking velocity as inflection indicator for surveillance software valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Model-Based Development Tooling Acquisition | Compresses DO-178C verification cycles for Flight Management System suppliers competing on delivery speed. |
| European Sovereignty Certification Investment | Unlocks French and German military contracts requiring domestic source code control and local verification facilities. |
| Ground-Air Hybrid Architecture Partnership | Redistributes computational load across edge nodes, opening subscription revenue streams beyond airframe-embedded delivery. |
| AI-Assisted Flight Function Regulatory Pathway | Positions early movers for EASA provisional certification of neural network-based trajectory prediction systems. |
| Security-Cleared Verification Center Expansion | Addresses classified defense program labor constraints concentrated in the Washington DC-Baltimore corridor. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FAA certification databases, EASA regulatory guidance documents, and OEM procurement disclosures. Primary interviews engaged avionics software engineering directors, airline technical procurement managers, defense program verification leads, and regulatory affairs specialists at civil aviation authorities. Secondary validation drew from DO-178C audit records, airline fleet upgrade announcements, and defense contract award notifications. Bottom-up segment sizing triangulated against top-down aerospace electronics spending analysis.
Forecast inputs span deployment architecture shifts, certification pathway harmonization across FAA and DGCA, and unmanned platform proliferation rates. Segmentation dimensions modeled include product type, deployment model, application category, and end-user procurement authority. CAGRs derive from installed base replacement cycles, fleet expansion trajectories, and software update frequency trends. Industry-specific inputs incorporate DAL A certification timeline elasticity and security-cleared labor pool growth constraints.
Stress conditions across regulatory reinterpretation velocity, AI-assisted function approval timelines, and European sovereignty procurement enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding certification harmonization progress and unmanned airspace integration pace. Cross-checking against airline capital expenditure disclosures and defense R&D budget allocations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Family Office Software Solutions Market
Software & Services
Photo Editing Software Market
Software & Services
Global Budgeting Software Market
Software & Services
PCB Design Software Market
Software & Services
Global HVAC Software Market
Software & Services
Audio and Video Editing Software Market
Software & Services
Quick Service Restaurants (QSR) IT Market
Software & Services
Document Capture Software Market
Software & Services
Global Mindfulness Meditation Apps Market
Software & Services
Cloud Testing and ASQ Software Market
Software & Services
Sales Dialer Software Market
Software & Services
ITSM Market
Software & Services
Global Recipe Apps Market
Software & Services
Laboratory Management Software Market
Software & Services
Global Headless CMS Software Market
Software & Services
US Enterprise Legal Management Software Market