
 Europe Business Software Market | 2026-2036
Europe Business Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Business Software Market Foresight
Germany's industrial software corridor is rewriting procurement patterns across the continent. SAP SE leverages its deep manufacturing heritage to anchor enterprise resource planning deployments in automotive and chemical sectors. Microsoft Corporation competes through cloud infrastructure density and platform integration breadth. Sage Group specializes in mid-market financial automation, occupying a distinct tier below full-suite ERP providers.
Europe Business Software encompasses enterprise applications for customer relationship management, resource planning, supply chain coordination, and human capital administration, typically delivered through modular architectures with API interoperability and role-based access controls. The primary commercial purpose is operational digitization, workflow automation, and real-time decision support across distributed organizations. Cloud-based and SaaS deployment modes now lead new installations, while on-premise retention persists in defense and critical infrastructure verticals where data sovereignty requirements dominate. CRM and ERP together capture the deepest margin pools, though HRM segments show faster trajectory among mid-market buyers replacing legacy payroll systems.
EU AI Act enforcement through national regulators, GDPR data residency mandates, and EBA guidelines on cloud outsourcing collectively shape product architecture and vendor liability frameworks across member states. CE marking for software with safety implications and CSRD reporting obligations further tighten compliance integration into platform roadmaps. Stakeholders must weigh interoperability investments against the fragmentation risk of divergent national implementation timelines for Brussels-level digital regulations.
Market Dynamics
The EU AI Act is forcing architectural redesigns across enterprise software stacks as algorithmic accountability requirements cascade from Brussels through national regulators. Vendors must embed explainability modules and risk classification frameworks directly into core platforms, compressing development timelines and expanding compliance budgets.
Growth Catalysts
- GDPR data residency mandates:Sovereign cloud deployments in Frankfurt and Paris data centers are pulling mid-market buyers off legacy on-premise systems.
- France's financial services sector:Algorithmic trading compliance and real-time risk engines are driving CRM and ERP replacement cycles.
- Generative AI integration:Natural language interfaces for enterprise search and contract analysis are expanding addressable seats per license.
Market Restraints
- CSRD reporting obligations:Scope 3 emissions tracking requirements are extending implementation timelines by eight to fourteen months for manufacturing clients.
- CE marking complexity:Safety-critical software modules in automotive and medical verticals face eighteen-month certification windows.
- Substitution by open-source ERP:Odoo and ERPNext deployments are capturing cost-sensitive mid-market accounts in Spain and Italy.
Strategic Opportunities
- Poland's underpenetrated manufacturing base:Shared service centers for German automotive suppliers are creating demand for Polish-language HRM and SCM modules.
- EU Green Deal procurement rules:Public sector tenders now require carbon footprint disclosure tools, opening municipal and utility verticals.
- Edge-to-cloud orchestration:Convergence of 5G private networks with containerized microservices is enabling predictive maintenance in chemical plants.
Industry Challenges
- Embedded systems integration:Shop-floor PLC protocols from Siemens and Rockwell Automation resist standard API connectivity, requiring custom middleware development.
- AI Act risk classification expertise:Shortage of qualified legal-technical translators is throttling product roadmap execution for high-risk system vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Business Software Market |
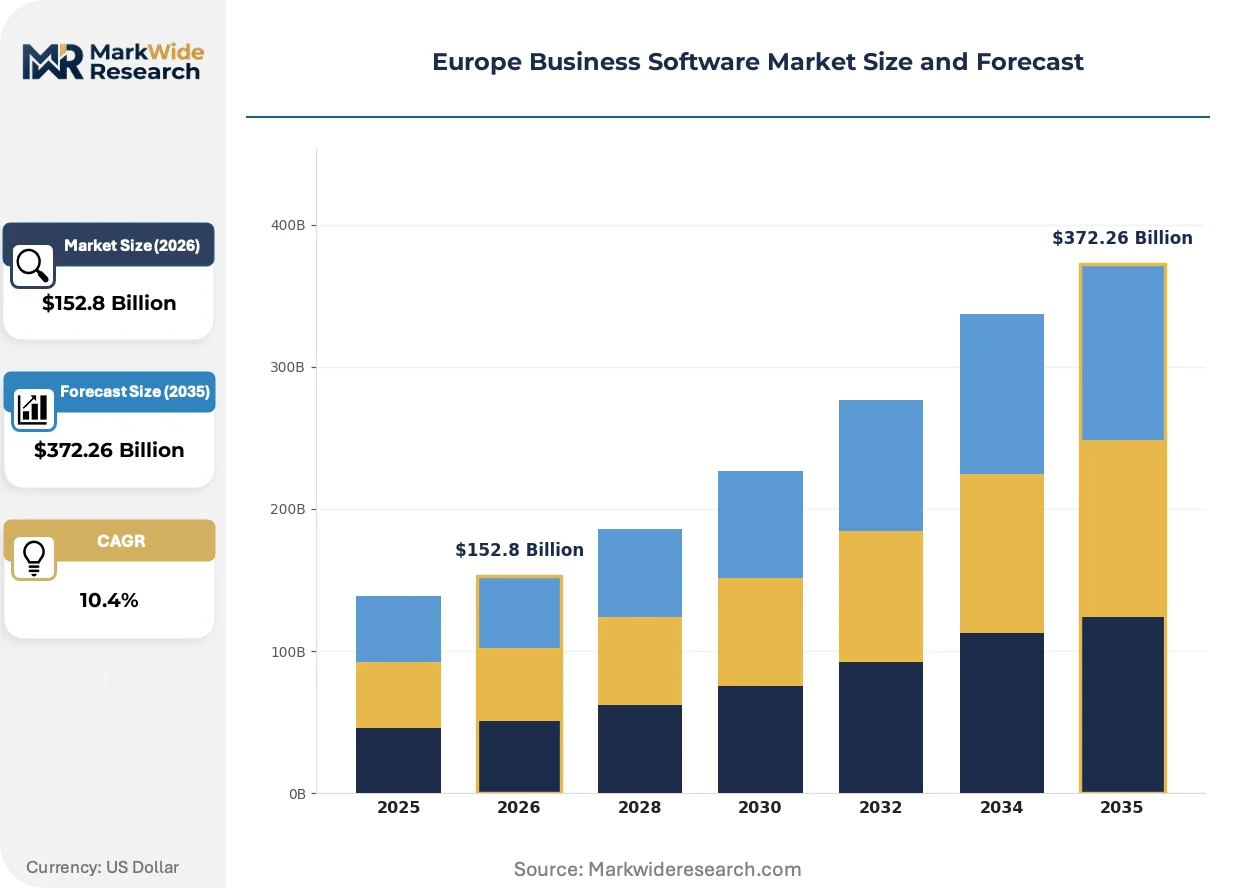
| Market Size in 2026 | $152.8 Billion |
| Market Size in 2035 | $372.26 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CRM, ERP, SCM, HRM Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: SMEs, Large Enterprises, Startups, Corporates Industry Vertical: Retail, Healthcare, Financial Services, Education |
| Companies Covered | Salesforce, Sage Group, SAP SE, IFS, Unit4, Microsoft Corporation, Workday, Dassault Systèmes, Oracle Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Business Software Market Shifts & Advancements
Enterprise software architectures are fragmenting into composable microservices as buyers reject monolithic suites. This decomposition is accelerating API-first development and rewiring vendor competitive moats around integration density rather than feature breadth.
Composable ERP architectures are hybridizing transaction processing with embedded analytics engines. Automotive suppliers in Stuttgart and Wolfsburg are piloting these stacks to unify MES and financial planning on single data fabrics. The technology is hybridizing procurement decisions by collapsing the traditional separation between operational and analytical systems.
The EU AI Act's risk-tiered obligations are mandating algorithmic impact assessments for high-risk deployments. Banking software vendors must now document training data provenance and model drift monitoring before national regulator approval. France's CNIL and Germany's KBA are interpreting Brussels guidelines with divergent enforcement calendars, creating compliance fragmentation.
Mid-market buyers are consolidating vendor relationships around platform ecosystems rather than best-of-breed point solutions. French insurance distributors and Dutch logistics operators are replacing three to four standalone tools with Microsoft or SAP native modules. This concentration is most visible in the Benelux region, where IT headcount constraints favor integrated support models over specialized implementations.
Europe Business Software Market Segmentation
Business software purchasing in Europe fragments across deployment preferences, organizational scale, and sector-specific compliance burdens. Vendors must architect modular platforms that traverse these boundaries without sacrificing regulatory coherence across GDPR, EU AI Act, and national implementations.
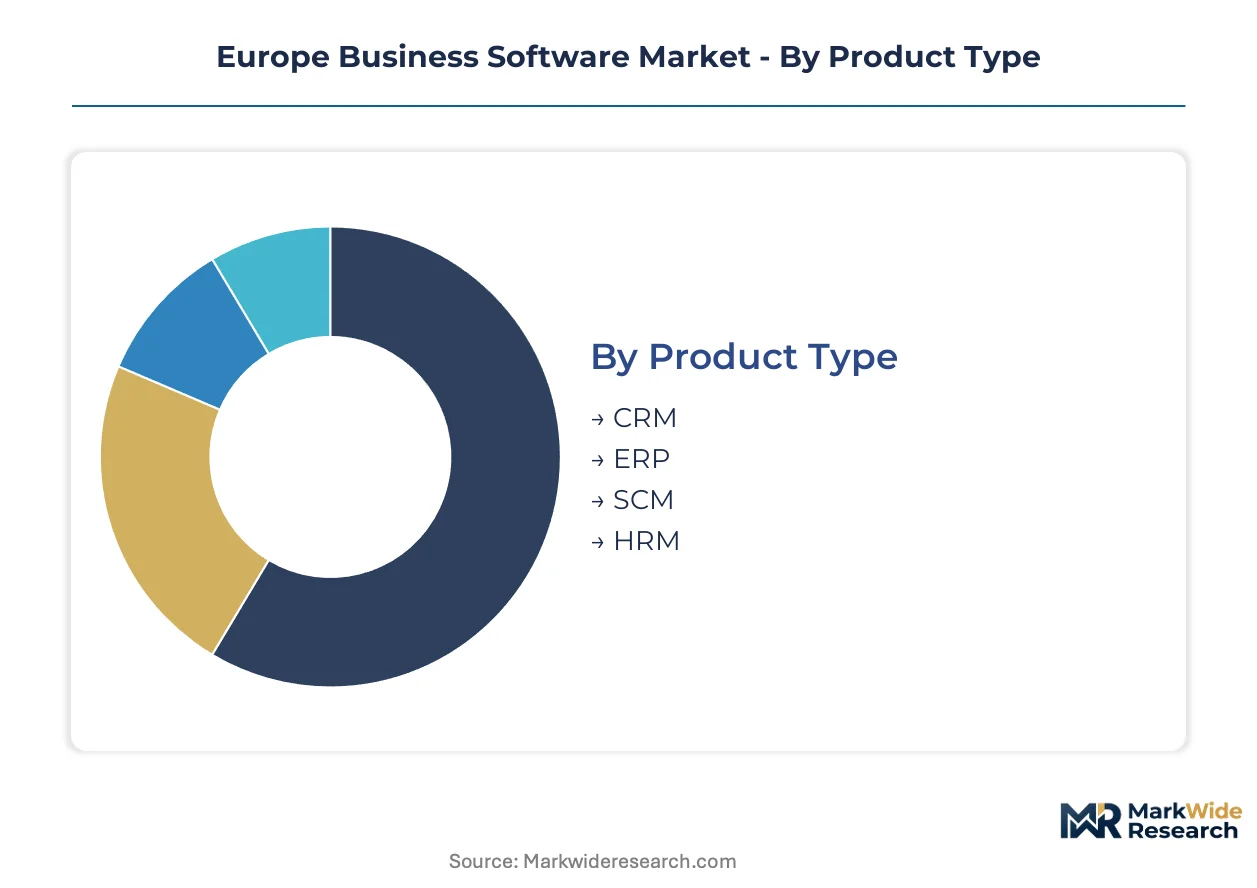
Product Type:
Mature suites dominate installed bases while emerging categories capture replacement cycles and greenfield expansion.
- CRM:Customer relationship management platforms integrate predictive lead scoring and conversation intelligence. French insurance distributors and Dutch logistics operators are consolidating around native modules within broader ecosystems, driven by IT headcount constraints favoring unified support models.
- ERP:Enterprise resource planning systems anchor manufacturing digitization with embedded analytics engines unifying MES and financial planning. Stuttgart and Wolfsburg automotive suppliers pilot composable stacks collapsing operational-analytical system boundaries.
- SCM:Supply chain management tools coordinate multi-tier supplier networks with real-time visibility.
- HRM:Human capital platforms replace legacy payroll systems fastest among mid-market buyers.
ERP retains volume leadership; HRM holds the steepest expansion curve.
Deployment:
Cost tier stratification separates premium sovereign infrastructure from economy multi-tenant offerings.
- Cloud-Based:Sovereign cloud deployments in Frankfurt and Paris data centers pull mid-market buyers off legacy systems, satisfying GDPR residency mandates without on-premise capital burden. German automotive manufacturers accelerate adoption here.
- SaaS:Subscription delivery models dominate new installations with natural language interfaces expanding addressable seats per license through generative AI integration for enterprise search and contract analysis.
- On-Premise:Retention persists in defense and critical infrastructure where data sovereignty requirements dominate procurement decisions.
- Hybrid:Edge-to-cloud orchestration enables predictive maintenance in chemical plants through 5G private network convergence.
Cloud-Based captures the deepest revenue pool; SaaS climbs the fastest among net-new deployments.
End User:
Customer type determines implementation complexity and compliance integration depth.
- Large Enterprises:Full-suite ERP deployments with algorithmic accountability modules embedded for EU AI Act risk classification. Banking software vendors here document training data provenance before national regulator approval.
- SMEs:Consolidated vendor relationships around platform ecosystems replace three to four standalone tools, concentrated in Benelux where specialized implementation capacity is scarce.
- Corporates:Multi-entity governance requirements drive API-first architectures.
- Startups:Cost-sensitive adoption of open-source alternatives in Southern Europe.
Large Enterprises command the highest per-seat pricing; SMEs represent the broadest addressable base.
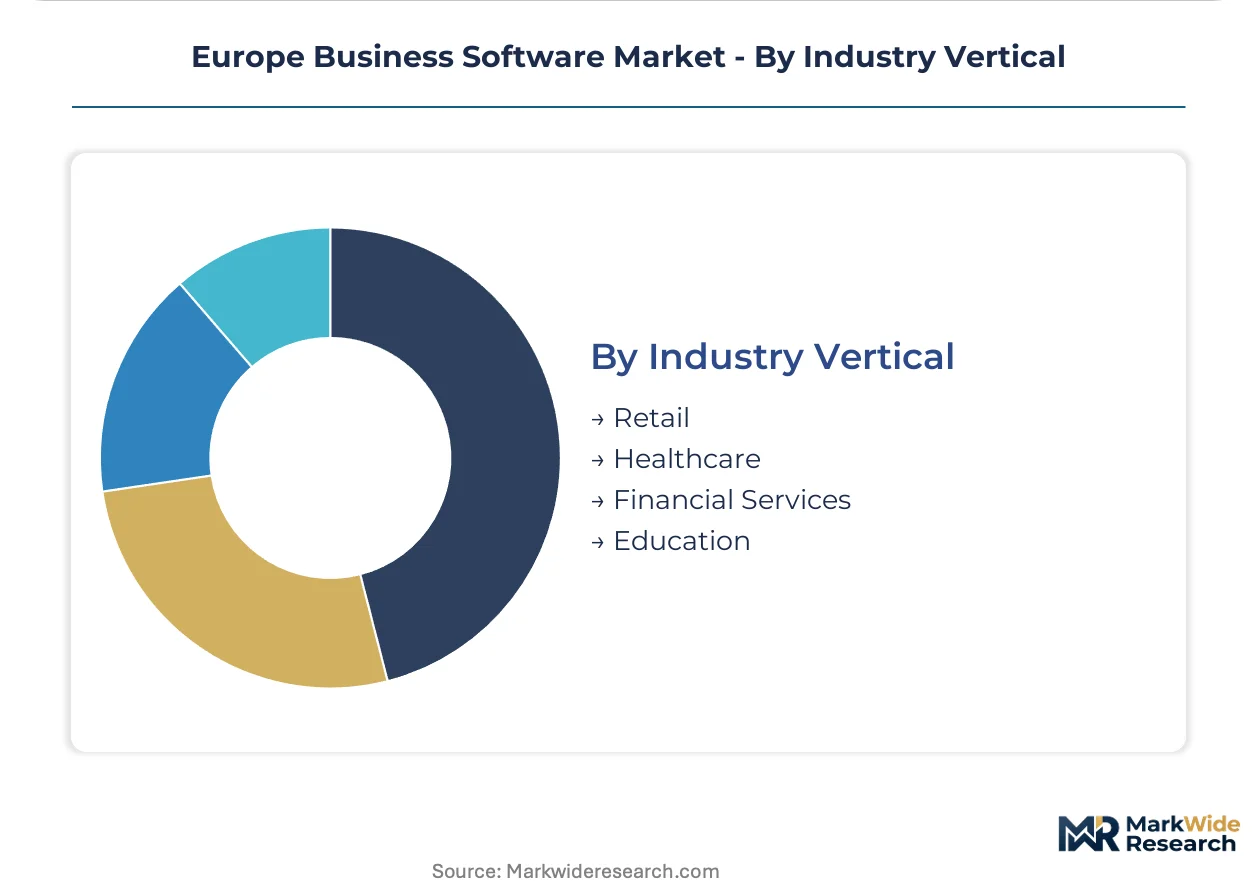
Industry Vertical:
Application-specific compliance obligations reshape feature roadmaps and certification timelines.
- Financial Services:Algorithmic trading compliance and real-time risk engines drive replacement cycles in France. EBA guidelines on cloud outsourcing shape vendor liability frameworks alongside divergent CNIL and KBA enforcement calendars.
- Healthcare:Safety-critical software modules face eighteen-month CE marking certification windows, with MDR obligations tightening compliance integration into platform roadmaps.
- Retail:Omnichannel inventory synchronization demands API interoperability across distributed fulfillment networks.
- Education:Municipal procurement under EU Green Deal rules requires carbon footprint disclosure tools.
Financial Services generates the highest margin concentration; Healthcare faces the most extended implementation timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development and enterprise deployment capacity clusters in Germany, France, and the United Kingdom, with emerging hubs in Poland and the Netherlands reshaping talent sourcing patterns for implementation services.
Germany
Automotive manufacturers in Stuttgart and Wolfsburg are accelerating ERP and SCM replacement cycles to unify manufacturing execution with financial planning. The KBA interprets EU AI Act guidelines with extended enforcement timelines for high-risk algorithmic systems. Frankfurt data centers anchor sovereign cloud infrastructure serving mid-market buyers migrating from on-premise legacy systems.
France
Financial services institutions in Paris drive demand for real-time risk engines and algorithmic trading compliance modules. The CNIL enforces GDPR data residency mandates with stricter localization requirements than neighboring jurisdictions. Insurance distributors in the Île-de-France region consolidate vendor relationships around integrated platform ecosystems rather than standalone point solutions.
United Kingdom
Professional services firms and fintech operators in London generate concentrated demand for cloud-native HRM and financial automation tools. Post-Brexit regulatory divergence from Brussels creates parallel compliance tracks for vendors serving both UK and EU clients. The Greater Southeast corridor houses the densest concentration of SaaS implementation partners outside Germany.
Poland
Shared service centers for German automotive suppliers in Kraków and Wrocław create demand for Polish-language HRM and SCM modules. EU Green Deal procurement rules open municipal and utility verticals requiring carbon footprint disclosure capabilities. The manufacturing base remains underpenetrated relative to Western European peers, offering greenfield expansion opportunities.
Netherlands
Logistics operators in Rotterdam and Amsterdam consolidate around integrated platform ecosystems due to IT headcount constraints favoring unified support models. EBA guidelines on cloud outsourcing shape vendor liability frameworks for financial services clients. The Benelux region demonstrates the fastest vendor relationship concentration among mid-market buyers replacing fragmented tool stacks.
Europe Business Software Market Competitive Landscape
Full-suite ERP incumbents and cloud-native platform providers split the market between manufacturing-heavy deployments and services-sector automation. The vendor base stratifies across three tiers: heritage manufacturing specialists, horizontal cloud platforms, and verticalized mid-market specialists. Consolidation pressure favors ecosystem breadth over point-solution depth. Strategic moves center on API interoperability investments and sovereign cloud infrastructure expansion.
Within the heritage manufacturing tier, SAP SE anchors enterprise resource planning deployments leveraging deep automotive and chemical sector relationships. Microsoft Corporation competes through cloud infrastructure density and platform integration breadth across horizontal workloads. Sage Group occupies a distinct mid-market tier specializing in financial automation below full-suite ERP complexity. These three exemplify the archetype segmentation pressuring pure-play specialists to embed within broader ecosystems or retreat to narrow vertical niches.
| Leading Market Players |
|---|
| Salesforce |
| Sage Group |
| SAP SE |
| IFS |
| Unit4 |
| Microsoft Corporation |
| Workday |
| Dassault Systèmes |
| Oracle Corporation |
| Others |
Supply & Pricing Matrix
Undercapacity in sovereign cloud infrastructure across Frankfurt and Paris data centers is compressing vendor margins while elevating pricing power for hyperscalers with certified GDPR-compliant capacity. This utilization squeeze forces mid-market buyers toward longer subscription commitments and bundles compliance modules into base pricing.
Pricing Analysis
GDPR data residency mandates dictate the pricing tier structure across the Europe Business Software Market. Three-tier pricing structure across premium sovereign-cloud, standard regional-cloud, and economy multi-tenant levels separates buyers by compliance sensitivity and data sovereignty requirements. Certification under the EU AI Act's high-risk system classification adds fifteen to twenty percent premiums for banking and automotive deployments. Cost compression in the economy tier is intensifying because open-source ERP alternatives capture price-sensitive accounts in Southern Europe. SMEs show highest price sensitivity due to IT headcount constraints, while defense contractors demonstrate lowest sensitivity given non-negotiable on-premise requirements.
Supply Chain Analysis
Export control restrictions on advanced GPU clusters and AI training hardware are fragmenting cloud infrastructure procurement across European member states. Supply concentration rests on Ireland and the Netherlands for hyperscaler data center capacity, Germany for embedded systems middleware, and Estonia for cybersecurity tooling. Raw material dependencies include specialized semiconductors for edge computing nodes, rare earth elements for server hardware, and licensed training datasets for generative AI modules. Single-source vulnerability around NVIDIA's GPU supply creates bottleneck risk for AI-enabled software stacks. Distribution runs through certified systems integrators in Stuttgart, Paris, and London who manage CE marking and GDPR compliance handoffs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Business Software represents a service-attach opportunity where managed compliance and sovereign cloud operations expand recurring revenue faster than perpetual license sales. Implementation and ongoing regulatory monitoring now capture margin pools exceeding base software subscriptions.
For Market Incumbents: Build ecosystem lock-in through API density and native module expansion. SAP SE and Microsoft Corporation should deepen vertical integration into automotive MES protocols and banking core systems before open-source alternatives standardize connectivity. Certification investment under divergent CNIL and KBA AI Act timelines defends against regulatory arbitrage by niche compliance specialists. Channel control through exclusive systems integrator partnerships in Benelux and DACH regions limits displacement by best-of-breed point solutions. For New Entrants and Emerging Players: Poland's underpenetrated manufacturing base offers greenfield expansion through Polish-language HRM and SCM modules for German automotive shared service centers. Municipal software procurement under EU Green Deal rules creates white-space in carbon footprint disclosure tools for utilities and regional governments. A verticalized go-to-market targeting Kraków and Wrocław manufacturing clusters with pre-configured GDPR and CSRD compliance templates bypasses incumbent ecosystem advantages. For Investors and Strategic Acquirers: Capital is best deployed toward verticalized compliance specialists with AI Act risk classification expertise and sovereign cloud operators with certified Frankfurt or Paris capacity. Long-term viability hinges on regulatory divergence between Brussels-level mandates and national implementation timelines creating persistent demand for legal-technical translation services. Watch for inflection signals in KBA and CNIL enforcement calendar alignment that would compress compliance service premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | Frankfurt and Paris data center accreditation under GDPR and EU AI Act unlocks public sector procurement. |
| Generative AI Module Integration | Natural language contract analysis expands addressable seats per license in French financial services. |
| Vertical Compliance Acquisition | Specialist firms with CE marking expertise accelerate eighteen-month automotive certification windows. |
| API-First Platform Expansion | Composable microservices architecture displaces monolithic ERP in Stuttgart automotive supplier networks. |
| Polish Manufacturing Penetration | Localized HRM and SCM modules capture shared service center demand from German automotive OEMs. |
Research Methodology
A standing panel of CTOs, IT procurement officers, platform engineers, and channel partners provided ongoing calibration across the research cycle. Primary interviews with integration specialists and regulatory affairs leads at banking software vendors were cross-validated against secondary sources including SEC filings, hyperscaler capex disclosures, EBA cloud outsourcing guidelines, and national regulator enforcement calendars. Bottom-up deployment estimates by vertical and organization size were triangulated against top-down market sizing from vendor revenue disclosures and systems integrator pipeline data.
Scenario bracketing around EU AI Act implementation timelines and GDPR enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model, organization scale, industry vertical, integration complexity, and regional adoption pattern. CAGRs were derived from fitted growth curves anchored to documented replacement cycles and greenfield expansion rates. Industry-specific inputs encompass algorithmic accountability module penetration in banking, sovereign cloud migration velocity in mid-market manufacturing, and open-source ERP substitution rates in Southern Europe.
Practitioners should monitor regulatory divergence between CNIL and KBA enforcement calendars, GPU export control expansion, and CE marking backlog duration for early signals of forecast revision. Material shifts in Brussels-level AI Act risk tier reclassification or sovereign cloud capacity buildout acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Self-Storage Software Market
Software & Services
Plant Design Software Market
Software & Services
Family Office Software Solutions Market
Software & Services
Bridge Analysis Software Market
Software & Services
Electronic Data Interchange (EDI) Software Market
Software & Services
Hotel Management Software Market
Software & Services
Enterprise Content Management Software Market
Software & Services
Freight Management Software Market
Software & Services
Binary Drivers Market
Software & Services
Global Website Builder Software Market
Software & Services
Global Configuration Management Software Market
Software & Services
Enterprise Software Market
Software & Services
Global Employee Engagement and Feedback Software Market
Software & Services
Small Business Marketing Software Market
Software & Services
Global Advanced Planning and Scheduling (APS) Software Market
Software & Services
Enterprise-Grade Saas Market