
 Nigeria ICT Market | 2026-2036
Nigeria ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria ICT Market Outlook
Enterprise-grade service tiers is rotating toward the center of competitive strategy in Nigeria's ICT landscape. MTN Nigeria Communications Plc leverages its fiber backbone and mobile money integration to anchor enterprise contracts in Lagos and Abuja. Airtel Africa Plc - Nigeria Operations competes through aggressive data pricing and rural base-station expansion. MainOne (Equinix Company) dominates subsea connectivity, controlling access to five of Nigeria's seven international cable systems.
Information and communications technology in Nigeria encompasses the infrastructure, systems, and services enabling data transmission, processing, and storage across telecommunications networks, enterprise software platforms, and cloud computing architectures. The sector operates on a foundation of 2,500+ base transceiver stations, submarine cable landing points in Lekki and Lagos, and national backbone fiber exceeding 35,000 route kilometers, serving as the operational nervous system for banking, government administration, and commercial logistics. Software and cloud services segments capture the fastest expansion trajectory, driven by banking sector migration to core banking SaaS platforms and government e-procurement mandates. Hardware deployment retains volume dominance but faces margin compression as import substitution policies and naira volatility elevate server and networking equipment costs.
The National Information Technology Development Agency enforces local content requirements that redirect government ICT procurement toward Nigerian-registered vendors and domestic data residency. The Nigerian Communications Commission governs spectrum allocation, interconnection rates, and quality-of-service benchmarks that directly shape operator revenue models and infrastructure rollout obligations. The Central Bank of Nigeria's cashless policy and open banking framework accelerate fintech-ICT convergence, creating compliance-driven demand for secure transaction processing infrastructure. Stakeholders must monitor regulatory divergence between federal mandates and state-level implementation, particularly where Lagos State's technology taxation precedents risk fragmenting national market access rules.
Market Dynamics
Nigerian banks are accelerating cloud migration mandates, forcing infrastructure providers to reconfigure data center capacity toward financial-grade security and latency specifications. This demand compression is restructuring vendor qualification protocols across Lagos and Abuja enterprise corridors.
Growth Catalysts
- Central Bank of Nigeria cashless policy:Transaction volume thresholds for digital payments are expanding secure processing infrastructure demand. Financial institutions must upgrade core banking systems to meet settlement speed requirements.
- Lagos State data center clustering:Submarine cable landings at Lekki and Apapa create latency advantages for enterprise cloud workloads. Density effects attract secondary fiber builds and edge computing nodes.
- National Information Technology Development Agency local content directives:Government procurement rules now mandate Nigerian-registered vendors for federal ICT contracts. Domestic software developers gain preferential access to public sector digital transformation budgets.
Market Restraints
- Naira volatility against dollar-denominated equipment:Server and networking hardware imports face margin compression from foreign exchange instability. Capital expenditure planning cycles lengthen as procurement costs become unpredictable.
- Base transceiver station deployment concentration:Rural coverage gaps persist where tower economics fail against diesel generator and security costs. Geographic digital divides reinforce enterprise service tier fragmentation.
- Spectrum auction delays:Nigerian Communications Commission licensing timelines create capacity bottlenecks for 5G rollout. Operators defer dense urban small-cell investments pending clarity on mmWave allocation.
Strategic Opportunities
- Northern Nigeria enterprise connectivity:Kano and Kaduna manufacturing corridors remain underserved by fiber backbone extensions. Agricultural commodity traders require reliable bandwidth for commodity exchange platforms.
- Fintech-ICT convergence:Open banking APIs are creating demand for embedded finance infrastructure. Payment processors seek white-label core banking integrations for non-bank financial institutions.
- Edge computing for oilfield operations:Niger Delta exploration companies need localized data processing for seismic analysis. Latency requirements for real-time drilling analytics exceed satellite link capabilities.
Industry Challenges
- Cloud architecture certification pipelines:Enterprise customers demand AWS, Azure, and Google Cloud partner credentials that local system integrators lack. Skills transfer programs struggle to match certification velocity with project timelines.
- Legacy core banking integration:Tier-2 and Tier-3 lenders operate on 1990s-era mainframe architectures that resist API-first modernization. Data migration risks trigger regulatory scrutiny from the Central Bank of Nigeria.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria ICT Market |
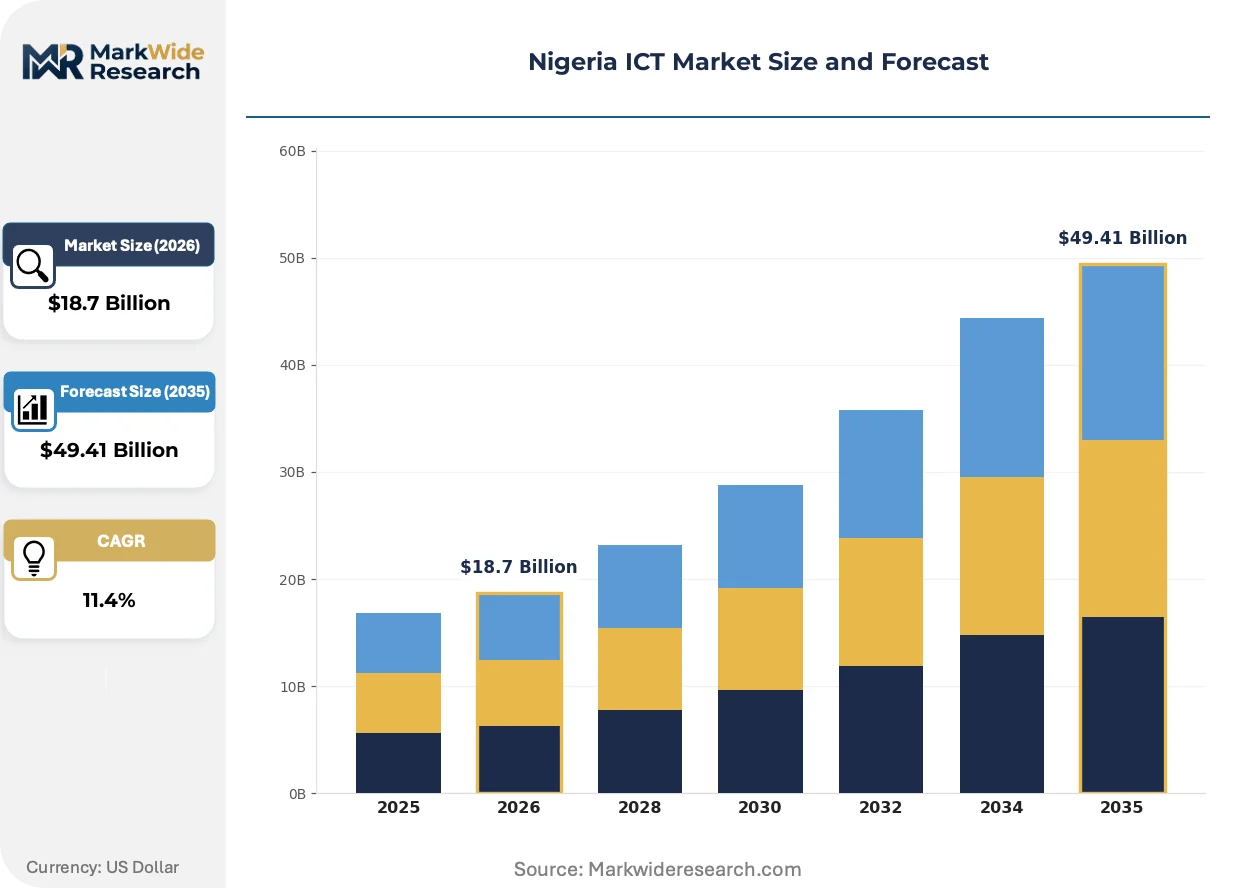
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Software, Hardware, Networking, Cloud Services Service Model: Infrastructure as a Service, Platform as a Service, Software as a Service, Managed Services End User: Government, Banking, Education, Healthcare Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | MTN Nigeria Communications Plc, Airtel Africa Plc - Nigeria Operations, Globacom Limited, Emerging Markets Telecommunication Services Limited (9mobile), MainOne (Equinix Company), Interswitch Limited, CWG Plc (Computer Warehouse Group), Microsoft Corporation, Huawei Technologies Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria ICT Market Strategic Shifts
Software-defined infrastructure is dissolving traditional hardware procurement cycles across Nigerian enterprise accounts. This architectural shift is compressing vendor lock-in durations and elevating subscription-based service models.
Container orchestration platforms are decomposing monolithic enterprise applications into microservices architectures. Nigerian banks and telecom operators are adopting Kubernetes-based deployments at accelerating velocity. This technology is decomposing legacy system integrator business models by enabling direct cloud-native development.
The National Information Technology Development Agency data residency enforcement is mandating local data center certification for government cloud workloads. Federal agencies must migrate sensitive records to Nigerian-sovereign infrastructure by specified compliance deadlines. Banking and healthcare verticals are preemptively adopting these standards to maintain public sector contract eligibility.
Enterprise buyers are unbundling hardware procurement from managed services contracts. Lagos-based corporations now source servers through distributor channels while retaining separate systems integration relationships. This pattern is most visible in financial services, where procurement teams seek price transparency on capital equipment distinct from operational expenditure service tiers.
Nigeria ICT Market Segmentation
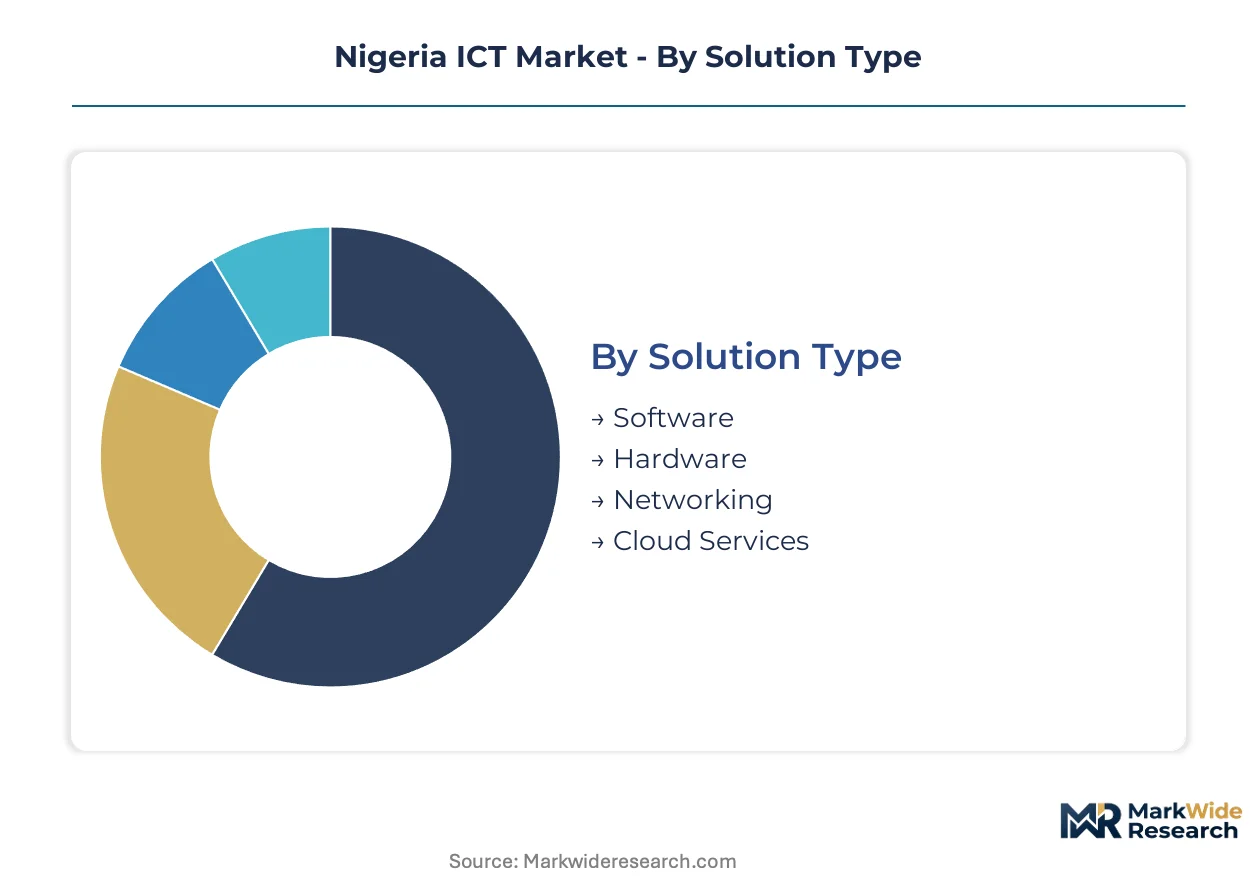
Segmentation in Nigeria's ICT market reveals how procurement patterns diverge between federal compliance mandates and enterprise performance requirements. Solution type and service model splits expose where vendor margins concentrate against naira-denominated budget pressures.
Solution Type:
Margin pools concentrate in software and cloud services where recurring revenue models offset hardware import volatility.
- Software:Enterprise applications span core banking platforms, ERP systems, and government e-procurement modules. Banking sector migration to API-first architectures in Lagos and Abuja is compressing perpetual license models toward subscription frameworks. Regulatory mandates from the National Information Technology Development Agency accelerate domestic developer qualification for federal contracts.
- Cloud Services:Public and private cloud deployments encompass compute, storage, and disaster recovery tiers. Lagos State data center clustering at Lekki cable landing points creates latency arbitrage for financial services workloads. Sovereign cloud certification requirements are reshaping provider qualification protocols.
- Hardware:Server, storage, and networking equipment imports face margin compression from foreign exchange instability.
- Networking:Fiber backbone extensions and microwave transmission systems connect enterprise sites to submarine cable landing points.
Software holds installed capacity. Cloud Services is rotating up the share rankings.
Service Model:
Application patterns across Nigerian enterprises show Infrastructure as a Service absorbing capital expenditure constraints while Managed Services captures compliance complexity.
- Infrastructure as a Service:Compute and storage virtualization eliminates upfront server procurement for naira-constrained enterprises. Tier-2 banks in Lagos are migrating disaster recovery workloads to IaaS providers certified under Central Bank of Nigeria operational resilience guidelines.
- Software as a Service:Subscription-based productivity and collaboration tools bypass lengthy procurement cycles. Federal agencies under National Information Technology Development Agency directives are adopting SaaS for non-sensitive administrative functions while mandating on-soil alternatives for classified data.
- Platform as a Service:Container orchestration and development environments accelerate Nigerian fintech application deployment.
- Managed Services:Outsourced network operations and security monitoring address skills gaps in northern Nigeria enterprise corridors.
Infrastructure as a Service dominates procurement volume. Software as a Service is climbing the fastest among service models.
End User:
Customer-type concentration shows banking and government verticals driving certified-vendor premiums against education and healthcare budget constraints.
- Banking:Commercial and merchant banks deploy core banking modernization, payment switch infrastructure, and open banking API gateways. Central Bank of Nigeria cashless policy thresholds mandate real-time settlement capacity upgrades across Tier-1 through Tier-3 institutions.
- Government:Federal ministries and state agencies implement e-procurement, tax administration digitization, and biometric identity systems. Local content mandates redirect contracts toward Nigerian-registered vendors with domestic data residency capabilities.
- Healthcare:Hospital information systems and telemedicine platforms expand in Lagos and Abuja urban centers.
- Education:University and secondary school connectivity programs face funding fragmentation across state budgets.
Banking holds installed capacity. Government is rotating up the share rankings.
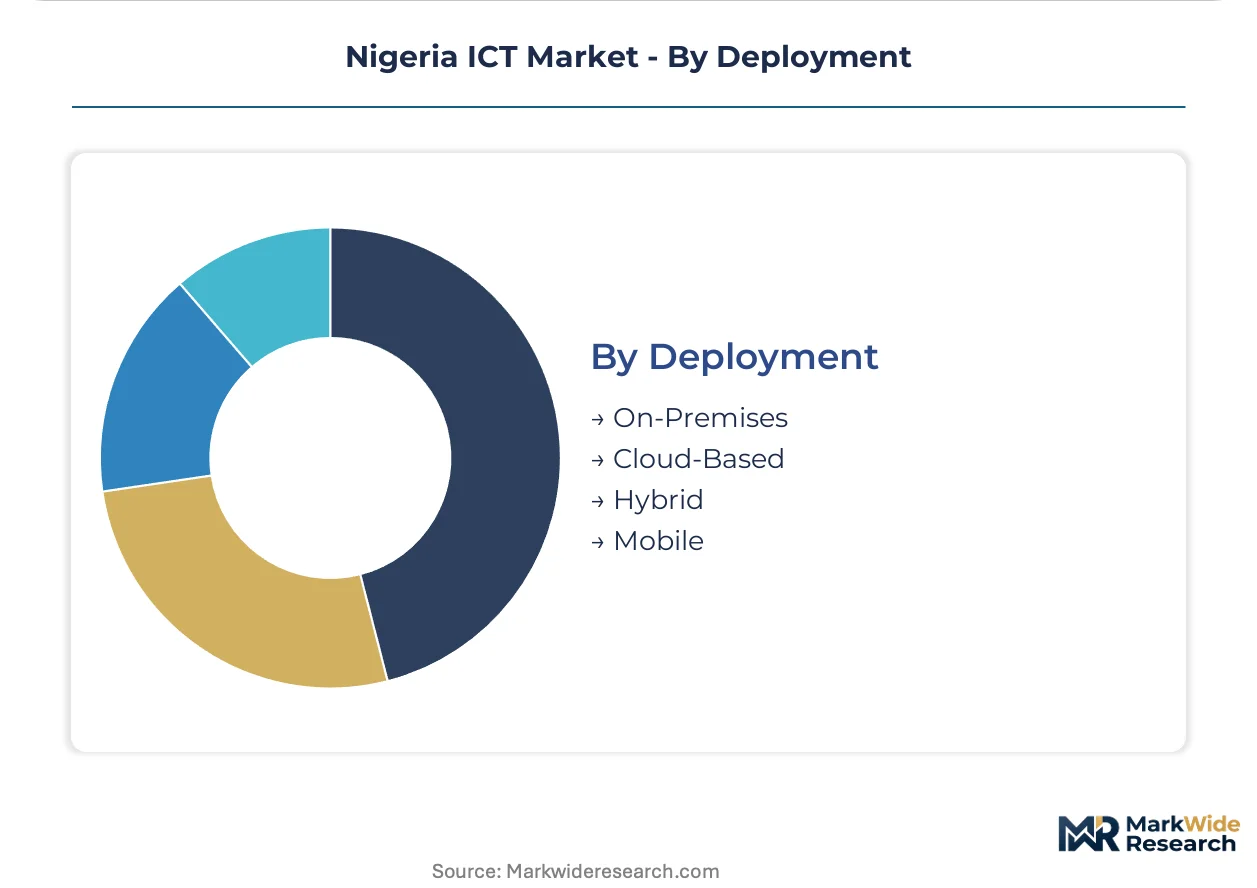
Deployment:
Architecture choices reflect latency requirements against sovereignty mandates, with hybrid configurations capturing regulatory ambiguity.
- Cloud-Based:Fully off-premises deployments serve software development and non-sensitive analytics workloads. Nigerian fintech startups leverage cloud-native architectures to bypass legacy infrastructure constraints, though data residency requirements limit workload types.
- Hybrid:Split architectures maintain sensitive transaction processing on-soil while bursting analytics to international regions. Banking sector adoption is accelerating as institutions seek to satisfy Central Bank of Nigeria data localization expectations without sacrificing elasticity.
- On-Premises:Dedicated data center deployments persist for classified government and core banking functions.
- Mobile:Edge computing and 5G-ready distributed architectures target field operations in Niger Delta oilfields and agricultural commodity trading posts.
On-Premises holds installed capacity. Hybrid is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nigeria's ICT sector maintains a structural trade deficit in hardware imports against software and services exports. Foreign exchange outflows concentrate on dollar-denominated server and networking equipment, while domestic cloud and fintech services generate limited hard currency inflows.
Lagos State
Submarine cable landings at Lekki and Apapa anchor Nigeria's internet bandwidth supply. The National Information Technology Development Agency mandates sovereign data center certification for federal workloads. Victoria Island and Ikoyi host financial services data center clusters serving Tier-1 banking clients.
Federal Capital Territory
Abuja concentrates government ICT procurement under local content directives. The Central Bank of Nigeria's cashless policy drives payment infrastructure investment across the territory. Garki and Maitama districts host enterprise connectivity hubs for ministry networks.
Kano State
Agricultural commodity trading platforms generate bandwidth demand from grain and livestock exchanges. The Nigerian Communications Commission's universal service fund subsidizes rural base station deployment. Kano metropolis anchors northern Nigeria's fiber backbone extensions.
Rivers State
Oilfield operations require edge computing for seismic data processing latency requirements. The Nigerian National Petroleum Corporation's digital transformation mandates local data residency for exploration data. Port Harcourt hosts energy sector dedicated connectivity infrastructure.
Oyo State
University research networks drive high-performance computing demand for agricultural and health analytics. State government e-procurement systems require certified domestic software vendors. Ibadan's technology corridor attracts secondary data center investment from Lagos-based operators.
Nigeria ICT Market Competitive Environment
Listed leaders compete with private specialists across spectrum access and infrastructure ownership dimensions. MTN Nigeria Communications Plc and Airtel Africa Plc operate as publicly traded entities with deep capital markets access, while Globacom Limited and Interswitch Limited remain privately held with concentrated founder control. The market structures around three archetypes: integrated telecom operators with mobile money capabilities, specialized data center and connectivity providers, and fintech-anchored platform companies. Competitive moves concentrate on fiber backbone expansion into underserved corridors and strategic partnerships with international cloud hyperscalers for sovereign certification.
Within the integrated operator tier, MTN Nigeria Communications Plc and Airtel Africa Plc exemplify scale-driven positioning through mobile subscriber bases and enterprise contract anchoring. Among specialized infrastructure providers, MainOne occupies a position representing subsea connectivity control, while CWG Plc sits within the domestic systems integration archetype serving government certification requirements. These named entities anchor industry-level patterns without specifying individual strategic actions or financial performance.
| Leading Market Players |
|---|
| MTN Nigeria Communications Plc |
| Airtel Africa Plc - Nigeria Operations |
| Globacom Limited |
| Emerging Markets Telecommunication Services Limited (9mobile) |
| MainOne (Equinix Company) |
| Interswitch Limited |
| CWG Plc (Computer Warehouse Group) |
| Microsoft Corporation |
| Huawei Technologies Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Subsea cable landing density at Lekki and Apapa creates bandwidth scale economies that compress price floors for enterprise connectivity while concentrating procurement leverage among Lagos-based data center operators. This infrastructure clustering simultaneously elevates import substitution premiums for naira-denominated software services and exposes hardware-dependent vendors to foreign exchange volatility.
Pricing Analysis
Banking sector buyers anchor subscription-based pricing structures across core banking SaaS and disaster recovery tiers. Price differentiation rests on Central Bank of Nigeria certification grade and sovereign data residency compliance, with uncertified providers competing on raw compute rates. Cost compression in hardware procurement is intensifying because naira depreciation against dollar-denominated server imports. Tier-2 banks exhibit highest price sensitivity, while Tier-1 institutions prioritize latency performance over unit economics.
Supply Chain Analysis
Apapa port congestion and container availability constraints on Asia-West Africa trade lanes extend lead times for networking equipment deliveries. Hardware supply concentrates in China, USA, and Germany for server and storage systems, while submarine cable systems draw from Japan, France, and USA manufacturing. Component dependencies span semiconductor chips, lithium-ion backup power systems, and precision cooling equipment. Single-source vulnerability runs through submarine cable landing station equipment. Distribution runs through Lagos-based systems integrators with federal certification credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in northern Nigeria enterprise corridors where fiber backbone extensions lag Lagos density, creating niche entry points for specialized connectivity providers.
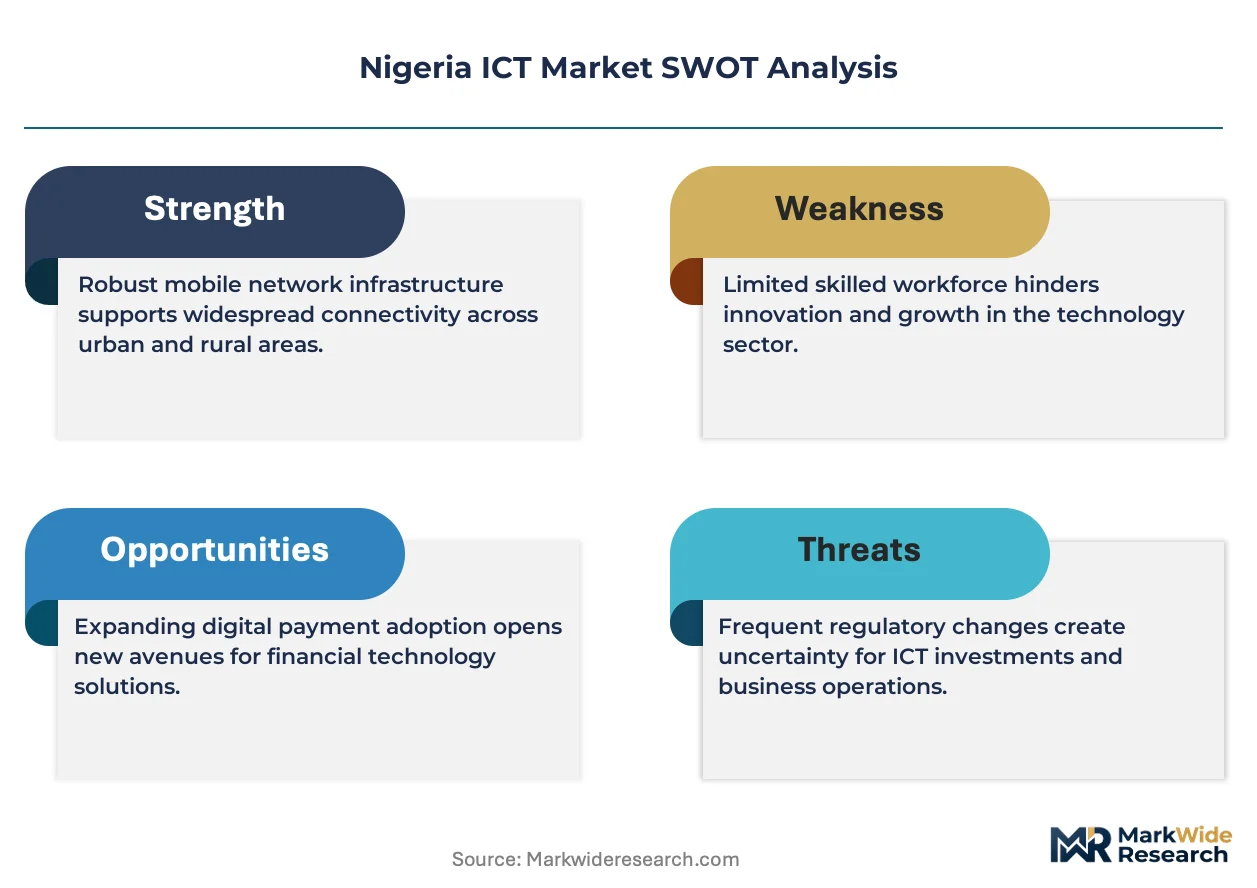
For Market Incumbents: Shield enterprise contract retention by accelerating sovereign cloud certification investments ahead of National Information Technology Development Agency compliance deadlines. Deepen backward integration into Lagos data center real estate to lock in latency advantages against submarine cable competitors. Counter emerging fintech-anchored platform entrants through exclusive payment infrastructure partnerships with Tier-1 banks. For New Entrants and Emerging Players: Rural base station management service gaps expose white-space where diesel logistics and security costs deter integrated operators. Penetrate Kano and Kaduna manufacturing corridors through agricultural commodity trading platform integrations. Pursue Nigerian Communications Commission universal service fund subsidies to offset tower economics in underserved northern zones. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed services providers with federal certification credentials and multi-year government contracts. Long-term viability favors domestic software developers with National Information Technology Development Agency vendor registration and proven public sector delivery. Monitor Central Bank of Nigeria open banking API mandate implementation velocity as inflection indicator for embedded finance infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | Secures eligibility for National Information Technology Development Agency federal procurement mandates and banking sector contracts. |
| Fiber Backbone Extension | Captures latency-sensitive enterprise workloads in northern Nigeria corridors underserved by submarine cable proximity. |
| Fintech Platform Integration | Locks in payment processing volume through Central Bank of Nigeria open banking API gateway partnerships. |
| Managed Services Outsourcing | Addresses skills gaps in Kubernetes container orchestration and cloud architecture certification pipelines. |
| Data Center Real Estate Acquisition | Controls scarce Lagos State power infrastructure access for financial-grade latency specifications. |
Study Parameters
Initial hypotheses were tested against primary input from chief technology officers at Tier-1 through Tier-3 banks, Nigerian Communications Commission regulatory affairs leads, federal ministry procurement officers, and data center operations directors, then refined against secondary validation. Sources included Central Bank of Nigeria circulars and policy frameworks, National Information Technology Development Agency vendor registry databases, Nigerian Communications Commission spectrum allocation records, SEC filings from listed operators, and submarine cable landing station capacity disclosures. Bottom-up enterprise spend estimates and top-down infrastructure deployment trajectories were triangulated to converge on market sizing.
Variance decomposition across solution type, service model, end-user vertical, and deployment architecture segments shaped the analytical framework throughout the projection horizon. CAGRs were derived from infrastructure investment pipeline tracking and enterprise procurement cycle analysis. Forecast inputs incorporated Nigerian Communications Commission base transceiver station deployment licenses and Central Bank of Nigeria cashless policy transaction volume thresholds.
Material uncertainties — naira exchange rate trajectories, spectrum auction timing delays, and federal election cycle procurement freezes — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement continuity and infrastructure investment commitment levels. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Next Generation Technologies
Smart Surfaces Market
Next Generation Technologies
M2M Connections Market
Next Generation Technologies
Bulgaria ICT Market
Next Generation Technologies
Information and Communications Technology (ICT) Market
Next Generation Technologies
Europe Quantum Computing Market
Next Generation Technologies
Hyperloop Technology Market
Next Generation Technologies
Malaysia ICT Market
Next Generation Technologies
Enterprise Quantum Computing Market
Next Generation Technologies
Poc Platform and Technology Market
Next Generation Technologies
Ireland ICT Market
Next Generation Technologies
Quantum Computing Market
Next Generation Technologies
Oman ICT Market
Next Generation Technologies
GCC ICT Market
Next Generation Technologies
Next Generation Network (NGN) Equipment Market
Next Generation Technologies
Hyperscale Edge Computing Market
Next Generation Technologies
Next-Generation Communication Devices Market