
 Europe Integration Platform As a Service Market | 2026-2036
Europe Integration Platform As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Integration Platform As a Service Market Insights
CE marking under the EU Cybersecurity Act is bifurcating the competitive landscape between certified and uncertified iPaaS vendors. Microsoft leverages its Azure infrastructure to dominate public cloud deployments across Northern Europe. IBM sustains entrenched positions in regulated industries through mainframe-compatible hybrid integration stacks. Informatica specializes in data governance tooling that addresses GDPR lineage requirements for financial services clients.
Integration Platform as a Service denotes cloud-native middleware delivered on subscription, enabling real-time API orchestration, event-driven architecture, and cross-application data synchronization without on-premises infrastructure. The technology abstracts protocol translation, authentication federation, and message transformation through containerized runtime engines deployed across distributed cloud regions. Hybrid Cloud deployments capture premium margins from European banks requiring on-premise data residency alongside burst capacity to public infrastructure. API Management services lead revenue contribution as enterprises externalize digital services to ecosystem partners. Process Automation segments accelerate fastest among SMEs replacing legacy RPA with embedded workflow engines.
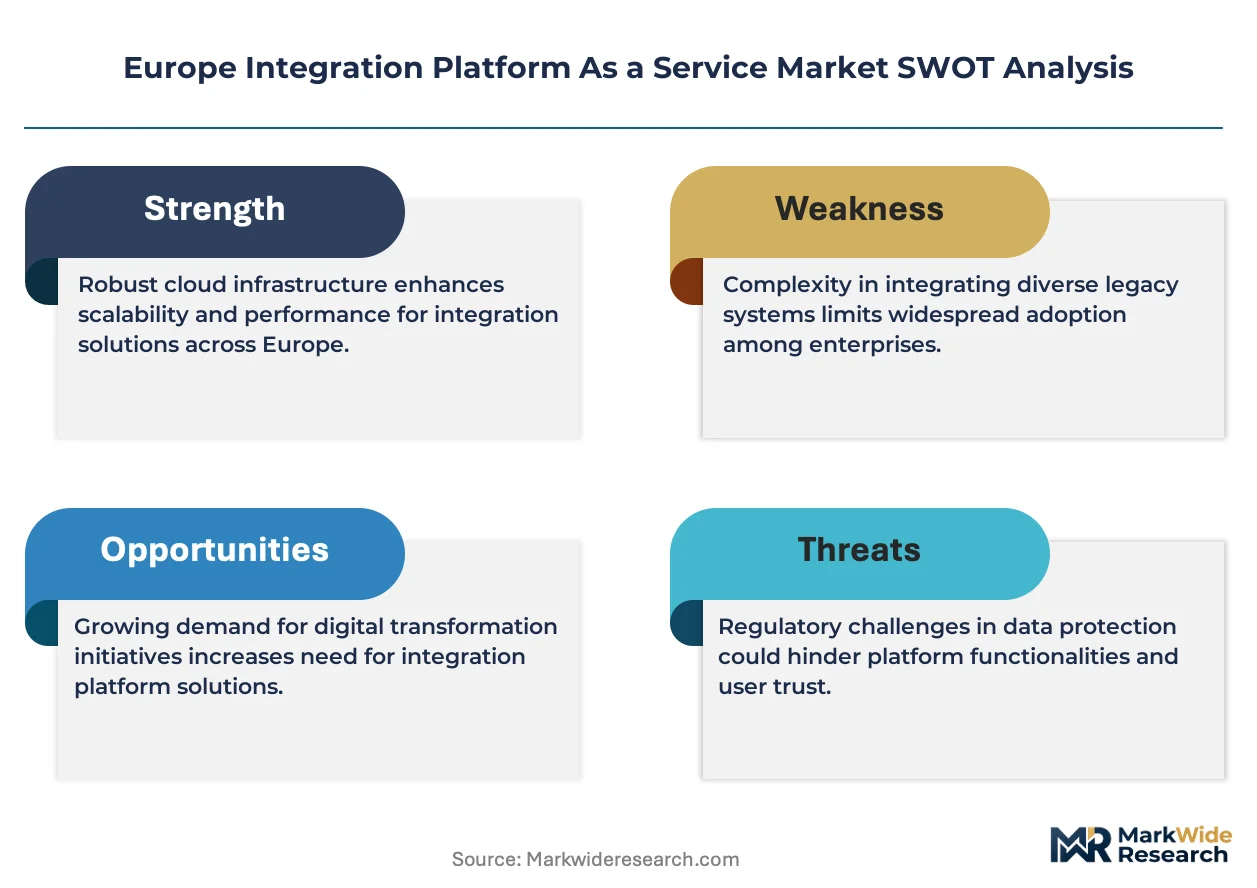
GDPR enforcement by national data protection authorities shapes vendor selection criteria around encryption standards and cross-border transfer mechanisms. The EU AI Act's risk classification system forces healthcare and public sector buyers to demand auditable integration pipelines for algorithmic decision systems. EMA guidelines on pharmaceutical data integrity extend validation requirements to cloud-based batch record integrations. Stakeholders must evaluate whether prospective vendors maintain EU-based processing nodes and third-party security certifications before committing to multi-year contracts.
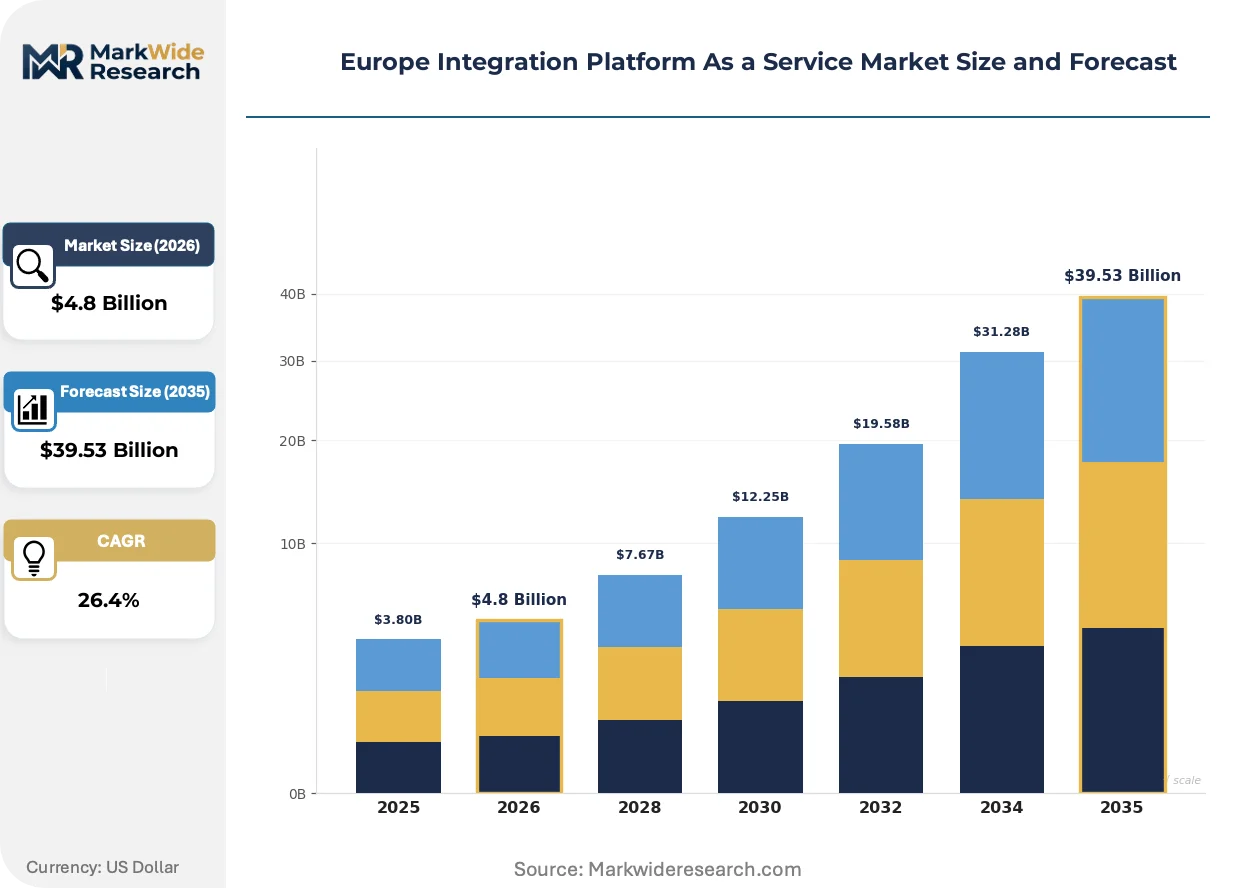
Market Dynamics
GDPR enforcement and the EU AI Act are compressing vendor selection cycles as enterprises demand pre-certified integration stacks with auditable data lineage and EU-sovereign processing nodes.
Growth Catalysts
- Automotive IoT convergence:German vehicle manufacturers deploy cloud-native middleware to bridge legacy ERP systems with real-time sensor networks, creating demand for low-latency edge orchestration.
- GDPR-mandated data governance:Financial services institutions in France and the Netherlands prioritize managed integration services with built-in encryption standards and cross-border transfer safeguards.
- Digital sovereignty initiatives:National cloud infrastructure programs across the Benelux region favor European-hosted iPaaS providers over non-EU alternatives.
Market Restraints
- CE certification backlog:The EU Cybersecurity Act's conformity assessment timeline creates 12-18 month vendor qualification delays for uncertified platforms.
- Mainframe integration complexity:European banks with IBM z/OS estates face elevated professional services costs to bridge on-premise batch systems with cloud-native APIs.
- Skilled integration architect scarcity:Shortages of specialists certified in both legacy protocol translation and Kubernetes-native event streaming constrain deployment velocity.
Strategic Opportunities
- Eastern European manufacturing:Polish and Romanian automotive suppliers remain underpenetrated for ecosystem integration, presenting whitespace for API-first platform vendors.
- EMA pharmaceutical validation:Guidelines on cloud-based batch record integrity create addressable demand for GxP-compliant integration pipelines in life sciences.
- Healthcare AI auditability:The EU AI Act's high-risk system classification forces hospitals to demand traceable data flows for diagnostic algorithm inputs.
Industry Challenges
- Hybrid cloud skill fragmentation:Teams struggle to maintain expertise across both on-premise message brokers and serverless cloud functions simultaneously.
- Multi-year contract lock-in:Enterprises face switching costs from deeply embedded custom transformation logic and partner-specific connector libraries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Integration Platform As a Service Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $39.53 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: API Management, Data Integration, Application Integration, Process Automation End User: SMEs, Large Enterprises, Public Sector, Non-Profit Organizations Industry Vertical: Healthcare, Manufacturing, Retail, Telecommunications |
| Companies Covered | MuleSoft, Dell Boomi, Informatica, SnapLogic, Microsoft, IBM, Oracle, TIBCO Software, Frends, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Integration Platform As a Service Market Trends and Innovations
Event-driven architecture and embedded workflow engines are displacing legacy RPA installations as European SMEs prioritize real-time responsiveness over batch processing.
Containerized runtime engines with native support for Apache Kafka and MQTT protocols are supplanting traditional ESB middleware in manufacturing environments. German automotive suppliers adopt these streaming-native stacks to enable sub-100ms latency for predictive maintenance alerts. The shift compresses integration project timelines from 18-month waterfall deployments to 6-week iterative sprints.
The EU AI Act's risk classification framework mandates auditable data pipelines for algorithmic decision systems in public sector procurement. Healthcare authorities in France now require documented provenance trails for patient data feeding diagnostic models. Vendors respond by embedding lineage tracking and immutable logging as standard platform features rather than premium add-ons.
Subscription-based consumption models with usage-tiered pricing are displacing perpetual license arrangements in mid-market enterprise software procurement. Dutch logistics firms and Nordic retail chains negotiate contracts tied to API call volumes rather than fixed seat counts. This reconfiguration shifts vendor incentives toward platform reliability and developer experience optimization.
Europe Integration Platform As a Service Market Segmentation
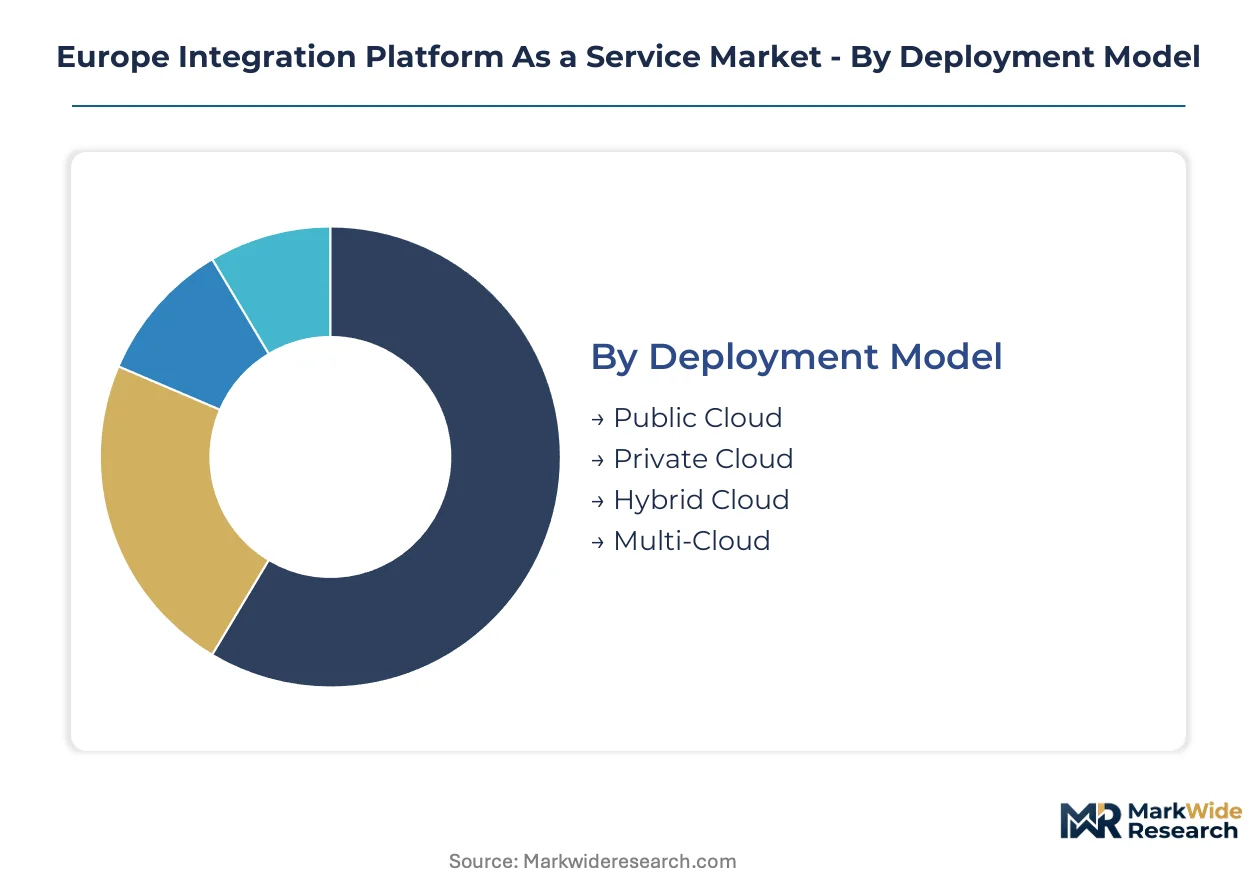
Integration Platform as a Service procurement patterns diverge sharply across deployment models, service tiers, and buyer sophistication. Understanding these fault lines reveals where vendors capture premium pricing versus where commoditization pressures concentrate.
Deployment Model:
Margin pools concentrate in configurations that address data residency mandates while preserving elastic scaling economics.
- Hybrid Cloud:Combines on-premise data residency with burst capacity to public infrastructure through containerized runtime engines. European banks in Frankfurt and Paris pay premium rates for this architecture to satisfy GDPR localization requirements without sacrificing peak-load performance.
- Public Cloud:Delivers API orchestration and event streaming through hyperscaler-hosted infrastructure with usage-tiered subscription pricing. German automotive manufacturers favor this model for IoT sensor network integration where latency tolerance permits off-premise processing.
- Private Cloud:Dedicated tenant environments with single-organization compute isolation. Healthcare authorities in the Netherlands specify this deployment for patient diagnostic data pipelines under EMA guidelines.
- Multi-Cloud:Distributed runtime across two or more hyperscaler environments to mitigate vendor concentration risk. French financial services firms adopt this pattern to satisfy operational resilience mandates from national regulators.
The dominant share belongs to Public Cloud, while Hybrid Cloud is closing the gap fastest as regulated industries reconcile sovereignty requirements with modernization timelines.
Service Type:
Revenue contribution patterns reflect which capabilities enterprises externalize versus retain in-house.
- API Management:Externalizes digital services to ecosystem partners through gateway federation, rate limiting, and developer portal provisioning. Dutch logistics chains and Nordic retail networks negotiate contracts tied to API call volumes rather than fixed licensing.
- Process Automation:Embedded workflow engines displace legacy RPA installations among European SMEs prioritizing real-time responsiveness. Polish and Romanian automotive suppliers represent underpenetrated whitespace for this segment.
- Data Integration:Cross-application synchronization with built-in lineage tracking for GDPR compliance. Financial institutions in France demand this service for auditable cross-border transfer mechanisms.
- Application Integration:Protocol translation and message transformation between legacy ERP and cloud-native systems. German manufacturers deploy this capability to bridge shop-floor sensor networks with central planning systems.
API Management captures the largest revenue share, though Process Automation is expanding most quickly as mid-market buyers replace batch-oriented legacy infrastructure.
End User:
Contract structures and sales cycles vary dramatically by organizational scale and procurement sophistication.
- Large Enterprises:Multi-year agreements with professional services attachments for mainframe-compatible hybrid stacks. IBM sustains entrenched positions here through z/OS integration expertise.
- SMEs:Subscription consumption with rapid deployment timelines and minimal customization. Containerized Kafka-native platforms compress integration sprints from 18-month waterfalls to 6-week iterations.
- Public Sector:Procurement governed by EU AI Act risk classification and CE marking requirements under the Cybersecurity Act. Healthcare authorities in France now mandate documented provenance trails for diagnostic algorithm inputs.
- Non-Profit Organizations:Cost-constrained deployments prioritizing donor data protection and grant reporting automation. GDPR enforcement shapes vendor selection around encryption standards.
Large Enterprises dominate absolute spending, while SMEs are gaining share fastest as self-service platforms reduce deployment barriers.
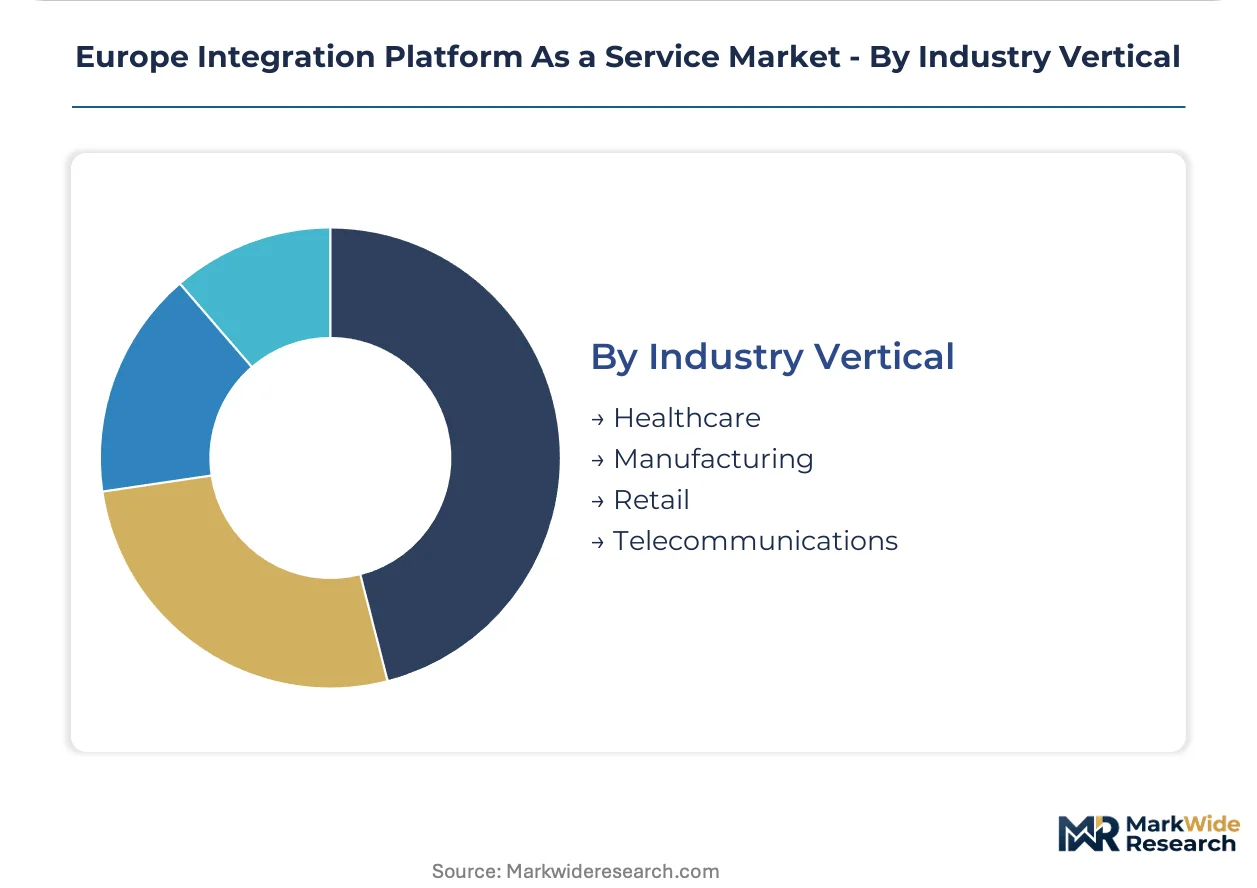
Industry Vertical:
Sector-specific compliance regimes create vendor stickiness and pricing power differentiation.
- Manufacturing:Event-driven architectures with sub-100ms latency for predictive maintenance alerts. German automotive suppliers adopt streaming-native stacks to connect legacy ERP with IoT sensor networks.
- Healthcare:GxP-compliant pipelines with immutable logging for pharmaceutical batch records. EMA guidelines extend validation requirements to cloud-based integrations in life sciences.
- Retail:Real-time inventory synchronization across distributed fulfillment networks. Benelux logistics firms leverage usage-tiered pricing tied to transaction volumes.
- Telecommunications:Network function virtualization orchestration and subscriber data management. National digital sovereignty initiatives favor European-hosted providers for this vertical.
Manufacturing holds the leading position, with Healthcare climbing fastest as the EU AI Act forces hospitals to demand traceable data flows for high-risk diagnostic systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act and GDPR enforcement are compressing vendor selection cycles across European enterprise buyers, with national digital sovereignty initiatives favoring EU-hosted providers over non-European alternatives.
Germany
Automotive IoT convergence drives cloud-native middleware procurement as vehicle manufacturers bridge legacy ERP with real-time sensor networks. The KBA (Federal Motor Transport Authority) and BSI (Federal Office for Information Security) impose stringent cybersecurity standards on connected vehicle data pipelines. Stuttgart and Munich host dense clusters of automotive suppliers adopting sub-100ms latency streaming stacks for predictive maintenance alerts.
France
Healthcare authorities demand auditable data provenance trails for diagnostic algorithm inputs under EU AI Act high-risk system classifications. ANSM and CNIL jointly enforce pharmaceutical data integrity and patient privacy requirements across cloud-based integrations. The Paris-Saclay research cluster and Lyon biotech corridor anchor GxP-compliant pipeline deployments for life sciences batch record synchronization.
Netherlands
Logistics chains and retail networks negotiate usage-tiered contracts tied to API call volumes rather than fixed licensing arrangements. National digital infrastructure programs under the Dutch Digitalization Strategy prioritize EU-sovereign processing nodes for critical supply chain data. Rotterdam's port ecosystem and Amsterdam's fintech cluster drive multi-cloud deployments to satisfy operational resilience mandates.
United Kingdom
Financial services institutions in the City of London and Canary Wharf prioritize managed integration services with built-in encryption for cross-border data transfers post-Brexit. The Financial Conduct Authority and Information Commissioner's Office shape vendor selection around auditable lineage and UK data residency requirements. Manchester and Edinburgh emerging tech clusters accelerate SME adoption of containerized workflow engines displacing legacy RPA.
Poland
Automotive suppliers in the Silesian and Greater Poland regions remain underpenetrated for ecosystem integration, presenting whitespace for API-first platform vendors serving German OEM supply chains. The Polish Financial Supervision Authority and Personal Data Protection Office align enforcement with GDPR standards for banking and insurance data flows. Warsaw's enterprise software market shows accelerating demand for subscription-based process automation among mid-market manufacturers.
Europe Integration Platform As a Service Market Competitive Landscape
Player mix skews toward hyperscaler-backed platforms and specialized data governance vendors, creating a bifurcated structure between scale-driven infrastructure providers and compliance-focused specialists. The competitive arena organizes around three strategic archetypes: cloud-native challengers with containerized runtime engines, legacy integration incumbents with mainframe-compatible hybrid stacks, and regional specialists emphasizing EU data sovereignty. Dominant competitive moves include M&A activity targeting Kubernetes-native workflow capabilities and strategic partnerships between European hosting providers and global software vendors to satisfy digital sovereignty requirements.
Within the hyperscaler tier, Microsoft leverages Azure infrastructure across Northern European deployments, while IBM sustains entrenched positions in regulated industries through hybrid integration expertise. Informatica occupies a specialist position addressing GDPR lineage requirements for financial services clients, exemplifying the compliance-focused archetype that gains traction as EU AI Act enforcement intensifies.
| Leading Market Players |
|---|
| MuleSoft |
| Dell Boomi |
| Informatica |
| SnapLogic |
| Microsoft |
| IBM |
| Oracle |
| TIBCO Software |
| Frends |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four month CE certification timelines for cloud integration platforms compress vendor qualification windows and concentrate pricing power among pre-certified incumbents serving GDPR-mandated European deployments. This lead-time band forces buyers into multi-year commitments with established providers, while uncertified challengers absorb carrying costs through extended sales cycles.
Pricing Analysis
Certification level under the EU Cybersecurity Act creates the primary spread between premium and standard tiers, with CE-marked platforms commanding substantial premiums over uncertified alternatives. Subscription models dominate, with usage-tiered pricing tied to API call volumes displacing fixed-seat licensing among Dutch logistics and Nordic retail buyers. Cost compression in the mid-market intensifies as containerized open-source alternatives erode margins on basic orchestration services. SMEs exhibit highest price sensitivity, while regulated financial institutions in Frankfurt and Paris prioritize compliance over cost optimization.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for specialized hardware appliances supporting on-premise hybrid deployments, though pure software iPaaS offerings remain insulated from physical supply chain disruptions. Software development concentrates in Germany, Ireland, and Poland, with runtime engine development anchored in Kubernetes-native engineering clusters. The supply chain draws from open-source Apache Kafka and MQTT protocol stacks, commercial cloud infrastructure, and specialized encryption hardware modules. Single-source vulnerability in hyperscaler compute capacity represents the dominant structural risk. Distribution runs through direct enterprise sales teams and hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across compliance requirements, deployment models, and vertical specializations creates multiple niche entry points as the EU AI Act and GDPR enforcement splinter homogeneous demand into segment-specific procurement criteria.
For Market Incumbents: Consolidate certification advantages by accelerating CE marking for adjacent workflow automation modules before regulatory backlogs extend further. Acquire Kubernetes-native talent pools in Poland and Romania to offset integration architect scarcity. Defend against open-source displacement by embedding immutable logging and lineage tracking as standard platform features rather than premium add-ons. For New Entrants and Emerging Players: GxP-compliant integration pipelines for pharmaceutical batch records represent the most penetrable whitespace, with EMA guidelines extending validation requirements to cloud-based systems faster than incumbents can adapt. Target Polish and Romanian automotive suppliers serving German OEM supply chains with API-first platforms compressing deployment timelines. Lead with usage-tiered pricing and rapid 6-week implementation sprints to bypass incumbent professional services dependencies. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-infrastructure play because regulatory complexity deepens moats around vendors with pre-certified, auditable integration stacks. Acquisition candidates include regional European hosting providers with sovereign cloud credentials and workflow engine specialists with healthcare AI auditability features. Monitor CE certification approval velocity at notified bodies as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Certification Acceleration | Pre-positions platforms for EU Cybersecurity Act procurement mandates before competitor qualification delays. |
| Kubernetes-Native Acquisition | Addresses skilled integration architect scarcity through containerized runtime engine talent consolidation. |
| Healthcare AI Partnership | Secures traceable data pipeline requirements under EU AI Act high-risk system classifications. |
| Multi-Cloud Distribution Alliance | Satisfies French operational resilience mandates through distributed runtime across hyperscaler environments. |
| Pharmaceutical Validation Program | Captures EMA-guided GxP-compliant demand for cloud-based batch record integrity in life sciences. |
Research Methodology
Desk research of hyperscaler capex disclosures, EU regulatory filings, and vertical industry procurement databases preceded structured interviews with CTOs, IT procurement officers, platform engineers, and integration specialists at European enterprises. Primary fieldwork across Germany, France, and the Netherlands validated deployment model preferences and pricing sensitivity thresholds. Secondary sources included SEC filings from listed integration vendors, EMA guideline documents, and national data protection authority enforcement records. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Variance decomposition across deployment models, service types, organization sizes, and industry verticals structured the analytical framework over the projection horizon. CAGRs derived from segment-level adoption curves weighted by regulatory enforcement timelines and digital sovereignty program allocations. Modeled inputs included API call volume growth rates at Dutch logistics firms, containerized platform deployment velocity among German automotive suppliers, and CE certification pipeline throughput at notified bodies.
Forecasts assume regulatory continuity in EU AI Act implementation and GDPR enforcement patterns; material policy shifts would require re-modeling. Technology substitution risks from generative AI-powered integration tools and hyperscaler bundling strategies represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Recreation Management Software Market
Software & Services
Global Cinema Software Market
Software & Services
Logistics Services Software Market
Software & Services
App Development Software Market
Software & Services
Global ITSM Software Market
Software & Services
Electronic Design Automation Software Market
Software & Services
Enterprise Performance Management (EPM) Software Market
Software & Services
Global Auction Software Market
Software & Services
North America Servicenow Store Apps Market
Software & Services
Push Notifications Software Market
Software & Services
Media Planning Software Market
Software & Services
Spend Analysis Software Market
Software & Services
Automotive Hypervisor Market
Software & Services
Business Activity Monitoring Software (BAM) Market
Software & Services
EDA Tools Market
Software & Services
Co-Browsing Software Market