
 Software Release Management Tools Market | 2026-2036
Software Release Management Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Software Release Management Tools Market Outlook
Multi-source tooling strategies is decoupling enterprise buyers from single-vendor CI/CD stacks. Red Hat (Ansible) leverages open-source automation to anchor hybrid deployment scenarios. Microsoft (Azure Pipelines) competes through native cloud integration with enterprise Microsoft ecosystems. Atlassian (Jira) extends issue-tracking dominance into release orchestration workflows.
Software release management tools coordinate the planning, scheduling, and controlling of software builds through staging environments and production deployment, typically integrating version control systems, automated testing frameworks, and rollback mechanisms to ensure release integrity. Cloud-based deployment models now capture the fastest expansion as enterprises retire on-premise infrastructure, while workflow automation functionality commands premium pricing due to its direct impact on mean-time-to-recovery metrics. The SMB end-user segment shows accelerating uptake of managed services offerings that abstract toolchain complexity.
FDA 21 CFR Part 11 requirements for validated software systems shape healthcare sector procurement, while SEC cybersecurity disclosure rules pressure finance verticals toward auditable release trails. ISO 27001 and SOC 2 Type II certifications function as gatekeepers for vendor selection in regulated industries. Stakeholders must weigh toolchain consolidation against best-of-breed flexibility as compliance documentation demands intensify.
Market Dynamics
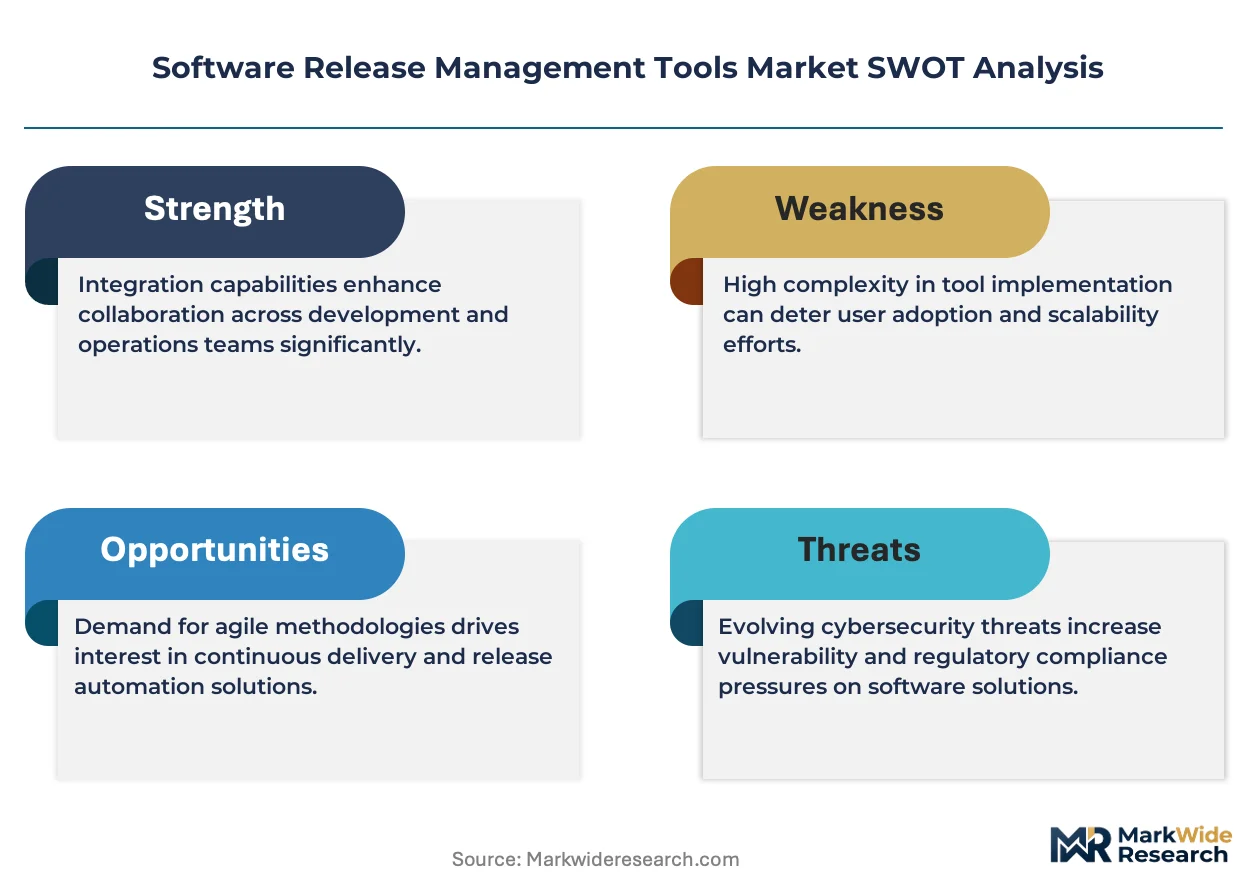
DevSecOps integration is compressing release cycles while expanding audit surface area, forcing enterprises to re-architect automation stacks around compliance-by-design rather than retrofitting controls post-deployment.
Growth Catalysts
- Federal IT Modernization Mandates:United States government cloud migration directives are accelerating procurement of FedRAMP-authorized release orchestration platforms across defense and civilian agencies.
- ISO 27001 Certification Requirements:Financial services procurement committees now gate vendor selection on SOC 2 Type II attestation, redirecting budget toward auditable pipeline tools.
- Container Orchestration Proliferation:Kubernetes-native deployment patterns in Silicon Valley enterprise clusters are standardizing GitOps workflows and infrastructure-as-code practices.
Market Restraints
- Specialized Talent Scarcity:DevSecOps engineer shortages in secondary technology hubs constrain enterprise ability to operate complex toolchain integrations.
- Legacy Mainframe Dependencies:Banking and insurance verticals maintain COBOL-based core systems that resist API-native release automation without expensive middleware layers.
- Open-Source License Uncertainty:Polyglot dependency trees in commercial distributions expose users to GPL and SSPL contagion risks that legal teams must adjudicate.
Strategic Opportunities
- Healthcare Validated Systems:FDA 21 CFR Part 11 compliance tooling for medical device software represents an underpenetrated segment with premium pricing tolerance.
- Edge Deployment Orchestration:Convergence of 5G network slicing and lightweight container runtimes enables release management extension into manufacturing floor and retail edge locations.
- India PLI Scheme Alignment:Domestic software product incentives are attracting multinational vendors to establish development centers and localized release infrastructure.
Industry Challenges
- Toolchain Sprawl Integration:Enterprises average 15+ discrete DevOps tools that resist unified telemetry, forcing expensive platform engineering investments.
- SBOM Generation Burden:Executive Order 14028 mandates for software bill of materials are creating documentation workflows that slow release velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software Release Management Tools Market |
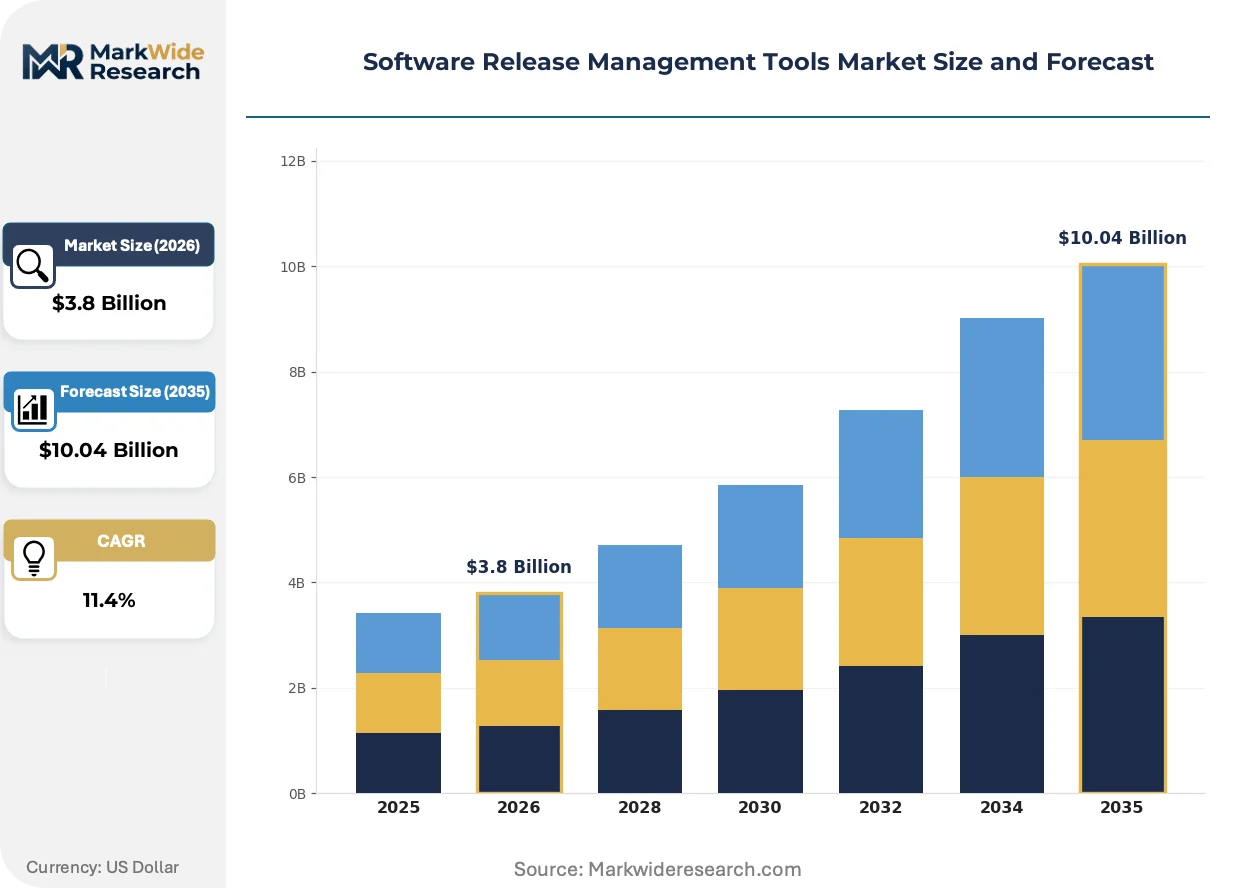
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Services End User: SMBs, Enterprises, Startups, Government Functionality: Continuous Integration, Automated Testing, Workflow Automation, Version Control Industry Vertical: Finance, Healthcare, IT, E-Commerce |
| Companies Covered | Red Hat (Ansible), Netflix (Spinnaker), ClickUp, Digital.ai, Octopus Deploy, Microsoft (Azure Pipelines), Plutora, Jenkins, Atlassian (Jira), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software Release Management Tools Market Strategic Shifts
Release automation is absorbing artificial intelligence capabilities that previously required separate operations teams, collapsing the traditional boundary between deployment orchestration and intelligent remediation.
AI-powered anomaly detection is absorbing failure-pattern recognition from post-incident retrospectives into pre-deployment gates. Financial services firms in New York and London are piloting these capabilities for trading system releases. The technology is absorbing risk-assessment functions that previously required manual change advisory boards, compressing approval timelines from days to minutes.
EU Cyber Resilience Act requirements are mandating software update transparency and vulnerability disclosure timelines for connected products. Industrial automation vendors must now embed release metadata into device firmware for CE marking compliance. German automotive suppliers are restructuring DevOps organizations to satisfy these documentation burdens ahead of enforcement deadlines.
Platform engineering teams are consolidating procurement authority previously distributed across individual development squads. Enterprise buyers in the United States are negotiating enterprise-wide site licenses that displace point-tool subscriptions. This concentration is most visible among Fortune 500 manufacturers standardizing on single-vendor pipelines to reduce support fragmentation.
Software Release Management Tools Market Segmentation
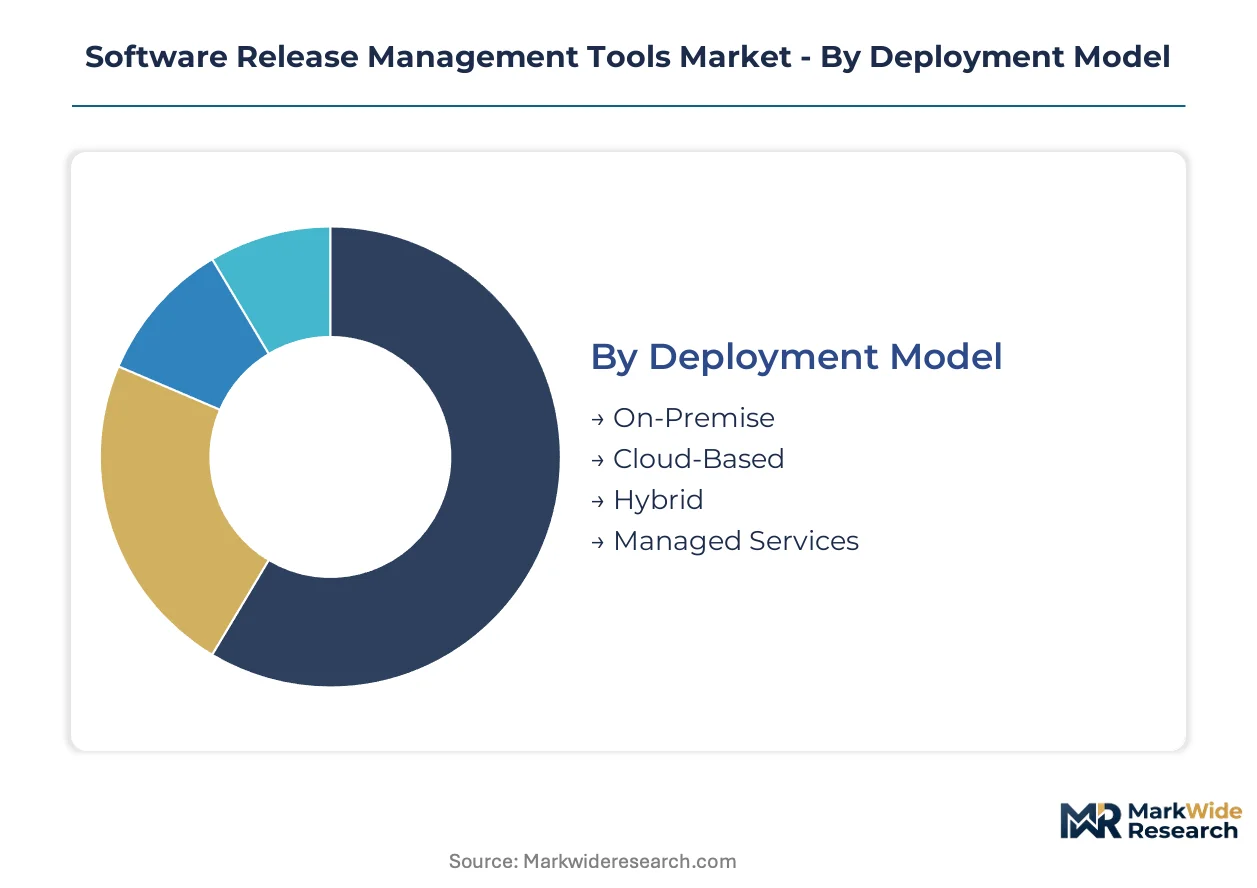
Release management procurement splits sharply between enterprises modernizing legacy stacks and cloud-native entrants building greenfield. Tool selection criteria diverge across these maturity stages, with replacement cycles driving consolidation in established accounts and flexibility dominating new deployments.
Deployment Model:
Upgrade cycles favor cloud migration, though regulatory latency preserves on-premise footprints in sensitive verticals.
- Cloud-Based:Multi-tenant architectures eliminate infrastructure maintenance overhead while enabling elastic scaling for seasonal release surges. United States federal agencies under FedRAMP authorization mandates are accelerating procurement of government cloud instances for civilian deployment pipelines.
- Hybrid:Split deployments maintain sensitive build artifacts on-premise while leveraging cloud orchestration for non-production environments. Financial services firms in New York and London use this model to satisfy data residency requirements without sacrificing velocity.
- On-Premise:Air-gapped installations persist in defense contractors and classified research facilities where external connectivity is prohibited.
- Managed Services:Vendor-operated toolchain abstraction appeals to SMBs lacking platform engineering expertise.
Cloud-Based sits at the top of the volume ranking, with Managed Services climbing the fastest.
End User:
Customer sophistication determines pricing tolerance and support requirements across the adoption spectrum.
- Enterprises:Fortune 500 manufacturers negotiate enterprise-wide site licenses consolidating 15+ point tools into unified pipelines. Platform engineering investments absorb toolchain sprawl while standardizing compliance documentation across distributed development squads.
- SMBs:Managed services offerings abstract Kubernetes complexity and GitOps workflow design, enabling release automation without dedicated DevSecOps headcount.
- Startups:Open-source CI/CD foundations with commercial add-on purchases minimize early-stage capital outlay.
- Government:FedRAMP-authorized platforms are mandatory for United States defense and civilian agency procurement, with authorization timelines stretching vendor sales cycles.
Enterprises dominate current procurement value, with SMBs expanding most quickly as managed services mature.
Functionality:
Feature depth correlates directly with mean-time-to-recovery improvements and audit trail completeness.
- Workflow Automation:Orchestration engines coordinate multi-environment promotion gates, rollback triggers, and notification routing. Premium pricing reflects direct impact on incident response metrics and change advisory board compression from days to minutes.
- Automated Testing:Pre-deployment validation pipelines integrate security scanning, performance benchmarking, and compliance policy enforcement. Healthcare sector adoption is accelerating under FDA 21 CFR Part 11 requirements for validated software systems.
- Continuous Integration:Build automation and artifact repository management form the foundational layer of modern release pipelines.
- Version Control:Source code management integration enables traceability from commit through production deployment.
Workflow Automation commands the highest pricing tier, with Automated Testing gaining share fastest in regulated verticals.
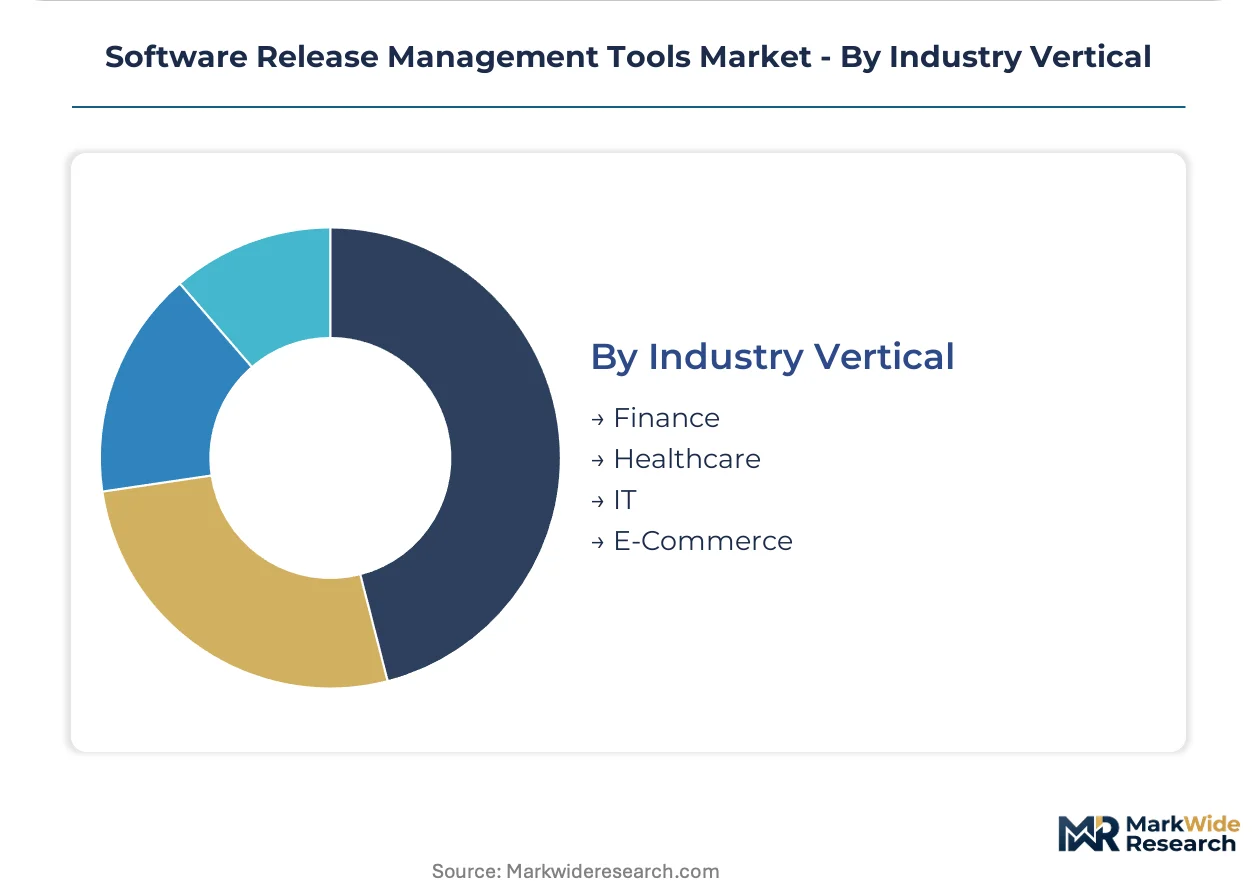
Industry Vertical:
Compliance mandates reshape vendor selection criteria and procurement committee composition sector by sector.
- Finance:SEC cybersecurity disclosure rules and SOC 2 Type II attestation requirements pressure institutions toward auditable release trails. Procurement committees now gate vendor selection on compliance documentation completeness.
- Healthcare:FDA 21 CFR Part 11 requirements for validated software systems shape medical device software procurement. German automotive suppliers are restructuring DevOps organizations to satisfy EU Cyber Resilience Act documentation burdens ahead of enforcement deadlines.
- IT:Silicon Valley enterprise clusters standardize on Kubernetes-native GitOps workflows and infrastructure-as-code practices.
- E-Commerce:Seasonal traffic spikes demand elastic release infrastructure capable of supporting multiple daily deployments during peak retail periods.
Finance leads vertical spending intensity, with Healthcare expanding most steeply under regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's cloud-native enterprise cluster anchors procurement intensity for release management platforms, with federal IT modernization mandates amplifying United States demand. DevSecOps integration and compliance requirements reshape vendor selection criteria across major technology hubs.
United States
FedRAMP-authorized release orchestration platforms dominate defense and civilian agency procurement under federal cloud migration directives. SEC cybersecurity disclosure rules pressure New York and Boston financial institutions toward auditable release trails. Platform engineering teams at Fortune 500 manufacturers in the Midwest negotiate enterprise-wide site licenses displacing point-tool subscriptions.
Germany
Industrial automation vendors restructure DevOps organizations to satisfy EU Cyber Resilience Act documentation burdens ahead of enforcement deadlines. CE marking compliance now mandates embedded release metadata in device firmware for connected products. Automotive suppliers in Bavaria and Baden-Württemberg pilot Kubernetes-native GitOps workflows for manufacturing floor deployment.
United Kingdom
Financial services firms in London accelerate adoption of automated release pipelines to meet stringent audit requirements from SOC 2 and ISO 27001 frameworks. DevSecOps engineer shortages constrain enterprise ability to operate complex toolchain integrations outside the capital. Platform engineering investments absorb toolchain sprawl across distributed development squads in the Southeast technology corridor.
India
Domestic software product incentives under the PLI scheme attract multinational vendors to establish development centers and localized release infrastructure. SMBs in Bangalore and Hyderabad adopt managed services offerings that abstract Kubernetes complexity and GitOps workflow design. Talent availability in secondary technology hubs lags primary metros, constraining enterprise toolchain integration capabilities.
Japan
Manufacturing enterprises in the Kanto and Kansai regions standardize on hybrid deployment models maintaining sensitive build artifacts on-premise while leveraging cloud orchestration. METI industrial digitization programs accelerate procurement of workflow automation functionality. DevSecOps integration compresses release cycles while expanding audit surface area for Tokyo-based financial institutions.
Software Release Management Tools Market Competitive Environment
Global majors compete with regional champions across hybrid deployment scenarios and compliance specialization tiers. The vendor base organizes around three strategic archetypes: open-source automation anchors, native cloud integrators, and issue-tracking extenders. Consolidation pressures intensify as platform engineering teams centralize procurement authority previously distributed across individual development squads. Dominant competitive moves include strategic partnerships for FedRAMP authorization and portfolio diversification into healthcare-validated systems.
Within the open-source automation tier, Red Hat (Ansible) and Jenkins exemplify hybrid deployment anchoring strategies. Microsoft (Azure Pipelines) and Atlassian (Jira) occupy positions as native cloud integrators and workflow extenders respectively. Netflix (Spinnaker) represents specialized continuous delivery orchestration for cloud-native enterprise clusters.
| Leading Market Players |
|---|
| Red Hat (Ansible) |
| Netflix (Spinnaker) |
| ClickUp |
| Digital.ai |
| Octopus Deploy |
| Microsoft (Azure Pipelines) |
| Plutora |
| Jenkins |
| Atlassian (Jira) |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure pricing indices cascade through software release management tool supply chains, compressing margins for vendors dependent on hyperscaler compute while amplifying pricing power for those with in-house orchestration layers. Enterprise buyers absorb tiered subscription costs that stratify by compliance certification depth and workflow automation sophistication.
Pricing Analysis
Input-cost pass-through from cloud compute and storage underpins SaaS-tiered subscription models across the market. Pricing stratifies across FedRAMP-authorized premium tiers, SOC 2 Type II validated standard tiers, and unmanaged economy tiers for non-regulated use cases. Cost compression in the economy tier is intensifying because open-source alternatives erode baseline willingness-to-pay. SMBs exhibit highest price sensitivity, while Fortune 500 manufacturers in regulated verticals demonstrate inelastic demand for audit-ready workflow automation.
Supply Chain Analysis
Specialized engineering talent supply rests on United States, India, and Germany as the primary concentration nodes for DevSecOps expertise. Commercial distributions draw from open-source CI/CD foundations, third-party security scanning engines, and hyperscaler infrastructure APIs. Single-source vulnerability concentrates in Kubernetes control plane dependencies maintained by the Cloud Native Computing Foundation. Distribution runs through direct enterprise sales teams, cloud marketplace listings, and managed service provider channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The software release management tools market functions as a stable compounder, with regulatory compliance mandates generating durable procurement tailwinds across financial services and healthcare verticals.
For Market Incumbents: Cement platform engineering mindshare by embedding AI-powered anomaly detection into pre-deployment gates before specialized vendors capture this workflow. Fortify FedRAMP authorization moats through strategic partnerships with government cloud providers, as authorization timelines stretch to 18-24 months. Deepen upstream control over security scanning engine supply through acquisition of specialist firms in the software composition analysis space.
For New Entrants and Emerging Players: Capture healthcare validated systems white space where FDA 21 CFR Part 11 compliance tooling commands premium pricing tolerance and incumbent coverage remains thin. Target edge deployment orchestration for manufacturing floor use cases as 5G network slicing matures. Lead with GitOps-native positioning that collapses the traditional boundary between infrastructure-as-code and release orchestration.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertical-specific compliance automation vendors that have achieved SOC 2 Type II attestation but not yet scaled beyond $50 million recurring revenue. Long-term viability hinges on platform consolidation dynamics as enterprise buyers displace 15+ point tools with unified pipelines. Watch toolchain sprawl integration failure rates as the inflection indicator for accelerated consolidation windows.
| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Partnership | Unlocks United States federal agency procurement pipelines under cloud migration directives. |
| Healthcare Validated Systems Development | Captures FDA 21 CFR Part 11 premium pricing in medical device software segments. |
| AI-Powered Anomaly Detection Integration | Absorbs risk-assessment functions from manual change advisory boards into pre-deployment gates. |
| Edge Deployment Orchestration Extension | Extends release management into manufacturing floor locations via 5G network slicing convergence. |
| Platform Engineering Team Consolidation | Centralizes procurement authority previously distributed across individual development squads. |
Study Parameters
Bottom-up enterprise and SMB deployment modeling reconciled against top-down vendor revenue tracking forms the analytical core of this study. Primary interviews with CTOs, platform engineering directors, IT procurement officers, and DevSecOps practitioners combined with secondary validation from SEC filings, hyperscaler capex disclosures, and FedRAMP authorization databases. Triangulation across these sources anchors segmentation-level estimates for cloud-based, hybrid, on-premise, and managed services deployment models.
Input-output matrices map workflow automation, automated testing, continuous integration, and version control functionality demand against end-user sophistication tiers across the projection horizon. Segmentation dimensions include deployment model, organization size, vertical compliance intensity, and integration complexity. CAGRs derive from regression against historical adoption curves in comparable enterprise software categories, with specific inputs from Kubernetes-native GitOps penetration rates and SOC 2 Type II certification velocity.
Regulatory enforcement delays, open-source license contagion events, and DevSecOps talent availability shocks are the dominant revision risks to modeled outcomes. Forecasts embed assumptions about compliance mandate timelines and cloud migration acceleration that warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Kiosk Software Market
Software & Services
Content Moderation Software Market
Software & Services
Global Enterprise Architecture Tools Market
Software & Services
Workshop Management Software Market
Software & Services
Cloud-Based Payroll Software Market
Software & Services
Braking Systems Software Market
Software & Services
Global Application Management Services Market
Software & Services
Global Nosql Software Market
Software & Services
Global Rapid Application Development Market
Software & Services
Storyboarding Software Market
Software & Services
Global Decision Support Software Market
Software & Services
School Timetable Software Market
Software & Services
Generative Design Software Market
Software & Services
Time and Attendance Software Market
Software & Services
Observability Platform Market
Software & Services
Pharmacy Billing Software Market