
 Medical E-Commerce Software Market | 2026-2036
Medical E-Commerce Software Market Size, Share, and Industry Trends Forecast 2026-2036
Medical E-Commerce Software Market Foresight
Market Context
North America is reshaping competitive dynamics in medical e-commerce software through accelerated cloud infrastructure investment and health system consolidation. Amazon Pharmacy leverages its logistics backbone to dominate same-day pharmaceutical delivery networks. CVS Health anchors its position through integrated pharmacy benefit management tied to retail clinic e-prescribing workflows. JD Health International competes by specializing in AI-driven diagnostic equipment marketplaces across East Asian hospital networks.
Technical Definition and Segment Structure
Medical e-commerce software denotes digital platforms enabling procurement, payment, and fulfillment of pharmaceuticals, medical devices, and clinical supplies between healthcare providers and vendors, typically incorporating encrypted transaction protocols, inventory synchronization APIs, and regulatory audit trails. The primary commercial purpose centers on reducing procurement cycle times, eliminating manual purchase order errors, and ensuring traceability for recalled or expired medical products. Cloud-Based deployment leads segment value generation as hospitals abandon on-premise maintenance burdens, while Telehealth Solutions represent the fastest-expanding product category as virtual care reimbursement codes expand provider willingness to integrate dispensing into remote consultations. Payment Processing commands concentrated margin pools due to PCI-DSS compliance complexity and interchange fee structures unique to healthcare merchant categories.
Regulatory Framework
FDA digital health software precertification frameworks and HIPAA security rule mandates jointly determine product development roadmaps and customer onboarding complexity for medical e-commerce vendors. The Drug Supply Chain Security Act serialization requirements enforced by the FDA further compel platform investments in track-and-trace interoperability. Stakeholders must monitor evolving state-level telehealth prescribing regulations and DEA controlled substance e-prescribing authentication standards to anticipate platform certification requirements that will determine market access eligibility.
Market Dynamics
Hospital procurement teams are consolidating supplier relationships onto unified cloud platforms as health system mergers accelerate vendor rationalization mandates. This structural consolidation is compressing the addressable vendor base while elevating platform-scale requirements.
Growth Catalysts
- HIPAA Security Rule Enforcement:Compliance mandates are compelling hospitals to replace fragmented purchasing tools with validated enterprise suites that embed encrypted audit trails.
- Cloud Infrastructure Migration:Health systems are abandoning on-premise procurement servers to eliminate maintenance overhead and enable real-time inventory synchronization across distributed facilities.
- Telehealth Reimbursement Expansion:New CPT codes for remote therapeutic monitoring are driving integration between virtual care platforms and dispensing workflows.
Market Restraints
- PCI-DSS Compliance Costs:Healthcare merchant category complexity elevates payment processor fees and technical validation expenses for patient-facing transactions.
- Legacy ERP Integration Friction:Hospital back-office systems built on 1990s architectures resist API-based data exchange with modern procurement platforms.
- Controlled Substance Authentication:DEA e-prescribing requirements for Schedule II-V drugs impose multi-factor identity verification that slows transaction velocity.
Strategic Opportunities
- Rural Health Network Digitization:Critical access hospitals in underserved regions lack integrated procurement infrastructure, creating whitespace for cloud-native platforms.
- AI-Driven Demand Forecasting:Machine learning models trained on surgical scheduling data can optimize par-level inventory and reduce carrying costs.
- Drug Supply Chain Security Act Track-and-Trace:FDA serialization mandates are forcing wholesale distributors to upgrade interoperability, opening integration service revenue.
Industry Challenges
- Cybersecurity Talent Scarcity:Healthcare IT departments struggle to recruit engineers with both HITRUST certification and e-commerce platform architecture experience.
- Multi-Stakeholder Workflow Design:Procurement software must simultaneously satisfy clinicians, supply chain managers, and revenue cycle teams with conflicting interface priorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical E-Commerce Software Market |
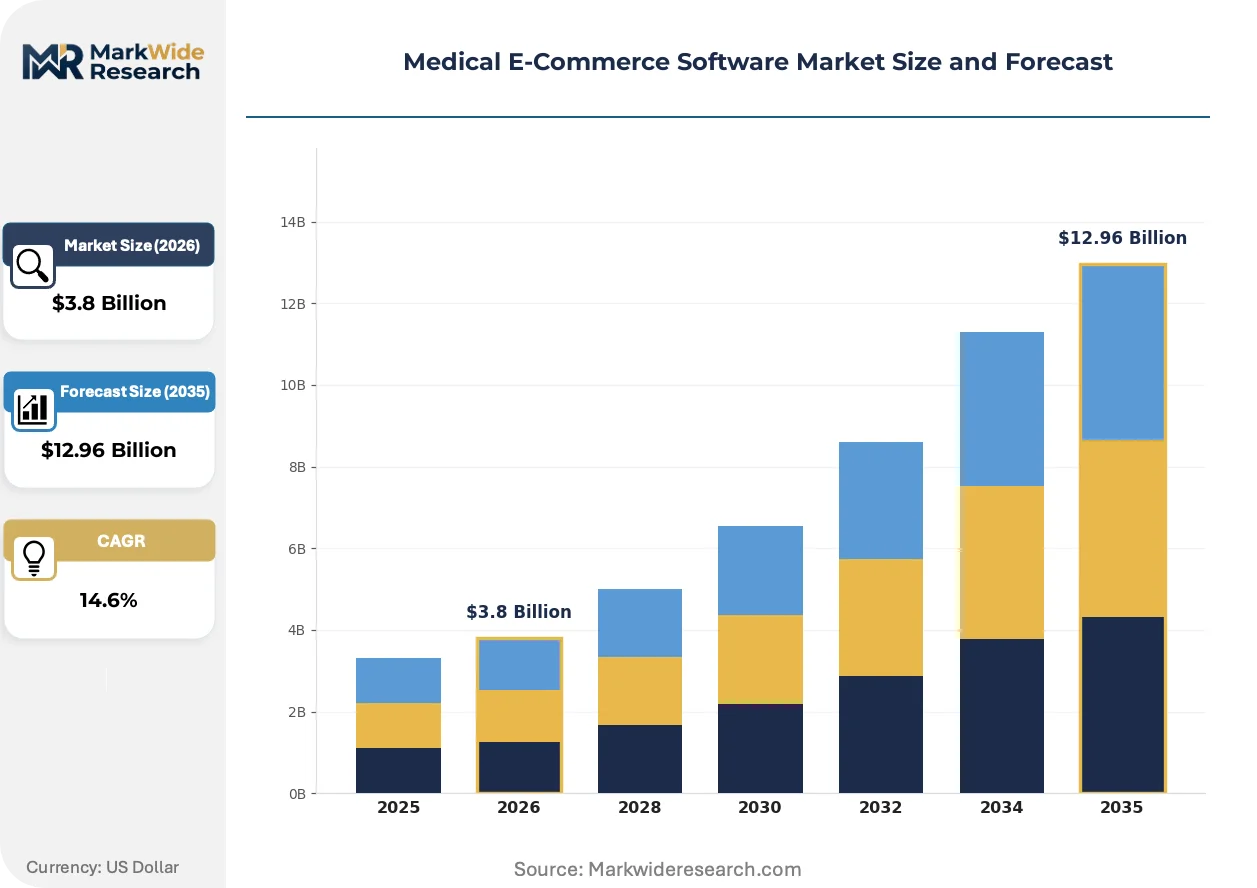
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EHR Systems, Telehealth Solutions, Inventory Management, Payment Processing End User: Pharmacies, Hospitals, Clinics, Individual Practitioners Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Platforms Technology: Blockchain, AI, Machine Learning, Mobile Apps |
| Companies Covered | Amazon Pharmacy, CVS Health, Walgreens Boots Alliance, Alibaba Health Information Technology, JD Health International, McKesson Corporation, GE Healthcare, Allscripts, Oracle NetSuite ERP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical E-Commerce Software Market Shifts & Advancements
Medical e-commerce platforms are converging clinical workflow integration with financial transaction infrastructure, blurring traditional boundaries between supply chain and care delivery software.
Blockchain-based provenance verification is migrating from pilot programs to production deployments for high-value implantable devices. Orthopedic surgery centers in the United States are adopting distributed ledger systems to authenticate device origin and sterilization history. This migration from paper-based chain-of-custody records is compressing recall response timelines from weeks to hours.
The FDA's digital health software precertification framework is restructuring vendor development priorities toward continuous validation models. Manufacturers must now embed automated testing pipelines that demonstrate real-time safety monitoring. Cloud-based procurement platforms face the steepest compliance burden as they handle both patient data and financial transactions.
Hospital buying committees are consolidating vendor relationships onto single-source contracts with enterprise-wide price guarantees. Integrated delivery networks in the United States are replacing spot-buying through distributor portals with committed volume agreements tied to EHR-embedded ordering workflows. This concentration is most visible among nonprofit health systems pursuing operating margin recovery through supply expense reduction.
Medical E-Commerce Software Market Segmentation
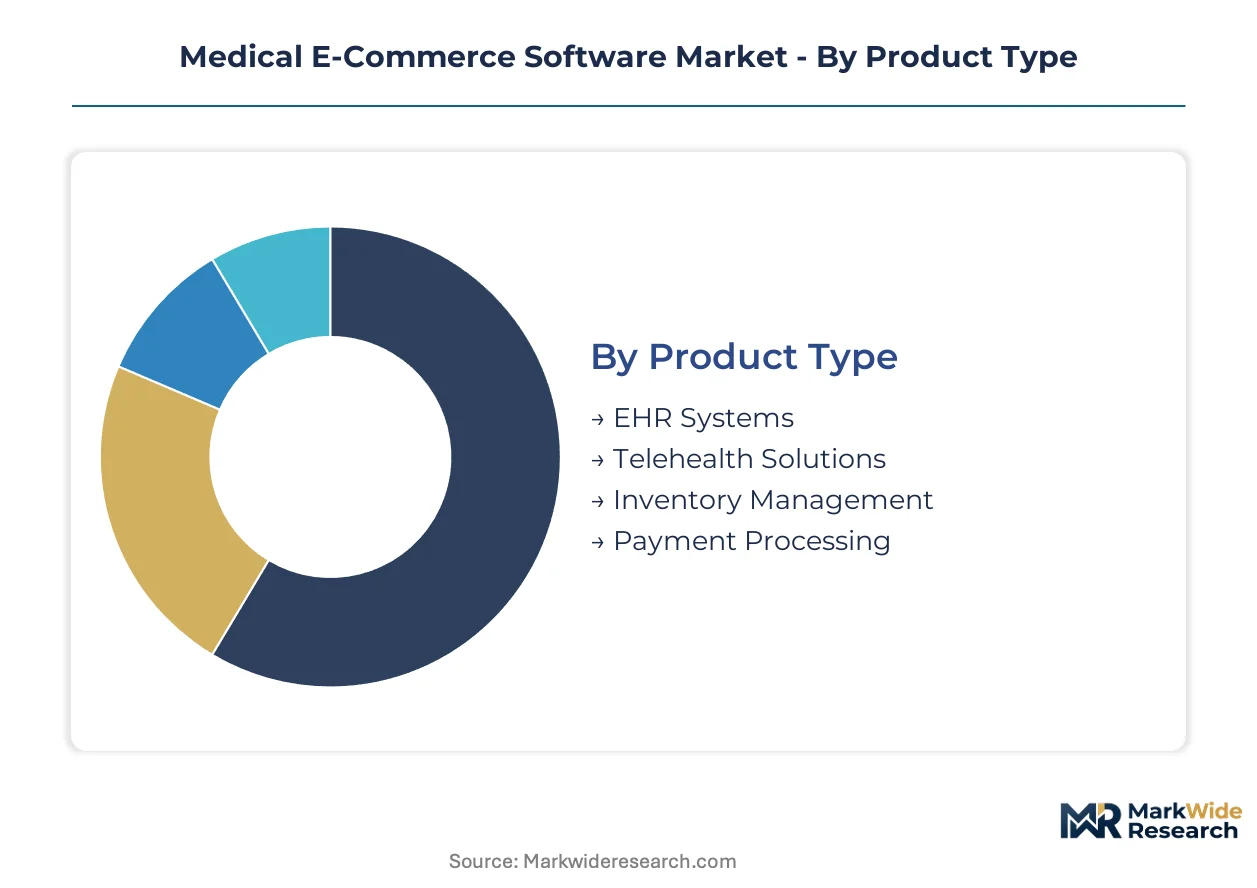
Medical e-commerce software segmentation reveals how procurement complexity fragments across clinical workflows, infrastructure maturity, and regulatory exposure. Vendors must align product architecture with specific deployment constraints and end-user technical capacity.
Product Type:
Mature transaction engines coexist with emerging care delivery integrations across this category.
- Payment Processing:PCI-DSS compliant transaction engines handle healthcare merchant category codes with specialized interchange fee structures. Hospital revenue cycle teams demand embedded audit trails for HIPAA financial privacy enforcement. Payment Processing retains volume leadership; Telehealth Solutions holds the steepest expansion curve.
- Telehealth Solutions:Virtual care platforms integrate e-prescribing and dispensing workflows through expanded CPT reimbursement codes. United States health systems prioritize these tools for remote therapeutic monitoring programs.
- EHR Systems:Electronic health record procurement modules embed supplier catalogs within clinical documentation interfaces.
- Inventory Management:Par-level optimization tools synchronize medical supply data across distributed hospital facilities through cloud APIs.
Payment Processing dominates current procurement budgets; Telehealth Solutions captures the fastest share gains.
End User:
Institutional scale determines platform complexity requirements and compliance burden distribution.
- Hospitals:Integrated delivery networks mandate enterprise-wide procurement consolidation with EHR-embedded ordering and FDA track-and-trace serialization compliance. These systems require multi-facility inventory visibility.
- Pharmacies:Retail and specialty pharmacies prioritize same-day fulfillment logistics with DEA-controlled substance authentication for Schedule II-V e-prescribing.
- Clinics:Ambulatory settings favor lightweight cloud platforms with minimal IT overhead for group practice procurement.
- Individual Practitioners:Solo providers need mobile-first dispensing tools with simplified credentialing for telehealth reimbursement.
Hospitals command the largest contract values; Individual Practitioners show the most rapid digitization acceleration.
Deployment:
Infrastructure cost structures divide customers across capital expenditure tolerance and technical staffing depth.
- Cloud-Based:Subscription models eliminate server maintenance overhead while enabling real-time inventory synchronization across health system networks. HIPAA business associate agreements govern vendor data handling.
- Hybrid:Mixed architectures preserve sensitive payment data on-premise while routing non-clinical workflows through cloud channels.
- On-Premise:Legacy installations persist where hospitals maintain dedicated cybersecurity teams and resist third-party data custody.
- Mobile Platforms:Native applications support point-of-care ordering for clinicians requiring bedside procurement access.
Cloud-Based deployments absorb the majority of new customer acquisitions; Mobile Platforms expand most quickly among frontline clinical users.
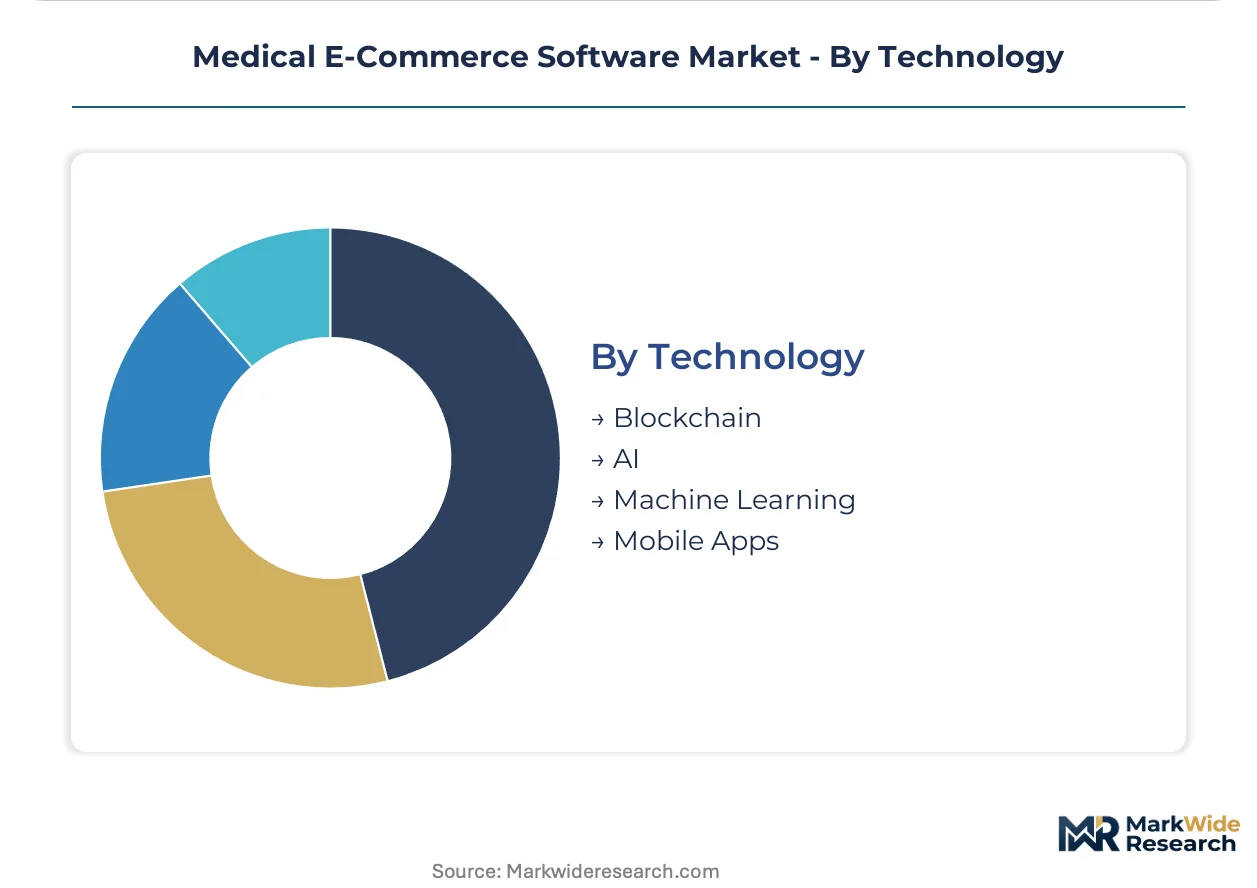
Technology:
Proven automation layers underpin experimental trust architectures in this segmentation.
- AI:Predictive models trained on surgical scheduling data optimize medical supply par levels and reduce carrying costs for orthopedic and cardiac service lines.
- Machine Learning:Demand forecasting algorithms process historical consumption patterns to automate reorder thresholds for high-turnover disposables.
- Blockchain:Distributed ledger systems authenticate implantable device provenance and sterilization history, compressing FDA recall response timelines from weeks to hours.
- Mobile Apps:Native interfaces enable barcode scanning and voice-activated ordering for warehouse and clinical floor staff.
AI commands the deepest R&D investment; Blockchain demonstrates the most dramatic compliance workflow transformation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA digital health oversight anchors the United States as the dominant geography, with HIPAA compliance mandates and health system consolidation driving procurement platform standardization. Health systems across multiple countries are rationalizing supplier relationships onto unified cloud infrastructure.
United States
Hospital procurement teams at integrated delivery networks are consolidating vendor contracts onto single-source agreements with enterprise-wide price guarantees. FDA Drug Supply Chain Security Act serialization requirements compel wholesale distributors to upgrade track-and-trace interoperability. The Greater Boston cluster hosts specialized vendors embedding automated testing pipelines for continuous validation models.
Germany
University hospital networks are migrating from on-premise procurement servers to cloud-based subscription models that eliminate maintenance overhead. EMA medical device regulations and GDPR financial privacy enforcement shape platform certification requirements. The Baden-Württemberg region concentrates health IT vendors serving orthopedic surgery centers with blockchain-based implant authentication.
China
Hospital networks in East Asia are adopting AI-driven diagnostic equipment marketplaces to optimize par-level inventory across distributed facilities. NMPA digital health software frameworks and dual carbon goals accelerate cloud infrastructure migration timelines. The Yangtze River Delta anchors JD Health International's logistics backbone for same-day pharmaceutical fulfillment.
United Kingdom
NHS trusts are replacing fragmented purchasing tools with validated enterprise suites that embed encrypted audit trails for HIPAA-equivalent data protection. MHRA medical device regulations and NHSX digital transformation mandates elevate platform-scale requirements. The London-Southeast corridor hosts vendors integrating EHR-embedded ordering workflows for ambulatory care networks.
India
Corporate hospital chains are expanding cloud-native procurement infrastructure to streamline medical supply purchasing across multi-facility networks. CDSCO pharmaceutical serialization requirements and PLI scheme incentives for health IT manufacturing shape vendor development priorities. The Karnataka-Telangana corridor concentrates telehealth platform developers serving individual practitioners with mobile-first dispensing tools.
Medical E-Commerce Software Market Competitive Landscape
Capability concentration sits with specialized health IT vendors; scale advantage sits with diversified retail and logistics conglomerates. The market structure reflects a tiered hierarchy where hospital-focused enterprise suites coexist with consumer-facing pharmacy platforms. Three strategic archetypes dominate: integrated health systems with captive pharmacy benefit management, cloud-native telehealth specialists, and logistics-heavy retail pharmacy operators. Competitive moves center on health system merger-driven vendor rationalization and API-based EHR integration partnerships.
Within the logistics-dominated tier, Amazon Pharmacy represents the scale-driven archetype leveraging distribution infrastructure for same-day pharmaceutical networks. CVS Health and Walgreens Boots Alliance occupy positions as integrated retail-healthcare hybrids combining pharmacy benefit management with clinic-based e-prescribing workflows. Among Asia-Pacific platform specialists, JD Health International exemplifies the AI-driven marketplace model serving hospital procurement teams with predictive demand forecasting capabilities.
| Leading Market Players |
|---|
| Amazon Pharmacy |
| CVS Health |
| Walgreens Boots Alliance |
| Alibaba Health Information Technology |
| JD Health International |
| McKesson Corporation |
| GE Healthcare |
| Allscripts |
| Oracle NetSuite ERP |
| Others |
Supply & Pricing Matrix
Overcapacity in cloud infrastructure across the United States is compressing SaaS subscription rates while elevating vendor switching incentives for hospital procurement teams. This utilization imbalance simultaneously pressures platform providers to absorb compliance costs and forces health systems to renegotiate multi-year contracts.
Pricing Analysis
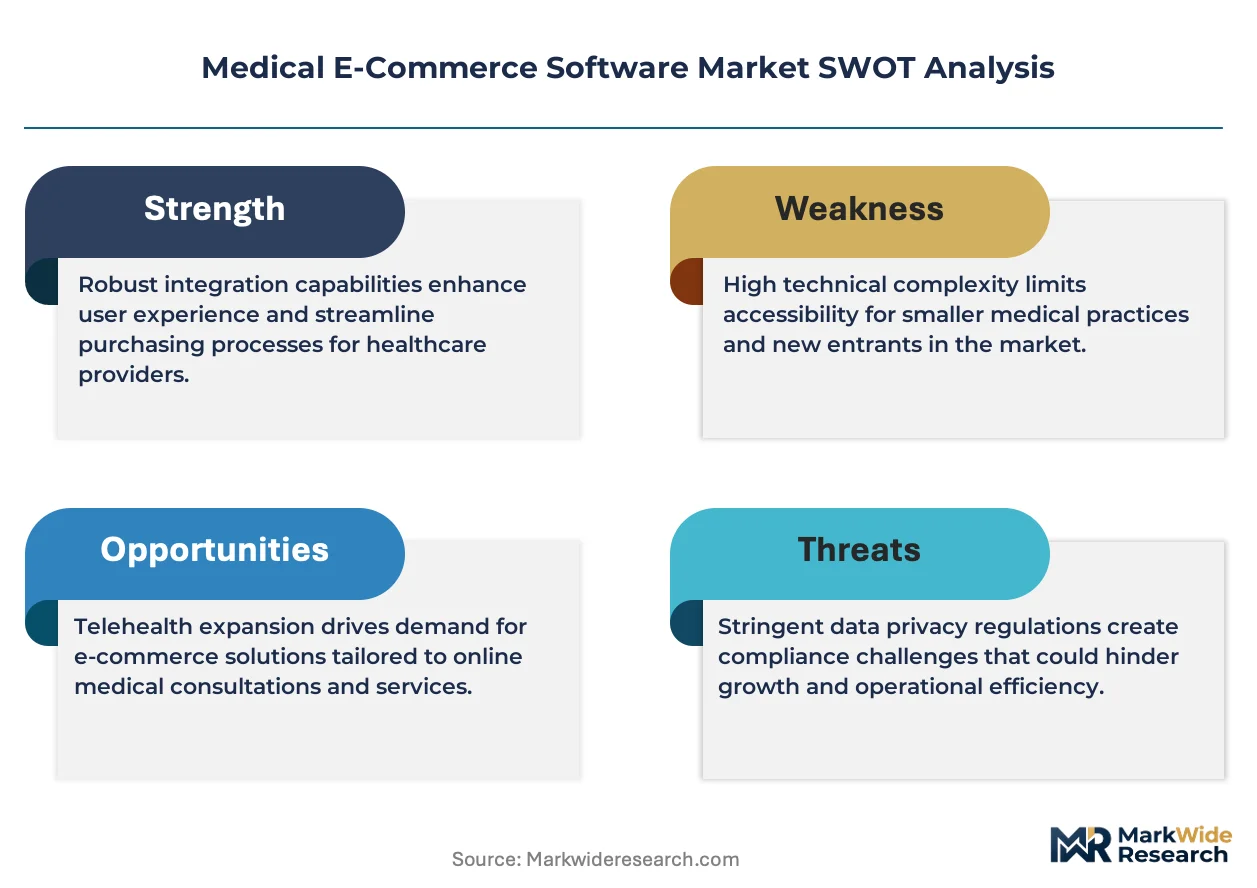
Geographic price spreads of 40-60% separate North American enterprise deployments from South Asian clinic-tier offerings. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by HIPAA certification tier and embedded EHR integration depth. Cost compression in the economy tier is intensifying because cloud-native entrants are undercutting legacy on-premise vendors. Individual practitioners show highest price sensitivity; integrated delivery networks prioritize total cost of ownership over per-seat rates.
Supply Chain Analysis
Export control regimes limiting AI chip flows to Chinese data centers are fragmenting cloud infrastructure supply across the United States, Ireland, and Singapore. Software development draws from Indian engineering talent pools, U.S. cybersecurity certification frameworks, and German encryption hardware. Single-source vulnerability concentrates in hyperscaler compute capacity controlled by three dominant providers. Distribution runs through direct enterprise sales teams supplemented by health IT systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in rural health network digitization as federal reimbursement expansion creates procurement budget availability outside metropolitan hospital clusters.
For Market Incumbents: Entrench position by embedding automated FDA validation pipelines into cloud-native platforms before precertification mandates harden. Acquire specialized telehealth workflow vendors to preempt API standardization by EHR giants. Threat substitution from Amazon Pharmacy's logistics integration demands backward control over fulfillment data layers. For New Entrants and Emerging Players: Rural health networks in the Upper Midwest and Mountain West represent the most penetrable geography, lacking integrated procurement infrastructure and facing vendor rationalization pressure from health system mergers. Target critical access hospitals with lightweight cloud platforms requiring minimal IT overhead. Go-to-market angle: pre-configured HIPAA business associate agreements with state hospital associations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across telehealth solutions as API commodification reduces development burn rates. Long-term viability favors platforms with embedded payment processing licenses and existing GPO contract relationships. Acquisition target archetype: cloud-native inventory management specialists with hospital reference accounts. Signal to watch: DEA e-prescribing certification backlogs as capacity constraint indicator.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Health Precertification | Automated validation pipelines embed continuous compliance into CI/CD workflows for cloud platforms. |
| Hospital System Partnership | Single-source enterprise agreements with IDNs lock out competitors through EHR-embedded ordering. |
| Blockchain Track-and-Trace Integration | Distributed ledger authentication compresses FDA recall response timelines for implantable devices. |
| Geographic Expansion | Rural health network penetration captures whitespace before incumbent vendor consolidation accelerates. |
| Strategic Partnership | GPO alliance integration embeds platforms within existing hospital procurement committee workflows. |
Research Methodology
A spread of perspectives from hospital procurement directors, health system CIOs, GPO contract managers, and FDA regulatory consultants converged on the working assumptions. Primary interviews with cloud platform engineers and revenue cycle leaders combined with secondary validation against CMS Medicare reimbursement databases, hospital procurement spend analyses, and SEC filings from publicly traded health IT vendors. Bottom-up facility-level adoption modeling triangulated against top-down health system IT budget projections.
Demand-supply balance across cloud infrastructure capacity and hospital procurement cycle timing anchored the analytical framework. Segmentation dimensions modeled include deployment architecture, health system scale tier, EHR integration complexity, and regional regulatory cluster. CAGRs derived from facility adoption curves weighted by procurement budget availability. Forecast inputs incorporated FDA precertification rollout velocity and telehealth reimbursement code expansion patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-backed pharmacy platforms would shift outcomes. Material shifts in DEA e-prescribing authentication requirements or state-level telehealth prescribing regulations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Internal Communications Software Market
Software & Services
Ecommerce Software and Platform Market
Software & Services
Global Screen and Script Writing Software Market
Software & Services
Global Building Information Modeling (BIM) Software Market
Software & Services
Digital Onboarding Platform Market
Software & Services
Enterprise Capture Software Market
Software & Services
Global Testing Software Market
Software & Services
Sales Intelligence Software Market
Software & Services
E-Invoicing Software Market
Software & Services
Global Headless CMS Software Market
Software & Services
Session Support Software Market
Software & Services
Cloud-Based Dental Practice Management Software Market
Software & Services
Computer Assisted Translation Software Market
Software & Services
Global IVR Software Market
Software & Services
Mainframe Software Market
Software & Services
Global Web Scraper Software Market