
 Software Testing Tools Market | 2026-2036
Software Testing Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Software Testing Tools Market Outlook
Healthcare software validation is pivoting toward automated compliance frameworks as patient data systems face stricter audit requirements. Tricentis leverages model-based test automation to sustain engagement with European pharmaceutical software suppliers. IBM anchors its position through enterprise-grade hybrid deployment architectures that span regulated and non-regulated workloads.
Software testing tools encompass platforms, frameworks, and utilities that execute, manage, and report on code verification processes, typically supporting test script execution rates exceeding thousands of cases per hour across distributed compute environments. These systems primarily assure functional correctness, security posture, and performance thresholds before production release. Test automation solutions command the largest revenue share by product type, while security testing exhibits the fastest structural expansion as supply chain code exploits multiply. Cloud-based deployment is displacing on-premises installations among mid-market buyers, though hybrid configurations retain dominance in banking and defense sectors where data residency constraints persist.
The US FDA mandates software validation for medical device systems under 21 CFR Part 820, directly expanding traceability requirements that testing tools must document. The EU AI Act imposes conformity assessments on high-risk automated decision systems, creating compliance demand for auditable test coverage across European deployments. Stakeholders must weigh whether their tooling investments accommodate emerging algorithmic accountability standards before procurement cycles lock in multi-year platform commitments.
Market Dynamics
DevOps pipeline maturation is compressing release cycles from quarterly to weekly deployments, forcing testing infrastructure to parallelize execution across containerized environments rather than sequential staging servers.
Growth Catalysts
- EU AI Act conformity assessments:High-risk automated decision systems in European healthcare and finance now require auditable test coverage, expanding demand for traceability tooling that documents algorithmic validation chains.
- Container orchestration platforms:Kubernetes-native test execution is enabling engineering teams to spin up ephemeral test environments that mirror production topology without permanent infrastructure overhead.
- Financial services compliance automation:Basel III operational risk frameworks and SEC cybersecurity disclosure rules are mandating continuous control validation, pulling automated testing into regulatory reporting workflows.
Market Restraints
- Specialized talent scarcity:SRE-engineers with dual fluency in test architecture and cloud infrastructure command compensation premiums that inflate tooling total cost of ownership by 40-60% in competitive labor markets.
- Hybrid deployment complexity:Banking and defense sector data residency requirements prevent full cloud migration, forcing vendors to maintain parallel on-premises codebases that fragment R&D investment.
- Open-source substitution pressure:Selenium, JMeter, and pytest ecosystems provide baseline functionality at zero license cost, constraining pricing power for commercial platforms in mid-market accounts.
Strategic Opportunities
- India's PLI scheme for IT hardware:Domestic data center expansion is creating captive demand for localized testing infrastructure that complies with RBI data localization mandates for financial services.
- API-first security validation:OWASP API Security Top 10 compliance is emerging as a discrete purchasing criterion, unbundling from general application security suites into specialized tooling categories.
- Observability-test convergence:Distributed tracing platforms from vendors like Honeycomb and Datadog are integrating assertion capabilities, blurring boundaries between production monitoring and pre-release validation.
Industry Challenges
- Test data provisioning bottlenecks:Synthetic data generation for GDPR-compliant European deployments requires differential privacy expertise that most QA organizations lack in-house, extending environment setup timelines.
- Flaky test remediation debt:Non-deterministic failures in parallelized suites consume 25-35% of engineering capacity at mature DevOps organizations, eroding confidence in automated gates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software Testing Tools Market |
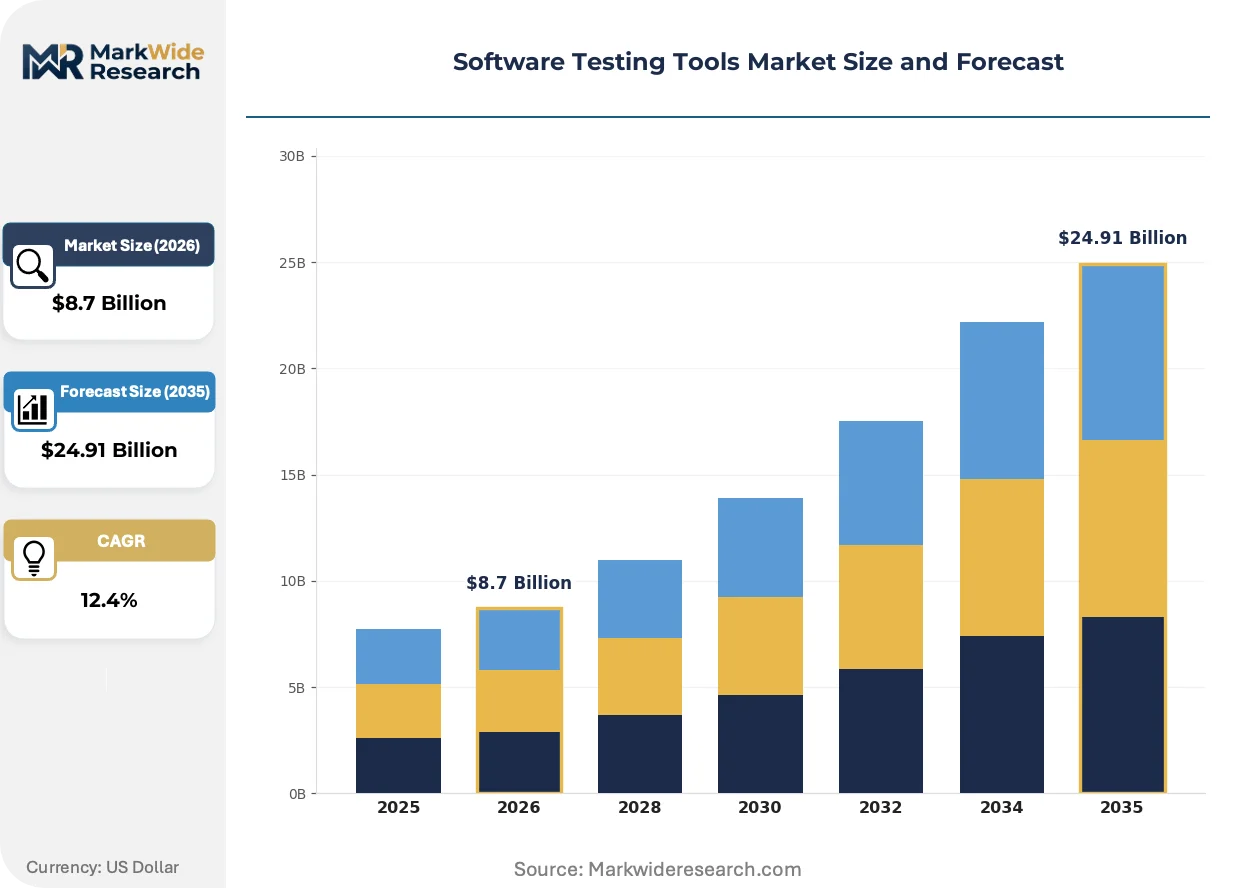
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $24.91 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Automation, Performance Testing, Security Testing, Mobile Testing Deployment: On-Premises, Cloud-Based, Hybrid, Open Source End User: Software Developers, QA Teams, IT Departments, Enterprises Solution: Continuous Testing, Functional Testing, API Testing, Load Testing |
| Companies Covered | Tricentis, IBM, Inflectra, QMetry, Micro Focus, SmartBear, Perforce, Synopsys, Parasoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software Testing Tools Market Strategic Shifts
Model-based test generation is replacing script-heavy automation paradigms, compressing maintenance overhead while expanding coverage depth for complex system interactions.
Generative AI is integrating into test case synthesis workflows, with large language models translating natural language requirements into executable validation scripts. European pharmaceutical software suppliers are piloting these tools to accelerate FDA 21 CFR Part 820 documentation. The structural consequence is a compression of test design labor that previously consumed 30-40% of automation project budgets.
The EU AI Act's risk-based classification system is mandating conformity assessments for high-risk automated decision systems before market deployment. Medical device manufacturers must now demonstrate traceable test coverage across training data, model architecture, and inference behavior. German notified bodies are developing specialized audit protocols for machine learning validation that extend traditional software lifecycle standards.
Platform engineering teams are consolidating testing infrastructure into internal developer platforms that abstract toolchain complexity behind self-service APIs. This procurement pattern displaces point-solution purchasing with bundled capability subscriptions. The shift is most visible in US technology enterprises where platform teams control 60-70% of infrastructure vendor selection.
Software Testing Tools Market Segmentation
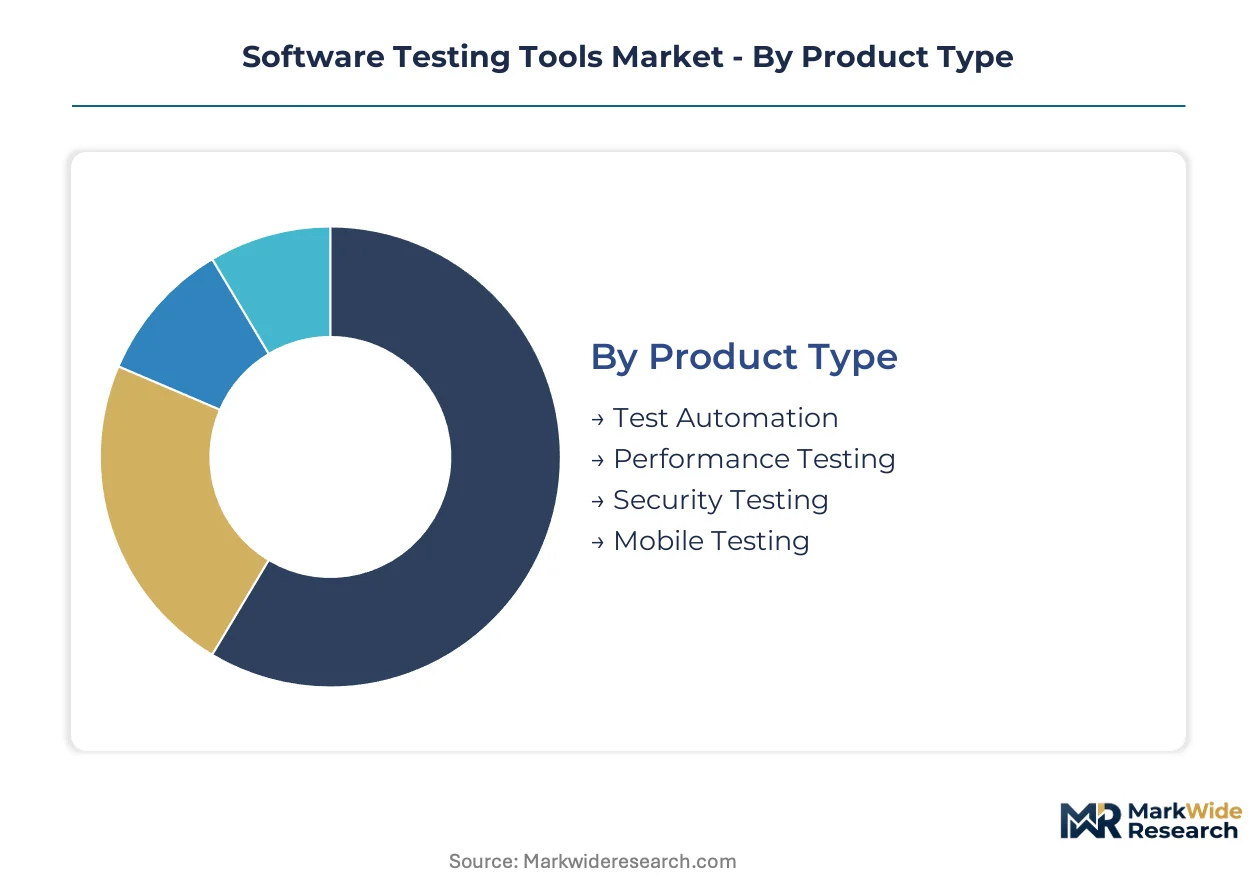
Segmentation in software testing tools reveals divergent procurement patterns between regulated enterprises and agile technology firms. Deployment architecture and compliance requirements create distinct purchasing clusters that vendors must navigate separately.
Product Type:
Test automation commands volume leadership while security testing captures premium pricing expansion.
- Test Automation:Platforms execute thousands of test cases hourly across distributed container environments. Financial services firms in Germany and the United Kingdom are consolidating procurement around model-based frameworks that compress maintenance overhead for regulatory compliance pipelines.
- Security Testing:Solutions validate code integrity against supply chain exploits and API vulnerabilities. Demand concentrates among European pharmaceutical software suppliers facing EU AI Act conformity assessments for high-risk automated decision systems.
- Performance Testing:Tools verify system responsiveness under simulated production load conditions. Kubernetes-native execution enables ephemeral environment provisioning without permanent infrastructure commitment.
- Mobile Testing:Frameworks address device fragmentation across iOS and Android ecosystems. Mid-market buyers favor open-source substitution where baseline functionality suffices.
Mature deployment sits with Test Automation. Newer deployment is concentrated in Security Testing.
Deployment:
Cloud migration accelerates among mid-market buyers while hybrid configurations retain banking sector dominance.
- Cloud-Based:Delivery eliminates infrastructure provisioning delays through SaaS consumption models. India's PLI scheme for IT hardware is creating captive demand for localized testing infrastructure compliant with RBI data localization mandates.
- Hybrid:Architectures span regulated and non-regulated workloads across on-premises and cloud substrates. IBM anchors enterprise positioning through this deployment mode serving medical device manufacturers under FDA 21 CFR Part 820.
- On-Premises:Installations persist where data residency constraints block full cloud migration. Defense sector procurement maintains parallel codebases that fragment vendor R&D investment.
- Open Source:Ecosystems including Selenium and JMeter provide baseline functionality at zero license cost. Mid-market accounts leverage these tools to constrain commercial platform pricing power.
Established procurement favors Hybrid. Cloud-Based adoption is climbing fastest among distributed engineering teams.
End User:
Platform engineering teams are consolidating vendor selection authority previously dispersed across functional silos.
- Enterprises:Organizations operate internal developer platforms that abstract toolchain complexity behind self-service APIs. US technology enterprises concentrate 60-70% of infrastructure vendor selection within platform teams.
- QA Teams:Groups require synthetic data generation capabilities for GDPR-compliant European deployments. Differential privacy expertise scarcity extends environment setup timelines.
- Software Developers:Practitioners integrate testing assertions into CI/CD pipelines through IDE-native tooling. DevOps maturation compresses release cycles from quarterly to weekly deployments.
- IT Departments:Units manage legacy system validation where flaky test remediation consumes 25-35% of engineering capacity at mature organizations.
Procurement authority centralizes with Enterprises. Developer-led adoption is expanding through embedded tooling integrations.
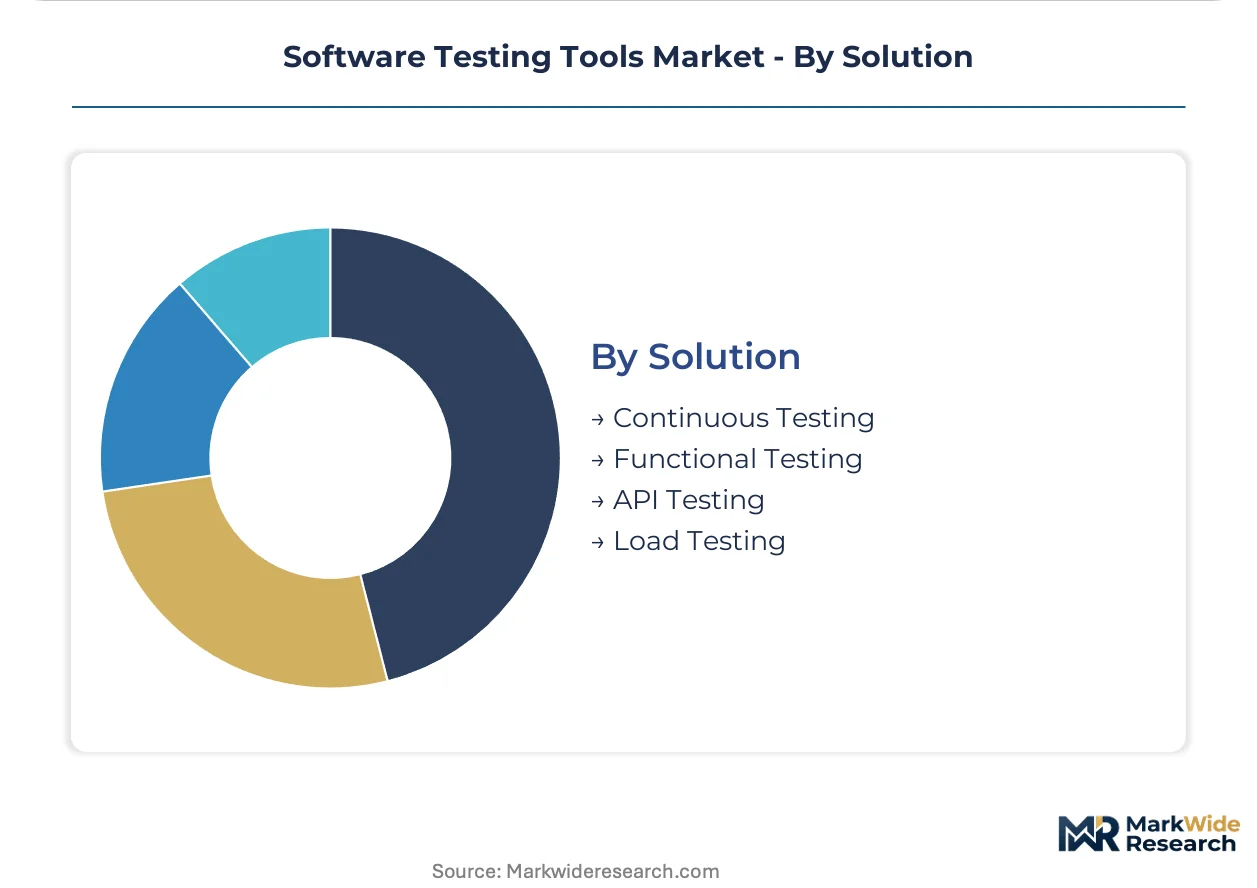
Solution:
Continuous testing integration separates mature DevOps organizations from sequential validation workflows.
- Continuous Testing:Solutions embed validation gates throughout CI/CD pipelines rather than post-development phases. Container orchestration platforms enable parallel execution across ephemeral environments.
- API Testing:Validation addresses OWASP API Security Top 10 compliance as a discrete purchasing criterion. Specialized tooling categories are unbundling from general application security suites.
- Functional Testing:Frameworks verify business logic correctness against requirements specifications. Generative AI integration compresses test design labor that previously consumed 30-40% of automation project budgets.
- Load Testing:Capabilities simulate concurrent user volumes to identify scalability thresholds. Observability-test convergence blurs boundaries between production monitoring and pre-release validation.
Functional Testing represents established deployment. Continuous Testing is gaining share fastest among weekly-release organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Software Technology Parks of India scheme and Special Economic Zones concentrate engineering talent procurement for distributed testing infrastructure. Cloud migration accelerates across Germany, the United Kingdom, and India as DevOps maturation compresses release cycles. Regulatory compliance mandates in healthcare and financial services reshape tooling procurement priorities.
United States
Medical device manufacturers drive demand for FDA 21 CFR Part 820 validation documentation. The FDA mandates software validation for patient data systems, expanding traceability requirements that testing tools must document. Boston and Minneapolis medical technology clusters anchor pharmaceutical software supplier engagement with model-based test automation frameworks.
Germany
Automotive and industrial software suppliers require conformity assessments under the EU AI Act for high-risk automated decision systems. German notified bodies develop specialized audit protocols for machine learning validation extending traditional software lifecycle standards. Munich and Stuttgart engineering hubs concentrate procurement for hybrid deployment architectures spanning regulated workloads.
United Kingdom
Financial services firms expand automated validation pipelines for Basel III operational risk frameworks and SEC cybersecurity disclosure alignment. The Financial Conduct Authority and Prudential Regulation Authority mandate continuous control validation, pulling automated testing into regulatory reporting workflows. London fintech clusters drive Kubernetes-native test execution for ephemeral environment provisioning.
India
The PLI scheme for IT hardware creates captive demand for localized testing infrastructure compliant with RBI data localization mandates. Domestic data center expansion accelerates cloud-based deployment adoption among distributed engineering teams. Bangalore and Hyderabad technology corridors concentrate platform engineering teams consolidating vendor selection authority.
Software Testing Tools Market Competitive Environment
Top-tier vendors anchor enterprise-grade hybrid deployment architectures, while mid-market specialists compete on Kubernetes-native execution and API security validation. The vendor base stratifies across three tiers: consolidated platform providers, open-source ecosystem integrators, and vertical-specific compliance specialists. Strategic archetypes include model-based test automation providers, security-first validation suites, and internal developer platform bundlers. Dominant competitive moves encompass strategic partnerships for synthetic data generation capabilities and portfolio diversification into observability-test convergence.
Within the enterprise platform tier, Tricentis and IBM exemplify divergent architectural approaches to regulated workload validation. Tricentis occupies a position emphasizing model-based frameworks for European pharmaceutical software suppliers facing FDA documentation requirements. IBM anchors hybrid deployment positioning spanning medical device manufacturers and financial services firms with data residency constraints. Among security-focused specialists, Synopsys represents the archetype of supply chain code exploit validation, while SmartBear sits within the API-first security tooling category addressing OWASP compliance as a discrete purchasing criterion.
| Leading Market Players |
|---|
| Tricentis |
| IBM |
| Inflectra |
| QMetry |
| Micro Focus |
| SmartBear |
| Perforce |
| Synopsys |
| Parasoft |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure costs cascade through SaaS pricing tiers as hyperscaler compute rates anchor vendor cost bases and compress margins for mid-market automation platforms competing against open-source substitution.
Pricing Analysis
Short lead-time premiums attach to Kubernetes-native test execution platforms serving financial services firms with compressed release cycles. Pricing stratifies across enterprise-grade hybrid deployments, mid-market SaaS tiers, and open-source baseline tiers. Price differentiation hinges on compliance certification depth and synthetic data generation bundling. Pricing pressure intensifies in the mid-market as Selenium and pytest ecosystems constrain commercial platform pricing power. Developer-led tooling adopters exhibit highest price sensitivity, while regulated medical device manufacturers demonstrate lowest sensitivity due to FDA validation documentation requirements.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler cloud infrastructure concentrated in the United States, Germany, and India for localized data center expansion. Vendor R&D investment draws from proprietary ML model training pipelines, open-source framework contributions, and specialized SRE talent pools. Supply chain risk centers on regulatory restriction as RBI data localization mandates and EU AI Act conformity assessments fragment deployment architectures. Distribution runs through direct enterprise sales, cloud marketplace listings, and platform engineering team procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Model-based test automation is displacing script-heavy paradigms, compressing maintenance overhead while expanding coverage depth for complex system interactions.
For Market Incumbents: Cement hybrid deployment dominance through synthetic data generation partnerships that address GDPR-compliant European provisioning bottlenecks. Deepen vertical integration into observability-test convergence capabilities before distributed tracing platforms from Honeycomb and Datadog erode pre-release validation boundaries. Prioritize certification investment for EU AI Act conformity assessment protocols under development by German notified bodies. For New Entrants and Emerging Players: Kubernetes-native ephemeral environment provisioning offers the most penetrable wedge for mid-market accounts seeking to bypass permanent infrastructure overhead. Target India's PLI scheme beneficiaries building localized testing infrastructure for RBI data localization compliance. Lead with API-first security validation positioning against OWASP API Security Top 10 requirements unbundling from general application security suites. For Investors and Strategic Acquirers: Platform engineering team consolidation of vendor selection authority is the leading indicator that infrastructure procurement is shifting from point-solution purchasing to bundled capability subscriptions. Target acquisition archetypes include vertical-specific compliance specialists with FDA 21 CFR Part 820 documentation expertise and security-first validation suites with supply chain code exploit detection capabilities. Watch for observability-test convergence integration signals as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Platform engineering teams at US technology enterprises now control 60-70% of infrastructure vendor selection authority. |
| Strategic Partnership | Synthetic data generation alliances address differential privacy expertise scarcity extending European environment setup timelines. |
| Acquisition of Specialist Firm | EU AI Act conformity assessment capabilities command premium positioning among German notified body audit protocols. |
| Geographic Expansion | India's PLI scheme for IT hardware creates captive demand for RBI-compliant localized testing infrastructure. |
| Product Launch | Generative AI test case synthesis compresses design labor that previously consumed 30-40% of automation project budgets. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with platform engineering directors, DevOps leads, QA automation architects, and compliance officers at financial services and pharmaceutical firms. FDA 21 CFR Part 820 documentation, EU AI Act conformity assessment guidelines, and RBI data localization circulars provided regulatory validation. SEC cybersecurity disclosure filings and hyperscaler capex disclosures supplied investment trajectory signals. Bottom-up deployment model sizing triangulated against top-down enterprise IT spend estimates.
Granularity-level modeling segmented the market by product type, deployment architecture, end-user organization size, and regional regulatory cluster across the analysis window. CAGRs derived from trend extrapolation of DevOps pipeline maturation rates, cloud migration trajectories, and compliance mandate expansion timelines. Kubernetes adoption curves and generative AI integration velocities served as technology-transition forecast inputs.
Several conditions sit outside the modeled scope, including geopolitical disruption to hyperscaler infrastructure access, fundamental breakthroughs in formal verification methods, and regulatory reversal of algorithmic accountability requirements. Forecasts reflect documented assumptions about SRE talent availability and open-source ecosystem maintenance continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Accounts Receivable Software Market
Software & Services
Gym Motion Tracking Software Market
Software & Services
Germany HR Payroll Software Market
Software & Services
Test Management Software Market
Software & Services
Artwork Management Software Market
Software & Services
Language Translation Software Market
Software & Services
Europe Feedback Management Software Market
Software & Services
Resonator Design Software Market
Software & Services
Advanced Process Control Software Market
Software & Services
Gym Management Software Market
Software & Services
Software Market
Software & Services
ID Photo Software Market
Software & Services
Cloud Testing and ASQ Software Market
Software & Services
Global Cloud Based Collaboration Software Market
Software & Services
Retail Core Banking Solution Market
Software & Services
Mindfulness Meditation Application Market