
 Global Test Data Management Market | 2026-2036
Global Test Data Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Test Data Management Market Foresight
Fragmentation across new digital-native buyers is repositioning procurement patterns in test data management. Microsoft leverages its Azure ecosystem to anchor enterprise deployments across hybrid environments. Informatica competes through specialized data masking and compliance modules for regulated industries. Delphix sustains technology leadership in dynamic data platform architectures for DevOps pipelines.
Test data management comprises methodologies and software platforms that provision, secure, and govern datasets used in software validation workflows, typically incorporating masking algorithms, subsetting engines, and synthetic generation protocols to replicate production schemas without exposing sensitive records. The primary commercial purpose centers on accelerating release cycles while maintaining regulatory adherence across quality assurance and security testing phases. Cloud deployment configurations now lead solution uptake as banking and telecommunications operators migrate validation workloads off-premises. Data masking and synthetic data generation command the strongest margin pools within solution offerings, reflecting premium pricing for privacy-preserving capabilities under GDPR and sector-specific mandates.
The EU AI Act, GDPR, and HIPAA constrain how personally identifiable information enters test environments, directly elevating demand for automated compliance and audit-trail functionalities. The US Federal Reserve's stress-testing protocols and the SEC's cybersecurity disclosure rules further tighten data lineage requirements for financial services test infrastructure. Stakeholders must monitor evolving algorithmic accountability standards across multiple jurisdictions to anticipate compliance-driven procurement cycles.
Market Dynamics
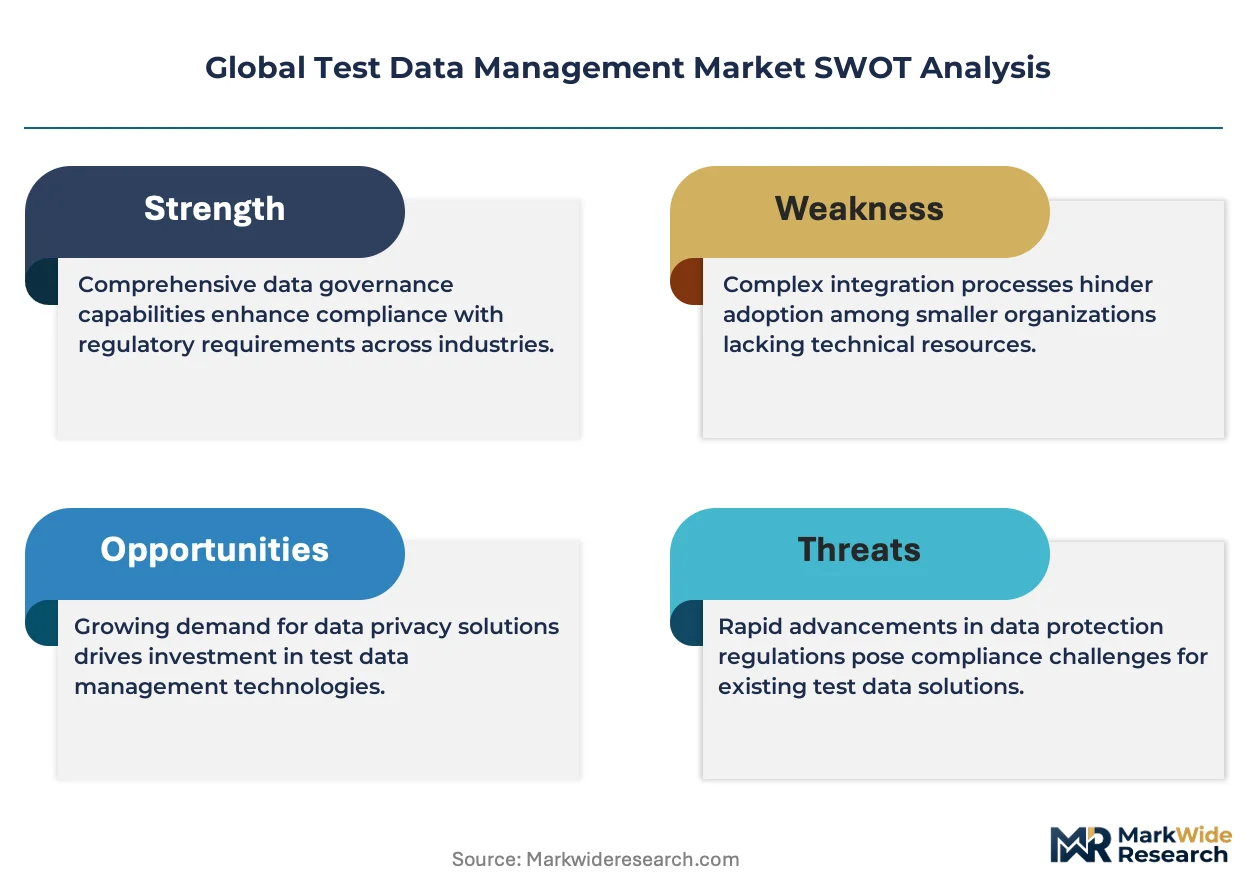
Cloud migration in banking and telecommunications is compressing on-premise infrastructure cycles while elevating demand for synthetic data pipelines that satisfy GDPR and HIPAA audit requirements without exposing production records.
Growth Catalysts
- GDPR Article 32 mandates:EU financial institutions must implement pseudonymization for test datasets, accelerating automated masking procurement.
- Federal Reserve stress-testing protocols:US banks require granular data lineage for CCAR submissions, expanding validation infrastructure budgets.
- DevOps pipeline automation:CI/CD acceleration in telecommunications demands sub-second data provisioning for parallel test environments.
Market Restraints
- Compute cost volatility:Synthetic generation workloads strain GPU and cloud storage budgets, particularly for petabyte-scale relational schemas.
- EU AI Act compliance friction:Algorithmic testing documentation requirements extend procurement cycles by 6-12 months for high-risk system deployments.
- Legacy mainframe integration:COBOL-based core banking systems resist API-native data virtualization, trapping institutions in hybrid complexity.
Strategic Opportunities
- India BFSI digitization:RBI's data localization norms create captive demand for domestic-hosted test data platforms.
- Edge computing convergence:5G network slicing in telecommunications requires distributed test data nodes at cell tower proximity.
- Subscription pricing models:Consumption-based SaaS contracts displace perpetual licenses among mid-market fintech entrants.
Industry Challenges
- Data engineering talent scarcity:Masking algorithm development requires rare combinations of cryptography and domain schema expertise.
- Cross-border data transfer restrictions:Schrems II rulings complicate multi-jurisdictional test environment synchronization for multinational banks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Test Data Management Market |
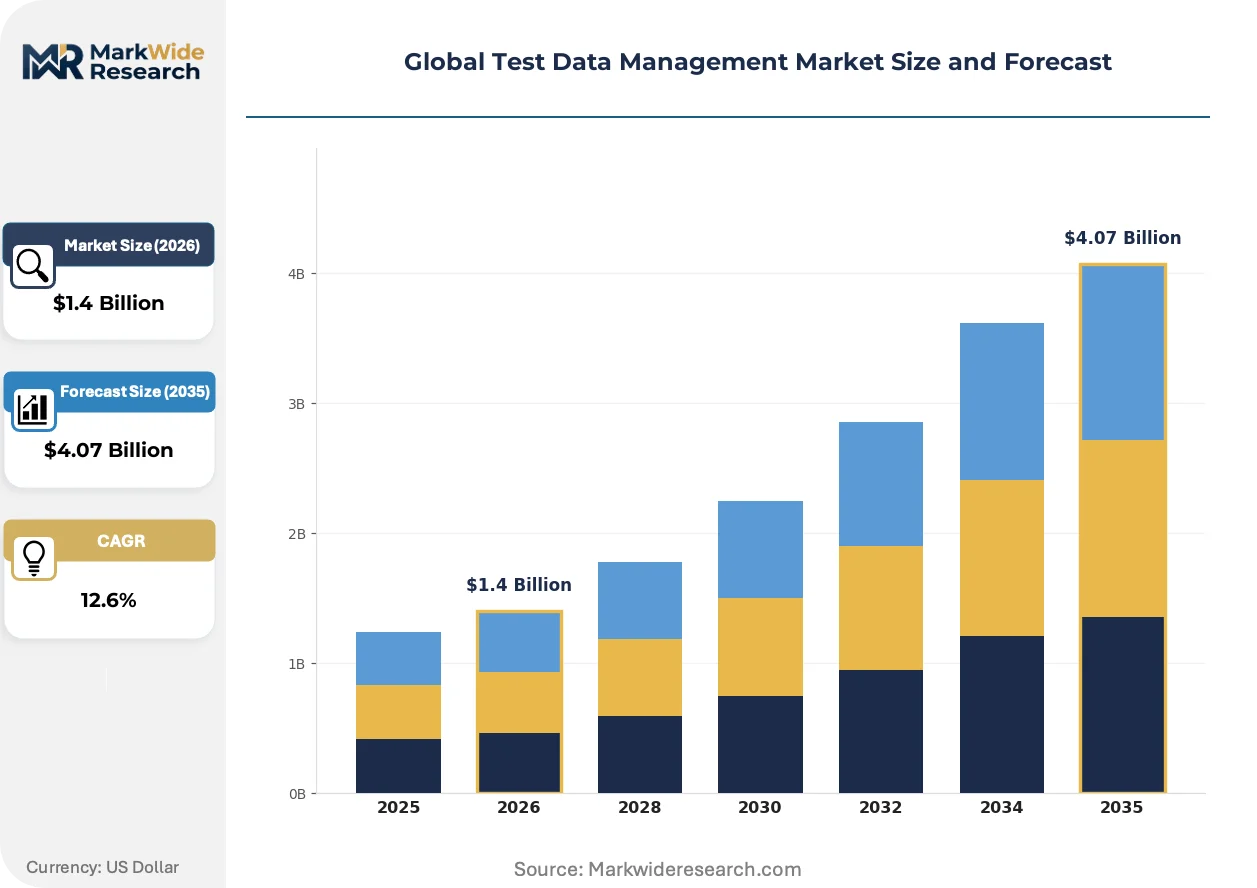
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.07 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud, Hybrid, Managed Services Solution Offering: Data Masking, Synthetic Data Generation, Data Subsetting, Data Auditing, Data Compliance Use Case: Software Development, Quality Assurance, Performance Testing, Security Testing, Regulatory Compliance End User Industry: Banking, Telecommunications, Insurance, Information Technology, Manufacturing |
| Companies Covered | Microsoft, Google Cloud, Informatica, Collibra, SAP, IBM, Amazon Web Services, Delphix, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Test Data Management Market Shifts & Advancements
Generative AI is compressing synthetic data fidelity gaps while regulatory fragmentation forces platform architectures toward modular compliance engines. These forces are reshaping vendor R&D priorities and buyer evaluation criteria simultaneously.
Neural synthetic data generation is unifying statistical fidelity with differential privacy guarantees. Large US banks and German automotive suppliers are deploying these engines for fraud detection model training. This convergence is collapsing the traditional separation between data masking and synthetic creation toolchains.
EU AI Act risk-classification tiers are mandating algorithmic testing documentation for high-risk financial and healthcare applications. Deployment approval now requires reproducible test datasets with full audit trails. French and Dutch regulators are conducting the first wave of compliance inspections, forcing vendors to embed governance modules natively.
Enterprise procurement teams are consolidating vendor relationships around integrated data platform suites. Standalone test data management point solutions face displacement by broader data governance contracts. This concentration is most visible among Fortune 500 financial services institutions in the United States and United Kingdom.
Global Test Data Management Market Segmentation
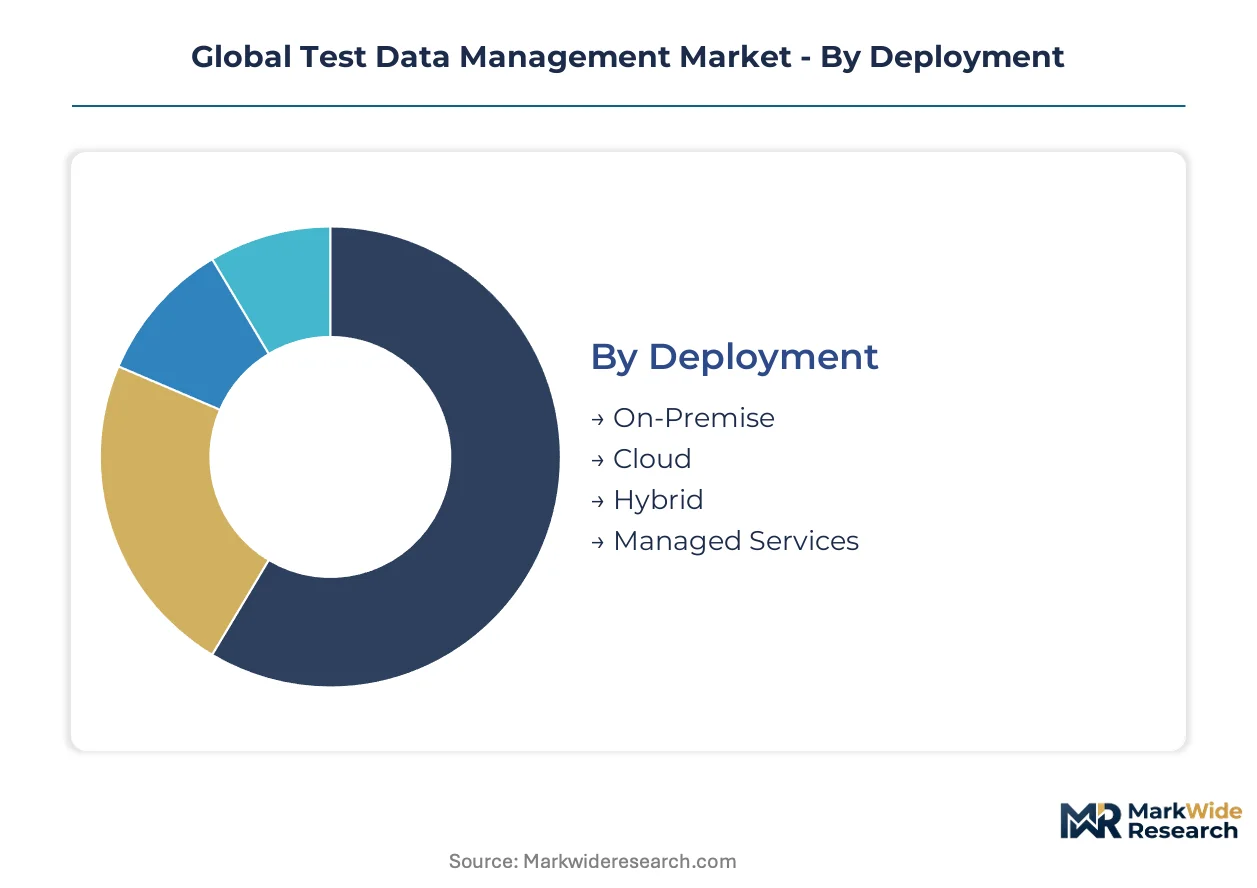
Test data management procurement diverges sharply across deployment architectures and regulatory exposure levels. Buyers evaluate solutions against data residency mandates, DevOps velocity requirements, and sector-specific compliance burdens.
Deployment:
Cloud migration velocity and data sovereignty requirements drive deployment selection across banking and telecommunications procurement teams.
- Cloud:Multi-tenant SaaS architectures dominate new procurement in North American banking. AWS, Azure, and Google Cloud host validation workloads for institutions seeking to exit capital-intensive data center commitments.
- Hybrid:Split configurations retain sensitive core banking schemas on-premise while pushing non-critical test environments to public infrastructure. German automotive suppliers and Japanese insurers favor this model for Schrems II compliance.
- On-Premise:Air-gapped installations persist where national regulators mandate physical data localization—Brazilian BFSI and Saudi healthcare systems require domestic hardware custody.
- Managed Services:Third-party operated platforms absorb operational complexity for mid-market fintechs lacking internal data engineering benches.
Cloud leads on scale; hybrid leads on momentum.
Solution Offering:
Privacy-preserving capabilities command pricing premiums as GDPR Article 32 and HIPAA Security Rule enforcement intensifies.
- Data Masking:Algorithmic substitution and shuffling techniques protect PII in non-production environments. US banks deploy these tools for Federal Reserve CCAR submission datasets.
- Synthetic Data Generation:Neural engines construct statistically faithful artificial records without production exposure. French and Dutch regulators now require reproducible synthetic datasets for high-risk AI system approvals under EU AI Act tiers.
- Data Subsetting:Relational integrity-preserving extraction reduces test environment footprint for CI/CD pipelines.
- Data Auditing:Immutable lineage tracking satisfies SEC cybersecurity disclosure and MAS Technology Risk Management requirements.
- Data Compliance:Automated policy enforcement modules embed regulatory logic for multi-jurisdictional deployments.
Synthetic data generation expands most quickly; data masking retains the largest installed base.
Use Case:
Release cycle compression and security validation intensity determine functional prioritization in enterprise procurement.
- Software Development:Agile and DevOps methodologies demand rapid provisioning of consistent test datasets across distributed engineering teams.
- Quality Assurance:Functional validation requires production-fidelity schemas with referential integrity preserved.
- Performance Testing:Volume-scaled datasets simulate production load conditions for telecommunications billing systems.
- Security Testing:Penetration testing and vulnerability assessment workflows utilize masked but structurally accurate data.
- Regulatory Compliance:Stress-testing and algorithmic accountability documentation mandates specialized audit-trail capabilities in EU and US financial services.
Quality assurance dominates current spending; regulatory compliance shows the steepest expansion trajectory.
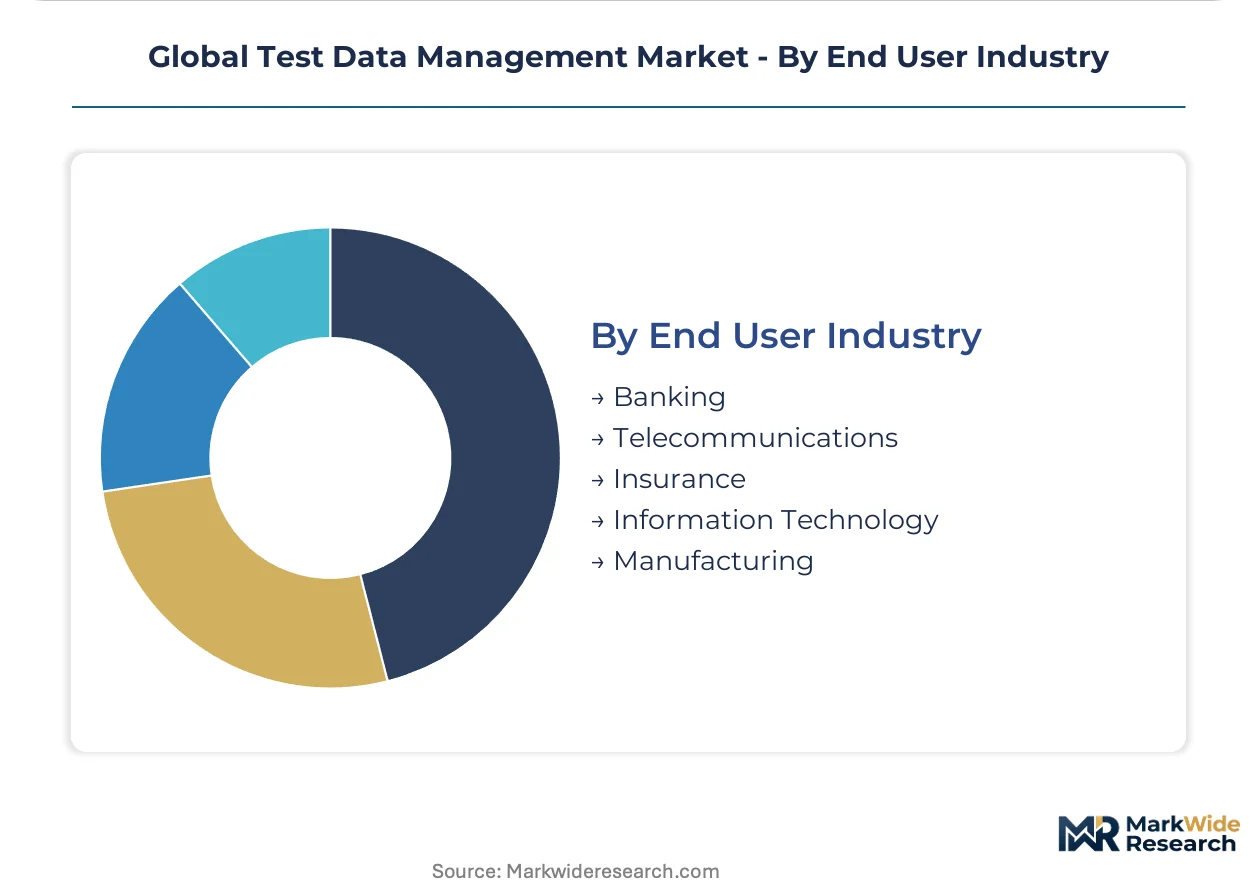
End User Industry:
Sector-specific data governance regimes and digital transformation maturity shape solution customization requirements.
- Banking:Core banking modernization and open banking API testing drive demand across Tier 1 institutions in the United States, United Kingdom, and Singapore.
- Telecommunications:5G network slicing and edge computing architectures require distributed test data nodes at cell tower proximity.
- Insurance:Legacy policy administration system replacement projects in Germany and Japan utilize synthetic data for migration validation.
- Information Technology:SaaS vendors and cloud-native enterprises embed test data management into continuous delivery pipelines.
- Manufacturing:Industrial IoT and predictive maintenance model development in German automotive and South Korean electronics sectors leverage synthetic operational data.
Banking anchors revenue concentration; telecommunications gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States financial institutions outpace German automotive suppliers in synthetic data procurement velocity, while Indian banks accelerate domestic platform investments under localization mandates. Cloud migration patterns diverge sharply across these jurisdictions.
United States
Federal Reserve CCAR stress-testing protocols and SEC cybersecurity disclosure rules drive validation infrastructure spending. Tier 1 banks in New York and Chicago deploy automated data lineage systems for regulatory submissions. San Francisco Bay Area cloud-native enterprises integrate test data management into CI/CD pipelines for fintech applications.
Germany
Schrems II rulings and BfDI enforcement compel hybrid deployment architectures for core banking schemas. Automotive suppliers in Stuttgart and Munich utilize synthetic operational data for predictive maintenance model development. Frankfurt financial institutions prioritize GDPR Article 32 pseudonymization for algorithmic testing environments.
India
RBI data localization norms and BFSI digitization programs create captive demand for domestic-hosted platforms. Mumbai and Bangalore technology hubs witness rapid adoption of consumption-based SaaS contracts among mid-market fintech entrants. Telangana's Hyderabad cluster attracts test data platform engineering centers serving regional banking clients.
Singapore
MAS Technology Risk Management requirements and open banking API testing mandates elevate data auditing procurement. Financial institutions in the central business district deploy sub-second data provisioning for distributed engineering teams. The city-state's regulatory sandbox framework accelerates validation workload migration to multi-tenant cloud architectures.
United Kingdom
FCA operational resilience rules and post-Brexit data governance adjustments reshape compliance-driven procurement. London's Square Mile institutions consolidate vendor relationships around integrated data platform suites. Edinburgh and Manchester regional banking centers invest in legacy policy administration system replacement projects utilizing synthetic data for migration validation.
Global Test Data Management Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment architecture and compliance module specialization. The vendor base clusters around three strategic archetypes: hyperscale cloud providers anchoring enterprise hybrid environments, specialized data governance platforms competing through masking algorithm sophistication, and dynamic data platform architects optimizing DevOps pipeline velocity. Dominant competitive moves include portfolio diversification into adjacent data governance segments and strategic partnerships with telecommunications operators for 5G edge computing deployments.
Among hyperscale cloud providers, Microsoft and Google Cloud occupy positions anchoring multi-tenant SaaS architectures for North American banking clients. Within the specialized tier, Informatica exemplifies focused competition through compliance module development for regulated industries. Delphix sits within the dynamic data platform archetype, serving DevOps pipeline requirements for telecommunications and financial services velocity demands. These three company types collectively represent the competitive structure shaping procurement evaluation criteria.
| Leading Market Players |
|---|
| Microsoft |
| Google Cloud |
| Informatica |
| Collibra |
| SAP |
| IBM |
| Amazon Web Services |
| Delphix |
| Oracle |
| Others |
Supply & Pricing Matrix
Captive cloud infrastructure investments by hyperscalers in the United States anchor both supply positioning and pricing power across test data management deployments. Microsoft Azure and AWS data center commitments in Virginia and Oregon create fixed-cost leverage that shapes SaaS tiering structures for banking and telecommunications buyers.
Pricing Analysis
Capacity additions in Ireland and Singapore are reshaping price floors for European and Asia-Pacific synthetic data generation workloads. Subscription pricing stratifies across enterprise, professional, and developer tiers, with GDPR Article 32 certification and FedRAMP authorization driving premium differentiation. Cost compression in mid-market SaaS tiers is intensifying because GPU compute spot pricing volatility strains synthetic generation margins. Developer-tier buyers show highest price sensitivity; Tier 1 banks demonstrate lowest.
Supply Chain Analysis
Cross-border data transfer costs and submarine cable latency dictate supplier geographic placement for distributed test data nodes. Engineering talent concentrates in the United States, India, and Germany. Cloud compute instances, encryption hardware, and compliance audit services constitute critical inputs. Single-source vulnerability rests on concentrated GPU foundry capacity in Taiwan. Distribution runs through direct enterprise sales teams and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Test data management procurement functions as a geographic-arbitrage play between EU regulatory stringency and US cloud infrastructure scale. GDPR Article 32 enforcement costs in Frankfurt exceed equivalent compliance spend in Singapore by meaningful margins.
For Market Incumbents: Lock in long-term capacity reservations at Irish and Singaporean data centers before 2025 cloud lease renewals. Consolidate masking algorithm IP through targeted acquisition of differential privacy specialists. The EU AI Act documentation requirements threaten margin erosion for non-compliant product lines. Vertical integration into synthetic data generation model training secures cost control.
For New Entrants and Emerging Players: RBI data localization norms in India open a window for domestic-hosted platforms serving Mumbai and Bangalore fintech clusters. Target mid-market insurance carriers in Japan and Germany replacing legacy policy administration systems. Lead with consumption-based SaaS contracts displacing perpetual licenses. Schrems II compliance friction creates procurement delay windows for agile entrants.
For Investors and Strategic Acquirers: Roll-up economics work for specialized masking algorithm shops because enterprise procurement teams are consolidating vendor relationships around integrated data platform suites. Five-to-ten year viability hinges on neural synthetic data generation capability maturation. Acquisition focus: differential privacy engineering teams with automotive or healthcare sector schemas. Watch for EU AI Act high-risk system inspection waves as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure ecosystem anchoring hybrid deployments for Federal Reserve CCAR submissions. |
| Compliance Module Development | GDPR Article 32 pseudonymization engines for French and Dutch regulator inspections. |
| Strategic Partnership | Telecommunications operators deploying 5G edge computing test data nodes at cell tower proximity. |
| Acquisition of Specialist Firm | Differential privacy engineering teams with automotive predictive maintenance schema expertise. |
| Geographic Expansion | Domestic-hosted platforms in Hyderabad serving RBI data localization mandates. |
Research Methodology
Bottom-up banking and telecommunications deployment modeling reconciled against top-down cloud infrastructure capacity tracking forms the analytical core. Primary interviews with CTOs, IT procurement officers, platform engineers, and compliance audit specialists informed demand-side validation. Secondary sources include SEC cybersecurity disclosure filings, EBA stress-testing documentation, RBI circulars on data localization, and hyperscaler capex expenditure reports. Cross-referencing bottom-up contract values against top-down vendor revenue disclosures ensures triangulation integrity.
Historical trendline analysis of synthetic data generation adoption curves and masking algorithm procurement cycles established baseline growth parameters. Segmentation dimensions span deployment architecture, solution offering, use case, and end-user industry vertical. CAGR derivation incorporates regulatory mandate enforcement timelines, DevOps pipeline automation rates, and cloud migration velocity across the analysis window. Industry-specific inputs include Federal Reserve CCAR submission schedules and EU AI Act risk-classification tier implementation phases.
Revisions become necessary when GDPR enforcement intensity shifts, Schrems II rulings expand, or GPU supply constraints disrupt synthetic generation economics. Forecasts reflect documented assumptions about regulatory compliance cost trajectories and cloud infrastructure pricing stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
Global Membership Management Software Market
Software & Services
Home Fitness App Market
Software & Services
Global Quantum Computing Software Market
Software & Services
Quality and Lifecycle Management Software Market
Software & Services
Professional Service Automation Market
Software & Services
Architectural Rendering Software Market
Software & Services
Global Affiliate Software Market
Software & Services
Kennel Management Software Market
Software & Services
Commercial Drone Software Market
Software & Services
Global OKR Software Market
Software & Services
Global SEO Software Market
Software & Services
Enterprise Data Observability Software Market
Software & Services
Global Auction Software Market
Software & Services
Telecom IT Services Market
Software & Services
Logistics Services Software Market