
 Global Localization Software Market | 2026-2036
Global Localization Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Localization Software Market Foresight
Neural machine translation is tilting the technology stack toward adaptive, context-aware localization pipelines. Lilt leverages human-in-the-loop AI to sustain translation quality at enterprise scale. RWS Group anchors its competitive position through deep specialization in life sciences regulatory content. Smartling competes by offering cloud-native workflow automation that reduces time-to-market for digital product rollouts.
Localization software encompasses tools that adapt digital content, user interfaces, and documentation across languages, currencies, and cultural conventions using translation memory, terminology databases, and automated quality assurance protocols. The primary commercial purpose is enabling organizations to operate software products in multiple regional markets without rebuilding core codebases. Cloud-based deployment leads the market as enterprises abandon on-premises infrastructure for elastic, API-driven translation workflows. Machine translation integration represents the fastest-growing solution offering as vendors embed large language models directly into content management systems. Gaming studios and mobile application developers form the most concentrated application segment, driven by simultaneous worldwide release schedules and in-game monetization localization.
The EU AI Act, GDPR, and ISO 17100 standards collectively shape product design by mandating transparency in automated translation systems and data residency controls for cross-border content processing. The FDA and EMA impose stringent multilingual labeling requirements on software-as-medical-device products, creating specialized demand for validated localization workflows. Stakeholders must monitor how divergent AI disclosure rules across jurisdictions fragment compliance architectures and inflate vendor certification costs.
Market Dynamics
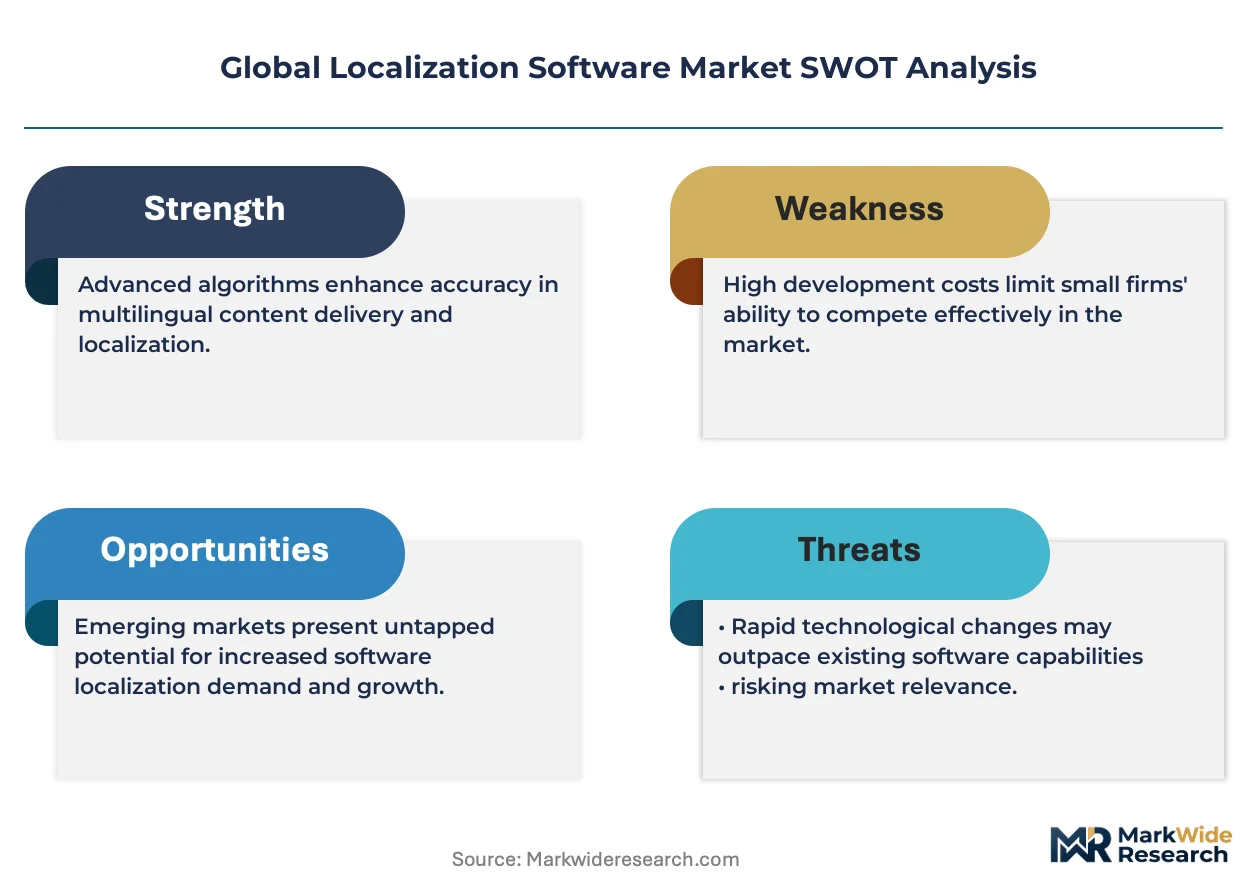
Neural machine translation architectures are compressing translation turnaround cycles from weeks to hours, forcing legacy localization vendors to rebuild service models around real-time API delivery rather than project-based workflows.
Growth Catalysts
- EU AI Act transparency mandates:The regulation's documentation requirements for automated decision systems are accelerating vendor investment in explainable translation pipelines. Compliance spending is creating pull for certified localization platforms.
- Gaming sector simultaneous release schedules:Studios in Japan and South Korea now require 40+ language variants at product launch. This operational reality is expanding recurring localization budgets.
- Automotive software export requirements:German OEMs need ISO-certified multilingual HMI interfaces for vehicles sold across 30+ markets. Regulatory labeling complexity is embedding localization deeper into product development cycles.
Market Restraints
- Compute cost volatility:Large language model inference expenses fluctuate with GPU availability and energy pricing. Smaller vendors face margin compression when cloud compute rates spike.
- Data residency fragmentation:GDPR, China's PIPL, and Russia's data localization laws force redundant infrastructure deployment. Cross-border content processing architectures are becoming prohibitively expensive to maintain.
- Human-in-the-loop dependency:High-stakes content in life sciences and legal sectors still requires certified linguist review. Automation ceilings limit scalability in premium pricing tiers.
Strategic Opportunities
- Medical device software localization:FDA and EMA multilingual labeling requirements for software-as-medical-device products are expanding. Validated translation workflows command 3-5x standard pricing.
- Voice and multimodal content:Dubbing and subtitling for streaming platforms converges with game audio localization. Synthetic voice technology is opening new service categories.
- India's PLI scheme for software exports:Government incentives for IT services are building localization capability clusters in Bangalore and Hyderabad. Cost arbitrage opportunities are emerging for European and North American buyers.
Industry Challenges
- Prompt engineering talent scarcity:Localization engineers who can optimize LLM outputs for domain-specific terminology are in short supply. Compensation inflation is hitting mid-tier vendors.
- Legacy TMS integration friction:Enterprises with decade-old translation management systems face multi-year migration timelines. API compatibility gaps delay cloud-native deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Localization Software Market |
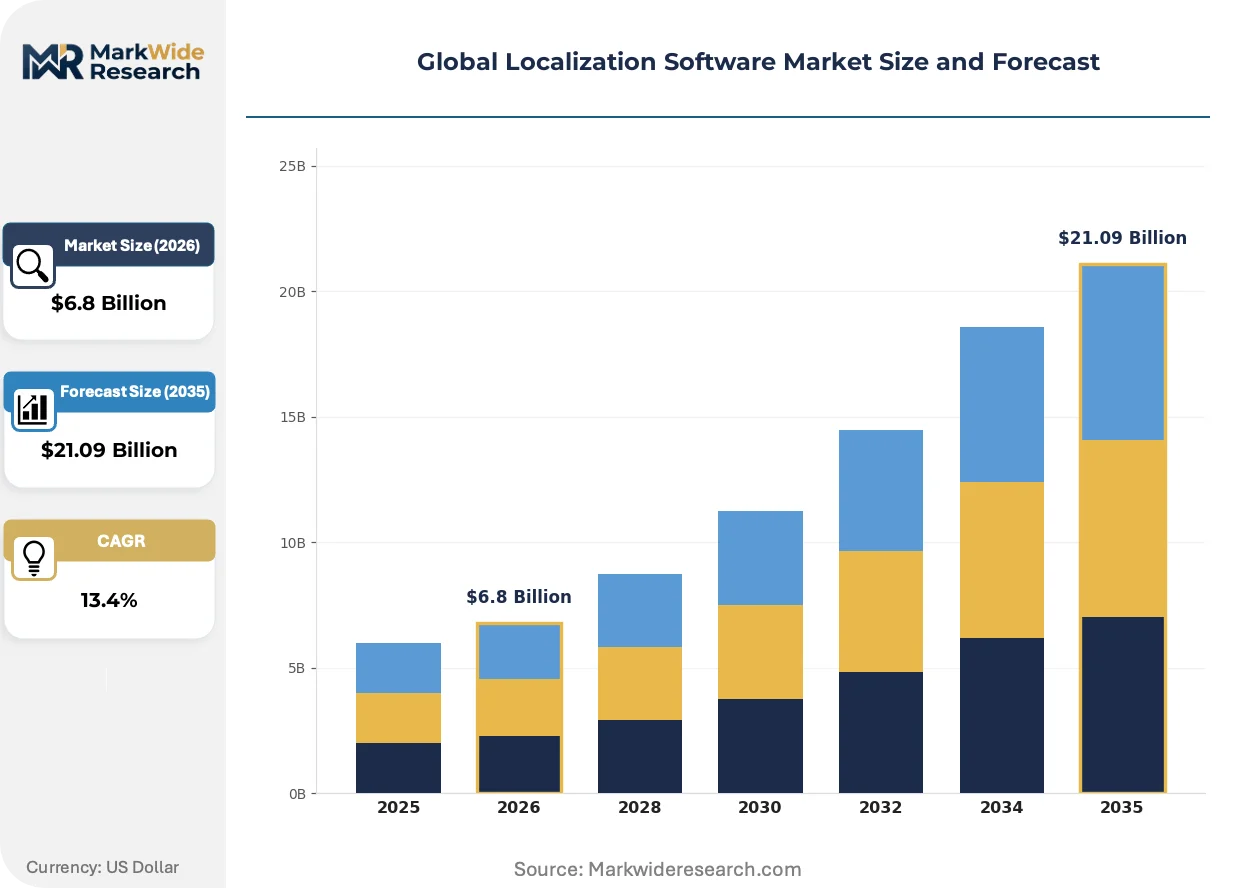
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.09 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
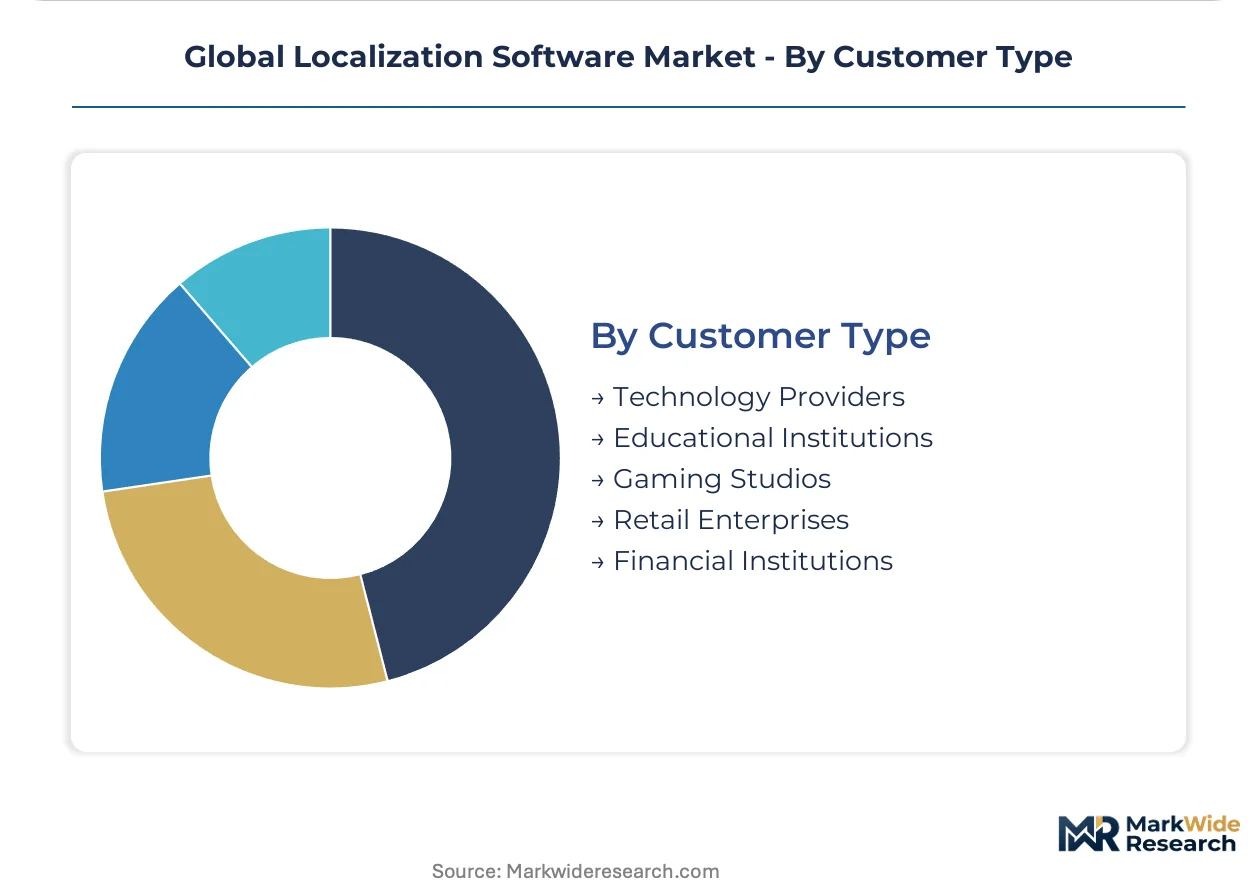
| Segmentation | Deployment: Cloud-based, On-premises, Hybrid, Software as a Service, Platform as a Service Solution Offering: Translation Management Systems, Content Localization, Workflow Automation, Quality Assurance, Machine Translation Integration Application: Enterprise Software, E-learning Platforms, Video Games, E-commerce Websites, Mobile Applications Customer Type: Technology Providers, Educational Institutions, Gaming Studios, Retail Enterprises, Financial Institutions |
| Companies Covered | Lilt, RWS Group, Smartling, Lokalise, Welocalize, Lionbridge, TransPerfect, Crowdin, BLEND, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Localization Software Market Shifts & Advancements
Adaptive localization pipelines are replacing static translation memory architectures. Vendors now compete on context preservation across multimodal content rather than word-rate efficiency alone.
Large language model fine-tuning for domain-specific terminology is rendering obsolete the rule-based post-editing workflows that dominated enterprise localization through the 2010s. Pharmaceutical and financial services buyers are deploying these systems for regulatory submission documents. The shift is compressing revision cycles from five rounds to two while raising quality consistency metrics.
The EU AI Act's algorithmic transparency requirements are mandating audit trails for machine translation decisions in high-risk applications. Vendors must now document training data provenance and model versioning for clients in medical and legal sectors. German automotive software exporters are requiring ISO 17100-certified human oversight layers to satisfy both the Act and their own liability frameworks.
Subscription-based localization operations are displacing per-project procurement in gaming and SaaS verticals. Buyers in South Korea and the United States are consolidating vendor relationships into annual capacity contracts with guaranteed throughput tiers. This model shift favors platforms with elastic cloud infrastructure over traditional agency networks with fixed linguist benches.
Global Localization Software Market Segmentation
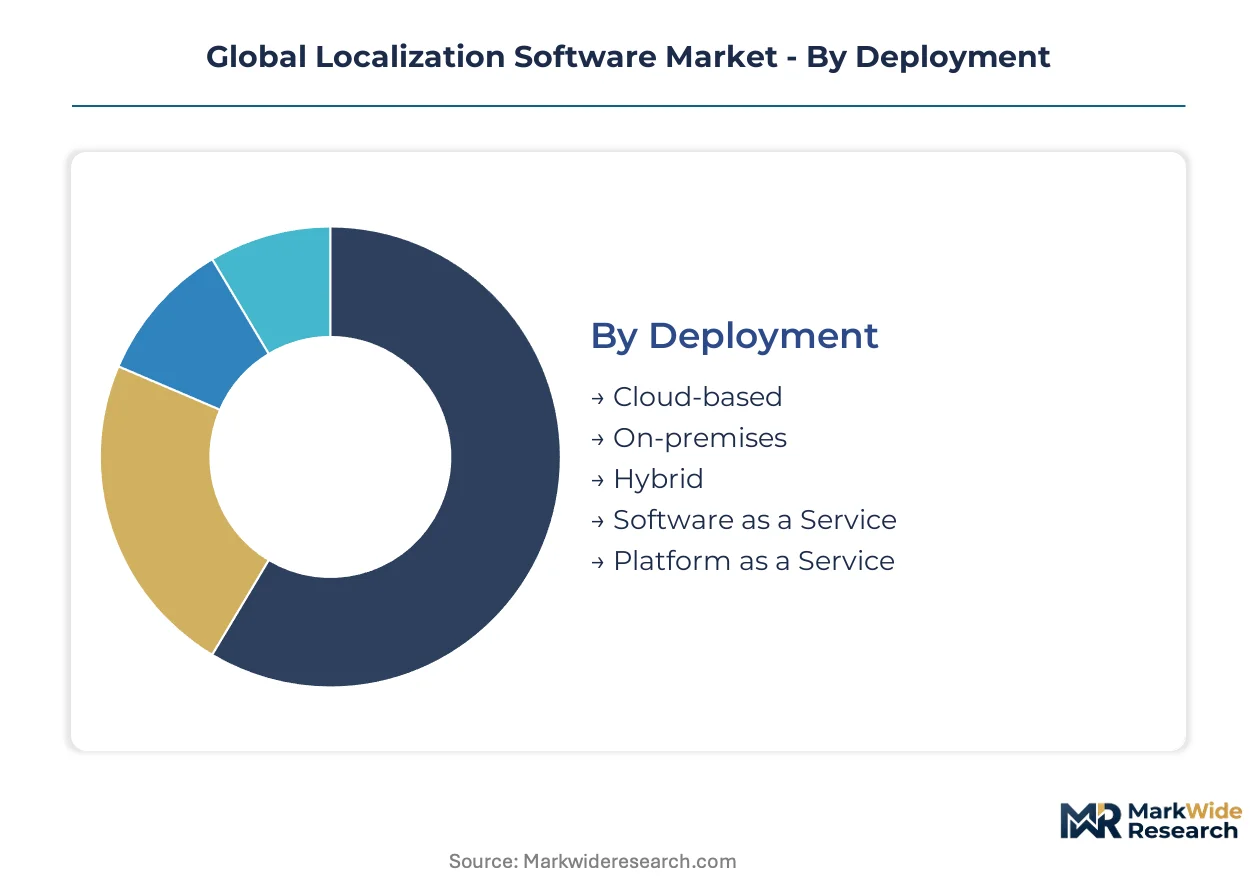
Localization software buyers prioritize different capabilities based on operational scale, content velocity, and regulatory exposure. Deployment architecture and solution composition determine total cost of ownership and integration complexity. Application context shapes whether buyers value speed, quality certification, or multimodal output.
Deployment:
Cloud-native architectures dominate where translation volumes fluctuate seasonally and API connectivity matters.
- Cloud-based:Elastic compute resources support burst capacity for simultaneous game launches and quarterly software releases. Gaming studios in South Korea and SaaS vendors in California favor this model for its elimination of capital expenditure on server infrastructure.
- On-premises:Air-gapped installations satisfy defense contractors and pharmaceutical manufacturers with data sovereignty requirements. German automotive software exporters deploy these behind firewall perimeters to satisfy ISO 27001 and GDPR Article 44 cross-border transfer constraints.
- Hybrid:Sensitive pre-release content processes locally while post-launch updates route through cloud APIs. Japanese console manufacturers use this split to protect intellectual property during development phases.
- Software as a Service:Subscription pricing aligns localization spend with recurring revenue streams. Mid-market e-learning platforms in India prefer predictable monthly costs over per-project procurement.
- Platform as a Service:Developer-centric toolchains embed translation into CI/CD pipelines. Fintech startups in Singapore leverage these APIs for real-time multilingual interface generation.
Established volume favors cloud-based deployments; emerging adoption favors platform-as-a-service configurations.
Solution Offering:
Technology stack composition determines whether buyers build in-house capabilities or outsource to managed service layers.
- Translation Management Systems:Centralized repositories for translation memory, terminology databases, and vendor coordination. Enterprise software vendors in Germany rely on these for ISO 17100-certified workflow documentation required by the EU AI Act.
- Content Localization:Adaptation of multimedia assets, currencies, date formats, and cultural references beyond literal translation. E-commerce platforms targeting Brazil and Saudi Arabia require these capabilities for conversion optimization.
- Workflow Automation:Rules-based routing of content through machine translation, human review, and quality gates. High-velocity mobile application developers in the United States deploy these to compress release cycles.
- Quality Assurance:Automated consistency checking, terminology validation, and compliance verification. Medical device software exporters to the FDA and EMA jurisdictions treat these as non-negotiable for regulatory submission.
- Machine Translation Integration:Large language model APIs embedded directly into content management systems. Video game studios generating 40+ language variants for day-one releases represent the steepest expansion trajectory.
Quality assurance commands premium pricing in regulated verticals; machine translation integration is climbing the fastest in gaming and digital media.
Application:
End-use context dictates whether buyers optimize for throughput, precision, or creative fidelity.
- Enterprise Software:User interface string management and documentation localization for multinational rollouts. SAP and Oracle ecosystem partners in Germany require these solutions for maintenance of multilingual ERP deployments across 30+ markets.
- E-learning Platforms:Course content adaptation with cultural pedagogy adjustments. Educational technology providers in India serving government skill development programs need scalable subtitle and voiceover pipelines.
- Video Games:Simultaneous multilingual releases with voice acting, lip-sync dubbing, and cultural content modification. Japanese and South Korean studios expanding into European and North American markets drive concentrated demand here.
- E-commerce Websites:Product catalog translation with SEO optimization and payment localization. Retail enterprises in the United States entering Latin American markets prioritize these capabilities.
- Mobile Applications:Continuous deployment of incremental updates across app store territories. Social media platforms with daily content cycles require automated string extraction and push localization.
Video games concentrate the highest per-project localization spend; mobile applications generate the most transaction volume through subscription-based delivery models.
Customer Type:
Procurement sophistication varies sharply between technology-native buyers and traditional enterprises digitizing legacy operations.
- Technology Providers:SaaS and infrastructure vendors localizing their own product interfaces and documentation. These buyers demand API-first architectures and granular usage-based pricing.
- Educational Institutions:Universities and online course platforms adapting curricula for international student cohorts. Budget constraints favor open-source tooling with community support over enterprise licenses.
- Gaming Studios:Developers and publishers managing simultaneous worldwide releases. These customers consolidate vendor relationships into annual capacity contracts with throughput guarantees.
- Retail Enterprises:Brick-and-mortar and digital retailers localizing product information and customer service channels. Seasonal promotional calendars create predictable demand spikes.
- Financial Institutions:Banks and insurers adapting regulatory disclosures and customer interfaces. GDPR, SEC, and RBI data residency requirements force careful vendor selection with regional infrastructure presence.
Gaming studios generate the most concentrated revenue per account; financial institutions impose the most stringent compliance and security requirements on vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented software economies generate disproportionate localization demand as domestic developers seek overseas revenue. Import-dependent markets concentrate spending on compliance-heavy verticals where translation quality carries liability exposure. The resulting trade flow creates distinct regional specialization patterns across the value chain.
Germany
Automotive software exporters from Bavaria and Baden-Württemberg drive ISO-certified multilingual HMI development for vehicles sold across 30+ markets. The EU AI Act mandates documented translation decision pathways for automated systems, forcing vendors to maintain audit-ready infrastructure. Stuttgart's automotive tech cluster embeds localization deeper into product development cycles than any other European hub.
United States
SaaS vendors in California and Washington State require elastic API-driven translation workflows to support quarterly release cadences. FDA multilingual labeling requirements for software-as-medical-device products create specialized demand in Boston's health-tech corridor. The SEC's disclosure rules for fintech interfaces add compliance complexity that favors vendors with domestic data residency options.
Japan
Tokyo and Osaka gaming studios expand localization budgets to capture overseas players through simultaneous worldwide releases. METI's digital export promotion programs subsidize translation infrastructure for small-to-mid-sized developers. Kyoto's console manufacturing ecosystem maintains hybrid deployment models to protect intellectual property during pre-release phases.
South Korea
Seoul-based mobile game publishers generate 40+ language variants for day-one global launches, creating concentrated demand for real-time localization pipelines. The MFDS imposes stringent multilingual requirements on medical software exports that parallel FDA and EMA standards. Pangyo Techno Valley hosts the densest cluster of gaming-focused localization operations in Asia-Pacific.
India
Bangalore and Hyderabad IT services clusters leverage PLI scheme incentives to build cost-competitive localization capabilities for European and North American buyers. RBI data residency requirements for fintech localization create domestic infrastructure demand. Educational technology providers in Pune require scalable subtitle and voiceover pipelines for government skill development programs.
Global Localization Software Market Competitive Landscape
On the supply side, the industry is bifurcated between cloud-native platforms and legacy agency networks rebuilding around API delivery. Consolidation pressure favors vendors with elastic infrastructure over fixed linguist benches. Two strategic archetypes dominate: human-in-the-loop AI specialists and regulatory-certified workflow providers. Competitive moves center on M&A for domain expertise and strategic partnerships for compute capacity.
Within the human-in-the-loop tier, Lilt exemplifies adaptive AI positioning, while RWS Group anchors the regulatory-certified archetype through life sciences specialization. Smartling occupies the cloud-native workflow automation segment. These three represent the dominant strategic postures vendors must adopt to capture enterprise spending.
| Leading Market Players |
|---|
| Lilt |
| RWS Group |
| Smartling |
| Lokalise |
| Welocalize |
| Lionbridge |
| TransPerfect |
| Crowdin |
| BLEND |
| Others |
Supply & Pricing Matrix
Trans-Pacific fiber-optic cable latency costs directly shape margin structures for cloud-native localization platforms, concentrating supply-side leverage among vendors with redundant Singapore-Tokyo-Los Angeles routing while forcing price stratification between real-time API tiers and batch-processing alternatives.
Pricing Analysis
Industrial OEM buyers anchor subscription-based pricing structures across three tiers: enterprise-grade ISO 17100-certified workflows, mid-market cloud deployments, and developer-centric pay-per-character APIs. Price differentiation hinges on audit trail depth and data residency guarantees, with German automotive exporters least sensitive due to liability exposure and Indian e-learning platforms most sensitive given government budget constraints. Cost compression in mid-market tiers is intensifying as GPU inference expenses fluctuate with energy pricing.
Supply Chain Analysis
Extended payment terms from hyperscaler cloud providers now stretch 90-120 days, squeezing working capital for smaller vendors. Compute infrastructure concentrates in the United States, Ireland, and Singapore, with model training feeds from licensed multilingual corpora, synthetic data generation pipelines, and human-annotated quality benchmarks. Single-source vulnerability around NVIDIA GPU supply creates procurement risk. Distribution runs through direct API marketplaces and systems integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's transparency mandates constitute a structural inflection, forcing vendors to rebuild architectures around explainable translation pipelines or forfeit regulated verticals entirely.
For Market Incumbents: Pre-empt margin erosion from open-source LLM commoditization by securing exclusive data partnerships with gaming studios and automotive OEMs. Lock in ISO 17100 certification moats before mid-tier competitors achieve compliance. Vertical integration into synthetic voice generation technology preserves premium positioning against API-only challengers. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized IT services corridor, where cost arbitrage opportunities attract European buyers seeking GDPR-compliant offshore processing. Target mid-sized Japanese gaming studios underserved by legacy agency networks. Lead with CI/CD-native deployment models that compress time-to-market versus incumbent project-based workflows. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate localization divisions lacking cloud-native infrastructure. Long-term viability favors platforms with elastic compute architectures over fixed linguist benches. Watch for inflection when FDA software-as-medical-device submission volumes accelerate, signaling validated workflow pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Life sciences regulatory expertise commands 3-5x standard pricing premiums from FDA-bound clients. |
| Platform Integration | Embedding LLM APIs into Salesforce and Adobe ecosystems captures enterprise workflow lock-in. |
| Geographic Expansion | Pangyo Techno Valley presence secures proximity to South Korean mobile game publishers. |
| Strategic Partnership | Hyperscaler compute agreements buffer GPU cost volatility for mid-tier vendors. |
| Product Launch | Synthetic voice dubbing pipelines open streaming platform and game audio localization revenue. |
Research Methodology
A spread of perspectives from localization engineering directors, gaming studio production heads, pharmaceutical regulatory affairs leads, and automotive software HMI managers converged on the working assumptions. These primary inputs were cross-referenced against SEC filings from publicly traded vendors, EU AI Act implementation guidance documents, FDA software-as-medical-device submission databases, and hyperscaler capex disclosures. Bottom-up transaction volume estimates were reconciled with top-down market sizing across deployment models, solution offerings, and application verticals.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry, integration complexity level, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to validated baseline estimates, with explicit inputs for gaming release schedule intensity and automotive export labeling requirement expansion.
Stress conditions across GPU cost volatility, data residency law proliferation, and prompt engineering talent scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement timelines and cloud adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Club Management Software Market
Software & Services
House Cleaning App Market
Software & Services
Chromatography Data System (CDS) Software Market
Software & Services
Preventive Maintenance Software Market
Software & Services
Global Cloud Based Collaboration Software Market
Software & Services
Kennel Management Software Market
Software & Services
Content Marketing Software Market
Software & Services
Global OEE Software Market
Software & Services
Mobile Application Testing Services (MATS) Market
Software & Services
Global Restaurant POS Software Market
Software & Services
Japan Qualitative Data Analysis Software Market
Software & Services
Small Business Manufacturing Software Market
Software & Services
Global Catalog Management Systems Market
Software & Services
Structured Data Management Software Market
Software & Services
RFP Software Market
Software & Services
Website Builder Tool Market