
 Wi-Fi Based Home Camera Market | 2026-2036
Wi-Fi Based Home Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Wi-Fi Based Home Camera Market Analysis
The capability gap between cloud-native platforms and legacy hardware vendors is collapsing as software-defined features replace dedicated silicon. Amazon.com, Inc. leverages its Alexa ecosystem to anchor recurring subscription revenue through cloud storage tiers. Arlo Technologies, Inc. competes through proprietary base station architecture that sustains lower latency streaming than direct-to-router alternatives. Wyze Labs, Inc. specializes in ultra-low-cost hardware that positions the brand within entry-level smart home adoption curves.
Wi-Fi based home cameras are internet-connected imaging devices transmitting encrypted video streams over IEEE 802.11 protocols, typically incorporating CMOS sensors with resolutions from 1080p to 4K and edge-based motion detection algorithms. Their primary commercial purpose centers on real-time property surveillance, remote monitoring, and automated alert generation for residential security workflows. Indoor cameras dominate unit shipments due to simpler installation requirements and lower weatherproofing costs, while battery-powered cameras represent the fastest-growing installation category as lithium-ion cell density improves and magnetic mounting eliminates wiring labor. Two-way audio technology captures disproportionate margin pools through premium subscription bundles that bundle cloud storage with voice interaction features.
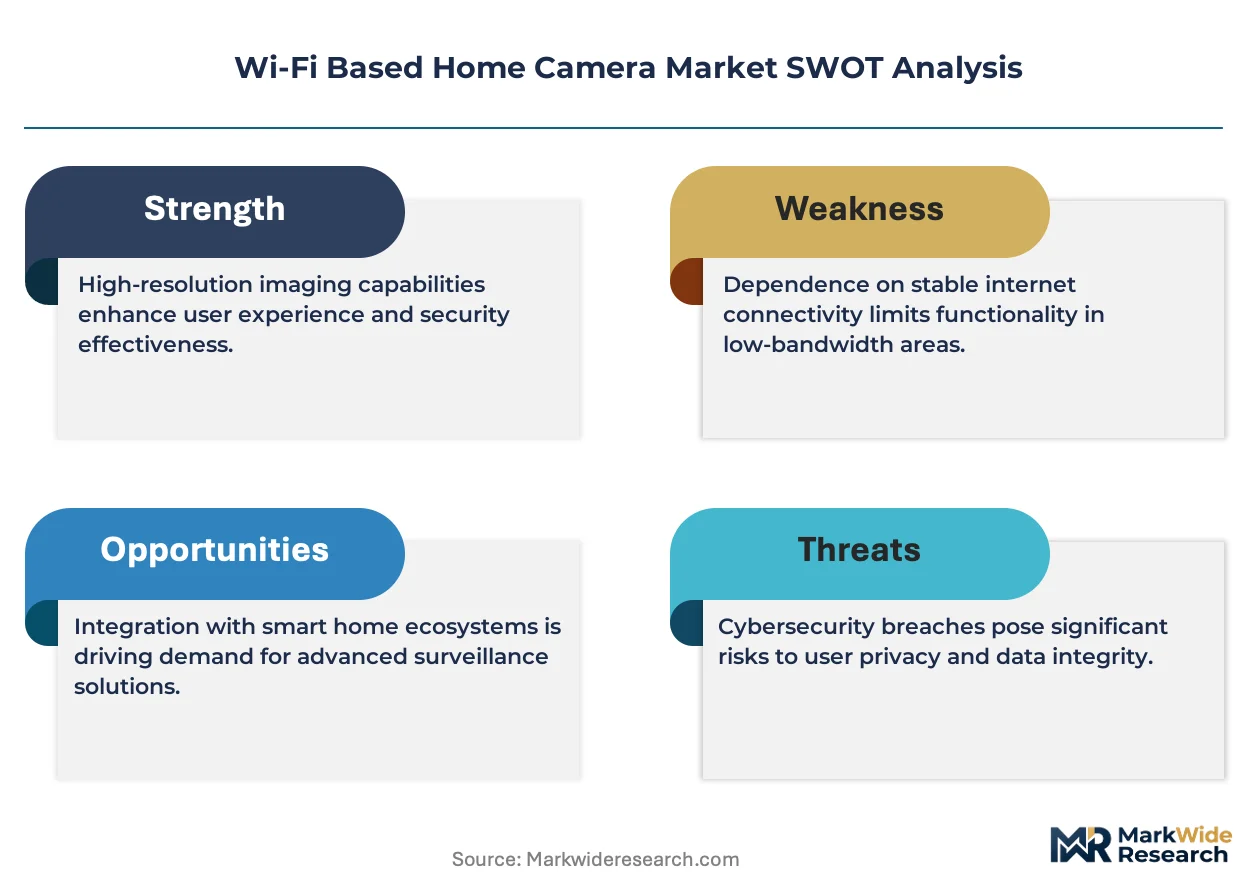
FCC Part 15 rules govern unlicensed radio frequency emissions for Wi-Fi cameras sold in the United States, while EU CE marking under the Radio Equipment Directive mandates cybersecurity baseline standards for devices entering European markets. GDPR compliance requirements in Europe reshape cloud storage architectures by restricting cross-border data flows and mandating encryption protocols. Stakeholders must monitor evolving AI governance frameworks that could reclassify facial recognition capabilities as high-risk biometric processing, triggering additional conformity assessment obligations.
Market Dynamics
Software-defined video analytics is collapsing the cost structure of intelligent surveillance, compressing margins for dedicated AI silicon vendors while democratizing computer vision capabilities across hardware tiers.
Growth Catalysts
- Smart home integration mandates:Rental property operators in the United States deploy Wi-Fi cameras as standard amenity infrastructure, driven by insurance premium reductions and tenant retention metrics.
- FCC Part 15 emission thresholds:Tightened RF power limits accelerate chipset miniaturization, enabling form-factor innovation in battery-powered outdoor units.
- Lithium-ion cell density improvements:Magnetic mounting systems eliminate electrical labor costs, expanding addressable installation scenarios for DIY consumers.
Market Restraints
- Cloud storage cost volatility:Tier-1 hyperscaler egress fees compress subscription margin pools for hardware vendors dependent on recurring revenue models.
- GDPR cross-border data restrictions:European cloud architectures require regional server deployment, fragmenting infrastructure economics versus unified global platforms.
- Facial recognition reclassification risk:Draft EU AI Act provisions threaten to categorize biometric processing as high-risk, triggering conformity assessment delays.
Strategic Opportunities
- India smart city infrastructure:Municipal surveillance tenders specify Wi-Fi backhaul for traffic monitoring, opening institutional procurement channels beyond residential segments.
- Two-way audio subscription bundling:Voice interaction features capture disproportionate margin pools when packaged with cloud storage tiers.
- CE marking cybersecurity baselines:EU Radio Equipment Directive compliance creates competitive moat against uncertified low-cost imports.
Industry Challenges
- Edge AI firmware engineering scarcity:Optimized neural network deployment on resource-constrained CMOS modules requires specialized embedded systems talent concentrated in Shenzhen and Taipei.
- Interoperability certification timelines:Matter protocol compliance testing extends product launch cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wi-Fi Based Home Camera Market |
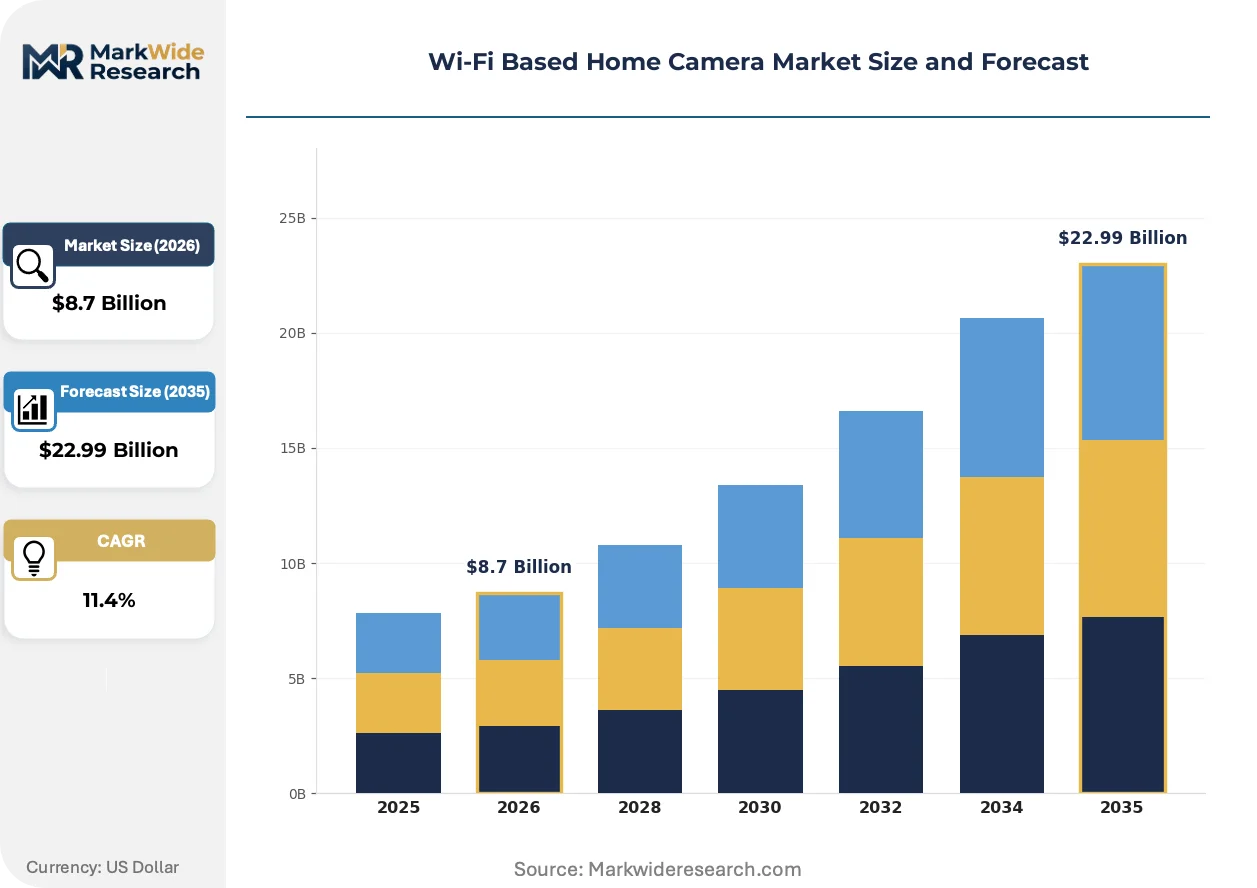
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Cameras, Outdoor Cameras, Battery-Powered Cameras, Wired Cameras Technology: HD Video, Night Vision, Motion Detection, Two-Way Audio Installation: Wall-Mounted, Ceiling-Mounted, Standalone, Integrated Systems End User: Homeowners, Renters, Property Managers, Security Professionals |
| Companies Covered | Arlo Technologies, Inc., Amazon.com, Inc., Wyze Labs, Inc., Samsung Electronics Co., Ltd., Anker Innovations, ADT Inc., SimpliSafe, Inc., Lorex Corporation, Vivint Smart Home, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wi-Fi Based Home Camera Market Emerging Trajectories
Edge-based inference engines are redistributing computational load from cloud data centers to camera SoCs, altering subscription economics and vendor lock-in dynamics across the residential security value chain.
On-device machine learning accelerators are displacing cloud-dependent motion detection, reducing latency for real-time alerts. Battery-powered camera manufacturers in Shenzhen integrate dedicated neural processing units to preserve cloud bandwidth quotas. This silicon migration compresses recurring infrastructure costs while enabling offline operation during network outages.
FCC Part 15 unlicensed emission rules are tightening RF power thresholds for 2.4 GHz and 5 GHz bands. Wi-Fi 6E chipset vendors redesign front-end modules to satisfy spurious emission limits. Outdoor camera deployments in the United States face pre-certification testing backlogs at Telecommunication Certification Bodies.
Subscription unbundling is fragmenting traditional cloud storage monetization. Property management platforms in Germany negotiate enterprise-wide API access rather than per-device licenses. This procurement pattern shifts margin capture toward software integration layers and away from hardware vendors.
Wi-Fi Based Home Camera Market Segmentation
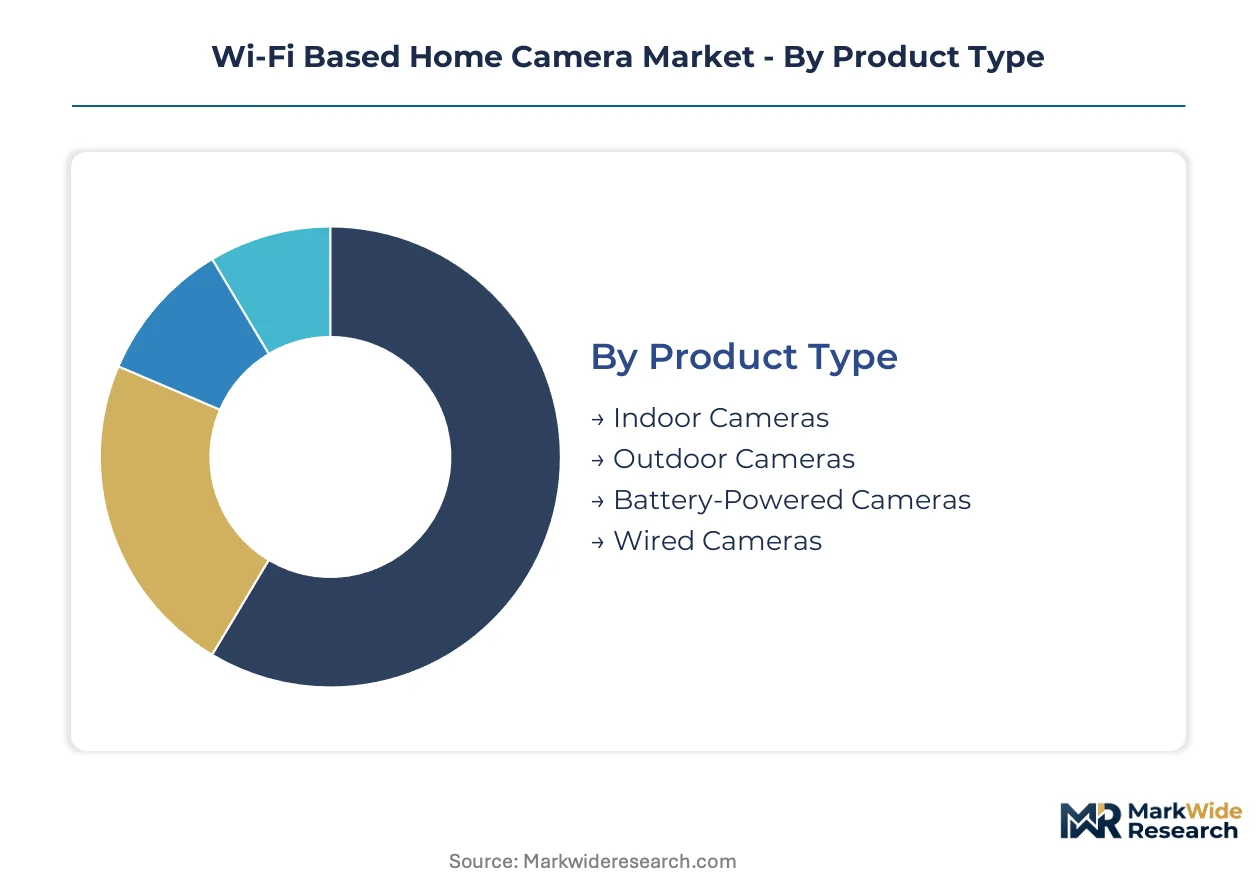
Wi-Fi based home cameras fragment across four intersecting dimensions that determine channel economics and margin capture. Product type and installation method dictate whether units flow through retail DIY shelves or professional security integrators. Technology tiers separate subscription-dependent revenue models from one-time hardware sales.
Product Type:
Indoor cameras dominate e-commerce fulfillment channels with lower return rates, while battery-powered units command premium placement in home improvement retail.
- Indoor Cameras:CMOS sensors from 1080p to 4K resolution operate within climate-controlled environments without IP65 weatherproofing costs. Rental property operators in the United States specify these for hallway and common area coverage where installation complexity must remain minimal for maintenance staff turnover.
- Outdoor Cameras:Housings incorporate ultraviolet-resistant polycarbonate and gasket-sealed cable entry points rated for temperature extremes. FCC Part 15 certification timelines extend for these units due to amplified RF front-end requirements for extended range through building materials.
- Battery-Powered Cameras:Lithium-ion cell densities above 300 Wh/kg enable six-month operation cycles with magnetic mounting brackets. Shenzhen manufacturers optimize these for direct-to-consumer cross-border e-commerce with minimal installation support infrastructure.
- Wired Cameras:Power over Ethernet (PoE) implementations satisfy security professional procurement specifications requiring 24/7 recording without battery maintenance windows.
By volume, Indoor Cameras leads. By growth pace, Battery-Powered Cameras is climbing the fastest.
Technology:
Feature differentiation determines whether vendors capture recurring subscription revenue or remain trapped in hardware margin compression.
- HD Video:1080p remains the volume baseline while 4K modules from Sony and OmniVision concentrate in premium tiers with H.265 compression to manage bandwidth consumption.
- Night Vision:940nm infrared LED arrays eliminate visible red glow for covert residential deployment, with sensor sensitivity measured in minimum lux thresholds.
- Motion Detection:Edge-based pixel-change algorithms reduce false alerts from cloud-dependent frame comparison, preserving battery life in wireless units.
- Two-Way Audio:Full-duplex echo cancellation hardware enables real-time conversation through integrated speaker-microphone arrays, anchoring premium subscription bundles with cloud storage.
Two-Way Audio commands the highest attachment rate to paid tiers. Motion Detection shows the steepest expansion trajectory as on-device AI displaces cloud processing.
Installation:
Mounting complexity segments procurement between self-install retail and professional channel dependency.
- Wall-Mounted:Bracket systems with 15-degree tilt adjustment accommodate exterior soffit positioning for optimal field-of-view coverage of entry points.
- Ceiling-Mounted:Recessed dome housings dominate commercial-adjacent residential deployments where aesthetic integration matters for common area surveillance.
- Standalone:Desktop or shelf positioning requires no drilling, capturing renter demographics with lease restrictions on permanent modifications.
- Integrated Systems:Pre-wired new construction specifications bundle cameras with centralized NVR infrastructure, locking in vendor ecosystems during builder selection phases.
Standalone units lead in absolute shipment volume. Integrated Systems gain share fastest in new residential construction pipelines.
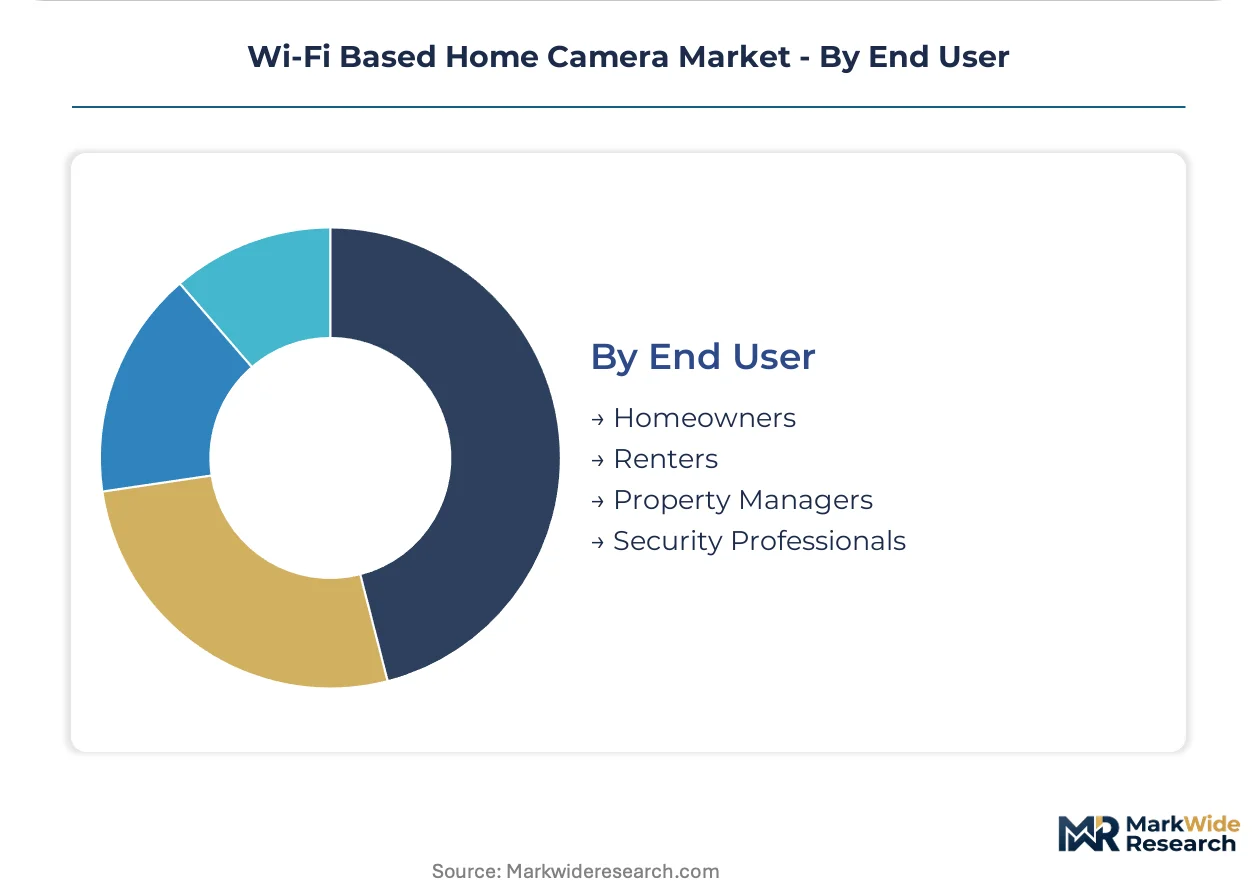
End User:
Customer type determines pricing tolerance, feature requirements, and support infrastructure investment.
- Homeowners:Permanent installation willingness supports higher upfront hardware expenditure with multi-year total cost of ownership calculations favoring local storage options.
- Renters:Lease duration uncertainty drives preference for removable mounting and month-to-month cloud subscriptions rather than capital-intensive NVR systems.
- Property Managers:Multi-unit portfolio operators negotiate enterprise API access for centralized monitoring dashboards across dispersed locations.
- Security Professionals:Installation firms demand UL-listed equipment with professional monitoring center integration and indemnification support.
Homeowners represent the largest installed base. Property Managers are expanding most quickly as institutional capital concentrates rental housing ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in China by a factor of three, reflecting divergent regulatory burdens and subscription monetization maturity. German and Japanese markets occupy intermediate positions where data sovereignty laws compress margins but sustain premium hardware valuations. India's emerging demand curve rewards ultra-low-cost manufacturing clusters with volume concentration.
United States
Rental property operators and insurance premium incentives drive procurement at scale. FCC Part 15 emission thresholds tighten RF certification timelines for outdoor battery-powered units. Shenzhen-to-Los Angeles logistics corridors concentrate cross-border e-commerce fulfillment for magnetic-mount cameras.
China
Domestic AI-enhanced CMOS module production scales through government-supported semiconductor foundry investments. MIIT cybersecurity review requirements for networked cameras reshape cloud architecture compliance costs. Huaqiangbei electronics markets in Shenzhen anchor global supply chains for edge AI firmware engineering talent.
Germany
Property management platforms negotiate enterprise API access for centralized monitoring dashboards. GDPR cross-border data restrictions mandate regional server deployment, fragmenting infrastructure economics. Munich and Berlin host compliance engineering consultancies specializing in CE marking cybersecurity baselines.
Japan
Aging demographics and single-person households sustain demand for standalone indoor units with minimal installation. METI energy efficiency guidelines influence lithium-ion cell density specifications for extended battery cycles. Tokyo-Osaka corridor distributors emphasize two-way audio subscription bundling for premium positioning.
India
Municipal smart city tenders specify Wi-Fi backhaul for traffic monitoring beyond residential segments. BIS certification requirements for electronic products extend market entry timelines for uncertified imports. Bengaluru and Hyderabad engineering centers concentrate embedded systems talent for edge AI optimization.
Wi-Fi Based Home Camera Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure with limited overlap. Cloud-native platform operators extract recurring subscription revenue through software-defined feature stacks. Dedicated hardware vendors compete on silicon integration density and supply chain velocity. Strategic moves concentrate on vertical integration into CMOS sensor sourcing and strategic partnerships with lithium-ion cell manufacturers for battery-powered form factors.
Within the ecosystem-anchored tier, Amazon.com, Inc. and Arlo Technologies, Inc. occupy positions defined by recurring revenue attachment and proprietary infrastructure differentiation. Wyze Labs, Inc. exemplifies the ultra-low-cost archetype that captures entry-level adoption curves through hardware margin compression. Samsung Electronics Co., Ltd. represents diversified electronics conglomerates leveraging captive semiconductor fabrication for vertical integration advantages. ADT Inc. and Vivint Smart Home, Inc. sit within the professional monitoring integration segment where UL-listed equipment requirements create certification moats.
| Leading Market Players |
|---|
| Arlo Technologies, Inc. |
| Amazon.com, Inc. |
| Wyze Labs, Inc. |
| Samsung Electronics Co., Ltd. |
| Anker Innovations |
| ADT Inc. |
| SimpliSafe, Inc. |
| Lorex Corporation |
| Vivint Smart Home, Inc. |
| Others |
Supply Flow & Price Mechanics
Ninety-day chipset lead times from Shenzhen contract manufacturers concentrate pricing power with vertically integrated CMOS module suppliers, while FCC certification backlogs in Los Angeles extend inventory cycles for US-bound outdoor camera shipments. This supply-chain friction amplifies margin compression for subscription-dependent hardware vendors competing against cloud-native platform operators with captive silicon sourcing.
Pricing Analysis
Configured-to-order pricing for integrated NVR systems commands a 40-60% premium over standalone magnetic-mount units, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade and after-sales service bundling. UL-listed equipment for security professional procurement sustains the highest price points, while direct-to-consumer cross-border e-commerce channels face the steepest price sensitivity among renter demographics. Cost compression in entry-tier hardware is intensifying because Shenzhen manufacturers are scaling AI-enhanced CMOS production with government foundry subsidies.
Supply Chain Analysis
Inventory cycles stretching 90-120 days for FCC-certified RF front-end modules reflect supply concentration in China, South Korea, and Taiwan for neural processing units and lithium-ion cells. The ecosystem draws from Huaqiangbei electronics markets for edge AI firmware engineering and rests on Sony and OmniVision for 4K CMOS sensor supply. Single-source vulnerability in MIIT cybersecurity review timelines creates regulatory chokepoint risk. Distribution runs through Shenzhen-to-Los Angeles logistics corridors for cross-border e-commerce, with German property management platforms bypassing retail channels through enterprise API procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellular-enabled security cameras and professional monitoring subscriptions pose substitution threats that Wi-Fi camera incumbents must neutralize through software-defined feature differentiation and ecosystem lock-in.
For Market Incumbents: Compound subscription attachment rates by bundling two-way audio with cloud storage tiers, while accelerating backward integration into CMOS sensor sourcing to offset hyperscaler egress fee pressure. Defend against cellular-enabled substitutes by embedding Matter protocol compatibility to sustain smart home ecosystem relevance.
For New Entrants and Emerging Players: CE marking cybersecurity fast-track compliance creates competitive moat against uncertified low-cost imports from Shenzhen. Target property management platforms in Germany with enterprise API access models rather than per-device licensing. Penetrate municipal smart city tenders in India by positioning Wi-Fi backhaul solutions for traffic monitoring beyond residential segments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across battery-powered camera manufacturing as lithium-ion cell density improvements reduce component count. Long-term viability favors platform operators with recurring revenue attachment over hardware vendors trapped in margin compression. Watch FCC Part 15 certification timeline extensions as signal for regulatory barrier escalation affecting outdoor unit economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Integration | Ensures interoperability certification with Apple HomeKit and Google Home ecosystems. |
| Edge AI Silicon Migration | Reduces cloud bandwidth costs through on-device neural processing unit deployment. |
| Enterprise API Licensing | Captures property management platform procurement shifting from per-device models. |
| Regional Cloud Architecture | Satisfies GDPR cross-border data restrictions through EU server deployment. |
| Cellular Backhaul Diversification | Addresses Wi-Fi coverage gaps in outdoor municipal surveillance deployments. |
Methodological Framework
Operator-level perspectives from rental property managers, security professional installation firms, smart home platform engineers, and FCC certification consultants anchored the qualitative base. Primary interview data combined with secondary validation from MIIT cybersecurity filings, FCC equipment authorization databases, ETSI standards documentation, and hyperscaler capex disclosures. Bottom-up unit shipment estimates triangulated against top-down subscription revenue analysis across product type, technology tier, installation method, and end-user segmentation.
Sensitivity analysis framed volume and value outputs across the projection horizon, with segmentation dimensions spanning indoor-outdoor-battery-wired product categories, HD video through two-way audio technology tiers, and homeowner-renter-property manager-security professional end-user archetypes. CAGRs derived from installed base growth rates and subscription attachment trajectories. Forecast inputs incorporated lithium-ion cell density improvement curves and FCC Part 15 emission threshold tightening schedules.
The analysis sits within stated boundaries; outcomes outside sustained lithium-ion cost reduction or accelerated EU AI Act biometric reclassification timelines would require recalibration. Forecasts reflect documented assumptions regarding smart home ecosystem penetration and hyperscaler cloud storage pricing stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Stalkerware Market
Security Software
United States Consumer Identity and Access Management Market
Security Software
Battery-Powered Doorbell Camera Market
Security Software
US Hardware Encryption Market
Security Software
Global Data Classification Market
Security Software
Asia Pacific Anti Money Laundering Solutions Market
Security Software
Global Data Protection As a Service (Dpaas) Market
Security Software
Global Mobile Security Software Market
Security Software
Global Email Verification Tools Market
Security Software
Online Background Check Market
Security Software
Patch and Remediation Software Market
Security Software
Global Security Assertion Markup Language (SAML) Authentication Market
Security Software
Security Software Market
Security Software
Global Wireless Intrusion Prevention System Market
Security Software
Mass Notification System Market
Security Software
Mobile Threat Management Security Software Market