
 Global Recruiting Software Market | 2026-2036
Global Recruiting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Recruiting Software Market Foresight
Healthcare hiring is recalibrating how enterprises evaluate recruiting platforms, with hospital networks and pharmaceutical manufacturers demanding tighter compliance integration. Workday leverages its unified HCM architecture to anchor large healthcare deployments. Oracle sustains competitive pressure through database-level analytics that serve Fortune 500 talent operations. SAP SuccessFactors dominates European manufacturing and industrial accounts with localized compliance modules.
Recruiting software comprises digital platforms that automate candidate sourcing, evaluation, and hiring workflows through structured data pipelines, API integrations, and machine-learning matching algorithms operating against structured job ontologies. The primary commercial purpose is reducing time-to-fill metrics while improving quality-of-hire outcomes through systematic candidate tracking. Cloud-based deployment leads segment value contribution due to lower capital barriers and faster implementation cycles for mid-market buyers. Applicant Tracking Systems remain the most mature software type, while Recruitment Marketing is the fastest-expanding category as employer branding shifts to programmatic channels. Talent Sourcing occupies a concentrated margin pool where AI-driven candidate discovery commands premium pricing.
The EU AI Act imposes algorithmic accountability requirements on automated candidate screening tools used across European jurisdictions, forcing vendors to document decision logic and audit trails. The US EEOC and OFCCP enforce anti-discrimination standards that shape how resume parsing and assessment modules must validate for disparate impact. China's SAMR and personal information protection standards constrain cross-border talent data flows. Stakeholders must monitor how divergent AI governance frameworks fragment product development roadmaps and compliance certification requirements.
Market Dynamics
The EU AI Act's algorithmic accountability mandates are forcing vendors to rearchitect automated screening modules, creating compliance-driven product differentiation that favors established platforms with audit-ready infrastructure over point solutions.
Growth Catalysts
- EU AI Act enforcement:Automated hiring tools across European jurisdictions must now document decision logic and maintain audit trails, accelerating replacement cycles for non-compliant legacy systems.
- German industrial clusters:Acute skilled labor shortages in manufacturing hubs are expanding talent acquisition technology budgets as workforce gaps threaten production targets.
- Healthcare network consolidation:Hospital systems and pharmaceutical manufacturers are standardizing on unified HCM platforms that embed recruiting, compliance, and workforce analytics.
Market Restraints
- Cross-border data fragmentation:China's SAMR personal information protection standards constrain talent data flows, complicating multinational deployment architectures.
- Algorithmic validation costs:US EEOC and OFCCP disparate impact testing requirements inflate R&D expenditure for resume parsing and assessment modules.
- Integration technical debt:Legacy HRIS systems in Fortune 500 enterprises resist API-native connectivity, extending implementation timelines and eroding SaaS margin profiles.
Strategic Opportunities
- India's PLI scheme expansion:Manufacturing incentives are creating greenfield hiring volume in automotive and electronics clusters lacking established talent infrastructure.
- Recruitment Marketing automation:Programmatic employer branding channels are displacing manual job board postings, opening margin pools for AI-driven content optimization platforms.
- API-first architecture convergence:Native connectivity between sourcing, assessment, and onboarding modules is enabling modular procurement that bypasses monolithic suite lock-in.
Industry Challenges
- Machine learning engineering scarcity:Candidate matching algorithm development requires specialized talent that vendors compete for against technology giants.
- Multi-jurisdiction certification timelines:ISO 30415 diversity and inclusion standards plus GDPR adequacy assessments delay product launches in regulated European markets.
- Legacy system integration complexity:SAP and Oracle on-premise HRIS instances in industrial accounts resist cloud-native middleware, forcing costly custom connector development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Recruiting Software Market |
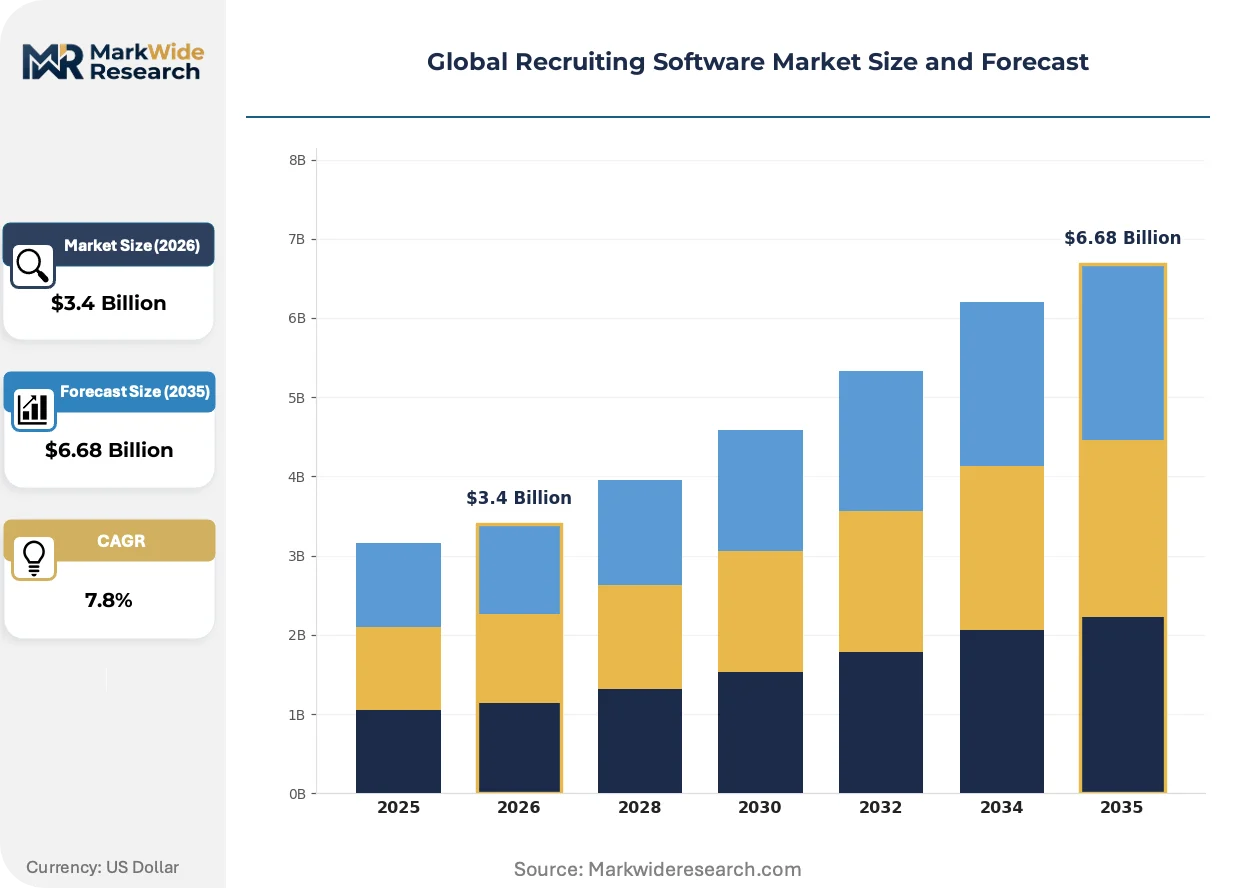
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.68 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Applicant Tracking System, Candidate Relationship Management, Onboarding Software, Talent Sourcing, Recruitment Marketing Deployment Model: Cloud-Based, On-Premises, Hybrid, Software as a Service, Managed Services End User: Human Resources, Recruitment Agencies, Staffing Firms, Corporate Talent Acquisition, Independent Recruiters Application: Resume Parsing, Interview Scheduling, Job Posting, Analytics & Reporting, Candidate Assessment |
| Companies Covered | Workday, Oracle, SAP SuccessFactors, Microsoft, iCIMS, ADP, Bullhorn, IBM, Greenhouse Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Recruiting Software Market Shifts & Advancements
Recruiting software architecture is pivoting from standalone applicant tracking toward embedded intelligence layers that automate decision workflows across the talent lifecycle. This shift compresses vendor consolidation timelines and redefines competitive moats around data network effects rather than feature breadth.
Generative AI is consolidating candidate communication and interview scheduling into autonomous workflow engines. Mid-market healthcare systems are deploying these tools at twelve-month replacement cycles. The technology is consolidating point-solution vendors into platform ecosystems as buyers prioritize unified data models over best-of-breed modularity.
REACH chemical safety documentation requirements are extending into HR tech supply chains as hardware-dependent assessment centers face substance compliance audits. Industrial manufacturing clients in Germany and France now mandate vendor certification. This pressure is compressing hardware-as-a-service pricing as distributors absorb compliance costs to maintain automotive and pharmaceutical accounts.
Subscription pricing for talent sourcing modules is displacing per-hire transaction models as buyer procurement functions demand predictable cost structures. Staffing agencies and RPO providers are converting fastest. This shift is most visible in US healthcare networks where CFO oversight of HR technology spend has tightened post-pandemic.
Global Recruiting Software Market Segmentation
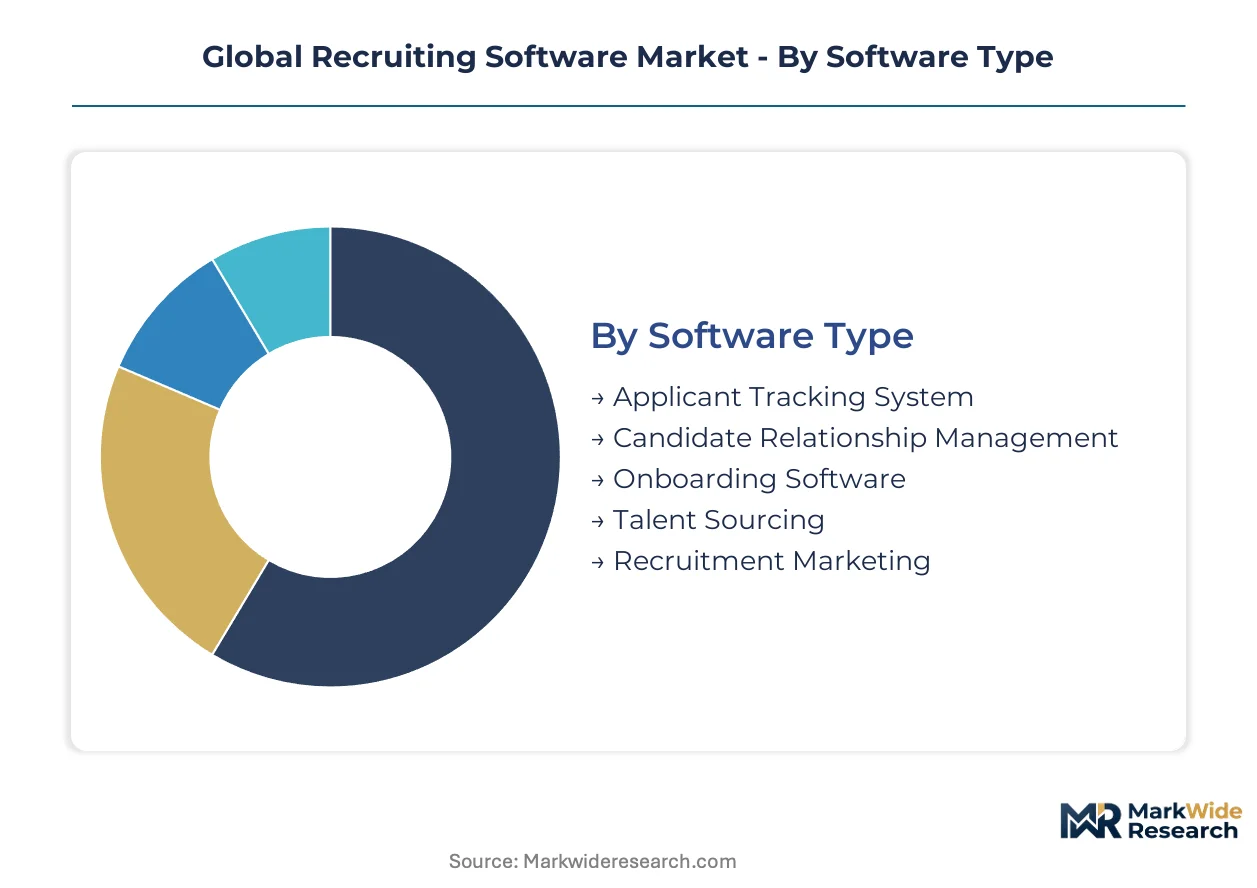
Recruiting software procurement patterns diverge sharply by buyer sophistication, compliance burden, and technical infrastructure maturity. Segmentation reveals how vendor architectures must adapt across deployment constraints, user workflows, and regulatory environments without fragmenting product roadmaps.
Software Type:
Functional specialization determines integration complexity and pricing power, with buyers prioritizing either workflow depth or platform breadth based on their existing HCM investments.
- Applicant Tracking System:Core workflow engine managing requisition creation, candidate pipeline staging, and offer management through configurable approval chains. Hospital networks in the United States standardize on these modules to consolidate EEOC compliance documentation across distributed hiring managers. Volume sits with Applicant Tracking System; growth tilts toward Recruitment Marketing.
- Recruitment Marketing:Programmatic employer branding and job distribution platform optimizing candidate funnel conversion through A/B-tested content and channel attribution. Pharmaceutical manufacturers in Germany deploy these tools to compete for scarce laboratory talent against industrial clusters. This segment is expanding most quickly as CFO oversight demands measurable talent pipeline ROI.
- Candidate Relationship Management:Talent pool nurturing system maintaining passive candidate engagement through automated drip campaigns and skill-tagging.
- Onboarding Software:Pre-boarding and first-day workflow automation integrating document collection, equipment provisioning, and training scheduling.
- Talent Sourcing:AI-driven candidate discovery module scraping professional networks and internal databases for passive talent matching.
Platform consolidation favors ATS-centric architectures; point solutions in sourcing and marketing face pressure to embed or partner.
Deployment Model:
Capital intensity and data sovereignty requirements segment buyers between predictable SaaS expenditures and controlled infrastructure ownership.
- Cloud-Based:Multi-tenant architecture delivering automatic updates, elastic scaling, and API-native connectivity without client-side infrastructure. Mid-market staffing firms in India favor this model for rapid deployment across manufacturing clusters lacking IT support. Deployment concentration favors Cloud-Based; expansion tilts toward Hybrid.
- Software as a Service:Subscription-licensed application with vendor-managed hosting and standardized configuration options limiting customization scope.
- Hybrid:Split architecture keeping sensitive candidate data on-premises while leveraging cloud analytics and AI services, addressing China's SAMR cross-border transfer restrictions. German automotive suppliers mandate this configuration to satisfy works council data localization requirements. This model is climbing the fastest as EU AI Act audit trails demand controlled data residency.
- On-Premises:Client-hosted installation requiring dedicated infrastructure, security management, and version upgrade cycles.
- Managed Services:Outsourced platform operation where vendors assume hosting, maintenance, and compliance monitoring responsibilities.
Compliance-driven buyers gravitate toward Hybrid; cost-sensitive adopters consolidate on Cloud-Based.
End User:
Scale and margin structure determine feature requirements, with high-volume transactional users demanding automation depth and enterprise buyers prioritizing governance controls.
- Corporate Talent Acquisition:Internal recruiting function managing full-cycle hiring for single employers, requiring deep HRIS integration and hiring manager self-service capabilities. Fortune 500 industrial conglomerates in the United States deploy these platforms to standardize OFCCP-compliant workflows across business units. Scale concentrates with Corporate Talent Acquisition; adoption momentum favors Recruitment Agencies.
- Recruitment Agencies:Third-party search firms placing candidates across multiple clients, prioritizing CRM depth, commission tracking, and client-branded communication portals. Specialized technology recruiters in London leverage these tools to maintain candidate relationships across competing employer mandates. This user type is gaining share fastest as contingent workforce expansion outpaces direct hiring.
- Staffing Firms:High-volume temporary labor providers managing time-to-fill metrics and worker redeployment at scale.
- Human Resources:Generalist HR departments handling recruiting alongside compensation, benefits, and employee relations with limited dedicated technology.
- Independent Recruiters:Solo practitioners or small partnerships requiring lightweight, mobile-first tools with minimal implementation overhead.
Enterprise procurement dominates revenue; agency automation represents the steepest expansion trajectory.
Application:
Workflow automation intensity varies by task complexity, with high-frequency administrative functions commoditizing faster than judgment-dependent evaluation tools.
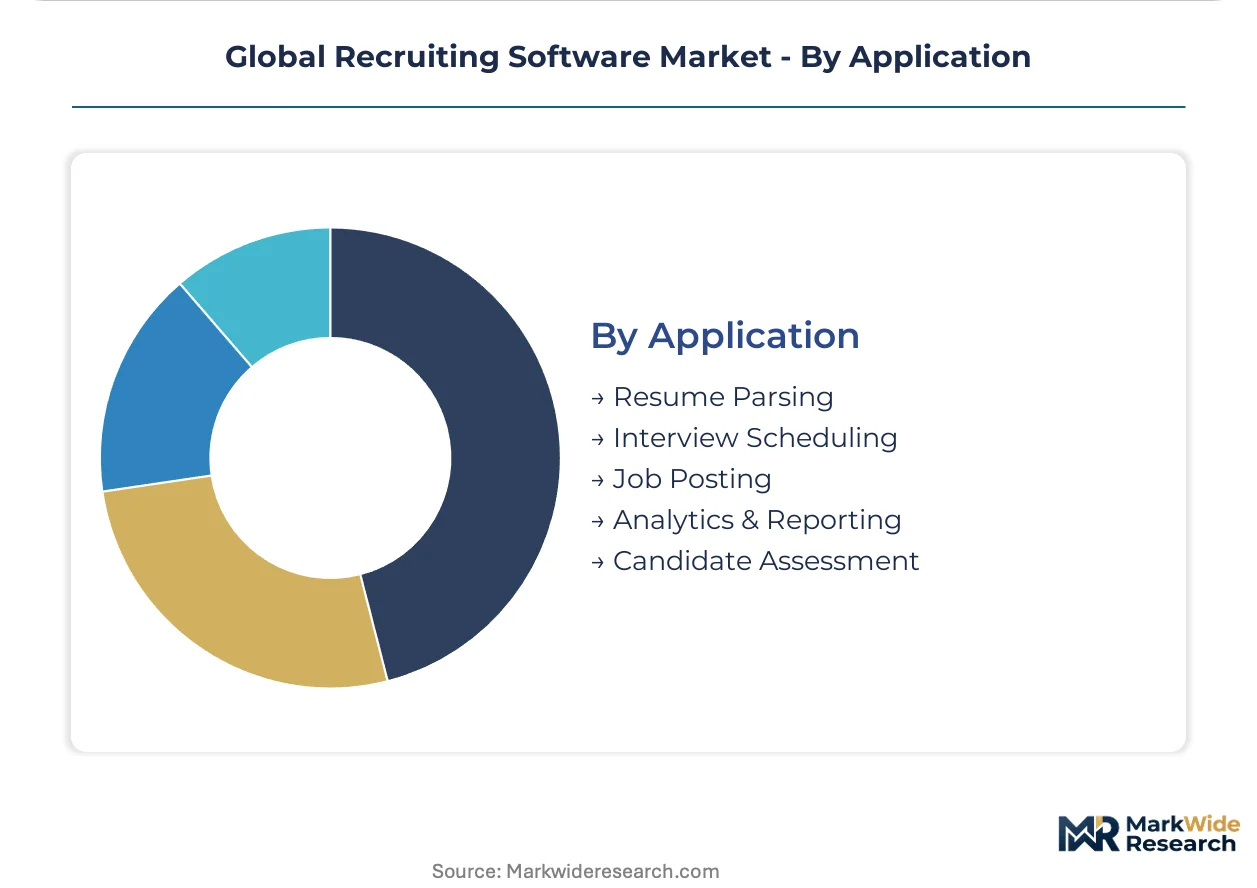
- Resume Parsing:Natural language processing engine extracting structured candidate data from unstructured documents, requiring continuous retraining against format variation and multilingual content. US-based RPO providers demand these modules with built-in EEOC disparate impact testing to defend against algorithmic discrimination claims. Transaction volume peaks with Resume Parsing; capability investment flows toward Candidate Assessment.
- Candidate Assessment:Psychometric, skills-based, and behavioral evaluation platform generating predictive hire quality scores through standardized testing protocols. Healthcare systems in France deploy these tools to validate clinical competency while documenting REACH-compliant safety training prerequisites. This application commands the highest R&D investment as EU AI Act explainability mandates reshape scoring algorithm architectures.
- Interview Scheduling:Calendar integration and automated coordination eliminating manual back-and-forth between candidates, hiring managers, and interview panels.
- Job Posting:Multi-channel distribution engine managing board integrations, sponsored spend optimization, and application flow tracking.
- Analytics & Reporting:Dashboard and visualization layer translating pipeline metrics, source effectiveness, and diversity outcomes into executive-facing insights.
Administrative automation saturates; predictive evaluation tools differentiate platform value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development concentrates in the United States and India, while enterprise procurement spreads across industrialized European economies. Demand intensity varies by regulatory environment and workforce structure. Compliance mandates in the European Union are accelerating replacement cycles faster than in other regions.
United States
Hospital networks and pharmaceutical manufacturers drive enterprise platform adoption. EEOC and OFCCP enforcement shapes how resume parsing and assessment modules validate for disparate impact. Healthcare systems in the Northeast and California standardize on unified HCM architectures to consolidate compliance documentation.
Germany
Automotive suppliers and industrial manufacturers face acute skilled labor shortages. Works councils mandate data localization requirements that favor hybrid deployment models. Manufacturing clusters in Bavaria and Baden-Württemberg are expanding talent acquisition technology budgets to close workforce gaps threatening production targets.
United Kingdom
Financial services and technology sectors prioritize AI-driven candidate matching capabilities. GDPR adequacy assessments delay product launches for vendors lacking audit-ready infrastructure. London-based recruitment agencies are converting fastest to subscription pricing models as procurement functions demand predictable cost structures.
India
Manufacturing incentives under the PLI scheme are creating greenfield hiring volume in automotive and electronics clusters. Mid-market staffing firms favor cloud-based deployment for rapid rollout across facilities lacking IT support. Industrial corridors in Gujarat and Tamil Nadu lack established talent infrastructure, opening opportunities for sourcing automation.
China
SAMR personal information protection standards constrain cross-border talent data flows. Multinational enterprises deploy hybrid architectures to keep sensitive candidate data on-premises while leveraging cloud analytics. Yangtze River Delta manufacturing hubs face compliance complexity that fragments deployment decisions.
Global Recruiting Software Market Competitive Landscape
Top-tier vendors anchor enterprise healthcare and industrial accounts, while mid-market specialists compete on implementation speed and vertical customization. The vendor base stratifies between unified HCM platforms with embedded recruiting modules and best-of-breed point solutions. Strategic archetypes include cloud-native disruptors, legacy database providers, and compliance-focused regional specialists. Consolidation pressure favors M&A activity and API-first partnership ecosystems over organic feature expansion.
Within the unified platform tier, Workday and Oracle exemplify contrasting architectural approaches to enterprise healthcare deployments. SAP SuccessFactors occupies a position anchoring European manufacturing accounts with localized compliance modules. Among point-solution specialists, iCIMS and Greenhouse Software represent the mid-market workflow automation segment where faster implementation cycles compete against suite breadth. These three archetypes—unified HCM, legacy-integrated database platforms, and agile point solutions—capture distinct procurement budgets based on buyer scale and integration complexity.
| Leading Market Players |
|---|
| Workday |
| Oracle |
| SAP SuccessFactors |
| Microsoft |
| iCIMS |
| ADP |
| Bullhorn |
| IBM |
| Greenhouse Software |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between EU AI Act-compliant audit-ready platforms and non-compliant legacy systems manifests in both pricing premiums and supply chain qualification requirements. Buyers in Germany and France now mandate vendor certification documentation that compresses hardware-as-a-service margins while elevating subscription pricing for compliant cloud-native architectures.
Pricing Analysis
Short lead-time deployments command premium pricing as hospital networks and pharmaceutical manufacturers accelerate replacement cycles to meet EU AI Act enforcement deadlines. Three-tier pricing structure across enterprise, mid-market, and staffing agency levels reflects integration complexity and compliance documentation depth. Cost compression in the mid-market tier is intensifying because CFO oversight demands predictable SaaS expenditures over per-hire transaction models. Staffing firms in India exhibit highest price sensitivity; Fortune 500 healthcare systems in the United States show lowest sensitivity due to bundled HCM procurement.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure and AI model training capacity are mandating multi-vendor qualification across United States, Germany, and India development centers. Software development draws from specialized machine learning engineering talent pools, API integration middleware, and compliance certification services. Single-source vulnerability concentrates in AI model training infrastructure as hyperscaler capacity constraints limit vendor options. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and cloud marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as vendors pursue backward integration into proprietary AI model training infrastructure to escape hyperscaler dependency and defend margin structures.
For Market Incumbents: Anticipate compliance-driven consolidation pressure by accelerating EU AI Act audit trail certification for legacy modules before replacement cycles peak. Anchor enterprise healthcare accounts through deeper HRIS integration that raises switching costs against cloud-native disruptors. Prioritize captive AI model development to reduce training cost exposure and differentiate matching algorithm performance.
For New Entrants and Emerging Players: Mid-market staffing firms in India's PLI scheme manufacturing corridors represent the most penetrable buyer archetype lacking established talent infrastructure. White-space opportunity sits with API-first sourcing modules that bypass monolithic suite lock-in through modular procurement. Pursue rapid cloud deployment partnerships with regional systems integrators lacking dedicated recruiting software practices.
For Investors and Strategic Acquirers: Re-rating potential sits with compliance-focused regional specialists given EU AI Act enforcement accelerating replacement demand across European jurisdictions. Long-term viability favors vendors with audit-ready infrastructure and localized data residency capabilities. Monitor German works council negotiation outcomes as the signal indicating hybrid deployment model adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies ATS, CRM, and onboarding modules to satisfy healthcare network consolidation mandates. |
| Compliance Certification Investment | Documents EU AI Act decision logic and audit trails for German automotive supplier procurement. |
| API-First Architecture Development | Enables modular procurement that bypasses Oracle and SAP SuccessFactors suite lock-in. |
| Geographic Expansion | Targets India's PLI scheme manufacturing clusters lacking established talent infrastructure. |
| Acquisition of Specialist Firm | Consolidates AI-driven candidate matching capabilities against technology giant competition. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with CHROs, talent acquisition directors, HR technology procurement officers, and systems integration specialists provided operational validation. Secondary sources encompassed EU AI Act implementation guidance, EEOC enforcement actions, SAMR cross-border data transfer rulings, and SEC 10-K disclosures from publicly traded HCM vendors. Bottom-up deployment modeling and top-down market sizing triangulated volume and value estimates.
Granularity-level modeling segmented the market by software type, deployment model, end user category, and application workflow across the projection horizon. Deployment architecture, organization size tier, vertical industry, and regional regulatory cluster dimensions shaped analytical frameworks. CAGRs derived from replacement cycle analysis, budget expansion patterns, and compliance-driven upgrade velocity. Forecast inputs incorporated EU AI Act implementation timelines and India's PLI scheme manufacturing incentive trajectories.
Revisions become necessary when EU AI Act enforcement intensity, SAMR data localization rulings, or hyperscaler AI training capacity constraints materialize differently than assumed. Deviation in German works council negotiation outcomes or US EEOC algorithmic discrimination enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Sports Production Software Market
Software & Services
Batch Management Software Market
Software & Services
VFX Software Market
Software & Services
Data Integration Software Market
Software & Services
Driver and Staff Management Software Market
Software & Services
Computer Software Market
Software & Services
Global Bug Tracking Software Market
Software & Services
Kennel Management Software Market
Software & Services
Output Management Software Market
Software & Services
Team Collaboration Software Market
Software & Services
AR Remote Collaboration Software Market
Software & Services
Smartphone Applications Market
Software & Services
Global Maintenance Management Software Market
Software & Services
PLM and Engineering Software Market
Software & Services
Poland IT Software and Service Market
Software & Services
Global Jewelry Store Management Software Market