
 Smartphone OS Market | 2026-2036
Smartphone OS Market Size, Share, and Industry Trends Forecast 2026-2036
Smartphone OS Market Outlook
ISO/IEC 27001 certification for mobile operating system security is rotating as a baseline qualifier for enterprise procurement contracts. Google leverages its Android Open Source Project to sustain developer ecosystem density across price tiers. Apple anchors premium segments through proprietary silicon-OS integration and controlled distribution. Huawei navigates geopolitical constraints by extending HarmonyOS into IoT adjacencies beyond smartphones.
A smartphone operating system is system software that manages hardware resources, mediates application execution through kernel-level process scheduling, and exposes APIs for third-party software development, with primary commercial purpose of enabling consumer and enterprise computing on handheld devices. Android dominates volume across emerging markets while iOS captures disproportionate margin pools in North America and Western Europe. Enterprise application deployments represent the fastest-expanding segment as BYOD policies and zero-trust architectures require OS-level security containers. Gaming-oriented OS optimizations concentrate in East Asian markets where high-refresh display synchronization and thermal management APIs differentiate flagship platforms.
The EU AI Act and GDPR impose algorithmic transparency and data minimization obligations on OS vendors processing biometric and behavioral signals. The FCC in the United States enforces equipment authorization and spectrum compliance that gates market entry for devices running modified OS kernels. India's BIS mandates local data residency certifications that influence OS architecture decisions for vendors targeting government and banking sectors. Stakeholders must monitor how fragmented national cybersecurity frameworks reshape engineering roadmaps and partnership requirements for cross-border OS distribution.
Market Dynamics
Enterprise zero-trust security mandates are compressing procurement cycles for managed smartphone OS deployments, forcing vendors to embed hardware-backed attestation and containerized execution environments at the kernel level.
Growth Catalysts
- EU AI Act compliance requirements:Algorithmic transparency obligations for biometric processing are accelerating vendor investment in on-device inference engines that minimize cloud data exposure.
- India's BIS data residency certifications:Localized OS architecture decisions for government and banking sectors are creating dedicated engineering pipelines for region-specific forks.
- High-refresh thermal management APIs:Gaming-oriented display synchronization optimizations in East Asian markets are differentiating flagship platform capabilities.
Market Restraints
- Proprietary silicon-OS integration concentration:Premium segment supply dependence on vertically integrated chip-design ecosystems limits second-source alternatives for performance-tier devices.
- GDPR algorithmic audit costs:Behavioral signal processing compliance is inflating engineering overhead for biometric authentication features across European deployments.
- Geopolitical licensing fragmentation:Modified kernel distribution restrictions are segmenting developer toolchain access across national boundaries.
Strategic Opportunities
- Brazil open-source derivative demand:Price-sensitive volume segments present white space for community-maintained Android forks with localized payment integration.
- IoT adjacency extension:HarmonyOS device convergence across wearables, automotive, and home automation is creating cross-platform developer ecosystem lock-in.
- Indonesia digital banking mandates:Central bank requirements for certified secure execution environments are opening procurement channels for hardened OS distributions.
Industry Challenges
- ISO/IEC 27001 certification timelines:Mobile security baseline qualification processes are extending enterprise sales cycles by 8-14 months.
- Legacy enterprise application containerization:BYOD policy enforcement requires retrofitting decades-old line-of-business software into modern attestation frameworks.
- Kernel-level patch distribution latency:Carrier certification bottlenecks for radio firmware updates delay critical vulnerability remediation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smartphone OS Market |
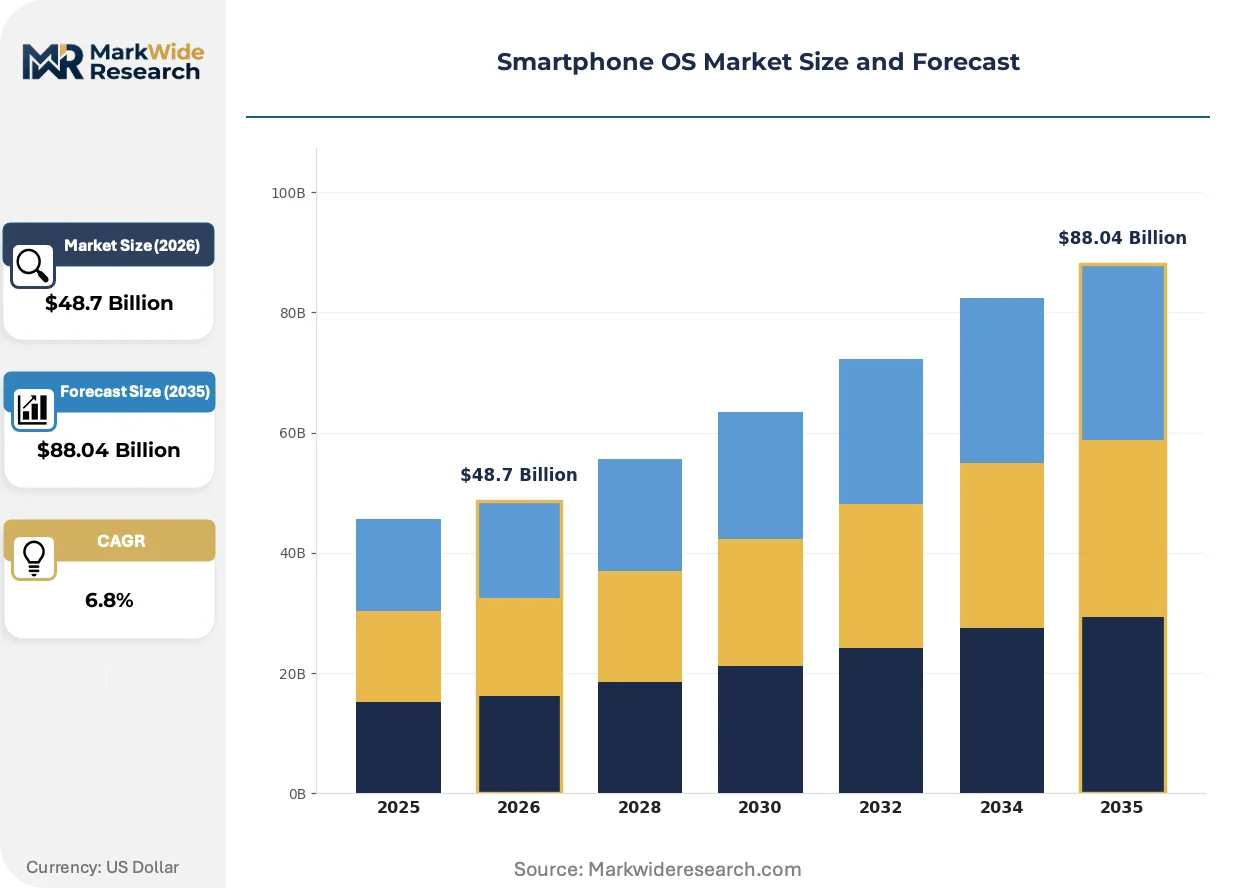
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Operating System: Android, iOS, HarmonyOS, KaiOS Device Type: Smartphones, Feature Phones, Tablets, Wearables Application Type: Consumer, Enterprise, Gaming, Education Distribution Model: Direct, Retail, Online, Carrier |
| Companies Covered | Google, Apple, Samsung, Xiaomi, Vivo, Oppo, Huawei, Motorola Mobility, Sony, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smartphone OS Market Strategic Shifts
On-device machine learning inference is redistributing computational workloads from cloud infrastructure to localized neural processing units, compressing latency-sensitive application architectures.
Hardware-backed secure enclaves are displacing software-only encryption for enterprise credential storage. Financial services procurement teams in North America and Western Europe now mandate dedicated isolated execution environments for mobile banking applications. This architectural shift is compressing market share for legacy OS versions lacking dedicated silicon support.
The EU AI Act's risk-classification framework for biometric identification systems is forcing OS vendors to restructure feature deployment pipelines. High-risk categorization for real-time facial recognition is triggering mandatory conformity assessments before market release. Premium device manufacturers are responding by decoupling certain AI features from default activation.
Enterprise procurement teams are consolidating vendor relationships around mobility suite providers capable of unified endpoint management. Device fleet purchasing is shifting from carrier-subsidized consumer channels to direct IT procurement with multi-year security update guarantees. This behavioral change is most pronounced in German and French manufacturing sectors where operational technology integration demands extended support lifecycles.
Smartphone OS Market Segmentation
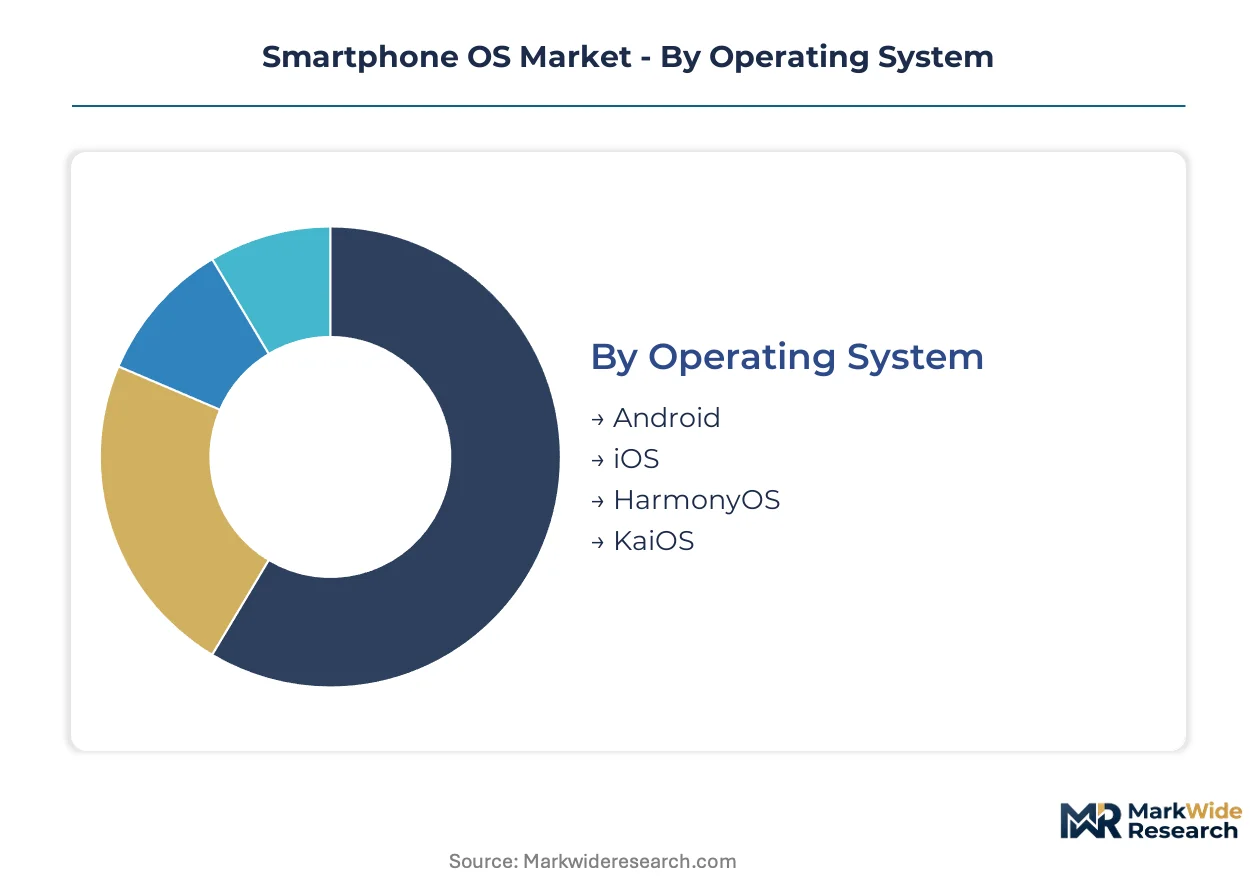
Smartphone OS segmentation reveals how platform economics fragment across hardware form factors and procurement channels. Vendor resource allocation and compliance engineering priorities diverge sharply between consumer volume plays and enterprise security contracts.
Operating System:
Substitution pressure concentrates on open-source derivatives facing proprietary platform bundling advantages and geopolitical licensing restrictions.
- Android:Open-source Linux-based kernel with Google Mobile Services integration dominates emerging market volume tiers. Indian and Indonesian government procurement channels increasingly demand localized forks with BIS-certified data residency architectures, compressing engineering timelines for standard distributions.
- iOS:Closed-source Unix-derived platform with vertically integrated silicon optimization captures premium segment margins in Germany and France. Enterprise zero-trust mandates for hardware-backed attestation reinforce procurement concentration among manufacturing sector fleet buyers requiring multi-year update guarantees.
- HarmonyOS:Microkernel architecture extending across IoT device categories beyond smartphones.
- KaiOS:Lightweight web-based platform targeting feature phone price tiers with limited application ecosystem density.
Android anchors the volume base while HarmonyOS gains share at the steepest rate through cross-device ecosystem convergence.
Device Type:
Cost tier stratification separates flagship silicon integration from emerging market entry-level specifications.
- Smartphones:Primary computing form factor with cellular modem integration and application store distribution. Enterprise BYOD policies and zero-trust container requirements in North American financial services are accelerating kernel-level security investments.
- Wearables:Constrained-resource platforms with health sensor fusion and notification relay functionality. EU AI Act biometric processing restrictions are forcing algorithmic transparency disclosures for continuous heart rate and SpO2 inference pipelines.
- Tablets:Expanded display form factor with stylus input APIs targeting education and creative professional segments.
- Feature Phones:Limited-functionality devices with basic voice and text capabilities serving price-sensitive demographics.
Smartphones dominate revenue concentration while wearables expand most quickly through health-monitoring regulatory tailwinds.
Application Type:
Customer type differentiation separates consumer advertising-supported models from enterprise security-guaranteed contracts.
- Enterprise:Managed deployment scenarios requiring ISO/IEC 27001 certification and hardware-backed credential isolation. German manufacturing procurement teams now mandate unified endpoint management integration with operational technology systems.
- Gaming:Performance-optimized distributions with thermal management APIs and high-refresh display synchronization. East Asian markets concentrate demand for 120Hz+ adaptive refresh and GPU driver customization.
- Consumer:Mass-market deployments with application store monetization and advertising personalization engines.
- Education:Institutional procurement with content filtering and multi-user session management requirements.
Enterprise contracts command premium pricing while gaming applications climb the fastest through hardware differentiation pressure.
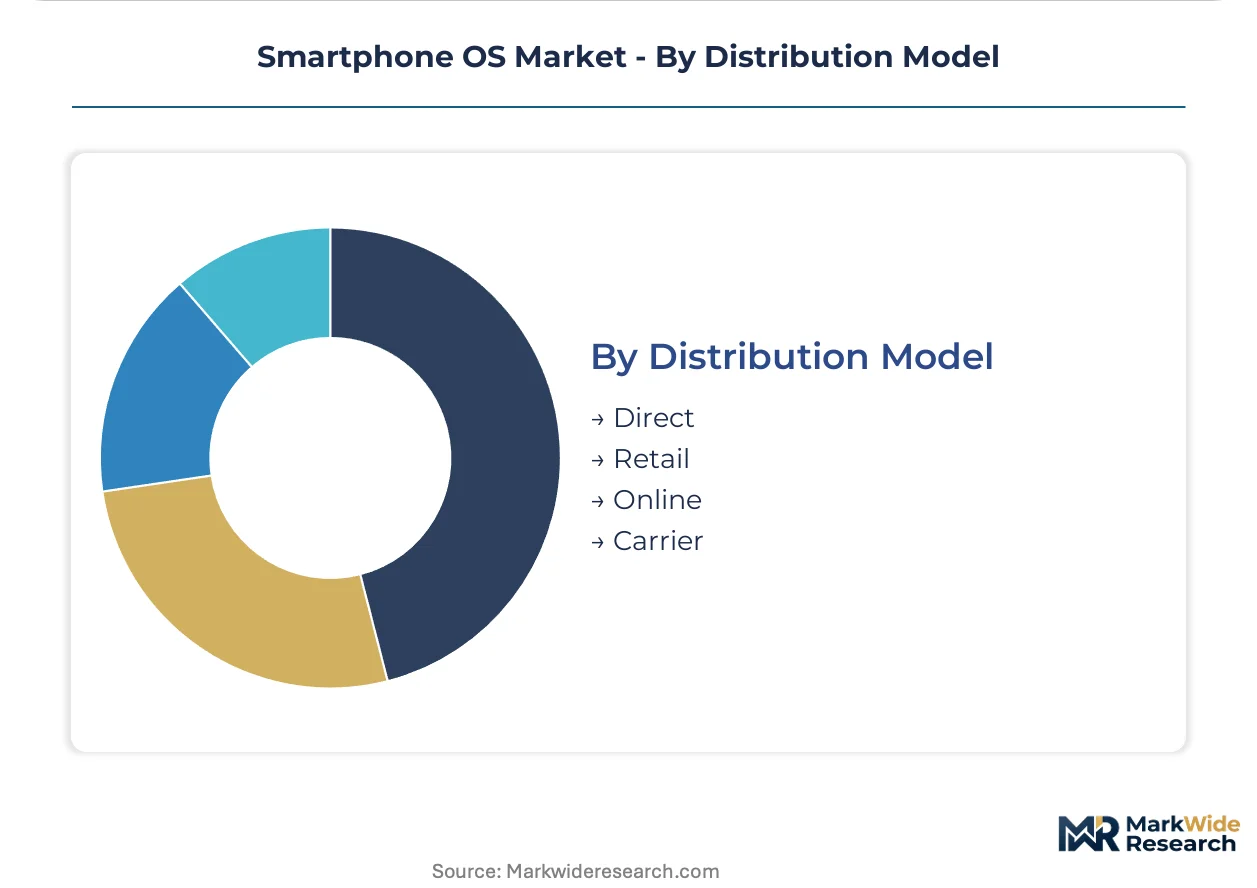
Distribution Model:
Supply concentration patterns fragment between carrier-controlled subsidy channels and direct procurement bypassing retail intermediaries.
- Carrier:Network-locked devices with installment financing and radio firmware certification bottlenecks. FCC equipment authorization requirements gate kernel modification distribution through operator quality assurance pipelines.
- Online:Direct-to-consumer fulfillment with unlocked bootloader policies and developer toolchain access. Brazilian price-sensitive segments concentrate here for gray-market import avoidance.
- Retail:Physical storefront presence with immediate device activation and technical support services.
- Direct:Manufacturer-controlled sales with extended warranty and trade-in program integration.
Carrier distribution retains volume concentration while online channels accelerate most quickly through financing fintech integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement teams in German manufacturing and North American financial services anchor premium-tier demand through multi-year security update contracts. Indian government banking channels and Indonesian central bank mandates drive mid-tier volume through certified data residency requirements. Brazilian price-sensitive consumers concentrate in online direct channels for open-source derivatives.
United States
Financial services enterprises mandate hardware-backed secure enclaves for mobile banking applications through procurement contracts. FCC equipment authorization requirements gate kernel modification distribution through carrier quality assurance pipelines. Silicon Valley clusters concentrate zero-trust architecture development for BYOD policy enforcement.
Germany
Manufacturing sector fleet buyers require ISO/IEC 27001 certification and unified endpoint management integration with operational technology systems. GDPR algorithmic audit costs inflate engineering overhead for biometric authentication features across European deployments. Bavarian industrial clusters anchor extended support lifecycle procurement for operational technology integration.
India
Government and banking sectors demand BIS-certified data residency architectures compressing engineering timelines for localized forks. RBI and SEBI regulations influence OS architecture decisions for vendors targeting financial services procurement channels. Bengaluru and Hyderabad clusters concentrate engineering pipelines for region-specific Android derivatives.
Brazil
Price-sensitive volume segments present white space for community-maintained Android forks with localized payment integration. ANVISA and central bank requirements shape procurement channels for certified secure execution environments. São Paulo retail clusters concentrate gray-market import avoidance through online direct distribution.
Indonesia
Central bank mandates for certified secure execution environments open procurement channels for hardened OS distributions. BIS-aligned data residency certifications influence vendor engineering decisions for government and banking sector targeting. Jakarta clusters concentrate digital banking infrastructure deployment requiring localized OS architecture compliance.
Smartphone OS Market Competitive Environment
Player mix skews toward vertically integrated platform vendors with proprietary silicon-OS integration and open-source ecosystem orchestrators with developer toolchain control. Structure concentrates around two dominant archetypes: premium-tier closed-stack vendors capturing enterprise security contracts and volume-tier open-source distributors serving emerging market price sensitivity. Competitive moves center on cross-device ecosystem convergence and kernel-level security certification acceleration.
Within the vertically integrated tier, Apple exemplifies proprietary silicon-OS optimization for premium margin capture. Google anchors open-source ecosystem density through Android Open Source Project maintenance across price tiers. Huawei occupies a position navigating geopolitical constraints through HarmonyOS extension into IoT adjacencies beyond smartphones.
| Leading Market Players |
|---|
| Apple |
| Samsung |
| Xiaomi |
| Vivo |
| Oppo |
| Huawei |
| Motorola Mobility |
| Sony |
| Others |
Value Chain & Pricing Dynamics
Foundry capacity utilization at leading semiconductor manufacturers anchors cost structures across the smartphone OS value chain, compressing price floors for entry-tier distributions while amplifying margin capture for vertically integrated premium platforms. Scale concentration in neural processing unit fabrication feeds directly into licensing tier differentiation and enterprise security certification premiums.
Pricing Analysis
Cost-plus contracts with foundry partners index wafer pricing to commodity memory and logic node availability, creating pass-through volatility for mid-tier Android distributions. Pricing stratifies across premium iOS ecosystems with proprietary silicon control, standard-tier GMS-licensed Android with Google service bundling, and economy-level open-source forks without certification overhead. Cost compression in Indian and Brazilian entry segments intensifies as local assembly incentives reduce hardware landed costs. Enterprise buyers in German manufacturing exhibit lowest price sensitivity due to ISO/IEC 27001 mandate requirements, while Southeast Asian consumer channels remain most elastic to device subsidy fluctuations.
Supply Chain Analysis
Strategic stockpiling of legacy node wafers characterizes vendor inventory strategy ahead of EU AI Act compliance deadlines, contrasting with just-in-time practices for flagship chiplet architectures. Taiwan, South Korea, and the United States anchor advanced logic fabrication for premium tier neural engines. Supply chains draw from rare earth processing in China, display driver ICs from Taiwan, and RF front-end modules from Japan and the United States. Single-source vulnerability concentrates in extreme ultraviolet lithography equipment access. Distribution runs through carrier-locked channels in North America and Western Europe, with online direct fulfillment expanding fastest in Latin American and Southeast Asian price-sensitive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Security update subscription services and enterprise mobility suite licensing expand faster than hardware unit economics, transforming smartphone OS markets into recurring-revenue attachment opportunities. Managed endpoint provisioning and zero-trust container management now command premium pricing multiples over bare OS licensing.
For Market Incumbents: Consolidate kernel-level security certification pipelines to compress ISO/IEC 27001 audit timelines threatening German manufacturing procurement cycles. Deepen backward integration into secure enclave silicon design to defend margin position against HarmonyOS cross-device ecosystem expansion. Prioritize direct enterprise sales channel control bypassing carrier subsidy intermediaries.
For New Entrants and Emerging Players: BIS fast-track certification for Indian government banking channels offers lowest barrier-to-entry among regulated procurement corridors. Target Indonesian central bank hardened OS mandates with localized architecture compliance. Pursue white-label Android fork distribution through Brazilian fintech-integrated online channels.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enterprise security container specialists with unified endpoint management integration capabilities. Long-term viability hinges on multi-year update guarantee contract density rather than device shipment volumes. Watch for EU AI Act high-risk algorithmic classification threshold crossings as inflection indicator for compliance engineering spend acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Kernel-Level Security Certification Acceleration | Compresses ISO/IEC 27001 audit timelines for German manufacturing procurement. |
| On-Device Inference Engine Investment | Addresses EU AI Act algorithmic transparency obligations for biometric processing. |
| Cross-Device Ecosystem Convergence | Extends HarmonyOS architecture into automotive and home automation adjacencies. |
| Direct Enterprise Sales Channel Buildout | Bypasses carrier certification bottlenecks for zero-trust container deployments. |
| Localized Fork Engineering Pipeline | Delivers BIS-certified data residency architectures for Indian government banking. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and regulatory submission databases. Primary interviews engaged mobile platform engineering directors, enterprise IT procurement officers, carrier device certification managers, and mobility suite product strategists. Bottom-up triangulation across OS distribution volume estimates and top-down reconciliation against foundry wafer allocation data validated market sizing.
Segmentation dimensions modeled include operating system type, device form factor, application deployment scenario, and distribution channel structure across the projection horizon. CAGRs derive from installed base growth rates, replacement cycle compression, and enterprise fleet penetration trajectories. Forecast inputs incorporate EU AI Act implementation timelines, BIS certification pipeline velocities, and FCC equipment authorization throughput capacities.
Decision-makers should treat outputs as directional under stable geopolitical licensing frameworks and foundry capacity expansion assumptions; material deviation would warrant model refresh. Revision becomes warranted when kernel modification distribution restrictions cross thresholds fragmenting developer toolchain access across national boundaries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Appointment Reminder Software Market
Software & Services
North America Enterprise Resource Planning Market
Software & Services
Europe HR Payroll Software Market
Software & Services
Global Business Software and Service Market
Software & Services
Collaborative Office Software Market
Software & Services
Account-Based Data Software Market
Software & Services
Web Development Market
Software & Services
Enterprise Application Market
Software & Services
Architectural Rendering Software Market
Software & Services
Embedded Graphical User Interface (GUI) Development Software Market
Software & Services
Global Online Assessment Software Market
Software & Services
Global Cloud Accounting Technology Market
Software & Services
Global Plumbing Software Market
Software & Services
Global Automotive Software Market
Software & Services
System Infrastructure Software Market
Software & Services
Anti-Plagiarism for the Education Sector Market