
 Global Small Cell 5G Network Market | 2026-2036
Global Small Cell 5G Network Market Size, Share, and Industry Trends Forecast 2026-2036
Global Small Cell 5G Network Market Foresight
Network procurement is shifting from single-source radio contracts toward multi-vendor open RAN arrangements. Nokia Corporation leverages its AirScale portfolio to anchor European operator relationships. Samsung Electronics Co., Ltd. sustains manufacturing scale through captive semiconductor supply. Huawei Technologies Co., Ltd. dominates integrated baseband-to-antenna systems across emerging markets.
Small cell 5G networks comprise low-power radio access nodes operating below 250 milliwatts, designed to extend macro coverage through sub-6 GHz and millimeter-wave spectrum bands in high-density environments. The technology primarily addresses capacity exhaustion in stadiums, transit corridors, and enterprise campuses where macro towers fail to penetrate. Indoor deployment leads current volume as enterprises replace legacy distributed antenna systems with 5G-native picocell architectures. Femtocell technology lags in commercial traction due to carrier provisioning complexity, while metrocells capture margin pools in smart city backhaul integration.
The FCC's CBRS rules and the EU's Radio Equipment Directive shape product certification timelines and cross-border market access for vendors. China's MIIT enforces GB standards that mandate domestic testing protocols, fragmenting global homologation pathways. Stakeholders must monitor spectrum refarming schedules and open interface maturation to calibrate R&D allocation across sub-6 GHz and millimeter-wave portfolios.
Market Dynamics
Network densification mandates from spectrum regulators are compressing deployment timelines while forcing architectural shifts from monolithic RAN toward disaggregated open interfaces.
Growth Catalysts
- CBRS framework:The FCC's three-tier spectrum access system unlocks private 5G deployments across US manufacturing campuses and logistics hubs without exclusive carrier licensing.
- Smart city backhaul integration:Metrocell installations in Chinese urban corridors leverage existing street furniture and utility pole attachments to reduce civil works expenditure.
- Millimeter-wave spectrum release:South Korea's MSIT allocation of 28 GHz bands enables ultra-dense hotspot coverage in Seoul's transit stations and entertainment districts.
Market Restraints
- GaN substrate supply concentration:Power amplifier manufacturing depends on captive gallium nitride wafer output concentrated among three East Asian foundry operators.
- GB standards fragmentation:China's MIIT mandates domestic testing protocols for radio equipment homologation, creating parallel certification tracks that delay cross-border product launches.
- Macro cell capacity substitution:Massive MIMO upgrades at existing tower sites absorb incremental traffic growth in suburban zones, reducing small cell urgency.
Strategic Opportunities
- Indian enterprise private networks:TRAI's administrative spectrum allocation framework permits captive 5G deployments across mining, ports, and automotive manufacturing facilities.
- Open RAN interface maturation:O-RAN Alliance specifications enable multi-vendor radio unit combinations, lowering switching costs for tier-two operators.
- Stadium distributed systems replacement:Legacy DAS infrastructure in European football venues and North American arenas reaches end-of-life, creating 5G-native picocell retrofit demand.
Industry Challenges
- RF engineering talent scarcity:Millimeter-wave beamforming optimization requires specialized expertise concentrated among semiconductor vendors and defense contractors.
- Multi-vendor integration complexity:Disaggregated RAN architectures demand systems integration capabilities that most operators have outsourced to incumbent suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Small Cell 5G Network Market |
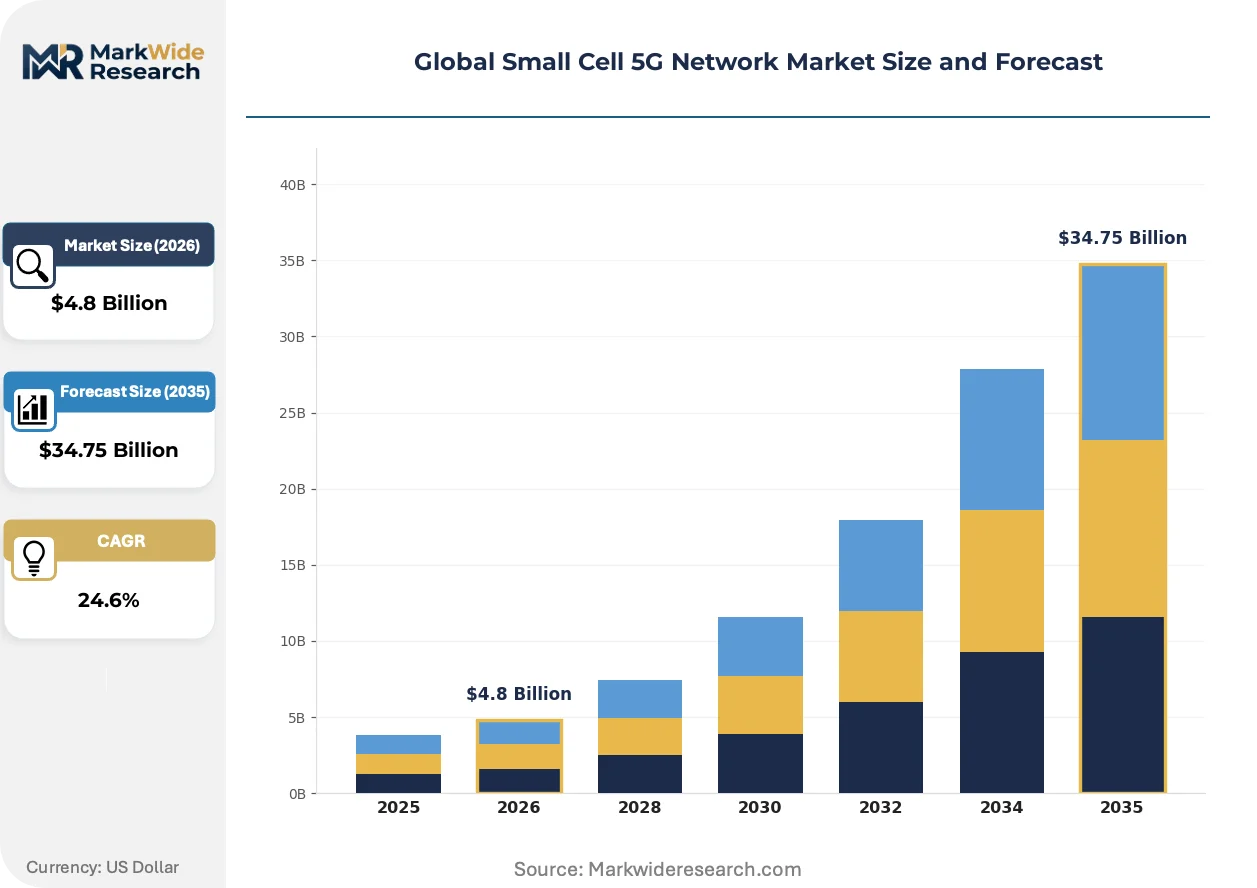
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $34.75 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
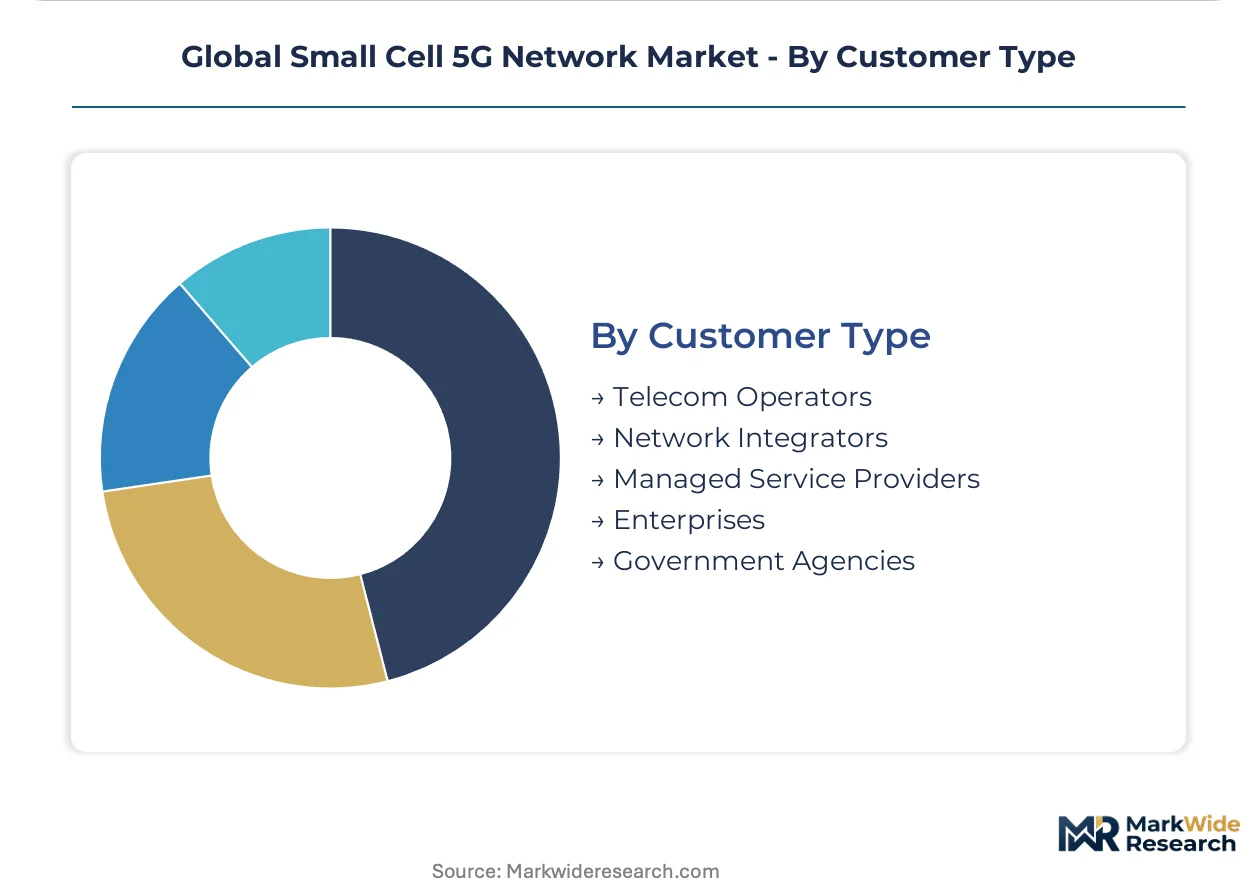
| Segmentation | Deployment Type: Outdoor, Indoor, Enterprise, Residential, Public Spaces Technology: Femtocell, Picocell, Microcell, Metrocells, Distributed Antenna Systems Application: Mobile Broadband, Fixed Wireless Access, IoT Connectivity, Smart Cities, Enhanced Mobile Broadband Customer Type: Telecom Operators, Network Integrators, Managed Service Providers, Enterprises, Government Agencies |
| Companies Covered | Huawei Technologies Co., Ltd., Nokia Corporation, Samsung Electronics Co., Ltd., Telefonaktiebolaget LM Ericsson, ZTE Corporation, Cisco Systems Inc., Fujitsu Limited, CommScope Inc., Qualcomm Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Small Cell 5G Network Market Shifts & Advancements
Open interface specifications are dismantling proprietary radio lock-in while AI-driven network automation compresses operational expenditure models for dense urban deployments.
Millimeter-wave active antenna units are expanding into indoor enterprise environments as manufacturing, healthcare, and logistics facilities pursue deterministic latency for automated systems. German automotive plants and Japanese electronics factories are deploying 28 GHz small cells to support AGV coordination and real-time quality inspection. This frequency band is expanding into settings previously reserved for sub-6 GHz coverage, enabling private network slicing that isolates critical operational traffic from public subscriber loads.
The EU's Radio Equipment Directive 2014/53/EU enforcement through notified body certification is lengthening product approval cycles for non-European vendors seeking CE marking. Harmonized standards under ETSI mandate specific electromagnetic compatibility and spectrum efficiency thresholds that diverge from FCC Part 27 rules. Equipment manufacturers are responding by establishing separate regional SKU configurations rather than pursuing unified global product platforms.
Enterprise buyers are consolidating vendor relationships through multi-site framework agreements that bundle small cell hardware with managed services and spectrum leasing. This pattern displaces transactional procurement of discrete radio units through systems integrators. The shift is most visible in US healthcare networks and UK university campuses, where facilities teams lack internal RF planning expertise and prefer outcome-based coverage guarantees over capital equipment ownership.
Global Small Cell 5G Network Market Segmentation
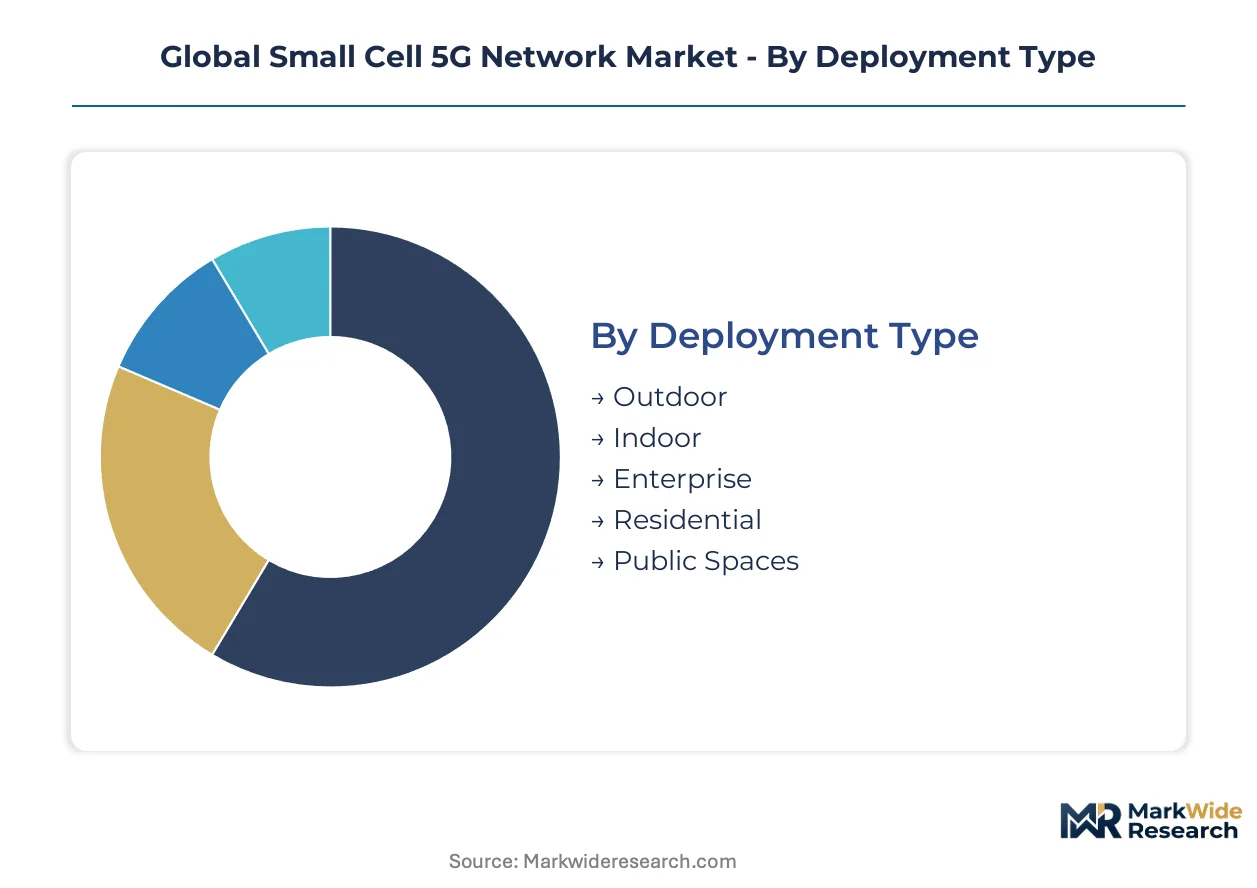
Small cell 5G procurement decisions pivot on deployment environment constraints, power output specifications, and backhaul integration requirements. Buyers evaluate radio node categories against spectrum licensing frameworks and civil infrastructure availability.
Deployment Type:
Site acquisition costs and zoning permissions determine deployment economics across radio node placement scenarios.
- Outdoor:Street-level pole-mounted installations leverage existing utility infrastructure in dense urban corridors. Demand clusters in Seoul's transit districts and Shanghai's commercial zones where macro coverage gaps persist.
- Indoor:Ceiling-mounted picocell arrays replace legacy distributed antenna systems in stadiums, airports, and convention centers. German automotive plants and Japanese electronics factories deploy these for deterministic latency in automated production lines.
- Enterprise:Private network installations on manufacturing campuses and logistics hubs utilize CBRS spectrum in the United States and TRAI-administered bands in India.
- Residential:Consumer-grade femtocell deployment remains constrained by carrier provisioning complexity and subscriber self-installation failure rates.
- Public Spaces:Metrocell integration with smart city street furniture reduces civil works expenditure in Chinese urban corridors and European municipal networks.
Outdoor leads on scale; Enterprise leads on momentum.
Technology:
Power output thresholds and coverage radius specifications segment vendor R&D allocation across radio node architectures.
- Femtocell:Low-power residential units operating below 100 milliwatts face commercial headwinds from Wi-Fi 6 substitution and complex carrier activation workflows.
- Picocell:Indoor-focused 250-milliwatt nodes dominate stadium retrofit cycles across European football venues and North American arenas replacing end-of-life DAS infrastructure.
- Microcell:Medium-power outdoor units bridge coverage gaps in suburban commercial districts and highway corridors where macro tower density proves insufficient.
- Metrocells:Street-level installations capture margin pools through smart city backhaul integration in Chinese urban corridors leveraging existing utility pole attachments.
- Distributed Antenna Systems:Legacy coax-based infrastructure faces displacement by 5G-native fiber-to-the-antenna architectures in healthcare networks and university campuses.
Metrocells command premium positioning; Picocell retrofit demand is climbing the fastest.
Application:
Traffic pattern characteristics and latency requirements shape radio resource allocation across use case categories.
- Mobile Broadband:Dense subscriber hotspot coverage drives volume in Seoul's entertainment districts and Tokyo's transit stations utilizing 28 GHz millimeter-wave allocations.
- Fixed Wireless Access:Last-mile broadband substitution targets suburban and rural zones where fiber trenching costs prove prohibitive for traditional wireline deployment.
- IoT Connectivity:Massive machine-type communications leverage small cell density for sensor grid backhaul in industrial facilities and agricultural monitoring networks.
- Smart Cities:Integrated street furniture deployments combine lighting control, traffic management, and public safety communications on unified backhaul infrastructure.
- Enhanced Mobile Broadband:High-throughput enterprise applications demand network slicing capabilities that isolate operational traffic from public subscriber loads.
Mobile Broadband anchors volume deployment; Fixed Wireless Access shows steepest expansion trajectory.
Customer Type:
Technical integration capabilities and spectrum access rights differentiate procurement authority across buyer categories.
- Telecom Operators:Licensed spectrum holders drive volume procurement through framework agreements with Nokia, Samsung, and Huawei for macro network densification.
- Network Integrators:Systems integration specialists manage multi-vendor open RAN deployments for tier-two operators lacking in-house RF engineering resources.
- Managed Service Providers:Outcome-based coverage guarantees displace capital equipment ownership in US healthcare networks and UK university campuses.
- Enterprises:Captive 5G deployments in mining, ports, and automotive manufacturing utilize India's TRAI administrative spectrum framework and US CBRS three-tier access.
- Government Agencies:Public safety and defense applications require hardened equipment meeting specific electromagnetic compatibility and security certification thresholds.
Telecom Operators dominate procurement volume; Enterprises are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's transit corridors anchor global small cell deployment velocity. The FCC's CBRS framework and South Korea's 28 GHz spectrum releases compress procurement timelines. Dense urban clusters in China, Germany, and India absorb disproportionate infrastructure investment.
United States
Private 5G deployments across manufacturing campuses and logistics hubs drive demand. The FCC's three-tier spectrum access system eliminates exclusive carrier licensing requirements. Detroit's automotive plants and Houston's port facilities deploy CBRS-enabled small cells for deterministic latency.
South Korea
Ultra-dense hotspot coverage in transit stations and entertainment districts accelerates installation. MSIT's 28 GHz millimeter-wave allocation enables Seoul's metro operators to densify radio nodes. Busan-Ulsan's industrial corridor integrates small cells with smart factory automation.
China
MIIT's 5G infrastructure targets mandate metrocell installations at scale across urban corridors. GB standards enforce domestic testing protocols that fragment global homologation pathways. Shanghai's commercial zones and Shenzhen's manufacturing clusters absorb concentrated vendor shipments.
Germany
Automotive plants in Bavaria and Baden-Württemberg deploy millimeter-wave small cells for AGV coordination. The EU's Radio Equipment Directive 2014/53/EU lengthens product approval cycles through notified body certification. Stuttgart's factory automation networks and Munich's research campuses lead enterprise private network adoption.
India
Captive 5G deployments across mining, ports, and automotive manufacturing facilities expand addressable market. TRAI's administrative spectrum allocation framework permits enterprise-controlled radio access networks. Maharashtra's Mumbai-Pune industrial belt and Gujarat's port zones concentrate early installations.
Global Small Cell 5G Network Market Competitive Landscape
Global majors compete with regional champions across spectrum licensing frameworks and integration capabilities. The vendor base organizes around three tiers: integrated baseband-to-antenna system providers, multi-vendor open RAN enablers, and specialized indoor coverage specialists. Strategic differentiation centers on captive semiconductor supply, regional certification expertise, and managed service bundling. Dominant competitive moves include geographic expansion through local partnership structures and portfolio diversification across sub-6 GHz and millimeter-wave portfolios.
Within the integrated system tier, Huawei Technologies Co., Ltd. and Nokia Corporation exemplify divergent geographic positioning strategies. Samsung Electronics Co., Ltd. anchors the manufacturing scale archetype through captive supply chain control. ZTE Corporation occupies a position bridging domestic market dominance with selective international expansion. These four entities collectively represent the competitive tension between proprietary end-to-end architectures and disaggregated open interface alternatives.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Nokia Corporation |
| Samsung Electronics Co., Ltd. |
| Telefonaktiebolaget LM Ericsson |
| ZTE Corporation |
| Cisco Systems Inc. |
| Fujitsu Limited |
| CommScope Inc. |
| Qualcomm Technologies Inc. |
| Others |
Supply & Pricing Matrix
Gallium nitride wafer pricing indices cascade through power amplifier manufacturing costs, compressing margins for radio unit vendors while stratifying end-equipment across premium certified and economy unlicensed tiers in dense urban deployments.
Pricing Analysis
Input-cost pass-through from GaN substrate supply concentration drives three-tier pricing structure across premium, standard, and economy levels for small cell radio units. CE marking under the EU's Radio Equipment Directive and FCC Part 27 certification differentiate price bands, with unlicensed CBRS gear facing steepest cost compression due to carrier-agnostic provisioning complexity. Enterprise buyers in US healthcare networks show highest price sensitivity, while South Korean telecom operators absorbing MSIT-mandated densification timelines exhibit lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Nokia and Samsung, while systems integrators serve tier-two operators lacking in-house RF engineering. GaN wafer fabrication concentrates in Taiwan, South Korea, and Japan, with final assembly drawing from China's Shenzhen and Dongguan electronics clusters. RF front-end components hinge on captive foundry output, exposing vendors to single-source vulnerability when East Asian logistics chokepoints congest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Small Cell 5G Network Market functions as a regulatory compounder where MIIT's infrastructure targets, the FCC's CBRS framework, and the EU's Radio Equipment Directive collectively accelerate procurement velocity beyond pure demand signals.
For Market Incumbents: Anchor manufacturing scale through captive semiconductor supply as Samsung Electronics sustains, while deepening backward integration into GaN substrate sourcing to offset foundry concentration risk. Defend against open RAN disaggregation by certifying AirScale-equivalent portfolios under both FCC Part 27 and ETSI harmonized standards, preserving operator relationships against multi-vendor switching cost reductions.
For New Entrants and Emerging Players: The premium-to-economy price gap in private 5G deployments creates entry space for TRAI-administered spectrum equipment in India's mining and port sectors, where incumbent presence remains thin. Target captive enterprise networks requiring deterministic latency for AGV coordination, leveraging O-RAN Alliance specifications to bypass proprietary radio lock-in without matching Huawei's integrated baseband-to-antenna R&D scale.
For Investors and Strategic Acquirers: Asymmetric upside sits with managed service providers bundling coverage guarantees for facilities teams lacking RF planning expertise. Five-to-ten year viability favors vendors controlling both millimeter-wave active antenna design and smart city backhaul integration capabilities. Monitor open interface maturation timelines as inflection indicator for switching cost erosion among tier-two operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-vendor Open RAN Certification | O-RAN Alliance specifications enable tier-two operators to combine radio units from non-integrated vendors. |
| Captive GaN Supply Chain Integration | Backward integration into gallium nitride wafer sourcing reduces dependency on Taiwan and South Korean foundries. |
| Smart City Backhaul Partnership | Metrocell installations leveraging Shanghai and Shenzhen utility pole attachments capture municipal infrastructure spend. |
| Private 5G Managed Service Launch | Outcome-based coverage guarantees displace capital equipment ownership in US healthcare and UK university campuses. |
| Regional SKU Configuration | Separate product platforms for FCC Part 27, ETSI harmonized standards, and MIIT GB protocols accelerate certification timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with RF engineering directors at telecom operators, procurement leads at German automotive plants, regulatory affairs specialists navigating CE marking pathways, and smart city infrastructure planners in Chinese municipal governments. Secondary validation drew from FCC spectrum allocation dockets, ETSI harmonized standard publications, MIIT GB standard filings, and customs records tracking GaN wafer trade flows. Bottom-up radio unit shipment aggregation and top-down infrastructure spend estimates triangulated market sizing.
Comparable-period anchoring linked historical small cell deployment cycles to forward projections across the analysis window, modeling volume and value through deployment type, technology tier, application use case, and customer category dimensions. CAGRs derived from segment-level growth rate reconciliation against macro infrastructure investment patterns, with millimeter-wave spectrum release schedules and open RAN interface maturation timelines serving as key forecast inputs.
Caveats apply where MIIT standard revisions, FCC spectrum reallocation, or ETSI electromagnetic compatibility threshold changes could materially shift the outlook. Forecasts reflect assumptions about carrier densification timelines and enterprise private network adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Qatar Telecom Market
Telecommunications
IoT MVNO (Services) Market
Telecommunications
Nigeria Satellite Communications Market
Telecommunications
IoT Telecom Services Market
Telecommunications
Japan 5G Small Cell Market
Telecommunications
Malaysia Telecom Towers Market
Telecommunications
Mexico MNVO Market
Telecommunications
Utility Communications Market
Telecommunications
Mftpaas Market
Telecommunications
Chile Telecom Market
Telecommunications
Poland Telecom Market
Telecommunications
Esim Subscription Market
Telecommunications
Africa Entertainment and Telecommunication Market
Telecommunications
Bahrain Telecom Market
Telecommunications
Transport Stream Switching Market
Telecommunications
Russia ICT Market