
 Poland Telecom Market | 2026-2036
Poland Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Telecom Market Analytics
Open RAN architecture is tilting vendor strategies away from proprietary hardware stacks toward interoperable software-defined networks. Orange Polska leverages its incumbent infrastructure to sustain nationwide fiber coverage leadership. Play Communications competes aggressively on mobile data pricing while extending 5G reach into secondary cities.
Poland telecom encompasses voice, data, and video transmission services delivered through wireless and wireline infrastructure operating across frequency bands from 700 MHz to 26 GHz and fiber optic cables with single-mode transmission rates exceeding 100 Gbps, serving residential consumption, enterprise productivity, and public administration connectivity needs. Fiber optic deployment under the Technology segment anchors capital intensity as operators replace copper last-mile infrastructure, while 5G network slicing within the Service Type dimension is opening premium revenue streams for ultra-reliable low-latency enterprise applications. The Customer Type split shows Enterprise and Government contracts commanding superior margins due to stringent service-level agreements and cybersecurity compliance requirements.
The Office of Electronic Communications enforces spectrum allocation and net neutrality rules that directly shape operator licensing costs and service pricing flexibility, while the Polish Financial Supervision Authority and EU GDPR framework impose data governance standards affecting cloud-integrated telecom offerings. Stakeholders must monitor how the national broadband plan interacts with EU-funded digital cohesion programs to identify infrastructure subsidy timing and geographic priority zones.
Market Dynamics
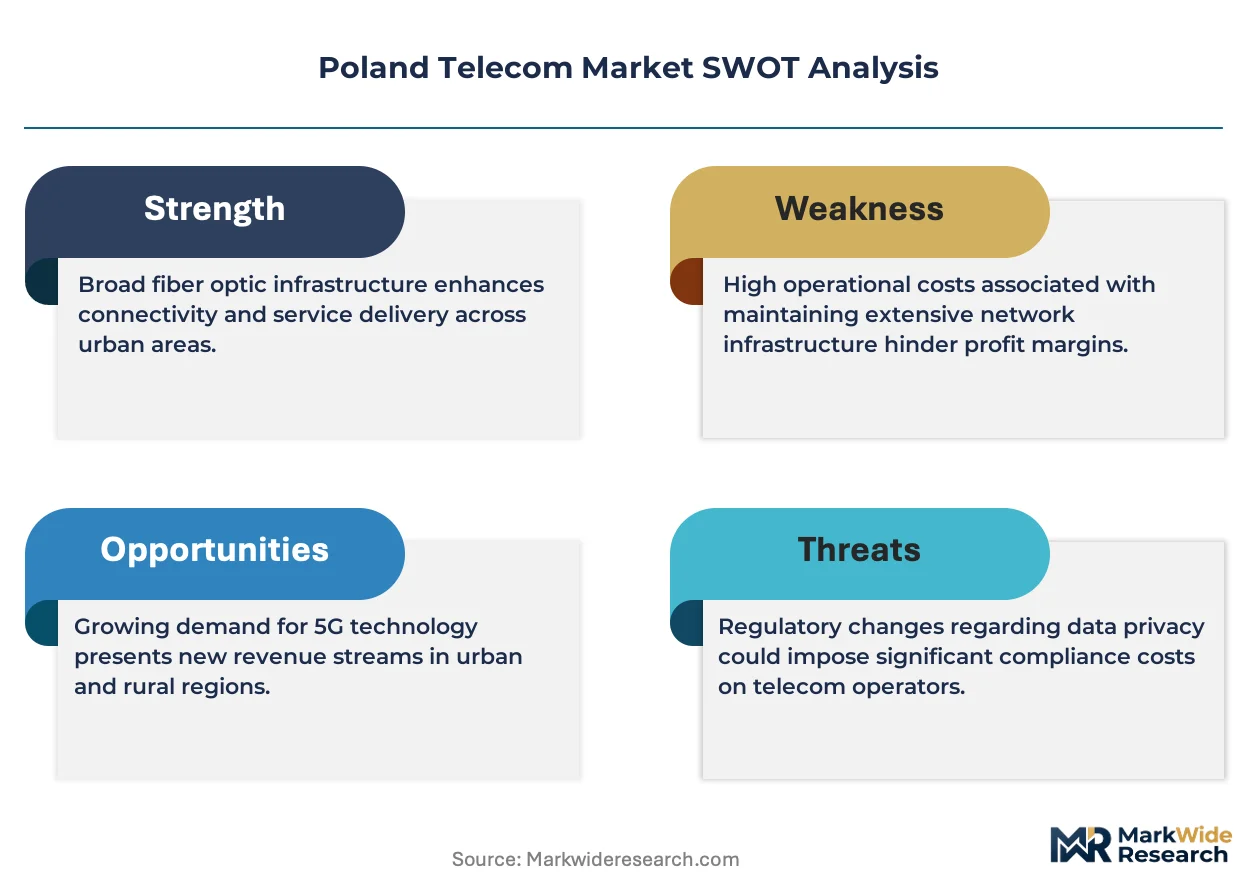
Poland's telecom sector is undergoing a fundamental architectural transition as Open RAN standards dismantle proprietary network equipment lock-in, forcing incumbent operators to renegotiate supplier relationships while enabling new software-centric entrants to challenge established infrastructure hierarchies.
Growth Catalysts
- EU Digital Cohesion funding:Brussels-backed infrastructure subsidies are accelerating fiber-to-the-premises rollout in underserved Polish voivodeships, reducing deployment cost barriers for regional operators.
- Manufacturing corridor demand:Polish automotive and electronics factories are contracting dedicated 5G network slices for ultra-reliable low-latency machine control, creating premium enterprise revenue streams.
- Spectrum reallocation:The Office of Electronic Communications' 5G auction framework is releasing 3.5 GHz and 26 GHz bands for next-generation services, enabling operators to densify urban coverage.
Market Restraints
- Fiber deployment cost structure:Last-mile trenching expenses in rural Polish territories consume disproportionate capital relative to subscriber density, constraining nationwide coverage parity.
- Equipment vendor concentration:Polish mobile operators remain dependent on a narrow base of Nordic and East Asian radio access network suppliers, exposing rollout timelines to geopolitical supply disruptions.
- Copper legacy technical limitation:Existing DSL infrastructure cannot sustain bandwidth demands from 4K video and cloud applications, forcing accelerated write-downs of amortized access networks.
Strategic Opportunities
- Eastern voivodeship underpenetration:Podlaskie and Lublin provinces exhibit fiber subscription rates below half the national average, presenting first-mover expansion potential for agile operators.
- Smart city mandate convergence:Warsaw and Kraków municipal governments are tendering integrated IoT connectivity for traffic management and environmental monitoring, bundling sensor networks with backhaul.
- Edge-cloud technology convergence:Polish manufacturing enterprises are requesting co-located compute and radio infrastructure, enabling operators to capture value from distributed cloud services beyond pure connectivity.
Industry Challenges
- Radio frequency engineering talent scarcity:Polish technical universities produce insufficient specialists in massive MIMO antenna design and millimeter-wave propagation modeling, extending recruitment cycles for 5G deployment teams.
- Multi-vendor integration complexity:Open RAN interoperability promises are colliding with real-world interface inconsistencies, forcing Polish operators to maintain expensive system integration capabilities in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Telecom Market |
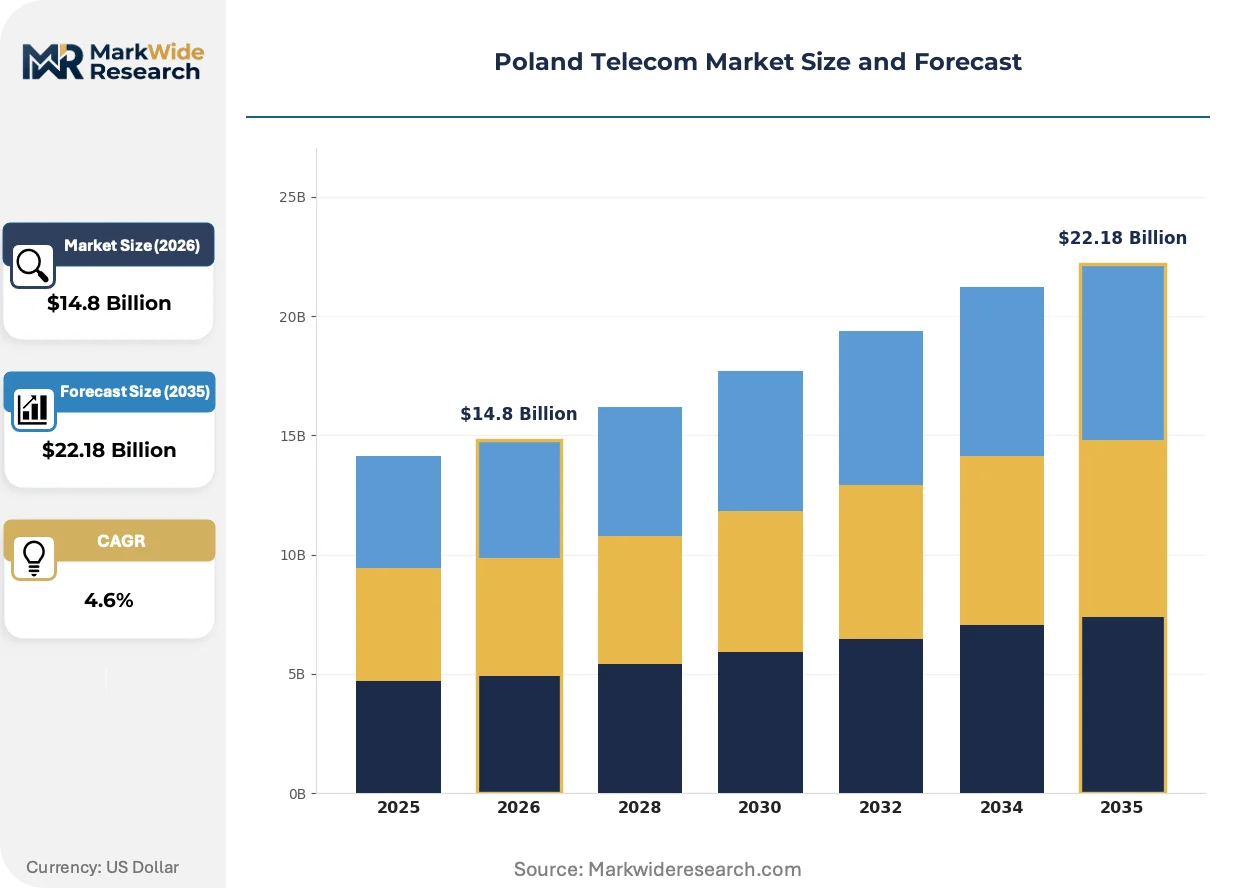
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile, Fixed Line, Broadband, VoIP Technology: 5G, LTE, Fiber Optic, DSL Customer Type: Residential, Small Business, Enterprise, Government Offering: Prepaid, Postpaid, Bundled Services, Unlimited Data |
| Companies Covered | Polkomtel, Netia, Orange Polska, Multimedia Polska, Vectra, Play Communications, Cyfrowy Polsat, Spectrum Poland, T-Mobile Polska, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Telecom Market Evolving Landscape
Software-defined architectures are dissolving traditional boundaries between hardware layers and service orchestration, enabling Polish operators to automate network operations while compressing time-to-market for differentiated enterprise offerings.
Virtualized radio access network functions are collapsing the distinction between baseband processing hardware and cloud-native software stacks. Polish mobile operators are deploying containerized RAN software on commodity servers in secondary cities. This architectural shift is collapsing capital requirements for network densification while accelerating feature deployment cycles.
GDPR enforcement by Poland's data protection authority is tightening consent requirements for location-based telecom analytics. Marketing departments must now implement granular opt-in mechanisms for subscriber data monetization. Enterprise IoT contracts are absorbing the most compliance scrutiny, with manufacturing clients demanding explicit data residency guarantees.
Subscription unbundling is fragmenting traditional triple-play bundles as Polish residential customers select standalone mobile data plans and over-the-top video services. Retail channels are responding with modular pricing tools that recombine connectivity, content, and device financing. This disaggregation is most pronounced among Warsaw apartment dwellers under age thirty-five.
Poland Telecom Market Segmentation
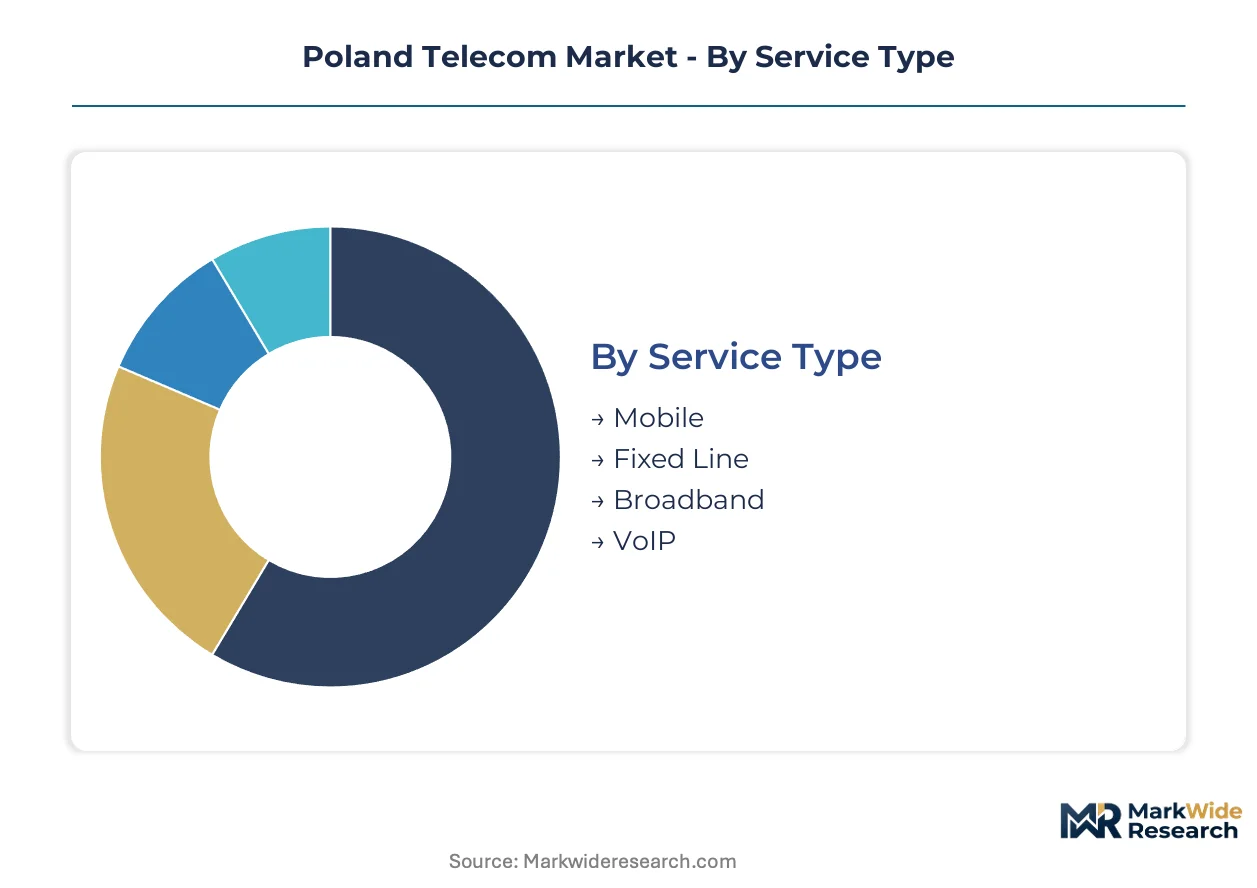
Segmentation reveals how capital allocation and margin structures diverge across the Polish telecom landscape. Each dimension exposes distinct competitive intensities and regulatory exposure profiles.
Service Type:
Service type captures revenue concentration across transmission modalities and subscription economics.
- Mobile:Cellular voice and data services operate across 700 MHz to 3.5 GHz spectrum allocations. Warsaw and the Silesian metropolitan area absorb the bulk of 5G network densification investment as manufacturing corridors demand ultra-reliable low-latency connectivity.
- Fixed Line:Traditional copper-based voice infrastructure delivers PSTN services with declining subscriber bases. Legacy DSL limitations force accelerated write-downs as bandwidth demands from cloud applications outstrip technical capacity.
- Broadband:High-speed internet access spans fiber-to-the-premises and cable modem technologies. EU Digital Cohesion funding accelerates rollout in underserved voivodeships, reducing deployment cost barriers for regional operators.
- VoIP:Packet-switched voice services ride over broadband infrastructure with lower per-minute economics. Small business adoption concentrates in urban centers where fiber penetration supports quality-of-service guarantees.
Mobile holds installed capacity. Broadband is rotating up the share rankings.
Technology:
Technology segmentation tracks infrastructure vintage and capital intensity across access network layers.
- 5G:New radio standards enable network slicing and massive MIMO antenna configurations. The Office of Electronic Communications' spectrum auction framework releases 3.5 GHz and 26 GHz bands for next-generation services, enabling urban coverage densification.
- LTE:Fourth-generation cellular technology provides fallback coverage and capacity in secondary cities. Rural Polish territories rely on LTE where fiber trenching costs consume disproportionate capital relative to subscriber density.
- Fiber Optic:Single-mode transmission infrastructure delivers rates exceeding 100 Gbps with minimal signal degradation. Last-mile deployment anchors capital intensity as operators replace copper infrastructure in residential and enterprise segments.
- DSL:Digital subscriber line technology leverages existing copper pairs with distance-limited bandwidth. Technical constraints prevent sustained delivery of 4K video and cloud application demands, forcing infrastructure obsolescence.
Fiber Optic commands deployment priority. 5G is climbing the fastest in capital allocation.
Customer Type:
Customer type stratifies margin profiles and contract complexity across consumption segments.
- Residential:Individual household subscriptions span voice, broadband, and entertainment bundles. Subscription unbundling fragments traditional triple-play offerings as Warsaw apartment dwellers under age thirty-five select standalone mobile data and over-the-top video.
- Small Business:Commercial establishments with limited IT staff require managed connectivity services. VoIP and basic broadband packages concentrate in urban centers with competitive pricing pressure from multiple access network providers.
- Enterprise:Large organizations contract dedicated infrastructure with stringent service-level agreements. Polish automotive and electronics factories contract 5G network slices for machine control, creating premium revenue streams with cybersecurity compliance requirements.
- Government:Public administration connectivity demands data residency guarantees and sovereign cloud integration. Municipal smart city tenders in Warsaw and Kraków bundle sensor networks with backhaul, absorbing the most compliance scrutiny under GDPR enforcement.
Enterprise holds pricing power. Residential is expanding most quickly in absolute connections.
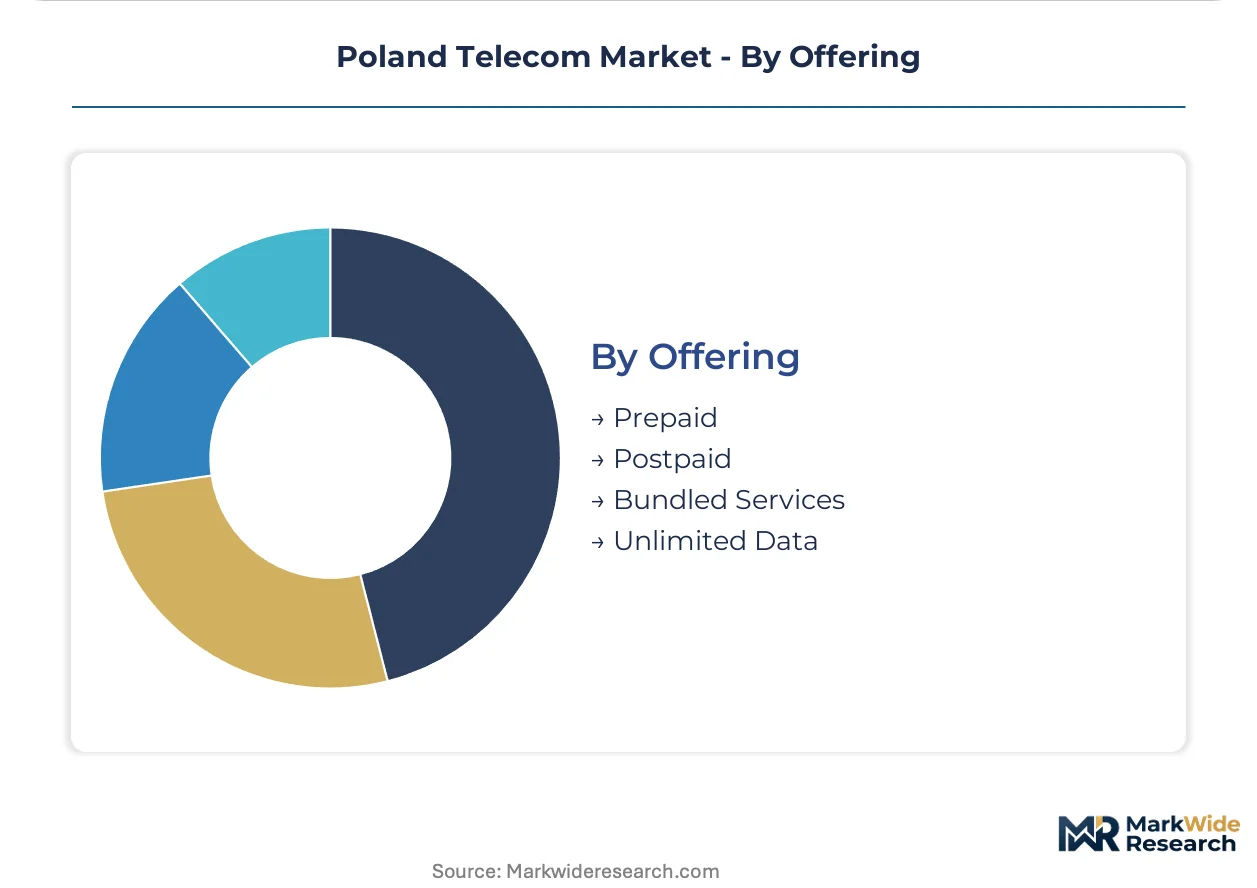
Offering:
Offering structure captures payment timing, commitment depth, and service packaging strategies.
- Prepaid:Advance payment for usage-capped services with no contractual obligation. Mobile data pricing competition from Play Communications concentrates subscriber acquisition in price-sensitive demographics.
- Postpaid:Monthly billing with minimum commitment terms and device financing integration. Orange Polska leverages incumbent infrastructure to sustain nationwide coverage leadership in this higher-loyalty segment.
- Bundled Services:Combined voice, broadband, and video subscriptions with volume discounts. Retail channels respond with modular pricing tools that recombine connectivity, content, and device financing for Warsaw metropolitan consumers.
- Unlimited Data:Flat-rate pricing for uncapped mobile consumption without overage exposure. Manufacturing corridor demand for 5G network slicing creates enterprise variants with quality-of-service prioritization.
Postpaid holds subscriber lifetime value. Unlimited Data is gaining share fastest in mobile plan migrations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in automotive and electronics manufacturing dominate telecom service procurement across Polish sub-regions, while residential demand concentrates in metropolitan corridors with fiber penetration.
Masovian Voivodeship
Warsaw's municipal smart city tenders bundle IoT sensor networks with backhaul infrastructure, creating integrated connectivity procurement opportunities. The Office of Electronic Communications enforces spectrum allocation rules that shape operator licensing costs in the capital region. Warsaw metropolitan fiber-to-the-premises deployment absorbs disproportionate capital investment relative to national subscriber density.
Silesian Voivodeship
Manufacturing corridors in Katowice and Gliwice contract dedicated 5G network slices for ultra-reliable low-latency machine control applications. EU Digital Cohesion funding accelerates infrastructure rollout in this historically industrial region. The Silesian metropolitan area anchors premium enterprise revenue streams with stringent service-level agreement requirements.
Lesser Poland Voivodeship
Kraków municipal government tenders integrated environmental monitoring and traffic management connectivity, bundling sensor deployments with municipal backhaul. GDPR enforcement by Poland's data protection authority tightens consent requirements for location-based analytics in this cultural center. Enterprise IoT contracts here absorb elevated compliance scrutiny with explicit data residency guarantees.
Podlaskie Voivodeship
Fiber subscription rates in Białystok and surrounding territories sit below half the national average, presenting first-mover expansion potential. EU-funded digital cohesion programs reduce deployment cost barriers for regional operators entering underserved eastern territories. Agricultural processing facilities in this border region generate emerging demand for rural broadband connectivity.
Pomeranian Voivodeship
Gdańsk port logistics and maritime services drive specialized connectivity requirements for supply chain digitization. The national broadband plan interacts with regional development strategies to prioritize infrastructure timing in this northern coastal cluster. Shipyard and container terminal operators contract dedicated enterprise infrastructure with cybersecurity compliance specifications.
Poland Telecom Market Competitive Landscape
Channel-controlling players compete with product-specialist players across infrastructure layers, producing a tiered structure where incumbent fiber operators face software-centric challengers. Orange Polska leverages nationwide coverage leadership while Play Communications drives mobile data pricing competition. Strategic archetypes include incumbent integrated operators, mobile-first challengers, and regional fiber specialists. Competitive moves center on fiber densification partnerships and Open RAN vendor diversification.
Among Poland-based operators, Orange Polska represents the incumbent integrated archetype with infrastructure depth across fixed and mobile segments. Play Communications occupies the mobile-first challenger position, while Netia exemplifies regional fiber specialization. These three anchors demonstrate how vendor strategies tilt from proprietary hardware stacks toward interoperable software-defined networks under Open RAN standards. Each sits within distinct capital intensity profiles shaped by legacy infrastructure vintage and spectrum position.
| Leading Market Players |
|---|
| Polkomtel |
| Netia |
| Orange Polska |
| Multimedia Polska |
| Vectra |
| Play Communications |
| Cyfrowy Polsat |
| Spectrum Poland |
| T-Mobile Polska |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Nordic and East Asian radio access network suppliers determines both pricing tier spreads and supply chain shape in Poland's telecom sector. Equipment vendor concentration exposes operators to geopolitical supply disruptions that widen premium-economy pricing gaps while forcing extended procurement cycles.
Pricing Analysis
Cost-plus contracts with Nordic and East Asian equipment vendors anchor Poland's infrastructure pricing, with indexation tied to euro-yen exchange movements and semiconductor component baskets. Three-tier pricing structure across premium, standard, and economy levels separates enterprise 5G network slicing from residential fiber and prepaid mobile tiers. Pricing pressure stems from Play Communications' aggressive mobile data competition, compressing subscriber acquisition costs in the prepaid segment. Enterprise and government contracts exhibit lowest price sensitivity due to cybersecurity compliance requirements and sovereign data residency mandates.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Nordic banking consortia ease working capital burdens for Polish operators deploying Open RAN infrastructure. Radio access network hardware concentrates in Finland, Sweden, South Korea, and Japan, while fiber optic cable draws from Chinese and German manufacturers. Critical dependencies include 5G massive MIMO antenna arrays, single-mode fiber strands, and cloud-native network function software. Tariff exposure on Chinese optical components presents structural vulnerability. Distribution runs through Warsaw-based system integrators and regional logistics hubs serving Silesian and Masovian deployment corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's telecom market demands substitution defense against over-the-top voice and video services that erode traditional carrier revenue streams. Incumbents must navigate this displacement threat while capitalizing on enterprise 5G and fiber densification cycles.
For Market Incumbents: Insulate core fiber infrastructure through backward integration into trenching and civil works capabilities, reducing exposure to subcontractor cost inflation. Secure Open RAN software partnerships with containerized network function vendors to diversify beyond proprietary hardware lock-in. Priority defensive moves center on locking enterprise 5G network slice contracts with automotive manufacturers in Silesia before mobile-first challengers establish presence. For New Entrants and Emerging Players: Podlaskie and Lublin provinces with fiber subscription rates below half the national average represent the most penetrable entry point for agile regional operators. EU Digital Cohesion funding reduces deployment cost barriers in these eastern voivodeships. Municipal smart city tenders in secondary cities offer bundled IoT connectivity procurement angles with lower incumbent saturation than Warsaw or Kraków. For Investors and Strategic Acquirers: The market sits at an infrastructure replacement phase that favors regional fiber specialists with disciplined capital deployment and Open RAN software capabilities. Long-term viability hinges on capturing enterprise-government contract mix above sixty percent of revenue. Watch the Office of Electronic Communications' spectrum auction timing as inflection indicator for 26 GHz band availability and urban densification economics.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Vendor Diversification | Reduces dependency on Nordic suppliers while accelerating feature deployment cycles for Polish operators. |
| Fiber-to-the-Premises Expansion | Captures EU Digital Cohesion subsidies in underserved Podlaskie and Lublin voivodeships. |
| Enterprise 5G Network Slicing | Locks premium revenue from Silesian automotive manufacturers requiring ultra-reliable low-latency connectivity. |
| Smart City Infrastructure Partnership | Bundles IoT sensor networks with municipal backhaul in Warsaw and Kraków tender processes. |
| Edge-Cloud Convergence Investment | Captures distributed compute value beyond pure connectivity for Polish manufacturing enterprises. |
Research Methodology
Operator-level perspectives from network engineering directors, procurement leads at mobile operators, municipal IT managers, and enterprise connectivity buyers anchored the qualitative base. Primary interviews combined with secondary validation from Office of Electronic Communications spectrum allocation filings, EU Digital Cohesion program disbursement records, and operator capex disclosures. Bottom-up subscriber and revenue modeling triangulated against top-down market size benchmarks.
Scenario-bracketing framed low, base, and high cases across the projection horizon, with segmentation dimensions spanning service type, technology vintage, customer archetype, and offering structure. CAGRs derived from infrastructure deployment run rates, spectrum auction timelines, and enterprise contract velocity. Forecast inputs incorporated Open RAN adoption curves and EU cohesion funding allocation patterns.
Stress conditions across equipment vendor concentration, euro-yen exchange volatility, and EU subsidy continuity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding spectrum release schedules and manufacturing corridor demand. Macroeconomic contraction, regulatory auction delays, or accelerated OTT substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
MVNO Market
Telecommunications
5G RAN Market
Telecommunications
Austria ICT Market
Telecommunications
Egypt Telecom Market
Telecommunications
Prepaid Communication Market
Telecommunications
5G Technology Market
Telecommunications
Kenya Telecom Market
Telecommunications
Belgium ICT Market
Telecommunications
Oman Telecom Market
Telecommunications
Satellite Broadband Communication in Public Safety Market
Telecommunications
Indonesia ICT Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
Voice Communication Control System Market
Telecommunications
Brazil Telecom Market
Telecommunications
Telecom Service Assurance Market
Telecommunications
Sri Lanka Telecom Market