
 Esim Subscription Market | 2026-2036
Esim Subscription Market Size, Share, and Industry Trends Forecast 2026-2036
Esim Subscription Market Foresight
GSMA's SGP.32 remote SIM provisioning standard is redrawing competitive boundaries for eSIM platform providers. Deutsche Telekom leverages its integrated carrier-grade infrastructure to dominate European enterprise subscriptions. Thales Group anchors the secure element supply chain through certified embedded UICC manufacturing.
An eSIM subscription constitutes a digitally provisioned cellular connectivity contract where operator credentials download over-the-air to a permanently soldered chip, typically operating within 2FF-4FF form factor equivalents or integrated MFF2 modules. The technology eliminates physical SIM swaps while enabling remote carrier switching across consumer and industrial devices. Smartphone subscriptions currently lead volume, yet IoT Device segments represent the fastest structural expansion as asset trackers and smart meters require zero-touch provisioning at scale. Corporate subscription types concentrate margin pools through multi-line managed connectivity contracts.
ETSI's M2M eSIM architecture and the EU Cybersecurity Act shape product certification requirements across European deployments, while the FCC governs device authorization for US eSIM-enabled hardware imports. India's TRAI mandates local data residency rules that constrain foreign MVNO platform operations. Stakeholders must monitor divergence between regional certification regimes when architecting unified subscription management platforms.
Market Dynamics
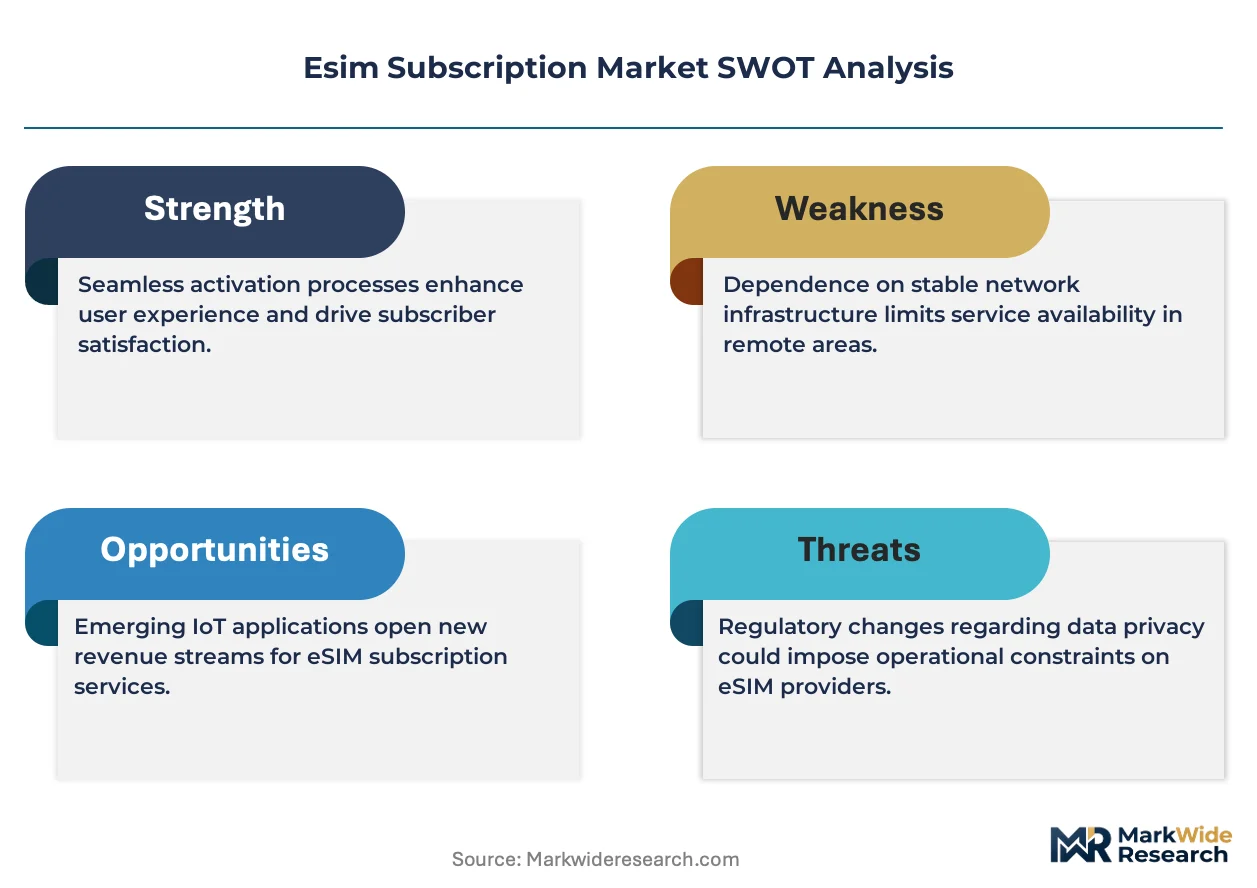
The GSMA's SGP.32 remote SIM provisioning standard is decomposing legacy carrier-lock business models by enabling seamless over-the-air carrier switching. This architectural shift forces platform providers to rebuild subscription orchestration layers around interoperability rather than proprietary control.
Growth Catalysts
- EU Cybersecurity Act mandates:Common Criteria certification requirements for cellular components create compliance-driven replacement cycles across European enterprise fleets.
- Automotive OEM embedded modules:Connected vehicle production lines in Germany and the United States now specify soldered eUICC chips as standard for telematics and OTA update pipelines.
- Zero-touch IoT provisioning:Asset tracker and smart meter deployments eliminate physical SIM logistics through remote credential management at manufacturing origin.
Market Restraints
- Secure element supply concentration:Certified embedded UICC manufacturing clusters in France and Germany create single-source vulnerability for platform operators.
- TRAI data residency rules:India's local storage mandates constrain foreign MVNO platforms from offering unified subscription management across South Asian operations.
- Legacy M2M infrastructure lock-in:ETSI's earlier eSIM architecture remains embedded in industrial installed bases, slowing migration to consumer-grade remote provisioning standards.
Strategic Opportunities
- Underpenetrated industrial asset tracking:Brazil's agribusiness and mining corridors present whitespace for satellite-backhauled eSIM deployments where terrestrial coverage fragments.
- Healthcare device convergence:Wearable patient monitors and remote diagnostic equipment combine cellular connectivity with FDA-mandated cybersecurity frameworks.
- Enterprise multi-line contracts:Corporate mobility managers seek consolidated billing across international employee pools, favoring platforms with carrier-agnostic orchestration.
Industry Challenges
- Certification timeline compression:Common Criteria evaluations for embedded UICC products extend 12-18 months, delaying product launches against software-only competitors.
- Integration complexity with legacy OSS/BSS:Tier-1 carriers must bridge SGP.32 provisioning APIs to decades-old billing and customer management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Esim Subscription Market |
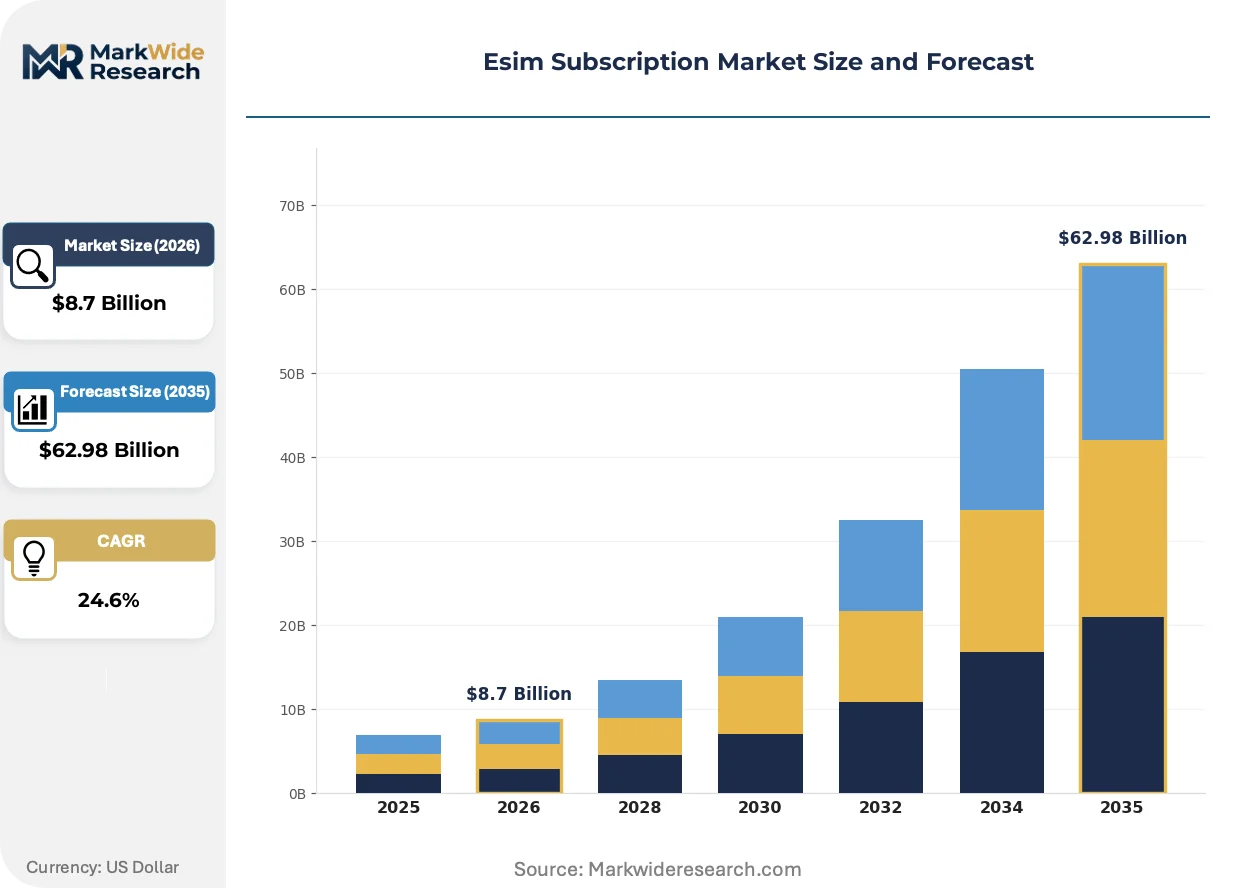
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Subscription Type: Postpaid, Prepaid, Hybrid, Corporate Device Type: Smartphone, Tablet, Wearable, IoT Device End User: Consumers, Enterprises, Government, M2M Service Provider: Telecom Operators, MVNOs, Multi-Brand, Others |
| Companies Covered | Deutsche Telekom AG, Telefónica, AT&T, Vodafone Group, Orange S.A., Giesecke+Devrient Mobile Security GmbH, Thales Group, Airalo, GigSky, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Esim Subscription Market Shifts & Advancements
Remote SIM provisioning architectures are fragmenting platform economics. The separation of subscription management from carrier core networks enables new intermediary layers, while regulatory mandates accelerate hardware security requirements.
Integrated secure elements with tamper-resistant hardware are decomposing the traditional smart card supply chain. Automotive OEMs in Stuttgart and Munich now specify MFF2 modules with pre-embedded credentials at vehicle assembly. This technology compression eliminates aftermarket SIM logistics while forcing semiconductor vendors to certify against both automotive AEC-Q100 and Common Criteria EAL4+ standards simultaneously.
REACH substance restrictions and the EU AI Act's cybersecurity annexes extend compliance obligations to connectivity hardware. Component suppliers must document conflict minerals and carbon footprint across embedded UICC supply chains. Medical device manufacturers face the strictest intersection, as FDA premarket submissions now incorporate FCC device authorization and ETSI security certifications in unified technical files.
Fleet procurement managers now demand consumption-based billing tied to actual data usage rather than fixed monthly rates. This unbundling disrupts traditional carrier prepaid models, particularly in German logistics and Dutch maritime sectors where asset utilization varies seasonally. Platforms offering real-time quota management and automatic carrier switching capture contract renewals from rigid incumbent providers.
Esim Subscription Market Segmentation
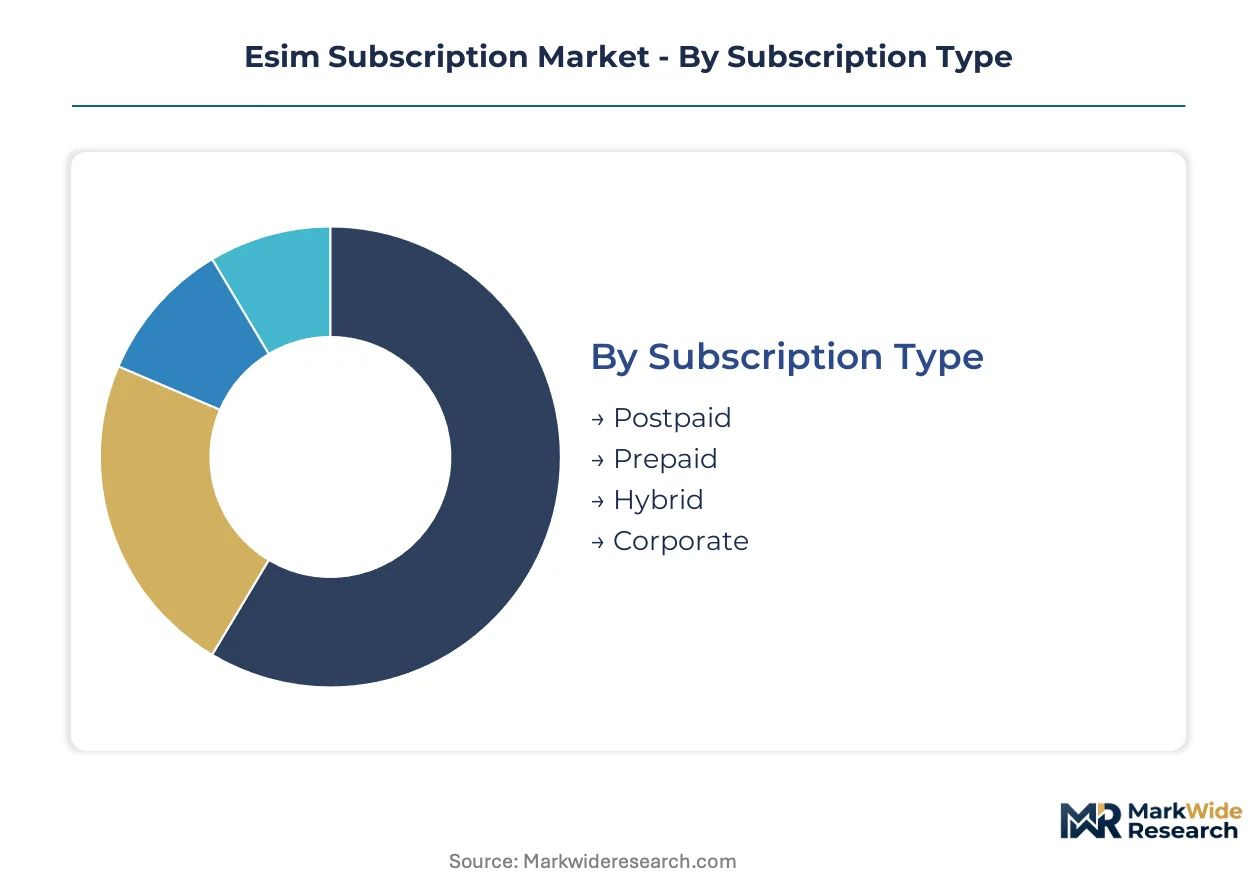
eSIM subscription architectures fragment along provisioning protocols and carrier integration models. Regulatory mandates from ETSI and the EU Cybersecurity Act create divergent certification requirements across segment boundaries, forcing platform providers to maintain parallel compliance tracks.
Subscription Type:
Regulatory differentiation separates consumer-grade remote provisioning from enterprise-managed connectivity contracts. Common Criteria certification requirements apply differentially based on subscription orchestration complexity and credential management scope.
- Postpaid:Monthly billing cycles with carrier-integrated credit verification dominate established consumer markets. Deutsche Telekom and Vodafone in Germany anchor volume through integrated carrier-grade infrastructure supporting seamless over-the-air carrier switching.
- Prepaid:Pay-in-advance models eliminate credit risk for platform operators while requiring real-time balance management. Demand concentrates in emerging markets where banking infrastructure lags, constrained by TRAI data residency rules in India.
- Hybrid:Flexible consumption models blend prepaid security with postpaid convenience. European logistics fleets favor these structures for seasonal asset utilization patterns.
- Corporate:Multi-line managed connectivity contracts consolidate billing across international employee pools. Margin pools concentrate here through carrier-agnostic orchestration platforms.
Established volume favors Postpaid; emerging adoption favors Corporate.
Device Type:
Application requirements drive hardware form factor selection and security certification tiers. Automotive and medical deployments demand AEC-Q100 and FDA-aligned frameworks respectively.
- Smartphone:2FF-4FF equivalent embedded UICC modules dominate current installation bases. Consumer electronics manufacturers in Asia-Pacific source from certified French and German secure element suppliers.
- Tablet:Larger form factors accommodate MFF2 modules with extended temperature ranges. Enterprise field service deployments in German manufacturing favor ruggedized variants.
- Wearable:Miniaturized secure elements face strict power budget constraints. Patient monitoring applications combine cellular connectivity with FDA-mandated cybersecurity frameworks, climbing the fastest among consumer-facing categories.
- IoT Device:Zero-touch provisioning at manufacturing origin eliminates physical SIM logistics. Asset trackers and smart meters in Brazilian agribusiness and mining corridors present whitespace where terrestrial coverage fragments.
Smartphone installations dominate current bases; IoT Device deployments show steepest expansion trajectory.
End User:
Customer type determines procurement complexity and contract duration. Government and M2M segments impose extended certification timelines that delay platform launches.
- Consumers:Individual subscribers prioritize seamless carrier switching and competitive data pricing. GSMA's SGP.32 standard enables interoperability that reduces switching friction.
- Enterprises:Corporate mobility managers demand consolidated billing across distributed workforces. German logistics and Dutch maritime sectors lead adoption of consumption-based billing tied to actual asset utilization.
- Government:Public sector contracts require Common Criteria EAL4+ certification and local data residency compliance. EU Cybersecurity Act mandates drive replacement cycles across European public fleets.
- M2M:Machine-to-machine deployments rely on ETSI's earlier eSIM architecture embedded in industrial installed bases. Migration to consumer-grade remote provisioning standards proceeds slowly due to legacy infrastructure lock-in.
Consumer volume anchors near-term revenue; M2M connectivity is gaining share fastest through industrial digitization.
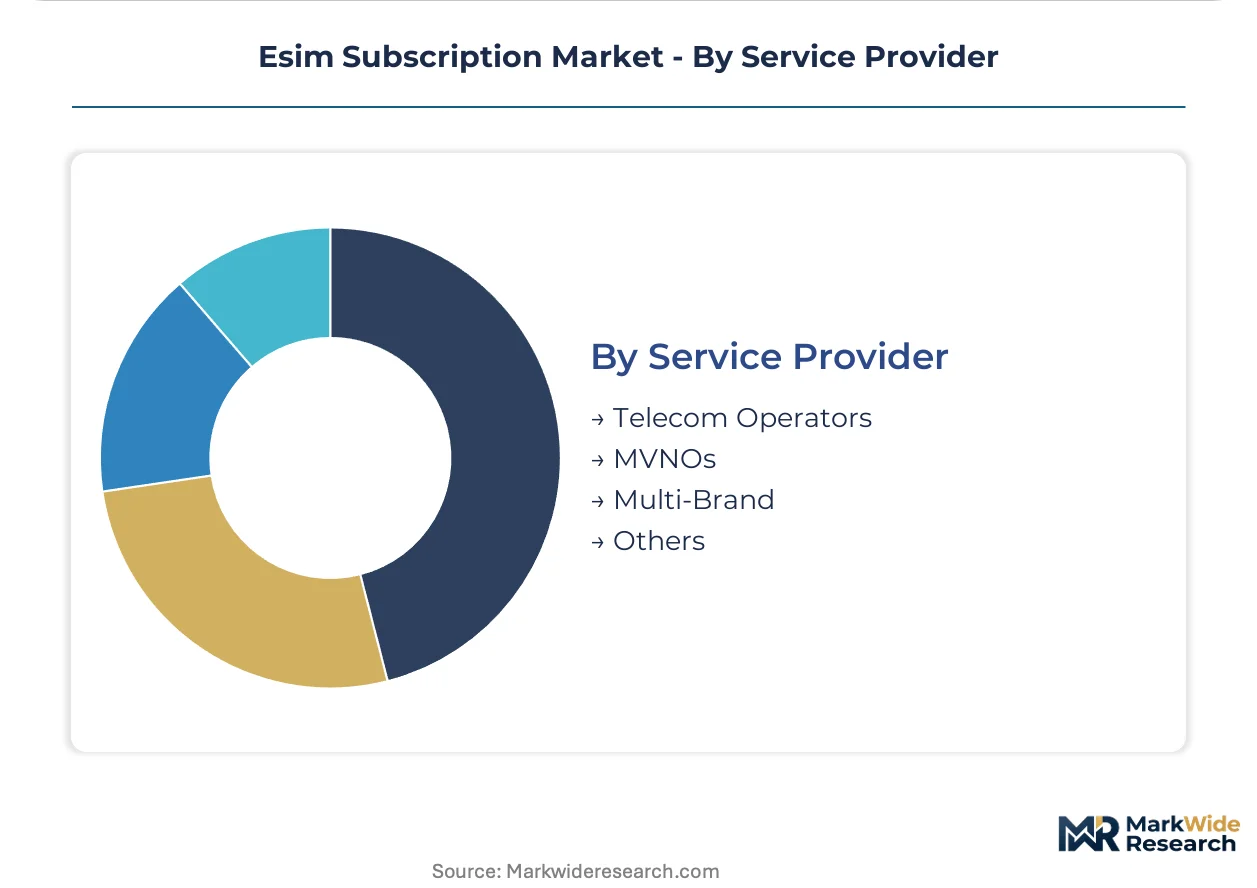
Service Provider:
Supply concentration shapes platform economics and geographic reach. Carrier integration depth determines provisioning API sophistication.
- Telecom Operators:Tier-1 carriers bridge SGP.32 provisioning APIs to decades-old OSS/BSS systems. Deutsche Telekom's integrated infrastructure dominates European enterprise subscriptions.
- MVNOs:Virtual operators rely on wholesale network access with limited core network control. India's TRAI local storage mandates constrain foreign MVNO platforms from unified South Asian operations.
- Multi-Brand:Aggregator platforms offer carrier-agnostic orchestration across multiple underlying networks. Enterprise multi-line contracts favor these intermediaries for international coverage.
- Others:Satellite-backhauled and specialized industrial connectivity providers serve coverage-gap segments. Brazilian mining corridors and maritime shipping lanes drive niche demand.
Telecom Operators retain established subscriber bases; Multi-Brand platforms capture emerging enterprise mobility contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government mandates for connected vehicle infrastructure and data residency requirements are redrawing geographic deployment patterns for eSIM subscription services. National regulators impose divergent certification timelines that fragment platform economics across borders.
Germany
Automotive OEMs in Stuttgart and Munich specify MFF2 modules with pre-embedded credentials for telematics and over-the-air update pipelines. The EU Cybersecurity Act mandates Common Criteria EAL4+ certification for cellular components deployed in public sector fleets. Deutsche Telekom and Vodafone operate dense M2M networks across North Rhine-Westphalia and Bavaria, anchoring European enterprise subscription volume.
United States
FCC device authorization governs eSIM-enabled hardware imports while automotive production lines specify soldered eUICC chips as standard. Tier-1 carriers bridge SGP.32 provisioning APIs to legacy OSS/BSS systems built over decades. Connected vehicle deployments concentrate in Michigan and California, where fleet managers demand consumption-based billing tied to actual asset utilization.
India
TRAI mandates local data residency rules that constrain foreign MVNO platforms from offering unified subscription management across South Asian operations. Pay-in-advance models eliminate credit risk for platform operators while requiring real-time balance management. Zero-touch IoT provisioning for smart meters and asset trackers expands through Gujarat and Maharashtra, constrained by banking infrastructure limitations in rural corridors.
Brazil
Satellite-backhauled eSIM deployments serve agribusiness and mining corridors where terrestrial coverage fragments across São Paulo and Minas Gerais. ANVISA certification requirements intersect with connectivity hardware for remote patient monitoring applications. Platform operators capture whitespace in industrial asset tracking as logistics fleets seek automatic carrier switching for seasonal utilization patterns.
Japan
METI industrial digitization programs accelerate M2M migration from ETSI's earlier eSIM architecture to consumer-grade remote provisioning standards. Wearable patient monitors combine cellular connectivity with PMDA-mandated cybersecurity frameworks. Manufacturing clusters in Aichi and Osaka prefectures drive demand for ruggedized MFF2 modules with extended temperature ranges.
Esim Subscription Market Competitive Landscape
Listed leaders compete with private specialists across carrier integration depth and secure element manufacturing. The vendor base separates into integrated telecom operators, secure element fabricators, and digital-native connectivity aggregators. Three archetypes dominate: carrier-grade infrastructure owners, certified hardware security suppliers, and software-only provisioning platforms. Strategic moves concentrate on bridging SGP.32 APIs to legacy billing systems and securing Common Criteria certification for embedded UICC products.
Within the carrier-grade tier, Deutsche Telekom AG and Vodafone Group exemplify integrated infrastructure owners with dense M2M network footprints. Among secure element specialists, Thales Group and Giesecke+Devrient Mobile Security GmbH occupy positions anchoring certified embedded UICC manufacturing. At the digital-native vector, Airalo and GigSky represent carrier-agnostic orchestration platforms targeting international mobility use cases. Each archetype faces distinct compliance timelines and carrier dependency structures.
| Leading Market Players |
|---|
| Deutsche Telekom AG |
| Telefónica |
| AT&T |
| Vodafone Group |
| Orange S.A. |
| Giesecke+Devrient Mobile Security GmbH |
| Thales Group |
| Airalo |
| GigSky |
| Others |
Supply & Pricing Matrix
Common Criteria certification timelines gate both supplier qualification and price differentiation simultaneously across European deployments. EAL4+ evaluations extending 12-18 months compress the qualified supplier pool while embedding compliance costs into premium-tier pricing for automotive and government segments.
Pricing Analysis
Certification level creates the primary spread between premium EAL4+ certified modules and standard commercial-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects Common Criteria tier, volume commitment scale, and after-sales credential management bundling. Cost compression in the standard tier is intensifying because software-only provisioning platforms bypass hardware security certification delays. Enterprise mobility managers show lowest price sensitivity given compliance mandates, while prepaid consumer segments in emerging markets drive hardest bargain on per-megabyte rates.
Supply Chain Analysis
Inventory lead times for certified embedded UICC products stretch 6-9 months due to constrained fab capacity at Common Criteria-accredited facilities. Manufacturing concentrates in France and Germany where Thales Group and Giesecke+Devrient operate certified secure element foundries. Raw material dependencies include silicon wafers, tamper-resistant substrates, and cryptographic processor cores. Single-source vulnerability runs through French certification labs for automotive AEC-Q100 qualification. Distribution runs through carrier-direct procurement for Tier-1 operators and aggregator platforms for enterprise multi-line contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified secure element fabrication capacity is tightening faster than platform orchestration talent, creating asymmetric scarcity that favors incumbents with captive certification relationships. This capability gap widens as automotive OEMs mandate pre-embedded credentials at vehicle assembly origin.
For Market Incumbents: Shield carrier-grade infrastructure investments by accelerating Common Criteria certification pipelines for next-generation MFF2 modules before software-only competitors close the security gap. Prioritize backward integration into secure element manufacturing through joint ventures with French and German fabricators to lock in fab allocation. Defend enterprise subscription margins by embedding consumption-based billing APIs directly into automotive telematics platforms. For New Entrants and Emerging Players: Differentiate on satellite-backhauled connectivity orchestration for Brazilian agribusiness and mining corridors where terrestrial coverage fragments and incumbent M2M networks underpenetrate. Target healthcare device convergence in Japan and Germany where FDA and PMDA cybersecurity frameworks create compliance moats too steep for carrier-agnostic aggregators. Lead with zero-touch provisioning at manufacturing origin to bypass legacy OSS/BSS integration complexity that slows Tier-1 carrier sales cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across certified embedded UICC manufacturing as automotive AEC-Q100 and Common Criteria EAL4+ dual qualification requirements layer capital equipment demands. Long-term viability hinges on owning compliance relationships rather than software scale. Acquisition targets should display simultaneous FCC device authorization and EU Cybersecurity Act certification track records. Monitor SGP.32 migration velocity in Japanese manufacturing clusters as the signal for platform economics inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Common Criteria Certification Acceleration | Shortens 12-18 month EAL4+ timelines to capture automotive OEM qualification windows. |
| Satellite-Backhauled IoT Expansion | Captures Brazilian agribusiness whitespace where terrestrial coverage fragments. |
| Consumption-Based Billing Platform | Aligns pricing with German logistics fleet utilization patterns to displace rigid prepaid models. |
| Healthcare Cybersecurity Convergence | Combines cellular connectivity with FDA-mandated frameworks for wearable patient monitors. |
| Carrier-Agnostic Orchestration Layer | Enables enterprise multi-line contracts across international employee pools through SGP.32 APIs. |
Research Methodology
A spread of perspectives from eSIM platform architects, secure element procurement leads at automotive OEMs, carrier enterprise sales directors, and regulatory compliance officers converged on the working assumptions. Primary interviews with Deutsche Telekom and Vodafone network operations teams supplemented secondary validation through GSMA technical specifications, ETSI documentation, EU Cybersecurity Act implementation guidance, and FCC device authorization filings. Bottom-up subscription volume estimates triangulated against top-down connectivity revenue projections.
Segmentation dimensions modeled include subscription type, device form factor, end-user category, and service provider integration depth across the analysis window. CAGRs derived from fitted growth curves incorporating automotive production line eSIM adoption rates, IoT device manufacturing origin provisioning penetration, and enterprise mobility contract renewal velocity. Forecast inputs weighted GSMA SGP.32 migration timelines and TRAI data residency rule enforcement intensity.
Material uncertainties — regulatory divergence between EU Cybersecurity Act and FCC device authorization pathways, secure element fab capacity constraints, and legacy M2M infrastructure lock-in — sit outside the modeled envelope. Forecasts reflect assumptions about standardization velocity and certification timeline compression. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Malaysia Telecom Towers Market
Telecommunications
Mexico Telecom Market
Telecommunications
Optical Network Terminal (ONT) Equipment Market
Telecommunications
Iran Telecom Market
Telecommunications
Australia Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Global Telecom Operations Management Market
Telecommunications
Thailand ICT Market
Telecommunications
Digital Mobile Radio (DMR) Market
Telecommunications
Software Defined Radio Market
Telecommunications
International Wholesale Voice Carrier Market
Telecommunications
Managed Mobility Services (MMS) Market
Telecommunications
Global Policy Management in Telecom Market
Telecommunications
GPON Market
Telecommunications
Telecom API Platform Market
Telecommunications
South Korea Telecom Market
Telecommunications
Philippines Telecom Market