
 Chile Telecom Market | 2026-2036
Chile Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Telecom Market Analysis
Enterprise buyer concentration in Chile is broadening as mining conglomerates and port logistics operators diversify vendor relationships beyond traditional carriers. Entel Chile leverages its northern territory infrastructure to anchor wholesale connectivity contracts with extractive industries. Telefónica Chile SA competes through integrated cloud and cybersecurity bundles aimed at mid-market enterprises. Claro Chile differentiates via aggressive fiber-to-the-home expansion in Santiago's peripheral municipalities.
Chile telecom encompasses voice, data, and internet services delivered through terrestrial and wireless infrastructure operating across 700 MHz to 3.5 GHz spectrum bands with fiber backhaul requirements exceeding 10 Gbps in core nodes. Mobile service revenue still leads total market value, though fiber optic broadband represents the fastest-expanding technology segment as SUBTEL's fiberization mandates push operators past DSL legacy networks. Residential customer segments dominate subscriber counts, yet large enterprises generate disproportionate margin pools due to customized SLA requirements and private network deployments.
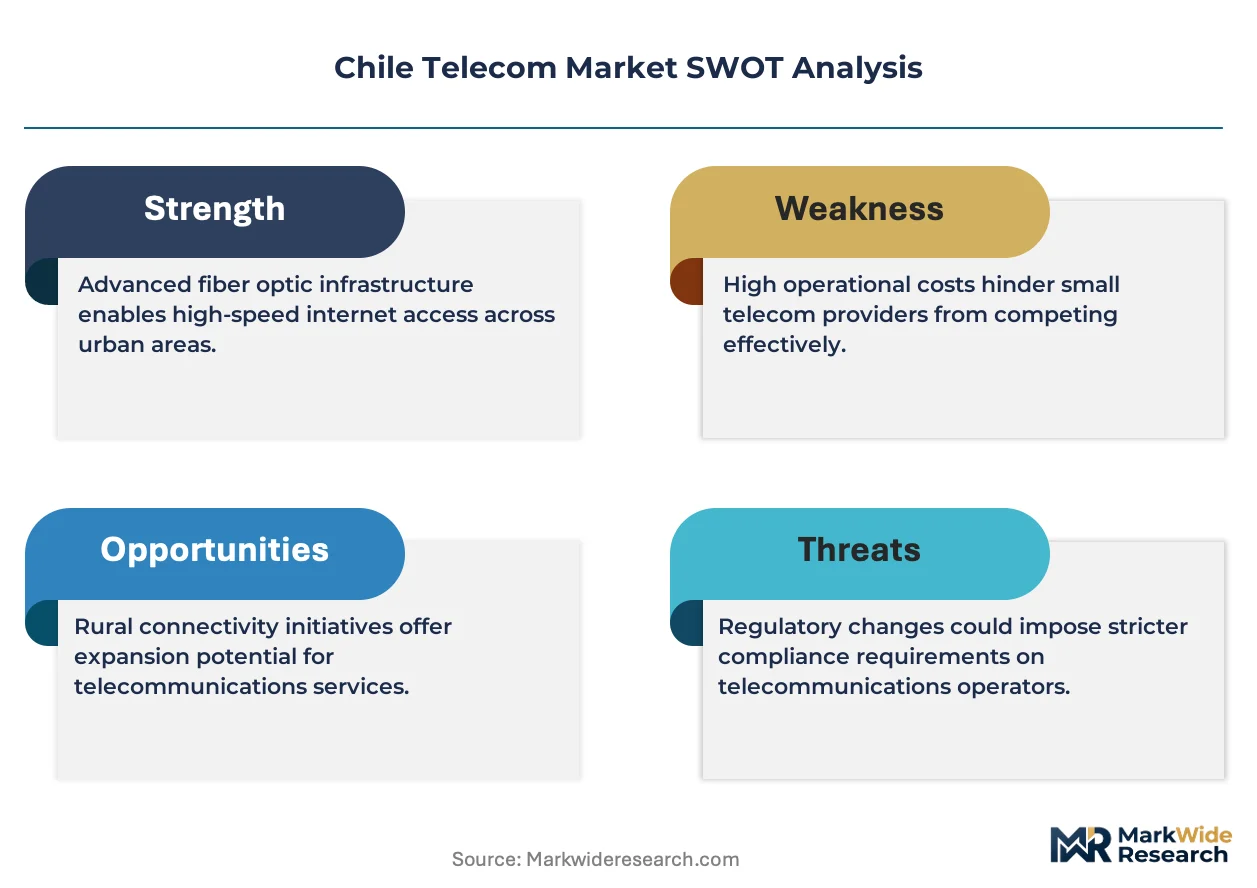
SUBTEL governs spectrum allocation and interconnection rules, while the country's competition authority monitors wholesale pricing and infrastructure sharing obligations to prevent dominant carrier leverage. Chile's 5G rollout timeline and SUBTEL's ongoing spectrum redistribution proceedings will determine which operators secure capacity for industrial IoT and smart mining applications. Stakeholders must track regulatory rulings on passive infrastructure sharing and tower divestiture requirements that could reshape deployment economics for regional challengers.
Market Dynamics
SUBTEL's spectrum redistribution proceedings are compressing deployment timelines while mining operators demand private 5G networks, forcing carriers to reallocate capital from consumer fiber toward industrial infrastructure.
Growth Catalysts
- Antofagasta Mining Corridor:Copper and lithium extraction operators are commissioning dedicated fiber routes and microwave backhaul to support autonomous haulage systems. SUBTEL's infrastructure sharing mandates reduce duplication costs for last-mile extensions into pit operations.
- Fiberization Mandates:SUBTEL's regulatory push to decommission copper DSL networks by fixed deadlines accelerates operator migration to GPON and XGS-PON platforms. Residential broadband ARPU improvements fund enterprise network expansion.
- Industrial IoT Protocols:3GPP Release 16 capabilities for ultra-reliable low-latency communication enable precision blasting and remote equipment monitoring. Mining safety regulations now specify redundant connectivity for underground operations.
Market Restraints
- Copper Cable Retirement Costs:Legacy DSL infrastructure decommissioning imposes stranded asset write-downs and customer migration expenses that compress near-term margins before fiber ARPU benefits materialize.
- Santiago Infrastructure Saturation:Rights-of-way congestion in dense metropolitan zones delays permitting for new fiber trenches, forcing reliance on aerial deployment with weather vulnerability.
- Optical Component Import Dependency:Chile lacks domestic manufacturing of 100G+ coherent optics and DWDM multiplexers, exposing deployment schedules to Asian supply chain volatility and currency fluctuation.
Strategic Opportunities
- Magallanes Submarine Cable Landings:Southern Patagonia's emerging status as a trans-Pacific cable landing zone creates wholesale capacity arbitrage opportunities for backhaul into Argentine and Brazilian markets.
- Smart Port Logistics:Valparaíso and San Antonio container terminals are piloting private LTE networks for crane automation and yard management, opening systems integration contracts beyond pure connectivity.
- Convergence of Edge Computing and 5G:Mining operators require localized data processing for real-time video analytics and predictive maintenance, creating demand for carrier-hosted multi-access edge computing nodes.
Industry Challenges
- RF Engineer Scarcity:5G massive MIMO and millimeter-wave deployment require specialized radio frequency planning expertise that outpaces Chilean technical university output, forcing reliance on expensive foreign contractors.
- Passive Infrastructure Unbundling:SUBTEL's tower divestiture and dark fiber access rules fragment network ownership, complicating end-to-end SLA guarantees and fault isolation procedures for enterprise contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Telecom Market |
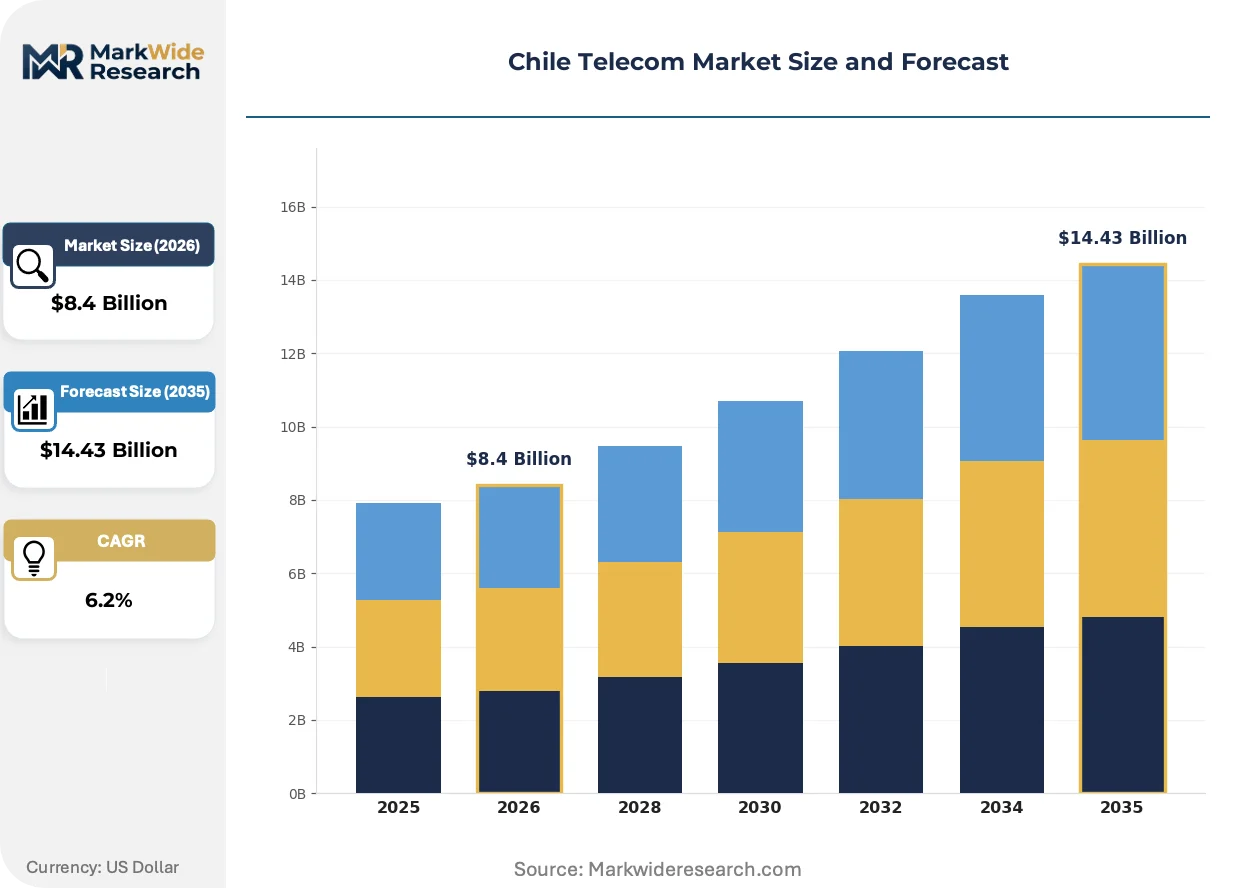
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile, Fixed-Line, Broadband, VoIP Technology: 4G LTE, 5G, DSL, Fiber Optic Customer Type: Residential, Business, Government, Large Enterprises Distribution Channel: Direct Sales, Retail, Online, Third-Party Resellers |
| Companies Covered | WOM Chile, Almendral SA, Entel Chile, GTD Grupo Teleductos SA, Telefónica Chile SA, Movistar Chile, Empresa Nacional de Telecomunicaciones SA, VTR FINANCE NV, Claro Chile, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Telecom Market Emerging Trajectories
Open RAN architectures are disrupting traditional vendor lock-in, while SUBTEL's spectrum policies accelerate industrial network specialization beyond consumer mobile services.
XGS-PON fiber technology is overtaking GPON as the default access platform for new Santiago deployments. Mid-density residential compounds and small business parks are specifying symmetric 10 Gbps capability to support cloud PBX and video surveillance backhaul. This capability compression is collapsing the historical segmentation between residential and entry-level enterprise service tiers.
SUBTEL's infrastructure sharing obligations now require dominant carriers to publish reference offers for tower colocation and dark fiber access. These rules reduce barriers for regional challengers entering the Antofagasta and Tarapacá mining zones. Wholesale pricing transparency is forcing incumbents to defend enterprise relationships through service-level customization rather than physical network exclusivity.
Enterprise procurement of connectivity services now separates network infrastructure from managed security and cloud integration. Mining operators are issuing RFPs that unbundle transport, CPE, and professional services, enabling multi-vendor architectures. This unbundling is most advanced among copper and lithium conglomerates operating in the Atacama Desert extraction zones.
Chile Telecom Market Segmentation
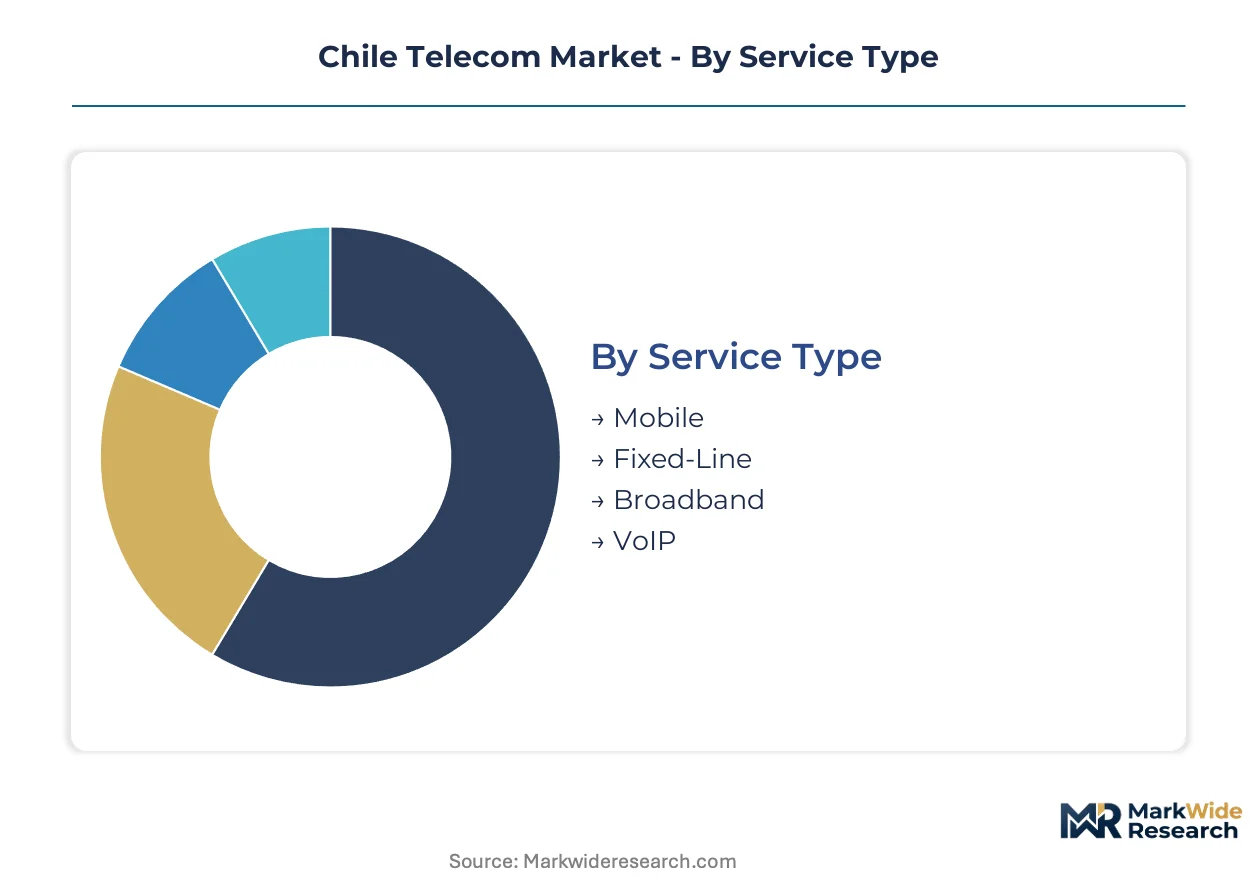
Segmentation in Chile's telecom market reveals how SUBTEL's regulatory mandates and mining corridor demand reshape operator investment priorities across service tiers. Distinct technology and customer boundaries are collapsing as fiberization accelerates and enterprise procurement unbundles transport from managed services.
Service Type:
Supply concentration in mobile and broadband services dominates revenue pools, while fixed-line and VoIP segments face diverging infrastructure economics under SUBTEL's copper retirement deadlines.
- Mobile:Voice and data services delivered over 700 MHz to 3.5 GHz spectrum bands with 5G NSA and SA architectures. Antofagasta mining operators commission private network slices for autonomous haulage, compressing carrier deployment timelines.
- Broadband:Internet access via fiber, cable, and fixed-wireless technologies. Santiago's peripheral municipalities drive GPON-to-XGS-PON upgrades as SUBTEL mandates decommission legacy DSL by fixed deadlines.
- Fixed-Line:Traditional PSTN voice services over copper infrastructure. Stranded asset exposure concentrates in rural zones where fiber overbuild economics remain marginal.
- VoIP:Packet-switched voice over IP networks with cloud PBX integration. Mid-market enterprises in Valparaíso and Concepción unbundle voice from transport contracts.
Today's leader: Broadband. Tomorrow's challenger: Mobile.
Technology:
Cost tier stratification separates premium 5G and fiber deployments from legacy DSL maintenance burdens, with 4G LTE occupying an intermediate position as rural coverage backstop.
- 5G:New radio architectures in sub-6 GHz and millimeter-wave bands with massive MIMO antenna configurations. Industrial IoT protocols for precision blasting and remote monitoring concentrate demand in the Atacama extraction zones.
- Fiber Optic:GPON, XGS-PON, and point-to-point Ethernet delivering symmetric 10 Gbps capability. Santiago's rights-of-way congestion forces aerial deployment with weather vulnerability.
- 4G LTE:Mature radio access network technology with carrier aggregation. Smart port logistics pilots at San Antonio container terminal create private LTE systems integration demand.
- DSL:Copper-based broadband over legacy telephone infrastructure. Customer migration expenses and stranded asset write-downs compress near-term margins before fiber ARPU benefits materialize.
Today's leader: Fiber Optic. Tomorrow's challenger: 5G.
Customer Type:
Margin concentration pools disproportionately with large enterprises due to customized SLA requirements, while residential volume funds infrastructure amortization.
- Large Enterprises:Mining conglomerates and port logistics operators procuring private networks with redundant connectivity. Copper and lithium extraction zones in Antofagasta and Tarapacá unbundle transport, CPE, and professional services.
- Business:Mid-market enterprises purchasing integrated cloud and cybersecurity bundles. Telefónica Chile SA targets this tier with managed service differentiation.
- Residential:Individual households consuming mass-market broadband and mobile services. Subscriber counts dominate but ARPU compression limits margin contribution.
- Government:Public sector procurement of secure connectivity and emergency communications. SUBTEL's infrastructure sharing mandates reduce duplication costs for last-mile extensions.
Today's leader: Large Enterprises. Tomorrow's challenger: Business.
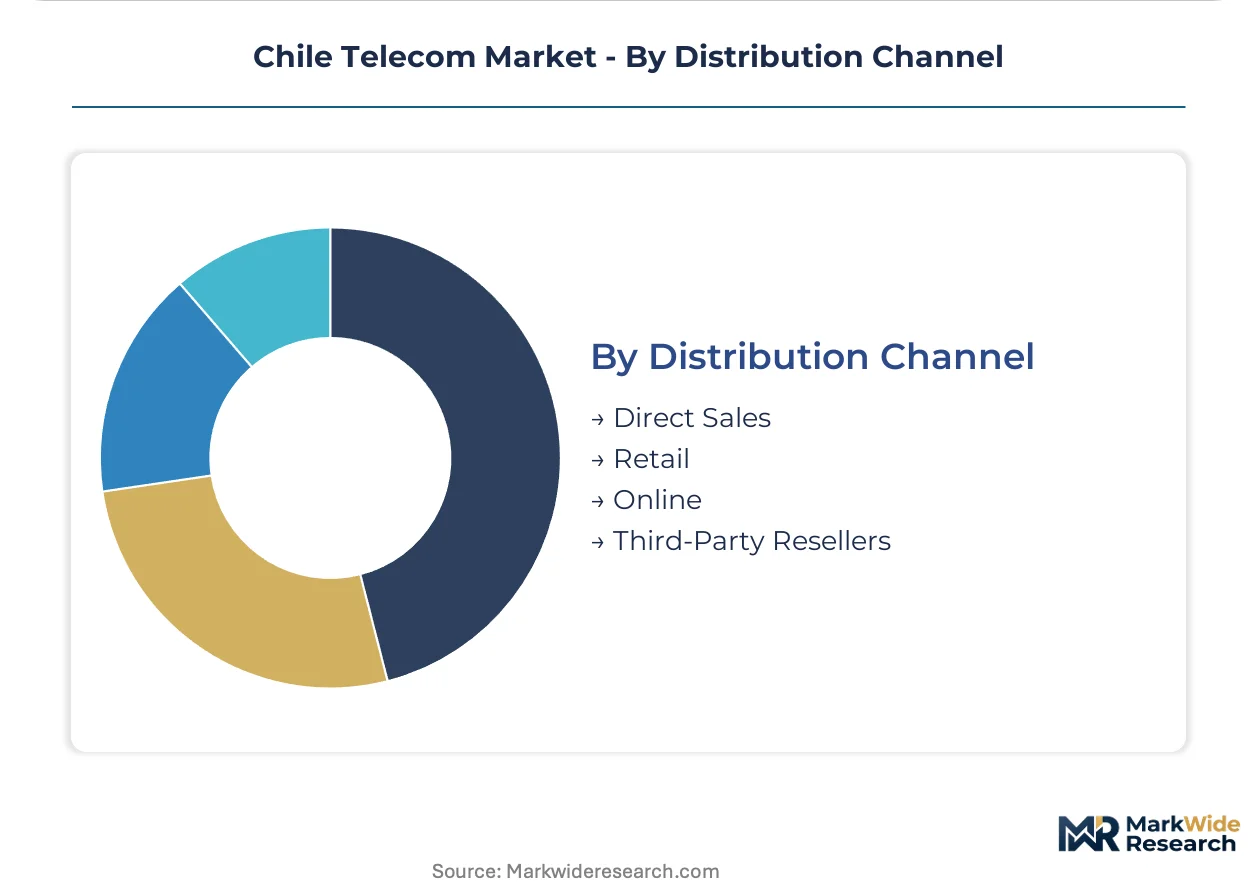
Distribution Channel:
Volume flows through retail and direct sales, while online and third-party resellers gain traction as enterprise procurement digitizes and regional challengers enter mining zones.
- Direct Sales:Carrier account teams managing enterprise relationships with customized SLA negotiation. Mining operators in the Atacama Desert specify redundant connectivity for underground operations through direct procurement.
- Retail:Branded storefronts and authorized dealer networks serving residential and small business segments. Claro Chile leverages retail presence for aggressive fiber-to-the-home expansion.
- Online:Digital self-service portals for plan selection and provisioning. Mid-density residential compounds specify symmetric capability through automated configuration.
- Third-Party Resellers:Independent agents and systems integrators bundling connectivity with vertical applications. Wholesale pricing transparency enables regional challengers to defend enterprise relationships through service customization.
Today's leader: Direct Sales. Tomorrow's challenger: Third-Party Resellers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's telecom infrastructure lags Chile's fiber density despite comparable mining economies, while Peru's Andean corridor attracts parallel investment from logistics operators seeking redundant connectivity paths. Both countries illustrate how regulatory frameworks and geographic constraints shape divergent deployment trajectories across South America's Pacific economies.
Argentina
Copper and lithium extraction in Catamarca and Salta provinces drives demand for private LTE networks and satellite backhaul redundancy. The country's national communications regulator enforces infrastructure sharing mandates similar to Chile's SUBTEL framework, though implementation timelines lag by 18-24 months. Buenos Aires concentrates wholesale data center investment while Mendoza's wine export logistics cluster pilots IoT-enabled cold chain monitoring.
Peru
Alpaca fiber cooperatives and quinoa export logistics in Arequipa and Cusco generate unexpected demand for rural broadband backhaul. The Ministry of Transport and Communications accelerates 4G rural coverage obligations through reverse auction mechanisms. Lima's port modernization at Callao competes with Chile's Valparaíso for trans-Pacific cable landing capacity, creating wholesale arbitrage opportunities for Andean corridor operators.
Brazil
Iron ore extraction in Minas Gerais and Pará states consumes massive private network bandwidth for autonomous haulage systems. Anatel's 5G spectrum auction structure prioritizes industrial IoT applications over consumer mobile density, diverging from Chile's enterprise-first approach. São Paulo's financial district anchors submarine cable landings from Angola and the United States, creating latency advantages for Atlantic-facing financial services.
Colombia
Emerald mining in Boyacá and coal extraction in La Guajira require ruggedized connectivity for pit operations and worker safety compliance. The National Spectrum Agency redistributes 700 MHz band capacity originally allocated to failed broadcast television projects. Bogotá's cloud services market concentrates demand for low-latency fiber routes to Cartagena's Caribbean cable landing stations.
Mexico
Automotive manufacturing clusters in Nuevo León and Guanajuato generate enterprise connectivity demand rivaling Chile's mining sector in revenue per site. IFT's wholesale open fiber rules force dominant carriers to unbundle last-mile infrastructure, creating regulatory precedent watched closely by SUBTEL officials. Mexico City's metro area saturates with 5G small cell deployment while Yucatán's data center tax incentives attract hyperscale cloud operators.
Chile Telecom Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across Chile's telecom value chain, creating a tiered structure where scale advantages in infrastructure clash with agility in vertical service customization. The market consolidates around three to four dominant carriers controlling fiber backbone and mobile spectrum, while regional challengers exploit wholesale access rules to penetrate mining corridor contracts. Strategic archetypes include integrated fixed-mobile operators, wholesale infrastructure specialists, and managed services integrators. Competitive intensity manifests through fiber-to-the-home expansion races in Santiago's periphery and private 5G network bidding wars in Antofagasta.
Among Chile-based operators with extensive northern territory infrastructure, Entel Chile occupies a position exemplifying the integrated carrier archetype, leveraging historical mining relationships to anchor enterprise contracts. Telefónica Chile SA represents the multinational subsidiary model, competing through bundled cloud and cybersecurity offerings rather than pure connectivity. Claro Chile sits within the aggressive residential expansion tier, prioritizing fiber-to-the-home penetration in Santiago's underserved municipalities. GTD Grupo Teleductos SA anchors the wholesale specialist segment, focusing on dark fiber and backhaul services rather than end-user retail relationships.
| Leading Market Players |
|---|
| WOM Chile |
| Almendral SA |
| Entel Chile |
| GTD Grupo Teleductos SA |
| Telefónica Chile SA |
| Movistar Chile |
| Empresa Nacional de Telecomunicaciones SA |
| VTR FINANCE NV |
| Claro Chile |
| Others |
Supply Flow & Price Mechanics
Optical component costs originating in Asian manufacturing hubs cascade through Chile's telecom value chain, compressing margins for XGS-PON deployments while SUBTEL's fiberization mandates accelerate demand for coherent 100G+ transceivers. This input-cost pressure stratifies final service pricing across residential, business, and mining enterprise tiers.
Pricing Analysis
Capacity additions in Santiago's peripheral municipalities are reshaping price floors for fiber broadband as Claro Chile and Entel Chile overbuild GPON infrastructure. Three-tier pricing structure across premium, standard, and economy levels prevails, with differentiation driven by symmetric speed tiers and SLA guarantees. Cost compression in residential segments is intensifying because wholesale dark fiber access rules erode physical network exclusivity. Mining enterprises exhibit least price sensitivity due to customized private network requirements, while residential subscribers in Santiago's saturated zones drive hardest bargain negotiations.
Supply Chain Analysis
SUBTEL's infrastructure sharing mandates are reshaping sourcing patterns by fragmenting network ownership and forcing carriers to unbundle tower and fiber assets. Optical component supply concentrates in China, South Korea, and Japan for coherent optics and DWDM multiplexers. Deployment schedules hinge on Asian manufacturing lead times and peso-dollar exchange volatility. Single-source vulnerability concentrates in 100G+ coherent transceiver supply. Distribution runs through carrier-direct procurement for enterprise contracts and retail dealer networks for residential subscriber acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's telecom market offers margin expansion through fiber ARPU uplift as SUBTEL's copper retirement deadlines force subscriber migration to higher-value XGS-PON tiers.
For Market Incumbents: Extend infrastructure sharing compliance into competitive advantage by publishing transparent wholesale reference offers that preempt regulatory penalties while capturing enterprise relationships through SLA customization rather than physical exclusivity. Defend against regional challengers exploiting SUBTEL's tower divestiture rules by accelerating proprietary fiber deployment in Antofagasta mining corridors before wholesale access obligations expand. Prioritize backward integration into edge computing node hosting to capture mining operator demand for localized data processing. For New Entrants and Emerging Players: Launch via third-party reseller and systems integrator channels to penetrate copper and lithium extraction zones in Tarapacá and Atacama Desert where incumbent relationships remain unconsolidated. Target private 5G network slices for autonomous haulage systems as the most penetrable enterprise segment, given compressed carrier deployment timelines and RF engineering scarcity. Exploit wholesale pricing transparency mandated by SUBTEL to undercut incumbents on transport while differentiating through vertical application bundling. For Investors and Strategic Acquirers: Roll-up economics work for wholesale infrastructure specialists because SUBTEL's passive infrastructure unbundling fragments network ownership and creates acquisition targets with contracted dark fiber and backhaul revenue streams. Focus on 5-10 year viability windows where fiberization mandates guarantee replacement demand for legacy copper infrastructure. Monitor SUBTEL spectrum redistribution rulings as the inflection signal determining which operators secure industrial IoT capacity for smart mining applications.| Strategic Initiative | Industry Significance |
|---|---|
| XGS-PON Network Upgrade | SUBTEL's fiberization mandates accelerate subscriber migration from DSL to symmetric 10 Gbps capability. |
| Private 5G Network Deployment | Antofagasta mining operators commission dedicated slices for autonomous haulage and precision blasting systems. |
| Edge Computing Node Hosting | Carrier-hosted MEC infrastructure captures mining demand for real-time video analytics and predictive maintenance. |
| Wholesale Infrastructure Unbundling | SUBTEL's tower divestiture rules create dark fiber and colocation revenue streams for specialist operators. |
| Industrial IoT Systems Integration | Valparaíso and San Antonio port logistics pilots open contracts beyond pure connectivity into crane automation. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining discussions with network planning engineers at dominant carriers, procurement leads at mining conglomerates, SUBTEL regulatory officials, and systems integrators serving port logistics operators with secondary validation. Regulatory filings from SUBTEL spectrum proceedings, carrier capex disclosures, and infrastructure deployment permits anchored the quantitative foundation. Bottom-up subscriber and revenue modeling triangulated against top-down market sizing from spectrum allocation records and fiber route documentation.
Segment-weighting approaches distributed value across mobile, broadband, fixed-line, and VoIP service types, with technology tiers spanning 5G, fiber optic, 4G LTE, and DSL, and customer categories separating large enterprises, business, residential, and government. CAGRs derived from infrastructure deployment trajectories, ARPU migration curves, and enterprise contract renewal patterns across the analysis window. Mining corridor demand density and Santiago rights-of-way congestion served as Chile-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under SUBTEL regulatory delays or Asian optical component supply disruptions. Projections reflect documented assumptions regarding spectrum auction timing, copper retirement deadlines, and enterprise procurement unbundling trends. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
IP DECT Phones Market
Telecommunications
Global Virtual PBX Market
Telecommunications
Cambodia ICT Market
Telecommunications
Kenya Telecom Market
Telecommunications
IoT MVNO (Services) Market
Telecommunications
5G Equipment Market
Telecommunications
IP Centrex Platforms Market
Telecommunications
Austria ICT Market
Telecommunications
5G Network and Service Assurance Market
Telecommunications
Satellite Broadband Communication in Public Safety Market
Telecommunications
Global Roaming Tariff Market
Telecommunications
Sri Lanka Telecom Tower Market
Telecommunications
Global Broadband Services Market
Telecommunications
Mobile Value-Added Services (MVAS) Market
Telecommunications
Angola Telecom Market
Telecommunications
North America Underwater Communication Systems Market