
 5G Enterprise Private Network Market | 2026-2036
5G Enterprise Private Network Market Size, Share, and Industry Trends Forecast 2026-2036
5G Enterprise Private Network Market Analysis
Manufacturing adoption is decoupling from legacy wireless infrastructure as industrial facilities pursue deterministic connectivity for automated guided vehicles and robotic process control. Nokia Corporation leverages its radio access portfolio to anchor private network deployments across European industrial zones. Samsung Electronics Co., Ltd. competes through integrated chipset-to-infrastructure offerings that sustain its position in Asian manufacturing hubs.
A 5G enterprise private network constitutes a localized cellular system operating on licensed, shared, or unlicensed spectrum bands with dedicated base stations and core network functions deployed on-site, typically delivering sub-10 millisecond latency and 99.999% reliability for mission-critical applications. Standalone architectures and edge computing integrations command premium positioning as enterprises prioritize data sovereignty and real-time processing autonomy over cloud-dependent alternatives. Managed service deployment models capture expanding margin pools as systems integrators assume operational complexity from end users lacking in-house telecommunications expertise.
The FCC governs CBRS spectrum access through its three-tier priority framework, while Germany's BNetzA administers local 5G licenses that directly shape industrial network procurement patterns. ETSI standards for network slicing and 3GPP Release 17 specifications define interoperability benchmarks that equipment vendors must satisfy for market access. Stakeholders must monitor evolving national spectrum allocation regimes and assess whether localized licensing or carrier-managed partnerships better align with operational control requirements.
Market Dynamics
Standalone 5G core architectures are displacing non-standalone alternatives as enterprises prioritize deterministic latency guarantees for autonomous mobile robots and precision motion control systems.
Growth Catalysts
- CBRS Priority Access Licenses:The FCC's three-tier spectrum framework in the United States unlocks 150 MHz of 3.5 GHz spectrum for industrial campuses without carrier intermediation.
- Automotive Electrification Workflows:Battery cell manufacturing lines in Germany demand sub-5 millisecond handover reliability for welding robot coordination that Wi-Fi cannot sustain.
- Edge-Native Network Slicing:ETSI MEC specifications enable factory operators to instantiate isolated network slices for safety-critical control traffic versus administrative data.
Market Restraints
- Radio Unit Supply Concentration:Baseband processor fabrication depends on advanced node semiconductor capacity concentrated in Taiwan and South Korea.
- Spectrum Licensing Friction:Germany's BNetzA local license auctions impose 50,000 euro minimum fees that exclude mid-sized machine builders from direct spectrum access.
- Technical Interoperability Gaps:3GPP Release 16 URLLC specifications lack unified conformance testing regimes, forcing redundant vendor validation cycles.
Strategic Opportunities
- India's PLI Scheme for Telecom:Production-linked incentives for 5G equipment manufacturing attract private network system integrators to establish local integration facilities.
- Healthcare Surgical Robotics:Telesurgery applications in Japan require guaranteed 1 millisecond latency that only localized 5G cores with distributed MEC can deliver.
- Open RAN Convergence:O-RAN Alliance specifications merging with 3GPP architectures create vendor-agnostic procurement pathways for multi-site manufacturing conglomerates.
Industry Challenges
- Telecommunications Engineering Talent Scarcity:Industrial enterprises lack in-house RF planning expertise for propagation modeling in metal-dense factory environments.
- Legacy OT System Integration:Profinet and EtherCAT industrial ethernet protocols require protocol translation gateways that introduce latency budget risk.
- Multi-Vendor Support Complexity:Disaggregated radio, core, and orchestration layers from different suppliers create finger-pointing during outage root-cause analysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Enterprise Private Network Market |
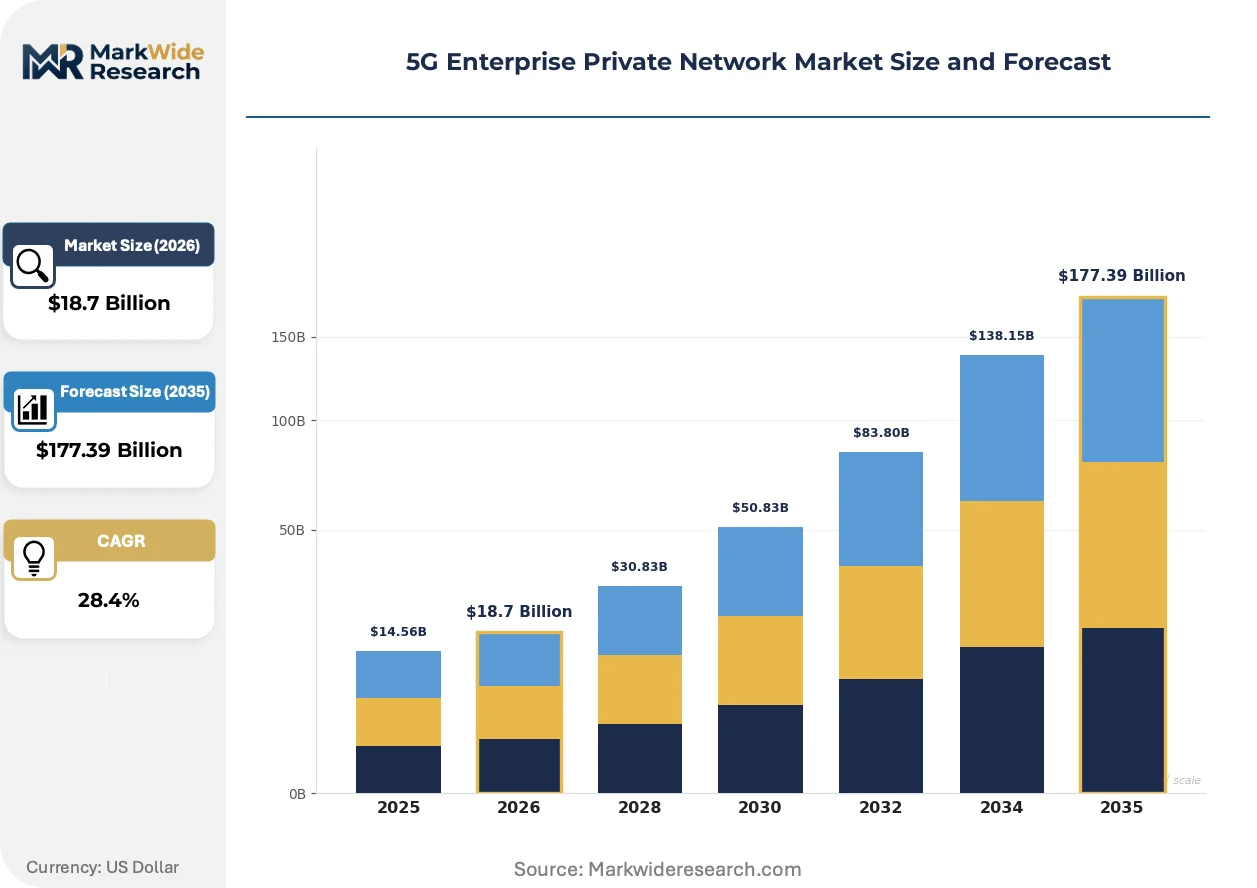
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $177.39 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Non-Standalone, Standalone, Hybrid, Edge Computing Deployment Model: On-Premises, Cloud-Based, Managed Service, Hybrid Solution End User: Manufacturing, Healthcare, Retail, Transportation Service Type: Network Setup, Maintenance, Integration, Consulting |
| Companies Covered | Huawei Technologies, Nokia Corporation, Telefonaktiebolaget LM Ericsson, Samsung Electronics Co., Ltd., Cisco Systems, AT&T, ZTE Corporation, Qualcomm, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Enterprise Private Network Market Emerging Trajectories
Radio access network disaggregation is fragmenting vendor lock-in patterns as enterprises evaluate multi-supplier deployments. Three developments merit particular attention.
Open RAN architectures are electrifying procurement flexibility for industrial network operators. The O-RAN 7-2x split separates distributed units from centralized baseband functions. German automotive suppliers now source radio units from specialized hardware vendors while procuring software stacks from independent suppliers. This decomposition compresses switching costs and accelerates feature deployment cycles.
Germany's BNetzA local 5G licensing regime is reshaping spectrum access economics for industrial campuses. The regulator's 2019 framework permits enterprises to acquire 100 MHz blocks in the 3.7-3.8 GHz range for facility-specific deployment. Chemical conglomerates in Ludwigshafen and Leverkusen have secured licenses bypassing carrier-managed service models. This regulatory pathway fragments traditional mobile network operator revenue pools in European manufacturing corridors.
Outcome-based connectivity contracts are displacing capital-intensive ownership models for mid-sized manufacturers. System integrators now offer guaranteed latency SLAs with equipment refresh obligations bundled into per-device monthly fees. This shift concentrates procurement authority with operational technology managers rather than capital expenditure committees. The pattern is most visible in Japan's precision equipment sector, where METI industrial digitization subsidies reduce adoption risk for sub-500 employee facilities.
5G Enterprise Private Network Market Segmentation
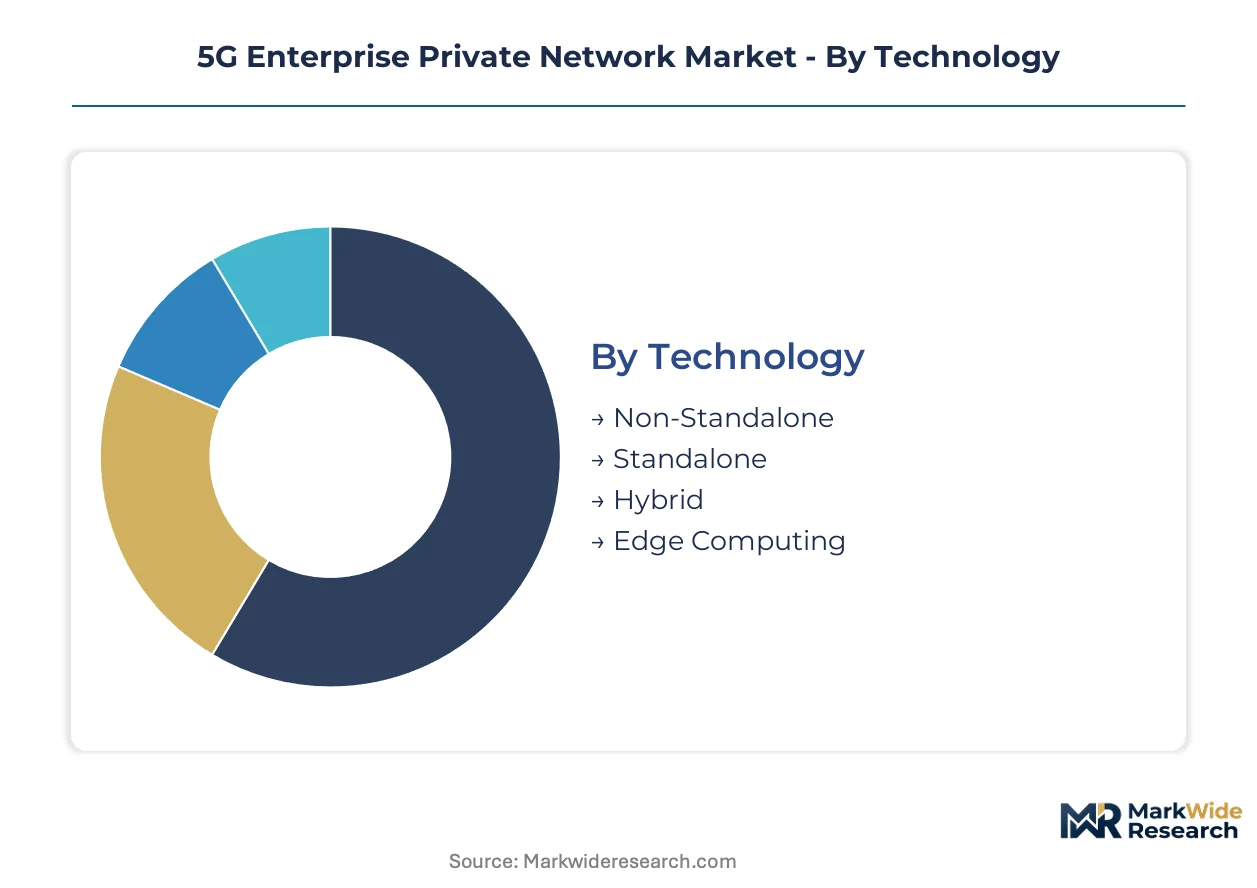
Technology architecture and deployment configuration determine latency guarantees, data sovereignty boundaries, and operational control levels for industrial 5G implementations. Procurement patterns diverge sharply between enterprises prioritizing capital ownership versus those outsourcing telecommunications complexity to managed service providers.
Technology:
Standalone architectures command premium positioning for deterministic applications, while non-standalone deployments retain cost advantages in transitional environments.
- Standalone:Dedicated 5G core functions deployed on-site deliver sub-10 millisecond latency with 99.999% reliability guarantees. German automotive welding robot coordination in Stuttgart manufacturing corridors demands this architecture for safety-critical control loops that Wi-Fi cannot sustain.
- Non-Standalone:Leverages existing 4G LTE infrastructure for control plane functions while 5G NR handles user plane traffic. Mid-sized machine builders in Japan's precision equipment sector favor this pathway to defer full core replacement costs during pilot deployments.
- Hybrid:Combines standalone and non-standalone elements for phased migration scenarios.
- Edge Computing:Distributed MEC nodes co-located with baseband functions enable real-time processing autonomy.
Today's leader: Standalone. Tomorrow's challenger: Edge Computing.
Deployment Model:
Operational technology managers increasingly control procurement authority as outcome-based contracts displace traditional capital expenditure cycles.
- Managed Service:System integrators assume full operational responsibility with guaranteed latency SLAs and equipment refresh obligations bundled into per-device monthly fees. Japan's METI industrial digitization subsidies accelerate adoption among sub-500 employee facilities seeking risk transfer.
- On-Premises:Enterprises retain full infrastructure ownership with dedicated engineering teams handling RF planning and propagation modeling. Chemical conglomerates in Ludwigshafen and Leverkusen prefer this model to maintain absolute data sovereignty over proprietary process parameters.
- Cloud-Based:Core network functions hosted in carrier or hyperscaler facilities reduce on-site hardware footprint.
- Hybrid Solution:Split architectures with sensitive functions on-premises and administrative traffic in cloud environments.
Procurement concentrates fastest in Managed Service arrangements, though On-Premises retains dominance among data-sensitive industrial sectors.
End User:
Application requirements vary dramatically across verticals, from surgical robotics latency demands to retail inventory tracking tolerance for intermittent connectivity.
- Manufacturing:Battery cell production lines require sub-5 millisecond handover reliability for welding robot coordination. The sector's decoupling from Wi-Fi dependence accelerates as automated guided vehicle fleets expand across German, Japanese, and South Korean industrial zones.
- Healthcare:Telesurgery applications in Tokyo metropolitan hospitals require guaranteed 1 millisecond latency that localized 5G cores with distributed MEC can deliver. Japan's regulatory framework for remote surgical procedures shapes equipment certification requirements.
- Retail:Warehouse robotics and augmented reality inventory systems tolerate higher latency budgets than industrial control applications.
- Transportation:Autonomous vehicle testbeds and port automation systems demand continuous coverage across geographically distributed facilities.
Manufacturing anchors current deployment volume. Healthcare represents the steepest expansion trajectory as regulatory frameworks mature for latency-critical medical applications.
Service Type:
Revenue pools shift toward recurring operational support as initial network builds reach saturation in early-adopter industrial corridors.
- Integration:Protocol translation between 5G systems and legacy Profinet or EtherCAT industrial ethernet networks commands specialized expertise. System integrators in Germany's Ruhr industrial region capture premium fees for OT-IT convergence projects.
- Maintenance:Predictive radio unit replacement and interference remediation sustain long-term vendor relationships.
- Network Setup:Initial RF planning and propagation modeling for metal-dense factory environments.
- Consulting:Spectrum licensing strategy and vendor selection advisory for enterprises navigating BNetzA or FCC frameworks.
Integration services currently capture the highest margins. Maintenance contracts are climbing fastest as installed bases mature across Asian and European manufacturing hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in spectrum licensing costs is redirecting private 5G deployment capital toward jurisdictions with streamlined local permitting regimes. Germany's BNetzA framework and the FCC's CBRS tiered access have created divergent cost structures that multinational manufacturers exploit when siting automated facilities.
United States
Automotive battery gigafactories in Michigan and Tennessee require deterministic connectivity for robotic welding coordination. The FCC's three-tier CBRS framework unlocks 150 MHz of 3.5 GHz spectrum without carrier intermediation. Industrial clusters in Detroit-Warren and Austin-Round Rock anchor early standalone 5G core deployments for automated guided vehicle fleets.
Germany
Chemical conglomerates in Ludwigshafen and Leverkusen pursue absolute data sovereignty over proprietary process parameters. BNetzA's 2019 local licensing regime permits 100 MHz blocks in 3.7-3.8 GHz for facility-specific deployment. Automotive suppliers in Stuttgart manufacturing corridors secure direct spectrum access bypassing traditional mobile network operator revenue pools.
Japan
Precision equipment manufacturers and telesurgery applications in Tokyo metropolitan hospitals demand guaranteed sub-1 millisecond latency. METI industrial digitization subsidies reduce adoption risk for sub-500 employee facilities seeking localized 5G cores with distributed MEC. Osaka-Kobe industrial zones concentrate outcome-based connectivity contracts with guaranteed latency SLAs.
China
MIIT spectrum allocations for industrial 5G in 3.3-3.6 GHz and 4.8-5.0 GHz bands support smart factory mandates under national manufacturing upgrade programs. Yangtze River Delta electronics assembly hubs and Pearl River Delta automotive clusters deploy integrated chipset-to-infrastructure solutions. State-directed investment accelerates private network builds for semiconductor fabrication facilities.
South Korea
Advanced node semiconductor capacity concentration in Gyeonggi Province creates radio unit supply dependencies for baseband processor fabrication. Daegu-Gyeongbuk manufacturing corridors integrate private 5G for robotic process control in display panel production. Government-backed 5G+ industrial convergence programs subsidize standalone architecture adoption among mid-sized component suppliers.
5G Enterprise Private Network Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated infrastructure vendors commanding premium positioning in standalone deployments while systems integrators capture recurring service revenue pools. The vendor base organizes around three strategic archetypes: radio access network equipment suppliers, cloud-native core platform developers, and managed service orchestrators. Consolidation pressures concentrate among multi-site manufacturing conglomerates seeking vendor-agnostic procurement pathways. Dominant competitive moves include spectrum licensing partnerships with national regulators and edge computing co-location agreements with industrial facility operators.
Within the integrated infrastructure tier, Nokia Corporation and Telefonaktiebolaget LM Ericsson exemplify European equipment vendors leveraging radio access portfolios to anchor private network deployments. Samsung Electronics Co., Ltd. occupies a position among Asian conglomerates competing through captive semiconductor-to-systems integration. These three entities represent divergent geographic anchoring strategies that shape procurement patterns across German automotive corridors, Japanese precision manufacturing zones, and South Korean electronics hubs.
| Leading Market Players |
|---|
| Huawei Technologies |
| Nokia Corporation |
| Telefonaktiebolaget LM Ericsson |
| Samsung Electronics Co., Ltd. |
| Cisco Systems |
| AT&T |
| ZTE Corporation |
| Qualcomm |
| Hewlett Packard Enterprise |
| Others |
Supply Flow & Price Mechanics
Baseband processor fabrication costs flow from advanced node semiconductor capacity in Taiwan and South Korea through tiered equipment pricing structures, with radio unit suppliers commanding premium positioning for standalone 5G core deployments while managed service providers compress upfront capital requirements into recurring operational expenditures for mid-sized industrial facilities.
Pricing Analysis
Distributor margins for radio access network equipment compress as enterprises shift toward direct procurement relationships with system integrators offering outcome-based connectivity contracts. Three-tier pricing structure across premium, standard, and economy levels separates standalone architecture deployments with sub-10 millisecond guarantees from non-standalone transitional configurations and hybrid edge computing bundles. Pricing pressure stems from Open RAN disaggregation enabling multi-vendor procurement flexibility that fragments traditional vendor lock-in premiums. Mid-sized machine builders exhibit highest price sensitivity, while chemical conglomerates in Germany's Ludwigshafen corridor demonstrate lowest sensitivity due to data sovereignty imperatives.
Supply Chain Analysis
Returns and refurbishment flows for radio units remain underdeveloped as semiconductor component scarcity prioritizes new unit allocation over circular economy models. Supply concentrates in Taiwan, South Korea, and China for baseband processors, radio frequency front-end modules, and antenna arrays. Raw material dependencies span gallium nitride substrates, high-purity silicon wafers, and specialized passive components. Single-source vulnerability in advanced node fabrication creates chokepoint exposure for standalone core deployments. Distribution runs through direct OEM relationships with Nokia, Ericsson, and Samsung rather than traditional telecom distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 5G enterprise private network market compounds steadily as industrial automation mandates across German, Japanese, and South Korean manufacturing corridors sustain replacement demand for legacy Wi-Fi infrastructure.
For Market Incumbents: Extend spectrum licensing partnerships with Germany's BNetzA and the FCC to secure regulatory moats against emerging Open RAN challengers. Deepen captive semiconductor supply through upstream control over baseband processor allocation from Taiwan and South Korean foundries. Anchor managed service orchestration capabilities to capture recurring revenue pools as capital expenditure cycles lengthen. For New Entrants and Emerging Players: Mid-sized precision equipment manufacturers in Japan's sub-500 employee segment represent an underserved buyer archetype seeking risk-transfer deployment models. Penetrate India's PLI scheme beneficiaries establishing local integration facilities under production-linked telecom incentives. Pursue healthcare surgical robotics applications in Tokyo metropolitan hospitals requiring guaranteed 1 millisecond latency as a differentiated entry vector. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-site manufacturing conglomerates demand vendor-agnostic procurement pathways spanning German automotive corridors and Asian electronics hubs. Long-term viability favors system integrators with proven OT-IT convergence expertise for Profinet and EtherCAT protocol translation. Monitor BNetzA local license auction participation rates as an inflection indicator for direct spectrum access economics.| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum Licensing Partnership | Direct BNetzA or FCC authorization bypasses carrier intermediation for industrial campuses. |
| Edge Computing Co-location | Distributed MEC nodes with baseband functions enable sub-1 millisecond telesurgery applications. |
| Open RAN Integration | O-RAN 7-2x split procurement reduces switching costs for multi-site manufacturing conglomerates. |
| Managed Service Orchestration | Outcome-based contracts transfer operational complexity from OT managers lacking RF expertise. |
| Semiconductor Supply Anchoring | Captive baseband processor allocation from Taiwan foundries secures standalone core deployment capacity. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at German automotive suppliers, RF planning specialists at system integrators, procurement leads at chemical conglomerates, and regulatory affairs managers navigating BNetzA frameworks with secondary validation against 3GPP release documentation, ETSI MEC specifications, FCC CBRS auction records, and equipment vendor SEC disclosures. Bottom-up deployment tracking across manufacturing verticals and top-down spectrum allocation analysis triangulated market sizing.
Segment-weighting approaches modeled technology architecture splits between standalone, non-standalone, and edge computing configurations alongside deployment model differentiation across managed service, on-premises, and hybrid solutions. End-use verticals including manufacturing, healthcare, retail, and transportation shaped demand elasticity parameters. CAGRs derived from installation base expansion rates and equipment refresh cycles across the analysis window, with semiconductor foundry capacity constraints and spectrum licensing fee structures incorporated as supply-side boundary conditions.
Underlying measurement precision varies by segment; manufacturing deployment volumes carry tighter precision than emerging healthcare telesurgery applications. Forecasts incorporate assumptions regarding BNetzA local license fee trajectories and Open RAN standardization timelines that regulatory acceleration or semiconductor supply disruptions could materially revise. Practitioners should monitor 3GPP Release 18 URLLC conformance testing regime development and CBRS Priority Access License secondary market activity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Europe Private 5G Network Market
Network Technology
ISP Management Systems Market
Network Technology
Router and Switch Market
Network Technology
Network Management Solutions Market
Network Technology
Private Network Services Market
Network Technology
Global Gigabit Wi-Fi Access Points Market
Network Technology
Network Management Systems (NMS) Market
Network Technology
Global Wireless Router Market
Network Technology
Global 5G Smart Antenna Market
Network Technology
Unified Network Management Market
Network Technology
DHCP and IP Address Management Market
Network Technology
Microduct Market
Network Technology
Application Delivery Controller (ADC) Market
Network Technology
Mobile Accelerator Market
Network Technology
Industrial Wireline Networking Market
Network Technology
North America Structured Cabling Market