
 Nigeria Satellite Communications Market | 2026-2036
Nigeria Satellite Communications Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Satellite Communications Market Insights
Managed bandwidth services is rewriting margin economics across the Nigeria satellite communications value chain. NigComSat leverages its NigComSat-1R orbital position to anchor domestic capacity leasing. Galaxy Backbone Plc sustains government and institutional demand through its federal network infrastructure monopoly. Gilat Satellite Networks Ltd. specializes in VSAT hub deployments for enterprise verticals.
Nigeria satellite communications encompasses the transmission, reception, and relay of voice, video, and data signals via orbital platforms operating in C-band, Ku-band, Ka-band, and L-band frequency allocations, utilizing geostationary and low-earth orbit architectures to bridge terrestrial infrastructure gaps. The primary purpose is to deliver ubiquitous connectivity across Nigeria's vast landmass where fiber penetration remains sparse, particularly for maritime, aviation, and remote terrestrial applications. Internet access services capture the fastest-expanding margin pool as enterprise and consumer demand for broadband backhaul surges. Low-earth orbit satellite technology is displacing legacy geostationary dominance in latency-sensitive use cases. Government end users sustain the largest procurement volumes through sovereign network programs.
The Nigerian Communications Commission governs spectrum allocation and service licensing, while the National Space Research and Development Agency oversees orbital coordination and national space policy implementation. These frameworks shape market access by mandating local landing rights and domestic gateway requirements for foreign satellite operators. Stakeholders must monitor regulatory shifts around spectrum harmonization and local content mandates as low-earth orbit constellations proliferate.
Market Dynamics
Low-earth orbit constellations are compressing latency benchmarks and forcing geostationary incumbents to reposition capacity pricing. This orbital technology shift is redrawing competitive boundaries between legacy satellite operators and new constellation deployers across Nigerian enterprise and government procurement channels.
Growth Catalysts
- Nigerian Communications Commission licensing frameworks:Domestic gateway mandates and local landing rights requirements create protected market space for indigenous operators. Foreign satellite service providers must establish Nigerian earth stations.
- Oil and gas offshore platforms:VSAT network expansion in the Niger Delta drives sustained demand for Ku-band and C-band maritime connectivity. Exploration activity in deepwater blocks requires redundant satellite backhaul.
- Ka-band frequency adoption:High-throughput spot beam technology enables cost-per-bit reduction for broadband internet services. Enterprise clusters in Lagos and Abuja are migrating from legacy Ku-band contracts.
Market Restraints
- Orbital slot scarcity:International Telecommunication Union coordination timelines extend 18-24 months for new geostationary positions. Nigerian operators face queuing delays for prime African orbital arcs.
- Foreign exchange volatility:Capacity leasing and ground segment equipment imports are dollar-denominated. Naira depreciation elevates total cost of ownership for domestic service providers.
- Fiber backhaul substitution:Subsea cable landings in Lagos and terrestrial fiber expansion along major corridors erode satellite's addressable market in urban enterprise segments.
Strategic Opportunities
- Northern Nigeria agricultural corridors:Unconnected rural farming cooperatives present white-space demand for precision agriculture IoT backhaul. Satellite remains the only viable connectivity layer outside state capitals.
- National Space Policy implementation:Sovereign satellite manufacturing and launch capability investments create domestic upstream opportunities. Local content mandates in government procurement favor Nigerian-registered operators.
- LEO-GEO hybrid architectures:Convergence of low-earth orbit constellations with geostationary trunking enables tiered service portfolios. System integrators can bundle latency-sensitive and broadcast applications.
Industry Challenges
- Satellite engineering talent pipeline:RF systems design and orbital mechanics expertise concentrates in South Africa and Europe. Nigerian universities lack accredited space technology programs.
- Type approval timelines:Nigerian Communications Commission equipment certification processes extend 6-9 months for new VSAT terminals. Hardware refresh cycles lag global product launches.
- Legacy hub integration:Enterprise customers operate mixed fleets of C-band, Ku-band, and emerging Ka-band terminals. Multi-frequency network management complexity elevates operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Satellite Communications Market |
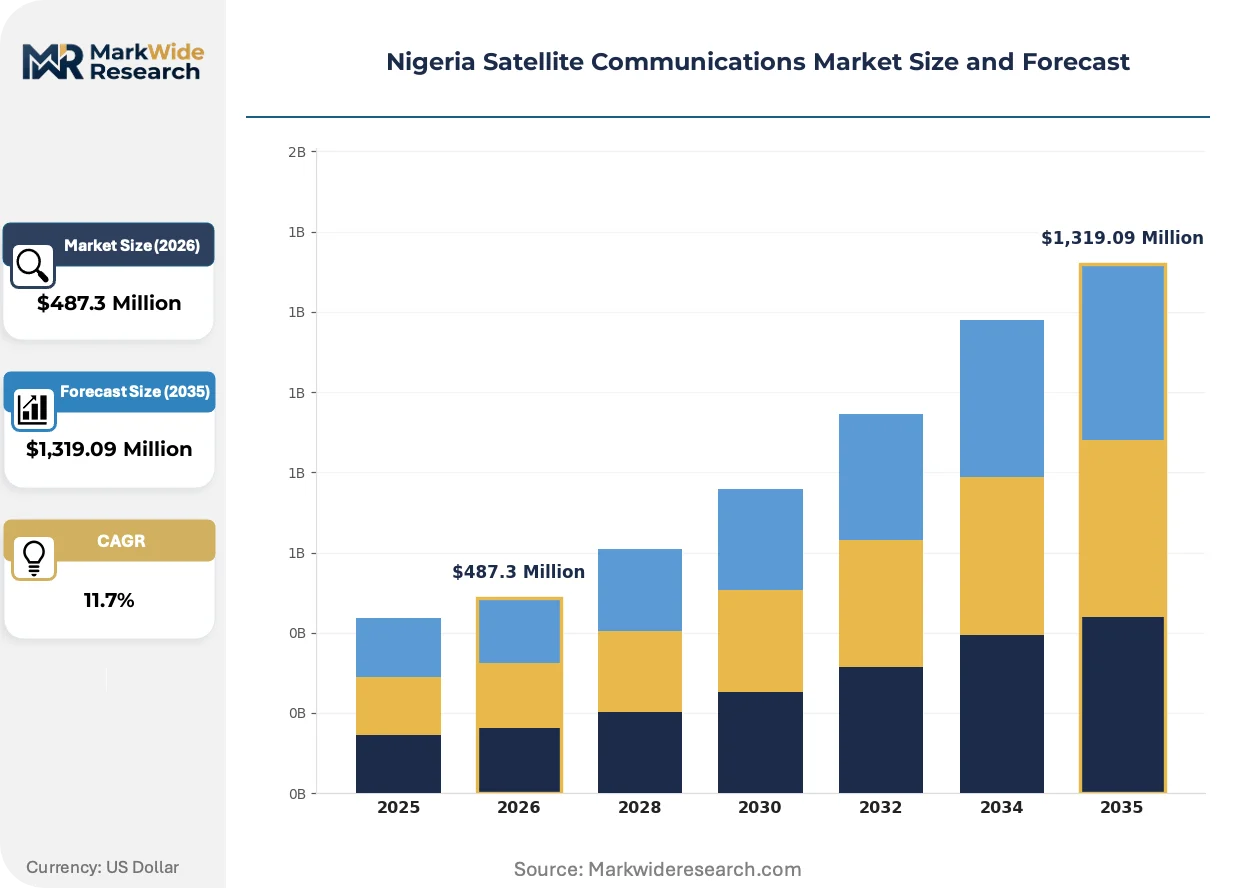
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Broadcasting, Internet Access, Data Communication, Disaster Recovery Technology: Geostationary Satellites, Low-Earth Orbit Satellites, Very Small Aperture Terminal, Direct Broadcast Satellite End User: Government, Telecommunications, Broadcasting Companies, Maritime Sector Application: Television Distribution, Emergency Services, Remote Sensing, Research |
| Companies Covered | Nigerian Communications Satellite Ltd. (NigComSat), Galaxy Backbone Plc, Globacom Ltd., Gilat Satellite Networks Ltd., Eutelsat Group (OneWeb), Starlink, Viasat Inc., Inmarsat Global Limited, Iridium Communications Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Satellite Communications Market Trends and Innovations
Software-defined satellite payloads and ground segment virtualization are collapsing traditional hardware refresh cycles. These architectural shifts enable dynamic bandwidth allocation and accelerate service deployment timelines across Nigerian verticals.
Software-defined radio technology is digitizing baseband processing functions previously locked in proprietary hardware. Nigerian enterprise customers are adopting virtualized hub architectures to collapse provisioning timelines from weeks to days. This flexibility is digitizing how satellite capacity is sold, compressing contract minimums and enabling usage-based billing models.
The Nigerian Communications Commission's spectrum harmonization directives are mandating interference coordination between satellite earth stations and terrestrial microwave links. This regulatory pressure is forcing relocation of existing ground facilities and redesign of link budgets. Oil and gas operators in the Niger Delta face the steepest compliance costs due to dense coastal microwave deployment.
Enterprise buyers are unbundling managed services from raw capacity contracts. Large agricultural cooperatives and federal agencies now procure satellite bandwidth separately from terminal management and field maintenance. This disintermediation is visible most acutely in Abuja government procurement, where Galaxy Backbone Plc competes against independent system integrators for network operations contracts.
Nigeria Satellite Communications Market Segmentation
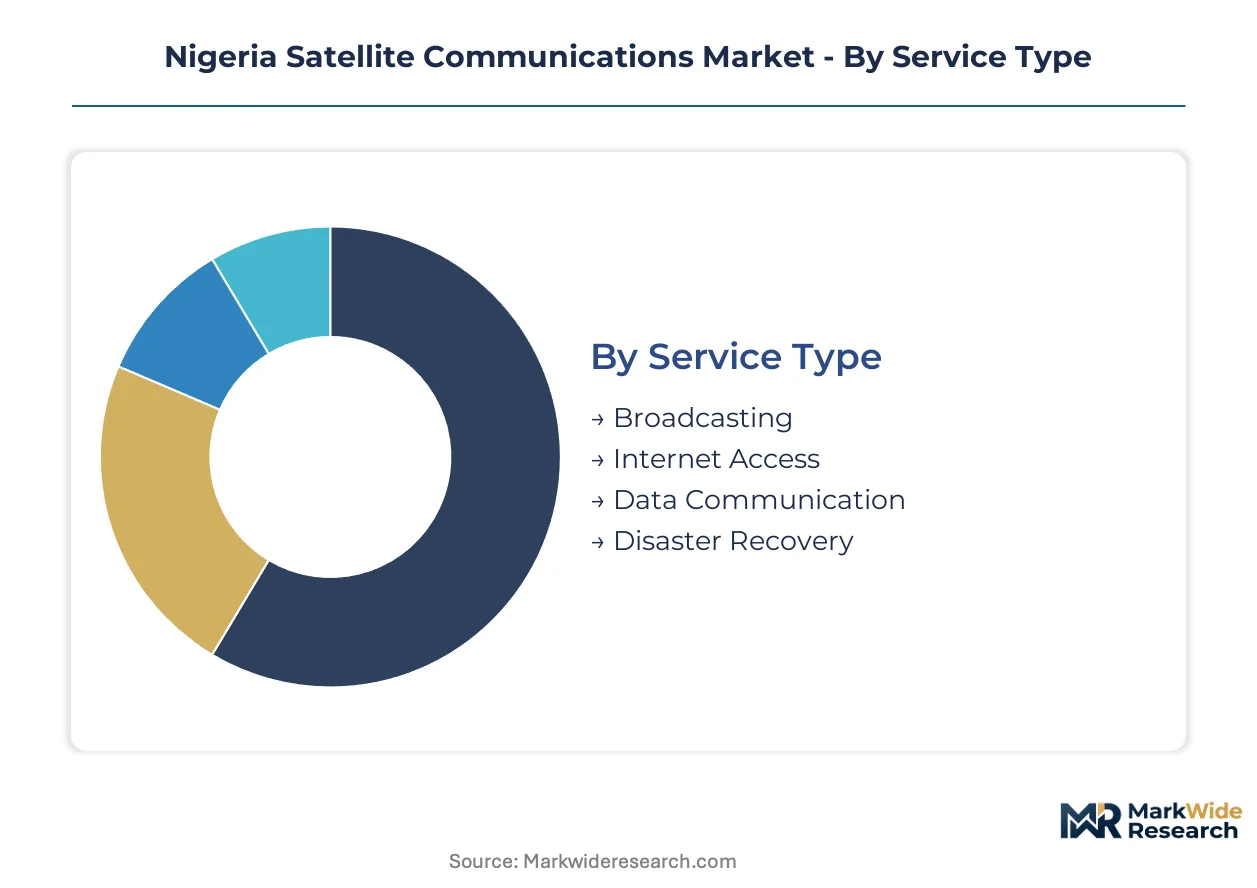
Nigeria's satellite communications market fragments across service delivery models, orbital architectures, customer verticals, and use-case applications. Each segmentation axis reveals distinct procurement patterns and margin structures that shape vendor positioning.
Service Type:
Mature revenue streams coexist with emerging service categories as enterprise buyers unbundle legacy bundled offerings.
- Broadcasting:Traditional DTH and radio distribution services utilize C-band and Ku-band transponders for nationwide coverage. NigComSat-1R anchors domestic capacity for Free-to-Air and Pay-TV platforms across Lagos and Abuja headends.
- Internet Access:Ka-band spot beams deliver broadband backhaul to unconnected rural cooperatives and SME clusters. Northern Nigeria agricultural corridors drive white-space demand where fiber cannot reach.
- Data Communication:Enterprise-grade private networks serve banking and oil sector WAN extension requirements. Nigerian Communications Commission licensing mandates domestic gateway termination for foreign operator traffic.
- Disaster Recovery:Backup connectivity for critical infrastructure activates during fiber cuts or grid failures. Federal agencies procure redundant satellite links through Galaxy Backbone Plc framework contracts.
Broadcasting retains volume leadership; Internet Access holds the steepest expansion curve.
Technology:
Cost tier differentiation separates legacy infrastructure investments from next-generation constellation deployments.
- Geostationary Satellites:Fixed orbital positions at 42.5°E and other African arcs provide reliable broadcast and trunking services. NigComSat-1R represents Nigeria's sovereign geostationary asset with continental coverage footprint.
- Low-Earth Orbit Satellites:Constellation operators compress latency to under 50ms for financial trading and cloud access applications. Maritime and aviation verticals in Lagos port and Murtala Muhammed International Airport trial LEO services.
- Very Small Aperture Terminal:Compact earth stations enable rapid deployment across Niger Delta oil platforms and remote government outposts. VSAT hub infrastructure concentrates in Lagos enterprise clusters.
- Direct Broadcast Satellite:Consumer-facing DTH terminals penetrate Nigerian households through retail distribution networks. Ku-band reception dominates urban installations while C-band serves interference-prone southern regions.
Geostationary Satellites retain volume leadership; Low-Earth Orbit Satellites hold the steepest expansion curve.
End User:
Customer type segmentation reveals procurement concentration in sovereign accounts versus commercial verticals.
- Government:Federal and state agencies procure secure networks for administrative, defense, and emergency coordination functions. National Space Policy implementation prioritizes Nigerian-registered operators in public tenders.
- Telecommunications:Mobile network operators lease satellite backhaul for rural base station connectivity outside fiber footprints. MTN Nigeria and Airtel Africa utilize C-band and Ku-band capacity for network extension.
- Broadcasting Companies:Television and radio stations rely on satellite distribution for content delivery to terrestrial transmitters. MultiChoice Nigeria and other Pay-TV platforms anchor transponder demand.
- Maritime Sector:Offshore oil platforms and coastal shipping require redundant connectivity beyond terrestrial reach. Deepwater exploration blocks in the Niger Delta mandate VSAT redundancy for safety compliance.
Government retains volume leadership; Maritime Sector holds the steepest expansion curve.
Application:
Application segmentation tracks how satellite capacity translates into specific mission outcomes across Nigerian verticals.
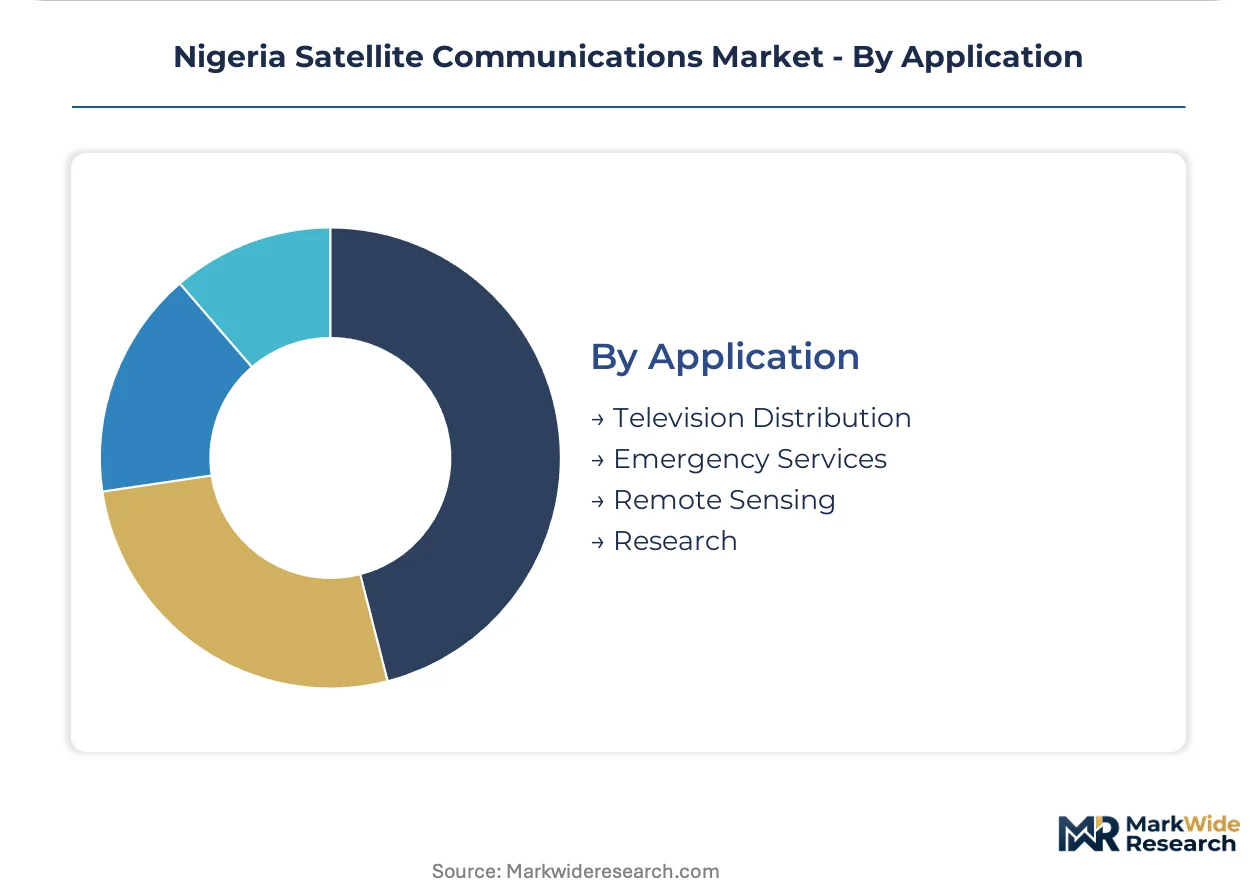
- Television Distribution:Primary revenue application delivering entertainment and news content to mass audiences. Free-to-Air and subscription television platforms consume the majority of domestic transponder capacity.
- Emergency Services:First responder communications and disaster coordination networks activate during floods, conflicts, and infrastructure failures. National Emergency Management Agency maintains satellite-equipped mobile command units.
- Remote Sensing:Earth observation data supports agricultural monitoring, security surveillance, and environmental management. Nigerian Communications Commission spectrum rules govern downlink frequencies for imagery reception.
- Research:Academic and scientific institutions access satellite data for climate, geospatial, and space technology studies. Nigerian universities lack dedicated space programs but partner with international agencies for capacity building.
Television Distribution retains volume leadership; Emergency Services holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Nigeria's satellite communications landscape diverge sharply between southern coastal corridors and northern inland territories. Lagos and Abuja concentrate enterprise-grade procurement for Ku-band and Ka-band services, while agricultural and security applications dominate northern demand profiles.
Lagos State
Maritime connectivity and financial services anchor satellite demand in Lagos. The Nigerian Communications Commission's domestic gateway mandates require foreign operators to terminate traffic at local earth stations. Apapa port and Victoria Island enterprise clusters drive VSAT hub deployments for banking WAN extension and offshore platform backhaul.
Abuja Federal Capital Territory
Federal government procurement concentrates in Abuja through Galaxy Backbone Plc framework contracts. The National Space Research and Development Agency coordinates orbital slot filings from its headquarters here. Garki and Maitama districts host the densest earth station clusters serving sovereign network programs.
Rivers State
Oil and gas exploration in the Niger Delta sustains C-band and Ku-band maritime connectivity demand. Deepwater block operators mandate redundant VSAT links for safety compliance. Port Harcourt serves as the primary logistics hub for offshore platform terminal deployments and maintenance operations.
Kano State
Northern agricultural corridors generate white-space demand for precision agriculture IoT backhaul. Satellite remains the sole viable connectivity layer outside Kano metropolis. The National Space Policy implementation prioritizes Nigerian-registered operators for rural connectivity tenders in these unconnected territories.
Delta State
Coastal microwave density creates spectrum coordination challenges for satellite earth stations in Delta. Nigerian Communications Commission interference directives force link budget redesigns for existing facilities. Warri and its surrounding oil-producing zones sustain specialized maritime terminal procurement for shallow-water platform connectivity.
Nigeria Satellite Communications Market Competitive Landscape
Capability concentration sits with sovereign infrastructure operators; scale advantage sits with international constellation deployers. The market structures around three distinct tiers: domestic orbital asset holders, federal network infrastructure monopolies, and foreign capacity lessors subject to local landing requirements. Strategic moves center on spectrum harmonization compliance and LEO-GEO hybrid service bundling.
Within the sovereign operator tier, Nigerian Communications Satellite Ltd. (NigComSat) and Galaxy Backbone Plc occupy foundational positions anchoring domestic policy implementation. Gilat Satellite Networks Ltd. represents the specialized VSAT deployment archetype serving enterprise verticals. These three entities exemplify how regulatory frameworks around local content mandates and gateway requirements shape competitive positioning.
| Leading Market Players |
|---|
| Nigerian Communications Satellite Ltd. (NigComSat) |
| Galaxy Backbone Plc |
| Globacom Ltd. |
| Gilat Satellite Networks Ltd. |
| Eutelsat Group (OneWeb) |
| Starlink |
| Viasat Inc. |
| Inmarsat Global Limited |
| Iridium Communications Inc. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Nigerian domestic gateway infrastructure concentrates pricing power among indigenous operators holding NigComSat-1R orbital assets and Galaxy Backbone federal contracts. This utilization squeeze forces foreign capacity lessors into longer contract terms and higher local landing fees, while dollar-denominated equipment imports amplify cost volatility for VSAT deployers serving Niger Delta oil platforms.
Pricing Analysis
Long-term transponder offtake contracts dominate enterprise procurement, with Ka-band spot beam services commanding premium pricing over legacy Ku-band due to throughput advantages. Price differentiation rests on orbital arc priority and Nigerian Communications Commission licensing tier, with government buyers showing lowest sensitivity due to sovereign network mandates. Cost compression in C-band maritime connectivity is intensifying as LEO constellations enter Lagos port trials, eroding geostationary incumbents' margin position.
Supply Chain Analysis
Contract manufacturing for satellite ground segment equipment concentrates in Israel, the United States, and France, with Gilat Satellite Networks and Viasat anchoring hub production. Nigerian operators draw from imported RF amplifiers, antenna subsystems, and baseband processors, creating single-source vulnerability around solid-state power amplifier suppliers. Distribution runs through Lagos-based system integrators serving oil sector and federal agency procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against fiber backhaul expansion along Lagos-Abuja corridors and emerging LEO constellation services targeting latency-sensitive financial trading applications.
For Market Incumbents: Pre-empt LEO displacement by bundling geostationary trunking with managed services for oil platform redundancy requirements. Deepen backward integration into Nigerian earth station operations to satisfy Nigerian Communications Commission local gateway mandates. Anchor federal contracts through Galaxy Backbone Plc framework relationships before sovereign satellite manufacturing investments mature.
For New Entrants and Emerging Players: Build out Ka-band capacity serving northern agricultural cooperatives in Kano State where fiber cannot reach. Target unconnected rural IoT backhaul for precision agriculture as the most penetrable white-space segment. Pursue Nigerian-registered operator status to qualify for National Space Policy local content procurement preferences.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed bandwidth service providers with federal framework contracts and long-term oil sector offtake agreements. Sovereign infrastructure operators with orbital slot holdings and domestic gateway assets represent the most defensible acquisition archetype over a multi-year horizon. Watch for Nigerian Communications Commission spectrum harmonization directives as inflection signals for ground segment relocation costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Gateway Establishment | Foreign operators must terminate traffic at Nigerian earth stations per NCC licensing mandates. |
| Ka-band Spot Beam Deployment | High-throughput technology enables cost-per-bit reduction for broadband internet services. |
| LEO-GEO Hybrid Architecture | System integrators bundle latency-sensitive applications with broadcast trunking capabilities. |
| Federal Framework Contracting | Galaxy Backbone Plc monopoly on sovereign networks creates protected procurement channel. |
| Orbital Slot Coordination | ITU queuing timelines for prime African arcs extend competitive moats for incumbent holders. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Nigerian Communications Commission licensing records, National Space Research and Development Agency policy documents, and ITU orbital coordination filings. Interviews with satellite service procurement officers at oil majors, federal network administrators, VSAT system integrators, and regulatory affairs specialists informed demand modeling. Trade data on ground segment equipment imports, transponder lease disclosures, and subsea cable landing statistics provided secondary validation. Bottom-up capacity deployment tracking and top-down addressable market sizing were triangulated for consistency.
Forecast inputs include orbital arc utilization rates, fiber backhaul substitution trajectories, and Nigerian Communications Commission licensing velocity across the analysis window. Segmentation dimensions encompass service delivery model, orbital architecture, end-user vertical, and application type. CAGRs were derived from capacity expansion pipelines and procurement contract renewal patterns. Ka-band adoption curves and LEO constellation trial outcomes served as technology-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Starlink or other LEO deployers would shift outcomes beyond modeled ranges. Quarterly review of NCC spectrum harmonization directives, ITU orbital slot filing queues, and subsea cable expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Thailand ICT Market
Telecommunications
Malaysia Telecom Market
Telecommunications
Sri Lanka Telecom Market
Telecommunications
Algeria Telecom Market
Telecommunications
LTE Advanced Pro Market
Telecommunications
Global 5G Services Market
Telecommunications
Super High Frequency Communication Market
Telecommunications
Turkey Telecom Market
Telecommunications
Private Branch Exchange Market
Telecommunications
CDMA Mobile Phone Market
Telecommunications
US Voice-Over LTE (Volte) Market
Telecommunications
Global Policy Management in Telecom Market
Telecommunications
Global IP Phone Market
Telecommunications
Global GPON Technology Market
Telecommunications
Global Telecom Order Management Market
Telecommunications
5G Fronthaul and Backhaul Equipment Market