
 Bahrain Telecom Market | 2026-2036
Bahrain Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Bahrain Telecom Market Insights
Enterprise cloud connectivity is expanding across Bahrain's banking and fintech verticals, pulling capital from legacy premises-based systems. Batelco (Beyon) leverages its nationwide fiber backbone to anchor wholesale bandwidth contracts with data center operators. stc Bahrain competes through aggressive 5G fixed-wireless positioning in residential zones. Zain Bahrain specializes in managed SD-WAN suites for mid-market enterprises seeking hybrid cloud access.
Bahrain telecom encompasses voice, data, and digital infrastructure services delivered over wireless and wireline networks operating between 700 MHz and 28 GHz spectrum bands, with fiber-to-the-premises achieving symmetrical gigabit throughput. Mobile services dominate revenue generation through postpaid enterprise plans and prepaid consumer bundles, while fiber optic infrastructure captures the fastest expansion as Bahrain pursues nationwide gigabit coverage. Internet services concentrate margin pools in enterprise-grade SLA contracts, whereas value-added services around IoT platforms and cybersecurity remain nascent but structurally important for vendor differentiation.
The Telecommunications Regulatory Authority of Bahrain governs spectrum allocation, interconnection pricing, and net neutrality compliance, while the National Cybersecurity Center mandates data sovereignty standards for government and financial sector contracts. TRA's wholesale access regulations compel infrastructure sharing, compressing retail margins while stimulating BNET's open-access fiber model. Stakeholders must monitor how TRA's pending cloud services framework and data localization directives reshape procurement criteria for enterprise and government segments.
Market Dynamics
Bahrain's telecom sector is reconfiguring around TRA-mandated infrastructure sharing and the national 5G rollout, compressing retail margins while forcing operators toward wholesale and enterprise service models.
Growth Catalysts
- Enterprise Cloud Migration:Bahrain's financial services sector is pulling capital from legacy premises-based systems into fiber-connected data centers, expanding demand for symmetrical gigabit throughput.
- TRA Wholesale Access Regulations:The Telecommunications Regulatory Authority compels infrastructure sharing through BNET's open-access fiber model, stimulating capital-efficient network expansion.
- 5G Fixed-Wireless Deployment:Residential zones across Manama and Muharraq are absorbing high-capacity fixed-wireless access as an alternative to fiber drops.
Market Restraints
- Retail Margin Compression:Wholesale access obligations and open-access fiber models are structurally eroding service provider profitability at the consumer tier.
- Spectrum Scarcity:Bahrain's available frequencies between 700 MHz and 28 GHz face competing demands from mobile broadband, fixed-wireless, and emerging IoT platforms.
- Capital Intensity of Fiber Overbuild:Achieving nationwide gigabit coverage requires sustained capex in low-density districts where returns dilute.
Strategic Opportunities
- Bahrain Bay Fintech Cluster:The concentrated fintech corridor presents unmet demand for managed SD-WAN suites and hybrid cloud connectivity.
- IoT Platform Services:Industrial and logistics verticals are creating white space for value-added services around connected asset monitoring.
- Cybersecurity Bundling:The National Cybersecurity Center's data sovereignty mandates for government and financial contracts enable security-service packaging.
Industry Challenges
- Legacy System Integration:Enterprise clients maintaining hybrid environments require seamless bridging between on-premises infrastructure and cloud endpoints.
- Skill Scarcity in SD-WAN Deployment:Mid-market service delivery lacks sufficient network engineering talent for complex managed service rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bahrain Telecom Market |
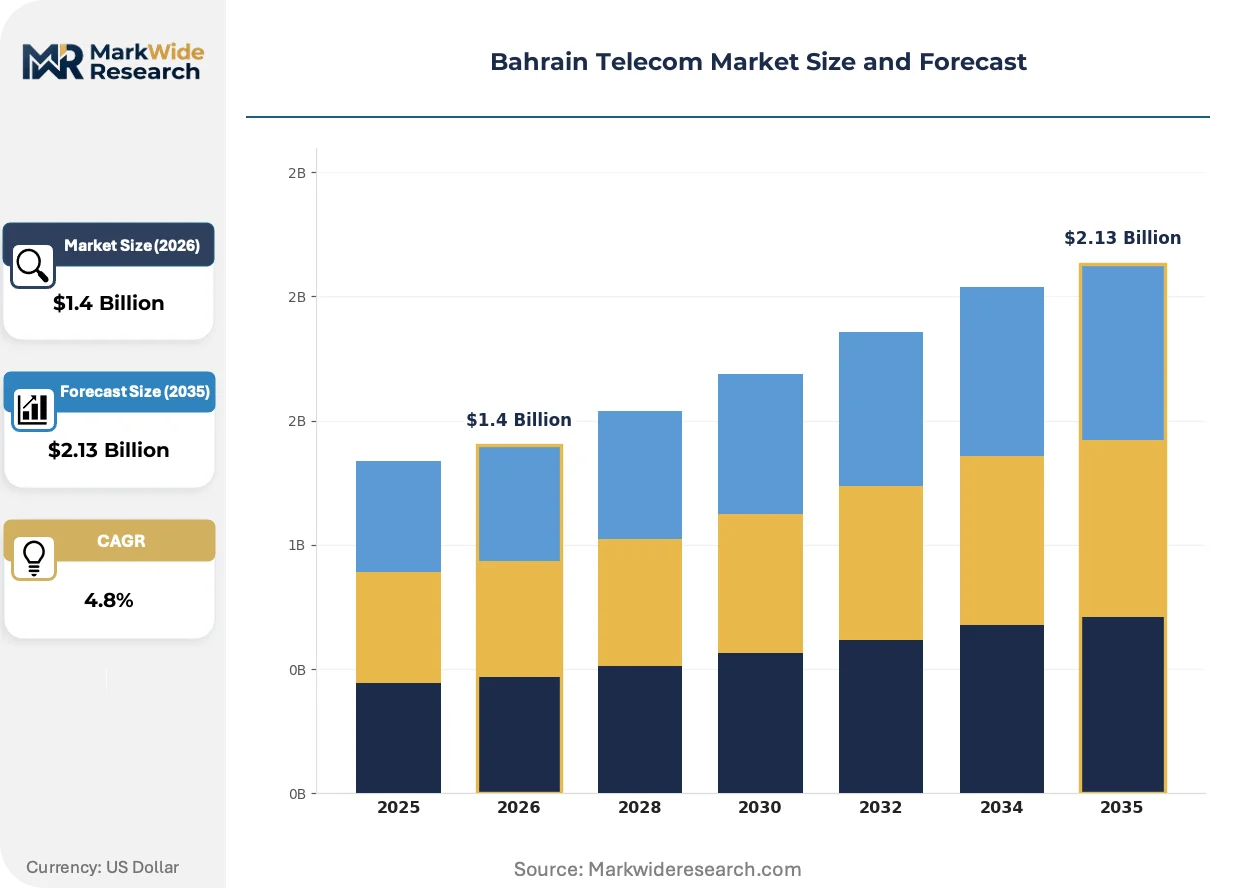
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Fixed-line Services, Internet Services, Value-added Services Technology: 5G, Fiber Optic, DSL, Satellite End User: Residential, Enterprises, Government, SOHO Deployment: On-premises, Cloud-based, Hybrid, Virtualized |
| Companies Covered | Batelco (Beyon), stc Bahrain, Zain Bahrain, BNET, Bahrain Telecommunications Company, Viva Bahrain, 4GTSS Corporation, Arabian Al Anar Company, DNS Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bahrain Telecom Market Trends and Innovations
Network function virtualization and edge computing architectures are disrupting Bahrain's traditional hardware-centric deployment models, opening paths for software-defined service differentiation.
Open RAN architectures are modularizing baseband processing and radio unit management across Bahrain's 5G infrastructure buildout. Batelco and stc Bahrain are piloting multi-vendor RAN deployments in Manama's enterprise corridor. This modularization is fragmenting vendor lock-in and compressing equipment procurement cycles.
TRA's pending cloud services framework is tightening data localization requirements for government and financial sector contracts. The regulation will mandate in-country storage and processing for sensitive workloads. Banks and fintech operators in Bahrain Bay are pre-positioning private cloud infrastructure to maintain procurement eligibility.
Enterprise buyers are unbundling connectivity from managed services, procuring raw bandwidth and overlaying third-party SD-WAN and security solutions. This disintermediation is eroding operator margins on traditional integrated offerings. The pattern is most visible among mid-market enterprises in Manama's commercial districts seeking hybrid cloud access flexibility.
Bahrain Telecom Market Segmentation
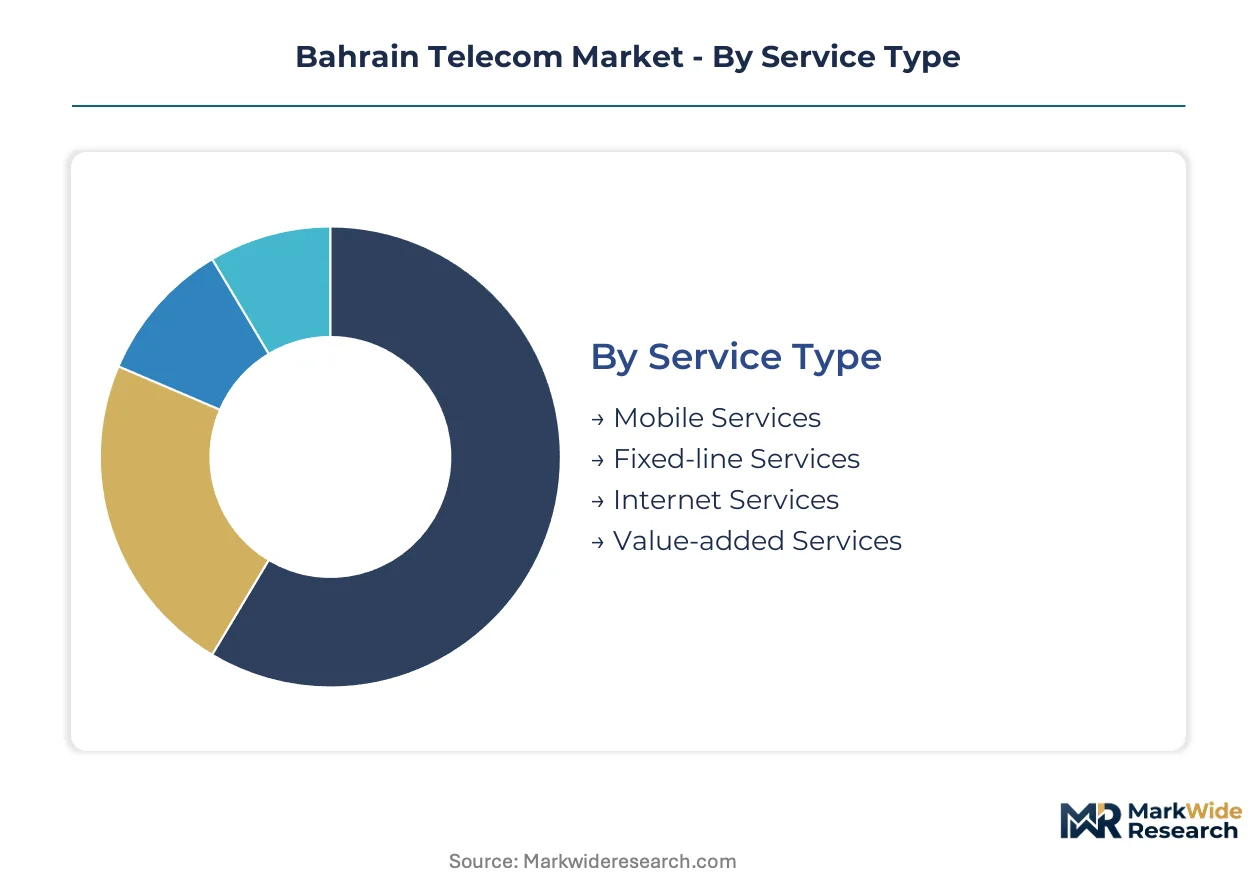
Segmentation in Bahrain's telecom market reveals how capital allocation shifts between legacy infrastructure and next-generation platforms. Each dimension exposes different margin structures and regulatory exposure across the value chain.
Service Type:
Replacement cycles vary sharply across service categories, with enterprises accelerating cloud migration while residential voice maintains extended depreciation schedules.
- Mobile Services:Postpaid enterprise plans and prepaid consumer bundles generate the dominant revenue share through 4G and 5G subscriptions. Demand concentrates in Manama's enterprise corridor where financial services firms mandate dual-SIM redundancy for trading floor operations.
- Internet Services:Enterprise-grade SLA contracts with symmetrical gigabit throughput command premium pricing over best-effort residential broadband. Bahrain Bay fintech operators are pulling capital into dedicated fiber leases with sub-10ms latency guarantees.
- Fixed-line Services:Legacy PSTN infrastructure faces accelerated depreciation as VoIP and mobile substitution erode subscriber bases.
- Value-added Services:IoT platforms and cybersecurity bundles remain nascent but structurally critical for vendor differentiation in government tenders.
Mobile Services sits at the top of the volume ranking, with Internet Services climbing the fastest.
Technology:
Cost tier differentiation separates capital-intensive fiber deployment from spectrum-dependent wireless alternatives.
- Fiber Optic:FTTP architectures achieve symmetrical gigabit throughput across Bahrain's nationwide coverage targets. BNET's open-access model stimulates wholesale competition while compressing retail margins in low-density districts.
- 5G:Fixed-wireless access in residential zones offers fiber-competitive speeds without last-mile trenching. stc Bahrain's aggressive positioning in Manama and Muharraq is displacing DSL subscriptions.
- DSL:Copper-based infrastructure faces technical obsolescence as fiber overbuild accelerates.
- Satellite:Niche coverage for offshore installations and remote industrial sites where terrestrial backhaul is uneconomical.
Fiber Optic commands the installed base, while 5G gains share fastest among new connections.
End User:
Customer type determines procurement complexity and contract duration across the market.
- Enterprises:Financial services and fintech verticals in Bahrain Bay drive managed SD-WAN and hybrid cloud connectivity demand. TRA's wholesale access regulations compel infrastructure sharing that reduces provisioning costs.
- Government:National Cybersecurity Center mandates data sovereignty standards that restrict vendor eligibility to operators with in-country data centers.
- Residential:Prepaid bundles and fixed-wireless alternatives dominate consumer acquisition in high-density urban zones.
- SOHO:Small office deployments favor converged voice-data packages with basic SLA coverage.
Enterprises anchor contract value, with Government expanding most quickly under cybersecurity procurement reforms.
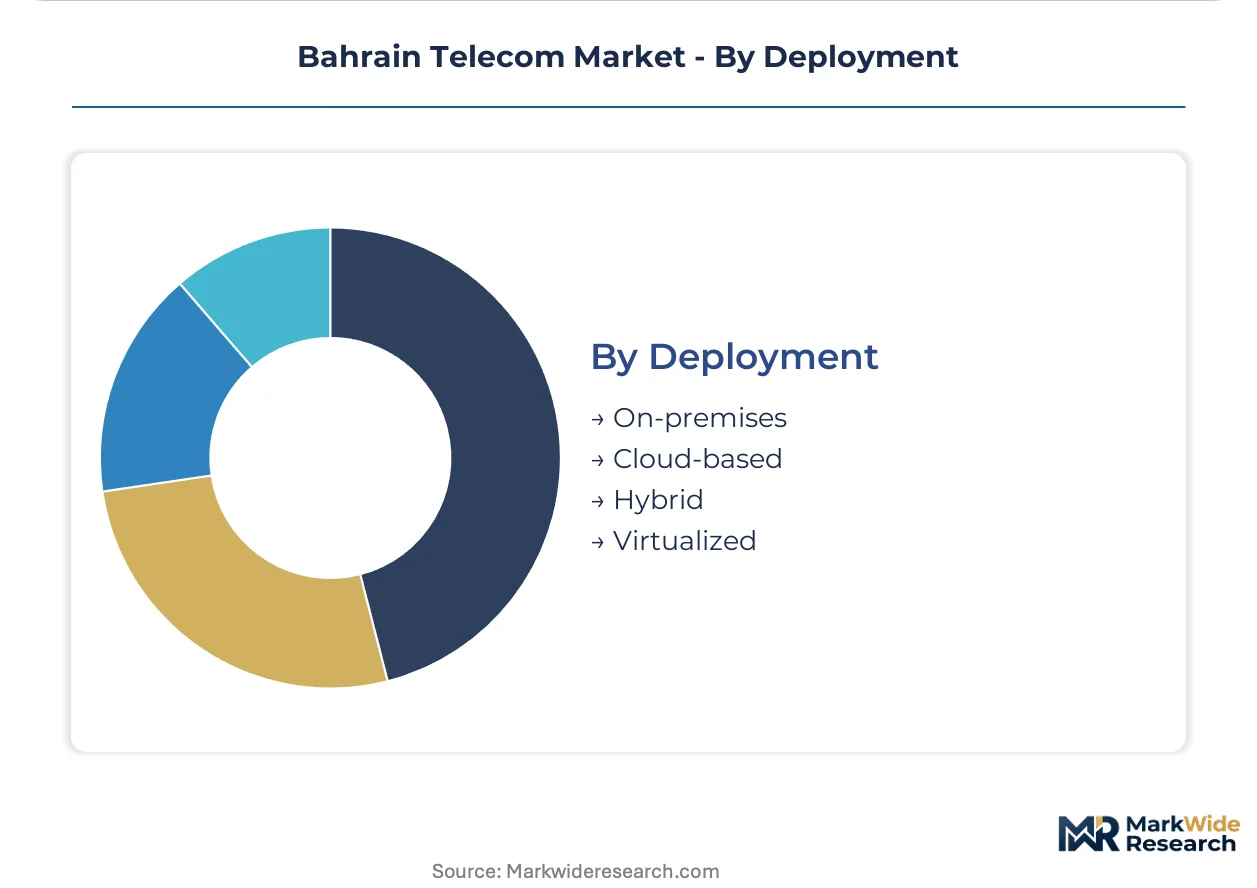
Deployment:
Maturity gradients separate legacy on-premises installations from cloud-native architectures.
- Cloud-based:Fully virtualized network functions enable rapid scaling for fintech operators requiring elastic bandwidth. TRA's pending cloud services framework will mandate in-country processing for sensitive workloads.
- Hybrid:Enterprises bridge on-premises legacy systems with cloud endpoints, creating integration complexity that favors managed service providers.
- On-premises:Hardware-centric deployments persist in security-sensitive government facilities with air-gapped requirements.
- Virtualized:NFV architectures reduce equipment procurement cycles but demand specialized engineering talent scarce in Bahrain's mid-market.
Hybrid deployment dominates current installations, with Cloud-based showing the steepest expansion trajectory among new enterprise contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping telecom investment flows across the Gulf Cooperation Council states. Bahrain's TRA-inspired spectrum frameworks and open-access fiber mandates create compliance-cost differentials that pull enterprise service contracts from neighboring markets with heavier legacy obligations.
Saudi Arabia
Enterprise cloud migration is accelerating across Riyadh's financial district and the Eastern Province's petrochemical complexes. The Communications and Information Technology Commission mandates infrastructure sharing rules that mirror Bahrain's wholesale access model. STC and Mobily are deploying fiber-to-the-premises in Jeddah's commercial corridors to capture fintech connectivity demand.
United Arab Emirates
Du and Etisalat compete through aggressive 5G fixed-wireless positioning in Dubai's residential zones and Abu Dhabi's government district. The Telecommunications and Digital Government Regulatory Authority enforces data localization standards for federal contracts that exceed Bahrain's current requirements. Dubai Internet City anchors hyperscale data center expansion serving regional enterprise workloads.
Qatar
Ooredoo and Vodafone Qatar specialize in managed SD-WAN suites for liquefied natural gas operators and sovereign wealth fund offices. The Communications Regulatory Authority imposes cybersecurity certification thresholds for critical infrastructure contracts. Lusail City's smart district deployment concentrates IoT platform investment in integrated utility networks.
Kuwait
Zain Kuwait and Ooredoo Kuwait leverage nationwide fiber backbones to anchor wholesale bandwidth contracts with regional data center operators. The Ministry of Communications oversees spectrum allocation between mobile broadband and emerging industrial IoT applications. Kuwait City's financial district drives demand for symmetrical gigabit throughput with sub-10ms latency guarantees.
Oman
Omantel and Ooredoo Oman face retail margin compression from wholesale access obligations in Muscat's enterprise corridor. The Telecommunications Regulatory Authority's pending cloud services framework will tighten data sovereignty requirements for government procurement. Sohar Port's logistics freezone creates specialized demand for connected asset monitoring and maritime connectivity services.
Bahrain Telecom Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with infrastructure operators and service providers occupying distinct competitive tiers. The vendor base concentrates around three strategic archetypes: nationwide fiber backbone operators, mobile-first 5G deployers, and managed services specialists targeting enterprise verticals. Dominant competitive moves include strategic partnerships with hyperscale data center operators and portfolio diversification into cybersecurity bundling for government tenders.
Within the infrastructure-operator tier, Batelco (Beyon) and stc Bahrain occupy positions as scale-driven national champions, while Zain Bahrain exemplifies the managed-services specialization archetype. BNET represents the open-access wholesale model mandated by regulatory framework. These three named entities anchor the competitive structure without exhaustive market share claims, serving as reference points for archetype-based strategic positioning rather than definitive competitive rankings.
| Leading Market Players |
|---|
| Batelco (Beyon) |
| stc Bahrain |
| Zain Bahrain |
| BNET |
| Bahrain Telecommunications Company |
| Viva Bahrain |
| 4GTSS Corporation |
| Arabian Al Anar Company |
| DNS Company |
| Others |
Pricing and Supply Chain Analysis
Global fiber optic cable price indices cascade through Bahrain's telecom supply chain, compressing wholesale bandwidth rates while amplifying margin pressure on retail service tiers. TRA-mandated infrastructure sharing obligations accelerate this pass-through, forcing operators to absorb input cost volatility rather than transmit it to enterprise contracts.
Pricing Analysis
Retailer markup layers dominate consumer-facing tariffs, while direct-to-enterprise contracts command volume discounts anchored in multi-year SLA commitments. Three-tier pricing structure across premium, standard, and economy levels separates financial services firms demanding sub-10ms latency guarantees from residential fixed-wireless subscribers. Pricing pressure stems from BNET's open-access fiber model, which erodes service provider control over last-mile provisioning. Residential segments exhibit highest price sensitivity, whereas Bahrain Bay fintech operators prioritize reliability over unit cost.
Supply Chain Analysis
Freight cost volatility from East Asian manufacturing hubs elevates equipment landed costs for 5G radio units and fiber termination hardware. Network infrastructure draws from China, South Korea, and Finland for baseband processors, optical transceivers, and core routing systems. Single-source vulnerability concentrates in specialized 5G semiconductor foundries. Distribution runs through Dubai's Jebel Ali logistics corridor into Bahrain's bonded warehousing facilities before final-mile technician deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bahrain's telecom market represents a late-cycle quality story as enterprise buyers migrate from best-effort connectivity toward SLA-governed fiber and managed SD-WAN services. Financial services firms in Manama's enterprise corridor now mandate symmetrical gigabit throughput with cybersecurity bundling as baseline procurement criteria.
For Market Incumbents: Cement wholesale fiber dominance through BNET partnership extensions that lock in data center operator contracts before TRA's cloud services framework tightens vendor eligibility. Batelco and stc Bahrain must accelerate edge computing infrastructure deployment to offset retail margin compression from open-access regulations. Vertical integration into cybersecurity operations centers addresses National Cybersecurity Center data sovereignty mandates.
For New Entrants and Emerging Players: Open RAN modularization offers a technology-first wedge against incumbent vendor lock-in, enabling multi-vendor RAN deployments without legacy equipment dependencies. White-space targets concentrate in Bahrain Bay's fintech cluster for managed SD-WAN suites and in Muharraq's residential zones for 5G fixed-wireless alternatives. Go-to-market execution favors channel partnerships with hyperscale data center operators over direct subscriber acquisition.
For Investors and Strategic Acquirers: Consolidation pressure builds where wholesale access obligations compress retail margins below sustainable reinvestment thresholds. Long-term viability favors infrastructure-light managed services specialists with recurring enterprise revenue streams over capital-intensive fiber overbuilders. The signal to watch is TRA enforcement intensity on cloud services framework data localization rules, which would revalue in-country data center assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | SD-WAN overlay integration with hyperscale cloud providers secures fintech procurement eligibility under TRA guidelines. |
| Strategic Partnership | BNET open-access fiber partnerships reduce capex intensity while preserving enterprise contract control. |
| Geographic Expansion | Bahrain Bay fintech cluster penetration captures unmet demand for sub-10ms latency connectivity services. |
| Product Launch | Cybersecurity bundling addresses National Cybersecurity Center mandates for government and financial tenders. |
| Acquisition of Specialist Firm | NFV engineering talent acquisition resolves skill scarcity blocking mid-market managed service rollouts. |
Research Methodology
Bottom-up enterprise connectivity modeling reconciled against top-down infrastructure deployment tracking forms the analytical core of this study. Primary interviews with network engineering directors, TRA regulatory affairs officers, data center procurement managers, and fintech CTOs combined with secondary validation from TRA spectrum allocation records, BNET infrastructure disclosure filings, and hyperscaler capex announcements. Triangulation across stakeholder inputs and documentary sources anchors volume and value estimates.
Input-output matrices map fiber port activation rates, 5G base station deployment schedules, and enterprise SD-WAN contract signings against projected service revenue across the modeling period. Segmentation dimensions include service type, technology platform, end-user vertical, and deployment architecture. CAGRs derive from regression analysis of historical subscription trajectories adjusted for regulatory inflection points and infrastructure buildout schedules. Forecast inputs incorporate TRA wholesale pricing determinations and National Cybersecurity Center procurement rule changes.
The model holds under stable regulatory enforcement and sustained enterprise cloud migration; deviation in TRA cloud services framework timing or spectrum reallocation decisions would shift trajectory. Forecasts reflect documented assumptions about infrastructure sharing compliance and fintech cluster expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Mobile Voice Market
Telecommunications
Angola Telecom Market
Telecommunications
5G Equipment Market
Telecommunications
Global Small Cell 5G Network Market
Telecommunications
Global Underwater Acoustic Communication Market
Telecommunications
SIP Trunking Services Market
Telecommunications
Global Policy Management in Telecom Market
Telecommunications
Cellular Modem Market
Telecommunications
Underwater Modems Market
Telecommunications
Kuwait Telecom Market
Telecommunications
Czech Republic Telecom Market
Telecommunications
Iceland Telecom Market
Telecommunications
Global GPON Technology Market
Telecommunications
United Kingdom Telecom Market
Telecommunications
Diameter Signaling Control Market
Telecommunications
Cloud Radio Access Network (C-RAN) Market