
 APAC Small Cell 5G Market | 2026-2036
APAC Small Cell 5G Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Small Cell 5G Market Outlook
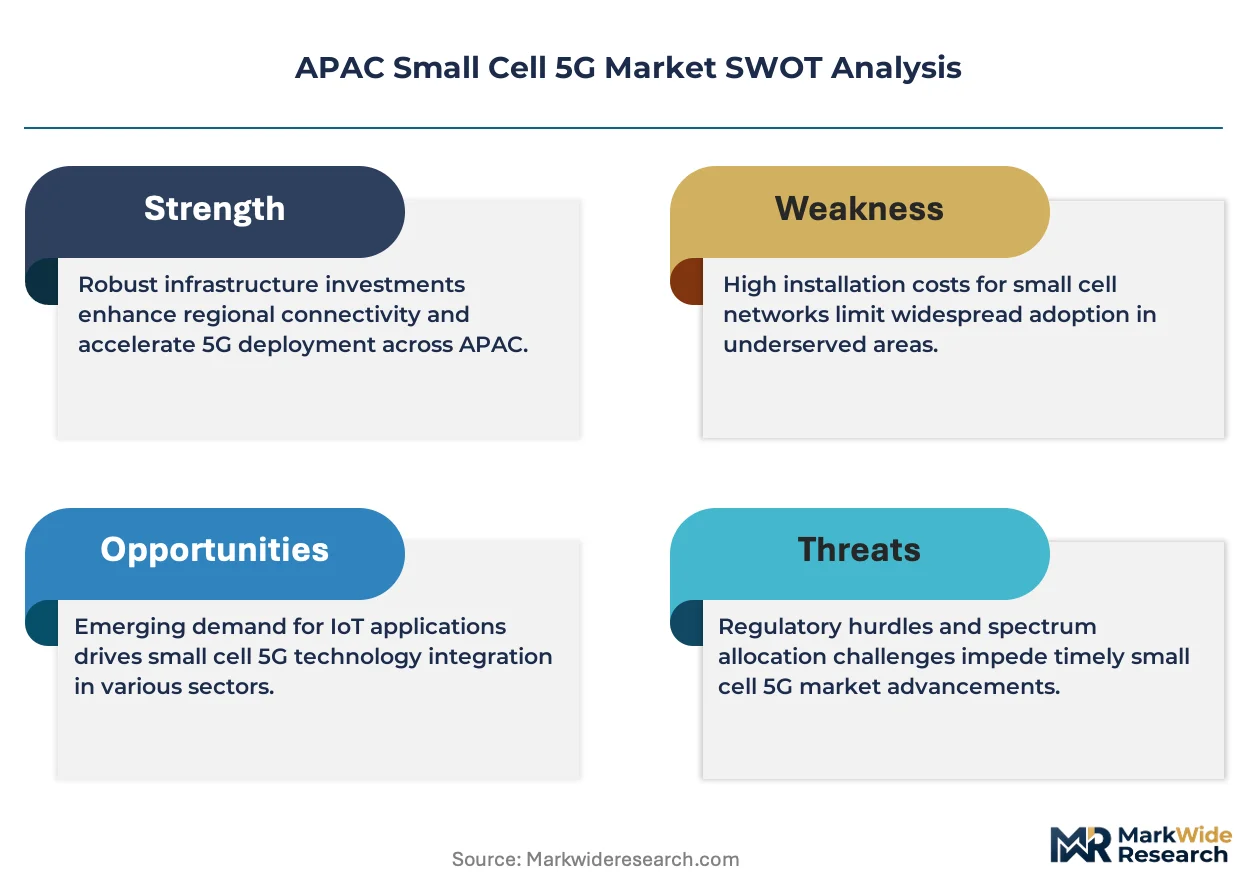
China's GB standards for 5G base station electromagnetic compatibility is repositioning certification costs for equipment vendors entering the market. Huawei Technologies leverages its captive semiconductor design capabilities to sustain cost advantages across femtocell and picocell portfolios. Nokia Corporation anchors its position through R&D intensity in Open RAN-compliant small cell architectures. Samsung Electronics dominates South Korea's enterprise segment with vertically integrated mmWave radio units.
APAC Small Cell 5G refers to low-power radio access nodes operating at sub-6 GHz and mmWave frequencies with coverage radii from ten meters to two kilometers, designed to augment macro network capacity in dense user environments. These units employ digital beamforming and massive MIMO techniques to deliver targeted throughput for industrial IoT, public safety, and immersive media applications. Picocells and microcells capture the bulk of current infrastructure spending as carriers prioritize outdoor urban densification over residential femtocell penetration. Enterprise use cases across manufacturing campuses and logistics hubs represent the fastest-growing demand pool, while metrocells retain premium positioning in venue and stadium deployments where concentrated traffic spikes justify higher unit economics.
Japan's Ministry of Internal Affairs and Communications, South Korea's MSIT, and India's TRAI collectively shape equipment authorization timelines, spectrum allocation rules, and local content requirements that determine vendor market access across the region. China's MIIT mandates domestic security certification for core network elements, creating a bifurcated compliance landscape that rewards pre-certified suppliers. Stakeholders must weigh Open RAN interoperability commitments against proprietary integrated stack performance when selecting long-term small cell partners for multi-country rollouts.
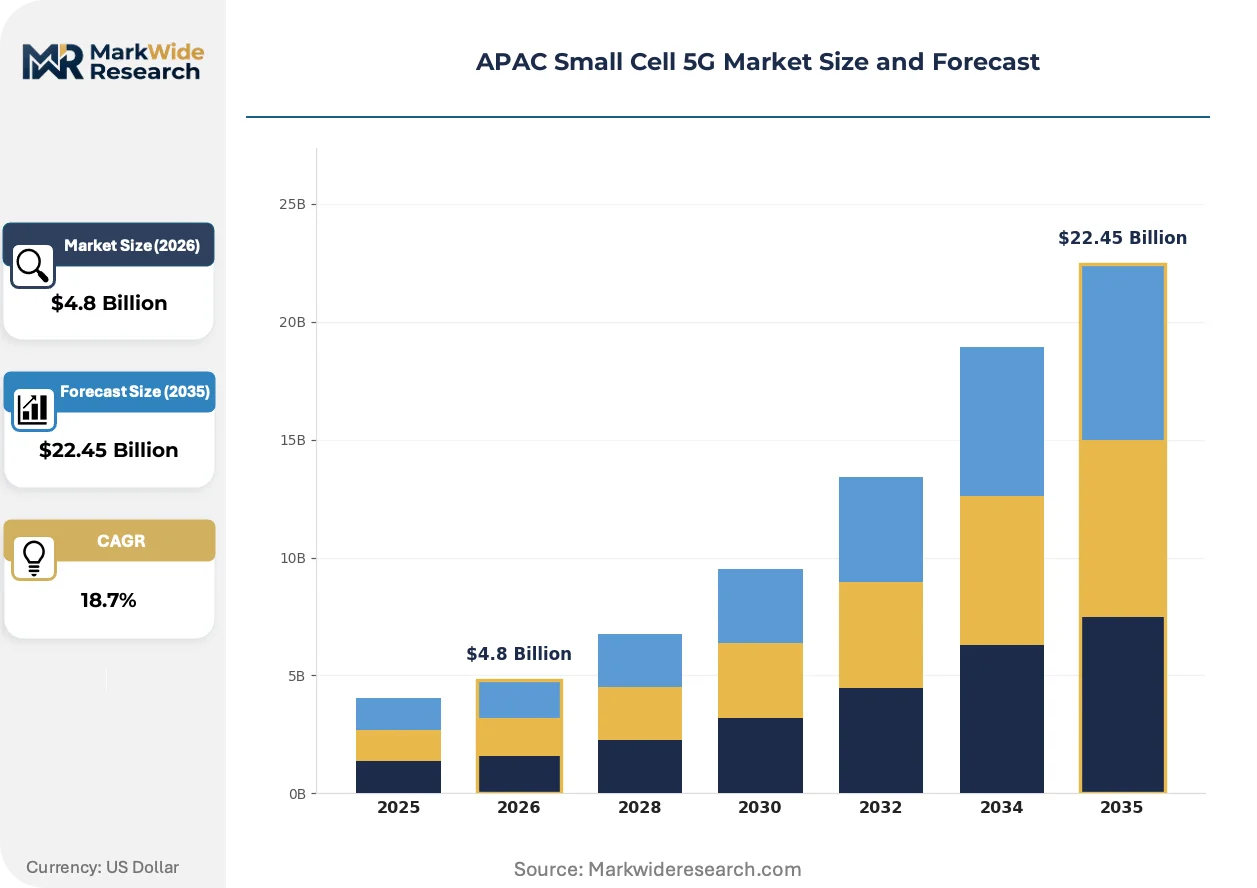
Market Dynamics
China's MIIT security certification mandates for core network elements are fragmenting vendor access across APAC, creating divergent compliance tracks that reward pre-certified suppliers and raise barriers for late entrants into enterprise and industrial segments.
Growth Catalysts
- TRAI spectrum reforms:India's private 5G network licensing liberalization lowers entry barriers for manufacturing campuses and logistics hubs seeking captive connectivity.
- Smart manufacturing clusters:South Korea's industrial zones in Gyeonggi-do and Ulsan drive concentrated femtocell and picocell deployment for industrial IoT and automated quality control.
- Dense urban corridor densification:Japan's railway operators and stadium venues generate sustained microcell and metrocell demand for traffic spike management.
Market Restraints
- GaN and RF frontend cost volatility:Compound semiconductor supply concentration in Taiwan and South Korea exposes equipment vendors to input price swings and allocation constraints.
- MIIT domestic certification bifurcation:China's mandatory security testing for core network elements creates dual compliance tracks that extend product launch timelines by 8-14 months for non-domestic suppliers.
- Macrocell capacity expansion:Carrier investments in massive MIMO macro upgrades in lower-density Australian and Southeast Asian markets delay small cell prioritization.
Strategic Opportunities
- Indonesia's industrial estate zones:Batam and Karawang manufacturing corridors remain underpenetrated for private 5G networks, offering first-mover positioning for integrated solution providers.
- Open RAN interoperability mandates:Japan's MIC and South Korea's MSIT equipment authorization guidelines increasingly favor disaggregated architectures, creating white space for multi-vendor system integrators.
- AI-driven radio resource management:Convergence of machine learning inference at the network edge with small cell baseband units enables dynamic spectrum allocation for Industry 4.0 applications.
Industry Challenges
- Massive MIMO beamforming expertise scarcity:RF system design and digital precoding algorithm development talent concentrates in Seoul, Shenzhen, and Tokyo, constraining vendor R&D scaling.
- Multi-country type approval complexity:Divergent electromagnetic compatibility testing between China's GB standards, Japan's TELEC, and Australia's ACMA extends certification cycles and fragments product SKUs.
- Legacy 4G small cell integration friction:Enterprise buyers demand seamless handoff management between existing LTE picocells and 5G NR units, complicating deployment architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Small Cell 5G Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Femtocells, Picocells, Microcells, Metrocells Installation Type: Indoor, Outdoor, Distributed Antenna System, Hybrid Use Case: Residential, Urban, Enterprise, Venue Service Type: Managed Service, Professional Service, Consulting, Integration |
| Companies Covered | Huawei Technologies, Nokia Corporation, Telefonaktiebolaget LM Ericsson, ZTE Corporation, Samsung Electronics, Qualcomm Technologies, NEC Corporation, Fujitsu, CommScope, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Small Cell 5G Market Strategic Shifts
Three forces are actively reshaping APAC small cell deployment architectures: edge-native intelligence migration, regulatory pressure toward vendor interoperability, and enterprise procurement consolidation around integrated solution bundles rather than discrete hardware transactions.
Massive MIMO digital beamforming is automating radio resource allocation in real-time for industrial IoT and immersive media workloads. Automotive manufacturers in South Korea and Japan are deploying these units at scale for connected factory floors. The technology is automating what previously required manual RF planning, compressing deployment timelines from months to weeks for dense venue environments.
Japan's Ministry of Internal Affairs and Communications has tightened Open RAN functional split requirements in its 2024 radio equipment authorization guidelines. This policy shift forces incumbent integrated-stack vendors to disaggregate their baseband and radio unit architectures to maintain market access. South Korea's MSIT is now considering parallel interoperability mandates, pressuring suppliers to accelerate RAN software roadmap investments.
Enterprise buyers across Vietnam and Thailand are consolidating procurement decisions under integrated digital infrastructure contracts that bundle small cell hardware with managed services and edge compute. Systems integrators and telecom operators are displacing direct vendor relationships as the primary channel for campus and venue deployments. This pattern is most visible in Thailand's Eastern Economic Corridor manufacturing zones, where conglomerates negotiate single-source connectivity partnerships.
APAC Small Cell 5G Market Segmentation
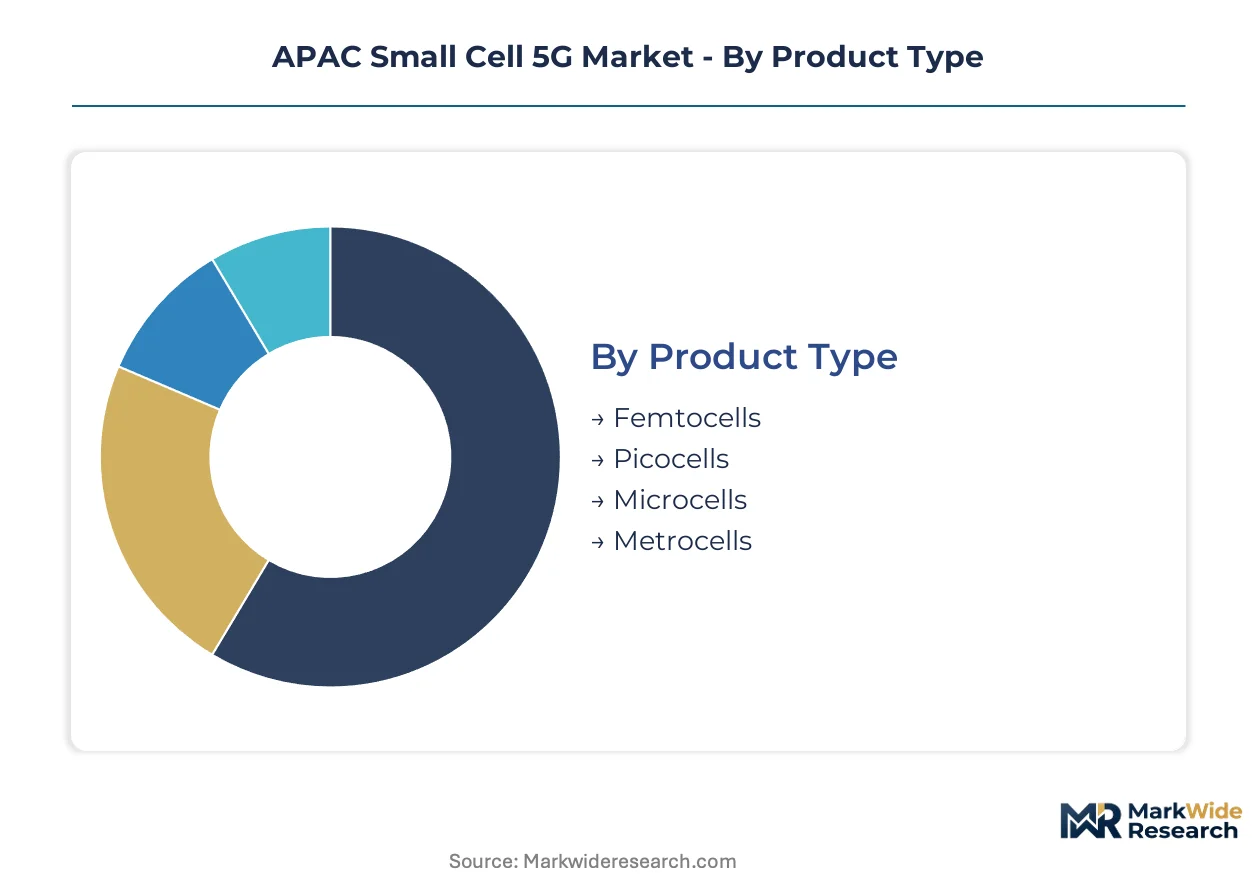
Segmentation in the APAC Small Cell 5G Market reveals how capital deployment, regulatory complexity, and end-use concentration create divergent margin profiles across hardware and service categories. Understanding these fault lines enables vendors to align R&D roadmaps with procurement patterns that differ sharply between carrier-led urban densification and enterprise-driven private network builds.
Product Type:
Capital intensity escalates dramatically with transmit power and coverage radius, separating low-volume femtocell residential deployments from infrastructure-grade metrocell investments that absorb the majority of carrier CapEx in dense urban corridors.
- Femtocells:Low-power units operating below 100 milliwatts serve residential and SOHO environments with plug-and-play simplicity. South Korea's apartment-dense districts generate concentrated demand for self-installed units that backhaul over existing fiber. Deployment constraints center on interference coordination with macro networks in spectrum-scarce Japanese urban cores.
- Picocells:Intermediate-power nodes covering 100-250 meters anchor indoor enterprise deployments across Thailand's Eastern Economic Corridor manufacturing campuses. Indian IT parks in Bangalore and Hyderabad drive procurement volume as TRAI's private 5G licensing enables captive network ownership. Capital requirements sit 3-4x above femtocells due to integrated baseband processing and carrier-grade synchronization.
- Microcells:Street-level units with 500-meter to 2-kilometer range target outdoor urban densification in China's tier-1 cities where MIIT mandates domestic security certification.
- Metrocells:High-capacity nodes engineered for concentrated traffic spikes dominate Japan's railway stations and stadium venues.
Most installed capacity flows through picocells. Expansion is steepest in metrocells.
Installation Type:
Site acquisition costs and backhaul complexity fragment deployment economics, with outdoor street furniture installations demanding 5-8x the upfront investment of indoor ceiling-mounted units despite similar hardware price points.
- Indoor:Ceiling-mounted and wall-mounted configurations dominate enterprise campus deployments across Vietnam's industrial zones. South Korean smart factories in Gyeonggi-do specify integrated small cell and edge compute enclosures. Cooling and power redundancy requirements elevate total cost of ownership versus residential femtocell alternatives.
- Outdoor:Pole-mounted and building-mounted installations face municipal permitting timelines that stretch 6-18 months in Australian metropolitan councils. Japan's MIC streamlines authorization for railway corridor deployments. Weatherproofing and passive thermal management add material cost premiums over indoor equivalents.
- Distributed Antenna System:Fiber-fed remote radio heads extend coverage through complex building geometries in Indonesia's Jakarta commercial towers.
- Hybrid:Combined indoor-outdoor architectures serve logistics hubs requiring seamless handoff across warehouse interiors and loading dock perimeters.
Indoor deployments absorb the majority of unit shipments. Outdoor configurations command the steepest expansion trajectory as urban densification accelerates.
Use Case:
Procurement authority concentration separates consumer-driven residential markets from enterprise segments where CIOs negotiate multi-year managed service bundles.
- Residential:Self-provisioned units purchased through carrier retail channels concentrate in South Korea's high-rise apartment districts. India's fiber-to-the-home expansion in Mumbai and Delhi creates addressable market growth. Price sensitivity limits average selling prices compared to commercial alternatives.
- Urban:Carrier-managed street-level densification targets pedestrian corridors and transport hubs across Singapore's downtown core. Australia's NBN backhaul integration shapes vendor selection criteria. Spectrum coordination with existing macro layers complicates deployment planning.
- Enterprise:Manufacturing campuses and logistics hubs in Thailand and Vietnam represent the most rapidly scaling demand pool as Industry 4.0 investments accelerate. Private 5G licensing enables captive spectrum ownership that reduces ongoing opex.
- Venue:Stadiums, convention centers, and exhibition halls in Japan and Australia justify premium metrocell configurations for event-driven traffic spikes.
Enterprise use cases absorb the fastest-growing share of new installations. Urban densification retains the largest cumulative deployed base.
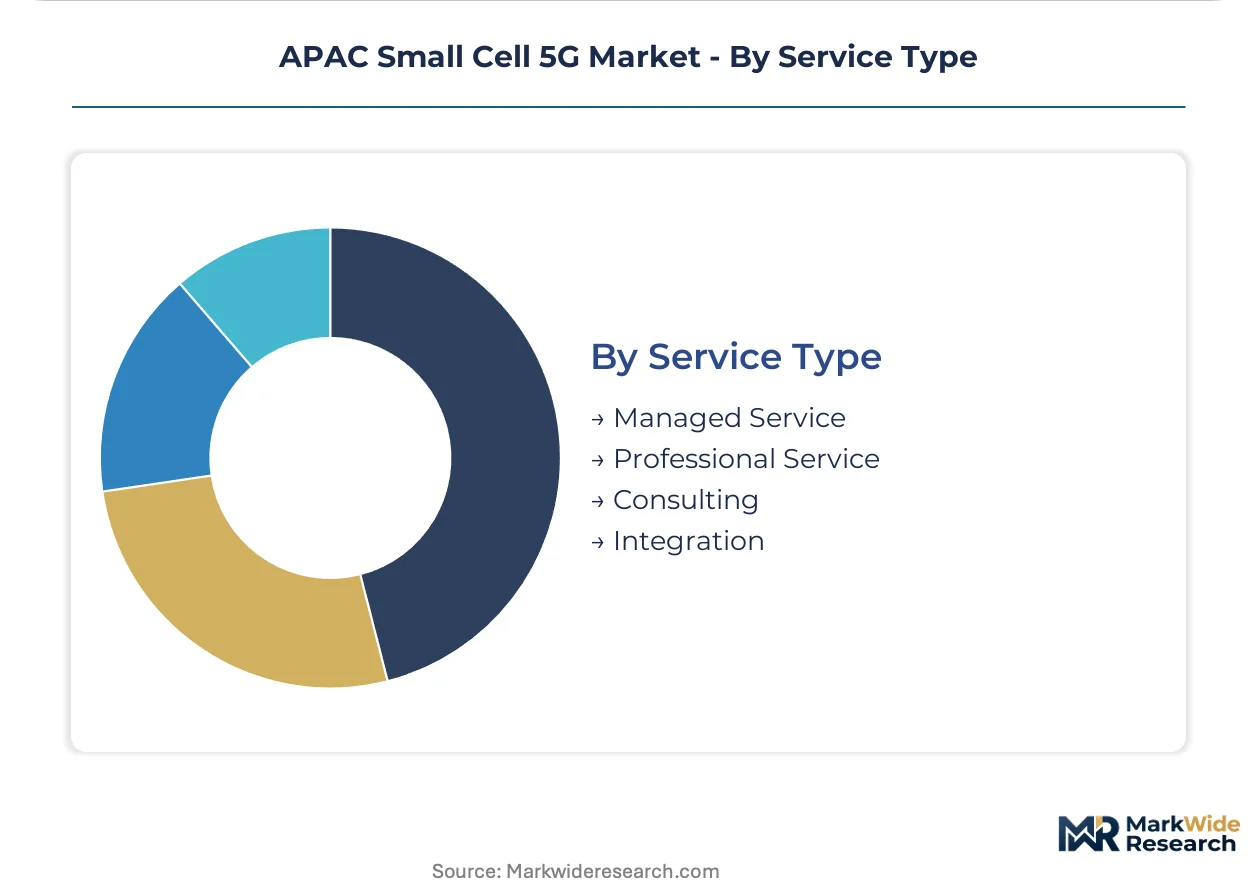
Service Type:
Margin structures invert between hardware-centric integration services and recurring managed service contracts that extend customer lifetime value across 5-7 year horizons.
- Managed Service:End-to-end network operation and maintenance contracts dominate enterprise procurement in Indonesia's Batam industrial zone where local IT capability constraints favor outsourcing. Japanese manufacturing conglomerates negotiate performance-based SLAs with penalties for downtime. Recurring revenue streams justify upfront hardware subsidies.
- Professional Service:Site survey, RF planning, and installation project work concentrates with systems integrators serving Thailand's Eastern Economic Corridor. South Korean carriers bundle professional services with hardware to defend against Open RAN disaggregation. Project-based revenue creates quarterly volatility.
- Consulting:Spectrum strategy and regulatory navigation support assists enterprises navigating India's TRAI private 5G licensing framework.
- Integration:Multi-vendor system assembly and testing services expand as Japan's MIC Open RAN mandates proliferate.
Managed services capture the majority of service revenue. Integration services are climbing the fastest as interoperability requirements fragment vendor ecosystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Small cell 5G infrastructure first achieved commercial scale in Japan and South Korea during the late 2010s, establishing the technical and regulatory templates that now propagate across emerging APAC markets. The regional landscape today reflects this bifurcated heritage: mature East Asian markets drive architectural innovation while Southeast Asian industrial corridors absorb deployment volume.
China
MIIT's domestic security certification for core network elements creates a bifurcated compliance environment that extends product launch timelines by 8-14 months for non-domestic suppliers. The Yangtze River Delta and Pearl River Delta industrial clusters concentrate demand from smart manufacturing campuses seeking captive 5G connectivity. Tier-1 cities including Shanghai and Shenzhen prioritize outdoor urban densification with microcell deployments.
Japan
Railway operators and stadium venues generate sustained demand for high-capacity metrocell configurations capable of managing concentrated traffic spikes. MIC's 2024 radio equipment authorization guidelines tightened Open RAN functional split requirements, forcing architecture disaggregation. The Kanto region around Tokyo anchors deployment volume, with Osaka's Kansai corridor following in enterprise adoption.
South Korea
MSIT equipment authorization frameworks increasingly favor disaggregated RAN architectures, creating procurement pathways for multi-vendor system integrators. The Gyeonggi-do and Ulsan industrial zones drive concentrated femtocell and picocell deployment for automated quality control and industrial IoT. Samsung Electronics leverages vertical integration to dominate the enterprise segment with mmWave radio units.
India
TRAI's private 5G network licensing liberalization lowers entry barriers for manufacturing campuses and logistics hubs seeking captive spectrum ownership. IT parks in Bangalore and Hyderabad represent the fastest-scaling demand pools as enterprises navigate the new regulatory framework. Mumbai and Delhi fiber-to-the-home expansion creates adjacent residential market growth.
Thailand
The Eastern Economic Corridor manufacturing zones consolidate procurement under integrated digital infrastructure contracts bundling hardware with managed services. Conglomerates negotiate single-source connectivity partnerships, displacing direct vendor relationships. Vietnam's adjacent industrial zones in Binh Duong and Dong Nai mirror this pattern as regional supply chain relocation accelerates.
APAC Small Cell 5G Market Competitive Environment
The competitive structure tilts toward integrated-stack incumbents with captive semiconductor capabilities, though regulatory pressure toward Open RAN interoperability is fragmenting traditional procurement patterns. Three archetypes dominate: vertically integrated conglomerates controlling RF frontend through captive chip design; European and North American vendors betting architecture disaggregation; and systems integrators capturing enterprise procurement consolidation. Competitive moves center on R&D intensity in massive MIMO beamforming and strategic positioning for Indonesia's underpenetrated industrial estate zones.
Among the integrated-stack anchors, Huawei Technologies and Samsung Electronics exemplify the conglomerate archetype with semiconductor self-sufficiency, while Nokia Corporation occupies a position representing European R&D-focused vendors navigating Open RAN mandates. ZTE Corporation and NEC Corporation sit within the tier of established infrastructure suppliers adapting product roadmaps to Japan's MIC and South Korea's MSIT interoperability guidelines. Qualcomm Technologies anchors the component-level specialist position supplying RF frontends across vendor ecosystems.
| Leading Market Players |
|---|
| Huawei Technologies |
| Nokia Corporation |
| Telefonaktiebolaget LM Ericsson |
| ZTE Corporation |
| Samsung Electronics |
| Qualcomm Technologies |
| NEC Corporation |
| Fujitsu |
| CommScope |
| Others |
Value Chain & Pricing Dynamics
Compound semiconductor spot prices for gallium nitride and silicon germanium cascade through RF frontend procurement tiers, compressing margins for equipment vendors while creating three distinct pricing bands tied to certification grade and volume scale.
Pricing Analysis
Project-based hardware procurement with multi-year managed service bundling dominates enterprise transactions across Thailand's Eastern Economic Corridor and Vietnam's Binh Duong industrial zones. Price differentiation hinges on MIIT domestic security certification status and Open RAN interoperability compliance, with pre-certified suppliers commanding 15-20% premiums over late entrants. Cost compression in residential femtocell tiers intensifies as South Korean carriers subsidize self-install units to defend subscriber bases. Manufacturing campuses exhibit lowest price sensitivity due to captive spectrum ownership reducing long-term opex, while residential buyers in India's fiber expansion zones resist hardware premiums above carrier-subsidized entry points.
Supply Chain Analysis
Dual-sourcing mandates from Japan's NTT and South Korea's SK Telecom require qualified secondary suppliers for RF power amplifiers and baseband processing units, fragmenting procurement concentration despite Taiwan and South Korea dominating GaN foundry output. Raw material dependencies center on gallium nitride substrates, high-purity silicon germanium, and advanced ceramic packaging from Japanese suppliers. Single-source vulnerability concentrates in Taiwan's 6-inch GaN-on-SiC wafer fabrication, where earthquake risk and water-intensive processing create supply continuity exposure. Distribution runs through carrier procurement consortia in mature markets and systems integrator channels in Indonesia's underpenetrated Batam and Karawang corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in APAC small cell 5G rests on GaN cost-down curves and enterprise buyers shifting procurement toward premium-tier integrated solution bundles with embedded edge compute.
For Market Incumbents: Acquire captive RF semiconductor design capabilities to defend against Open RAN disaggregation pressure from Japan's MIC interoperability mandates. Consolidate certification pre-qualification across China's MIIT, Japan's TELEC, and South Korea's MSIT to compress product launch timelines by 8-14 months. Deepen backward integration into GaN power amplifier fabrication to offset Taiwan foundry allocation constraints and input price volatility. For New Entrants and Emerging Players: Cloud-native network management platforms offer the lowest-friction entry vector for Indonesia's Batam and Karawang industrial estates, where local IT capability gaps favor outsourced network operations. Target Thailand's Eastern Economic Corridor manufacturing zones with private 5G-as-a-service offerings that bundle hardware, spectrum access, and managed SLAs under single-source contracts. Lead with AI-driven radio resource management as the primary technical differentiator against incumbent integrated-stack vendors. For Investors and Strategic Acquirers: Asymmetric upside sits with multi-vendor system integrators possessing pre-certified Open RAN interoperability and established carrier relationships across Japan and South Korea. Long-term viability favors specialists with software-defined RAN expertise over hardware-centric vendors exposed to GaN cost volatility. Watch for Indonesia's industrial estate authority issuing private 5G spectrum framework guidance as the inflection signal for Southeast Asian deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Interoperability Certification | Japan's MIC 2024 guidelines force architecture disaggregation, rewarding pre-certified suppliers with faster market access. |
| Captive GaN Semiconductor Fabrication | Backward integration into RF power amplifiers insulates margins from Taiwan foundry allocation constraints and price swings. |
| Private 5G Managed Service Bundling | Thailand's Eastern Economic Corridor conglomerates consolidate procurement under single-source connectivity partnerships. |
| AI-Driven Radio Resource Management | Machine learning inference at the network edge enables dynamic spectrum allocation for Industry 4.0 manufacturing applications. |
| Multi-Country Type Approval Pre-Qualification | Simultaneous certification across China's MIIT, Japan's TELEC, and South Korea's MSIT compresses product launch timelines. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with carrier procurement executives, RF system design engineers, enterprise IT directors at manufacturing campuses, and regulatory affairs specialists at equipment vendors with secondary validation. Secondary sources included MIIT equipment authorization filings, TELEC certification databases, TRAI private 5G licensing circulars, carrier CapEx disclosure filings, and hyperscaler edge compute partnership announcements. Bottom-up unit shipment modeling across femtocell, picocell, microcell, and metrocell categories triangulated against top-down carrier infrastructure spending forecasts.
Segment-weighting approaches applied differential growth assumptions across enterprise, residential, urban densification, and venue use cases, with additional granularity for indoor versus outdoor installation economics and managed service versus professional service revenue mix. Modeled dimensions included product type, installation configuration, end-use application, and service delivery model. CAGRs derived from regression analysis of historical deployment trajectories in Japan and South Korea, applied to emerging market penetration curves with adjustments for regulatory timeline uncertainty. Industry-specific inputs incorporated GaN substrate pricing indices, spectrum auction schedules, and Open RAN interoperability mandate implementation pace.
Regulatory timeline slippage, compound semiconductor supply disruption, and macrocell capacity substitution in lower-density markets are the dominant revision risks that could compress deployment forecasts or shift capital allocation priorities. Forecasts reflect documented assumptions about carrier CapEx commitment durability and enterprise private network licensing uptake rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Distributed Antenna System Market
Wireless Technologies
Global Wireless Testing Market
Wireless Technologies
5G Spectrum Market
Wireless Technologies
P2P Antennas Market
Wireless Technologies
Global in-Building Wireless Market
Wireless Technologies
Latin America Wireless Mesh Networking Market
Wireless Technologies
APAC Small Cell Tower Market
Wireless Technologies
Industrial Bluetooth Market
Wireless Technologies
Wi-Fi 7 Market
Wireless Technologies
Wireless Paging Systems Market
Wireless Technologies
Underwater Wireless Communication Market
Wireless Technologies
Wireless Phone Chargers Market
Wireless Technologies
Global WLAN Market
Wireless Technologies
Cellular Repeater Market
Wireless Technologies
Wireless Microphone Market
Wireless Technologies
Wireless Intercoms Market