
 Utility Communications Market | 2026-2036
Utility Communications Market Size, Share, and Industry Trends Forecast 2026-2036
Utility Communications Market Analysis
Aftermarket network management services is reconfiguring margin pools away from one-time hardware sales toward recurring software revenue in the utility communications sector. Schneider Electric SE leverages its integrated energy management platform to anchor long-term service contracts across European grid operators. Siemens AG competes through its specialized automation portfolio for SCADA-centric deployments, while Cisco Systems Inc. dominates cybersecurity-layer subscriptions that protect critical infrastructure endpoints.
Utility communications encompasses the transmission infrastructure, protocols, and management systems that enable real-time data exchange between generation assets, distribution networks, and consumer endpoints, operating across fiber optic backbones, microwave relays, satellite links, and power-line carrier channels with latency requirements typically below 100 milliseconds for protection signaling. The technology dimension shows fiber optics commanding the largest installed base for metropolitan substation interconnects, though power-line carrier retains cost advantages in rural distribution feeders where trenching costs prove prohibitive. Application-level spending tilts toward SCADA systems and outage management platforms as utilities prioritize operational resilience over incremental metering deployments.
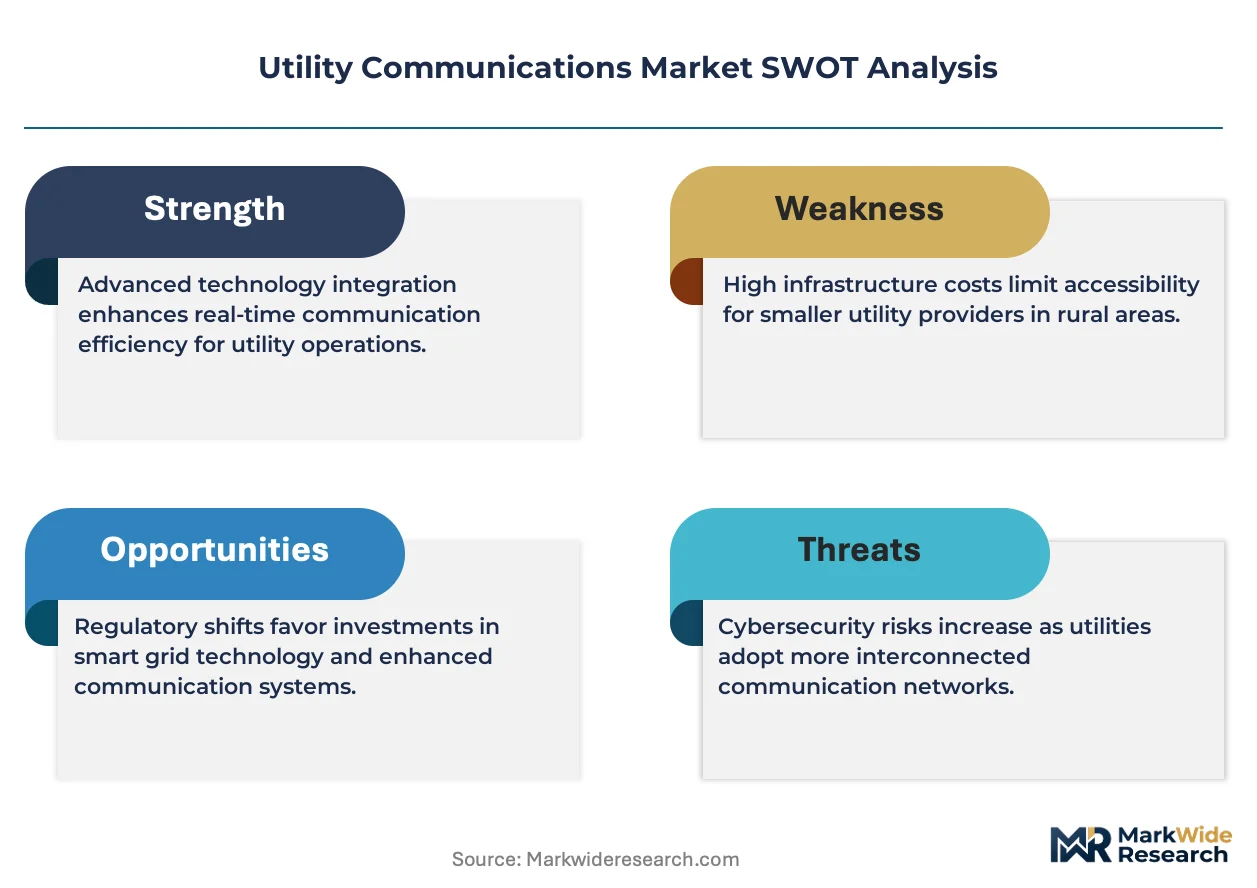
The Federal Energy Regulatory Commission in the United States enforces mandatory reliability standards through NERC CIP that dictate encryption and access-control specifications for bulk electric system communications. The European Union's Cybersecurity Act and NIS2 Directive establish baseline certification requirements for operators of essential energy infrastructure across member states. Stakeholders must monitor evolving cross-border harmonization between these frameworks as procurement specifications increasingly embed compliance prerequisites into vendor selection criteria.
Market Dynamics
Grid operators are reallocating capital from proprietary radio-frequency networks toward IP-native fiber infrastructure as NERC CIP encryption mandates harden protection signaling requirements across North American bulk electric systems.
Growth Catalysts
- FERC Order 2222:Distributed energy resource aggregation rules in the United States are forcing utilities to deploy bidirectional communication gateways for behind-the-meter asset coordination.
- AMI 2.0 specifications:Advanced metering infrastructure upgrades are pulling capital toward mesh network architectures capable of 15-minute interval data transmission.
- Substation automation:IEC 61850 protocol adoption is accelerating process bus deployments for sampled value messaging in high-voltage protection schemes.
Market Restraints
- Copper and optical fiber input costs:Raw material price volatility is compressing margins on cable-heavy rural distribution projects.
- Semiconductor foundry concentration:Taiwan-based chip fabrication bottlenecks are extending lead times for field-programmable gate arrays used in intelligent electronic devices.
- Power-line carrier bandwidth ceiling:Narrowband PLC throughput limitations below 500 kbps are restricting video surveillance backhaul on distribution feeders.
Strategic Opportunities
- India rural electrification:The country's SAUBHAGYA scheme is creating demand for low-cost narrowband RF mesh in unserved distribution territories.
- EU Cybersecurity Act certification:Common Criteria evaluation mandates for critical infrastructure are opening service revenue streams for compliance consulting.
- 5G private network slicing:Convergence of cellular radio access network technology with time-sensitive networking is enabling microsecond-synchronized protection for distributed generation.
Industry Challenges
- IEC 61850 engineering expertise:Shortage of substation automation specialists fluent in SCL configuration and GOOSE messaging is delaying commissioning timelines.
- Multi-protocol gateway integration:Translating between DNP3, Modbus, and IEC 61850 in brownfield substations is introducing latency and cybersecurity attack surfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility Communications Market |
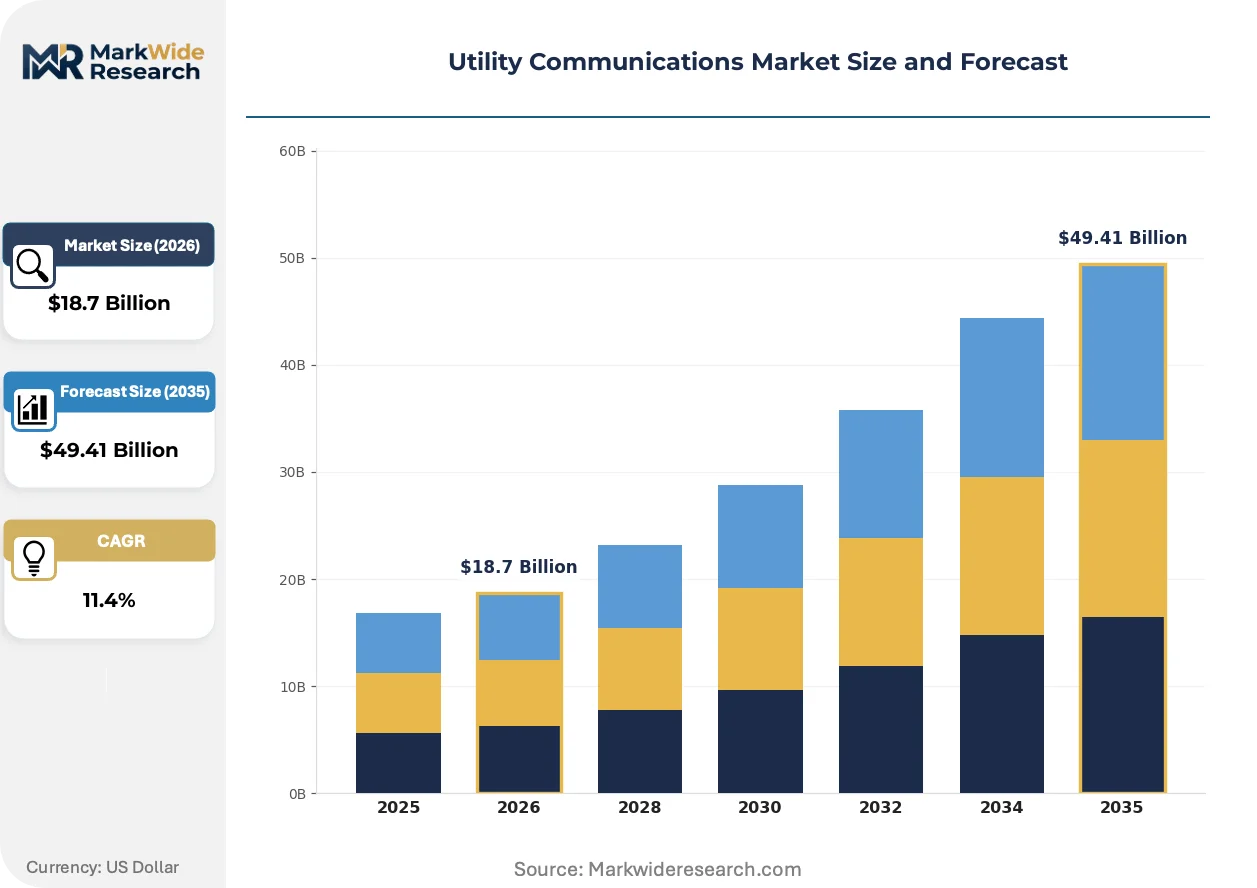
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fiber Optics, Microwave, Satellite, PLC Application: Smart Metering, SCADA Systems, Outage Management, Demand Response End User: Electric Utilities, Water Utilities, Gas Utilities, Energy Providers Solution: Network Management, Data Analytics, Security Solutions, Billing Systems |
| Companies Covered | Schneider Electric SE, Landis+Gyr, Siemens AG, General Electric Company, Huawei Technologies Co., Ltd., Cisco Systems Inc., Itron Inc., Telefonaktiebolaget LM Ericsson (publ), ABB Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility Communications Market Emerging Trajectories
Communications architecture decisions are pivoting from coverage-centric radio deployments toward deterministic latency guarantees that protect revenue-grade metering and synchronous machine control.
Time-sensitive networking over Ethernet is migrating from pilot substation trials toward standardized protection relay backhaul. European transmission operators in Germany and France are adopting TSN-enabled process buses for sampled value streams. This migration is compressing the installed base of copper-based point-to-point wiring inside high-voltage yards.
The European Union's NIS2 Directive is mandating incident reporting thresholds and supply-chain security audits for operators of essential energy infrastructure. Member state regulators are transposing these requirements into procurement specifications that disqualify vendors lacking CE-marked cybersecurity certification. Scandinavian distribution utilities are responding by consolidating vendor panels to reduce third-party risk exposure.
Utility procurement departments are unbundling network management software from hardware supply agreements. North American cooperatives and municipal utilities are subscribing to cloud-hosted SCADA platforms rather than capitalizing on-premise servers. This shift is most visible in the southwestern United States where capital-constrained rural utilities lack internal IT staffing depth.
Utility Communications Market Segmentation
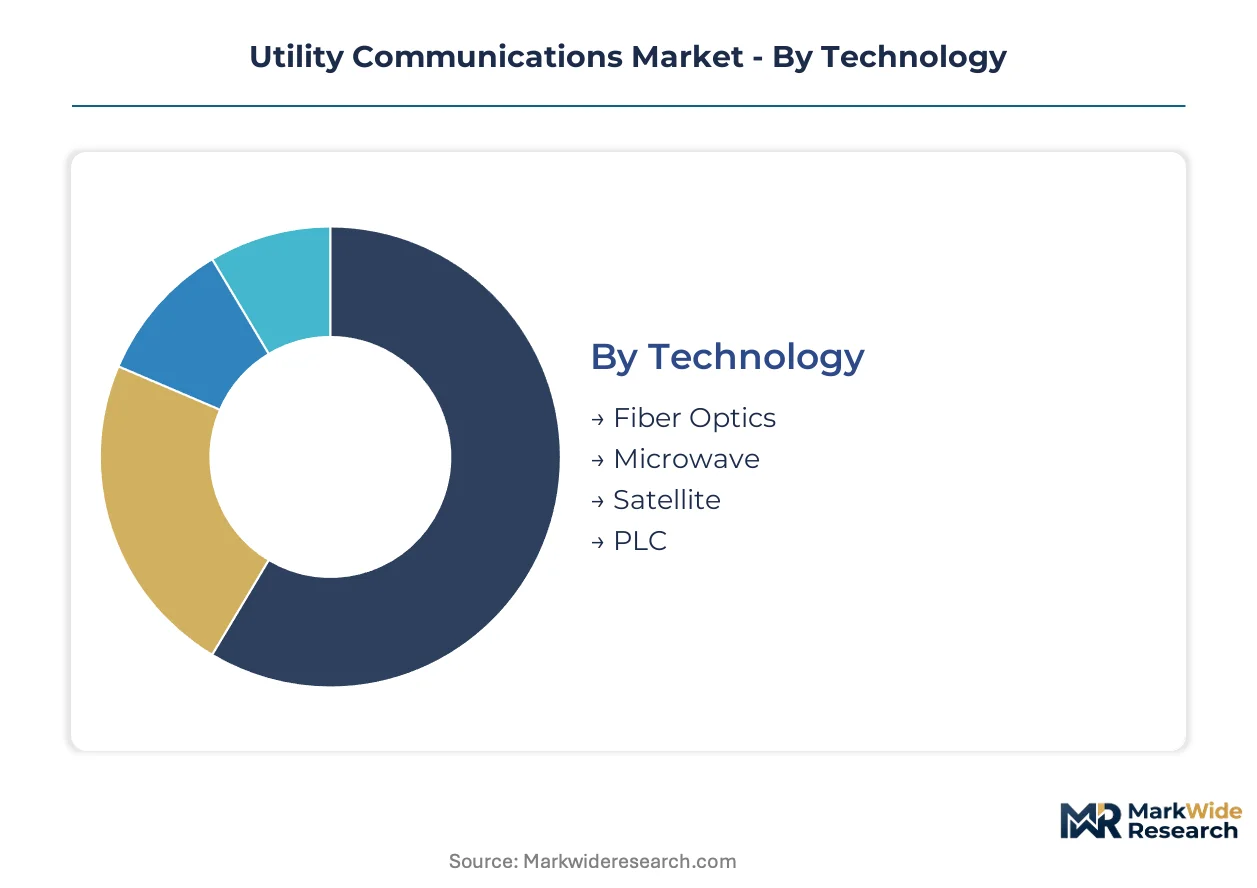
Utility communications segmentation reveals stark divergence in asset lifecycles. Fiber infrastructure commits capital for decades while software solutions turn over in 3-5 year refresh cycles. Procurement strategies must calibrate to these mismatched horizons.
Technology:
Replacement cycles stretch from 7 years for wireless links to 25+ years for buried fiber, creating stranded asset risk when protocols evolve mid-deployment.
- Fiber Optics:Single-mode and multimode glass fiber delivers sub-millisecond latency across metropolitan substation rings. United States transmission operators in Texas and California are trenching dedicated optical ground wire circuits to satisfy NERC CIP encryption mandates for protection signaling.
- Power-Line Carrier:Narrowband and broadband signal injection over medium-voltage conductors avoids civil works costs in rural territories. German distribution utilities in Bavaria retain PLC for last-mile feeder automation where terrain obstructs radio line-of-sight.
- Microwave:Point-to-point radio links bridge geographic barriers across river valleys and protected land.
- Satellite:Geostationary and low-earth-orbit constellations serve remote generation outposts beyond terrestrial infrastructure reach.
Fiber optics anchors the volume base while satellite gains share at the steepest rate as LEO constellation economics improve.
Application:
Capital allocation tilts toward operational resilience platforms over consumer-facing metering as grid hardening priorities intensify.
- SCADA Systems:Supervisory control and data acquisition platforms aggregate real-time telemetry from remote terminal units. IEC 61850 protocol adoption in French transmission operator RTE's substations is accelerating process bus deployments for sampled value messaging.
- Outage Management:Geographic information system integration with automated switching minimizes restoration intervals. Hurricane-prone utilities in Florida are prioritizing fault location isolation and service restoration analytics over incremental metering density.
- Smart Metering:Advanced metering infrastructure enables 15-minute interval consumption data for time-of-use tariffs.
- Demand Response:Aggregated behind-the-meter load curtailment programs require bidirectional gateway coordination.
SCADA systems command the largest installed value while outage management platforms expand most quickly following climate-driven reliability mandates.
End User:
Regulatory exposure and rate-base treatment create divergent procurement appetites across utility ownership structures.
- Electric Utilities:Vertically integrated and unbundled power companies face NERC CIP and NIS2 compliance burdens driving security-layer investment. Investor-owned utilities in Ohio and Pennsylvania are consolidating vendor panels to reduce third-party cyber risk exposure.
- Water Utilities:Municipal and regional water authorities deploy AMI for leak detection and pressure management. California's urban water districts are accelerating advanced metering to meet state conservation mandates under persistent drought conditions.
- Gas Utilities:Distribution operators monitor pipeline pressure and cathodic protection systems.
- Energy Providers:Competitive retail suppliers and distributed generation aggregators require customer-facing communication gateways.
Electric utilities dominate capital deployment while water utilities are climbing the fastest as smart city funding unlocks AMI budgets.
Solution:
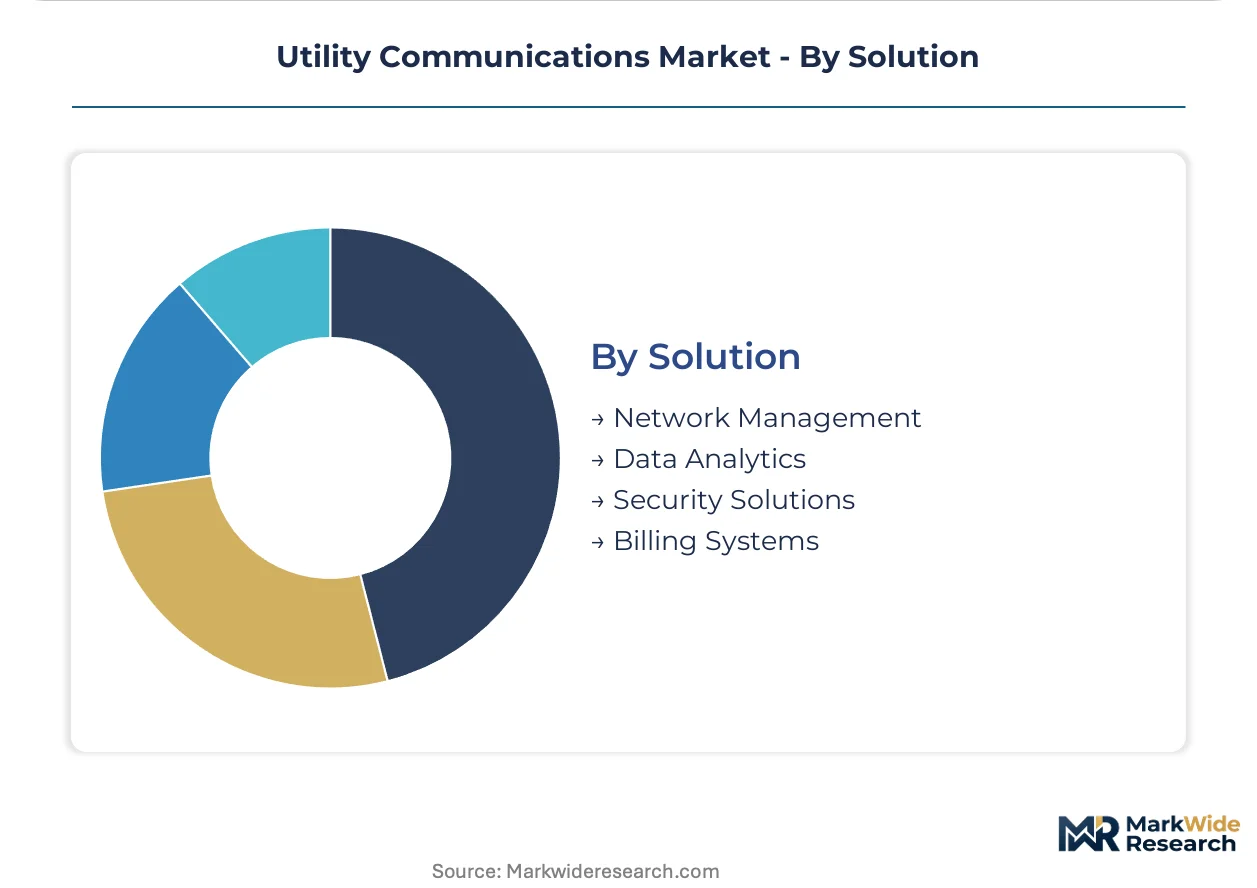
Revenue models are pivoting from perpetual licenses toward recurring subscriptions as cloud delivery matures.
- Security Solutions:Encryption, access control, and intrusion detection systems protect critical infrastructure endpoints. FERC Order 848 mandates internal network security monitoring across bulk electric system assets, pulling utilities toward managed detection and response services.
- Data Analytics:Predictive maintenance and load forecasting platforms process streaming sensor telemetry. Texas grid operator ERCOT's congestion management systems rely on real-time nodal price analytics to coordinate distributed generation dispatch.
- Network Management:Configuration, performance, and fault management software orchestrates multi-vendor device fleets.
- Billing Systems:Meter-to-cash platforms integrate interval data with customer information systems.
Security solutions generate the highest margin per dollar deployed while data analytics platforms are expanding most quickly as AI-enabled forecasting matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility communications deployment patterns diverge sharply by geography. The United States prioritizes cybersecurity-hardened fiber backbones for bulk electric systems. Germany emphasizes substation automation with IEC 61850 protocols. China scales narrowband PLC for rural electrification while India pursues low-cost RF mesh networks.
United States
FERC Order 2222 and NERC CIP mandates are accelerating IP-native fiber deployment across Texas and California transmission operators. The Federal Energy Regulatory Commission enforces encryption standards that disqualify legacy radio-frequency networks from protection signaling circuits. ERCOT's nodal congestion management systems in Austin and Dallas anchor real-time analytics demand for distributed generation coordination.
Germany
Bavarian distribution utilities retain power-line carrier for terrain-challenged feeder automation where radio line-of-sight fails. The EU Cybersecurity Act and NIS2 Directive transposed into German procurement specifications require CE-marked certification for critical infrastructure vendors. RTE's TSN-enabled process bus trials in French substations are spurring cross-border harmonization pressure on German transmission operator TenneT.
China
State Grid Corporation deploys narrowband PLC at scale for unserved rural distribution territories under universal electrification targets. The country's national energy regulator enforces smart grid investment quotas that channel capital toward AMI 2.0 mesh architectures. Yangtze River Delta utilities in Shanghai and Jiangsu province concentrate demand for metropolitan fiber rings serving high-density substation interconnects.
India
SAUBHAGYA rural electrification scheme is generating procurement volume for low-cost narrowband RF mesh in Bihar and Uttar Pradesh distribution territories. The Central Electricity Authority mandates communication redundancy standards that favor multi-technology deployments. Maharashtra State Electricity Distribution Company in Mumbai anchors urban smart metering pilots with 15-minute interval data requirements.
Utility Communications Market Vendor Landscape
Capability concentration sits with specialized automation vendors; scale advantage sits with diversified industrial conglomerates. The market structures around three tiers: integrated energy management platforms, SCADA-centric automation portfolios, and cybersecurity-layer subscription services. Strategic archetypes include full-stack platform providers, protocol-specialist relay manufacturers, and managed security service operators. Competitive moves center on vendor panel consolidation to reduce third-party cyber risk and cloud-hosted service unbundling from hardware supply agreements.
Within the integrated platform tier, Schneider Electric SE and Siemens AG represent contrasting European approaches to long-term service contracting. Schneider Electric SE anchors its position through energy management platform integration, while Siemens AG exemplifies SCADA-centric automation specialization. Cisco Systems Inc. occupies the cybersecurity subscription vector, protecting critical infrastructure endpoints through encryption and access-control layers. These three companies illustrate how procurement specifications increasingly embed compliance prerequisites into vendor selection criteria across North American and European grid operators.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Landis+Gyr |
| Siemens AG |
| General Electric Company |
| Huawei Technologies Co., Ltd. |
| Cisco Systems Inc. |
| Itron Inc. |
| Telefonaktiebolaget LM Ericsson (publ) |
| ABB Ltd |
| Others |
Supply Flow & Price Mechanics
Taiwan-based semiconductor foundry concentration determines both margin compression in intelligent electronic device tiers and the geographic reshaping of component sourcing across utility communications hardware. FERC encryption mandates for NERC CIP compliance widen pricing spreads between certified and uncertified equipment, forcing procurement departments toward long-term service contracts that absorb volatility.
Pricing Analysis
Long-term service contracts dominate capital allocation as utilities shift from perpetual software licenses toward recurring cybersecurity subscriptions. Pricing stratifies across IEC 61850-certified protection relays, CE-marked network gateways, and uncertified commodity radios based on compliance tier and after-sales support bundling. Cost compression in rural fiber trenching projects intensifies as copper and optical fiber input costs fluctuate. Municipal utilities exhibit highest price sensitivity due to rate-base constraints, while investor-owned transmission operators absorb premium tiers for NERC CIP-mandated encryption layers.
Supply Chain Analysis
Export controls on field-programmable gate arrays and encryption chipsets limit component flows from Taiwan, South Korea, and the United States into Chinese and Russian utility infrastructure projects. Manufacturing rests on gallium arsenide substrates, single-mode fiber preforms, and precision optical transceivers concentrated in East Asian fabrication hubs. Single-source vulnerability in Taiwan-based foundries extends lead times for intelligent electronic devices during geopolitical friction. Distribution runs through authorized vendor panels consolidated by European and North American grid operators to reduce third-party cyber risk exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortage of substation automation engineers fluent in SCL configuration and GOOSE messaging constrains deployment velocity, creating a capability bottleneck that favors incumbents with established training pipelines and certification programs.
For Market Incumbents: Entrench market position by acquiring IEC 61850 engineering consultancies to internalize scarce commissioning expertise and accelerate project timelines. Consolidate vendor panels proactively to preempt EU NIS2 Directive supply-chain audit requirements. Expand cloud-hosted SCADA service capacity in southwestern United States municipal utility territories where capital constraints favor subscription models over on-premise deployment. For New Entrants and Emerging Players: Narrowband RF mesh deployments in Bihar and Uttar Pradesh distribution territories under India's SAUBHAGYA scheme represent the most penetrable entry point for cost-optimized hardware without legacy fiber infrastructure competition. Cloud-native cybersecurity subscription services for NERC CIP compliance monitoring offer a second white-space target as investor-owned utilities outsource internal network security operations. Partner with established European automation vendors to bypass CE-marked certification barriers for EU Cybersecurity Act compliance. For Investors and Strategic Acquirers: The market sits at a protocol-transition phase that favors acquisition targets with IEC 61850 process bus deployment experience and existing utility relationships. Long-term viability hinges on recurring revenue exposure through software subscriptions rather than transactional hardware sales. Monitor 5G private network slicing pilot results with transmission operators as the signal for whether cellular-based protection signaling displaces fiber-dominant architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Vendor Panel Consolidation | Reduces third-party cyber risk exposure under EU NIS2 Directive supply-chain audit mandates. |
| Cloud-Hosted SCADA Migration | Captures municipal utility budgets in capital-constrained southwestern United States territories. |
| IEC 61850 Engineering Acquisition | Internalizes scarce SCL configuration expertise that delays substation commissioning timelines. |
| 5G Private Network Slicing Pilots | Validates microsecond-synchronized protection for distributed generation coordination with ERCOT. |
| CE-Marked Cybersecurity Certification | Qualifies vendors for German and French transmission operator procurement specifications under EU Cybersecurity Act. |
Methodological Framework
Desk research of FERC filings, EIA grid infrastructure databases, and IEC protocol specification documents preceded structured interviews with utility planning officers, substation automation engineers, cybersecurity compliance leads, and EPC contractors across North American and European markets. Primary fieldwork captured procurement specification evolution, commissioning timeline bottlenecks, and vendor selection criteria. Secondary validation drew from NERC CIP enforcement records, EU NIS2 Directive transposition documents, and State Grid Corporation investment disclosures. Bottom-up unit deployment estimates triangulated against top-down capital expenditure projections from transmission operator rate-case filings.
Assumptions held fixed include NERC CIP encryption mandate enforcement intensity, EU Cybersecurity Act certification timeline adherence, and Taiwan-based foundry capacity allocation to industrial semiconductor tiers. Variables modeled across the analysis window encompass AMI 2.0 mesh deployment pace, 5G private network slicing adoption curves, and power-line carrier versus fiber substitution rates in rural distribution territories. Segmentation dimensions included technology type, application function, end-user ownership structure, and solution delivery model. CAGRs derived from logistic diffusion curves fitted to smart metering infrastructure penetration data and substation automation upgrade cycles.
Practitioners should monitor FERC Order 2222 implementation delays, EU NIS2 Directive enforcement variance across member states, and Taiwan semiconductor export control expansion for early signals of forecast deviation. Material shifts in NERC CIP reliability standard revision timing or IEC 61850 protocol adoption acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Europe Telecom Expense Management Market
Telecommunications
North America Underwater Communication Systems Market
Telecommunications
Free Space Optics (FSO) Communication Market
Telecommunications
Global 5G in Healthcare Market
Telecommunications
Managed Mobility Services (MMS) Market
Telecommunications
Saudi Arabia Telecom Market
Telecommunications
South Africa MNO - MVNO Market
Telecommunications
Diameter Signaling Market
Telecommunications
India Optical Transport Network (OTN) Market
Telecommunications
Africa Entertainment and Telecommunication Market
Telecommunications
5G Transport Networks Market
Telecommunications
Voip Phone Market
Telecommunications
Mobile Value-Added Services (MVAS) Market
Telecommunications
South Africa Telecom Tower Market
Telecommunications
Call Control (PBX-IP PBX) Market
Telecommunications
Global Policy Management in Telecom Market