
 Mftpaas Market | 2026-2036
Mftpaas Market Size, Share, and Industry Trends Forecast 2026-2036
Mftpaas Market Foresight
North American enterprise software vendors is consolidating around hybrid cloud managed file transfer architectures. IBM Corporation leverages its mainframe integration heritage to anchor high-security government and banking workflows. Oracle Corporation competes through embedded MFT capabilities within its broader cloud infrastructure stack. Axway Software SA specializes in B2B interoperability protocols that sustain its position in European supply chain networks.
Managed File Transfer Platform as a Service (MFT PaaS) denotes cloud-native environments that automate, encrypt, and audit bulk data exchanges between organizations, typically supporting file sizes from gigabytes to terabytes with end-to-end SFTP, FTPS, or AS2 protocol coverage. The primary purpose centers on replacing legacy on-premise file transfer appliances with elastic, API-orchestrated pipelines that reduce operational overhead while preserving non-repudiation logs. Public cloud deployment leads in absolute volume due to cost elasticity, though private cloud configurations command premium pricing from healthcare and defense buyers governed by data residency mandates. API-based integration is displacing traditional FTP-based connectivity as enterprises embed file transfer logic directly into microservices architectures.
FDA 21 CFR Part 11 and HIPAA in the United States impose audit trail and access control requirements that elevate demand for compliant MFT PaaS configurations in healthcare and life sciences. The EU GDPR and forthcoming NIS2 Directive tighten breach notification and cross-border transfer rules, compelling European buyers to prioritize vendors with EU-based data processing certifications. Stakeholders must evaluate whether their current vendor's encryption standards and geographic data residency options align with emerging sector-specific mandates before committing to multi-year platform contracts.
Market Dynamics
API-native orchestration is compressing deployment cycles for managed file transfer platforms, forcing incumbent vendors to rearchitect legacy FTP-based stacks while financial services buyers demand sub-hour provisioning for cross-border settlement workflows.
Growth Catalysts
- EU AI Act compliance mandates:Automated audit trails and algorithmic transparency requirements are accelerating replacement of on-premise appliances with cloud-native MFT pipelines that embed non-repudiation logging.
- Healthcare data exchange:HIPAA-covered entities in the United States are consolidating point-to-point interfaces into unified MFT PaaS layers to satisfy FDA 21 CFR Part 11 electronic record standards.
- Industrial automation clusters:German automotive and machinery manufacturers are deploying private cloud MFT nodes to maintain data sovereignty while integrating supplier networks across Bavaria and Baden-Württemberg.
Market Restraints
- Encryption export controls:US Bureau of Industry and Security restrictions on cryptographic modules create licensing friction for vendors serving defense and intelligence buyers.
- Cloud egress cost volatility:Unpredictable data transfer pricing from hyperscale providers erodes margin predictability for MFT PaaS operators running multi-tenant architectures.
- Skills concentration:DevSecOps engineers with hybrid cloud and PKI expertise cluster in London, Frankfurt, and Singapore, inflating implementation costs for mid-market buyers elsewhere.
Strategic Opportunities
- NIS2 Directive preparation:European critical infrastructure operators face 2024 breach notification deadlines, creating replacement demand for MFT platforms with embedded EU-based data residency.
- Edge-to-core synchronization:Convergence of 5G private networks and containerized MFT agents enables real-time file exchange for offshore energy platforms and autonomous logistics fleets.
- Channel partner ecosystems:Systems integrators in India and Brazil are building MFT practices around localized compliance templates, opening indirect routes to mid-market manufacturing buyers.
Industry Challenges
- Mainframe integration complexity:COBOL-era batch scheduling systems at Tier-1 banks resist API abstraction, forcing parallel maintenance of legacy FTP gateways during multi-year migration programs.
- Cross-border key management:Divergent national cryptographic standards between France, Germany, and Switzerland fragment certificate authority trust models for unified European deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mftpaas Market |
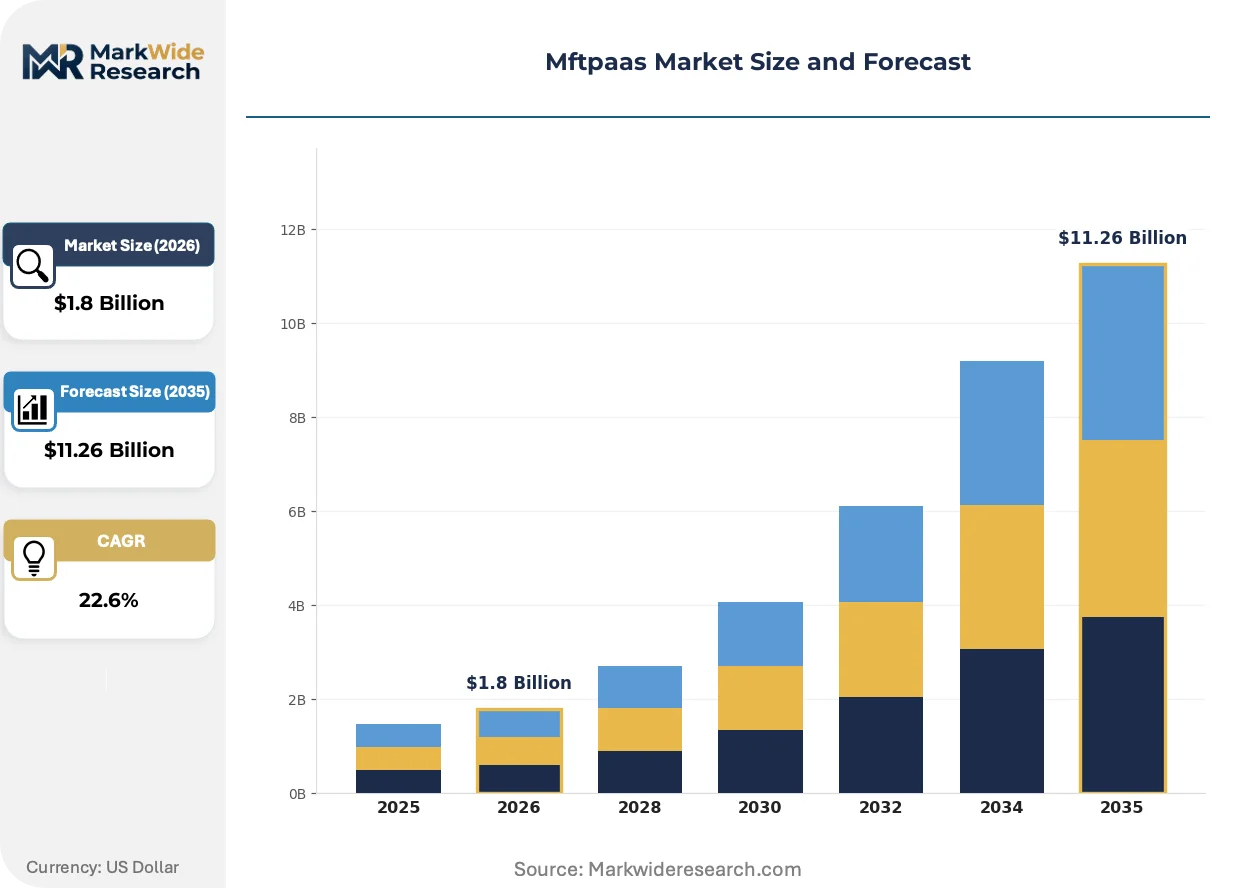
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.26 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: File Transfer, Data Integration, Workflow Automation, Security Management End User: Retail, Healthcare, Manufacturing, Financial Services Integration Level: API-Based, FTP-Based, SFTP-Based, Managed File Transfer |
| Companies Covered | IBM Corporation, Axway Software SA, OpenText Corporation, Progress Software Corporation, Oracle Corporation, Micro Focus, Software AG, GlobalSCAPE, Inc., Wipro Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mftpaas Market Shifts & Advancements
Event-driven architecture is displacing scheduled batch transfers across financial services, compressing settlement windows and eliminating overnight file exchange windows that previously dominated corporate treasury operations.
Event streaming fabrics built on Apache Kafka and cloud-native message brokers are electrifying MFT infrastructure by replacing polling-based retrieval with push-based delivery. Capital markets firms in New York and London are adopting these pipelines for real-time trade confirmation flows. The technology is electrifying competitive positioning by collapsing the distinction between file transfer and application messaging, forcing pure-play MFT vendors to embed stream processing or cede ground to full-stack integration platforms.
The EU NIS2 Directive tightens incident reporting timelines and supply chain security obligations for critical service operators across energy, transport, and financial infrastructure. Covered entities must demonstrate encrypted data flows with documented access controls by October 2024. German energy utilities and Dutch payment processors are prioritizing MFT vendors with pre-certified EU sovereign cloud deployments to accelerate compliance timelines.
Buyer procurement patterns are fragmenting from enterprise-wide platform contracts toward modular, workload-specific subscriptions. Mid-market manufacturers in Italy and Spain now procure MFT capacity through embedded procurement within broader ERP SaaS agreements rather than standalone RFPs. This shift concentrates vendor selection influence with Oracle and SAP account teams, compressing independent MFT specialists into niche protocol support roles.
Mftpaas Market Segmentation
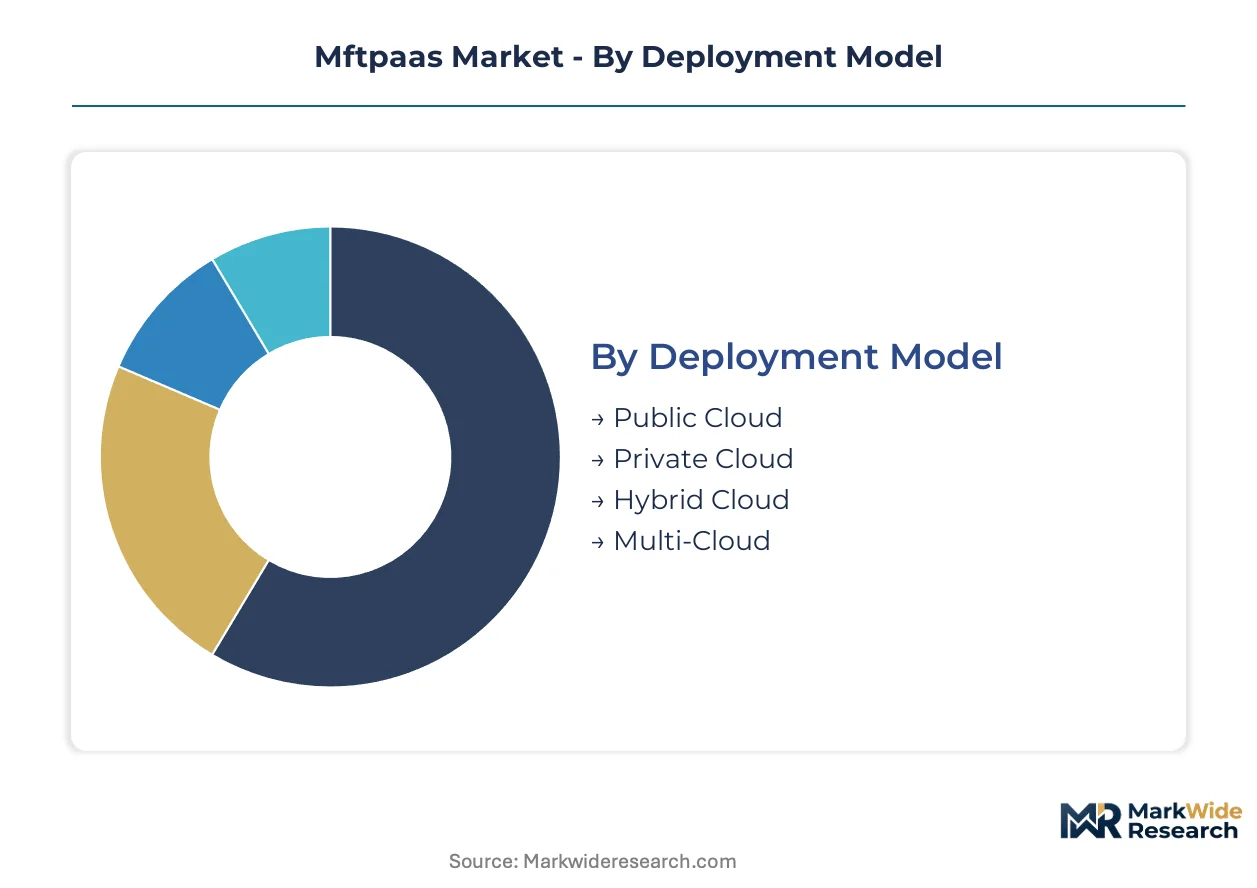
Enterprise procurement of MFT PaaS follows distinct upgrade cycles across deployment architectures, service layers, and integration depths. Each segment carries unique compliance burdens and technical debt considerations that reshape vendor selection criteria and contract renewal timelines.
Deployment Model:
Replacement cycles for on-premise file transfer infrastructure are compressing as API-native alternatives reach feature parity with legacy appliances.
- Public Cloud:Elastic compute pools enable pay-per-transfer pricing without capital provisioning. Demand clusters among mid-market financial services firms in Singapore and Toronto seeking rapid cross-border settlement pipelines without data center overhead.
- Private Cloud:Dedicated tenant isolation satisfies GDPR Article 44 transfer restrictions and German BSI IT-Grundschutz requirements. Bavarian automotive suppliers and Swiss pharmaceutical manufacturers anchor procurement volume here.
- Hybrid Cloud:Burst capacity models partition sensitive metadata on-premises while pushing bulk payload processing to public nodes. Healthcare networks in California and Texas adopt this architecture to preserve HIPAA audit control.
- Multi-Cloud:Orchestration layers abstract AWS, Azure, and GCP storage APIs into unified transfer endpoints. This configuration spreads operational risk across hyperscale providers but demands specialized FinOps tooling.
Volume placements concentrate in Public Cloud; the faster expansion belongs to Private Cloud.
Service Type:
Cost tier differentiation separates commodity file movement from value-added orchestration layers.
- File Transfer:Core payload encryption and protocol conversion (SFTP, FTPS, AS2) with guaranteed delivery receipts. Baseline service tier captures high-volume manufacturing and logistics workflows where speed outweighs transformation complexity.
- Data Integration:Schema mapping, ETL preprocessing, and real-time synchronization between ERP and CRM systems. Financial services buyers in London and Frankfurt prioritize this layer for treasury reconciliation automation.
- Workflow Automation:Event-triggered routing, exception handling, and SLA-based retry logic. Healthcare providers deploy these capabilities to streamline FDA 21 CFR Part 11 compliant document chains.
- Security Management:Key rotation, certificate lifecycle management, and zero-trust access policies. Defense contractors and EU critical infrastructure operators mandate this tier under NIS2 Directive supply chain provisions.
Margin concentration sits with Security Management; Workflow Automation is gaining share fastest among new deployments.
End User:
Application-specific compliance mandates fragment procurement authority across functional departments.
- Retail:High-frequency inventory synchronization between POS systems and supplier portals. Omnichannel fulfillment networks in the United States and United Kingdom drive seasonal capacity spikes.
- Healthcare:HIPAA-covered entities consolidate point-to-point interfaces into auditable pipelines. FDA 21 CFR Part 11 electronic record standards elevate demand for non-repudiation logging in life sciences.
- Manufacturing:Supplier network integration across tiered automotive and electronics supply chains. German industrial clusters in Baden-Württemberg deploy private cloud nodes to maintain data sovereignty.
- Financial Services:Cross-border settlement workflows with sub-hour provisioning requirements. SWIFT network integration and real-time payment rails in Singapore and Switzerland anchor premium pricing.
Procurement scale favors Financial Services; Healthcare shows the steepest expansion trajectory as legacy interface consolidation accelerates.
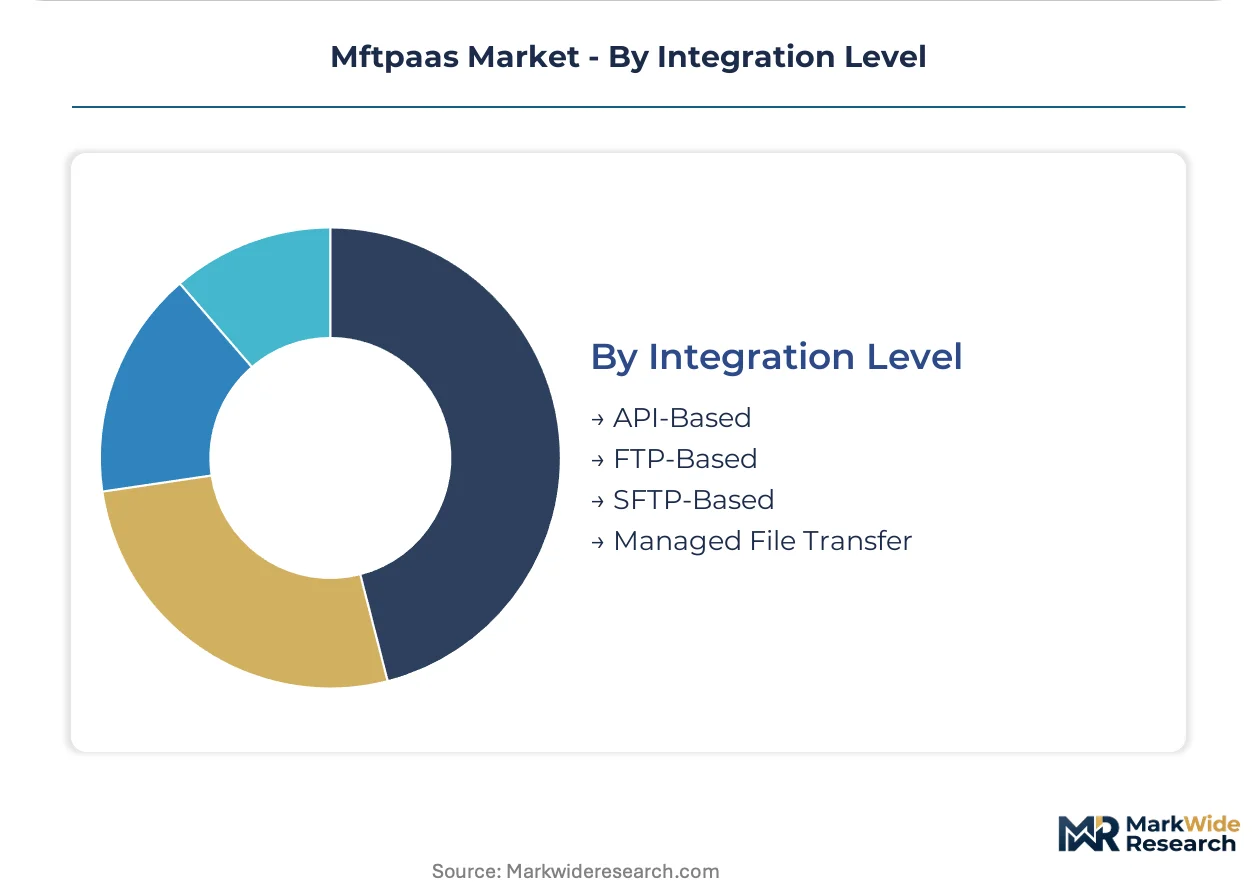
Integration Level:
Technical maturity curves separate modern API-native stacks from protocol-bound legacy estates.
- API-Based:REST and GraphQL endpoints embed transfer logic directly into microservices architectures. DevOps teams in technology-forward banks and fintech platforms favor this approach for CI/CD pipeline integration.
- FTP-Based:Scheduled batch transfers over standard FTP ports persist in industrial automation and legacy ERP environments. Maintenance costs rise as security scanners flag plaintext protocol usage.
- SFTP-Based:SSH-encrypted sessions with public-key authentication bridge security and compatibility requirements. Mid-market manufacturers adopt this as a transitional step from FTP.
- Managed File Transfer:Full-stack platforms combining protocol abstraction, governance dashboards, and SLA monitoring. Enterprise buyers consolidate fragmented point solutions under unified vendor contracts.
Greenfield deployments cluster around API-Based; Managed File Transfer retains the largest installed base renewal pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's hyperscale data centers anchor cloud-native infrastructure deployment patterns that diffuse outward through Frankfurt, Singapore, and Mumbai financial districts.
United States
FDA 21 CFR Part 11 and HIPAA compliance mandates drive healthcare and life sciences procurement of auditable file transfer pipelines. The SEC's cybersecurity disclosure rules accelerate replacement of legacy FTP appliances in financial services. New York and Chicago trading floors demand sub-hour provisioning for cross-border settlement workflows.
Germany
BSI IT-Grundschutz requirements and GDPR Article 44 data residency rules elevate private cloud MFT configurations. The EU NIS2 Directive compels critical infrastructure operators to demonstrate encrypted data flows by October 2024. Bavarian automotive suppliers and Baden-Württemberg machinery manufacturers deploy sovereign cloud nodes to integrate tiered supplier networks.
United Kingdom
FCA operational resilience requirements tighten recovery time objectives for payment systems and trading infrastructure. The UK GDPR retains EU-equivalent data transfer restrictions post-Brexit. London capital markets firms adopt event-driven architectures for real-time trade confirmation flows.
Singapore
MAS technology risk management guidelines mandate secure data exchange for banking and fintech license holders. The Personal Data Protection Act cross-border transfer rules align with ASEAN data governance frameworks. Marina Bay financial district hosts regional treasury centers demanding SWIFT-integrated MFT pipelines.
Switzerland
Swiss FINMA operational risk circulars enforce documented access controls for financial institutions. The Federal Act on Data Protection strengthens breach notification requirements beyond EU baselines. Zurich and Geneva private banking clusters prioritize vendors with EU-sovereign cloud certifications for wealth management data flows.
Mftpaas Market Competitive Landscape
Global majors compete with regional champions across hybrid cloud integration depth, with North American hyperscalers anchoring financial services workflows while European specialists dominate B2B protocol interoperability. Market structure tilts toward consolidated platform plays as enterprise buyers reduce vendor fragmentation. Three archetypes define competitive positioning: mainframe-heritage systems integrators, cloud-native API orchestrators, and compliance-specialized regional champions. Dominant moves include strategic partnerships with hyperscale infrastructure providers and geographic expansion through localized certification templates.
Within the mainframe-heritage tier, IBM Corporation and Oracle Corporation exemplify vendors leveraging decades of banking and government relationships to anchor high-security deployments. Axway Software SA occupies a position among European protocol specialists, sustaining presence through B2B interoperability expertise in supply chain networks. These three entities represent the spectrum from infrastructure-integrated platforms to standalone compliance-focused solutions.
| Leading Market Players |
|---|
| IBM Corporation |
| Axway Software SA |
| OpenText Corporation |
| Progress Software Corporation |
| Oracle Corporation |
| Micro Focus |
| Software AG |
| GlobalSCAPE, Inc. |
| Wipro Limited |
| Others |
Supply & Pricing Matrix
Horizontal integration through hyperscale cloud partnerships anchors supply positioning for MFT PaaS vendors while concentrating pricing power among AWS, Azure, and GCP infrastructure providers. This partnership model feeds into tiered service bundling where encryption modules and EU data residency certifications command premium positioning against commodity file transfer tiers.
Pricing Analysis
Warranty and service bundling separates premium MFT PaaS contracts from unbundled API-only offerings. Three-tier pricing structure across premium, standard, and economy levels tracks compliance certification depth, with FDA 21 CFR Part 11 and EU GDPR attestation driving standard-to-premium spreads. Pricing pressure stems from hyperscaler egress cost volatility eroding multi-tenant operator margins. Mid-market manufacturers in Southern Europe exhibit highest price sensitivity, while defense contractors and Swiss private banking clusters show lowest elasticity due to mandatory security management tier requirements.
Supply Chain Analysis
Single-source vulnerability sits with cryptographic module suppliers subject to US Bureau of Industry and Security export licensing restrictions. Primary infrastructure provisioning concentrates in the United States, Germany, and Singapore, with specialized certificate authority services drawing from France, Germany, and Switzerland. Raw material dependencies include FIPS 140-2 validated hardware security modules, quantum-resistant algorithm libraries, and sovereign cloud compute capacity. Tariff exposure on cryptographic components fragments unified European deployments. Distribution runs through direct enterprise sales teams and systems integrator channel partners in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
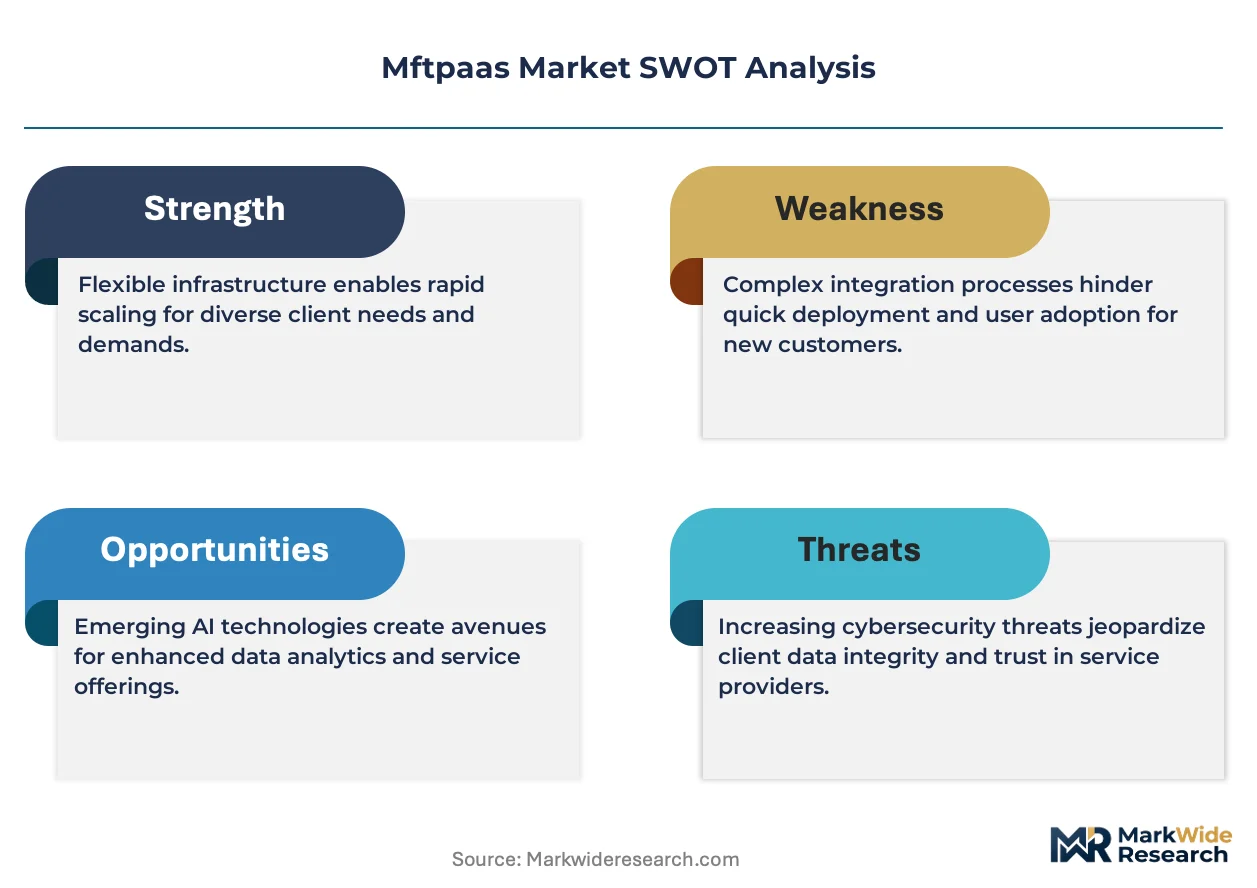
The MFT PaaS market functions as a cost-of-compliance story where EU NIS2 Directive breach notification mandates erect barrier-to-entry moats for vendors with pre-certified EU sovereign cloud deployments.
For Market Incumbents: Lock in government and banking relationships by embedding mainframe integration heritage into high-security workflow pipelines. Defensive moves center on anchoring IBM and Oracle account teams within enterprise-wide platform consolidation cycles while neutralizing cloud-native API orchestrators through embedded procurement within broader ERP SaaS agreements. Channel control through localized compliance template partnerships in India and Brazil preserves margin position against mid-market price erosion. For New Entrants and Emerging Players: EU NIS2 Directive in Germany, Netherlands, and France opens a window for compliance-specialized regional champions to capture critical infrastructure replacement demand ahead of October deadlines. Most penetrable white space sits with private cloud MFT nodes for Bavarian automotive suppliers requiring BSI IT-Grundschutz alignment. Go-to-market angle targets DevSecOps engineers through containerized MFT agents with event-driven architecture positioning against scheduled batch legacy estates. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler acquisition of API-native orchestrators with established financial services workflows. Long-term viability favors vendors with demonstrated EU data residency certifications and mainframe integration capabilities spanning multi-year migration programs. Signal to watch is consolidation of point-to-point interfaces into unified MFT PaaS layers among HIPAA-covered entities, indicating replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU Sovereign Cloud Certification | BSI IT-Grundschutz alignment accelerates German critical infrastructure procurement timelines. |
| API-Native Orchestration Development | REST and GraphQL endpoints embed transfer logic into microservices architectures for fintech platforms. |
| Event-Driven Architecture Migration | Apache Kafka fabrics compress settlement windows for New York and London capital markets. |
| Channel Partner Ecosystem Expansion | Systems integrators in India and Brazil build localized compliance practices for manufacturing buyers. |
| Mainframe Integration Modernization | COBOL-era batch scheduling abstraction preserves banking relationships during multi-year transitions. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and EU regulatory submission databases formed the secondary backbone for this analysis. Primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists at financial services, healthcare, and industrial automation enterprises combined with secondary validation through bottom-up and top-down triangulation approaches.
Historical trendline analysis across deployment model, service type, end user vertical, and integration complexity dimensions established baseline growth patterns. CAGRs were derived through segment-level growth rate reconciliation against macroeconomic indicators and technology adoption curves. Forecast inputs incorporated API-native penetration rates, event-driven architecture adoption, and NIS2 Directive compliance preparation timelines.
The model assumes a particular technology adoption path; alternative pathways for quantum-resistant encryption would alter the outlook. Forecasts reflect assumptions around regulatory deadline adherence, hyperscaler pricing stability, and cryptographic export licensing continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Private Branch Exchange Market
Telecommunications
IP DECT Phones Market
Telecommunications
Norway Telecom Market
Telecommunications
Algeria Telecom Market
Telecommunications
Global Small Cell 5G Network Market
Telecommunications
5G Network and Service Assurance Market
Telecommunications
Argentina ICT Market
Telecommunications
Mobile Satellite Services (MSS) Market
Telecommunications
SIP Trunking Services Market
Telecommunications
Global Hosted PBX Market
Telecommunications
Global Underwater Acoustic Communication Market
Telecommunications
Thailand Telecom Market
Telecommunications
Poland Telecom Market
Telecommunications
Telecom Expense Management Market
Telecommunications
Video Door Phones Market
Telecommunications
DWDM System Market