
 US Private LTE and 5G Network Market | 2026-2036
US Private LTE and 5G Network Market Size, Share, and Industry Trends Forecast 2026-2036
US Private LTE and 5G Network Market Intelligence
CBRS certification for 3.5 GHz spectrum access is collapsing the barrier between traditional carriers and enterprise self-builders. Cisco Systems leverages its enterprise routing heritage to anchor campus-wide private network deployments for Fortune 500 manufacturers. Samsung Electronics competes through integrated radio and core offerings that sustain price pressure on pure-play infrastructure vendors. Qualcomm Technologies specializes in chipset-level 5G modems that dominate the embedded device ecosystem for industrial IoT endpoints.
Private LTE and 5G networks constitute localized cellular infrastructure operating on licensed, shared, or unlicensed spectrum with base stations, core networks, and subscriber identity modules managed by a single enterprise or consortium, typically delivering sub-20 millisecond latency for deterministic industrial control. These systems replace Wi-Fi in environments requiring seamless mobility, deterministic quality of service, and radio-level security isolation for autonomous guided vehicles and robotic process automation. Deployment mode segmentation shows on-premises core installations capturing the highest margin pools due to perpetual licensing and integration services, while cloud-based orchestration grows fastest among mid-market enterprises seeking operational expenditure flexibility. End user demand from manufacturing verticals leads absolute revenue contribution, though healthcare networks for connected surgical suites and real-time patient monitoring represent the fastest-expanding application category.
FCC Part 96 rules for CBRS, NIST cybersecurity frameworks for critical infrastructure, and FDA guidance on wireless medical device coexistence collectively shape product certification timelines and spectrum allocation strategies for US market participants. FCC auction structures and PAL licensing terms directly determine which industrial consortia can secure protected spectrum blocks versus operating under general authorized access tiers. Stakeholders must monitor emerging FAA rulings on 5G C-band interference with aviation altimeters, as these decisions will constrain available spectrum for private network deployments near commercial flight corridors.
Market Dynamics
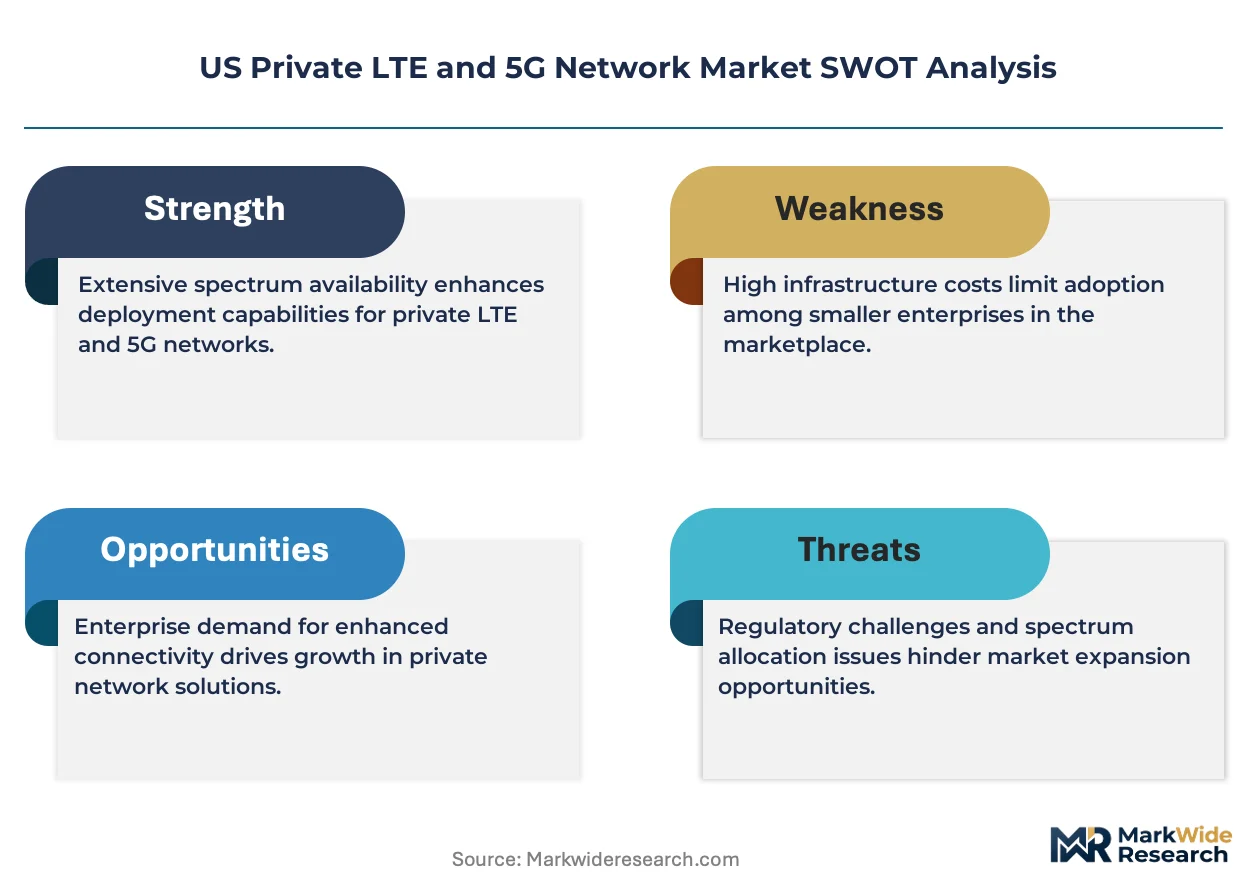
FCC Part 96 rules for CBRS spectrum access are fragmenting traditional carrier control over enterprise connectivity, enabling manufacturing facilities and petrochemical complexes to self-provision deterministic wireless infrastructure without mobile network operator intermediation.
Growth Catalysts
- CBRS General Authorized Access tier:The FCC's three-tier spectrum framework grants enterprises immediate 3.5 GHz access without auction participation, collapsing deployment timelines for industrial IoT networks.
- Smart factory automation:Michigan and Ohio manufacturing clusters demand sub-20 millisecond latency for robotic process control, replacing Wi-Fi with cellular-grade reliability.
- Gulf Coast petrochemical corridor:Texas and Louisiana refineries deploy mission-critical private networks to support hazardous-area sensor telemetry and autonomous guided vehicle fleets.
Market Restraints
- mmWave propagation limitations:Line-of-sight requirements and rain fade sensitivity constrain 28 GHz and 39 GHz deployments to dense indoor environments with high infrastructure density.
- Radio unit supply concentration:Baseband processor and massive MIMO antenna module fabrication concentrates in East Asian foundries, exposing lead time volatility for US system integrators.
- Legacy OT/IT integration friction:Ethernet/IP and Profinet industrial protocols require protocol translation layers that introduce latency overhead incompatible with closed-loop control requirements.
Strategic Opportunities
- Healthcare surgical suites:Connected operating theaters for real-time imaging and robotic telesurgery represent the fastest-expanding application category beyond manufacturing.
- Cloud-native core orchestration:Containerized 5G core deployments enable mid-market enterprises to shift from capital-intensive on-premises installations to operational expenditure models.
- FAA C-band coordination frameworks:Emerging rulings on aviation altimeter interference will clarify spectrum availability near commercial flight corridors, unlocking previously restricted deployment zones.
Industry Challenges
- RF engineering talent scarcity:Compound semiconductor design and propagation modeling expertise concentrates among legacy telecom vendors, constraining enterprise self-build capabilities.
- NIST cybersecurity framework compliance:Critical infrastructure operators must implement zero-trust architectures and continuous monitoring that extend deployment timelines by 6-12 months.
- Multi-vendor interoperability certification:Disaggregated RAN components from different suppliers require extensive lab validation before production deployment, compressing margin pools for systems integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Private LTE and 5G Network Market |
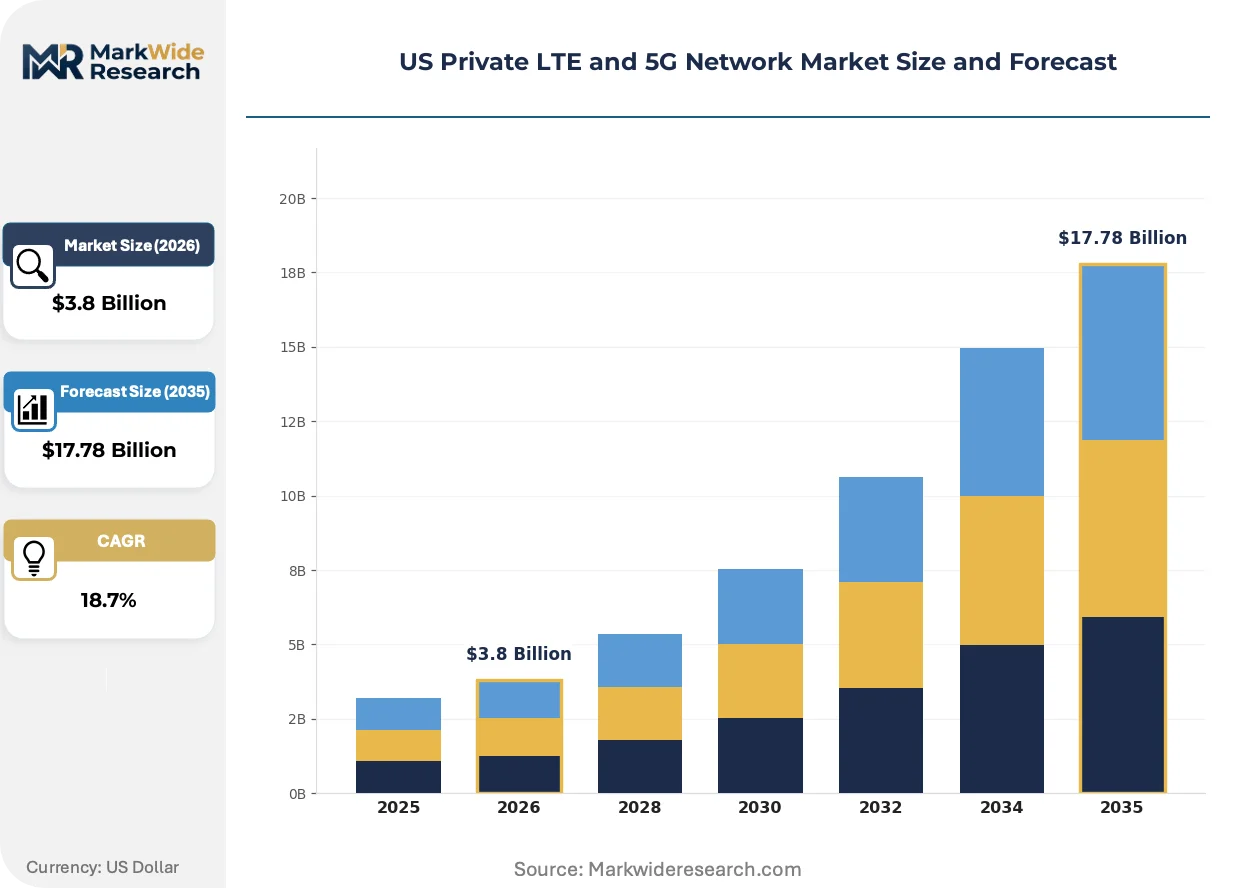
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Network Type: Private LTE, 5G, Hybrid Network, Dedicated Network Deployment Mode: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Manufacturing, Healthcare, Transportation, Education Application: Remote Monitoring, Asset Tracking, Video Surveillance, Smart Manufacturing |
| Companies Covered | Cisco Systems, Inc., Samsung Electronics Co., Ltd., Verizon Communications Inc., Broadcom Inc., Telefonaktiebolaget LM Ericsson, AT&T Inc., Qualcomm Technologies, Inc., T-Systems International GmbH, Nokia Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Private LTE and 5G Network Market Strategic Shifts & Innovations
Open RAN architectures are dismantling proprietary vendor lock-in across the radio access network stack, enabling enterprises to mix baseband, radio unit, and software components from independent suppliers rather than accepting vertically integrated system bundles.
Virtualized distributed unit and centralized unit software is decomposing traditional base station hardware into cloud-native functions that run on commercial off-the-shelf servers. Fortune 500 manufacturers in the Midwest are piloting these disaggregated stacks to reduce per-site infrastructure costs by half. This decomposition is compressing margin structures for incumbent radio vendors while expanding addressable market access for software-centric challengers.
FCC Part 96 Priority Access License auctions are formalizing spectrum property rights for industrial consortia, creating transferable leaseholds that collateralize network investments. The three-tier framework now permits secondary market trading of PAL rights, enabling spectrum aggregation strategies for multi-facility deployments. Gulf Coast petrochemical operators are acquiring contiguous 10 MHz blocks to support deterministic quality-of-service guarantees for safety instrumented systems.
Network-as-a-service procurement models are displacing capital purchase cycles for mid-market enterprises lacking internal RF engineering capabilities. Systems integrators and managed service providers now offer subscription-based private network operations, absorbing spectrum coordination, core maintenance, and radio optimization responsibilities. This shift is most visible among regional healthcare systems seeking connected surgical suites without building captive wireless expertise.
US Private LTE and 5G Network Market Segmentation
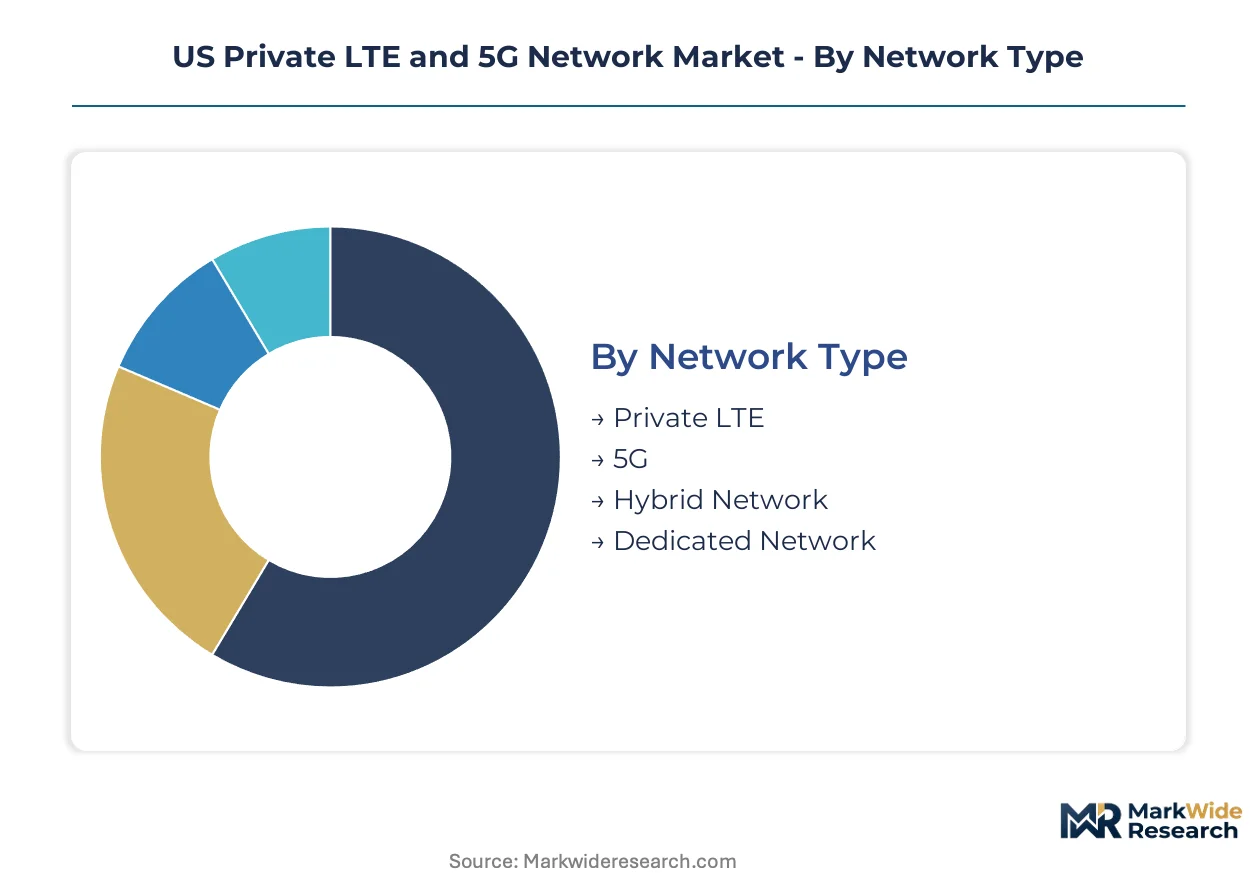
Segmentation reveals how private cellular infrastructure fragments across technology generations, operational architectures, and industrial use cases. Each dimension exposes distinct margin structures and deployment complexity thresholds that determine vendor selection and systems integrator specialization.
Network Type:
Margin pools concentrate in 5G deployments where massive MIMO and network slicing command premium integration fees, while legacy LTE retains volume through brownfield industrial retrofits.
- 5G:New Radio massive MIMO arrays and network slicing capabilities enable deterministic sub-10 millisecond latency for closed-loop robotic control. Michigan automotive assembly plants and Ohio steel foundries anchor demand as they replace aging Wi-Fi with cellular-grade mobility for autonomous guided vehicle fleets.
- Private LTE:Established 3GPP Release 13+ infrastructure operates in CBRS Band 48 with mature device ecosystems and lower radio unit costs. Gulf Coast petrochemical complexes in Texas and Louisiana favor this technology for hazardous-area sensor telemetry where 5G capability surplus offers no operational advantage.
- Hybrid Network:Dual-mode cores simultaneously anchor LTE-MTC for low-power IoT endpoints alongside 5G eMBB for high-throughput video analytics.
- Dedicated Network:Spectrum-isolated deployments using FCC PAL licenses or mmWave bands provide radio-level security isolation for defense contractors and critical infrastructure operators.
Private LTE holds installed capacity across brownfield industrial sites. 5G is rotating up the share rankings as greenfield smart factory builds accelerate in the Midwest manufacturing corridor.
Deployment Mode:
Cloud-native orchestration is climbing fastest among mid-market enterprises seeking to externalize RF engineering complexity, while on-premises cores retain margin concentration through perpetual licensing and captive integration services.
- On-Premises:Physical 5G core and baseband hardware installations within facility data centers deliver complete data sovereignty and deterministic latency for safety instrumented systems. Regional healthcare systems in the Southeast deploy this architecture for connected surgical suites where milliseconds determine patient outcomes.
- Cloud-Based:Containerized core functions running on hyperscale infrastructure shift capital expenditure to operational expenditure models with elastic scaling. Mid-market manufacturers in the Great Plains adopt this mode to avoid building captive wireless expertise.
- Hybrid:Distributed user plane functions at the edge combine with centralized control plane orchestration to balance latency requirements against management simplicity.
- Edge Computing:Multi-access edge computing nodes collocate radio access network processing with application workloads for real-time video analytics and AR-assisted maintenance.
On-premises deployments retain the highest margin capture per site. Cloud-based orchestration is expanding most quickly as managed service providers absorb operational complexity for resource-constrained enterprises.
End User:
Application complexity and regulatory burden vary sharply across verticals, with healthcare demanding FDA wireless coexistence validation while manufacturing prioritizes deterministic throughput.
- Manufacturing:Smart factory automation for robotic process control and autonomous material handling dominates absolute revenue contribution. Michigan and Ohio facilities lead adoption as they modernize legacy Ethernet/IP networks.
- Healthcare:Connected surgical suites for real-time imaging and robotic telesurgery represent the steepest expansion trajectory among all verticals. FDA guidance on wireless medical device coexistence extends certification timelines but creates durable competitive moats for compliant vendors.
- Transportation:Private networks support port automation and rail yard logistics where seamless mobility across large geographic footprints exceeds Wi-Fi architectural limits.
- Education:Campus-wide deployments replace fragmented Wi-Fi with unified cellular coverage for immersive learning and research collaboration.
Manufacturing anchors current installed base. Healthcare is gaining share fastest as surgical robotics and remote procedure networks mature.
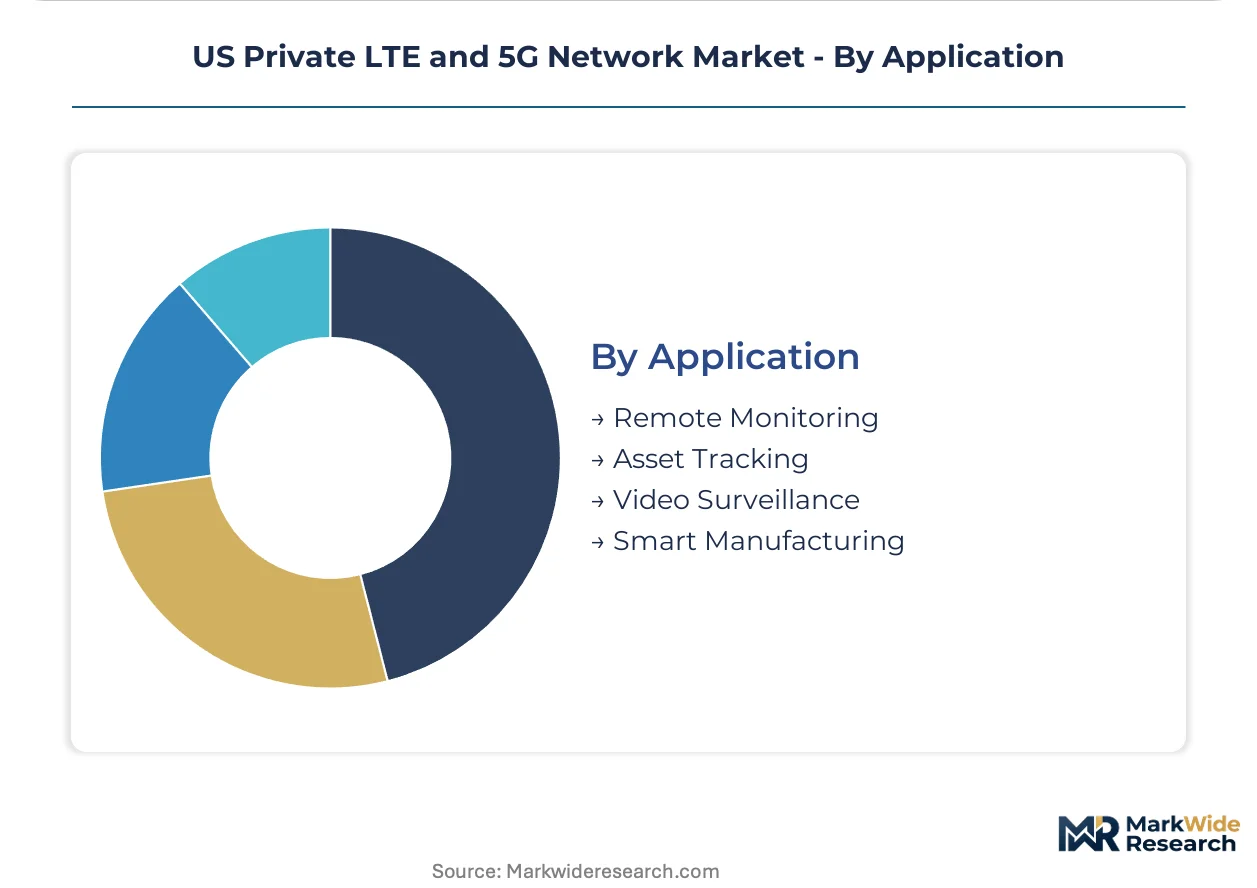
Application:
Latency tolerance and throughput requirements segment the application landscape, with closed-loop control commanding premium infrastructure while monitoring applications tolerate higher latency.
- Smart Manufacturing:Deterministic wireless for programmable logic controller synchronization and robotic arm coordination demands sub-20 millisecond latency with 99.999% availability. Ohio automotive suppliers deploy these networks to eliminate Ethernet cabling constraints on reconfigurable production lines.
- Remote Monitoring:Sensor telemetry for predictive maintenance and environmental safety systems operates with relaxed latency requirements but requires deep indoor penetration. Louisiana refineries utilize CBRS-based monitoring for corrosion detection in hazardous classified areas.
- Asset Tracking:Real-time location systems for high-value equipment and inventory leverage cellular positioning for yard and warehouse environments.
- Video Surveillance:High-definition video backhaul for security and quality inspection consumes significant radio resources but enables centralized analytics.
Remote monitoring holds installed capacity across legacy industrial deployments. Smart manufacturing is climbing the share rankings as robotic density increases in Midwest production facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers cluster in three distinct archetypes: Gulf Coast petrochemical operators securing PAL spectrum blocks, Midwest automotive manufacturers modernizing brownfield facilities, and Southeast healthcare systems deploying connected surgical infrastructure.
Gulf Coast Corridor
Texas and Louisiana refineries drive demand for mission-critical sensor telemetry and autonomous vehicle fleets in hazardous classified areas. FCC Part 96 rules enable Priority Access License acquisition for deterministic quality-of-service guarantees. Petrochemical complexes along the Houston Ship Channel and Lake Charles industrial zone deploy private networks to replace hardwired safety instrumented systems.
Midwest Manufacturing Belt
Michigan and Ohio automotive suppliers seek sub-20 millisecond latency for robotic process control and reconfigurable production lines. NIST cybersecurity frameworks extend deployment timelines but create compliance moats for certified integrators. Detroit-area assembly plants and Cleveland steel foundries anchor the nation's densest concentration of smart factory automation pilots.
Southeast Healthcare Cluster
Regional hospital systems in Florida and Georgia pursue connected surgical suites for real-time imaging and robotic telesurgery. FDA guidance on wireless medical device coexistence shapes vendor selection and certification pathways. Atlanta and Tampa medical centers lead adoption of on-premises core installations where milliseconds determine patient outcomes.
Mountain West Defense Corridor
Colorado and Arizona defense contractors require radio-level security isolation for classified manufacturing and R&D facilities. FAA rulings on 5G C-band interference constrain spectrum availability near Denver International Airport and Phoenix Sky Harbor. Lockheed Martin and Raytheon suppliers in the Denver-Aurora tech center deploy dedicated mmWave networks for sensitive aerospace production.
US Private LTE and 5G Network Market Key Industry Players
Player mix skews toward diversified technology conglomerates with enterprise networking heritage, creating a tiered structure where infrastructure specialists compete against integrated system vendors. Three archetypes dominate: telecom equipment manufacturers with radio access network portfolios, enterprise networking vendors leveraging campus IT relationships, and semiconductor designers supplying modem chipsets for industrial endpoints. Competitive moves center on spectrum coordination partnerships with systems integrators and cloud-native core orchestration capabilities for mid-market managed service offerings.
Within the infrastructure tier, Cisco Systems and Nokia Corporation exemplify contrasting approaches to enterprise market entry, with the former emphasizing campus-wide IT integration and the latter stressing radio access network disaggregation. Samsung Electronics occupies a position between these poles with integrated radio and core offerings. Qualcomm Technologies anchors the component layer through 5G modem dominance in embedded industrial devices. Ericsson and Verizon Communications represent carrier-captive and carrier-independent deployment models respectively, while AT&T and T-Systems illustrate managed service strategies for enterprises lacking internal RF engineering capabilities.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Samsung Electronics Co., Ltd. |
| Verizon Communications Inc. |
| Broadcom Inc. |
| Telefonaktiebolaget LM Ericsson |
| AT&T Inc. |
| Qualcomm Technologies, Inc. |
| T-Systems International GmbH |
| Nokia Corporation |
| Others |
Cost & Logistics Intelligence
Twenty-six-week lead times for massive MIMO antenna modules signal supply scarcity that amplifies pricing power for radio unit vendors while compressing margins for US systems integrators caught between fixed-price enterprise contracts and variable component costs.
Pricing Analysis
Cost-plus contracts indexed to semiconductor foundry utilization rates dominate procurement between radio vendors and petrochemical operators. Three-tier pricing structure across premium, standard, and economy levels separates FCC PAL-licensed dedicated networks from CBRS General Authorized Access deployments and hybrid cloud-managed offerings. Cost compression in the standard tier intensifies as Open RAN disaggregation enables multi-vendor sourcing. Mid-market manufacturers lacking captive RF engineering exhibit highest price sensitivity, while defense contractors prioritize security isolation over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies falter against foundry allocation volatility, pushing Gulf Coast operators toward strategic stockpiles of baseband processors and power amplifiers. Fabrication concentrates in Taiwan, South Korea, and mainland China for advanced node chipsets, while radio unit assembly localizes in Mexico and Vietnam to mitigate tariff exposure. Supply chain risk centers on single-source vulnerability for gallium nitride power amplifiers. Distribution runs through tier-one systems integrators who bundle spectrum coordination, core deployment, and managed services into consolidated procurement vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against Wi-Fi 7 substitution in latency-tolerant applications where enterprise IT departments resist cellular complexity premiums.
For Market Incumbents: Fortify PAL spectrum positions through contiguous block aggregation across multi-facility deployments in Texas and Louisiana. Deepen backward integration into cloud-native core software to offset margin erosion from Open RAN radio commoditization. Prioritize NIST cybersecurity framework pre-certification to compress six-to-twelve-month compliance timelines that currently cede early-mover advantage to specialized integrators.
For New Entrants and Emerging Players: Differentiate on managed network-as-a-service orchestration for regional healthcare systems in Florida and Georgia lacking internal wireless expertise. Target cloud-based deployment mode penetration among Great Plains mid-market manufacturers. Pursue FAA C-band coordination partnerships near Denver and Phoenix to unlock defense corridor deployments currently spectrum-constrained by aviation altimeter interference rulings.
For Investors and Strategic Acquirers: Carve-out targets emerge from telecom equipment manufacturers spinning enterprise-facing private network divisions to focus on carrier infrastructure. Long-term viability hinges on software-centric margin capture rather than hardware shipment volumes. Watch for inflection when Open RAN interoperability certification labs achieve FCC recognition, signaling vendor-agnostic procurement normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum Aggregation Partnership | Contiguous PAL block acquisition enables deterministic QoS guarantees for safety instrumented systems. |
| Cloud-Native Core Development | Containerized 5G core functions shift mid-market enterprises from CapEx to OpEx procurement models. |
| Open RAN Interoperability Certification | FCC-recognized lab validation accelerates multi-vendor deployment timelines for systems integrators. |
| Managed Network-as-a-Service Launch | Subscription-based operations absorb RF engineering complexity for resource-constrained healthcare systems. |
| NIST Cybersecurity Pre-Certification | Zero-trust architecture validation compresses deployment timelines for critical infrastructure operators. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with private network deployment directors at Michigan automotive suppliers, RF engineering leads at Texas petrochemical complexes, procurement officers at Southeast healthcare systems, and cloud infrastructure architects at managed service providers. Secondary validation drew from FCC Part 96 rulemaking dockets, FAA C-band coordination filings, NIST cybersecurity framework documentation, and SEC 10-K disclosures from infrastructure vendors. Bottom-up unit economics triangulated against top-down spectrum allocation models.
Across the projection horizon, the analytical framework modeled network type segmentation, deployment mode architecture, end-user vertical concentration, and application latency requirements. CAGRs derived from facility-level deployment velocity curves weighted by PAL license auction participation rates and CBRS equipment certification volumes. Forecast inputs incorporated smart factory automation density metrics from Ohio and Michigan production facilities alongside connected surgical suite expansion trajectories in Atlanta and Tampa medical centers.
The analysis sits within stated boundaries; outcomes outside FCC regulatory stability, semiconductor foundry capacity normalization, or FAA C-band interference resolution would require recalibration. Forecasts reflect documented assumptions regarding CBRS General Authorized Access tier utilization and Open RAN interoperability maturation. Revision becomes warranted when PAL secondary market trading volume crosses thresholds indicating spectrum liquidity transformation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
North America Enterprise WLAN Market
Network Technology
Middle East & Africa Video Conferencing Hardware Market
Network Technology
Gigabit Ethernet Market
Network Technology
Germany Residential Gateway Market
Network Technology
DNS DHCP and IPAM Market
Network Technology
Service Provider Network Infrastructure Market
Network Technology
SP Routing and Ethernet Switching Market
Network Technology
US Private 5G Network Market
Network Technology
Enterprise Routers Market
Network Technology
Microduct Market
Network Technology
Industrial Wireline Networking Market
Network Technology
Unified Network Management Market
Network Technology
Managed MPLS Market
Network Technology
Internet Protocol Address Management (IPAM) Market
Network Technology
Malaysia Wireless Router Market
Network Technology
Global Internet Transit Market