
 Qatar Telecom Market | 2026-2036
Qatar Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Telecom Market Outlook
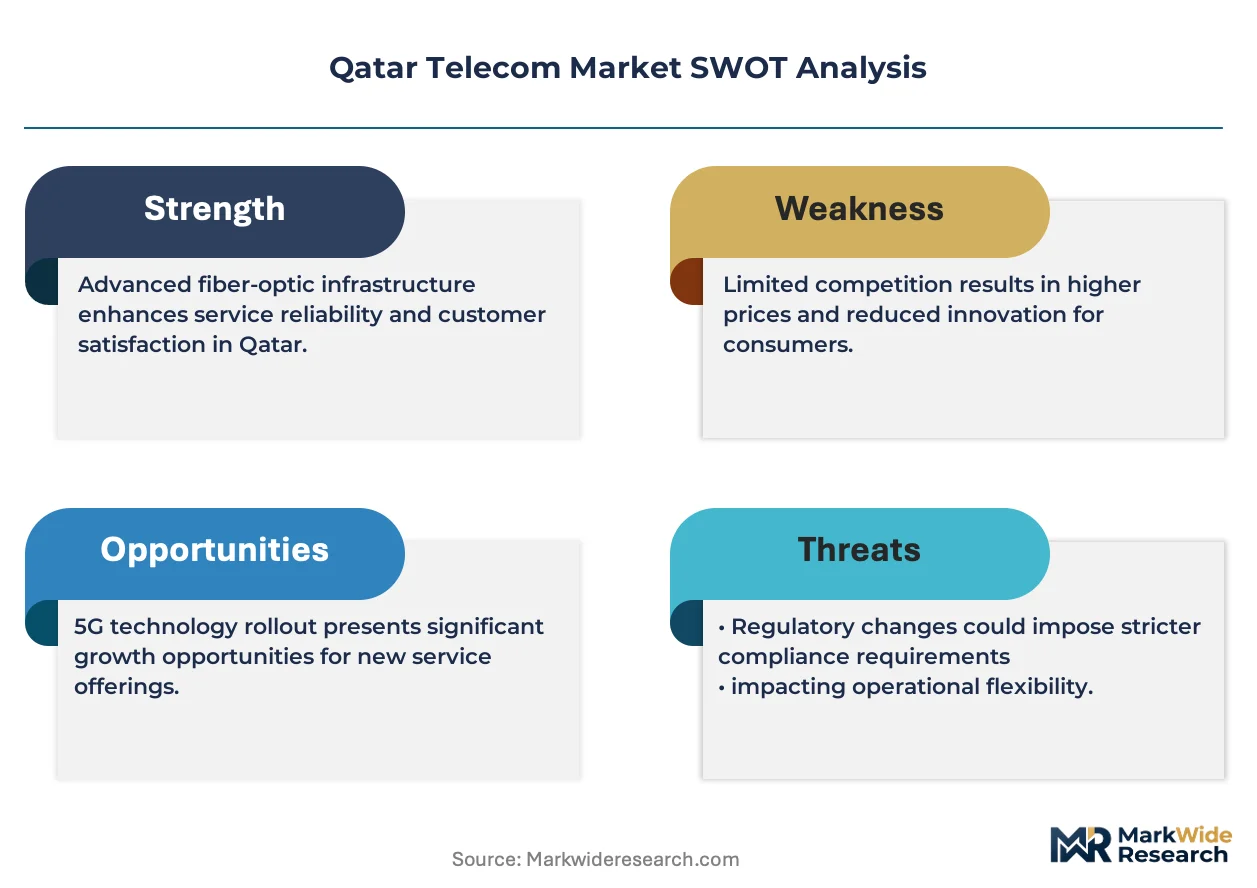
The Qatar telecom sector is recalibrating around a widening split between premium enterprise-grade managed services and commoditized residential broadband. Ooredoo Group leverages its state-backed infrastructure concessions to dominate fiber deployment across Doha's commercial corridors. Vodafone Group competes through specialized SMB bundling that anchors its position outside the enterprise tier. Huawei sustains equipment supply relationships despite geopolitical headwinds affecting vendor selection criteria.
Qatar telecom encompasses voice, data, and internet service provision across fixed and wireless infrastructure, with 5G New Radio operating in sub-6 GHz and millimeter-wave bands to deliver sub-10 millisecond latency for industrial automation and smart city applications. The primary commercial purpose centers on enabling digital economy participation for energy, finance, and logistics verticals that underpin national diversification goals. Mobile services generate the largest revenue pool, while value-added services represent the fastest-expanding margin category as enterprises adopt IoT connectivity and edge computing overlays. Fiber optics technology leads capital deployment, though 5G is displacing legacy 4G LTE in industrial zone coverage where low-latency requirements dominate procurement specifications.
The Communications Regulatory Authority governs spectrum allocation and interconnection pricing, while Qatar Central Bank cybersecurity directives shape data governance requirements for financial services connectivity. The National Cybersecurity Agency mandates encryption standards and incident reporting protocols that elevate compliance costs for foreign-managed service entrants. Stakeholders must monitor how sovereign cloud localization requirements interact with cross-border submarine cable capacity controlled by Gulf Bridge International and regional consortium arrangements.
Market Dynamics
Enterprise cloud migration is compressing procurement cycles for managed connectivity services, forcing operators to bundle fiber, 5G, and edge compute into unified service tiers. The Communications Regulatory Authority's spectrum auction timelines are accelerating infrastructure deployment decisions across Doha's industrial zones.
Growth Catalysts
- Smart City Infrastructure Mandates:Qatar National Vision 2030 targets are channeling public investment into IoT-enabled utility networks and intelligent transport systems that require low-latency fiber and 5G backhaul.
- Energy Sector Digitalization:North Field expansion projects are deploying private 5G networks for remote monitoring of LNG processing facilities, creating dedicated demand for industrial-grade connectivity.
- Financial Services Regulation:Qatar Central Bank cybersecurity directives are compelling banks to upgrade to encrypted leased lines and sovereign cloud connectivity, lifting enterprise ARPU.
Market Restraints
- Input Cost Concentration:Optical transport equipment and 5G radio units depend on concentrated Asian semiconductor fabrication, exposing capex budgets to supply chain volatility.
- Skilled Labor Scarcity:Fiber splicing, millimeter-wave antenna alignment, and network function virtualization expertise remain concentrated among a limited pool of certified technicians in the Gulf.
- Regulatory Friction:National Cybersecurity Agency incident reporting mandates impose compliance overhead that extends sales cycles for foreign-managed service providers seeking market entry.
Strategic Opportunities
- Industrial Zone Edge Computing:Ras Laffan and Mesaieed petrochemical complexes present white space for localized edge nodes that reduce latency for predictive maintenance applications.
- Converged Fixed-Wireless Bundles:Integration of fiber-to-the-premises with 5G fixed wireless access is opening new subscriber acquisition channels in suburban Doha where trenching costs delay fiber rollout.
- Sovereign Cloud Localization:Data residency requirements under Qatar's national cybersecurity framework are creating captive demand for in-country data center interconnection services.
Industry Challenges
- Legacy System Integration:Enterprise customers in logistics and manufacturing maintain heterogeneous operational technology stacks that complicate seamless 5G private network deployment.
- Certification Timeline Compression:Equipment type approval processes through the Communications Regulatory Authority create deployment gaps between product availability and commercial launch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Telecom Market |
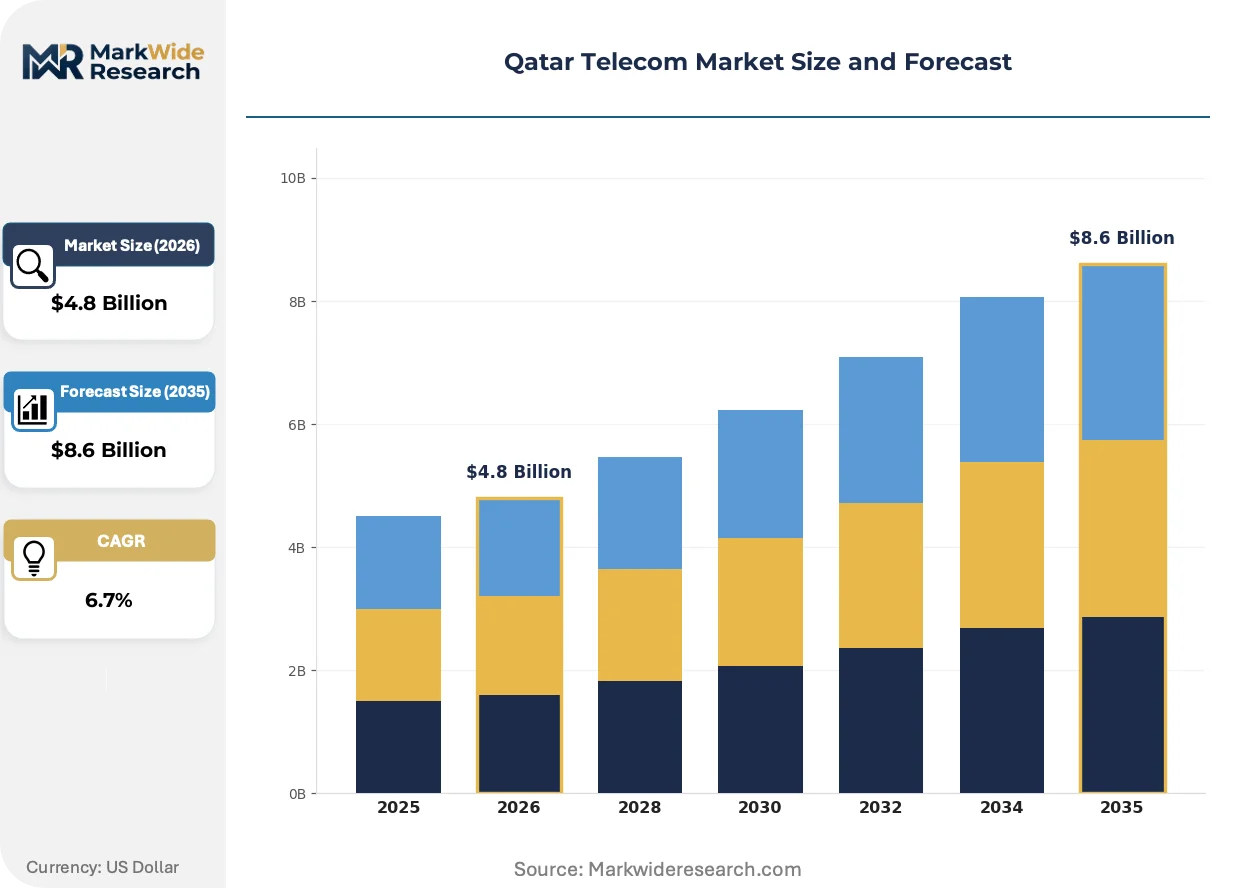
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Fixed-line Services, Broadband Services, Value-added Services Technology: 4G LTE, 5G, Fiber Optics, VoIP Customer Type: Residential, SMBs, Enterprises, Government Deployment Model: On-premises, Cloud-based, Hybrid, Managed Services |
| Companies Covered | Workz Middle East, Qatar National Broadband Network Company, Ooredoo Group, Huawei, Starlink, Vodafone Group, Etisalat, ZTE Corporation, Gulf Bridge International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Telecom Market Strategic Shifts
Network function virtualization is decoupling hardware from software layers, enabling operators to deploy services faster and reduce proprietary equipment lock-in. This architectural shift is reshaping vendor relationships and procurement specifications across Qatar's enterprise segment.
Open RAN architectures are integrating disaggregated baseband and radio unit components from multi-vendor ecosystems. Industrial zone operators are piloting these deployments to avoid single-source dependency in critical automation networks. The technology is integrating cloud-native orchestration tools that compress service provisioning from weeks to hours.
Communications Regulatory Authority spectrum refarming policies are mandating accelerated 4G LTE shutdown timelines to reclaim sub-3 GHz bands for 5G standalone deployment. Mobile network operators must migrate voice and IoT traffic to VoNR and 5G RedCap standards. Enterprise customers dependent on legacy machine-to-machine modules face forced hardware refresh cycles.
Enterprise buyers are consolidating connectivity procurement under chief information officers rather than distributed facility managers. Long-term managed service agreements are displacing transactional bandwidth contracts in energy and finance verticals. This concentration is most visible in Doha's West Bay commercial district where multinational headquarters negotiate master service frameworks covering regional operations.
Qatar Telecom Market Segmentation
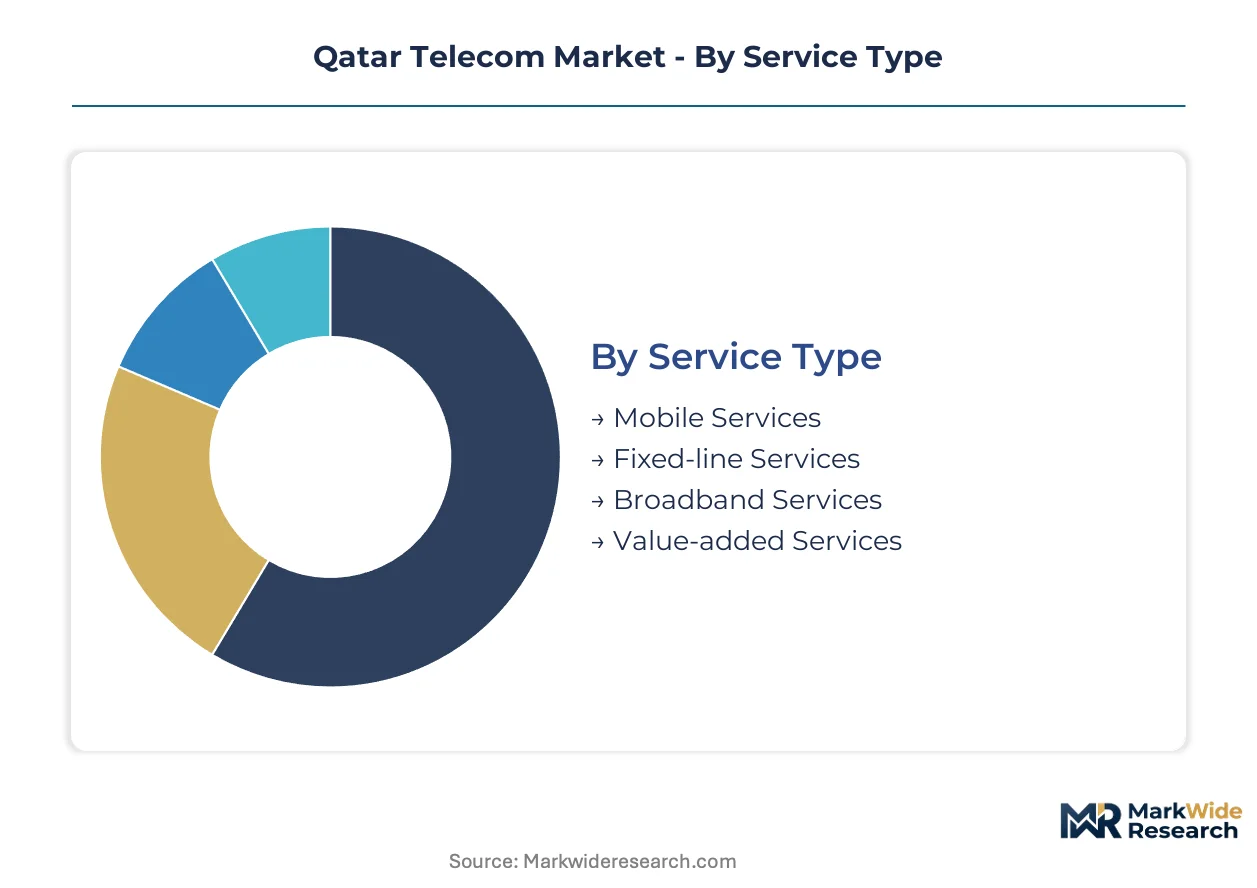
Qatar's telecom market stratifies sharply across service tiers and customer sophistication levels. Enterprise procurement concentrates on managed connectivity bundles, while residential demand fragments across price-sensitive mobile and broadband offerings. Understanding these segment boundaries reveals where operators can defend margin versus chase volume.
Service Type:
Mobile services dominate transaction volume, yet value-added services command the steepest margin expansion trajectory as enterprises adopt IoT and edge overlays.
- Mobile Services:Voice and data subscriptions across 4G LTE and 5G New Radio networks generate the largest revenue pool through consumer and enterprise accounts. Doha's dense commercial corridors and industrial zones concentrate the heaviest data consumption, driven by smartphone penetration and mobile-first workforce behavior.
- Value-added Services:IoT connectivity platforms, cloud security overlays, and edge computing integrations attach to core connectivity contracts. Energy sector digitalization at North Field LNG facilities and smart city mandates under Qatar National Vision 2030 are compressing procurement cycles for these high-margin bundles.
- Broadband Services:Fiber-to-the-premises and 5G fixed wireless access serve residential and SMB subscribers across Doha metropolitan areas.
- Fixed-line Services:Legacy copper and fiber voice circuits persist in enterprise leased-line configurations for financial services compliance.
Today's leader: Mobile Services. Tomorrow's challenger: Value-added Services.
Technology:
Capital deployment tilts toward fiber optics and 5G infrastructure, though 4G LTE retains residual coverage obligations in peripheral districts.
- Fiber Optics:Dense wavelength division multiplexing and passive optical networks deliver symmetric gigabit throughput for enterprise data centers and residential premium tiers. West Bay commercial district and Ras Laffan industrial zone anchor the heaviest fiber trenching activity, compelled by Qatar Central Bank cybersecurity directives for encrypted leased lines.
- 5G:New Radio deployments in sub-6 GHz and millimeter-wave bands achieve sub-10 millisecond latency for industrial automation. Communications Regulatory Authority spectrum refarming policies are accelerating 4G LTE shutdown timelines to reclaim sub-3 GHz bands for standalone 5G.
- 4G LTE:Legacy macro cell infrastructure carries voice and IoT traffic pending VoNR and 5G RedCap migration.
- VoIP:Session initiation protocol trunking and unified communications platforms displace traditional PSTN connectivity in enterprise environments.
Deployment gravity centers on fiber and 5G convergence, with VoIP gaining fastest among enterprise voice replacements.
Customer Type:
Enterprise and government contracts yield the highest ARPU, while residential and SMB segments drive subscriber scale.
- Enterprises:Multinational headquarters in Doha's West Bay district negotiate master service frameworks covering regional operations. Chief information officers now consolidate connectivity procurement, displacing distributed facility manager decisions and favoring long-term managed service agreements over transactional bandwidth contracts.
- Government:Smart city infrastructure mandates under Qatar National Vision 2030 channel public investment into IoT-enabled utility networks and intelligent transport systems requiring sovereign-grade connectivity.
- Residential:Consumer households subscribe to bundled mobile and broadband packages, with price sensitivity highest in suburban Doha where trenching costs delay fiber rollout.
- SMBs:Small and medium businesses access standardized connectivity tiers through channel partner distribution.
Enterprise ARPU expansion outpaces residential volume growth, though government procurement timelines introduce quarterly volatility.
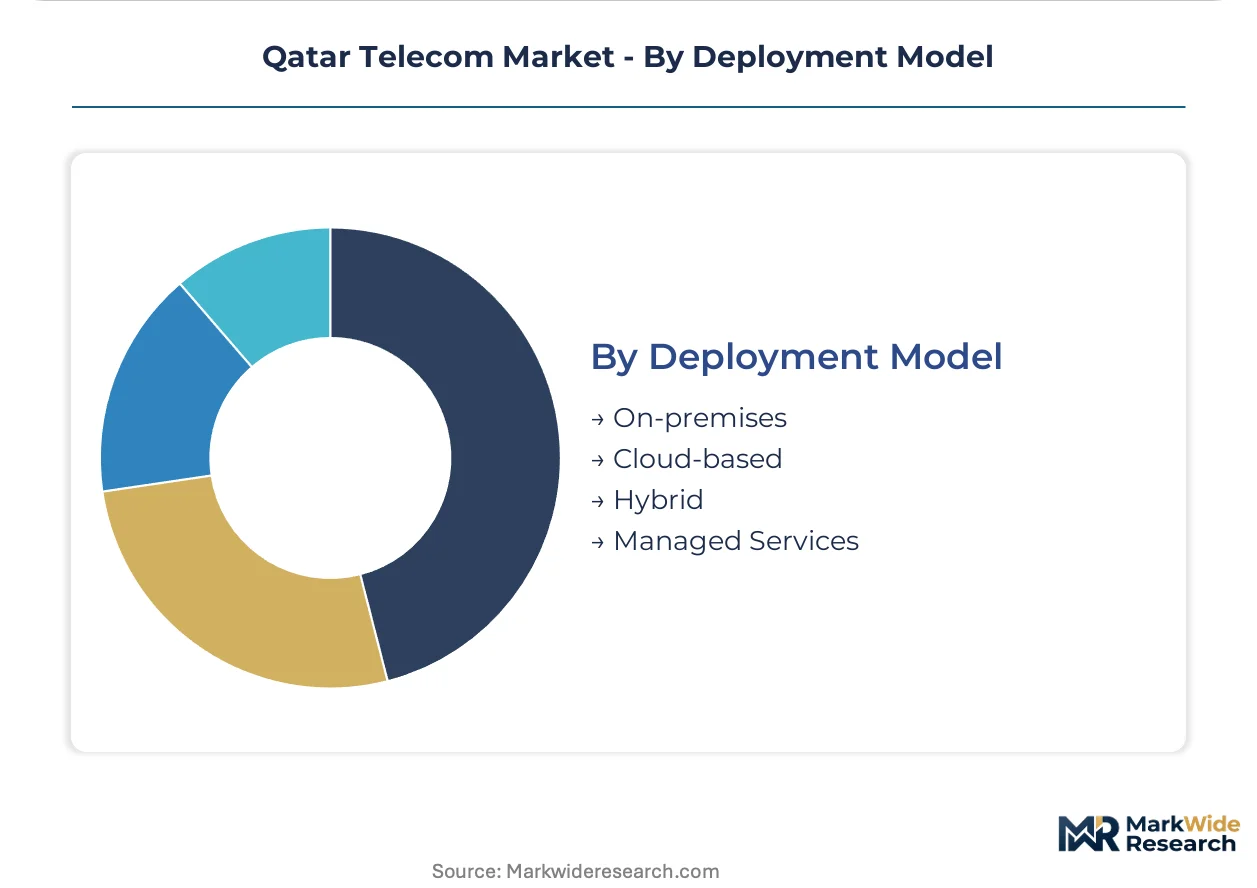
Deployment Model:
Managed services and hybrid architectures are displacing pure on-premises installations as enterprises prioritize operational expenditure over capital commitment.
- Managed Services:Operators bundle fiber, 5G, and edge compute into unified service tiers with guaranteed SLAs. Enterprise cloud migration is compressing procurement cycles, forcing vendors to absorb network function virtualization complexity.
- Hybrid:Split traffic routing between on-premises infrastructure and cloud platforms accommodates data residency requirements under National Cybersecurity Agency frameworks.
- Cloud-based:Fully virtualized network functions run on operator-hosted infrastructure, reducing proprietary equipment lock-in.
- On-premises:Dedicated customer premises equipment persists in financial services and energy sectors with stringent latency or sovereignty constraints.
Managed services capture the dominant share of new enterprise contract value, with hybrid architectures expanding most quickly among compliance-sensitive verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fiber technicians and 5G radio engineers concentrate in Doha metropolitan clusters, anchoring Qatar's telecom infrastructure deployment capacity. This talent pool directs investment toward industrial zones and commercial corridors where latency-sensitive applications dominate procurement.
Doha Metropolitan Area
West Bay commercial district and Lusail City generate concentrated demand for symmetric gigabit fiber and managed connectivity bundles. Qatar Central Bank cybersecurity directives compel financial institutions to upgrade encrypted leased lines. Multinational headquarters negotiate master service frameworks covering regional operations from Doha.
Ras Laffan Industrial Zone
North Field LNG expansion projects deploy private 5G networks for remote monitoring of processing facilities. Communications Regulatory Authority spectrum policies accelerate infrastructure deployment timelines for industrial automation. Petrochemical complexes present white space for localized edge computing nodes reducing predictive maintenance latency.
Mesaieed Industrial Area
Heavy manufacturing and logistics operations require low-latency fiber backhaul for IoT-enabled asset tracking. National Cybersecurity Agency encryption standards elevate compliance costs for foreign-managed service entrants. Aluminum smelting and steel production facilities anchor the heaviest private network installation activity.
Al Wakrah and Southern Suburbs
Residential and SMB demand fragments across price-sensitive mobile and broadband offerings. 5G fixed wireless access opens subscriber acquisition channels where fiber trenching costs delay rollout. Suburban households subscribe to bundled packages with lower ARPU than enterprise counterparts.
Education City and Technology Clusters
Research institutions and innovation hubs drive specialized connectivity requirements for high-performance computing. Qatar Foundation's smart campus mandates channel investment into IoT-enabled utility networks. University and research park procurement favors cloud-native network functions over legacy on-premises installations.
Qatar Telecom Market Competitive Environment
Capital-heavy infrastructure operators compete with asset-light service integrators across Qatar's telecom value chain. The market structure tilts toward consolidated control of fiber and spectrum assets, with tiered competition separating state-backed incumbents from specialized entrants. Two strategic archetypes dominate: vertically integrated national champions holding infrastructure concessions, and technology-focused specialists supplying equipment and managed services. Competitive moves center on spectrum acquisition timing and enterprise service bundling rather than price-based residential rivalry.
Within the national champion tier, Ooredoo Group and Vodafone Group exemplify divergent positioning strategies. Ooredoo leverages state-backed infrastructure concessions across Doha's commercial corridors. Vodafone competes through specialized SMB bundling outside the enterprise tier. Among equipment suppliers, Huawei and ZTE Corporation occupy positions shaped by geopolitical vendor selection criteria. Gulf Bridge International anchors submarine cable capacity controlling cross-border data flows.
| Leading Market Players |
|---|
| Workz Middle East |
| Qatar National Broadband Network Company |
| Ooredoo Group |
| Huawei |
| Starlink |
| Vodafone Group |
| Etisalat |
| ZTE Corporation |
| Gulf Bridge International |
| Others |
Value Chain & Pricing Dynamics
Captive infrastructure control through state-backed fiber concessions anchors both supply security and pricing power for dominant operators, while vendor diversification mandates reshape procurement economics across Qatar's telecom value chain.
Pricing Analysis
Bundled service contracts dominate enterprise procurement, compressing standalone connectivity margins while lifting attached-service ARPU. Three-tier pricing structure across premium enterprise, standard SMB, and economy residential levels separates Qatar Central Bank-mandated encrypted leased lines from commodity broadband. Cost compression in residential fiber is intensifying because 5G fixed wireless access substitutes delay trenching investments. Residential households in suburban Doha exhibit highest price sensitivity, whereas West Bay financial institutions accept premium tiers for compliance-grade latency guarantees.
Supply Chain Analysis
Dual-sourcing requirements for 5G radio units and optical transport equipment now appear in Qatar Communications Regulatory Authority procurement guidelines, forcing operators to qualify secondary vendors beyond incumbent relationships. Equipment supply draws from China, South Korea, and Finland for baseband processors, millimeter-wave arrays, and dense wavelength division multiplexing systems. Semiconductor fabrication concentration in East Asia creates single-source vulnerability for specialized ASICs and power amplifiers. Distribution runs through operator-led direct procurement for infrastructure, with channel partners handling SMB CPE and residential installation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's telecom market functions as a regulatory compounder where Communications Regulatory Authority spectrum refarming deadlines and National Cybersecurity Agency encryption mandates continuously refresh capital deployment cycles.
For Market Incumbents: Anchor market position through preemptive fiber densification in Ras Laffan and Mesaieed industrial zones before private 5G network tenders finalize. Accelerate VoNR and 5G RedCap migration to capture legacy IoT module replacement demand. Defend against Starlink and low-earth orbit entrants by locking enterprise customers into sovereign-guaranteed latency SLAs that satellite cannot match.
For New Entrants and Emerging Players: Begin with sovereign cloud interconnection services targeting Qatar Central Bank data residency requirements, where foreign hyperscalers lack local presence. The most penetrable white space sits in edge computing nodes for predictive maintenance at petrochemical facilities, bypassing fiber trenching barriers through wireless backhaul partnerships. A direct sales model to CIOs consolidating regional procurement outperforms channel distribution for enterprise traction.
For Investors and Strategic Acquirers: Consolidation pressure builds where managed service capabilities fragment across equipment vendors, systems integrators, and connectivity operators with overlapping enterprise relationships. Long-term viability favors asset-light specialists controlling network function virtualization orchestration layers rather than capital-intensive infrastructure holders facing 5G spectrum renewal cliffs. Watch Communications Regulatory Authority open-access fiber mandates as the inflection signal that would erode incumbent concession value.
| Strategic Initiative | Industry Significance |
|---|---|
| Private 5G Network Deployment | Captures North Field LNG automation budgets requiring sub-10 millisecond latency for remote monitoring. |
| Sovereign Cloud Interconnection | Addresses Qatar Central Bank data residency mandates for financial services connectivity contracts. |
| Open RAN Architecture Adoption | Reduces Huawei dependency risks while accelerating multi-vendor qualification under regulatory guidelines. |
| Edge Computing Node Installation | Targets predictive maintenance applications at Ras Laffan and Mesaieed petrochemical complexes. |
| 5G Fixed Wireless Access Launch | Opens subscriber acquisition in suburban Doha where fiber trenching economics remain unfavorable. |
Study Parameters
Direct dialogue with network operations executives, enterprise CIOs, regulatory affairs specialists, and fiber installation contractors grounded qualitative findings, validated against Communications Regulatory Authority spectrum allocation records, Qatar Central Bank cybersecurity circulars, submarine cable capacity disclosures from Gulf Bridge International, and operator capex filings. Bottom-up and top-down triangulation cross-checked service revenue estimates against infrastructure deployment permits and equipment import manifests.
Bottom-up modeling aggregated segment-level service adoption curves across mobile, broadband, and value-added categories, while top-down validation anchored aggregate market size to national digital economy targets under Qatar National Vision 2030. The analytical framework incorporated deployment model splits, customer type concentration, and technology transition timelines across the projection horizon. CAGRs derived from fitted adoption curves for 5G standalone, fiber-to-the-premises, and IoT connectivity overlays, with sensitivity analysis around spectrum auction timing and sovereign cloud procurement acceleration.
Several conditions sit outside the modeled scope, including geopolitical equipment vendor bans, Gulf Bridge International cable system disruptions, and abrupt Qatar National Vision 2030 target revisions. Deviation in Communications Regulatory Authority open-access infrastructure mandates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global 5G Enterprise Market
Telecommunications
Global B2B Telecommunication Market
Telecommunications
Thailand Telecom Market
Telecommunications
DECT System Market
Telecommunications
Norway Telecom Market
Telecommunications
Nigeria Satellite Communications Market
Telecommunications
United Kingdom Telecom Market
Telecommunications
Rich Communication Services (RCS) Messaging Market
Telecommunications
Russia Telecom Market
Telecommunications
Belgium Telecom Market
Telecommunications
Video Door Phones Market
Telecommunications
Global SMB Telecom Voice and Data Services Market
Telecommunications
Europe Telecom Expense Management Market
Telecommunications
Vietnam Telecom Market
Telecommunications
North America Underwater Communication Systems Market
Telecommunications
CDMA Mobile Phone Market