
 Africa Entertainment and Telecommunication Market | 2026-2036
Africa Entertainment and Telecommunication Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Entertainment and Telecommunication Market Outlook
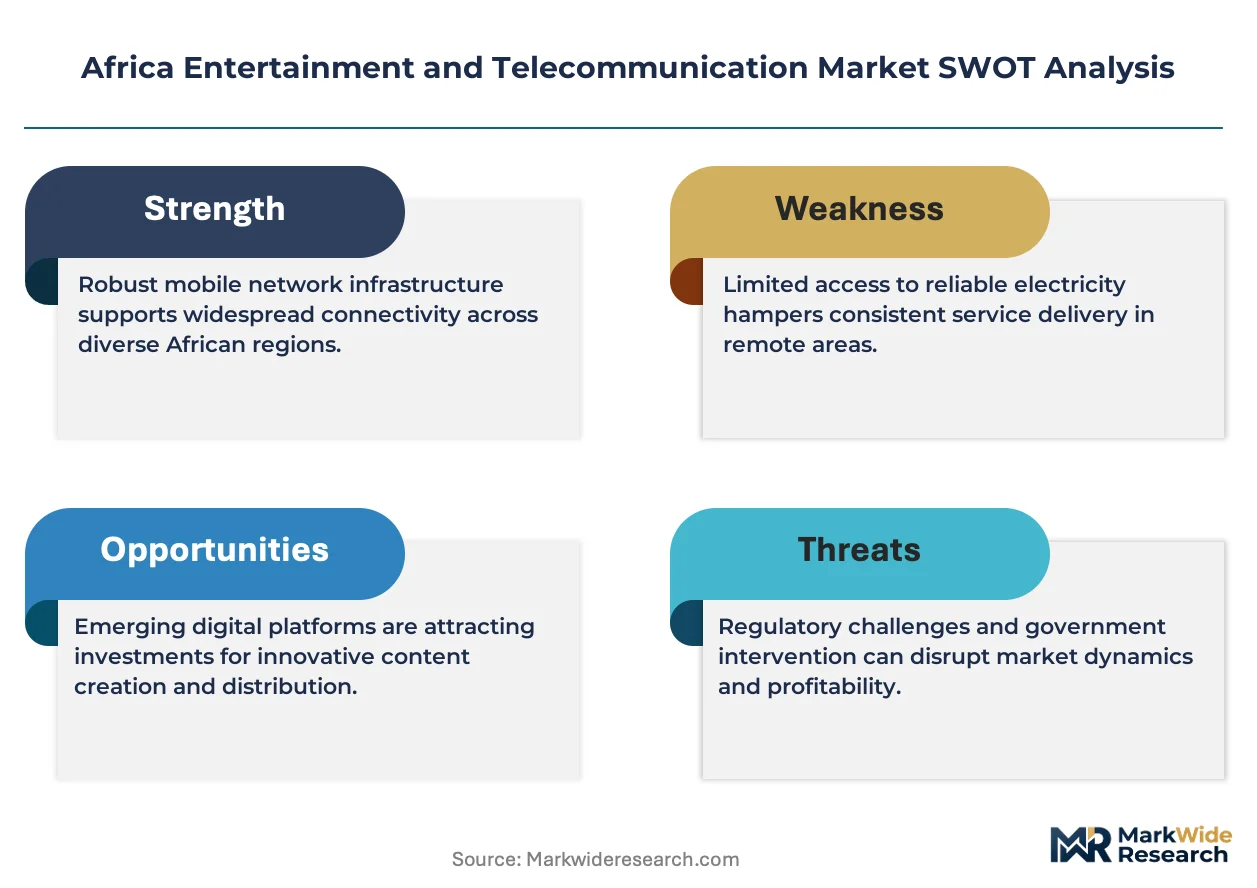
Project finance partnerships for submarine cable and tower infrastructure are reshaping competitive dynamics across Africa's entertainment and telecommunication landscape. MTN Group leverages its mobile money platform to sustain subscriber stickiness in fourteen African markets. Airtel Africa anchors its growth strategy on affordable data bundles and digital financial services penetration. Vodacom competes through network densification and enterprise cloud offerings in Southern and East Africa.
The Africa entertainment and telecommunication sector encompasses the production, distribution, and consumption of audio-visual content alongside voice and data transmission services across wireless and fixed-line networks. Fiber optic backbone deployment and 4G LTE spectrum allocation determine service quality thresholds for streaming latency and call reliability across the continent's varied terrain. Mobile data and streaming services represent the fastest-expanding revenue pools as smartphone penetration deepens and local content production accelerates. Fixed broadband and broadcast media retain structural importance in urban commercial centers where fiber-to-the-premises infrastructure supports enterprise-grade connectivity requirements.
National communications regulators in Nigeria, South Africa, and Kenya enforce spectrum allocation frameworks and local content quotas that directly shape market entry conditions and infrastructure investment timelines. The African Union's Digital Transformation Strategy coordinates cross-border data governance standards while country-level central banks supervise mobile money licensing to maintain financial system integrity. Stakeholders must monitor spectrum auction schedules and data localization mandates to anticipate competitive repositioning opportunities.
Market Dynamics
Spectrum liberalization by national communications authorities is compressing infrastructure deployment timelines while mobile money integration is digitizing rural consumer access across the continent's fragmented terrain.
Growth Catalysts
- 4G LTE spectrum allocation:Nigeria's national communications authority has released additional frequency bands, enabling tower operators to extend coverage into secondary cities and reduce streaming latency for video-on-demand services.
- Mobile money platform integration:Rural individual consumers in Kenya and Ghana now subscribe to data bundles through interoperable financial rails, eliminating cash friction and reducing churn.
- Local content production quotas:South Africa's broadcasting regulator mandates minimum domestic programming hours, driving studio infrastructure investment and talent pool expansion in Johannesburg and Cape Town.
Market Restraints
- Diesel generator dependency:Base station operators in markets with unreliable grid power face fuel cost volatility that erodes tower economics and constrains rural rollout feasibility.
- Submarine cable concentration:West African coastal landing stations route through a limited number of fiber optic entry points, creating single-point-of-failure risk for international bandwidth pricing.
- Device import duties:Smartphone affordability thresholds remain elevated in landlocked markets due to customs regimes that inflate retail hardware costs for mass-market consumers.
Strategic Opportunities
- Ethiopia's market liberalization:The partial privatization of the incumbent operator creates greenfield entry points for infrastructure investors and streaming platform localization.
- Enterprise cloud convergence:Financial services and logistics verticals in Lagos and Nairobi demand hybrid connectivity solutions combining fiber, fixed wireless, and edge computing.
- Cross-border data governance:The African Union's Digital Transformation Strategy harmonizes certification requirements, reducing compliance fragmentation for pan-regional service providers.
Industry Challenges
- Fiber trenching permits:Municipal approval timelines for right-of-way access in dense urban corridors delay last-mile deployment and inflate project carrying costs.
- Legacy billing system integration:Established operators migrating to real-time charging platforms face data migration complexity that disrupts customer experience during transition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Entertainment and Telecommunication Market |
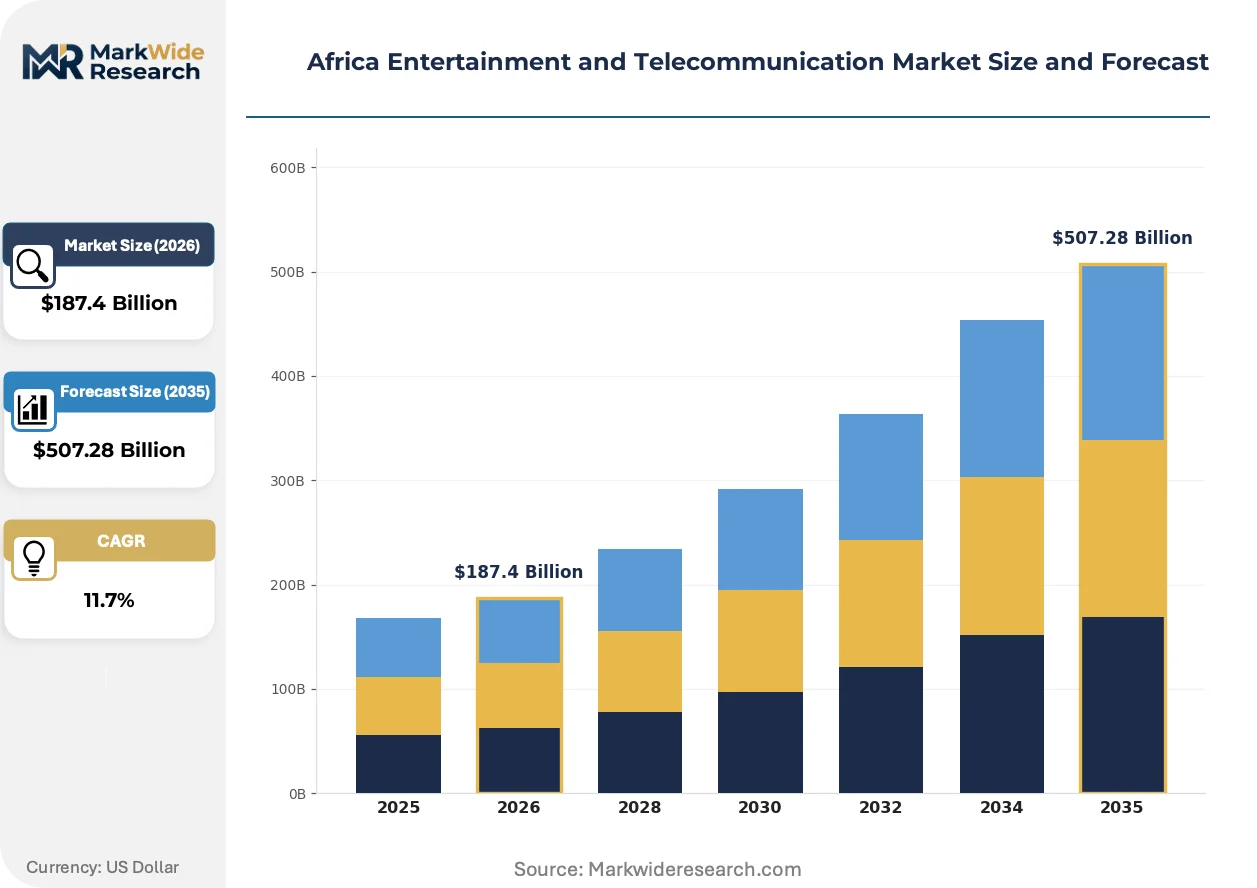
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Voice, Mobile Data, Fixed Voice, Fixed Broadband Customer Type: Individual Consumers, Businesses, Government, Educational Institutions Technology: 4G LTE, 5G, Fiber Optic, Satellite Content Type: Streaming Services, Broadcast Media, Gaming, Social Media |
| Companies Covered | Telkom SA SOC Ltd, Airtel Africa, MTN Group, Netflix, Globacom, Vodacom, Maroc Telecom SA, Spotify, Orange Africa & Middle-East, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Entertainment and Telecommunication Market Strategic Shifts
Convergence between financial technology rails and entertainment distribution is restructuring how African consumers discover, purchase, and consume content across device categories.
Edge computing nodes deployed at cellular base stations are digitizing content delivery architecture. Streaming platforms in Nigeria and South Africa cache high-bandwidth video closer to end-users, reducing backhaul congestion during peak evening viewing hours. This distributed infrastructure is digitizing the economics of rural subscriber acquisition by compressing data delivery costs below urban parity thresholds.
Kenya's data protection framework and South Africa's information regulator guidelines are tightening cross-border data flow governance. Multinational platform operators must localize subscriber data storage and establish domestic legal entities to maintain licensing compliance. East African markets with mature regulatory capacity are experiencing accelerated vendor qualification timelines as authorities enforce certification requirements for payment-integrated services.
Subscription bundling is displacing standalone service purchases across West African urban corridors. Consumers in Lagos-Abuja corridor markets consolidate mobile money, data, and streaming access through single-provider relationships, reducing price comparison behavior and lengthening contract tenures. This consolidation pattern concentrates most visibly among salary-earning demographics with formal banking access.
Africa Entertainment and Telecommunication Market Segmentation
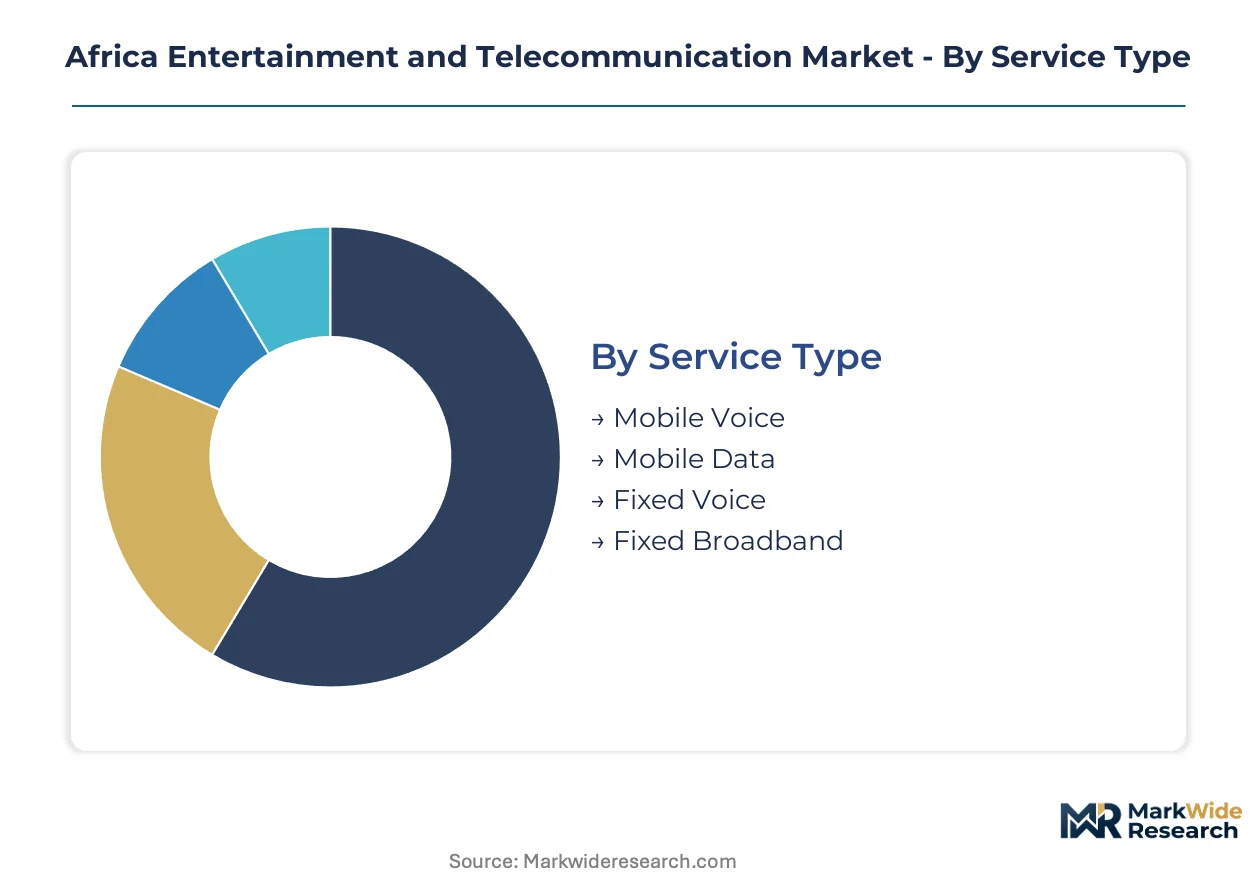
Segmentation across Africa's entertainment and telecommunication landscape reveals distinct infrastructure requirements, pricing elasticities, and regulatory exposure profiles. Service providers calibrate network investments and content licensing strategies differently for each dimension, from spectrum-dependent mobile delivery to fiber-backed enterprise connectivity.
Service Type:
Service type segmentation spans the full connectivity spectrum from low-bandwidth voice to high-throughput broadband, each carrying divergent capital intensity and margin profiles.
- Mobile Voice:Circuit-switched and VoLTE services deliver basic telephony across 2G and 3G networks still prevalent in rural catchments. Demand concentrates among informal sector workers in Nigeria's northern states and Ethiopia's agricultural zones where smartphone penetration remains limited and per-call pricing sensitivity is acute.
- Mobile Data:4G LTE and emerging 5G services support streaming, mobile money, and enterprise applications. Nigeria's Lagos-Abuja corridor and South Africa's Gauteng province drive volume, propelled by video consumption growth and fintech platform integration that locks subscribers into data-heavy usage patterns.
- Fixed Voice:Copper-line and VoIP services persist in legacy enterprise installations and government offices. Kenya's Nairobi commercial district and Morocco's Casablanca financial center sustain residual demand from regulated institutions with mandated landline redundancy requirements.
- Fixed Broadband:Fiber-to-the-premises and fixed wireless access deliver enterprise-grade connectivity with service level agreements. South Africa's Western Cape tech corridor and Kenya's Konza Technopolis anchor demand from data center operators and offshore business process outsourcing facilities requiring sub-10ms latency guarantees.
The dominant share belongs to Mobile Data, while Mobile Voice is closing the gap fastest through VoLTE substitution and bundled data-voice packages.
Customer Type:
Customer segmentation reflects divergent procurement authority, contract structures, and price elasticity across consumer and institutional categories.
- Individual Consumers:Prepaid and postpaid subscribers purchasing through retail channels with high churn sensitivity. Nigeria's youth demographic and Ghana's urban salary earners concentrate demand, driven by social media platform engagement and mobile money-enabled micro-transactions for content access.
- Businesses:Small enterprises through multinational corporations procuring connectivity with dedicated account management. Kenya's Nairobi logistics hubs and South Africa's Johannesburg financial district sustain premium pricing for guaranteed uptime, with demand accelerating for hybrid cloud-connectivity bundles.
- Government:National and sub-national agencies with mandated local procurement and sovereign data routing requirements. Ethiopia's federal ministries and Senegal's regional administrations drive tender volumes, constrained by budget approval cycles and preference for incumbent operator relationships.
- Educational Institutions:Universities and vocational centers requiring campus-wide coverage and research network access. Morocco's Rabat university cluster and Uganda's Makerere University anchor demand, with procurement shifting toward multi-year managed service contracts bundling device financing.
Individual Consumers command the largest addressable base, though Businesses deliver superior unit economics and contract tenures.
Technology:
Technology segmentation tracks infrastructure vintage and spectral efficiency, determining coverage economics and service quality thresholds.
- 4G LTE:Dominant radio access technology across urban and peri-urban deployments with mature device ecosystems. Nigeria's spectrum liberalization and Kenya's base station densification programs concentrate rollout momentum, enabling streaming services to achieve rural penetration previously blocked by 3G capacity constraints.
- 5G:Next-generation radio with millimeter-wave and sub-6GHz deployments limited to high-density commercial zones. South Africa's Johannesburg Sandton district and Nigeria's Lagos Island financial center host initial coverage, with enterprise private network deployments driving early monetization before consumer handset affordability thresholds shift.
- Fiber Optic:Backbone and last-mile terrestrial infrastructure delivering unconstrained bandwidth for fixed services. Egypt's Suez Canal corridor and Angola's Luanda metropolitan fiber ring anchor continental capacity, with open-access regulatory mandates in Kenya and Rwanda accelerating wholesale pricing compression.
- Satellite:Geostationary and low-earth orbit constellations serving beyond-fiber rural and maritime markets. Mozambique's coastal provinces and Mali's Sahelian interior depend on satellite backhaul, with emerging LEO provider competition threatening legacy VSAT pricing structures.
4G LTE retains the installed base advantage, while Fiber Optic is expanding most quickly through metropolitan open-access mandates and development finance institution project finance.
Content Type:
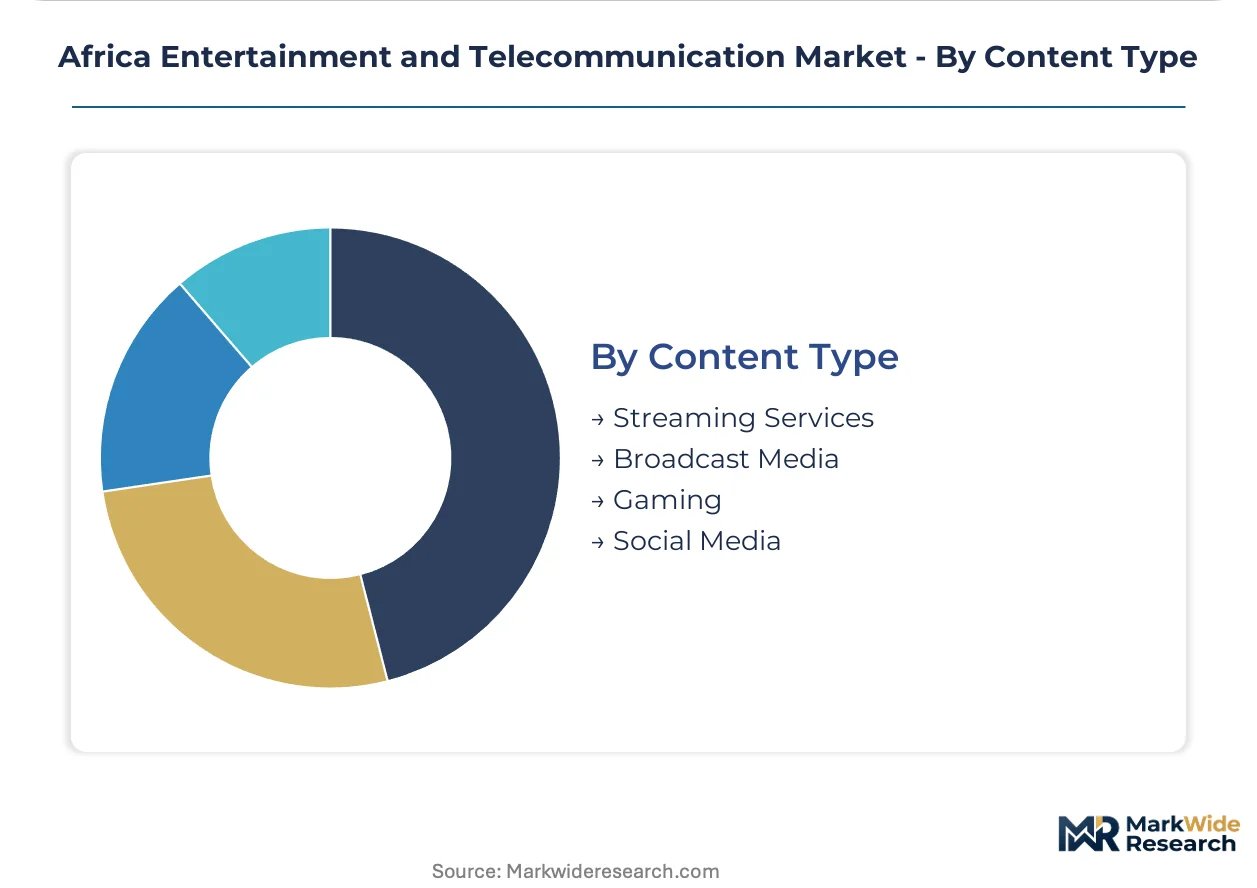
Content type segmentation distinguishes bandwidth intensity, licensing complexity, and platform business model variation across entertainment categories.
- Streaming Services:Subscription and advertising-supported video-on-demand platforms requiring sustained high-throughput delivery. Nigeria's Nollywood production ecosystem and South Africa's Showmax localization investments concentrate subscriber acquisition spend, with mobile data bundle partnerships reducing payment friction.
- Broadcast Media:Terrestrial and satellite television with regulatory-mandated local content quotas. Kenya's digital migration completion and Ghana's broadcasting authority licensing frameworks shape competitive entry, with advertising revenue pools contracting as audiences fragment toward on-demand alternatives.
- Gaming:Mobile, console, and cloud gaming services with low-latency requirements and in-transaction monetization. Egypt's Cairo youth demographic and South Africa's Gauteng gaming lounges drive engagement, with mobile esports tournament platforms emerging as distribution channels for telco data bundle promotion.
- Social Media:Messaging, short-form video, and content-sharing platforms dominating consumer screen time. Nigeria's Instagram and TikTok creator economy and Ethiopia's Telegram channel proliferation concentrate usage, with zero-rating negotiations between platforms and operators determining access economics for price-sensitive segments.
Streaming Services capture the premium revenue trajectory, while Social Media commands the aggregate engagement minutes that underpin advertising and data bundle monetization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spectrum liberalization policies and mobile money integration are reshaping infrastructure deployment across the continent's most populous markets. National communications authorities in Nigeria, South Africa, Kenya, and Egypt are accelerating 4G LTE rollout timelines through competitive auction frameworks. Ethiopia's partial privatization of its incumbent operator creates new entry corridors for infrastructure investors and streaming platform localization.
Nigeria
Lagos-Abuja corridor demand concentrates around video streaming and fintech platform integration among salary-earning demographics. The Nigerian Communications Commission enforces spectrum allocation frameworks that shape market entry conditions and infrastructure investment timelines. Tower operators extend coverage into secondary cities, reducing streaming latency for video-on-demand services as additional frequency bands release.
South Africa
Gauteng province and Western Cape tech corridor anchor enterprise-grade connectivity requirements from data center operators and offshore business process outsourcing facilities. The Independent Communications Authority of South Africa mandates local content quotas that drive studio infrastructure investment in Johannesburg and Cape Town. Network densification programs compete with enterprise cloud offerings for capital allocation across Southern Africa operations.
Kenya
Nairobi logistics hubs and Konza Technopolis sustain premium pricing for guaranteed uptime and hybrid cloud-connectivity bundles. The Communications Authority of Kenya supervises mobile money licensing through interoperability frameworks that digitize rural consumer access. Base station densification programs enable streaming services to achieve rural penetration previously blocked by 3G capacity constraints.
Egypt
Cairo youth demographic engagement with mobile esports tournament platforms drives data bundle promotion channels. The National Telecom Regulatory Authority coordinates fiber optic backbone deployment along the Suez Canal corridor anchoring continental capacity. Terrestrial infrastructure delivers unconstrained bandwidth for fixed services through metropolitan open-access mandates accelerating wholesale pricing compression.
Ethiopia
Partial privatization of Ethio Telecom creates greenfield entry points for infrastructure investors navigating federal ministry procurement preferences. The Ethiopian Communications Authority establishes licensing frameworks for mobile money platform integration among agricultural zone consumers. Federal ministries and regional administrations drive tender volumes constrained by budget approval cycles and preference for incumbent operator relationships.
Africa Entertainment and Telecommunication Market Competitive Environment
On the supply side, the industry is consolidating around pan-regional mobile network operators with integrated financial services platforms and global streaming platforms with localized content strategies. Three strategic archetypes dominate: telecommunications conglomerates with mobile money infrastructure, pure-play streaming services with original content production, and tower operators with energy-efficient rural deployment capabilities. Competitive positioning depends on spectrum acquisition timing and fiber backbone access rather than manufacturing scale or raw material sourcing.
Within the pan-African telecommunications tier, MTN Group, Airtel Africa, and Vodacom represent the integrated mobile money and data infrastructure archetype. MTN Group leverages its platform across fourteen markets to sustain subscriber stickiness through interoperable financial rails. Airtel Africa anchors positioning on affordable data bundles and digital financial services penetration. Vodacom competes through network densification concentration in Southern and East Africa. Among global streaming entrants, Netflix and Spotify exemplify the content licensing and localization model, negotiating zero-rating arrangements with operators to reduce payment friction for price-sensitive segments. Orange Africa & Middle-East and Maroc Telecom SA occupy positions bridging European headquarters coordination with national operating company execution across Francophone markets.
| Leading Market Players |
|---|
| Telkom SA SOC Ltd |
| Airtel Africa |
| MTN Group |
| Netflix |
| Globacom |
| Vodacom |
| Maroc Telecom SA |
| Spotify |
| Orange Africa & Middle-East |
| Others |
Value Chain & Pricing Dynamics
Diesel generator dependency across Nigeria's northern states and Kenya's rural catchments compresses tower economics and forces a three-tier pricing structure that separates premium urban fiber from standard peri-urban wireless and economy rural satellite backhaul tiers.
Pricing Analysis
Spectrum scarcity in Lagos-Abuja corridor and Johannesburg-Cape Town axis creates the primary spread between premium enterprise-grade connectivity with guaranteed uptime and economy prepaid data bundles for price-sensitive rural consumers. Three-tier pricing structure across premium, standard, and economy levels stratifies by latency guarantees and data volume caps. Cost compression in economy tiers is intensifying because smartphone affordability thresholds remain elevated due to customs regimes inflating retail hardware costs. Individual consumers in informal sectors exhibit acute price sensitivity, while financial services and logistics verticals in Nairobi and Lagos accept premium pricing for hybrid cloud-connectivity bundles.
Supply Chain Analysis
Optical fiber draw towers in China, submarine cable manufacturing in France, and base station equipment assembly in South Korea feed the upstream infrastructure pipeline for African deployment. Equipment sourcing draws from Huawei and Ericsson assembly facilities, fiber optic cable from Corning and Prysmian plants, and diesel generators from Cummins and Caterpillar distribution networks. Single-source vulnerability concentrates in submarine cable landing stations along West African coastal corridors where limited fiber optic entry points create pricing volatility risk for international bandwidth. Distribution runs through pan-regional mobile network operators with integrated procurement functions and tower operators with energy-efficient rural deployment capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Over-the-top streaming platforms and mobile money-enabled fintech rails threaten to disintermediate traditional telecommunications revenue pools, forcing incumbents to defend subscriber relationships through bundled service consolidation.
For Market Incumbents: Entrench subscriber stickiness through mobile money platform interoperability that locks rural consumers into data-heavy usage patterns across fourteen-market footprints. Deepen backward integration into tower infrastructure through project finance partnerships for energy-efficient rural deployment, insulating against diesel cost volatility that erodes base station economics. Spectrum acquisition timing in Nigeria and South Africa remains the critical defensive lever against emerging 5G private network competitors. For New Entrants and Emerging Players: Build out edge computing nodes at cellular base stations to capture streaming latency reduction contracts from Nollywood and Showmax localization investments in Nigeria and South Africa. Ethiopia's partial privatization of Ethio Telecom presents the most penetrable greenfield entry corridor for infrastructure investors and platform localization. Target enterprise cloud convergence in Lagos logistics hubs and Nairobi Konza Technopolis through hybrid fiber-fixed wireless solutions with sub-10ms latency guarantees. For Investors and Strategic Acquirers: The market sits at a spectrum liberalization phase that favors tower operators with energy-efficient rural deployment capabilities and streaming platforms with original content production. Long-term viability over a 5-10 year window rests on fiber backbone access and mobile money licensing breadth rather than manufacturing scale. Acquisition target archetypes include pan-regional operators with interoperable financial rails and localized content studios in Johannesburg and Cape Town. Watch for African Union Digital Transformation Strategy harmonization progress as the inflection signal for pan-regional compliance cost reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum Acquisition | 4G LTE and 5G frequency band access in Nigeria and South Africa determines streaming latency thresholds and enterprise service quality. |
| Mobile Money Integration | Interoperable financial rails in Kenya and Ghana eliminate cash friction and reduce subscriber churn for data bundle subscriptions. |
| Fiber Backbone Deployment | Terrestrial infrastructure along Egypt's Suez Canal corridor anchors continental capacity for fixed broadband enterprise services. |
| Local Content Production | South Africa's broadcasting regulator mandates drive studio infrastructure investment and talent pool expansion in Johannesburg. |
| Edge Computing Nodes | Base station caching in Nigeria reduces backhaul congestion during peak evening streaming hours for video-on-demand platforms. |
Study Parameters
The analysis maps mobile voice, mobile data, fixed broadband, and streaming services segments, each validated through network planning executives, mobile money platform managers, content licensing directors, and national communications authority officials. Primary interviews with MTN Group and Airtel Africa infrastructure strategists combined with secondary validation through Nigerian Communications Commission spectrum auction records, South Africa's ICASA licensing frameworks, and Kenyan Communications Authority interoperability guidelines. Trade data from submarine cable consortia, tower operator deployment disclosures, and streaming platform subscriber metrics anchored bottom-up and top-down triangulation.
Assumptions held fixed include current spectrum allocation timelines and mobile money licensing frameworks across the analysis window, while variables included 5G deployment pace and Ethiopia market liberalization depth. Segmentation dimensions modeled span service type, customer category, technology vintage, and content bandwidth intensity. CAGRs derived from equipment shipment trajectories, subscriber growth curves, and average revenue per user migration patterns across prepaid-to-postpaid transitions. Fiber trenching permit timelines and diesel generator fuel cost volatility served as industry-specific forecast sensitivity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive infrastructure sharing moves by tower operators or regulatory acceleration by national communications authorities would shift outcomes. Cross-checking against African Union Digital Transformation Strategy implementation progress and central bank mobile money interoperability mandates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Africa Roaming Tariff Market
Telecommunications
Italy Telecom Market
Telecommunications
Telecom Radio System Software Market
Telecommunications
Embedded SIM (Esim) Market
Telecommunications
Managed Mobility Services (MMS) Market
Telecommunications
Global Esim Market
Telecommunications
Cloud Telephony Service Market
Telecommunications
Norway Telecom Market
Telecommunications
Global Radio Access Network Market
Telecommunications
Smart Feature Phone Market
Telecommunications
Peru Telecom Market
Telecommunications
Mobile Satellite Services (MSS) Market
Telecommunications
5G in Defense Market
Telecommunications
Global LTE Market
Telecommunications
Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Managed M2M Services Market