
 IoT Telecom Services Market | 2026-2036
IoT Telecom Services Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Telecom Services Market Intelligence
The convergence of 5G network slicing and edge computing is reconfiguring how IoT telecom services are delivered, enabling new low-latency applications. Ericsson leverages its extensive network infrastructure portfolio to support massive IoT deployments for industrial clients. Huawei Technologies competes on the basis of its end-to-end hardware and software solutions, particularly in developing economies. Meanwhile, Verizon Communications positions its services around high-bandwidth 5G use cases in the United States.
IoT telecom services encompass the provisioning and management of cellular and satellite connectivity for distributed devices. These services involve SIM lifecycle management, secure data routing, and API-driven platforms for controlling large-scale deployments. Connectivity Management remains the foundational service type, while Data Analytics and Security Solutions are becoming key differentiators for providers. Demand from Industrial Automation and Connected Vehicles use cases is driving requirements for higher reliability and lower latency services.
Data sovereignty and privacy regulations, such as the EU's GDPR, impose strict requirements on how IoT data is handled and stored. In parallel, bodies like the US FCC regulate spectrum allocation for cellular IoT, while ISO standards guide device and network interoperability. Stakeholders must now decide whether to build proprietary security stacks or partner with specialized providers to meet evolving cyber threat landscapes.
Market Dynamics
The fundamental dynamic shaping the IoT telecom services market is the divergence in network requirements. This split is between the massive demand for low-cost, low-power connectivity for simple devices and the growing need for ultra-reliable, low-latency services for critical industrial and automotive applications.
Growth Catalysts
- 5G Infrastructure Expansion:The widespread deployment of 5G networks enables new use cases in industrial automation and connected health that require high bandwidth and low latency, pulling demand for advanced telecom services.
- Automotive Sector Demand:The automotive industry's push towards Cellular Vehicle-to-Everything (C-V2X) communication for safety and autonomous functions creates a large-scale, high-value demand anchor for specialized connectivity.
- Smart Metering Mandates:Government policies mandating smart utility meters, particularly in European Union member states and parts of Asia, compel utilities to secure long-term connectivity contracts for millions of endpoints.
Market Restraints
- Component Cost Structure:The higher unit cost of cellular modules compared to Wi-Fi or LoRaWAN alternatives restricts adoption in highly price-sensitive consumer electronics and agricultural sensor applications.
- Device Power Consumption:Battery life limitations in mobile and remote IoT devices that rely on cellular connectivity remain a significant engineering and deployment barrier, particularly for massive-scale deployments.
- International Roaming Complexity:Fragmented and costly international roaming agreements for IoT SIMs create logistical and financial friction for companies managing global asset tracking and supply chain logistics.
Strategic Opportunities
- Non-Terrestrial Networks:Integrating satellite connectivity with terrestrial cellular networks opens up service delivery for agriculture, maritime, and mining operations in regions with no terrestrial coverage.
- Private 5G for Industry:The expansion of private cellular networks within factories and logistics centers creates an opportunity for specialized service offerings focused on industrial IoT protocols and security.
- Underpenetrated Geographies:India's rapid industrialization and smart city initiatives present a vast market for IoT connectivity services, supported by government programs promoting domestic manufacturing and digital infrastructure.
Industry Challenges
- Legacy System Integration:Connecting new IoT service platforms with an enterprise's existing operational technology (OT) and IT infrastructure is a primary source of complexity, cost overruns, and project delays.
- Cybersecurity Threat Surface:The sheer volume and diversity of connected devices create a massive and constantly evolving attack surface, requiring continuous investment in threat detection and mitigation capabilities.
- Interoperability Standards:A lack of universal interoperability across different device and platform vendors, despite efforts by bodies like ISO, complicates large-scale, multi-vendor deployments for enterprise clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Telecom Services Market |
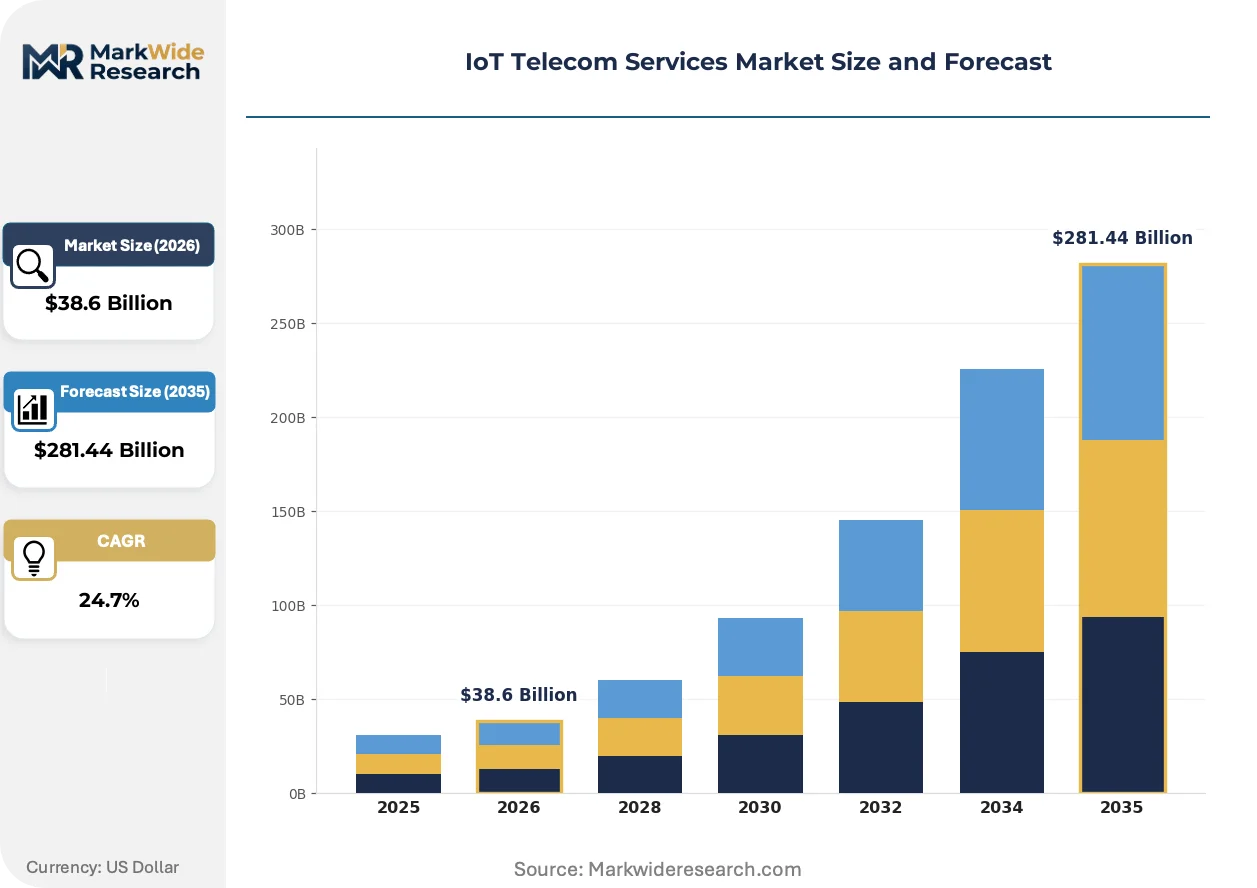
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $281.44 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Connectivity Management, Device Management, Data Analytics, Security Solutions, Network Provisioning Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Edge Computing, On-Premises Use Case: Smart Cities, Connected Vehicles, Industrial Automation, Agriculture Monitoring, Energy Management Client Type: Telecom Operators, System Integrators, Enterprises, Managed Service Providers, Original Device Manufacturers |
| Companies Covered | Deutsche Telekom, Huawei Technologies, Vodafone Group, Nokia, Ericsson, AT&T, China Mobile, Orange S.A., Verizon Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Telecom Services Market Strategic Shifts & Innovations
The market's evolution is defined by a move away from providing simple data transport toward delivering integrated, application-aware network services. This progression is driven by the convergence of advanced network capabilities with specific enterprise IT requirements, creating new value beyond basic connectivity.
The integrated SIM (iSIM) embeds subscriber identity functionality directly into a device's primary system-on-a-chip (SoC). Device manufacturers in industrial sensing and consumer wearables are adopting iSIM to reduce physical size, component cost, and power consumption. The market's approach to device provisioning is migrating from physical SIM card logistics to a fully software-defined, over-the-air lifecycle management model enabled by this technology.
The European Union's GDPR imposes strict rules on the processing and transfer of personal data, which includes data from many consumer IoT devices. This regulation compels service providers to offer localized data routing and storage solutions, ensuring data from EU-based devices remains within the jurisdiction. The connected health and smart home segments are most affected, now requiring providers to build robust, region-specific data sovereignty frameworks.
Enterprise customers are increasingly acquiring bundled solutions that include device management, security, and data analytics, rather than just raw connectivity on a per-gigabyte basis. This shift favors managed service providers who can offer end-to-end application enablement over pure-play connectivity resellers. This trend is most prominent in the fleet management and industrial automation verticals, where operational uptime is valued more than the raw cost of data transport.
IoT Telecom Services Market Segmentation
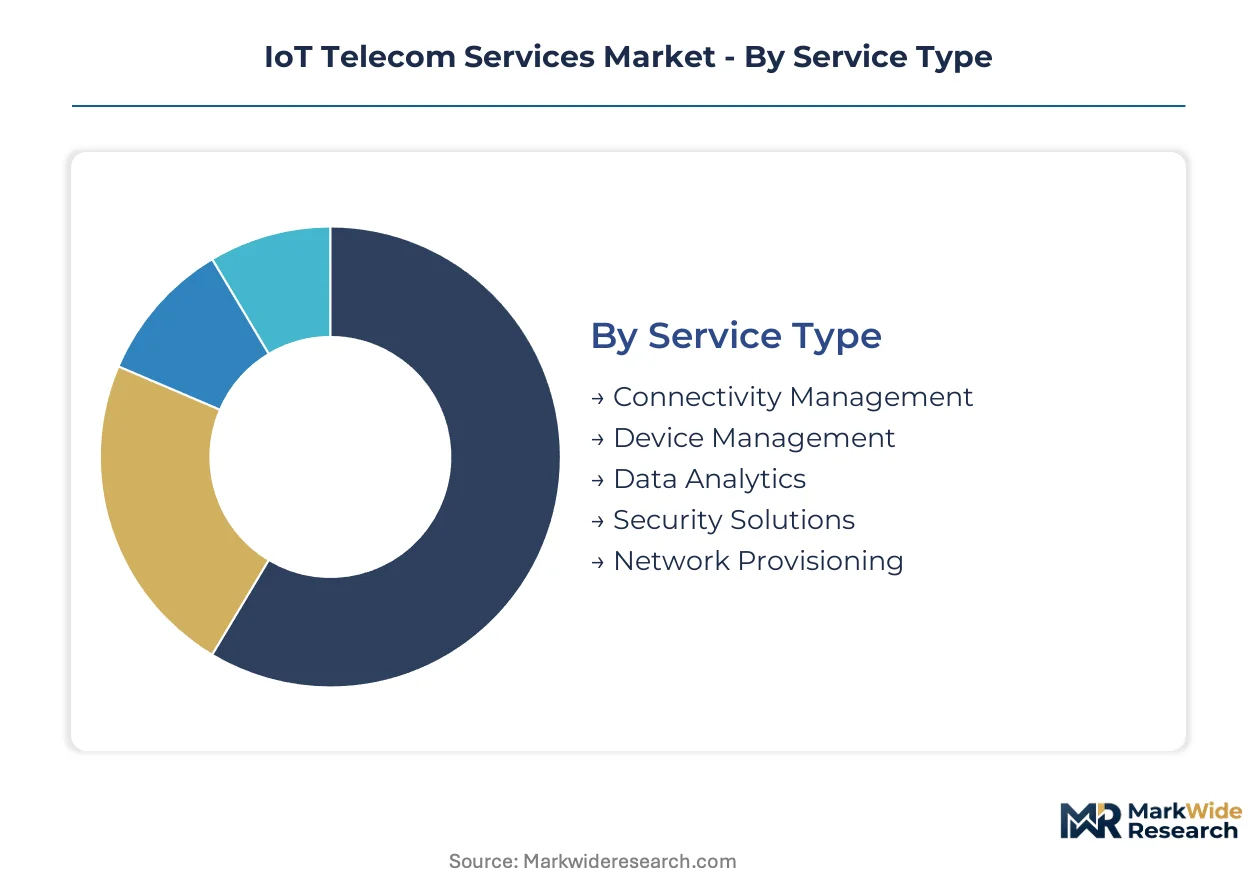
The IoT telecom services market exhibits diverse requirements across various dimensions, necessitating a granular understanding of its structure. Segmentation helps to identify distinct demand patterns, technology preferences, and operational models that influence service provisioning. This granular analysis is crucial for providers to tailor offerings and address specific industry challenges.
Service Type:
The service types available delineate the core functionalities provided within the IoT telecom ecosystem.
- Connectivity Management:This service involves the provisioning, activation, and monitoring of cellular and satellite connections for IoT devices globally. Demand concentrates in large-scale deployments like smart metering and fleet management, driven by the need for reliable, always-on communication.
- Security Solutions:These services encompass end-to-end protection for IoT devices, networks, and data, including threat detection, identity management, and secure data routing. Industrial and automotive enterprises are significant consumers, driven by stringent regulatory compliance and the critical nature of their operations.
- Device Management:This category covers the remote monitoring, configuration, and troubleshooting of connected devices throughout their lifecycle.
- Data Analytics:These services transform raw IoT data into actionable insights, supporting predictive maintenance and operational optimization.
- Network Provisioning:This involves setting up and maintaining the underlying network infrastructure required for IoT connectivity.
Connectivity Management holds installed capacity. Security Solutions is rotating up the share rankings.
Deployment Model:
The operational architecture chosen by clients significantly impacts service delivery and data handling.
- Edge Computing:This model processes data closer to the source of generation, reducing latency and bandwidth consumption for real-time applications. Industrial automation and connected vehicles represent strong demand for edge solutions due to their ultra-low latency requirements for critical functions.
- Public Cloud:Public cloud platforms offer scalable and flexible infrastructure for hosting IoT applications and data storage, accessible over the internet. Enterprises leverage public cloud for its cost-effectiveness and ease of deployment for non-critical IoT workloads.
- Private Cloud:Private cloud solutions provide dedicated infrastructure for enhanced security and compliance, typically within an organization's own data center.
- Hybrid Cloud:This model combines elements of both public and private clouds, allowing workloads to move between environments based on specific needs.
- On-Premises:On-premises deployments involve hosting all IoT infrastructure and applications within a company's physical location, offering maximum control.
Public cloud models offer scalability, while edge computing solutions address latency-sensitive industrial applications.
Use Case:
Specific IoT applications drive varied requirements for connectivity characteristics.
- Connected Vehicles:This segment includes telematics, infotainment, and C-V2X communication, requiring high-bandwidth, low-latency, and ultra-reliable connectivity. The automotive sector's push for autonomous driving and enhanced safety features creates a large-scale demand anchor in the United States and Germany.
- Industrial Automation:IoT telecom services enable real-time monitoring, control, and predictive maintenance in factories and industrial settings. Manufacturers in Germany and Japan require robust and secure connectivity for their operational technology environments.
- Smart Cities:This category encompasses applications like smart street lighting, waste management, and public safety, often requiring broad-area, low-power connectivity.
- Agriculture Monitoring:IoT solutions in agriculture involve tracking livestock, monitoring crop health, and managing irrigation systems in remote areas.
- Energy Management:This segment includes smart grids, utility metering, and remote monitoring of energy infrastructure.
Connected vehicles demonstrate significant demand for high-bandwidth services, while smart cities require broad-area low-power connectivity.
Client Type:
The primary customer base for IoT telecom services reflects diverse operational and strategic needs.
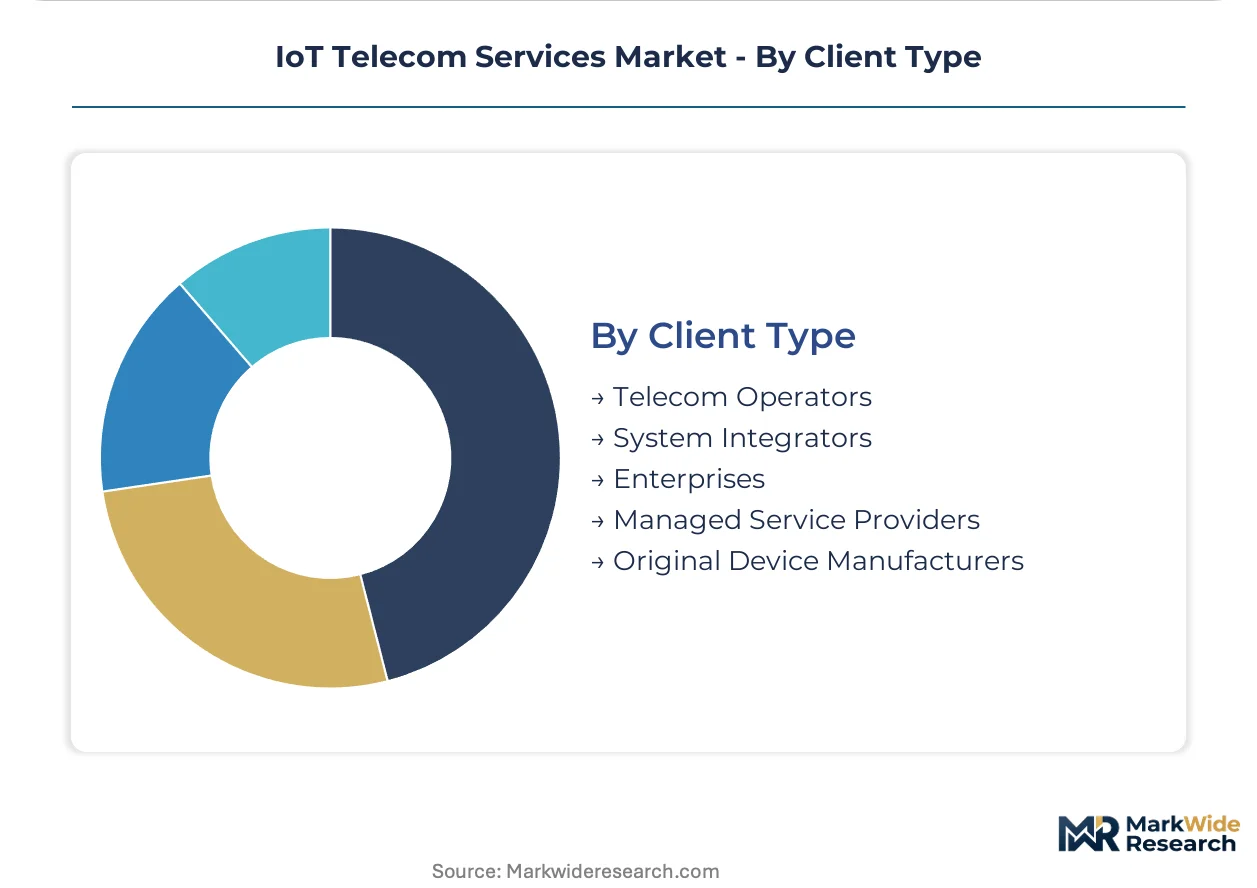
- Enterprises:Large businesses across various sectors, including manufacturing, logistics, and healthcare, adopt IoT telecom services for operational efficiency and digital transformation. These clients prioritize integrated solutions that include security, device management, and data analytics.
- Telecom Operators:These companies are both providers and consumers of IoT telecom services, leveraging their network infrastructure to offer connectivity and value-added services. Telecom operators often partner with other stakeholders to expand their IoT service portfolios.
- System Integrators:These firms specialize in combining different IoT components, including hardware, software, and connectivity, into a cohesive solution for end-clients.
- Managed Service Providers:MSPs deliver comprehensive IoT solutions, handling the entire lifecycle from deployment to ongoing management and support.
- Original Device Manufacturers:ODMs embed connectivity into their devices, often relying on telecom services for activation and management.
Enterprises seek bundled solutions for operational efficiency, and managed service providers enable end-to-end application deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The concentration of industrial and automotive enterprises significantly influences regional demand for IoT telecom services. These specialized connectivity services are crucial for advanced manufacturing, logistics, and smart mobility applications across key economic hubs. Government policies and regulatory frameworks also play a substantial role in shaping market development and technology adoption in various countries.
United States
Industrial and automotive enterprises drive substantial demand for IoT telecom services, particularly for connected vehicles and smart factory initiatives. The US FCC regulates spectrum allocation, facilitating the deployment of 5G networks for these high-bandwidth use cases. Major automotive manufacturing and technology development clusters in Detroit and Silicon Valley are at the forefront of adopting these services.
Germany
Demand for industrial automation and connected vehicle applications is strong in Germany, where manufacturers require ultra-reliable, low-latency connectivity. The GDPR imposes strict data handling requirements for IoT data, affecting service providers operating within the European Union. The industrial regions of Bavaria and North Rhine-Westphalia actively integrate IoT telecom services into their advanced manufacturing processes.
Japan
Industrial automation and smart city initiatives generate significant demand for IoT telecom services in Japan. METI promotes digital transformation across industries, encouraging the adoption of advanced connectivity solutions. Technology clusters in Tokyo and Nagoya are actively developing and deploying IoT applications for intelligent infrastructure and efficient manufacturing.
India
India's rapid industrialization and smart city programs present a vast market for IoT connectivity services, supported by government initiatives. The PLI scheme encourages domestic manufacturing, which in turn drives the need for connected operations. Major industrial and technology hubs like Maharashtra and Bengaluru are experiencing a surge in IoT deployments across various sectors.
France
Smart metering mandates and connected health applications are key demand drivers for IoT telecom services in France. The GDPR strongly influences data sovereignty requirements, compelling providers to offer localized data routing solutions. The Île-de-France region, with its strong tech and innovation ecosystem, is a significant adopter of advanced IoT connectivity for urban and industrial applications.
IoT Telecom Services Market Key Industry Players
Channel-controlling players compete with product-specialist players in the IoT telecom services market, creating a dynamic competitive environment. The market structure involves a mix of established telecom operators and specialized IoT connectivity providers. Key strategic archetypes include global network infrastructure providers, dedicated IoT connectivity management platforms, and end-to-end solution integrators. Strategic partnerships between technology vendors and telecom operators, alongside portfolio diversification into value-added services, are dominant competitive moves.
Within the global telecom operator tier, Verizon Communications exemplifies a focus on high-bandwidth 5G use cases, particularly within the United States. Huawei Technologies, a Shenzhen-based Co., Ltd., anchors the end-to-end hardware and software solutions segment, especially in developing economies. Deutsche Telekom AG, a major European player, occupies a position leveraging its extensive network infrastructure to support massive IoT deployments for industrial clients across Europe.
| Leading Market Players |
|---|
| Deutsche Telekom |
| Huawei Technologies |
| Vodafone Group |
| Nokia |
| Ericsson |
| AT&T |
| China Mobile |
| Orange S.A. |
| Verizon Communications |
| Others |
Cost & Logistics Intelligence
Global cellular module shipping lanes face cost dynamics directly influencing supply concentration from Asian manufacturers and downstream price differentiation for specialized IoT devices. These logistics costs feed back into the pricing models of connectivity providers, particularly for hardware-intensive deployments.
Pricing Analysis
Cost-plus contracts for specialized IoT telecom services often incorporate indexation to underlying network infrastructure costs. Subscription-based tiered pricing dominates for enterprise clients, offering different service level agreements based on reliability and security features. Pricing pressure stems from the commoditization of basic connectivity, especially for high-volume, low-value use cases. Industrial automation and connected vehicle segments exhibit lower price sensitivity, prioritizing ultra-reliability and low-latency, while consumer electronics and agricultural sensors remain highly price-sensitive.
Supply Chain Analysis
Geopolitical tensions affecting semiconductor supply chains, particularly between the United States and China, pose a significant risk to IoT telecom hardware availability. Component manufacturing for cellular modules and iSIMs concentrates heavily in East Asia, primarily in Taiwan, China, and South Korea. This creates dependencies on specialized semiconductor chips and radio frequency components. Single-source vulnerability for specific modem chipsets represents a structural risk. Distribution runs through a blend of direct sales to large enterprises and channel partnerships with system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
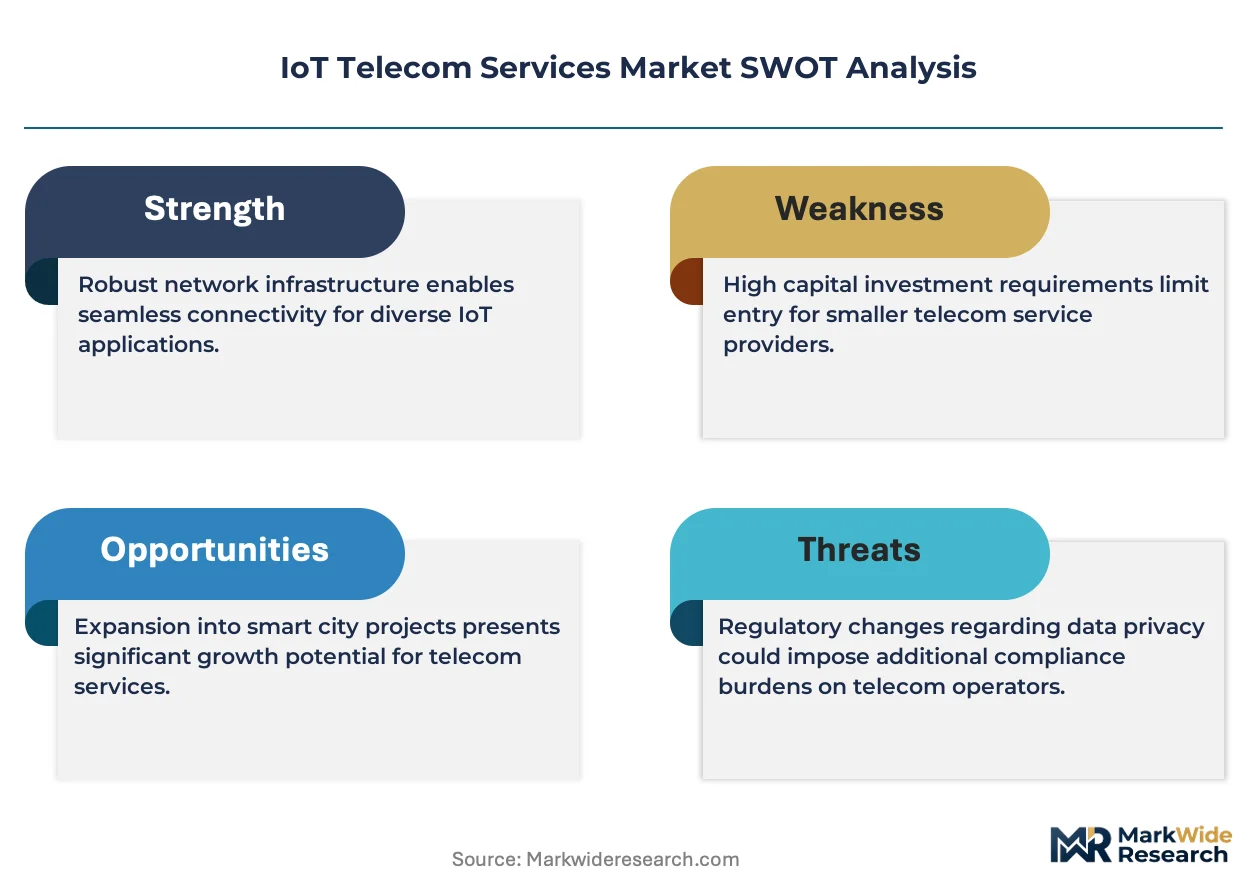
The IoT telecom services market necessitates a robust substitution defense, as incumbents must navigate the threat posed by lower-cost, alternative connectivity technologies like LoRaWAN for many basic IoT applications.
For Market Incumbents: Pre-empt commoditization of raw connectivity by aggressively expanding value-added services, particularly in security solutions and advanced data analytics. Deepen integration with edge computing platforms to offer ultra-low latency services for critical industrial applications. Invest in R&D for network slicing capabilities to meet diverse enterprise requirements, countering the threat from specialized IoT connectivity providers.
For New Entrants and Emerging Players: Build out highly specialized, application-aware network services tailored for specific industrial verticals like smart manufacturing or connected health. Target underpenetrated geographies such as India, leveraging government initiatives like the PLI scheme to foster adoption. Focus go-to-market strategies on partnerships with local system integrators to deliver comprehensive solutions for complex operational technology environments.
For Investors and Strategic Acquirers: Dedicated IoT connectivity management platforms specializing in secure data routing and device lifecycle management represent attractive acquisition targets for long-term portfolio growth. The market's shift towards bundled solutions for operational efficiency ensures sustained viability over the next decade. A signal to watch is the increasing consolidation of smaller connectivity management platform providers by major telecom operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Edge Computing Integration | This move enables ultra-low latency applications for connected vehicles and industrial automation. |
| Expand Private 5G Offerings | It addresses the specific security and reliability needs of factories and logistics centers. |
| Acquire Niche Security Provider | This strengthens end-to-end data protection capabilities for critical IoT deployments. |
| Invest in Non-Terrestrial Network (NTN) Partnerships | This extends service delivery to remote agriculture and maritime operations lacking terrestrial coverage. |
| Develop iSIM-enabled Solutions | This reduces component cost and power consumption for massive-scale device deployments across Europe. |
Research Approach
Initial hypotheses were tested against primary input from telecom executives, IoT solution architects, and enterprise IT/OT managers, refined through iterative feedback loops. Secondary validation drew from a diverse array of sources, including FCC filings, EU GDPR reports, ISO standards documents, and industry association publications. Both bottom-up and top-down triangulation methods were applied to ensure robust data integrity.
Demand-supply balance modeling formed the core analytical framework across the modeling period, integrating granular segmentation across service type, deployment model, and use case. Compound annual growth rates were derived from historical data analysis and projected future market dynamics. Key industry-specific forecast inputs included 5G infrastructure rollout schedules and connected vehicle production forecasts.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale cloud providers or disruptive connectivity startups would shift outcomes. Geopolitical disruptions to chip supply or unforeseen regulatory changes, such as spectrum allocation by the US FCC, pose specific risk factors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Telecom Service Assurance Market
Telecommunications
Global 5G in Healthcare Market
Telecommunications
Prepaid Communication Market
Telecommunications
Global Small Cell 5G Network Market
Telecommunications
Sri Lanka Telecom Market
Telecommunications
Cambodia Telecom Tower Market
Telecommunications
United States Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Nigeria Telecom Market
Telecommunications
Global 5G Base Station Market
Telecommunications
Philippines Telecom Market
Telecommunications
Global 5G Services Market
Telecommunications
IP Centrex Platforms Market
Telecommunications
Egypt Telecom Tower Market
Telecommunications
IP Telephony Market
Telecommunications
Voice Over Internet Protocol (Voip) Over WLAN (Vowlan) Market
Telecommunications
Software Defined Radio Market