
 Malaysia Telecom Towers Market | 2026-2036
Malaysia Telecom Towers Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Telecom Towers Market Insights
Managed services bundling is hardening into the core revenue model for tower companies, shifting transactions from pure steel-and-concrete leasing toward performance-based uptime contracts. EDOTCO Group Sdn Bhd leverages its ASEAN footprint to anchor multi-tenancy ratios above industry averages in Malaysian operations. Edge Point Towers SDN BHD competes through specialized urban infill solutions that sustain premium pricing in density-constrained Kuala Lumpur precincts.
Malaysia telecom towers are steel or composite structures engineered to heights between 30 and 120 meters, designed to host multiple antenna arrays, transmission equipment, and power systems while withstanding tropical wind loads exceeding 140 km/h; their primary purpose is to elevate wireless communication hardware above terrain and building clutter to ensure line-of-sight propagation for cellular and broadband networks. Lattice configurations dominate rural and highway corridors where structural efficiency at height offsets higher footprint requirements, while monopole designs capture urban deployment where aesthetic constraints and site scarcity compress available space. Stealth towers command margin pools in heritage-sensitive zones and high-income residential districts where local planning authorities impose strict visual impact thresholds.
The Malaysian Communications and Multimedia Commission enforces infrastructure sharing guidelines that compel mobile operators to co-locate on existing towers before greenfield construction, directly constraining standalone build rates and amplifying tenancy revenue per asset. The Communications and Multimedia Act 1998, administered by MCMC, establishes licensing frameworks that shape market access for foreign tower investors and domestic entrants alike. Stakeholders must monitor spectrum auction schedules and 5G standalone rollout commitments by Digital Nasional Berhad to calibrate capacity expansion timing against tenancy demand curves.
Market Dynamics
Malaysia's telecom tower sector is compressing toward shared infrastructure models as the Malaysian Communications and Multimedia Commission enforces co-location mandates that eliminate redundant steel construction and amplify tenancy stacking per asset.
Growth Catalysts
- 5G Standalone Deployment:Digital Nasional Berhad's nationwide 5G rollout requires dense small cell backhaul and macro tower densification across Peninsular Malaysia.
- MCMC Infrastructure Sharing Guidelines:The regulator's co-location-first policy diverts capital from greenfield builds toward tenancy expansion on existing assets.
- Klang Valley Data Center Cluster:Hyperscale cloud facilities in Cyberjaya and Shah Alam generate fiber-to-the-tower demand for low-latency edge connectivity.
Market Restraints
- Steel Price Volatility:Hot-rolled coil import costs from China fluctuate with regional trade policy, compressing margin on lattice tower fabrication.
- Site Acquisition Friction:State land offices in Selangor and Johor impose inconsistent lease renewal terms that extend deployment timelines.
- Grid Power Reliability:Tenaga Nasional Berhad's rural distribution network suffers voltage instability, forcing tower operators to over-specify diesel backup systems.
Strategic Opportunities
- East Malaysia Penetration:Sarawak and Sabah maintain sub-70% 4G coverage, creating first-mover tenancy pools for tower companies willing to navigate Borneo's terrain logistics.
- Solar-Diesel Hybrid Power:Malaysia's renewable energy feed-in tariff incentives enable capex recovery on photovoltaic backup systems for off-grid tower sites.
- Smart City Integration:Iskandar Malaysia's digital infrastructure masterplan embeds multi-utility poles that combine 5G antennas with traffic sensors and environmental monitors.
Industry Challenges
- RF Engineering Talent Scarcity:Malaysian universities produce insufficient antenna propagation specialists to support accelerated 5G deployment timelines.
- Heritage Zone Aesthetic Compliance:Local councils in George Town and Malacca enforce strict visual impact assessments that delay stealth tower approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Telecom Towers Market |
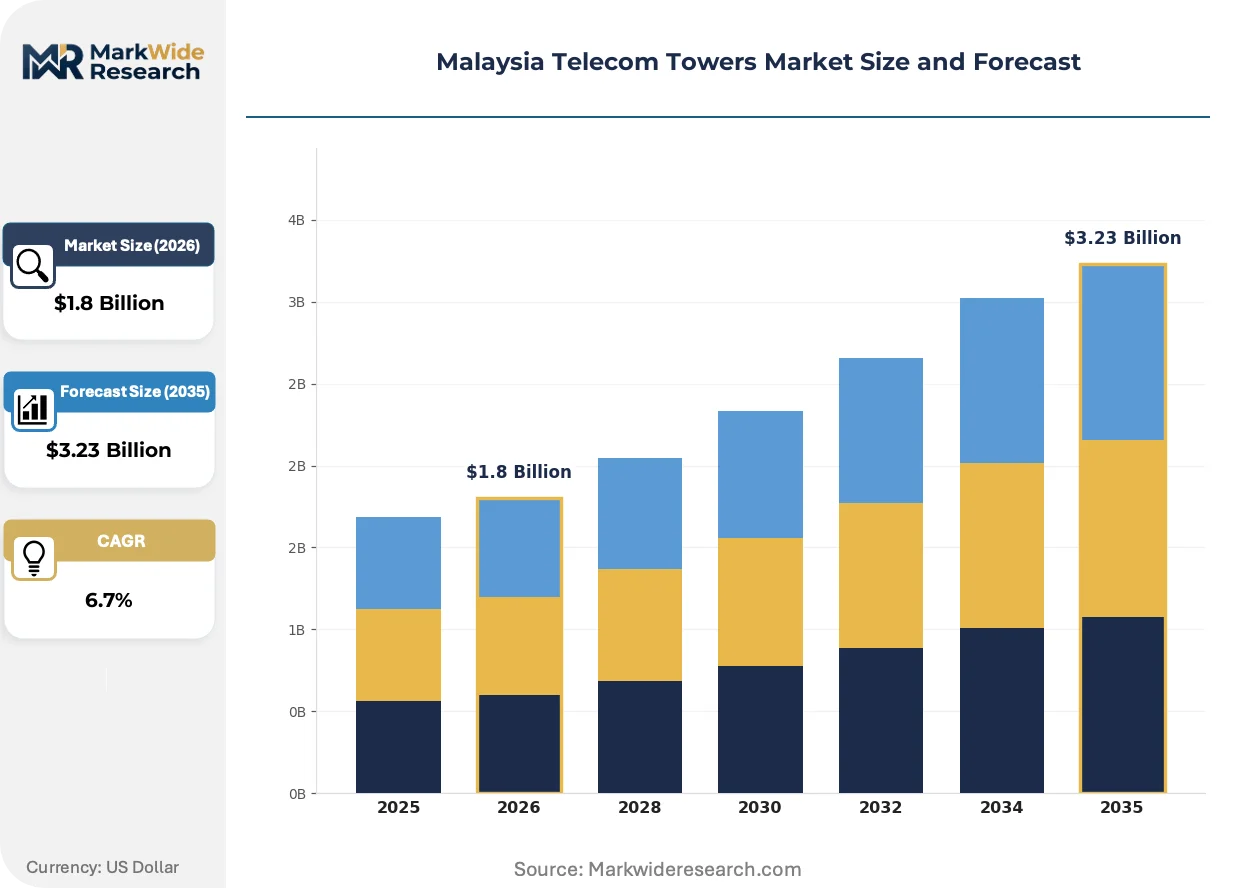
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monopole, Lattice, Stealth, Guyed End User: Mobile Operators, Internet Service Providers, Enterprises, Government Deployment: Urban, Suburban, Rural, Remote Solution: Infrastructure Leasing, Managed Services, Site Acquisition, Network Optimization |
| Companies Covered | EDOTCO Group Sdn Bhd, Edge Point Towers SDN BHD, Telekom Malaysia, OCK Group Berhad, OPCOM Holdings Berhad, Common Tower Technologies SDN, ITMAX System Berhad, Silver Ridge Holdings Bhd, PDC Telecommunications Services Sdn Bhd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Telecom Towers Market Trends and Innovations
Malaysian tower operators are converging on three structural shifts: steel-to-composite material transitions, regulatory compression of build timelines, and procurement migration toward performance-guaranteed service bundles.
Carbon fiber-reinforced polymer (CFRP) mast sections are consolidating market share in height-constrained urban deployments. EDOTCO and Edge Point deploy these materials in Kuala Lumpur's heritage precincts where weight limits and crane access restrictions rule out conventional lattice assembly. The technology is consolidating supplier relationships around Southeast Asian composite fabricators with tropical UV-stabilization expertise.
Malaysia's Communications and Multimedia Act 1998 amendments have tightened licensing scrutiny on foreign tower investors, requiring 30% Bumiputera equity participation for new market entrants. The industrial consequence is a partnership-heavy entry model where ASEAN tower companies anchor through domestic joint ventures. Peninsular Malaysia's Klang Valley corridor faces the steepest compliance burden as MCMC prioritizes infrastructure security reviews for assets near critical government facilities.
Mobile operators are abandoning capital-heavy tower ownership in favor of managed service agreements that transfer power, maintenance, and uptime liability to tower companies. CelcomDigi and Maxis have completed this transition in Peninsular Malaysia, with U Mobile following in Johor. The shift is most visible in Selangor's industrial zones where tenancy contracts now specify 99.95% availability SLAs with penalty clauses rather than traditional steel-and-concrete leases.
Malaysia Telecom Towers Market Segmentation
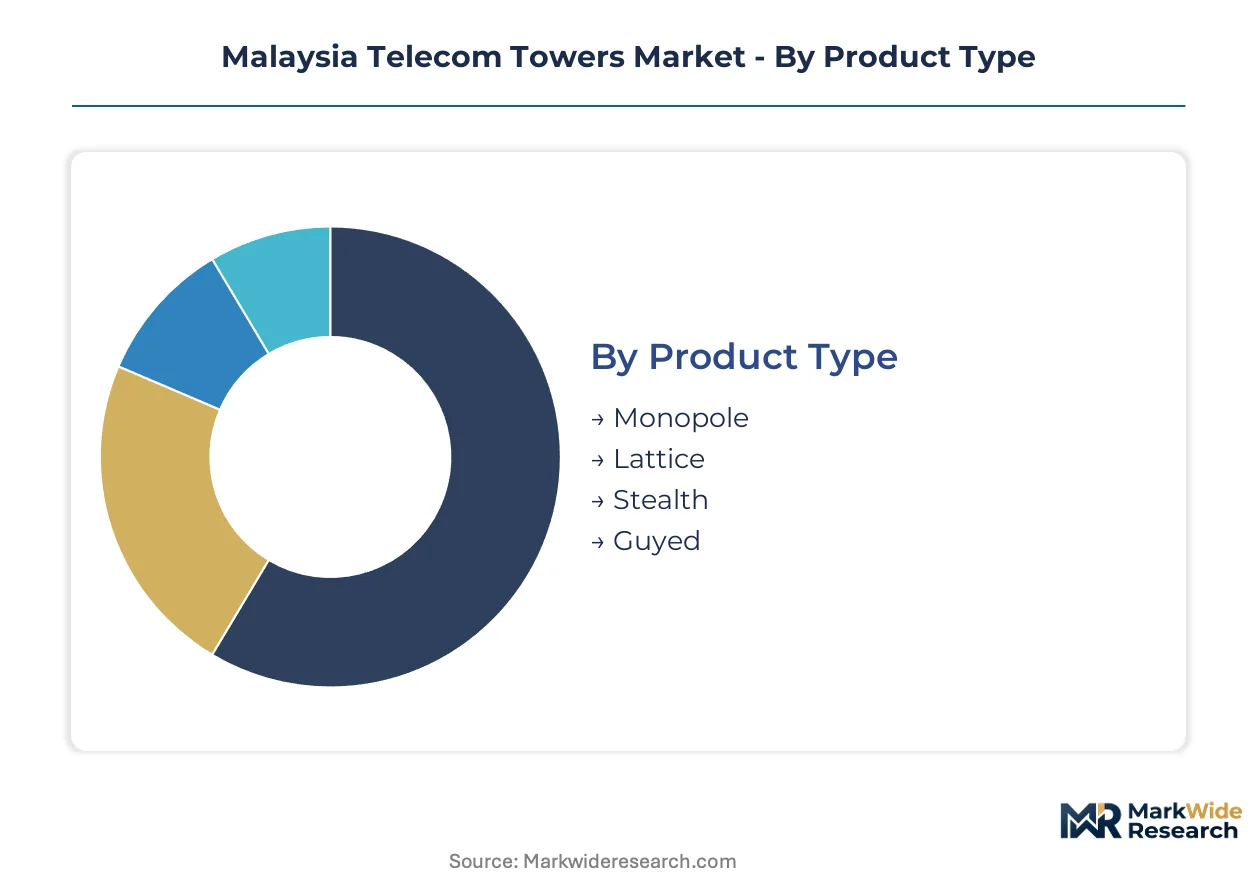
Malaysia's telecom tower segmentation reflects structural pressures from MCMC co-location mandates and Digital Nasional Berhad's 5G rollout. Product configurations, end-user contracting models, and deployment geographies each carry distinct regulatory compliance burdens and margin profiles.
Product Type:
MCMC structural safety certifications and local council aesthetic approvals create divergent compliance pathways across tower configurations. Lattice and monopole designs face the heaviest engineering scrutiny for tropical wind load ratings.
- Monopole:Single-shaft steel or composite structures engineered for 30-50 meter heights in density-constrained Kuala Lumpur precincts. Demand concentrates in heritage-sensitive zones where crane access restrictions and visual impact thresholds favor compact footprints over lattice alternatives.
- Lattice:Triangular or square truss configurations fabricated from hot-rolled steel sections, optimized for 60-120 meter rural and highway corridor deployments. Peninsular Malaysia's east-west highway network drives volume, with structural efficiency at height offsetting higher foundation requirements and land footprint.
- Stealth:Disguised structures mimicking palm trees, clock towers, or building elements to satisfy local planning authority aesthetic mandates in George Town and Malacca heritage districts.
- Guyed:Mast structures stabilized by tensioned cable arrays, deployed where guy wire anchor zones are geotechnically feasible and zoning permits extended land use.
Lattice sits at the top of the volume ranking, with monopole climbing the fastest.
End User:
Contracting sophistication varies sharply across customer categories, with tenancy stacking economics and SLA penalty structures defining procurement differentiation.
- Mobile Operators:CelcomDigi, Maxis, and U Mobile drive tenancy demand through performance-guaranteed managed service agreements. The shift from capital-heavy tower ownership to 99.95% uptime SLAs with penalty clauses is most visible in Selangor's industrial zones.
- Internet Service Providers:Fixed wireless access providers and fiber backhaul operators lease tower space for point-to-point microwave links. Cyberjaya and Shah Alam data center clusters generate concentrated fiber-to-the-tower demand for low-latency edge connectivity.
- Enterprises:Private network operators in Iskandar Malaysia's special economic zones contract dedicated tower segments for industrial IoT and campus connectivity.
- Government:Digital Nasional Berhad's 5G infrastructure procurement and state-level rural connectivity programs impose Bumiputera equity participation requirements on tower vendors.
Mobile operators command the dominant revenue share, while government contracts are expanding most quickly.
Deployment:
Site acquisition friction and grid reliability constraints create tiered cost structures across Malaysia's settlement hierarchy, with rural economics forcing diesel-heavy power specifications.
- Urban:Kuala Lumpur and Johor Bahru metropolitan clusters face the steepest site scarcity premiums. Stealth tower deployments and monopole infill solutions sustain premium pricing where heritage zoning and building clutter restrict greenfield construction.
- Suburban:Selangor and Johor's peri-urban corridors balance co-location density with available land parcels. Tenancy stacking approaches industry averages as MCMC infrastructure sharing guidelines compress redundant build timelines.
- Rural:Peninsular Malaysia's agricultural heartlands and East Malaysia's coastal settlements suffer Tenaga Nasional Berhad voltage instability, forcing tower operators to over-specify diesel backup systems and solar-diesel hybrid configurations.
- Remote:Sarawak and Sabah's interior terrain presents first-mover tenancy pools for operators navigating Borneo's logistics constraints, with sub-70% 4G coverage creating infrastructure gaps.
Urban deployments generate the highest tenancy revenue per asset, with remote sites showing the steepest expansion trajectory.
Solution:
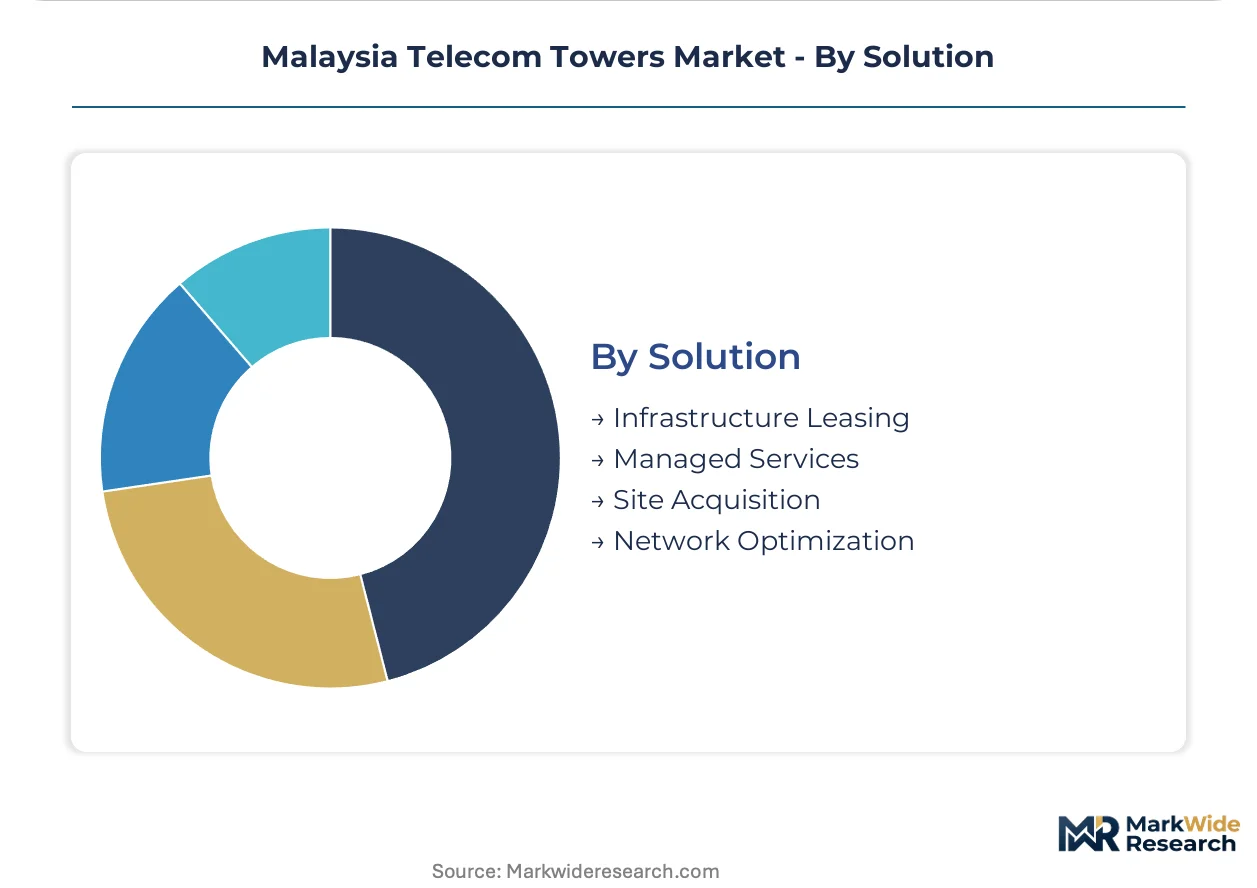
Service bundling intensity determines customer stickiness, with pure leasing giving way to outcome-based contracts that transfer operational liability.
- Infrastructure Leasing:Traditional steel-and-concrete tenancy agreements with per-antenna rental structures. Pure leasing persists in mature Peninsular Malaysia markets where operators retain in-house maintenance capabilities.
- Managed Services:Performance-based contracts bundling power, maintenance, and uptime liability. CelcomDigi and Maxis have completed this transition, with contracts specifying availability SLAs rather than asset rental.
- Site Acquisition:Turnkey land procurement and permitting services, critical in Selangor and Johor where state land offices impose inconsistent lease renewal terms.
- Network Optimization:RF engineering and capacity planning services addressing talent scarcity in Malaysian antenna propagation specialist pipelines.
Managed services dominate new contract value, with network optimization gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's tower density contrasts sharply with Indonesia's archipelago complexity, where maritime logistics fragment deployment economics. Peninsular Malaysia's concentrated population corridors enable co-location stacking that East Malaysian states struggle to replicate across Borneo's terrain.
Selangor
Digital Nasional Berhad's 5G procurement concentrates tower demand in Cyberjaya and Shah Alam data center clusters. The Malaysian Communications and Multimedia Commission enforces infrastructure sharing guidelines that compress redundant builds in this corridor. Klang Valley's site scarcity premiums sustain stealth tower deployments where heritage zoning restricts conventional structures.
Johor
Iskandar Malaysia's smart city masterplan embeds multi-utility poles combining 5G antennas with traffic sensors. State land offices impose inconsistent lease renewal terms that extend deployment timelines for greenfield sites. Johor Bahru metropolitan cluster attracts edge computing facilities requiring fiber-to-the-tower backhaul for low-latency connectivity.
Sarawak
Sub-70% 4G coverage creates first-mover tenancy pools for operators navigating Borneo's interior terrain logistics. The state's renewable energy feed-in tariff incentives enable capex recovery on photovoltaic backup systems for off-grid tower sites. Coastal settlements from Kuching to Miri suffer Tenaga Nasional Berhad voltage instability, forcing diesel-heavy power specifications.
Sabah
Mount Kinabalu's elevation corridors and dense rainforest canopy complicate line-of-sight propagation for cellular networks. Federal rural connectivity programs impose Bumiputera equity participation requirements on tower vendors seeking government contracts. Sandakan and Tawau municipal clusters present concentrated demand pockets amid otherwise dispersed settlement patterns.
Penang
George Town's UNESCO heritage status triggers strict visual impact assessments that delay stealth tower approvals. Local planning authorities enforce aesthetic mandates favoring disguised structures mimicking palm trees or building elements. Bayan Lepas industrial zone generates enterprise tenancy demand for private network tower segments serving manufacturing IoT applications.
Malaysia Telecom Towers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated tower operators commanding tenancy stacking advantages over pure fabrication plays. The vendor base organizes around three strategic archetypes: ASEAN-footprint regional platforms, domestic joint-venture specialists, and state-linked infrastructure incumbents. Market consolidation proceeds through Bumiputera equity partnerships rather than outright acquisition. Competitive intensity centers on managed service bundling and uptime guarantee differentiation.
Among Malaysia-based operators, EDOTCO Group Sdn Bhd and Edge Point Towers SDN BHD occupy positions within the integrated platform tier, while OCK Group Berhad exemplifies the domestic specialist archetype navigating MCMC licensing requirements. These entities represent contrasting responses to the Communications and Multimedia Act 1998's foreign investment constraints, with some anchoring through joint ventures and others leveraging established tenancy relationships. Their collective positioning illustrates how regulatory compression of build timelines favors operators with in-house site acquisition capabilities and existing asset portfolios.
| Leading Market Players |
|---|
| EDOTCO Group Sdn Bhd |
| Edge Point Towers SDN BHD |
| Telekom Malaysia |
| OCK Group Berhad |
| OPCOM Holdings Berhad |
| Common Tower Technologies SDN |
| ITMAX System Berhad |
| Silver Ridge Holdings Bhd |
| PDC Telecommunications Services Sdn Bhd |
| Others |
Pricing and Supply Chain Analysis
RF engineering talent scarcity in Peninsular Malaysia widens pricing spreads between premium managed-service contracts and commodity tenancy agreements, as tower operators absorb specialist labor premiums into performance-guaranteed SLAs while passing steel-input volatility through to baseline leases.
Pricing Analysis
Capacity additions in Johor and Selangor are reshaping price floors for lattice tower fabrication as domestic steel rolling mills expand hot-rolled coil processing. Three-tier pricing structure separates uptime-guaranteed managed services from standard co-location leases and bare-metal infrastructure rentals. Price differentiation rests on MCMC certification tier and after-sales service bundling intensity. Cost compression in standard tenancy tiers is intensifying because mobile operators consolidate procurement through framework agreements. Government contracts show lowest price sensitivity due to Bumiputera equity mandates; pure-play ISPs exhibit highest sensitivity to per-antenna rental rates.
Supply Chain Analysis
Refurbishment flows for diesel generator sets and battery backup systems circulate from Peninsular Malaysia's decommissioned 3G sites toward East Malaysia's rural deployment programs. Primary steel sourcing draws from China, South Korea, and domestic hot-rolled coil processors. Carbon fiber-reinforced polymer mast sections feed from Southeast Asian composite fabricators with tropical UV-stabilization expertise. Single-source vulnerability concentrates in specialized antenna propagation equipment where Malaysian universities produce insufficient RF engineering specialists. Distribution runs through EDOTCO's ASEAN regional platform and domestic joint-venture specialists with in-house site acquisition capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's telecom tower market functions as a geographic-arbitrage play between Peninsular Malaysia's co-location-saturated corridors and East Malaysia's infrastructure-deficient terrain, where regulatory compliance costs in Selangor exceed site acquisition premiums in Sarawak by substantial margins.
For Market Incumbents: Anchor tenancy stacking advantages through exclusive managed-service agreements with Digital Nasional Berhad's 5G rollout, while backward integration into solar-diesel hybrid power systems defends margin position against Tenaga Nasional Berhad's rural voltage instability. CelcomDigi and Maxis procurement consolidation threatens pricing power; counter through site acquisition capabilities that compress MCMC-mandated co-location timelines. For New Entrants and Emerging Players: State land offices in Sabah and Sarawak present partnership pathways for tower operators willing to navigate Borneo's logistics constraints. First-mover tenancy pools in sub-70% 4G coverage zones offer the most penetrable geographic white space. Joint venture structures with Bumiputera equity partners satisfy Communications and Multimedia Act licensing requirements while accessing federal rural connectivity program contracts. For Investors and Strategic Acquirers: ASEAN regional tower platforms are the most active acquirer in this space, seeking domestic joint-venture anchors to satisfy foreign investment constraints. Long-term viability hinges on managed-service contract duration rather than steel-and-concrete asset ownership. Acquisition target archetype: domestic specialists with in-house RF engineering capabilities and established site acquisition relationships. Watch Digital Nasional Berhad's spectrum auction schedules as the inflection indicator for capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Solar-Diesel Hybrid Power Deployment | Malaysia's renewable energy feed-in tariff enables capex recovery on photovoltaic backup systems for off-grid sites. |
| Managed Services Transition | CelcomDigi and Maxis shift from capital-heavy ownership to 99.95% uptime SLAs with penalty clauses. |
| Bumiputera Joint Venture Formation | Communications and Multimedia Act amendments require 30% domestic equity participation for foreign entrants. |
| East Malaysia Geographic Expansion | Sarawak and Sabah's sub-70% 4G coverage creates first-mover tenancy pools for logistics-capable operators. |
| Carbon Fiber Mast Adoption | CFRP sections consolidate supplier relationships around Southeast Asian fabricators with tropical UV expertise. |
Research Methodology
Direct dialogue with tower company operations directors, MCMC regulatory affairs officers, mobile operator network procurement managers, and Tenaga Nasional Berhad rural electrification planners grounded qualitative findings. Secondary validation drew from MCMC infrastructure sharing guidelines, Digital Nasional Berhad 5G rollout disclosures, Communications and Multimedia Act amendments, and Bursa Malaysia tower company filings. Bottom-up tenancy revenue modeling triangulated against top-down addressable market sizing across the analysis window.
Bottom-up segment modeling tracked tower configuration mix, deployment geography, and solution bundling intensity against tenancy stacking economics. Segmentation dimensions spanned product type, end-user contracting sophistication, deployment settlement tier, and service solution category. CAGRs derived from regression against historical build rates, co-location mandate compliance trajectories, and Digital Nasional Berhad capacity procurement schedules. Forecast inputs incorporated steel price volatility indices and MCMC enforcement intensity proxies.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to spectrum auction timing, Bumiputera equity policy shifts, and Tenaga Nasional Berhad rural grid stabilization investments. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global Telecom Operations Management Market
Telecommunications
LTE Advanced Pro Market
Telecommunications
Video Door Phones Market
Telecommunications
North America Underwater Communication Systems Market
Telecommunications
Ireland Telecom Market
Telecommunications
Global SS7 Market
Telecommunications
Australia Telecom Market
Telecommunications
IoT Telecom Services Market
Telecommunications
IP Telephony Market
Telecommunications
IoT MVNO (Services) Market
Telecommunications
Australia Telecom Tower Market
Telecommunications
Kuwait Telecom Market
Telecommunications
Satcom Terminal Market
Telecommunications
LTE and LTE Advance Market
Telecommunications
Optical Network Terminal (ONT) Equipment Market
Telecommunications
Myanmar Telecom Market