
 IoT MVNO (Services) Market | 2026-2036
IoT MVNO (Services) Market Size, Share, and Industry Trends Forecast 2026-2036
IoT MVNO (Services) Market Foresight
A capital-intensity divergence between network-owning MNOs and asset-light MVNOs is reorganizing competitive dynamics in IoT connectivity. KORE leverages its managed services portfolio to serve enterprise clients across multiple geographies without spectrum ownership. emnify sustains a cloud-native core network architecture that reduces infrastructure overhead compared to traditional carrier models. floLIVE anchors its position through distributed core networks that localize data processing for regional compliance requirements.
IoT MVNO services encompass third-party cellular connectivity provision where virtual operators lease wholesale network capacity from MNOs and repackage it with value-added management layers for device fleets, typically operating over standardized 3GPP radio interfaces with subscription management via embedded SIM or eSIM orchestration. The primary commercial purpose centers on decoupling IoT device connectivity from single-carrier lock-in while centralizing billing, monitoring, and lifecycle management through unified platforms. Connectivity services and platform services command the deepest margin pools as enterprises prioritize operational visibility over raw bandwidth, while NB-IoT and LPWAN technology segments attract specialized positioning as utilities and agriculture deploy low-throughput, long-battery sensor networks at scale.
FCC spectrum auctions and the EU's GDPR data-localization mandates shape how IoT MVNOs architect their core network footprints and subscriber data handling across jurisdictions. ETSI standards for M2M communications and the GSMA's eSIM specifications further constrain interoperability approaches and device onboarding workflows. Stakeholders must monitor evolving national spectrum allocation policies and cross-border data governance to calibrate network expansion investments against compliance exposure.
Market Dynamics
The FCC's spectrum auction frameworks and the EU's GDPR data-localization mandates are forcing IoT MVNOs to re-architect core network footprints and subscriber data handling across multiple jurisdictions simultaneously.
Growth Catalysts
- Industrial automation clusters in Germany:Carrier-grade connectivity requirements from manufacturing hubs are pulling dedicated IoT MVNO infrastructure investments into Central Europe.
- eSIM orchestration standards:GSMA specifications for embedded SIM management are decoupling device connectivity from single-carrier lock-in and accelerating enterprise fleet deployments.
- NB-IoT network densification:Low-throughput sensor networks for utilities and agriculture are expanding addressable device populations beyond traditional broadband IoT applications.
Market Restraints
- Licensed spectrum access costs:FCC auction pricing for cellular bands in the United States compresses margins for virtual operators lacking MNO-scale balance sheets.
- MNO wholesale dependency:Concentrated control of radio access networks by incumbent carriers in Germany and the United States limits MVNO negotiating leverage on capacity pricing.
- LPWAN substitution threat:Unlicensed LoRa and Sigfox networks for low-data applications erode addressable market for cellular-based IoT connectivity in agricultural monitoring segments.
Strategic Opportunities
- Regional compliance localization:Distributed core networks that process data within national borders address GDPR requirements across EU member states.
- Connected fleet telemetry:Automotive OEMs are consolidating multi-country vehicle connectivity under single MVNO management platforms.
- Cloud-native core convergence:Containerized network functions combined with eSIM provisioning APIs reduce infrastructure overhead versus legacy carrier models.
Industry Challenges
- Multi-jurisdiction certification timelines:Device type approval processes across FCC, CE marking, and national telecom regulators delay market entry for cross-border IoT deployments.
- Legacy M2M system integration:Enterprises with embedded 2G/3G device fleets face complex migration paths to NB-IoT and LTE-M architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT MVNO (Services) Market |
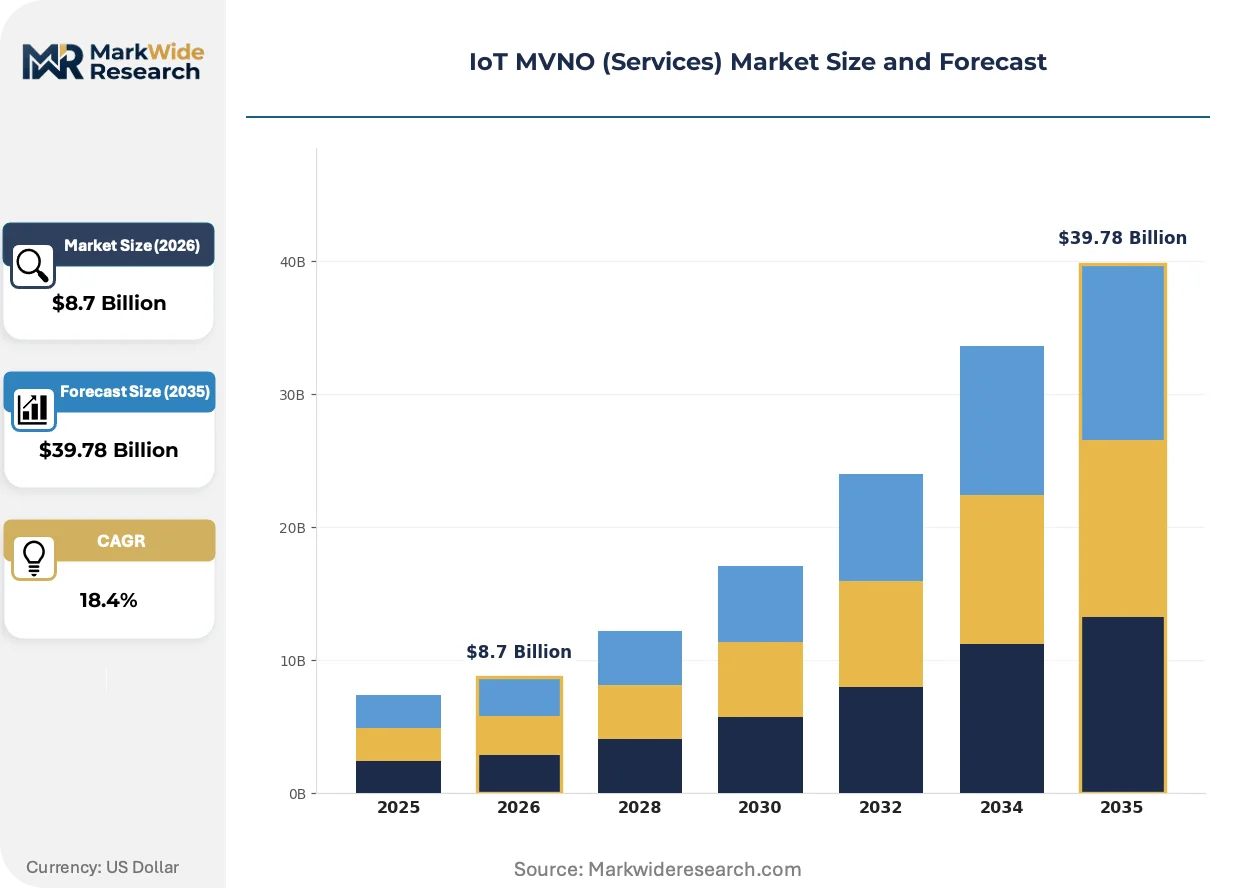
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Plans, Connectivity Services, Device Management, Platform Services End User: Smart Cities, Agriculture, Healthcare, Automotive Technology: LTE, NB-IoT, 5G, LPWAN Deployment Model: Private Network, Public Network, Hybrid Model, Cloud-Based |
| Companies Covered | Velos IoT, Eseye, Plintron, KORE, floLIVE, Transatel, emnify, 1NCE, Telna, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT MVNO (Services) Market Shifts & Advancements
eSIM provisioning platforms are decoupling hardware manufacturing from carrier selection, enabling enterprises to switch connectivity providers post-deployment without physical device intervention.
Cloud-native mobile core software is fragmenting the traditional vendor landscape for IoT connectivity infrastructure. Containerized packet core deployments allow MVNOs to spin up network functions in regional data centers within weeks rather than months. Agricultural equipment manufacturers and utility operators are adopting these architectures to localize data processing for compliance while reducing dependency on single-vendor hardware stacks.
The EU's GDPR and the FCC's evolving spectrum management frameworks are reshaping how IoT MVNOs architect data residency and licensed band access. GDPR's data-localization mandates require subscriber information processing within EU jurisdictional boundaries, forcing network footprint expansion. US-based fleet operators are responding by demanding contractual guarantees on data sovereignty from their connectivity providers.
Enterprise procurement of IoT connectivity is consolidating under multi-year managed service contracts with unified billing and lifecycle management platforms. Device fleet operators in automotive and industrial automation are displacing transactional SIM purchasing with subscription-based models that bundle monitoring, security patches, and carrier switching rights. Germany's manufacturing clusters exhibit the most advanced adoption of these procurement structures.
IoT MVNO (Services) Market Segmentation
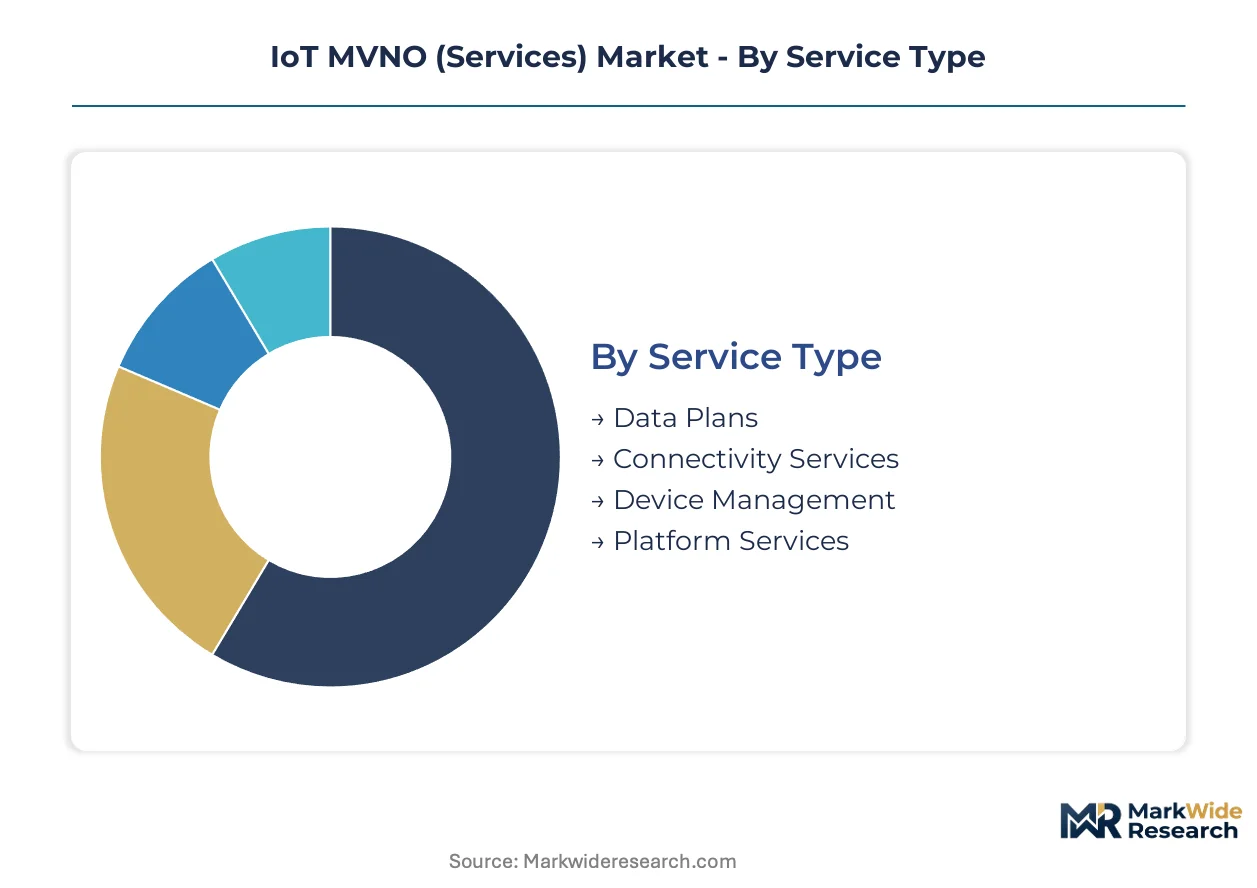
IoT MVNO service segmentation reveals how virtual operators calibrate margin capture against infrastructure investment. Service type and deployment model choices determine whether providers compete on connectivity commoditization or platform value-add.
Service Type:
Platform services face intensifying substitution pressure from hyperscaler cloud offerings, while raw connectivity confronts MNO direct-selling campaigns.
- Platform Services:Unified lifecycle management portals bundle billing, monitoring, and eSIM orchestration into subscription contracts. German industrial automation clusters prioritize these integrated suites over point connectivity solutions.
- Connectivity Services:Wholesale capacity repackaging with SLA guarantees and multi-carrier redundancy. Fleet operators in automotive consolidate multi-country vehicle telemetry under single MVNO management platforms to simplify procurement.
- Data Plans:Tiered volume commitments with overage structures for variable-throughput device fleets.
- Device Management:Firmware distribution, security patching, and remote diagnostic tools for distributed sensor populations.
Platform services retain volume leadership; connectivity services hold the steepest expansion curve as enterprise procurement consolidates under managed service contracts.
End User:
Cost tier stratification separates high-ARPU automotive deployments from price-sensitive agricultural monitoring networks.
- Automotive:Connected vehicle fleets demand carrier-grade latency and seamless cross-border handoff. OEM procurement teams negotiate multi-year MVNO contracts covering telemetry, infotainment, and over-the-air update pipelines.
- Smart Cities:Municipal infrastructure deployments span traffic sensors, environmental monitors, and public safety networks. GDPR data-localization mandates in EU member states force core network localization for these government contracts.
- Healthcare:Remote patient monitoring and medical device connectivity with HIPAA compliance requirements in the United States.
- Agriculture:Low-throughput soil moisture and livestock tracking sensors compete against unlicensed LoRa alternatives.
Automotive commands premium pricing tiers; agriculture faces the most acute margin compression from LPWAN substitution.
Technology:
Maturity gradients separate established LTE deployments from nascent 5G network slicing opportunities.
- NB-IoT:Narrowband specification optimized for stationary sensors with decade-long battery requirements. Utility operators deploy these modules for smart metering at scale across FCC-regulated US markets.
- 5G:Network slicing capabilities enable guaranteed latency tiers for industrial automation and autonomous vehicle telemetry. Manufacturing hubs in Germany drive early adoption of these premium connectivity tiers.
- LTE:Broadband IoT workhorse for mobile assets requiring higher throughput than narrowband alternatives.
- LPWAN:Unlicensed spectrum protocols including LoRa and Sigfox compete directly with cellular MVNO offerings in agricultural segments.
NB-IoT sustains deployment volume leadership; 5G network slicing gains share fastest among premium industrial applications.
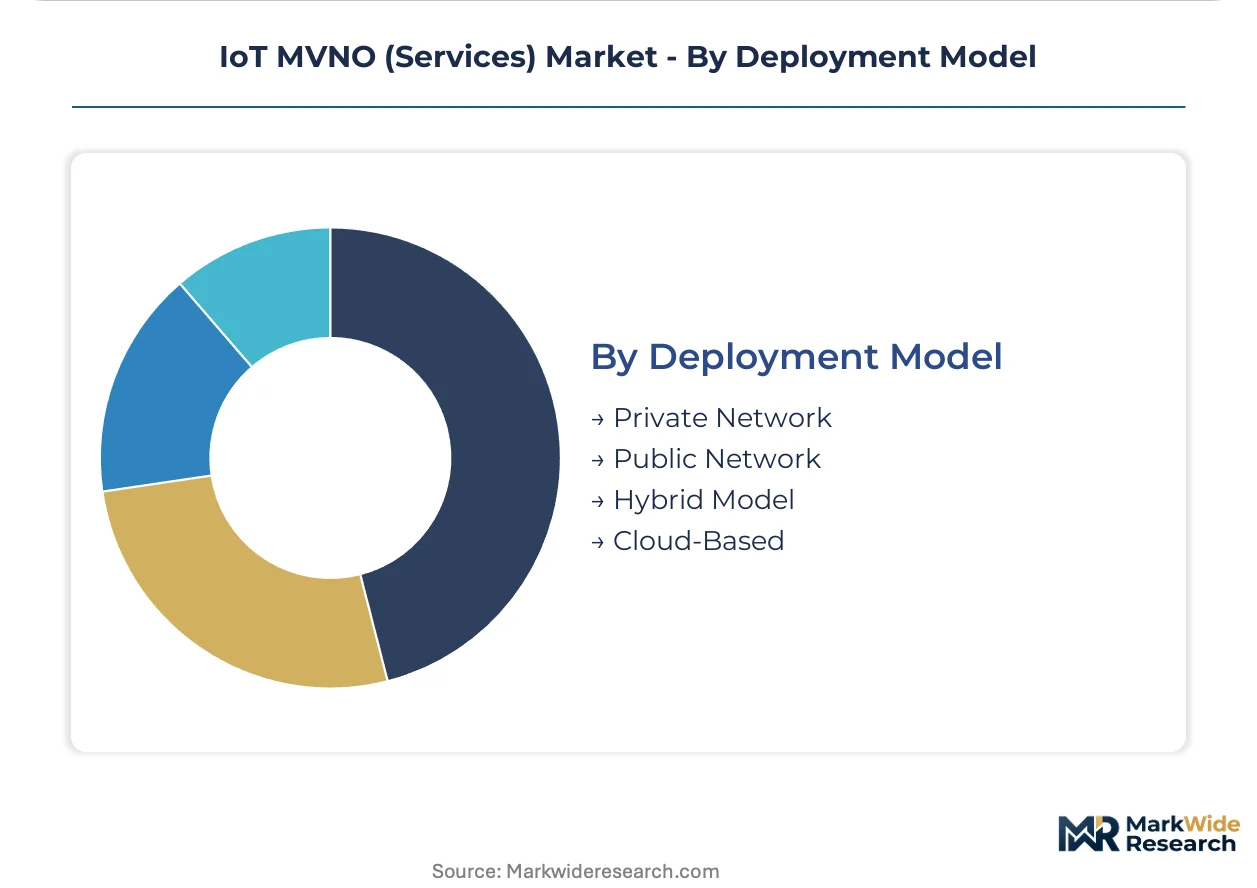
Deployment Model:
Supply concentration in cloud infrastructure shapes how MVNOs architect core network footprints across jurisdictions.
- Cloud-Based:Containerized packet core functions deployed across regional data centers enable rapid GDPR-compliant localization. emnify and floLIVE leverage this architecture to reduce infrastructure overhead versus legacy carrier models.
- Hybrid Model:Split processing between cloud orchestration and on-premises gateways for sensitive industrial data. German manufacturing clusters favor this approach to satisfy both performance and compliance requirements.
- Public Network:Shared MNO infrastructure with wholesale capacity agreements.
- Private Network:Dedicated spectrum allocations and localized base stations for campus-scale deployments.
Cloud-based deployment retains implementation volume leadership; hybrid models are climbing fastest as compliance localization requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's industrial automation corridors while US fleet operators face margin compression from FCC spectrum auction costs. This asymmetry reshapes where MVNOs deploy capital-intensive core network infrastructure versus asset-light orchestration platforms.
United States
Connected vehicle OEMs and utility operators drive carrier-grade connectivity procurement across FCC-regulated markets. The FCC's spectrum auction frameworks inflate licensed band access costs for virtual operators lacking MNO-scale balance sheets. Fleet telemetry deployments concentrate in Michigan's automotive manufacturing belt and California's technology corridors.
Germany
Industrial automation clusters in Bavaria and Baden-Württemberg generate sustained demand for low-latency machine-to-machine connectivity. GDPR data-localization mandates force MVNOs to localize subscriber data processing within national borders. Manufacturing hubs around Stuttgart and Munich anchor premium 5G network slicing adoption for factory automation.
United Kingdom
Smart city infrastructure deployments across Greater London and Manchester municipal networks require GDPR-compliant data residency architectures. The country's national telecom regulator shapes device type approval timelines for cross-border IoT deployments. Fleet operators in the Midlands logistics corridor consolidate multi-country connectivity under unified management platforms.
Japan
Automotive OEMs and precision manufacturing facilities in the Chubu and Kansai regions demand seamless cross-border handoff capabilities. METI industrial policy frameworks influence spectrum allocation for private 5G campus deployments. Manufacturing clusters around Nagoya and Osaka drive early adoption of containerized network core functions.
France
Healthcare remote monitoring and agricultural sensor networks expand addressable device populations in rural and metropolitan zones. CNIL data protection requirements complement GDPR mandates for subscriber information handling. The Île-de-France region hosts concentrated demand from public sector smart city initiatives and enterprise fleet management.
IoT MVNO (Services) Market Competitive Landscape
Concentration sits with cloud-native specialists that have decoupled infrastructure ownership from service delivery. The market structure fragments across three tiers: network-owning MNOs with captive wholesale operations, asset-light MVNOs with platform value-add, and hyperscalers encroaching on orchestration software. Strategic archetypes include distributed core architects, managed service bundlers, and eSIM provisioning specialists. Competitive moves center on regional data center expansion for compliance localization and multi-year managed service contract consolidation.
Within the cloud-native tier, emnify and floLIVE exemplify distributed core architectures that reduce infrastructure overhead versus legacy carrier models. KORE occupies a position among managed service bundlers serving enterprise clients across multiple geographies without spectrum ownership. These three companies represent divergent approaches to the capital-intensity divergence between network ownership and asset-light service delivery.
| Leading Market Players |
|---|
| Velos IoT |
| Eseye |
| Plintron |
| KORE |
| floLIVE |
| Transatel |
| emnify |
| 1NCE |
| Telna |
| Others |
Supply & Pricing Matrix
Cloud-native core infrastructure substitution for legacy carrier hardware simultaneously redistributes supply geography toward software development hubs and compresses pricing economics for connectivity services. German industrial automation clusters absorb premium pricing for GDPR-compliant localized processing, while US fleet operators face margin pressure from FCC spectrum auction costs.
Pricing Analysis
The customization-premium spread separates configured-to-order private network deployments from standard public connectivity tiers. Subscription-based managed service contracts dominate enterprise procurement, with price differentiation driven by latency-grade certification and cross-border redundancy guarantees. Pricing pressure stems from MNO wholesale capacity concentration in Germany and the United States, compressing MVNO margins. Agricultural sensor networks exhibit acute price sensitivity against unlicensed LoRa alternatives, while automotive OEMs accept premium tiers for seamless multi-country handoff capabilities.
Supply Chain Analysis
MNO wholesale agreements function as a chokepoint where concentrated radio access network ownership in Germany and the United States constrains MVNO negotiating leverage. Supply geography centers on cloud infrastructure regions in Ireland, Frankfurt, and Northern Virginia, with hardware dependencies spanning baseband processors from Taiwan, radio units from South Korea, and core network software from Israel and the United States. Single-source vulnerability in eSIM provisioning platforms elevates supply chain risk. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection arrives through eSIM orchestration decoupling hardware manufacturing from carrier selection, enabling post-deployment provider switching that restructures ecosystem lock-in dynamics.
For Market Incumbents: Fortify regional data center footprints to satisfy GDPR data-localization mandates across EU member states. Deepen backward integration into cloud-native core software development to reduce dependency on third-party network function vendors. Cloud hyperscaler encroachment on orchestration software represents the primary threat to platform service margins.
For New Entrants and Emerging Players: Lead with compliance-first positioning in France and the United Kingdom where CNIL and national telecom regulator requirements create certification barriers for established US-centric providers. Agricultural sensor networks in France present the most penetrable segment given incumbent neglect of low-ARPU deployments. Go-to-market execution should emphasize LoRa-to-cellular migration consulting bundled with connectivity contracts.
For Investors and Strategic Acquirers: Capital is best deployed toward distributed core architects with proven multi-jurisdiction deployment velocity rather than pure-play connectivity resellers. Long-term viability hinges on software-defined infrastructure ownership that transcends MNO wholesale dependency. Watch FCC spectrum auction pricing trajectories as the signal for MVNO margin compression severity.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Core Network Expansion | GDPR-compliant data residency in Frankfurt and Dublin secures German manufacturing contracts. |
| eSIM Platform Integration | GSMA-compliant orchestration APIs enable post-deployment carrier switching for enterprise fleets. |
| Cloud-Native Architecture Migration | Containerized packet core functions reduce infrastructure overhead versus legacy carrier models. |
| Strategic Partnership with MNOs | Wholesale capacity agreements with Deutsche Telekom and Verizon anchor multi-carrier redundancy. |
| Acquisition of Device Management Specialist | Firmware distribution capabilities differentiate platform services from commodity connectivity. |
Research Methodology
Operator-level perspectives from IoT platform engineers, enterprise fleet procurement managers, MNO wholesale contract leads, and eSIM provisioning specialists anchored the qualitative base. Primary interview insights combined with secondary validation from FCC spectrum auction records, GSMA eSIM specification documents, ETSI M2M standards filings, and hyperscaler infrastructure capex disclosures. Bottom-up device deployment estimates triangulated against top-down connectivity revenue projections.
Sensitivity analysis tested forecast robustness across alternative MNO wholesale pricing scenarios and LPWAN substitution rates. The analytical framework modeled segmentation dimensions spanning service type, deployment model, end-use vertical, and technology protocol across the analysis window. CAGRs derived from installed base growth curves and ARPU compression trajectories. Industry-specific inputs included connected vehicle production forecasts from IHS Markit and smart meter deployment pipelines from utility regulatory filings.
Underlying assumptions cover sustained FCC spectrum auction participation, stable GSMA eSIM specification adoption, and GDPR enforcement continuity, with deviation risk concentrated in unlicensed LPWAN technology cost curves and MNO wholesale pricing renegotiations. Practitioners should keep alternative scenarios live as national data-localization requirements proliferate beyond EU jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Cloud Radio Access Network (C-RAN) Market
Telecommunications
MENA Mobile Virtual Network Operator Market
Telecommunications
Global 5G in Healthcare Market
Telecommunications
Global Esim Market
Telecommunications
United Kingdom Telecom Market
Telecommunications
Standalone 5G Network Market
Telecommunications
Cellular Modem Market
Telecommunications
Voice Communication Control System Market
Telecommunications
GSM Mobile Phone Market
Telecommunications
Voice Over LTE (Volte) Market
Telecommunications
IP Centrex Platforms Market
Telecommunications
Costa Rica Telecom Market
Telecommunications
MVNO Market
Telecommunications
Australia Telecom Tower Market
Telecommunications
Virtual CPE (Vcpe) Market
Telecommunications
IP DECT Phones Market