
 Transport Stream Switching Market | 2026-2036
Transport Stream Switching Market Size, Share, and Industry Trends Forecast 2026-2036
Transport Stream Switching Market Outlook
Germany is reshaping competitive dynamics in transport stream switching through major broadcast infrastructure modernization across ARD and ZDF networks. Harmonic leverages its video delivery portfolio to sustain strong positioning in European headend deployments. ROHDE&SCHWARZ anchors German-language market presence through precision test and measurement heritage that extends into broadcast switching systems. Starfish Technologies specializes in software-based stream processing, differentiating its offering against hardware-centric rivals.
Transport stream switching governs the real-time selection, routing, and redundancy management of MPEG-transported digital video and audio packets across broadcast and IP networks, operating typically at bitrates from 1.5 Mbps to 80 Mbps depending on codec and resolution profiles. Switches and routers capture the largest product category share due to their centrality in master control room architectures, while HEVC technology segments expand fastest as broadcasters compress higher-resolution feeds into existing bandwidth allocations. OTT platforms represent the most dynamic end-user segment, driving demand for IP-native switching fabrics that bridge traditional broadcast and internet delivery workflows.
The FCC mandates ATSC 3.0 transition timelines that compel U.S. broadcasters to replace legacy MPEG-2 switching infrastructure, while the EMA and national regulators across Europe enforce DVB-T2 and HbbTV interoperability standards that shape product certification requirements. China's MIIT and GB standards authorities impose distinct terrestrial broadcasting protocols that fragment equipment specifications for vendors serving that market. Stakeholders must weigh regional codec standardization trajectories against the capital risk of overcommitting to any single transport technology before next-generation IP-based broadcast convergence stabilizes.
Market Dynamics
The broadcast infrastructure replacement cycle is compressing as ATSC 3.0 mandates in the United States and DVB-T2 rollouts across Europe force synchronous hardware refreshes, creating concentrated demand spikes that strain semiconductor supply chains.
Growth Catalysts
- ATSC 3.0 Transition Mandates:The FCC's next-generation broadcast timeline compels U.S. stations to replace MPEG-2 switching infrastructure, generating equipment demand across terrestrial and satellite multiplexing operations.
- HEVC Compression Adoption:Broadcasters deploy High Efficiency Video Coding to squeeze 4K and 8K feeds into existing bandwidth allocations, requiring IP-native switching fabrics that handle variable bitrate streams.
- OTT Platform Expansion:Streaming services bridge traditional broadcast and internet delivery workflows, driving procurement of hybrid switching systems that manage both ASI and IP transport streams.
Market Restraints
- FPGA Supply Concentration:Xilinx and Intel dominate programmable logic device manufacturing for real-time packet processing, creating single-source vulnerability for switch fabric controllers.
- Codec Licensing Fragmentation:Patent pools from MPEG LA, HEVC Advance, and Access Advance impose royalty stacking that elevates total cost of ownership for HEVC-enabled switching equipment.
- Terrestrial Bandwidth Scarcity:Spectrum reallocation to mobile broadband in the United States and Europe compresses available UHF channels, limiting multiplex capacity expansion regardless of switching sophistication.
Strategic Opportunities
- India Terrestrial Digitization:The country's Phase III and IV DTH and digital terrestrial television expansion creates demand for cost-optimized transport stream switches in emerging broadcast markets.
- Cloud-Native Playout Integration:Software-defined switching instances deployed on AWS, Azure, and private cloud infrastructure enable broadcasters to shift capital expenditure to operational expenditure models.
- 5G Broadcast Convergence:3GPP Release 16 and 17 specifications for 5G multicast-broadcast services position transport stream switches as bridge components between terrestrial and cellular distribution.
Industry Challenges
- Real-Time Engineering Talent Scarcity:Deep expertise in MPEG transport stream semantics, PCR jitter management, and IP multicast routing remains concentrated among veteran broadcast engineers nearing retirement.
- Interoperability Certification Delays:DVB and ATSC compliance testing for new switching platforms extends product launch timelines by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transport Stream Switching Market |
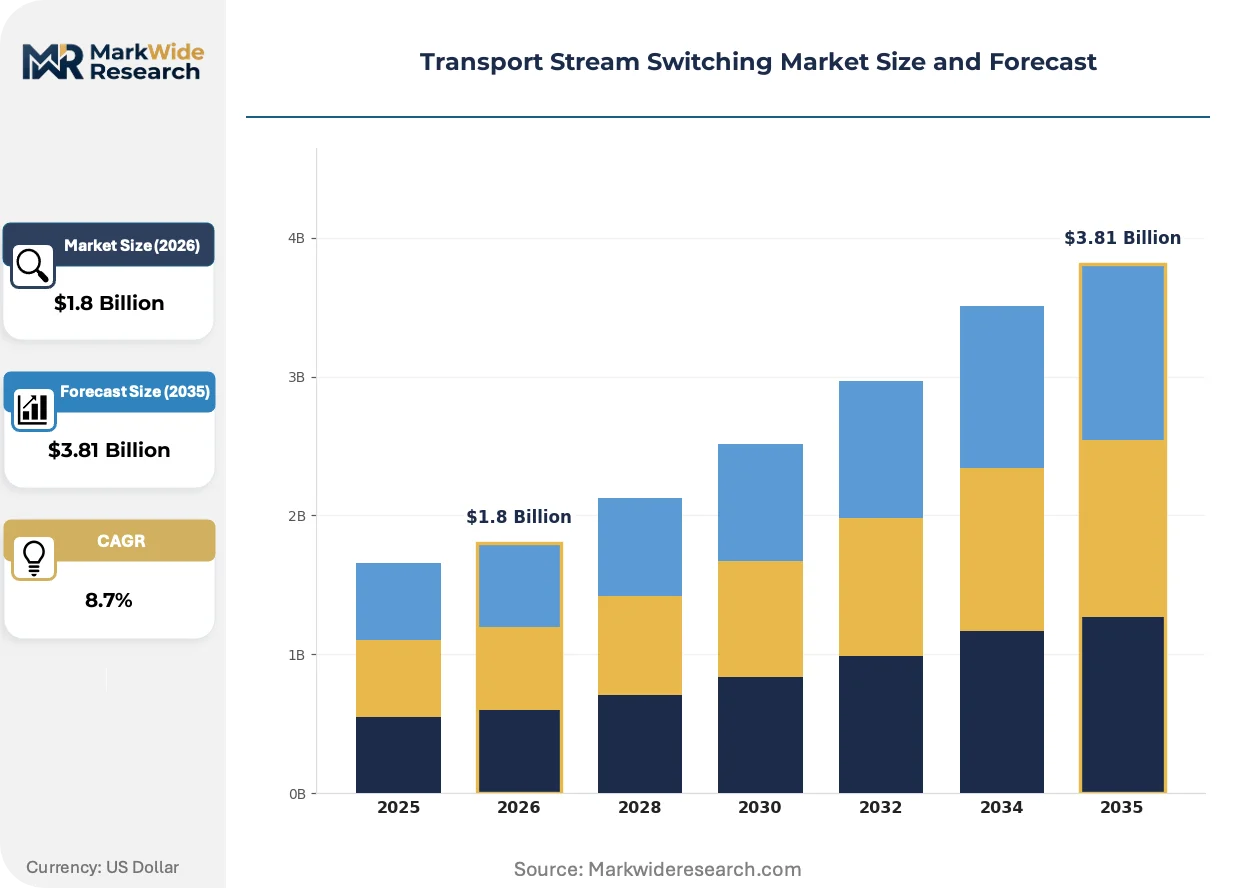
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Encoders, Decoders, Switches, Routers Technology: MPEG, DVB, ATSC, HEVC End User: Broadcasters, Telecom, Cable Operators, OTT Platforms Application: Live Streaming, Video On Demand, Broadcast Distribution, IPTV |
| Companies Covered | Telestream, Starfish Technologies, Harmonic, Mediaware International, MIVIDI, VBrick Systems, Nevion, Manzanita Systems, ROHDE&SCHWARZ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transport Stream Switching Market Strategic Shifts
Broadcast infrastructure is pivoting from hardware-centric master control rooms to software-defined video processing chains, compressing equipment refresh cycles and redistributing value toward IP networking and cloud orchestration layers.
Software-based stream processing is migrating from niche applications to mainstream deployment. Virtualized switching functions running on commercial-off-the-shelf servers now handle redundancy failover and service protection that dedicated hardware previously managed. European public broadcasters lead this transition, with ARD and ZDF networks consolidating regional playout centers. The technology is migrating from edge redundancy systems to core multiplexing operations, collapsing the distinction between transport stream switching and general-purpose IP routing.
REACH and RoHS substance restrictions in the European Union constrain solder alloys and flame retardants used in broadcast equipment printed circuit boards. Manufacturers reformulate component finishes to maintain thermal performance under lead-free mandates. Switching equipment destined for German and French broadcast headends faces the most stringent material compliance verification, with suppliers maintaining dual bill-of-materials configurations for EU and non-EU shipments.
Service contracts are unbundling from hardware procurement as broadcasters favor multi-vendor maintenance agreements over single-source OEM support. Large station groups in the United States negotiate enterprise-wide technical service contracts that span switching, encoding, and modulation equipment. This pattern concentrates most visibly among Nexstar, Sinclair, and Tegna station portfolios, where centralized technical operations centers manage dispersed geographic footprints through remote monitoring and vendor-agnostic sparing pools.
Transport Stream Switching Market Segmentation
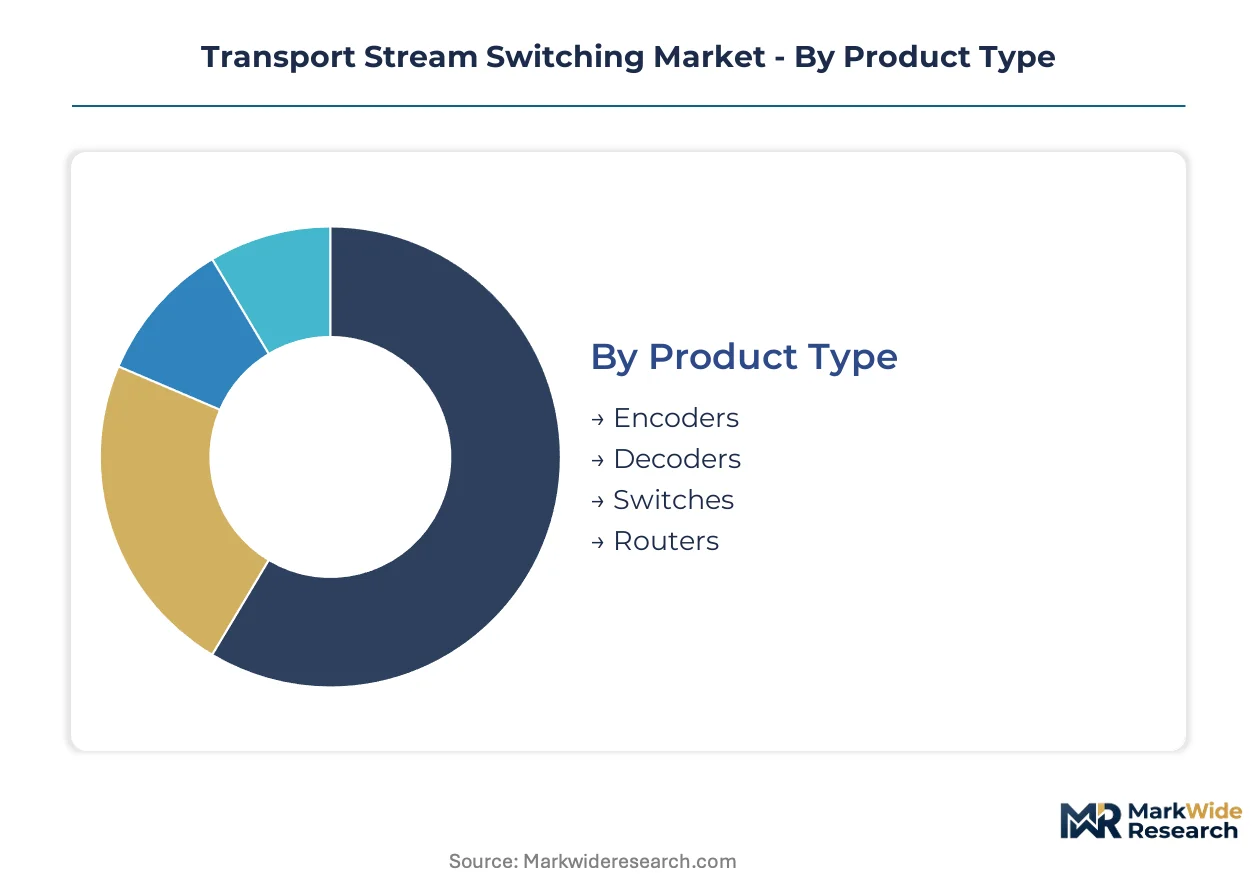
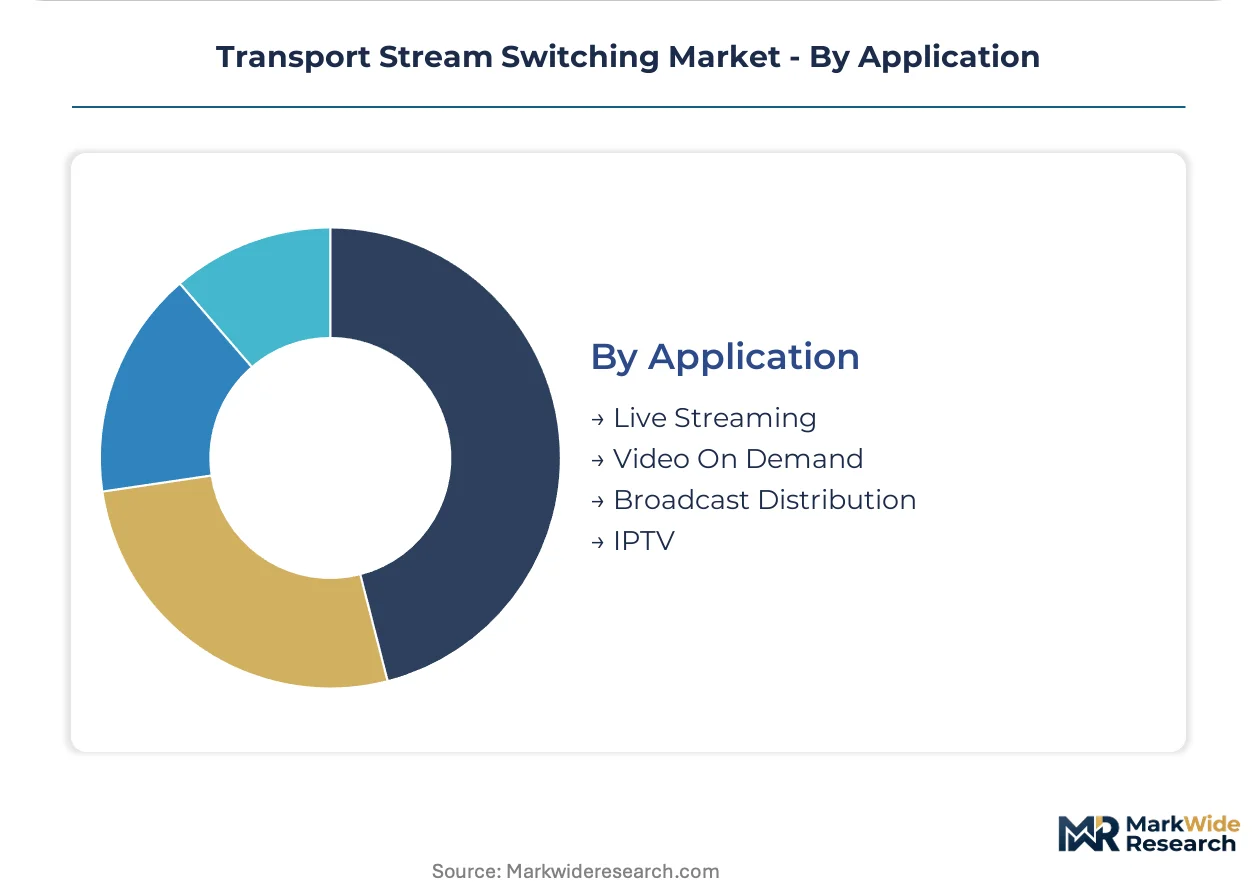
Transport stream switching equipment serves distinct technical workflows across broadcast, telecom, and streaming domains. Segmentation reveals how codec standards, distribution architectures, and end-user business models reshape procurement patterns and product specifications.
Product Type:
Hardware form factors diverge sharply in cost tier and functional integration, with master control deployments favoring different equipment classes than edge distribution nodes.
- Switches and Routers:These devices anchor master control room architectures with real-time packet routing, redundancy failover, and ASI-to-IP bridging capabilities. Demand concentrates among U.S. station groups executing FCC-mandated ATSC 3.0 infrastructure replacement, where synchronous hardware refreshes strain semiconductor supply chains.
- Encoders:Compression engines transform baseband video into MPEG transport streams across MPEG-2, H.264, and HEVC profiles. German public broadcasters drive procurement of dual-channel encoding platforms that feed complex terrestrial and satellite multiplexing networks.
- Decoders:Signal restoration devices convert compressed transport streams back to baseband for monitoring, confidence checking, and downstream processing.
Switches and routers command the established base. The steepest expansion runs through encoder platforms supporting HEVC and VVC transitions.
Technology:
Codec and transmission standards fragment procurement specifications across regional regulatory jurisdictions, forcing vendors to maintain multiple certification tracks.
- HEVC:High Efficiency Video Coding enables 4K and 8K distribution within existing bandwidth allocations through improved compression efficiency. OTT platforms in the United States drive fastest adoption as streaming services bridge traditional broadcast and IP-native delivery workflows.
- MPEG:Legacy MPEG-2 and MPEG-4 AVC standards persist in installed base equipment, particularly where capital constraints delay infrastructure refresh cycles.
- ATSC:The FCC's next-generation broadcast standard mandates specific transport stream syntax and signaling tables for U.S. terrestrial transmission.
- DVB:European digital video broadcasting specifications govern satellite, cable, and terrestrial multiplexing across EMA-regulated markets.
MPEG retains the installed base dominance. HEVC climbs the fastest as bandwidth economics favor compression efficiency over legacy compatibility.
End User:
Customer type determines volume scale, service level requirements, and procurement centralization patterns across the value chain.
- Broadcasters:Terrestrial and satellite station groups operate the most demanding real-time switching requirements with sub-frame redundancy failover specifications.
- OTT Platforms:Streaming-native distributors drive hybrid switching architectures that manage both traditional ASI feeds and IP multicast streams.
- Cable Operators:Multi-system operators consolidate headend operations through centralized transport stream grooming and regional ad insertion.
- Telecom:Carriers deploy switching equipment for IPTV service delivery and mobile video offload applications.
Broadcasters anchor the revenue base. OTT platforms gain share fastest as internet-distributed video displaces traditional transmission economics.
Application:
Use case maturity shapes performance specifications, with live workflows demanding deterministic latency that on-demand services relax.
- Live Streaming:Real-time event distribution requires PCR-accurate switching with seamless redundancy protection. Sports rights holders in Germany and the United States drive premium equipment specifications.
- Broadcast Distribution:Scheduled linear programming remains the volume anchor for terrestrial and satellite multiplexing infrastructure.
- IPTV:Telco-managed television services use switched video architectures to optimize last-mile bandwidth utilization.
- Video On Demand:File-based workflows tolerate higher switching latency, enabling software-defined and cloud-native processing alternatives.
Broadcast distribution holds the volume foundation. Live streaming expands most quickly as direct-to-consumer sports and event rights fragment traditional windowing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Programmable logic device fabrication concentrates among a handful of semiconductor foundries, creating geographic chokepoints for switch fabric controller supply. Broadcast infrastructure procurement patterns diverge sharply across regulatory jurisdictions. Equipment vendors maintain region-specific certification tracks to satisfy divergent codec mandates.
United States
FCC-mandated ATSC 3.0 transition timelines compel synchronous hardware refreshes across terrestrial station groups. The Commission's next-generation broadcast standard dictates specific transport stream syntax and signaling tables. Nexstar, Sinclair, and Tegna station portfolios concentrate procurement through centralized technical operations centers in Texas and Illinois.
Germany
Public broadcasters ARD and ZDF operate Europe's most complex terrestrial and satellite multiplexing networks, driving demand for precision switching equipment. REACH and RoHS substance restrictions constrain solder alloys and flame retardants in printed circuit boards. Broadcast headends in Munich and Cologne face the most stringent material compliance verification, with suppliers maintaining dual bill-of-materials configurations.
China
MIIT and GB standards authorities impose distinct terrestrial broadcasting protocols that fragment equipment specifications for vendors serving this market. The country's national broadcast regulator enforces certification requirements that diverge from DVB and ATSC frameworks. Manufacturing clusters in Shenzhen and Beijing produce cost-optimized switching platforms for domestic Phase III and IV digital television expansion.
India
Phase III and IV DTH and digital terrestrial television expansion creates demand for cost-optimized transport stream switches in emerging broadcast markets. TRAI oversees interoperability standards that shape product certification timelines. Mumbai and Delhi-NCR serve as procurement hubs where system integrators aggregate orders from regional broadcasters and cable operators.
United Kingdom
Commercial and public service broadcasters consolidate regional playout centers, collapsing distinctions between transport stream switching and general-purpose IP routing. Ofcom regulates spectrum allocation and broadcast standards compliance. London and Salford MediaCityUK host the primary technical facilities where software-defined switching migration proceeds fastest.
Transport Stream Switching Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the programmable logic and signal processing layers. The vendor base organizes around three archetypes: broadcast heritage suppliers with test and measurement lineages, software-native stream processing specialists, and video delivery portfolio conglomerates. Consolidation pressure runs through capacity expansion in IP-native switching fabrics and strategic partnerships bridging terrestrial and OTT workflows.
Within the broadcast heritage tier, ROHDE&SCHWARZ anchors German-language market presence through its precision instrumentation legacy extending into switching systems. Harmonic occupies a position among video delivery portfolio suppliers sustaining European headend deployments. Starfish Technologies exemplifies the software-native specialist archetype, differentiating through virtualized stream processing against hardware-centric rivals.
| Leading Market Players |
|---|
| Telestream |
| Starfish Technologies |
| Harmonic |
| Mediaware International |
| MIVIDI |
| VBrick Systems |
| Nevion |
| Manzanita Systems |
| ROHDE&SCHWARZ |
| Others |
Value Chain & Pricing Dynamics
Xilinx and Intel's lock on programmable logic devices for real-time packet processing concentrates upstream margin capture among semiconductor foundries, while downstream equipment vendors compete on service bundling and certification breadth to defend pricing power in fragmented broadcast procurement.
Pricing Analysis
FCC mandates for ATSC 3.0 transition dictate the pricing tier structure across U.S. terrestrial station groups. Three-tier pricing structure across premium, standard, and economy levels separates redundant master-control configurations from single-channel edge deployments. Price differentiation rests on certification grade and volume scale, with Nexstar and Sinclair station groups extracting bulk discounts through centralized technical operations centers. Pricing pressure stems from codec licensing fragmentation across MPEG LA, HEVC Advance, and Access Advance patent pools. OTT platforms exhibit lowest price sensitivity due to IP-native switching requirements, while India's Phase III broadcasters face acute cost constraints.
Supply Chain Analysis
Hon Hai Precision Industry and Flex hold dominant contract manufacturing capacity for broadcast equipment chassis and power assemblies. Component sourcing draws from Taiwan for FPGA fabrication, South Korea for high-speed memory, and Germany for precision RF connectors. Raw material dependencies center on copper-clad laminates, lead-free solder alloys under REACH mandates, and specialized aluminum heat sinks. Single-source vulnerability runs through Xilinx and Intel programmable logic devices. Distribution runs through direct OEM relationships with station groups and systems integrators in Munich, Dallas, and Mumbai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deep expertise in MPEG transport stream semantics and PCR jitter management remains concentrated among veteran broadcast engineers nearing retirement, constraining execution capacity across vendor and operator organizations alike.
For Market Incumbents: Insulate core master-control relationships through embedded service contracts that span encoding, switching, and modulation equipment. Pursue backward integration into FPGA firmware customization to reduce dependence on Xilinx and Intel roadmaps. Defend against software-native specialists by accelerating virtualized switching certifications for AWS and Azure deployments. For New Entrants and Emerging Players: Establish a beachhead in India's Phase III and IV digital terrestrial expansion where cost-optimized transport stream switches face limited incumbent saturation. Target cloud-native playout integration as broadcasters shift capital expenditure to operational expenditure models. Lead with software-defined instances that collapse distinction between transport stream switching and general-purpose IP routing. For Investors and Strategic Acquirers: Capital is best deployed toward software-native stream processing specialists with virtualized switching deployments already operational at ARD, ZDF, or BBC technical facilities. Long-term viability hinges on bridging terrestrial broadcast and OTT convergence workflows. Watch 3GPP Release 17 multicast-broadcast specifications as inflection signal for 5G broadcast equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Playout Integration | AWS and Azure deployments enable broadcasters to shift from capital expenditure to operational expenditure models. |
| HEVC-Enabled Switching Certification | FCC mandates for ATSC 3.0 compel synchronous hardware refreshes across U.S. terrestrial station groups. |
| 5G Broadcast Convergence Partnership | 3GPP Release 16 specifications position transport stream switches as bridge components between terrestrial and cellular distribution. |
| India Market Localization | Phase III and IV DTH expansion creates procurement hubs in Mumbai and Delhi-NCR for cost-optimized switches. |
| Service Contract Unbundling | Nexstar and Sinclair negotiate enterprise-wide technical agreements spanning switching, encoding, and modulation equipment. |
Study Parameters
Desk research of FCC equipment authorization databases, DVB interoperability certification records, and semiconductor foundry capacity disclosures preceded structured interviews with broadcast engineering directors, headend operations managers, and procurement leads at station groups. Primary fieldwork encompassed technical directors at ARD and ZDF networks, cloud solutions architects at AWS Media Services, and systems integrators in Mumbai and Dubai. Secondary validation drew from EMA regulatory filings, TRAI consultation papers, and customs data for broadcast equipment trade flows. Bottom-up demand modeling triangulated against top-down market sizing across hardware and software revenue streams.
Assumptions held fixed include ATSC 3.0 transition timelines per FCC mandates, DVB-T2 rollout schedules across EMA-regulated markets, and HEVC patent pool royalty structures. Variables stress-tested encompass FPGA supply disruption scenarios, spectrum reallocation decisions in the United States and Europe, and cloud migration acceleration rates among public broadcasters. Segmentation dimensions modeled span product type, codec technology, end-user archetype, and application workflow across the projection horizon. CAGRs derived from equipment replacement cycle compression analysis and OTT platform infrastructure scaling patterns.
Stress conditions across semiconductor lead times, regulatory certification delays, and terrestrial bandwidth scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including single-source programmable logic dependency and codec licensing fragmentation. Cross-checking against FCC equipment authorization trends and EMA market surveillance data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Private LTE in Mining Industry Market
Telecommunications
Telecom Expense Management Market
Telecommunications
Global Fixed-Mobile Convergence Market
Telecommunications
Promotional Sms Market
Telecommunications
Czech Republic Telecom Market
Telecommunications
Bangladesh Telecommunication Industry Market
Telecommunications
Iceland Telecom Market
Telecommunications
Explosion Proof Mobile Communication Devices Market
Telecommunications
5G Monetization Market
Telecommunications
Global SMB Telecom Voice and Data Services Market
Telecommunications
Smart SIM Market
Telecommunications
Esim Subscription Market
Telecommunications
Global 5G Services Market
Telecommunications
Global B2B Telecommunication Market
Telecommunications
5G in Defense Market
Telecommunications
Europe Telecom Expense Management Market