
 Japan 5G Small Cell Market | 2026-2036
Japan 5G Small Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Japan 5G Small Cell Market Insights
JIS standards compliance for radio equipment certification is reorganizing vendor eligibility in Japan's 5G small cell arena. NEC Corporation leverages its domestic manufacturing footprint to anchor supply continuity for NTT DOCOMO and KDDI deployments. Fujitsu Limited sustains R&D intensity in Open RAN-compatible small cell architectures, differentiating its portfolio from integrated-stack competitors. Samsung Electronics Co., Ltd. competes through aggressive positioning in mmWave outdoor units, navigating Japan's stringent electromagnetic compatibility requirements.
5G small cells are low-power radio access nodes operating in sub-6 GHz and mmWave spectra, typically delivering coverage radii under 250 meters with integrated MIMO antenna arrays and Ethernet or fiber backhaul interfaces; they densify network capacity in high-traffic zones where macro cells prove insufficient. Indoor deployments command premium pricing due to complex RF propagation engineering and enterprise-grade security integration, while outdoor pole-mounted installations lead volume through municipal smart-city partnerships. Femtocell technology remains mature in residential applications, whereas distributed antenna systems capture expanding share in stadium and transit hub venues where seamless handoff density matters.
METI spectrum policy and Ministry of Internal Affairs and Communications base station licensing frameworks dictate deployment cadence and equipment interoperability mandates, compressing product development cycles for vendors seeking market access. The Telecommunications Business Law and Radio Law establish technical conformance benchmarks that filter out non-compliant hardware, reinforcing domestic incumbent advantages. Stakeholders must monitor Open RAN standardization momentum and local government digital infrastructure procurement shifts to anticipate procurement priority changes.
Market Dynamics
NTT DOCOMO and KDDI are compressing vendor qualification timelines through accelerated base station certification demands, forcing equipment suppliers to restructure R&D cycles around METI spectrum allocation deadlines.
Growth Catalysts
- METI spectrum policy:The Ministry of Economy, Trade and Industry's sub-6 GHz and mmWave band allocations are mandating densification targets in Tokyo, Osaka, and Fukuoka corridors.
- Open RAN architectures:Interface standardization is lowering barriers for specialized radio unit vendors to interoperate with incumbent baseband suppliers.
- Smart city partnerships:Municipal governments in Yokohama and Sapporo are embedding small cell pole mounts into streetlight upgrade contracts.
Market Restraints
- GaN-on-SiC substrate costs:Power amplifier material expenses constrain mmWave unit economics for outdoor deployments.
- Domestic manufacturing concentration:JIS-certified fabrication capacity clusters in Nagoya and Kyoto prefectures, creating geographic supply risk.
- Radio Law compliance friction:Ministry of Internal Affairs and Communications electromagnetic compatibility testing extends product launch windows by four to six months.
Strategic Opportunities
- Hokkaido industrial zones:Cold-climate logistics hubs remain underserved for private 5G network coverage.
- Private network slicing:Manufacturing automation in Aichi Prefecture is creating demand for campus-scale small cell deployments.
- Local government procurement:Digital infrastructure bonds issued by Fukuoka City are prioritizing neutral-host small cell infrastructure.
Industry Challenges
- RF propagation engineering talent:mmWave beamforming expertise concentrates among retiring NTT legacy engineers.
- Multi-vendor integration complexity:Open RAN disaggregation is forcing carriers to absorb system-level interoperability testing costs previously borne by integrated-stack suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan 5G Small Cell Market |
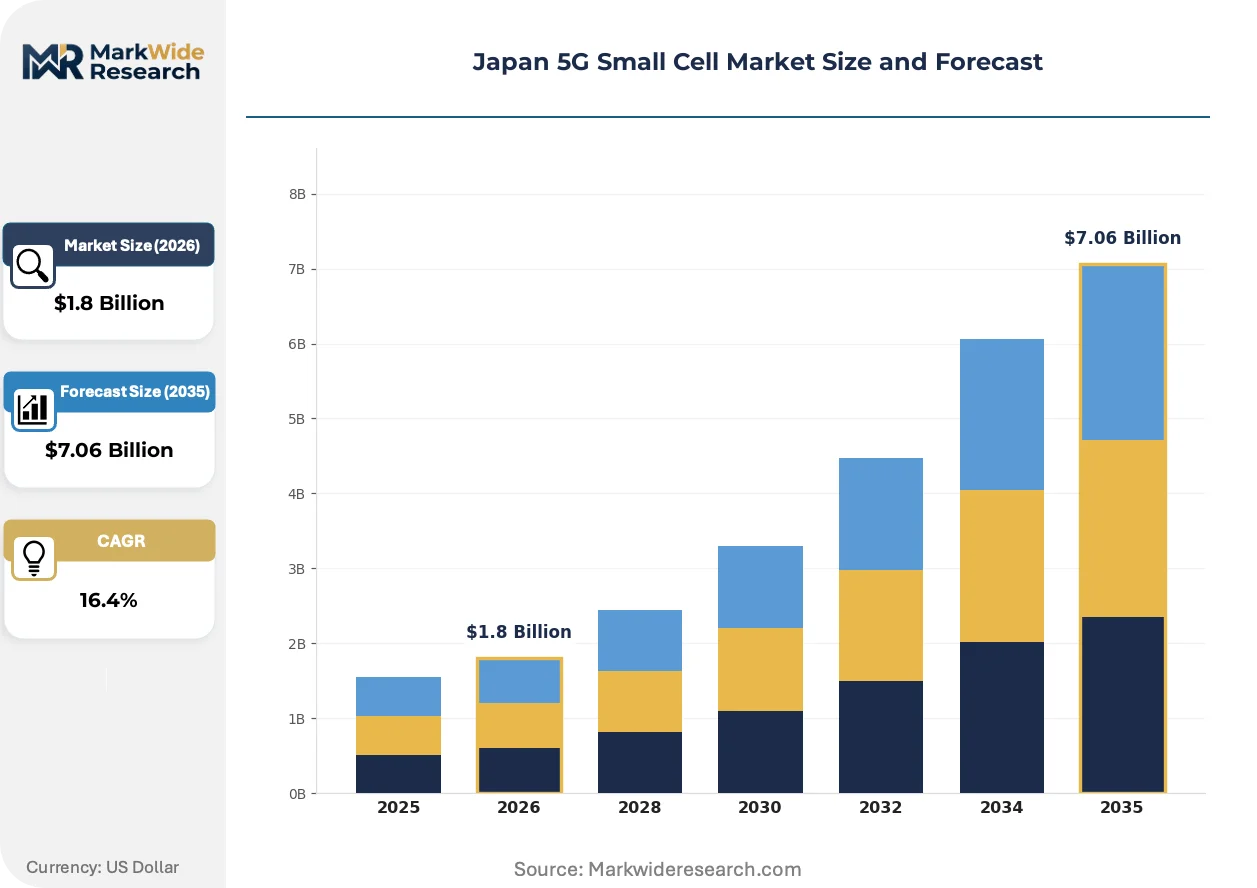
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor, Outdoor, Pico, Micro Technology: Femtocells, IP-based, Distributed Antenna Systems, MIMO End User: Telecom Operators, Enterprises, Government, Public Venues Installation: Standalone, Integrated, Wall-mounted, Pole-mounted |
| Companies Covered | Telefonaktiebolaget LM Ericsson, Huawei Technologies Co., Ltd., Nokia Corporation, Samsung Electronics Co., Ltd., NEC Corporation, Fujitsu Limited, ZTE Corporation, Qualcomm Technologies Inc., Airspan Networks Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan 5G Small Cell Market Trends and Innovations
Open interface specifications are dissolving traditional vendor lock-in structures, enabling carrier procurement teams to unbundle radio units from baseband software and source each layer independently.
Virtualized distributed unit software is fragmenting hardware procurement patterns across NTT DOCOMO's network. Tier-2 system integrators in Osaka are now bidding standalone DU contracts previously captured by integrated equipment vendors. This disaggregation is compressing margins for full-stack suppliers while expanding addressable market entry points for specialized radio hardware vendors.
METI's local 5G licensing framework is accelerating enterprise-private network deployments beyond carrier-managed infrastructure. Manufacturing conglomerates in Toyota City are securing dedicated spectrum blocks for factory-floor automation. The Ministry of Internal Affairs and Communications is processing local 5G permits at triple the rate of standard base station licenses, redirecting vendor sales resources toward direct enterprise engagements.
Neutral-host infrastructure models are displacing carrier-captive deployment structures in dense commercial districts. Property developers in Tokyo's Marunouchi district are contracting shared small cell networks serving multiple mobile operators simultaneously. This architecture concentrates capital expenditure with real estate owners rather than distributing it across competing carrier buildouts, altering vendor customer relationship dynamics and technical support obligations.
Japan 5G Small Cell Market Segmentation
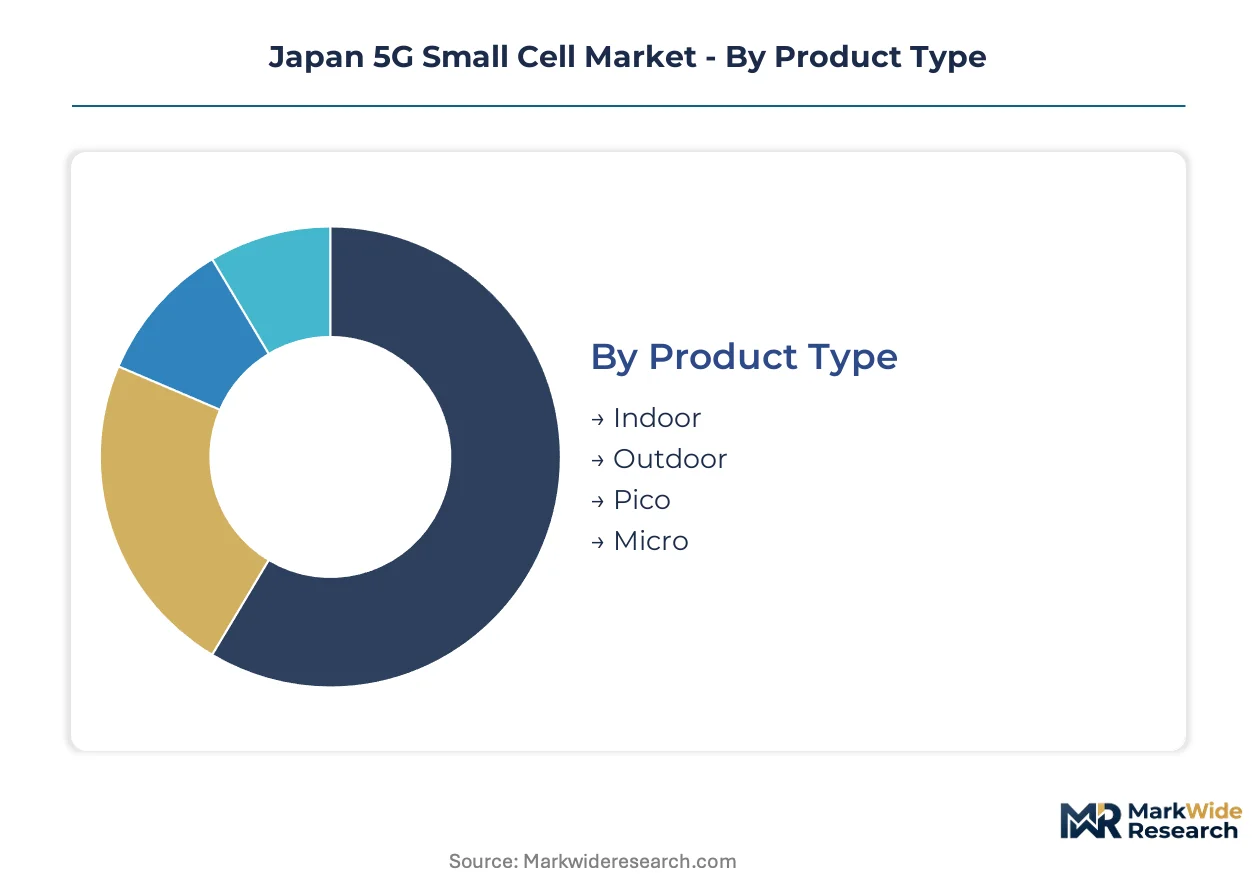
Segmentation in Japan's 5G small cell market reflects the interplay between METI spectrum mandates and the Ministry of Internal Affairs and Communications certification tiers. Deployment economics vary sharply across indoor versus outdoor configurations, with JIS compliance requirements filtering vendor participation differently by product category.
Product Type:
METI's sub-6 GHz and mmWave band allocations impose distinct electromagnetic compatibility thresholds that reshape procurement patterns across indoor and outdoor equipment categories.
- Indoor:Compact units integrate MIMO antenna arrays with Ethernet backhaul for enterprise and residential densification. Premium pricing persists in Tokyo commercial districts due to complex RF propagation engineering requirements and enterprise-grade security integration mandated by building codes in Marunouchi and Roppongi clusters.
- Outdoor:Pole-mounted and streetlight-integrated configurations dominate municipal smart-city partnerships in Yokohama and Sapporo. mmWave outdoor units face extended Ministry of Internal Affairs and Communications electromagnetic compatibility testing cycles that compress deployment windows for carriers.
- Pico:Low-power nodes serve targeted coverage gaps in transit corridors and retail concourses.
- Micro:Mid-range power class bridges capacity between femtocell and macro cell footprints in Osaka manufacturing zones.
Established volume favors Outdoor; emerging adoption favors Indoor.
Technology:
Cost tier differentiation separates legacy integrated architectures from disaggregated Open RAN-compatible alternatives.
- Femtocells:Mature residential technology with standardized residential gateway integration. Deployment concentrates in suburban Tokyo prefectures where NTT DOCOMO and KDDI prioritize last-mile coverage extension over capacity densification.
- IP-based:Packet-optimized transport architectures enable virtualized baseband processing. Adoption accelerates in Fukuoka technology corridors where carriers test cloud-native network slicing for enterprise clients.
- Distributed Antenna Systems:Seamless handoff density for stadium and transit hub venues. Osaka's Kansai International Airport expansion and Tokyo Olympic legacy venues sustain demand concentration.
- MIMO:Multi-input multi-output antenna configurations deliver spectral efficiency gains in sub-6 GHz deployments. Beamforming complexity concentrates RF engineering talent among legacy NTT technical staff approaching retirement.
Revenue concentration favors MIMO; technology transition momentum favors IP-based.
End User:
Customer type determines procurement channel structure and support obligation intensity.
- Telecom Operators:NTT DOCOMO and KDDI compress vendor qualification timelines through accelerated base station certification demands. Their procurement volumes anchor supplier revenue stability across Nagoya and Kyoto fabrication clusters.
- Enterprises:Manufacturing conglomerates in Toyota City secure dedicated spectrum blocks under METI's local 5G licensing framework. Direct vendor engagement bypasses traditional carrier-managed infrastructure procurement.
- Government:Municipal digital infrastructure bonds in Fukuoka City prioritize neutral-host small cell architecture.
- Public Venues:Shared infrastructure contracts with real estate developers alter technical support obligations toward multi-tenant service level agreements.
Procurement scale favors Telecom Operators; margin expansion favors Enterprises.
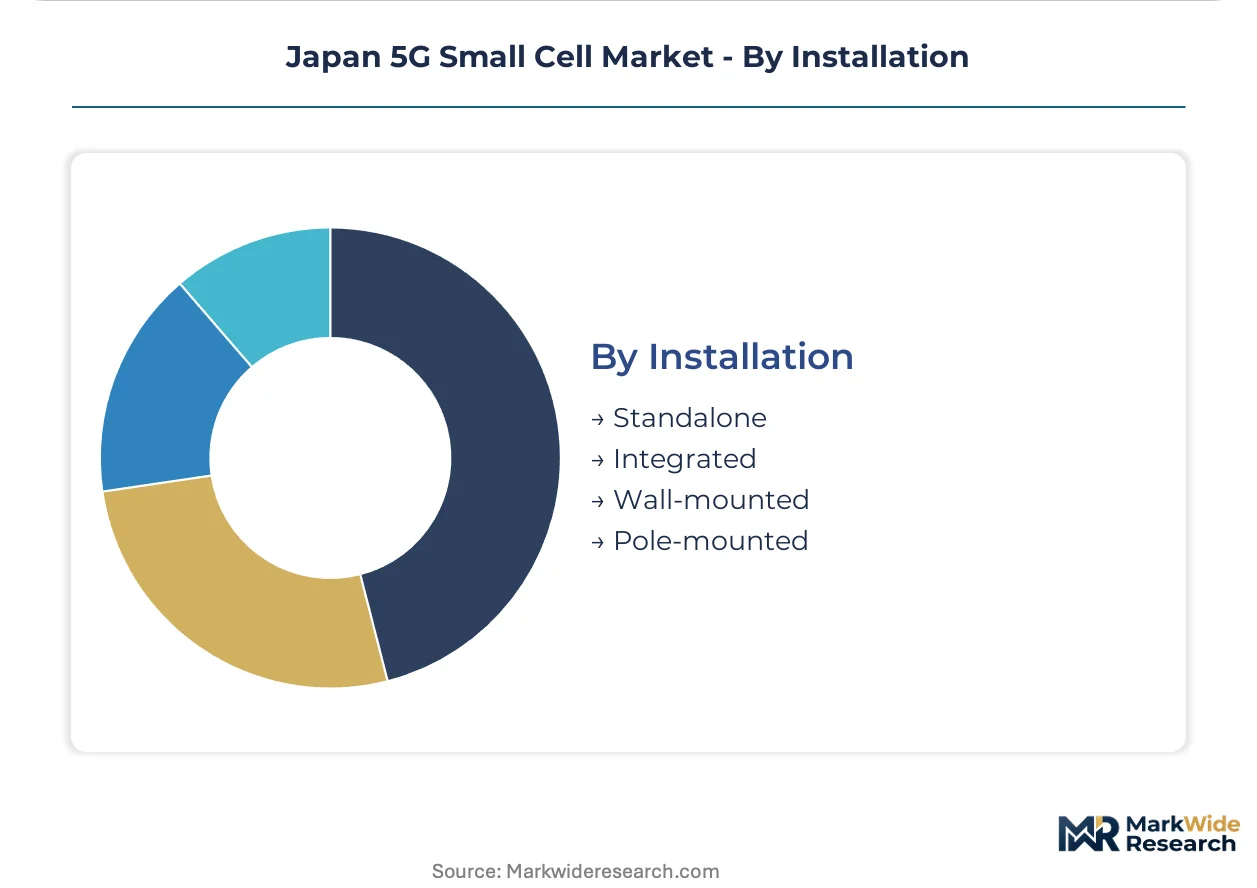
Installation:
Geographic deployment patterns concentrate supply chain configuration in specific prefectural manufacturing zones.
- Standalone:Discrete enclosure deployments suit rapid site acquisition in greenfield industrial zones. Cold-climate logistics hubs in Hokkaido remain underserved, creating private network opportunity.
- Integrated:Combined radio and baseband units preserve incumbent vendor relationships. JIS-certified fabrication capacity in Nagoya prefecture supports integrated-stack production continuity.
- Wall-mounted:Enterprise and residential interior placement requires building owner coordination.
- Pole-mounted:Streetlight upgrade contracts embed small cells in municipal infrastructure. Yokohama and Sapporo smart-city partnerships standardize this configuration.
Deployment velocity favors Pole-mounted; customization premium favors Standalone.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecom operators and enterprise buyers concentrate procurement authority in Japan's three metropolitan manufacturing belts, with municipal governments in secondary cities emerging as infrastructure co-investors.
Kanto/Tokyo
NTT DOCOMO and KDDI compress vendor qualification timelines through accelerated base station certification demands. METI spectrum allocation policies mandate densification targets across Tokyo's commercial districts. Marunouchi and Roppongi clusters anchor premium indoor small cell deployments with complex RF propagation engineering requirements.
Kansai/Osaka
Manufacturing automation in Osaka's industrial zones drives demand for campus-scale small cell networks. The Ministry of Internal Affairs and Communications processes local 5G permits at triple the rate of standard licenses. Toyota City manufacturing conglomerates secure dedicated spectrum blocks for factory-floor automation under METI's local 5G framework.
Chubu/Nagoya
JIS-certified fabrication capacity clusters in Nagoya and Kyoto prefectures, creating geographic supply concentration for integrated-stack production. The Radio Law establishes technical conformance benchmarks that filter non-compliant hardware. Nagoya fabrication zones support NEC Corporation and Fujitsu Limited manufacturing continuity for domestic carrier deployments.
Kyushu
Fukuoka City digital infrastructure bonds prioritize neutral-host small cell architecture serving multiple mobile operators. Municipal governments embed small cell pole mounts into streetlight upgrade contracts. Fukuoka technology corridors sustain demand for cloud-native network slicing trials with enterprise clients.
Hokkaido
Cold-climate logistics hubs remain underserved for private 5G network coverage, creating greenfield deployment opportunities. Standalone discrete enclosure configurations suit rapid site acquisition in industrial zones. Sapporo smart-city partnerships standardize pole-mounted configurations in municipal infrastructure programs.
Japan 5G Small Cell Market Competitive Landscape
Player mix skews toward integrated-stack incumbents with domestic manufacturing footprints and specialized radio unit vendors pursuing Open RAN interoperability. The vendor base separates into three strategic archetypes: full-stack suppliers with captive fabrication, disaggregated radio specialists, and neutral-host infrastructure operators. Competitive moves center on JIS certification acceleration and municipal partnership anchoring rather than price-based displacement.
Among Japan-based fabricators, NEC Corporation and Fujitsu Limited occupy positions within the integrated-stack tier, while Samsung Electronics Co., Ltd. represents the mmWave specialist archetype competing through outdoor unit positioning. These three companies exemplify the competitive tension between domestic manufacturing continuity and international technology access that shapes procurement outcomes for NTT DOCOMO and KDDI.
| Leading Market Players |
|---|
| Telefonaktiebolaget LM Ericsson |
| Huawei Technologies Co., Ltd. |
| Nokia Corporation |
| Samsung Electronics Co., Ltd. |
| NEC Corporation |
| Fujitsu Limited |
| ZTE Corporation |
| Qualcomm Technologies Inc. |
| Airspan Networks Inc. |
| Others |
Pricing and Supply Chain Analysis
GaN-on-SiC substrate utilization rates in Nagoya fabrication clusters anchor both unit cost floors and supplier pricing power across mmWave outdoor equipment tiers. This concentration compresses margin flexibility for vendors while amplifying procurement leverage for NTT DOCOMO and KDDI through volume commitment structures.
Pricing Analysis
Cost-plus contracts with GaN substrate indexation dominate NTT DOCOMO procurement frameworks for outdoor small cell deployments. Pricing stratifies across JIS-certified premium tiers, standard commercial grades, and economy residential femtocell configurations, with certification level and volume scale as primary differentiation drivers. Cost compression in mmWave units is intensifying because METI spectrum deadlines compress vendor R&D amortization periods. Enterprise buyers in Toyota City manufacturing zones exhibit lowest price sensitivity due to automation ROI requirements, while municipal governments in Sapporo and Yokohama anchor highest sensitivity through bond-financed procurement constraints.
Supply Chain Analysis
Inventory buffers for GaN-on-SiC power amplifiers stretch lead times across Nagoya and Kyoto prefecture fabrication zones, creating procurement scheduling rigidity for carriers. Supply draws from Japan for JIS-certified integrated stacks, South Korea for specialized RF components, and Taiwan for baseband processing silicon. Raw material dependencies center on silicon carbide substrates, gallium nitride epitaxy, and high-frequency laminates. Single-source vulnerability concentrates in Nagoya-area JIS-certified cleanroom capacity. Distribution runs through carrier-direct procurement channels for telecom operators and system integrator intermediaries for enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's 5G small cell market operates as a substitution defense against Wi-Fi 6E/7 enterprise encroachment in manufacturing automation and neutral-host commercial deployments. Incumbents must navigate this threat while compressing vendor qualification timelines.
For Market Incumbents: Secure JIS certification acceleration through Ministry of Internal Affairs and Communications pre-submission consultation programs to compress product launch windows. Anchor backward integration into GaN-on-SiC substrate sourcing through Nagoya fabrication partnerships to defend margin position against Samsung Electronics Co., Ltd. mmWave pricing pressure. Prioritize Open RAN interoperability investment to preserve procurement relevance as NTT DOCOMO disaggregates radio unit from baseband software sourcing.
For New Entrants and Emerging Players: Anchor in Hokkaido cold-climate logistics hubs where private 5G network coverage remains underserved and carrier-managed infrastructure procurement channels are weakest. Target Fukuoka City neutral-host municipal contracts as the most penetrable procurement segment given digital infrastructure bond prioritization of shared infrastructure. Pursue direct enterprise engagement in Aichi Prefecture manufacturing zones under METI local 5G licensing framework, bypassing traditional carrier qualification barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors disaggregated radio unit specialists with Open RAN interoperability credentials over integrated-stack incumbents facing margin compression. Long-term viability hinges on vendor ability to capture enterprise-private network deployments outside carrier-managed infrastructure. Acquisition target archetype: specialized mmWave radio vendors with Ministry of Internal Affairs and Communications electromagnetic compatibility testing completion and established NTT DOCOMO or KDDI pilot deployments. Signal to watch: local 5G permit processing rates at triple standard license velocity indicating enterprise demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| JIS Certification Acceleration | Ministry of Internal Affairs and Communications pre-consultation compresses product launch windows by four to six months. |
| GaN-on-SiC Backward Integration | Nagoya fabrication partnerships reduce power amplifier material cost exposure in mmWave outdoor units. |
| Open RAN Interoperability Investment | Interface standardization preserves vendor relevance as NTT DOCOMO unbundles procurement layers. |
| Enterprise Direct Engagement | METI local 5G licensing redirects sales resources toward Toyota City manufacturing automation demand. |
| Neutral-Host Infrastructure Partnership | Fukuoka City digital infrastructure bonds concentrate capital expenditure with real estate owners. |
Research Methodology
Initial hypotheses were tested against primary input from NTT DOCOMO and KDDI procurement executives, Ministry of Internal Affairs and Communications certification officers, Nagoya fabrication plant managers, and enterprise IT directors in Toyota City manufacturing zones, and refined through secondary validation. Primary intelligence combined structured interviews with carrier network planning teams and vendor sales leadership. Secondary sources encompassed METI spectrum allocation filings, Ministry of Internal Affairs and Communications base station license databases, JIS standards documentation, and municipal digital infrastructure bond disclosures. Bottom-up deployment volume estimates triangulated against top-down carrier capex allocation patterns.
Variance decomposition across product type, technology architecture, end user category, and installation configuration shaped the analytical framework throughout the forecast period. Segmentation dimensions modeled include indoor versus outdoor deployment, integrated versus disaggregated technology, telecom operator versus enterprise procurement channel, and standalone versus pole-mounted installation. CAGRs derived from deployment volume trajectories indexed to METI spectrum allocation deadlines and carrier densification targets. Industry-specific forecast inputs incorporated GaN-on-SiC substrate cost curves and Open RAN standardization momentum.
Material uncertainties — METI spectrum policy revisions, Ministry of Internal Affairs and Communications electromagnetic compatibility testing duration changes, and GaN-on-SiC supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding carrier densification timelines and enterprise adoption rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
LTE Emergency Networks Market
Telecommunications
MVNO Market
Telecommunications
South Africa Telecom Market
Telecommunications
Singapore Telecom Market
Telecommunications
Mobile Fronthaul and Backhaul Market
Telecommunications
Asia Pacific Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Austria ICT Market
Telecommunications
US 5G Radio Access Network Professional Services Market
Telecommunications
Mobile Voice Market
Telecommunications
Europe Telecom Expense Management Market
Telecommunications
Cambodia ICT Market
Telecommunications
Peru Telecom Market
Telecommunications
Global International Calling Apps Market
Telecommunications
Nigeria Satellite Communications Market
Telecommunications
Middle East and Africa Telecom Market
Telecommunications
5G Core Market