
 Russia ICT Market | 2026-2036
Russia ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Russia ICT Market Insights
Telecom distribution channels in Russia is fragmenting as state procurement platforms and direct enterprise sales displace traditional reseller networks. Rostelecom PJSC anchors government and rural connectivity through its fiber backbone dominance. MegaFon leverages its mobile infrastructure to compete in enterprise IoT and private network segments. Yandex LLC extends its position into cloud and AI services through vertical integration of data center assets.
Information and communications technology in Russia encompasses hardware systems, software applications, telecommunications infrastructure, and digital services governed by domestic technical regulations mandating FSB-certified encryption and local data processing. The primary purpose is enabling secure digital transformation across state administration, defense-critical industries, and regulated commercial sectors. Software and services together capture the dominant margin pool as import substitution policies redirect spending toward domestic vendors. Cloud Computing is accelerating fastest among solution types as federal agencies migrate workloads to compliant sovereign platforms under data localization requirements. Cybersecurity within the technology category commands premium pricing due to mandatory certification regimes and state-directed critical infrastructure protection.
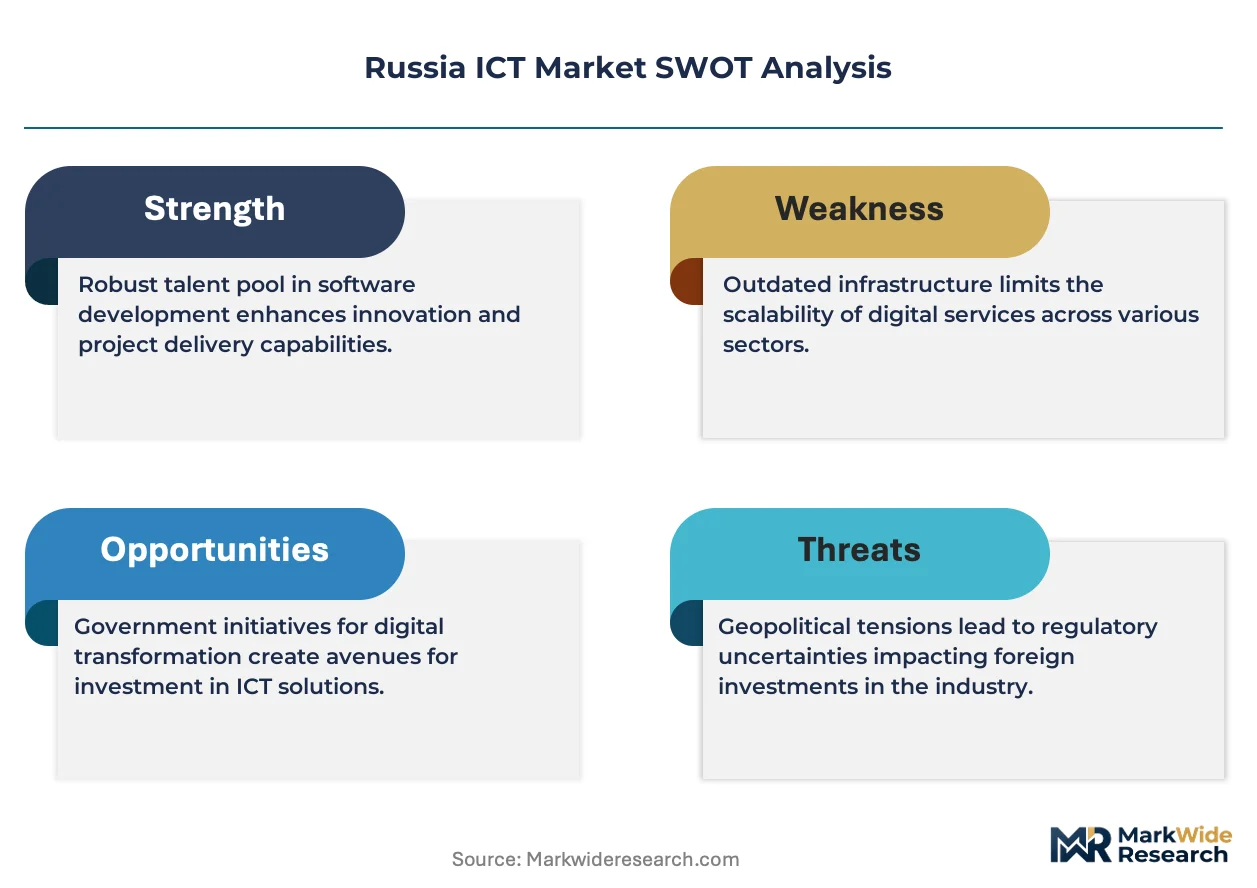
Russia's ICT sector operates under oversight from the Ministry of Digital Development, Communications and Mass Media alongside Roskomnadzor's data localization enforcement and FSB cryptographic compliance mandates. These frameworks restrict foreign cloud participation while creating protected demand channels for domestic hardware and certified software vendors. Stakeholders must monitor regulatory alignment between import substitution directives and evolving technical standards for sovereign infrastructure procurement.
Market Dynamics
Data localization mandates under Russia's sovereign internet framework are redirecting cloud infrastructure investment toward compliant domestic platforms, compressing procurement timelines for federal agencies and defense-critical enterprises.
Growth Catalysts
- Federal Modernization Programs:State-directed digital transformation initiatives are deepening software procurement across public administration, creating protected demand channels for domestic vendors certified under FSB cryptographic standards.
- Sovereign Cloud Infrastructure:Roskomnadzor's enforcement of local data processing requirements is pulling enterprise workloads toward compliant data centers in Moscow and the Central Federal District.
- Import Substitution Policies:Restrictions on foreign hardware and software are redirecting enterprise ICT spending toward domestic semiconductor assembly and locally developed enterprise applications.
Market Restraints
- Semiconductor Supply Concentration:Dependence on imported chip fabrication equipment and advanced process nodes limits domestic server and networking hardware production scalability.
- Capital Intensity of Data Center Buildouts:Sovereign cloud compliance requires redundant facility construction across multiple federal districts, stretching vendor balance sheets.
- Technical Talent Scarcity:Shortages of engineers skilled in FSB-certified encryption implementation and sovereign infrastructure architecture constrain deployment velocity.
Strategic Opportunities
- Far East Connectivity Expansion:Underpenetrated broadband and mobile infrastructure in the Siberian and Far Eastern Federal Districts present greenfield deployment opportunities for fiber and 5G networks.
- Industrial IoT Convergence:Integration of edge computing with operational technology systems in oil, gas, and mining sectors is opening new service revenue pools for systems integrators.
- Cybersecurity Certification Services:Mandatory FSB and FSTEC compliance timelines for critical infrastructure operators are creating recurring demand for audit and implementation consulting.
Industry Challenges
- Legacy System Integration Complexity:Federal agencies and state enterprises operate heterogeneous hardware estates from multiple eras, complicating cloud migration and security patching workflows.
- Compliance Timeline Compression:Accelerated deadlines for data localization and cryptographic certification are forcing vendors to parallelize product development and regulatory approval processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia ICT Market |
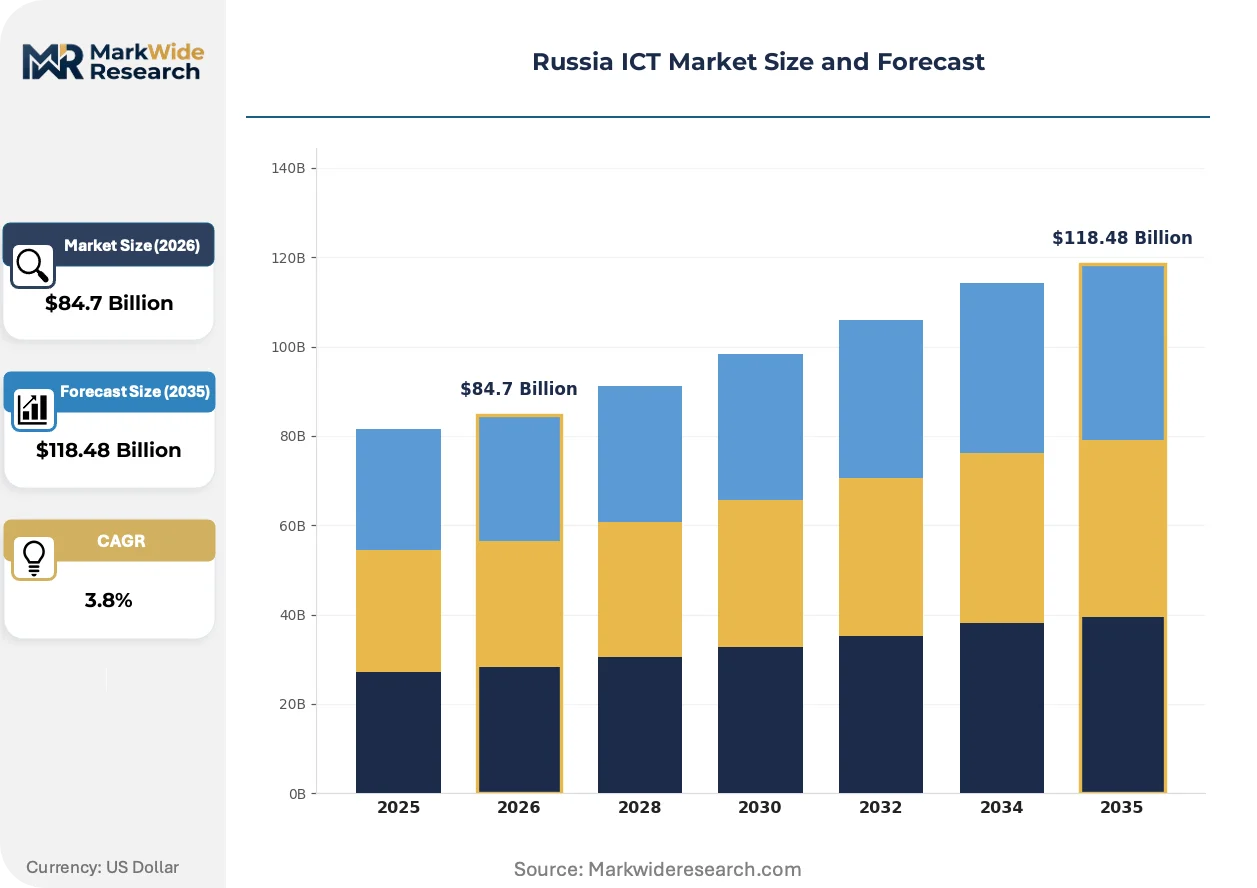
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $118.48 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Software, Hardware, Services, Cloud Computing End User Sector: Government, Healthcare, Education, Retail Deployment Model: On-Premises, Hybrid, Public Cloud, Private Cloud Technology Category: AI, IoT, Cybersecurity, Big Data |
| Companies Covered | Rostelecom PJSC, Mobile TeleSystems PJSC (MTS), MegaFon, Beeline, Yandex LLC, VK, Sber ecosystem businesses, Kaspersky Lab AO, 1C Company LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia ICT Market Trends and Innovations
Artificial intelligence deployment is accelerating across Russian enterprise and government sectors, with sovereign infrastructure requirements shaping how machine learning workloads are hosted and secured.
Edge computing architectures are digitizing operational technology environments in resource extraction and manufacturing facilities. Mining conglomerates and oilfield operators are deploying containerized inference nodes at remote production sites to reduce latency for predictive maintenance algorithms. This distributed topology is compressing the addressable market for centralized cloud processing in industrial verticals.
Roskomnadzor's data localization enforcement is tightening compliance scope for foreign software vendors. The regulator's technical requirements now mandate local encryption key storage and domestic personnel access controls for all platforms processing Russian citizen data. Banking and telecommunications verticals are responding fastest, accelerating vendor replacement cycles to avoid operational license suspensions.
Enterprise buyers are consolidating vendor relationships around integrated platform providers capable of delivering hardware, software, and managed services under unified contractual frameworks. State procurement platforms are displacing traditional reseller networks, compressing channel margins and favoring direct manufacturer engagement. This concentration is most visible in Moscow, where federal procurement authority centralizes decision-making for nationwide technology deployments.
Russia ICT Market Segmentation
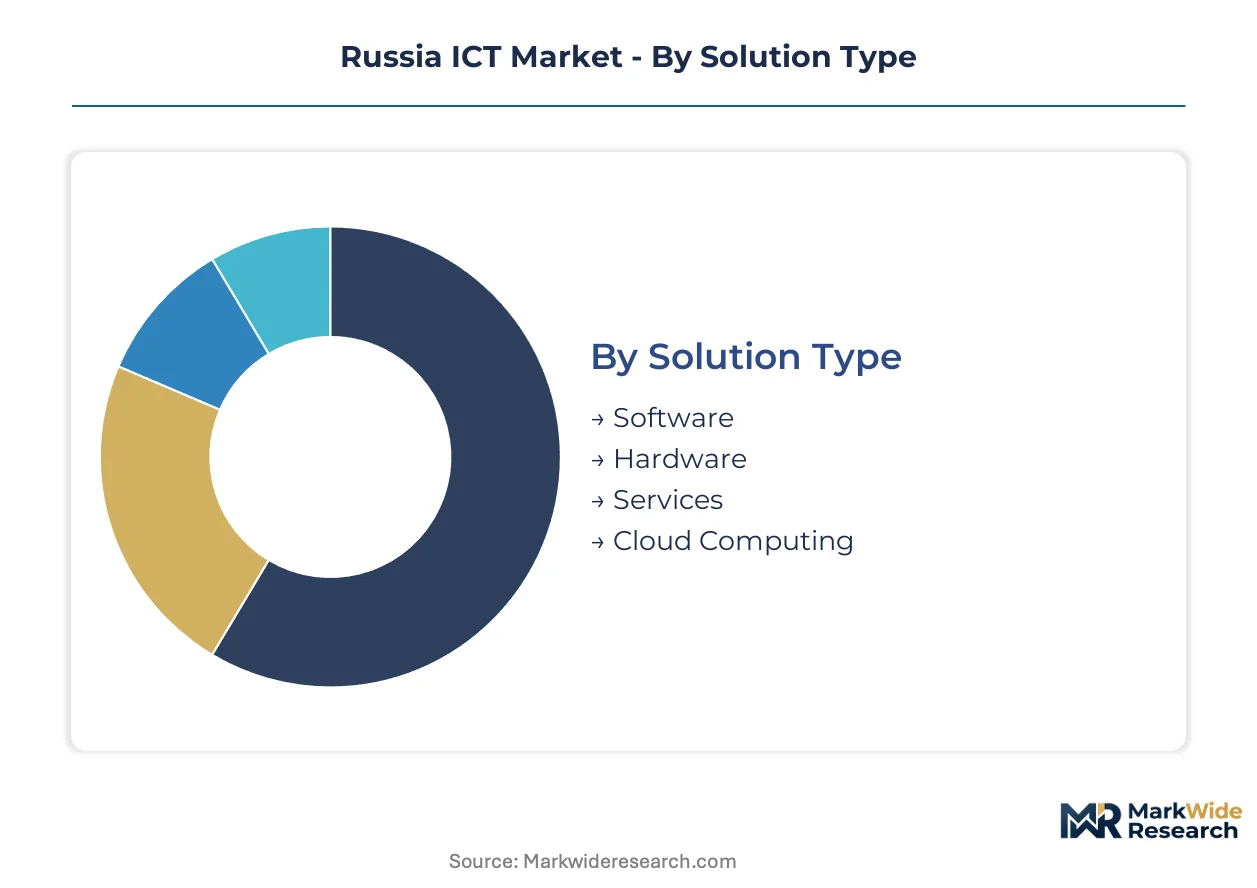
Russia's ICT market segmentation reflects the sovereign internet framework's imprint on procurement patterns. Federal mandates reshape how solution types, deployment models, and technology categories compete for budget allocation across state-directed buyers.
Solution Type:
Software and hardware procurement spans mission-critical administration systems through commodity endpoint devices, with compliance requirements fragmenting vendor eligibility.
- Software:Enterprise applications and operating systems certified under FSB cryptographic standards dominate public-sector tenders. Moscow-based developers capture federal modernization program spending as import substitution policies displace foreign productivity suites.
- Cloud Computing:Sovereign infrastructure platforms compliant with Roskomnadzor data localization mandates attract accelerated enterprise migration. Central Federal District data center operators benefit from proximity to federal procurement authority and fiber backbone concentration.
- Hardware:Servers, networking equipment, and endpoint devices face semiconductor supply constraints despite assembly localization efforts.
- Services:Systems integration and managed services support heterogeneous legacy estates across federal agencies and state enterprises.
Established volume favors Software; emerging adoption favors Cloud Computing.
End User Sector:
Budget concentration and regulatory exposure determine sector attractiveness for ICT vendors navigating certification requirements.
- Government:Federal agencies and regional administrations drive standardized procurement through state platforms. Digital transformation directives mandate encrypted communication systems and sovereign cloud migration for classified and citizen-facing workloads.
- Healthcare:Medical institutions modernize electronic health record infrastructure under mandatory data localization for patient information. Regional hospital networks in the Central and Volga Federal Districts lead deployment timelines.
- Education:Universities and technical colleges upgrade laboratory computing and distance learning platforms.
- Retail:Omnichannel payment systems and supply chain digitization proceed despite consumer spending pressure.
Procurement scale concentrates in Government; compliance urgency accelerates Healthcare.
Deployment Model:
Architecture choices reflect risk tolerance for data sovereignty, latency requirements, and legacy system interdependencies.
- Private Cloud:Dedicated infrastructure satisfies defense-critical and financial sector requirements for physical isolation and encryption key control. Defense enterprises and state banks in Moscow and St. Petersburg anchor demand.
- Hybrid:Workload portability between on-premises systems and compliant cloud platforms appeals to industrial conglomerates with distributed operations. Oil and gas majors balance edge processing needs with centralized analytics.
- On-Premises:Legacy mainframe and proprietary control systems persist in regulated verticals with extended replacement cycles.
- Public Cloud:Limited to non-sensitive workloads as foreign provider restrictions tighten.
Security-sensitive buyers prefer Private Cloud; operational flexibility demands Hybrid.
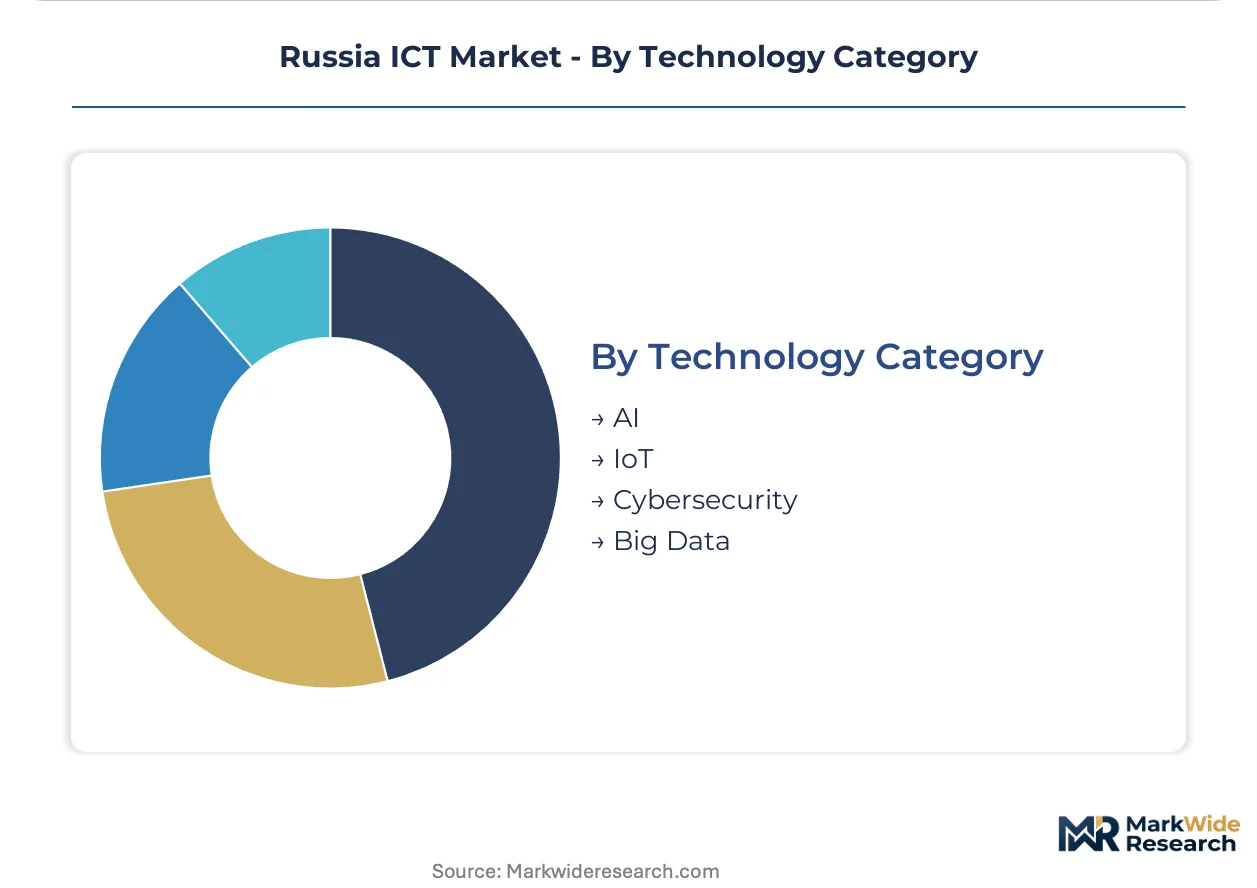
Technology Category:
Investment priority follows state technology sovereignty roadmaps and critical infrastructure protection mandates.
- Cybersecurity:FSB and FSTEC certification services command premium pricing as mandatory compliance deadlines approach. Critical infrastructure operators in energy and telecommunications accelerate audit and implementation spending.
- AI:Machine learning deployment concentrates in Moscow's technology cluster, with sovereign hosting requirements shaping infrastructure procurement. Federal AI development programs channel funding toward domestic algorithm training platforms.
- IoT:Industrial sensor networks and predictive maintenance systems penetrate resource extraction and manufacturing facilities.
- Big Data:Analytics platforms support state statistical services and enterprise business intelligence.
Regulatory pressure elevates Cybersecurity; state funding prioritizes AI.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's federal digital transformation directives channel ICT investment toward Moscow-centered procurement while regional connectivity gaps create deployment opportunities across Siberia and the Far East. The Ministry of Digital Development's modernization programs distribute budget authority unevenly, concentrating vendor engagement in the Central Federal District while mandating infrastructure buildouts elsewhere.
Central Federal District
Moscow anchors sovereign cloud infrastructure deployment under Roskomnadzor's data localization mandates. Federal procurement platforms centralize nationwide technology tenders, pulling systems integrators and certified software vendors toward the capital. The Skolkovo technology cluster hosts domestic AI training platforms and FSB-compliant encryption development.
Northwestern Federal District
St. Petersburg's industrial base drives private cloud demand from defense enterprises and state banks requiring physical infrastructure isolation. The city's port infrastructure supports hardware import channels for data center equipment. Regional telecommunications operators compete for enterprise IoT contracts in manufacturing corridors.
Siberian Federal District
Novosibirsk's academic institutions anchor cybersecurity research and technical talent pipelines for FSB-certified encryption implementation. Underpenetrated broadband infrastructure in remote territories creates greenfield fiber deployment opportunities. Energy sector digitization projects in Kemerovo and Krasnoyarsk drive edge computing adoption.
Far Eastern Federal District
Vladivostok's position as a Pacific gateway shapes cross-border connectivity investments and submarine cable landing infrastructure. The Ministry of Digital Development's eastern digitalization programs target healthcare and education network modernization. Sakhalin and Magadan resource extraction operations deploy industrial IoT for predictive maintenance.
Volga Federal District
Kazan and Nizhny Novgorod manufacturing clusters generate hybrid cloud demand from industrial conglomerates balancing legacy systems with sovereign platform migration. Regional hospital networks accelerate electronic health record infrastructure under mandatory patient data localization. Automotive and aerospace suppliers invest in operational technology security compliance.
Russia ICT Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated platform providers capable of delivering hardware, software, and managed services under unified state procurement frameworks. Traditional reseller networks face margin compression as direct manufacturer engagement displaces channel intermediaries. Two strategic archetypes dominate: telecommunications operators leveraging infrastructure ownership for enterprise cloud capture, and technology conglomerates extending consumer-facing platforms into B2B services. Competitive moves center on data center capacity expansion in Moscow and certification acceleration under FSB cryptographic standards.
Within the telecommunications operator tier, Rostelecom PJSC anchors government and rural connectivity through backbone infrastructure ownership. MegaFon occupies a position competing in enterprise IoT and private network segments. Yandex LLC exemplifies vertical platform extension, leveraging data center assets to capture cloud and AI service demand. These three entities represent distinct strategic paths: state-contracted infrastructure monopoly, mobile-first enterprise diversification, and consumer-to-business platform migration.
| Leading Market Players |
|---|
| Rostelecom PJSC |
| Mobile TeleSystems PJSC (MTS) |
| MegaFon |
| Beeline |
| Yandex LLC |
| VK |
| Sber ecosystem businesses |
| Kaspersky Lab AO |
| 1C Company LLC |
| Others |
Pricing and Supply Chain Analysis
The Trans-Siberian Railway corridor's freight cost dynamics amplify supply concentration effects across Russia's ICT hardware tiers, compressing margins for inland distributors while Moscow-based data center operators capture pricing premiums through proximity to federal procurement authority.
Pricing Analysis
FSB cryptographic certification level creates the primary spread between premium and standard tiers, with certified encryption modules commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects compliance grade, volume commitment scale, and bundled managed service depth. Pricing pressure stems from import substitution mandates accelerating domestic assembly scale-up, narrowing the cost gap with foreign alternatives. State enterprises exhibit lowest price sensitivity due to procurement platform standardization, while regional commercial buyers face acute budget constraints.
Supply Chain Analysis
Extended payment terms from 90 to 180 days now dominate supplier-financing arrangements as domestic semiconductor assemblers stretch working capital to match import substitution timelines. Hardware sourcing draws from China, Taiwan, and South Korea for server components, networking silicon, and storage controllers. Supply chain risk centers on lithography equipment licensing restrictions constraining domestic fabrication scalability. Distribution runs through state procurement platforms consolidating vendor relationships and displacing traditional reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's ICT sector sits at an inflection point where sovereign internet enforcement is compressing vendor replacement cycles and redirecting infrastructure investment toward compliant domestic platforms.
For Market Incumbents: Insulate core cloud and cybersecurity revenue streams by accelerating FSB certification pipelines for next-generation encryption products. Deepen backward integration into captive data center capacity across the Central Federal District to preempt capacity constraints from federal migration timelines. Counter emerging vertical platform threats by locking multi-year managed service contracts with defense-critical enterprises before procurement platform standardization hardens.
For New Entrants and Emerging Players: Establish a beachhead in Far Eastern Federal District connectivity infrastructure where underpenetrated broadband creates greenfield deployment opportunities beyond incumbent fiber footprints. Target industrial IoT integration services for remote resource extraction operations as edge computing adoption outpaces centralized cloud growth in Siberian territories. Lead with sovereign hosting compliance as the primary go-to-market differentiator against foreign-origin alternatives.
For Investors and Strategic Acquirers: Roskomnadzor's tightening data localization enforcement reshapes the acquisition landscape toward certified infrastructure operators with established federal procurement relationships. Long-term viability hinges on regulatory alignment durability rather than technology differentiation alone. Priority acquisition targets include mid-tier systems integrators holding FSTEC audit credentials and regional data center assets. Monitor federal modernization program budget allocation shifts as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FSB Certification Acceleration | Compresses product approval timelines to capture federal procurement windows before competitor compliance. |
| Sovereign Data Center Expansion | Moscow facility buildouts satisfy Roskomnadzor localization mandates for banking and telecom verticals. |
| Industrial IoT Platform Launch | Edge computing integration targets predictive maintenance revenue pools in oil and mining operations. |
| Cybersecurity Audit Services Buildout | Recurring FSTEC compliance consulting captures mandatory critical infrastructure operator spending. |
| Far East Connectivity Infrastructure | Submarine cable and fiber deployments address Ministry of Digital Development eastern digitization mandates. |
Research Methodology
Operator-level perspectives from federal procurement officers, data center infrastructure directors, FSB-certified software developers, and systems integration project managers anchored the qualitative base for this analysis. Primary field engagement combined structured interviews with secondary validation through Roskomnadzor regulatory filings, Ministry of Digital Development program disclosures, and federal contract registry data. Bottom-up vendor revenue aggregation triangulated against top-down budget allocation analysis across state modernization programs.
Scenario-bracketing around regulatory enforcement intensity and semiconductor supply elasticity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include solution type, deployment architecture, end-user sector, and federal district concentration. CAGRs derived from polynomial trend fitting of historical procurement volumes adjusted for policy acceleration effects. Forecast inputs incorporated sovereign cloud migration timelines and critical infrastructure protection mandate compliance deadlines.
Sensitivities concentrate around Roskomnadzor enforcement consistency, domestic semiconductor yield rates, and federal budget allocation continuity for digital transformation programs. Forecasts reflect documented assumptions regarding regulatory stability and import substitution progress. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Norway Telecom Market
Telecommunications
Global 4G LTE Market
Telecommunications
Thailand ICT Market
Telecommunications
Telecom Service Assurance Market
Telecommunications
Explosion Proof Mobile Communication Devices Market
Telecommunications
Virtual CPE (Vcpe) Market
Telecommunications
Global Esim Market
Telecommunications
5G System Integration Market
Telecommunications
Optical Network Terminal (ONT) Equipment Market
Telecommunications
Vietnam Telecom Market
Telecommunications
Oman Telecom Market
Telecommunications
International Wholesale Voice Carrier Market
Telecommunications
Vietnam ICT Market
Telecommunications
TD-LTE Ecosystem Market
Telecommunications
MVNO Market
Telecommunications
Singapore Telecom Market