
 APAC Ballistic Missile Market | 2026-2036
APAC Ballistic Missile Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Ballistic Missile Market Outlook
Chinese state-owned production complexes is recalibrating solid-fuel motor output to match expanded theatre-range requirements. Bharat Dynamics Limited leverages in-house propulsion expertise to anchor India's submarine-launched ballistic missile roadmap. LIG Nex1 sustains precision-guided munition leadership through sustained R&D partnerships with the Republic of Korea Armed Forces.
APAC ballistic missiles are self-propelled strategic weapons employing solid or liquid propellant stages, typically exceeding Mach 5 terminal velocity with circular error probable below 100 metres in precision-guided variants, designed to deliver conventional or special payloads against fixed and mobile targets across theatre ranges. Land-based platforms dominate procurement volumes across the region's territorial defence postures, while hypersonic glide vehicle programs represent the fastest-growing technology segment as China and Australia accelerate testing schedules. Sea-based launch platforms command premium margins due to integration complexity with submarine combat systems and survivability requirements.
China's SAMR oversees state defence contractor certification under national GB standards, while Australia's TGA-equivalent defence export framework shapes technology transfer permissions for BAE Systems and RTX Corporation regional subsidiaries. India's DRDO operates under CEA-mandated strategic project classifications that restrict foreign vendor participation in nuclear-capable systems. Stakeholders must monitor evolving missile technology control regime alignments as regional governments reassess indigenous content thresholds.
Market Dynamics
Hypersonic glide vehicle programs across China and Australia are compressing development timelines and forcing legacy platform obsolescence across Southeast Asian arsenals. Solid-fuel motor miniaturization is simultaneously reducing launch signature while extending range envelopes, altering theatre deterrence calculations.
Growth Catalysts
- Naval Modernization Mandates:Southeast Asian fleets are prioritizing submarine-launched ballistic missile integration under revised maritime domain awareness frameworks. Indonesia and Vietnam are accelerating sea-based deterrent procurement.
- CEA Strategic Project Classifications:India's nuclear-capable system restrictions are channeling domestic engineering capacity toward indigenous propulsion development. DRDO laboratories are expanding solid-fuel research budgets.
- Precision-Guided Munition Standards:Republic of Korea Armed Forces are mandating circular error probable thresholds below 50 metres for new theatre-range acquisitions. LIG Nex1 is scaling dual-mode seeker production.
Market Restraints
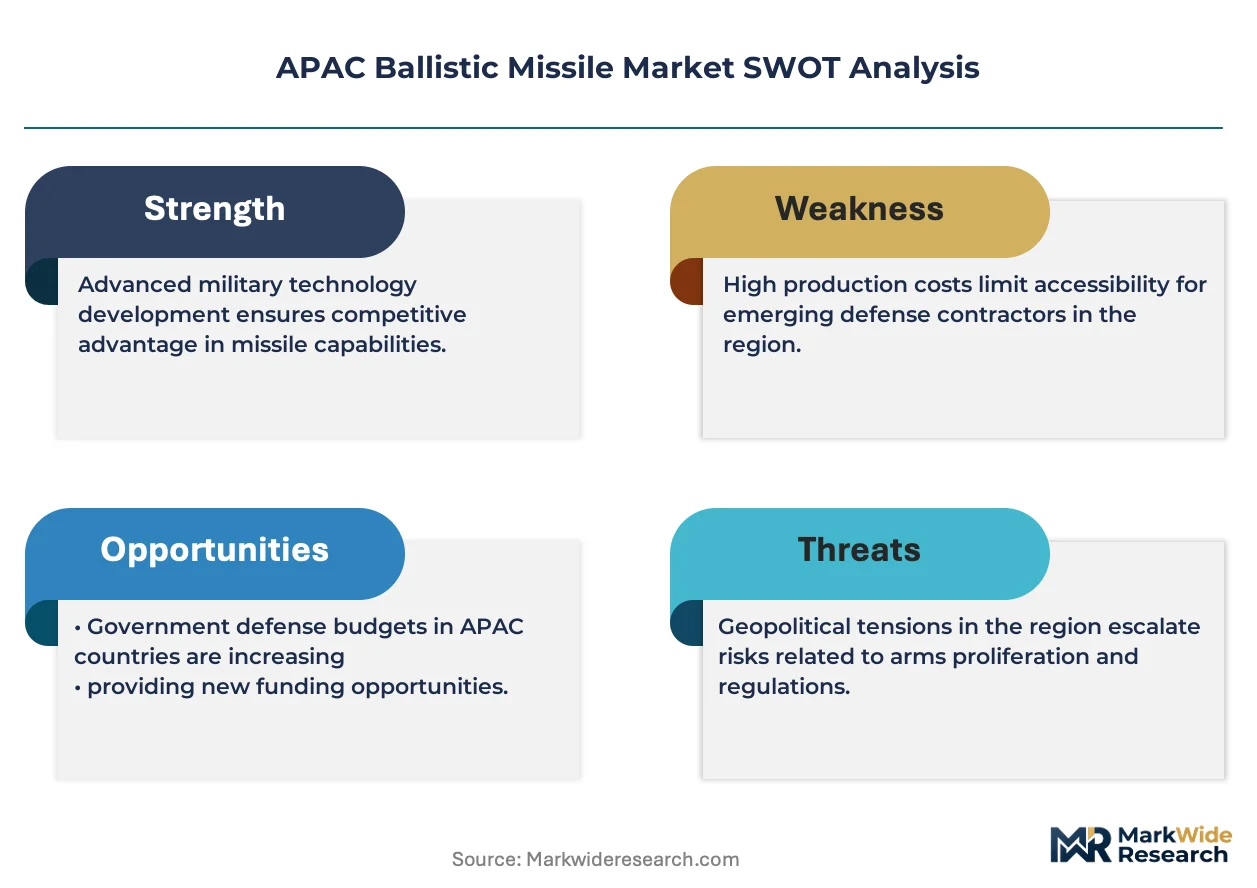
- Rare Earth Magnet Supply Concentration:Guidance system actuator production depends on neodymium-dysprosium supply chains centered in Chinese processing facilities. Non-Chinese motor manufacturers face input cost volatility.
- SAMR State Contractor Certification:GB standards compliance for solid-fuel motor exports creates asymmetric market access. Foreign suppliers encounter extended technical review periods.
- Thermal Protection Material Bottlenecks:Hypersonic nose cone fabrication requires carbon-carbon composites with limited qualified vendors. Australian testing programs are experiencing component lead time extensions.
Strategic Opportunities
- Underpenetrated Philippine Archipelago Defence:The Armed Forces of the Philippines lacks integrated coastal missile systems across its western seaboard. Shore-based anti-ship ballistic missile deployment represents greenfield procurement.
- Dual-Use Space Launch Convergence:Solid-fuel ballistic missile technology is transferring to small satellite launch vehicle programs. Japan's METI is streamlining commercial-military technology transfer permits.
- Indigenous Content Threshold Revisions:India's revised strategic autonomy guidelines are raising local component mandates for foreign joint ventures. Domestic subsystem suppliers are gaining tier-one access.
Industry Challenges
- Hypersonic Aerodynamics Talent Scarcity:Computational fluid dynamics specialists with plasma sheath modeling expertise are concentrated in national laboratories. Private sector recruitment is bidding against classified government programs.
- Submarine Combat System Integration Complexity:Vertical launch system modification for existing hulls requires combat management software re-architecture. Korean and Indian shipyards are experiencing sea trial delays.
- Missile Technology Control Regime Alignment Friction:Divergent national interpretations of Category I and II thresholds are complicating component sourcing. Australian and Japanese exporters face conflicting end-use certification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Ballistic Missile Market |
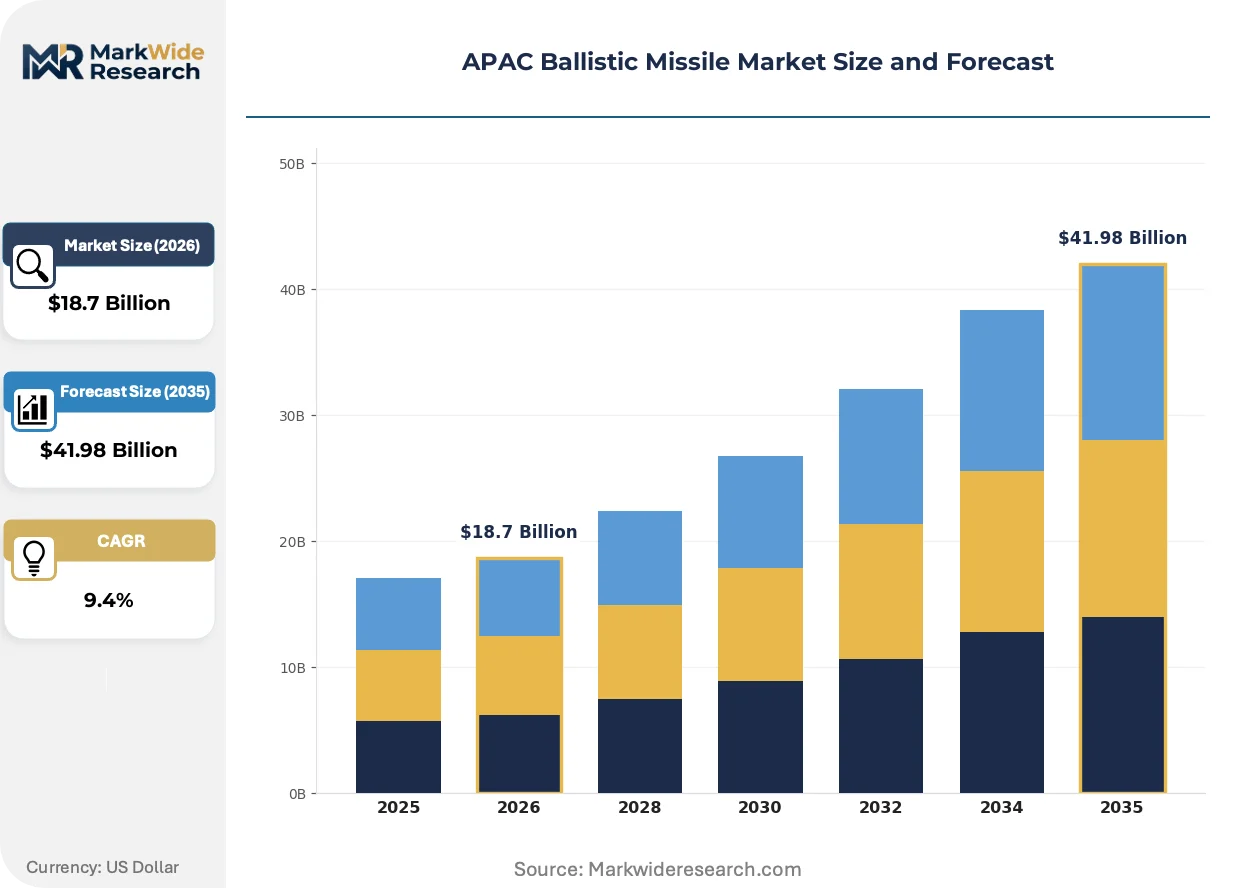
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Conventional, Nuclear, Precision-Guided, Hypersonic Launch Platform: Land-Based, Sea-Based, Air-Launched, Mobile Operator Type: Military, Paramilitary, Government, Allies Role: Offensive, Defensive, Deterrence, Research |
| Companies Covered | Bharat Dynamics Limited, LIG Nex1, China Aerospace Science & Industry Corporation Limited, RTX Corporation, Lockheed Martin Corporation, Defence Research and Development Organisation, Kawasaki Heavy Industries, BAE Systems plc, Mitsubishi Heavy Industries, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Ballistic Missile Market Strategic Shifts
Solid-fuel motor architecture is fragmenting into specialized variants optimized for either rapid reaction or extended range, forcing propulsion suppliers to maintain parallel production lines. This technical divergence is compressing platform lifecycle expectations.
Carbon-carbon composite thermal protection systems are modularizing across Chinese and Australian hypersonic test programs. Defence research agencies are adopting standardized nose cone geometries that interchange across glide vehicle prototypes. This standardization is reducing qualification timelines from multi-year to single-year cycles.
SAMR oversight of state defence contractor certification under GB standards is tightening foreign participation in solid-fuel supply chains. Non-Chinese motor manufacturers are establishing alternative rare earth processing partnerships. Australian and Indian programs are most affected, accelerating domestic magnet alloy development.
Acquisition patterns among Southeast Asian navies are compressing from platform-centric to capability-centric procurement. Republic of Korea shipyards are displacing European suppliers in submarine combat system integration contracts. This shift is most visible in Indonesia's revised fleet modernization schedule.
APAC Ballistic Missile Market Segmentation
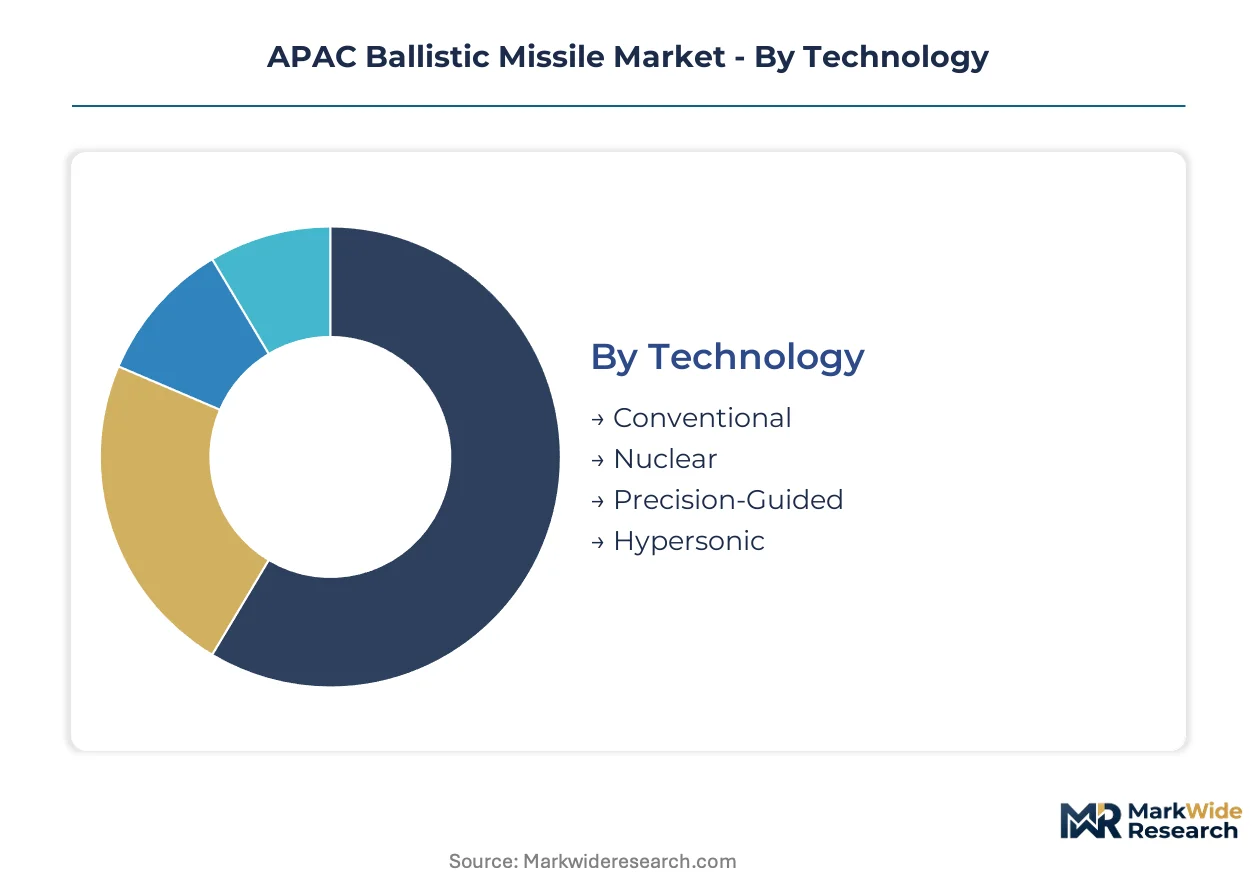
APAC ballistic missile procurement patterns diverge sharply across technology tiers and operational roles, with defence ministries calibrating platform choices against theatre-range requirements and indigenous production capacity. Segmentation reveals where budget concentration aligns with strategic priority versus where legacy systems face replacement pressure.
Technology:
Customization intensity spans from off-the-shelf conventional designs to bespoke hypersonic prototypes requiring national laboratory involvement.
- Conventional:Solid and liquid propellant configurations deliver conventional warheads at sub-hypersonic velocities. Demand concentrates in Southeast Asian land-based deterrent programs where cost-per-round economics dominate procurement calculus.
- Nuclear:Specialized delivery vehicles with hardened electronics and enhanced radiation shielding meet strategic force requirements. India's DRDO and Pakistan's NESCOM anchor regional development under strict national security classifications that exclude foreign vendor participation.
- Precision-Guided:Terminal guidance packages achieve circular error probable below 100 metres through dual-mode seekers.
- Hypersonic:Glide vehicles and scramjet-powered systems exceed Mach 5 sustained flight with manoeuvring re-entry profiles.
Most installed capacity flows through Conventional systems. Expansion is steepest in Hypersonic programs across China and Australia.
Launch Platform:
Platform selection tracks survivability requirements against integration complexity, with maritime nations prioritizing sea-based concealment over land-based responsiveness.
- Land-Based:Fixed silo and mobile transporter-erector-launcher configurations dominate territorial defence postures. South Korea and Taiwan are accelerating mobile launcher procurement to enhance launch-site unpredictability against counterforce targeting.
- Sea-Based:Submarine vertical launch systems and surface vessel canister launchers command premium procurement margins. Integration with combat management software creates extended qualification timelines for Indonesian and Vietnamese naval modernization programs.
- Air-Launched:Strategic bomber and tactical aircraft carriage extends standoff range through altitude-velocity boost.
- Mobile:Road-mobile and rail-mobile platforms prioritize launch-site ambiguity over reaction speed.
Land-Based platforms absorb the largest share of regional procurement budgets. Sea-Based systems are climbing the fastest as Southeast Asian fleets expand submarine capabilities.
Operator Type:
End-user classification determines funding source transparency and technology access tier, with allied nation sales triggering multilateral control regime reviews.
- Military:Formal armed forces branches operate the preponderance of regional ballistic missile inventory. Republic of Korea Armed Forces and Japan Self-Defense Forces are consolidating precision-guided munition standards across service branches.
- Paramilitary:Coast guard and internal security forces field short-range coastal defence variants. China's Maritime Safety Administration and Vietnam's Maritime Police are acquiring shore-based anti-ship ballistic systems under dual-use justifications.
- Government:Civilian space agencies and research institutes operate sounding rocket and technology demonstrator programs.
- Allies:Foreign military sales and technology transfer arrangements extend regional capabilities to partner nations.
Military operators control the dominant share of active inventory. Paramilitary acquisition is expanding most quickly as maritime law enforcement agencies assume coastal defence roles.
Role:
Operational purpose shapes platform specification divergence, with deterrence-optimized systems trading responsiveness for survivability.
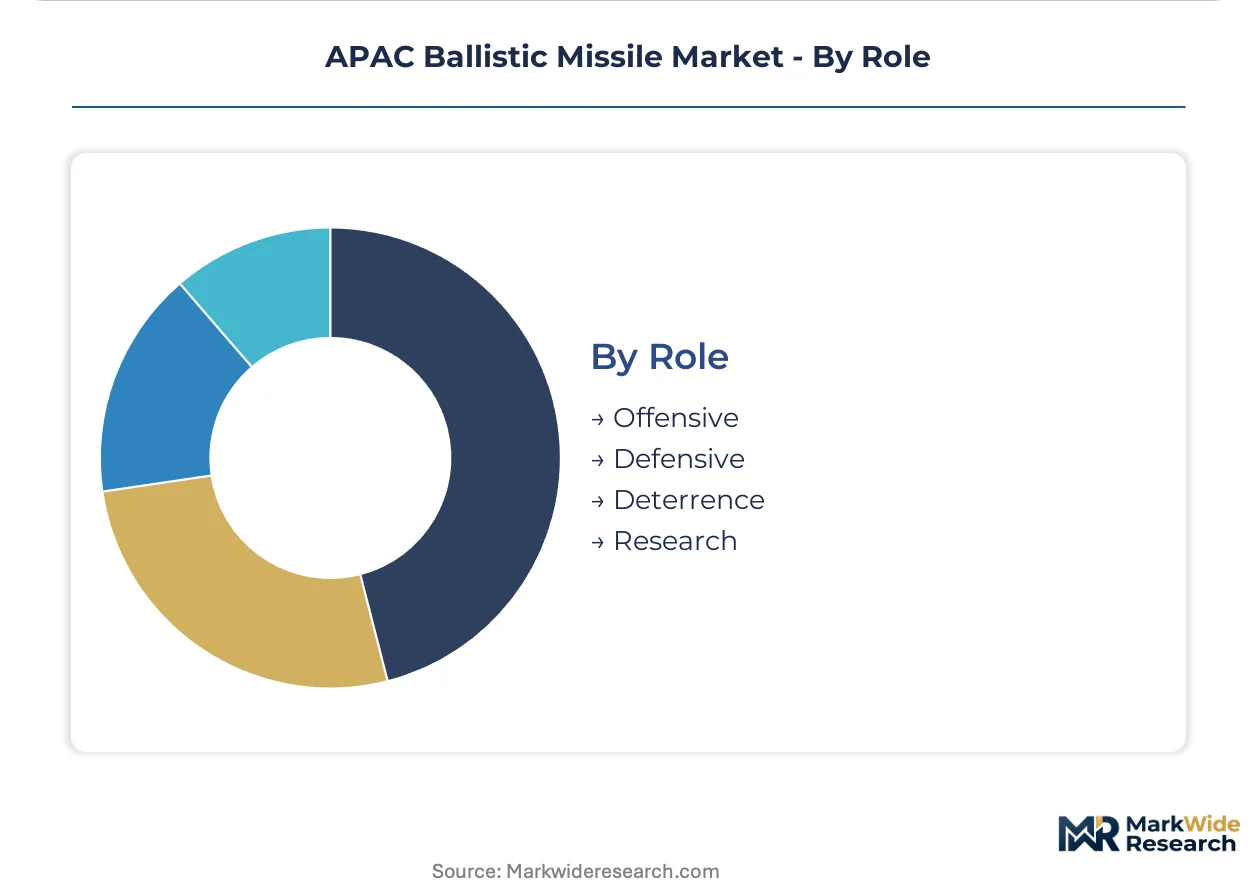
- Offensive:Theatre-range strike systems prioritize payload fraction and penetration aids against integrated air defence networks. China's Rocket Force maintains the region's largest offensive inventory with expanded conventional precision-strike mandates.
- Defensive:Anti-ballistic missile interceptors and counter-battery systems require accelerated reaction timelines. South Korea's Korea Air and Missile Defense system is integrating indigenous interceptors with US-supplied early warning architecture.
- Deterrence:Strategic force visibility and second-strike assurance drive platform survivability investments.
- Research:Technology demonstrators and test vehicles advance propulsion and guidance architectures.
Offensive systems represent the largest committed procurement volume. Defensive roles are gaining share fastest as regional missile defence architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Rocket Force maintains the region's largest offensive inventory while India's DRDO accelerates indigenous submarine-launched development; both trajectories diverge from Southeast Asia's procurement concentration in coastal defence systems.
China
State-owned production complexes are recalibrating solid-fuel motor output to match expanded theatre-range requirements. SAMR oversees state defence contractor certification under national GB standards that restrict foreign vendor participation. Beijing-Tianjin-Hebei clusters concentrate hypersonic glide vehicle prototyping with modular carbon-carbon composite thermal protection systems.
India
CEA-mandated strategic project classifications channel domestic engineering capacity toward indigenous propulsion development under revised strategic autonomy guidelines. DRDO laboratories are expanding solid-fuel research budgets with raised local component mandates for foreign joint ventures. Bengaluru and Hyderabad anchor submarine-launched ballistic missile roadmap execution with tier-one domestic subsystem supplier access.
South Korea
Republic of Korea Armed Forces are mandating circular error probable thresholds below 50 metres for new theatre-range acquisitions. LIG Nex1 sustains precision-guided munition leadership through sustained R&D partnerships with military branches. Seoul Capital Area concentration drives dual-mode seeker production scaling for precision-guided variants.
Australia
TGA-equivalent defence export frameworks shape technology transfer permissions for BAE Systems and RTX Corporation regional subsidiaries. Hypersonic testing programs are experiencing carbon-carbon composite component lead time extensions. Woomera test ranges and Adelaide defence clusters accelerate scramjet-powered system development schedules alongside AUKUS alignment.
Indonesia
Naval modernization programs prioritize submarine-launched ballistic missile integration under revised maritime domain awareness frameworks. Republic of Korea shipyards are displacing European suppliers in submarine combat system integration contracts. Surabaya naval facilities and Jakarta defence procurement offices coordinate extended qualification timelines for vertical launch system modifications.
APAC Ballistic Missile Market Competitive Environment
Chinese state-owned producers anchor one tier; Indian and Korean specialists hold differentiated positions in precision-guided and indigenous development segments. The vendor base structures around consolidated state-controlled entities alongside fragmented domestic champions serving national strategic autonomy mandates. Three archetypes dominate: vertically integrated state conglomerates with captive supply chains, precision-guided munition specialists with military R&D partnerships, and foreign defence contractors operating through regional technology transfer arrangements. Competitive moves concentrate on strategic partnerships for combat system integration and geographic expansion through offset-driven joint ventures.
Within the state conglomerate tier, China Aerospace Science & Industry Corporation Limited exemplifies vertically integrated production architecture spanning solid-fuel motors through terminal guidance packages. Among precision-guided specialists, LIG Nex1 occupies a position representing sustained Republic of Korea Armed Forces collaboration on dual-mode seeker development. Bharat Dynamics Limited anchors the indigenous propulsion archetype under India's CEA strategic project classifications, exemplifying tier-one domestic supplier access for nuclear-capable system roadmaps.
| Leading Market Players |
|---|
| Bharat Dynamics Limited |
| LIG Nex1 |
| China Aerospace Science & Industry Corporation Limited |
| RTX Corporation |
| Lockheed Martin Corporation |
| Defence Research and Development Organisation |
| Kawasaki Heavy Industries |
| BAE Systems plc |
| Mitsubishi Heavy Industries |
| Others |
Value Chain & Pricing Dynamics
Solid-fuel motor miniaturization across Chinese and Korean production lines is simultaneously compressing unit costs and concentrating supplier tiers, as foundries capable of precision-casting high-performance grains capture disproportionate pricing power from legacy liquid-fuel assemblers.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for precision-guided variants, with LIG Nex1 scaling dual-mode seeker output under fixed-price development contracts. Procurement stratifies across premium sea-based systems with integrated combat management software, standard land-based mobile launchers, and economy fixed-silo configurations for territorial defence postures. Price differentiation hinges on certification grade under SAMR GB standards and indigenous content thresholds mandated by India's CEA classifications. Cost compression in conventional solid-fuel segments is intensifying because Indonesian and Vietnamese naval programs are consolidating orders for submarine vertical launch system modifications. Paramilitary operators across Southeast Asian maritime law enforcement agencies exhibit highest price sensitivity, while strategic force commands in China and India prioritize survivability specifications over per-unit economics.
Supply Chain Analysis
Regional distribution centers in Singapore and Yokohama anchor hub-and-spoke patterns for carbon-carbon composite thermal protection components, with qualified vendors concentrated in China, Japan, and Australia. Rare earth magnet supply for guidance system actuators draws from Chinese neodymium-dysprosium processing facilities, creating single-source vulnerability for non-Chinese motor manufacturers. Australian hypersonic testing programs and Indian DRDO laboratories experience component lead time extensions due to thermal protection material bottlenecks. Distribution runs through defence procurement offices coordinating extended qualification timelines for vertical launch system combat software re-architecture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-fuel motor architecture specialization is expanding margin capture for suppliers mastering rapid-reaction grain formulations, while hypersonic thermal protection standardization opens premium-tier pricing for qualified carbon-carbon composite vendors.
For Market Incumbents: Cement captive supply of rare earth magnet alloys through backward integration into Australian and Indian domestic processing partnerships, insulating against SAMR export certification delays. Lock in long-term combat system integration contracts with Republic of Korea shipyards before European suppliers re-enter Indonesian and Vietnamese naval modernization programs. Prioritize R&D investment in modular nose cone geometries that interchange across glide vehicle prototypes, compressing competitor qualification timelines. For New Entrants and Emerging Players: Enter via shore-based anti-ship ballistic missile deployment across the Philippine western seaboard, where the Armed Forces of the Philippines lacks integrated coastal missile systems and procurement offices actively solicit greenfield proposals. Target precision-guided munition subsystems for Republic of Korea Armed Forces acquisitions mandating circular error probable thresholds below 50 metres. Pursue dual-use space launch convergence through Japan's METI streamlined commercial-military technology transfer permits, leveraging solid-fuel ballistic missile heritage for small satellite launch vehicle programs. For Investors and Strategic Acquirers: Roll-up economics work for precision-guided seeker specialists because Republic of Korea Armed Forces consolidation of munition standards across service branches is concentrating procurement volumes with dual-mode capability vendors. Five-to-ten year viability favors tier-one domestic subsystem suppliers gaining access under India's revised strategic autonomy guidelines. Watch for CEA-mandated local component threshold revisions as inflection indicator for foreign joint venture restructuring and domestic supplier elevation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Processing | Australian and Indian programs reduce neodymium-dysprosium supply chain dependence on Chinese SAMR-certified facilities. |
| Dual-Mode Seeker Production Scale-Up | LIG Nex1 captures Republic of Korea Armed Forces precision-guided munition procurement under 50-metre circular error probable mandates. |
| Hypersonic Thermal Protection Standardization | Chinese and Australian defence research agencies reduce qualification timelines from multi-year to single-year cycles through modular carbon-carbon composite geometries. |
| Submarine Combat System Integration Partnership | Republic of Korea shipyards displace European suppliers in Indonesian and Vietnamese naval modernization vertical launch system contracts. |
| Indigenous Content Threshold Compliance | Domestic subsystem suppliers in Bengaluru and Hyderabad gain tier-one access under India's CEA strategic project classification revisions. |
Study Parameters
Coverage spans China, India, South Korea, Australia, Indonesia, Vietnam, Japan, and the Philippines, with primary inputs from each defence procurement office and national laboratory cluster. Interviews with DRDO propulsion directors, LIG Nex1 precision-guided munition program managers, Republic of Korea Armed Forces acquisition officers, SAMR certification auditors, and Indonesian naval shipyard engineers combined with secondary validation from customs trade data, national defence budget disclosures, CEA strategic project classifications, and SAMR GB standard filings. Bottom-up platform procurement tallies triangulated against top-down defence expenditure allocations.
Granularity-level modeling captured technology tier, launch platform, operator type, and operational role dimensions across the projection horizon. Conventional, nuclear, precision-guided, and hypersonic segments were modeled with separate propulsion architecture cost curves. Land-based, sea-based, air-launched, and mobile platform categories incorporated distinct integration complexity premiums. CAGRs derived from defence budget trajectory analysis, procurement schedule acceleration factors, and indigenous content mandate implementation timelines. Hypersonic glide vehicle program expansion and solid-fuel motor miniaturization diffusion curves served as primary demand-side forecast inputs.
Inputs from Chinese state-owned production complex disclosures and Indian parliamentary defence committee reports were available through the study window; gaps in Pakistani NESCOM and North Korean program specifics introduce uncertainty bands around nuclear-capable system estimates. Forecasts reflect documented assumptions regarding CEA strategic autonomy guideline implementation pace and AUKUS technology transfer alignment. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Light Weapons Market
Weapons and Ammunition
Ammunition Handling Systems Market
Weapons and Ammunition
Space Weapons Market
Weapons and Ammunition
Shoulder Fixed Weapons Market
Weapons and Ammunition
North America Weapon Night Sight Market
Weapons and Ammunition
Less Lethal Ammunition Market
Weapons and Ammunition
Airborne Weapon System Market
Weapons and Ammunition
Weapons Release System Market
Weapons and Ammunition
Particle Beam Directed Energy Weapon Market
Weapons and Ammunition
Sports Shotgun Market
Weapons and Ammunition
Ballistic Missile Market
Weapons and Ammunition
US Small Caliber Ammunition Market
Weapons and Ammunition
Europe Ammunition Market
Weapons and Ammunition
Global Rockets and Missiles Market
Weapons and Ammunition
Smart Bullets Market
Weapons and Ammunition
Mortar Artillery System Market