
 Shotgun Shell Market | 2026-2036
Shotgun Shell Market Size, Share, and Industry Trends Forecast 2026-2036
Shotgun Shell Market Analysis
Multi-source procurement of propellants and primers is restructuring supply relationships across the shotgun shell industry. Vista Outdoor Inc. leverages captive production of Federal Premium lines to control input costs and batch consistency. Olin Corporation anchors its Winchester operations through integrated brass and chemical manufacturing. Remington Ammunition competes by specializing in regional distribution density across rural retail networks.
A shotgun shell is a self-contained cartridge comprising a plastic or paper hull, a metallic base, propellant charge, primer, and shot payload or single projectile, engineered to function in smoothbore firearms for hunting, sport, or defensive applications. Buckshot and slug configurations command premium positioning due to law enforcement qualification protocols and tactical training cycles. Steel and bismuth material segments are gaining shelf space as waterfowl zones enforce non-toxic shot compliance. Hunting application volumes remain structurally dominant, though sport shooting channels exhibit faster turnover velocity through recurring competitive consumption.
EPA regulations on lead deposition in wetlands, ATF licensing requirements for interstate ammunition transfers, and state wildlife agency non-toxic zone designations collectively constrain formulation choices and distribution logistics. The EU REACH framework and F-Gas Regulation extend compliance obligations for exporters serving European hunters and security agencies. Stakeholders must monitor evolving material bans and qualification standards to align R&D allocation with enforceable procurement specifications.
Market Dynamics
Lead-free material mandates from the EPA and state wildlife agencies are forcing wholesale reformulation of shot payloads, redirecting manufacturing investment toward steel and bismuth alternatives while compressing margins on legacy lead product lines.
Growth Catalysts
- Sport shooting expansion:Competitive clay disciplines and recreational shooting clubs are driving recurring ammunition consumption with predictable volume patterns.
- EPA wetland regulations:Federal and state-level non-toxic zone designations are mandating lead-free alternatives, creating compliant product demand.
- Law enforcement training cycles:Buckshot and slug qualification protocols sustain institutional procurement volumes independent of consumer seasonality.
Market Restraints
- Propellant supply concentration:Nitrocellulose and specialty chemical inputs face sourcing bottlenecks from limited qualified suppliers.
- Non-toxic material cost premiums:Steel and bismuth shot production carries 40-60% higher raw material costs versus lead equivalents.
- ATF interstate transfer licensing:Ammunition distribution across state lines requires federal firearms licensing, constraining logistics flexibility.
Strategic Opportunities
- European export alignment:REACH and F-Gas Regulation compliance investments open access to EU hunting and security agency markets.
- Reloading component sales:Component hulls, primers, and wads serve hobbyist self-loaders through specialty retail channels.
- Biodegradable wad technology:Water-soluble or compostable wad materials address marine plastic accumulation concerns.
Industry Challenges
- Ballistic engineer scarcity:Specialized expertise in non-toxic shot patterning and propellant chemistry commands premium compensation.
- Legacy equipment retooling:Converting lead shot production lines to steel or bismuth requires substantial capital expenditure and downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shotgun Shell Market |
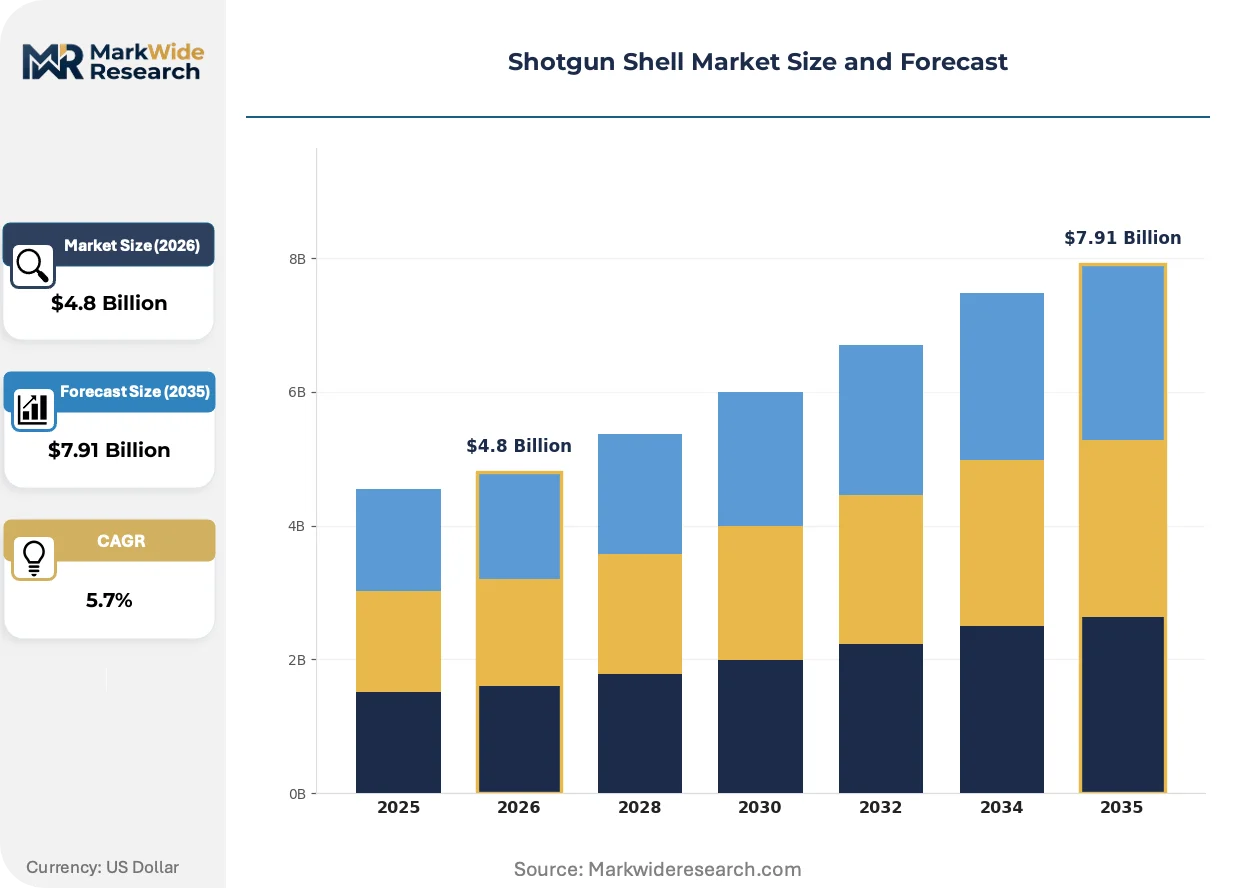
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Birdshot, Buckshot, Slug, Specialty Loads Material: Lead, Steel, Bismuth, Copper Application: Hunting, Sport Shooting, Self-Defense, Law Enforcement Distribution Channel: Online Retail, Sporting Goods Stores, Gun Shops, Wholesale |
| Companies Covered | Vista Outdoor Inc. (Federal Premium), Olin Corporation (Winchester), Remington Ammunition, FN HERSTAL, Fiocchi Munizioni, BAE Systems, CBC Global Ammunition, Kent Cartridge, RUAG Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shotgun Shell Market Emerging Trajectories
Formulation chemistry and manufacturing automation are absorbing capital allocation as producers navigate material bans and quality consistency requirements. Three developments are restructuring competitive capabilities.
High-density bismuth-tin alloys are absorbing market share in premium waterfowl segments where steel performance proves inadequate. Hunters in coastal flyway states are adopting these loads despite price premiums. The technology is absorbing R&D budgets previously directed toward incremental lead improvements.
EPA lead deposition rules and EU REACH substance restrictions are converging to eliminate cross-Atlantic regulatory arbitrage. Manufacturers serving both markets must unify formulation standards rather than maintaining separate product lines. Waterfowl ammunition faces the most stringent compliance timelines.
Direct-to-consumer subscription models are bypassing traditional rural retail distribution for recurring sport shooters. Online platforms with automated reorder algorithms capture volume from competitive disciplines with predictable consumption rates. This pattern concentrates in states with streamlined ammunition shipping regulations.
Shotgun Shell Market Segmentation
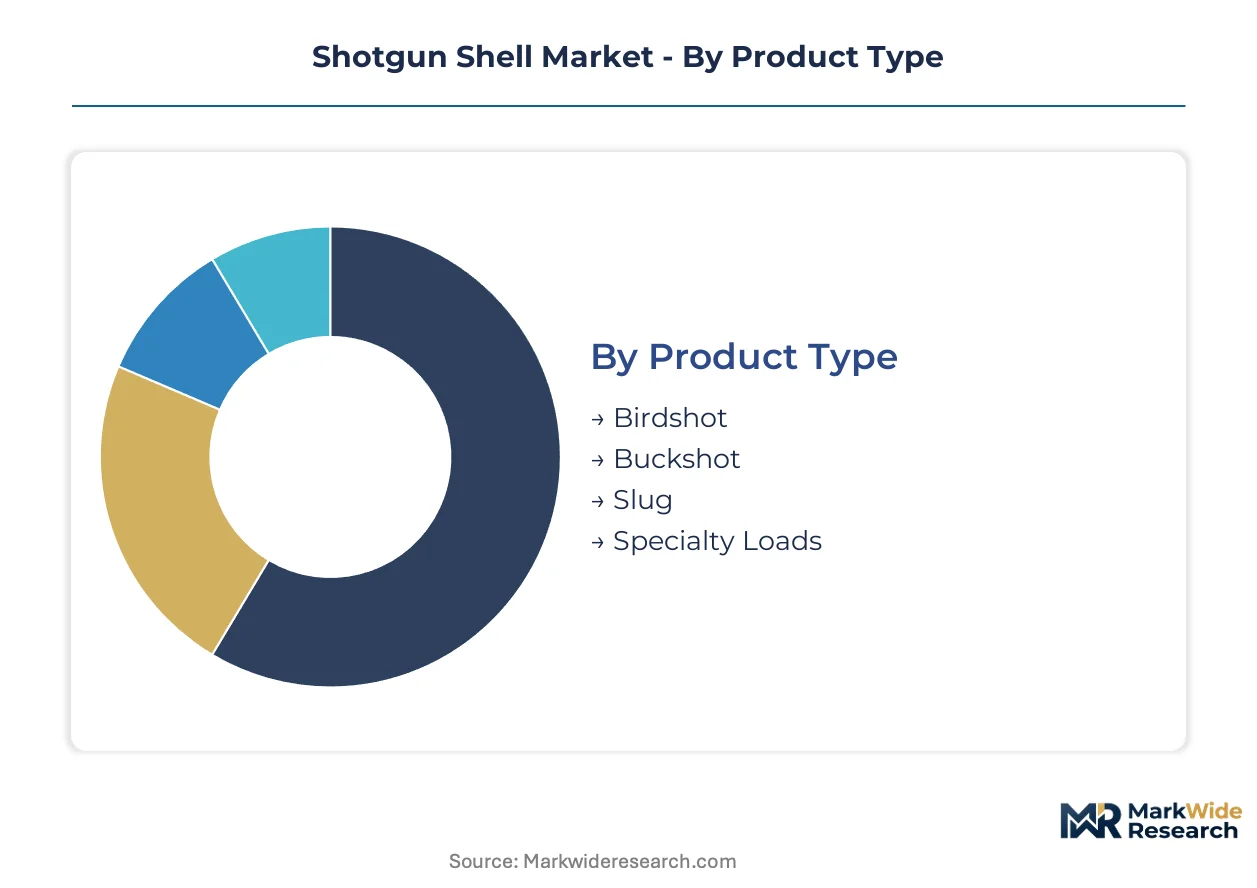
Shotgun shell manufacturers configure production lines around distinct performance specifications, material compliance tiers, and channel economics. Each segmentation axis carries implications for formulation chemistry, regulatory exposure, and margin structure.
Product Type:
Payload configuration determines ballistic performance, manufacturing complexity, and end-use pricing power across the market.
- Birdshot:Multiple small-diameter pellets dispersed through a shot cup deliver pattern density optimized for flying game. Waterfowl hunters in coastal states drive volumes where EPA non-toxic mandates apply. This configuration absorbs the highest absolute unit sales but faces margin compression from steel substitution requirements.
- Buckshot:Larger spherical pellets arranged in graduated sizes penetrate defensive barriers and meet law enforcement qualification standards. Tactical training cycles and home defense procurement sustain premium positioning independent of hunting seasonality. Agencies specify pellet count and velocity windows that constrain supplier qualification.
- Slug:Single solid projectiles deliver rifled or smoothbore accuracy for deer hunting and tactical applications. Demand concentrates in Midwestern states with slug-only deer regulations.
- Specialty Loads:Less-lethal, breaching, and signal cartridges serve narrow institutional and industrial niches. Volumes remain constrained by procurement bureaucracy.
Mature deployment sits with birdshot configurations. Newer deployment is concentrated in specialty loads for institutional security applications.
Material:
Shot composition has become the primary axis of regulatory compliance and manufacturing capital allocation.
- Lead:Traditional density and malleability deliver superior pattern performance at lower cost. Remaining demand concentrates in upland game and target shooting outside restricted zones. EPA wetland deposition rules are compressing addressable market scope.
- Steel:Iron-based shot satisfies federal waterfowl regulations at substantially lower material cost than alternatives. Pattern degradation versus lead drives ongoing R&D in shot cup and buffering systems. Production volumes are climbing fastest as manufacturers convert legacy lead lines.
- Bismuth:Tungsten-alloyed formulations approach lead density without toxicity, commanding price premiums in premium waterfowl segments. Hunters in restrictive flyway states absorb cost differentials for performance equivalence.
- Copper:Solid copper slugs and buckshot serve lead-free defensive and hunting applications where barrier penetration matters. Niche positioning reflects material cost and machining complexity.
Steel shot carries the steepest expansion trajectory as regulatory deadlines approach. Bismuth maintains premium positioning where performance gaps persist.
Application:
End-use context shapes procurement patterns, customer concentration, and product specification rigor.
- Hunting:Seasonal license issuance drives predictable demand spikes aligned with migratory patterns and state openers. Waterfowl and upland segments diverge sharply on material compliance requirements.
- Sport Shooting:Competitive clay disciplines generate recurring consumption through registered shoots and club practice volumes. This application expands most quickly through subscription replenishment models.
- Self-Defense:Home protection purchasers prioritize terminal performance and reliability over cost minimization. Buckshot and slug configurations dominate with minimal price sensitivity.
- Law Enforcement:Agency qualification protocols and training cycles institutionalize procurement volumes. Buckshot pattern standards and slug barrier penetration specifications limit qualified suppliers.
Hunting maintains volume leadership. Sport shooting channels are gaining share fastest through recurring competitive consumption.
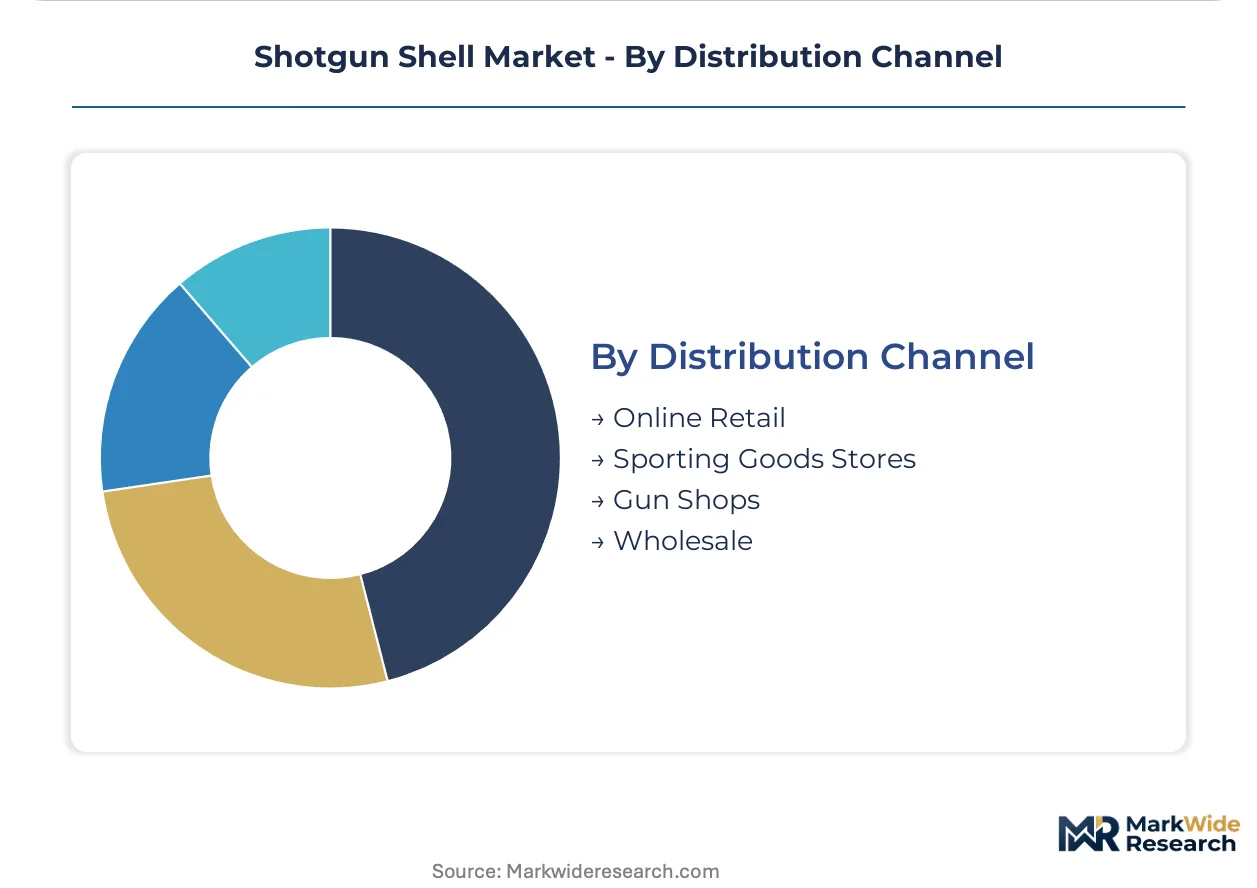
Distribution Channel:
Channel selection determines customer access costs, regulatory compliance burden, and inventory velocity.
- Online Retail:Direct-to-consumer platforms with automated reorder algorithms capture sport shooter loyalty. ATF licensing requirements for interstate ammunition transfers constrain operational flexibility.
- Sporting Goods Stores:Big-box and specialty retailers aggregate seasonal hunters and recreational shooters. Shelf space allocation favors established brands with promotional support.
- Gun Shops:Federally licensed dealers provide regulated transfer services and technical consultation. Rural density sustains regional procurement patterns.
- Wholesale:Distributors aggregate volume for institutional, commercial, and international customers. Concentrated buyer power pressures margin structures.
Wholesale channels anchor institutional procurement. Online retail is expanding most quickly where state shipping regulations permit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nitrocellulose propellant production concentrates in the United States and Germany, anchoring supply security for NATO-aligned ammunition manufacturers. Shot payload foundries in Italy and Brazil serve regional hunting demand with lead-free formulation capabilities.
United States
Waterfowl hunting license issuance in coastal flyway states drives steel and bismuth shell procurement volumes. EPA wetland deposition rules and state wildlife agency non-toxic zone designations mandate lead-free alternatives in federal refuges. Manufacturing clusters in Missouri and Arkansas convert legacy lead production lines to steel shot capacity.
Germany
Competitive clay shooting clubs sustain recurring sport ammunition consumption through registered tournament circuits. EU REACH substance restrictions and F-Gas Regulation compliance obligations unify formulation standards for exporters. RUAG Group operations in Thuringia anchor institutional procurement for European security agencies.
Italy
Upland game hunting traditions in Tuscany and Piedmont maintain demand for premium birdshot configurations. ECHA chemical authorization requirements constrain propellant chemistry choices for ammunition exports. Fiocchi Munizioni's manufacturing presence in Lecco exemplifies integrated brass and chemical production capabilities.
Brazil
Rural sport shooting clubs and competitive clay disciplines expand ammunition consumption in São Paulo and Minas Gerais states. ANVISA chemical regulations and environmental agency shot deposition rules redirect formulation investments toward steel alternatives. CBC Global Ammunition's production facilities in São Paulo state serve Latin American hunting and security markets.
United Kingdom
Game shooting estates in Scotland and northern England sustain seasonal demand for high-performance birdshot. Health and Safety Executive chemical regulations and impending lead shot phase-out mandates accelerate steel and bismuth adoption. Kent Cartridge's manufacturing operations in Kent county specialize in premium waterfowl ammunition for restrictive flyway compliance.
Shotgun Shell Market Vendor Landscape
Global majors compete with regional champions across propellant integration and distribution density. The vendor base organizes around three tiers: integrated chemical manufacturers controlling nitrocellulose supply, specialized ammunition brands leveraging regional retail networks, and state-affiliated producers serving institutional security contracts. Consolidation pressures concentrate among mid-scale fabricators lacking captive chemical inputs. Dominant competitive moves include backward integration into brass and propellant manufacturing and geographic expansion through distributor acquisition.
Among North American integrated manufacturers, Vista Outdoor Inc. and Olin Corporation occupy positions exemplifying captive supply chain control over Federal Premium and Winchester product lines respectively. Remington Ammunition represents the regional distribution density archetype, anchoring rural retail network penetration. These three structures illustrate the strategic choice between chemical integration and channel specialization.
| Leading Market Players |
|---|
| Vista Outdoor Inc. (Federal Premium) |
| Olin Corporation (Winchester) |
| Remington Ammunition |
| FN HERSTAL |
| Fiocchi Munizioni |
| BAE Systems |
| CBC Global Ammunition |
| Kent Cartridge |
| RUAG Group |
| Others |
Supply Flow & Price Mechanics
Law enforcement agency procurement programs concentrate buyer power in institutional buckshot and slug contracts, anchoring premium pricing for qualified suppliers while recreational hunters face transactional spot-market exposure on steel and bismuth alternatives. This bifurcation between contract-anchored institutional tiers and commoditized retail channels structures margin distribution across the value chain.
Pricing Analysis
Warranty and ballistic performance guarantees bundle with law enforcement qualification contracts, while consumer-facing birdshot lines ship unbundled without pattern-density assurances. Three-tier pricing structure across premium, standard, and economy levels separates bismuth-tin alloy waterfowl loads from baseline steel and remaining lead upland products. Cost compression in steel shot manufacturing is intensifying because foundry conversion capex amortization pressures margins. Recreational hunters in non-restrictive zones exhibit highest price sensitivity, whereas tactical training procurement shows minimal elasticity.
Supply Chain Analysis
Domestic-content mandates from the Department of Defense and Buy American Act provisions are redirecting brass sourcing toward Missouri and Arkansas manufacturing clusters. Nitrocellulose propellant supply draws from United States and German chemical producers, while bismuth and tungsten feedstock rests on Chinese and Vietnamese mining operations. Single-source vulnerability concentrates in specialty primer chemistries qualified for temperature-stable performance. Distribution runs through federally licensed dealers and direct-to-consumer platforms with ATF-compliant interstate transfer protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nitrocellulose production capacity constraints prop pricing power for integrated manufacturers, sustaining margin premiums as conversion timelines for new chemical plants extend across multi-year horizons.
For Market Incumbents: Anticipate regulatory acceleration in lead-free zone designations by securing captive bismuth-tin alloy supply through offtake agreements with tungsten processors. Lock in rural retail network density before digital-native competitors achieve ATF licensing scale in key flyway states. For New Entrants and Emerging Players: Subscription-based direct-to-consumer platforms offer the most penetrable route for recurring sport shooter volumes in states with streamlined ammunition shipping regulations. Target competitive clay disciplines with automated replenishment algorithms bypassing traditional wholesale markups. For Investors and Strategic Acquirers: The window for entry favors mid-scale fabricators with brass-forming capabilities and existing ATF licensing infrastructure. Monitor EPA wetland rulemaking timelines as the inflection signal for steel shot capacity valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propellant Chemistry | Captive nitrocellulose supply insulates Federal Premium and Winchester from specialty chemical bottlenecks. |
| Steel Shot Foundry Conversion | Legacy lead line retooling in Missouri and Arkansas positions manufacturers for EPA compliance deadlines. |
| Direct-to-Consumer Platform Launch | Automated reorder algorithms capture sport shooter loyalty in states with permissive interstate shipping rules. |
| Bismuth-Tin Alloy R&D Partnership | High-density shot formulations address performance gaps in coastal waterfowl zones with restrictive non-toxic mandates. |
| European REACH Compliance Certification | Unified formulation standards open EU hunting and security agency procurement to exporters. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with ammunition plant managers, state wildlife agency procurement officers, sporting goods retail buyers, and competitive shooting club directors. EPA enforcement databases, ATF licensing registries, National Shooting Sports Foundation shipment reports, and EU ECHA substance restriction notices provided validation layers. Bottom-up production capacity estimates and top-down consumption surveys underwent triangulation to reconcile volume figures.
Data-stream reconciliation across the analysis window applied segmentation modeling by payload configuration, material compliance tier, end-use application, and distribution channel. CAGRs derived from unit shipment trajectories and value-per-unit inflation adjustments. Forecast inputs incorporated migratory waterfowl population surveys, state hunting license issuance trends, and law enforcement training budget appropriations.
Inputs from ammunition manufacturers and regulatory agencies were available through the study window; gaps in real-time propellant inventory data and proprietary ballistic R&D expenditures introduce uncertainty bands around capacity expansion timelines. Forecasts reflect documented assumptions on regulatory enforcement intensity and substitution elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Hypersonic Missile Market
Weapons and Ammunition
Europe Ammunition Market
Weapons and Ammunition
Precision Guided Munition Market
Weapons and Ammunition
Small and Medium Caliber Ammunition Market
Weapons and Ammunition
Electromagnetic Weapons Market
Weapons and Ammunition
Close-In Weapon Systems Market
Weapons and Ammunition
Shotgun and Rifles Market
Weapons and Ammunition
Enclosed Smokeless Flares Market
Weapons and Ammunition
Intercontinental Ballistic Missile Market
Weapons and Ammunition
Surface to Air Missiles Market
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
Manned Anti-Tank Guided Missile System Market
Weapons and Ammunition
Supersonic and Hypersonic Weapons Market
Weapons and Ammunition
Ammunition Belt Market
Weapons and Ammunition
Middle East and Africa Ammunition Market