
 Particle Beam Directed Energy Weapon Market | 2026-2036
Particle Beam Directed Energy Weapon Market Size, Share, and Industry Trends Forecast 2026-2036
Particle Beam Directed Energy Weapon Market Analysis
ISO 9001 defense contractor certification is rotating as the primary gate for program eligibility, disqualifying smaller subsystem vendors from prime-tier competitions. Lockheed Martin Corporation leverages captive pulsed power R&D to sustain accelerator subsystem leadership. Northrop Grumman Corporation anchors naval directed-energy integration through its shipboard combat systems division. Raytheon Technologies competes on microwave-to-particle hybrid architectures for layered missile defense.
Particle beam directed energy weapons generate and accelerate subatomic particles to near-light velocities, directing kinetic and radiative energy onto targets through magnetic lensing systems operating at cryogenic temperatures; their primary purpose is precision engagement of ballistic missiles, satellites, and hypersonic vehicles at standoff distances exceeding conventional interceptors. Charged particle beam systems dominate current procurement budgets due to mature power-handling infrastructure, while neutral particle beam technology represents the fastest-expanding segment as space-based deployment concepts mature. Ground-based systems capture the largest installed base, though airborne platforms concentrate near-term R&D investment as beam propagation through atmospheric attenuation improves.
The U.S. Missile Defense Agency and Japan's METI coordinate test-range protocols for exoatmospheric neutral beam trials, while NATO standardization agreements govern interoperability requirements for allied platform integration. These frameworks restrict technology transfer to cleared defense contractors and mandate radiation-hardened component traceability. Stakeholders must monitor superconducting magnet supply chain concentration and accelerator miniaturization benchmarks to anticipate procurement timeline shifts.
Market Dynamics
Superconducting magnet supply concentration in Japanese and German specialty manufacturers is compressing accelerator subsystem lead times, forcing defense primes to qualify second-source magnet vendors or absorb 18-24 month procurement delays.
Growth Catalysts
- Neutral beam space deployment:The U.S. Missile Defense Agency's exoatmospheric test protocols validate neutral particle beam architectures for satellite defense, pulling forward R&D budgets from allied NATO procurement offices.
- Japan METI coordination:Bilateral test-range agreements with U.S. agencies accelerate joint demonstration schedules, reducing technical risk for dual-use space-based platforms.
- Superconducting magnet advances:Niobium-tin magnet performance gains shrink accelerator footprints below 40-ton transport thresholds, enabling tactical vehicle integration previously restricted to fixed installations.
Market Restraints
- Cryogenic infrastructure costs:Liquid helium consumption rates exceeding 500 liters per hour constrain operational tempo and tie lifecycle costs to volatile helium spot markets concentrated in Qatar and the United States.
- Beam propagation physics:Atmospheric attenuation below 30 km altitude limits charged particle effectiveness, forcing neutral beam architectures for tactical applications with unproven space-to-ground lethality.
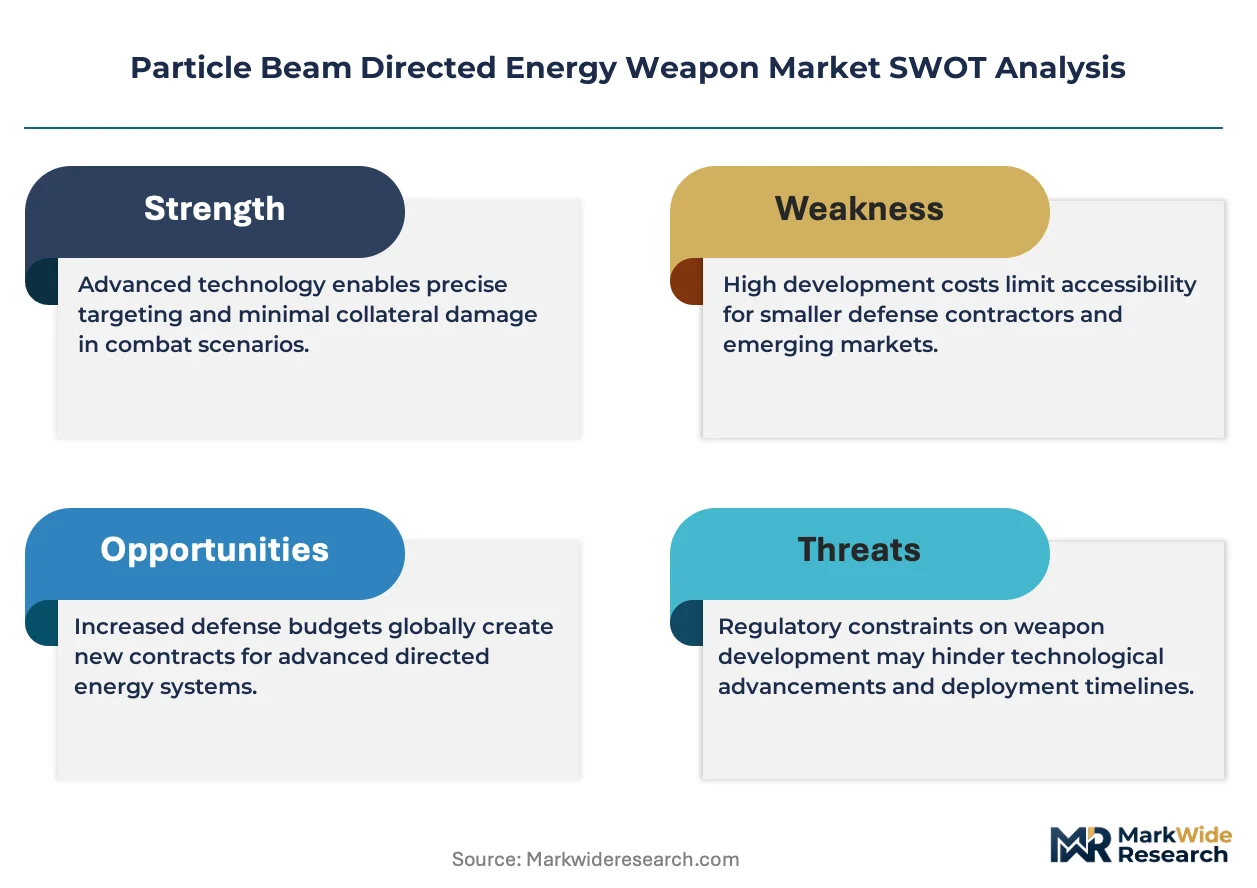
- ISO 9001 certification barriers:Defense contractor eligibility gates exclude subsystem vendors lacking AS9100 traceability, concentrating prime-tier competitions among three integrated primes.
Strategic Opportunities
- Airborne platform integration:High-altitude unmanned carriers above 20 km bypass atmospheric scattering losses, opening precision engagement missions against hypersonic glide vehicles.
- PLA threat response:Japanese and Australian defense white papers explicitly cite counter-satellite requirements, creating procurement mandates outside U.S. budget cycles.
- Hybrid microwave-particle architectures:Layered defense concepts pair terminal particle beams with standoff microwave disruption, capturing bundled system awards from integrated missile defense commands.
Industry Challenges
- Accelerator physicist scarcity:Workforce pipelines for radio-frequency cavity design and beam optics modeling remain concentrated at five U.S. national laboratories, constraining program staffing.
- Radiation-hardened component traceability:NATO standardization agreements mandate lot-level pedigree for power semiconductor substrates, extending subsystem qualification timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Particle Beam Directed Energy Weapon Market |
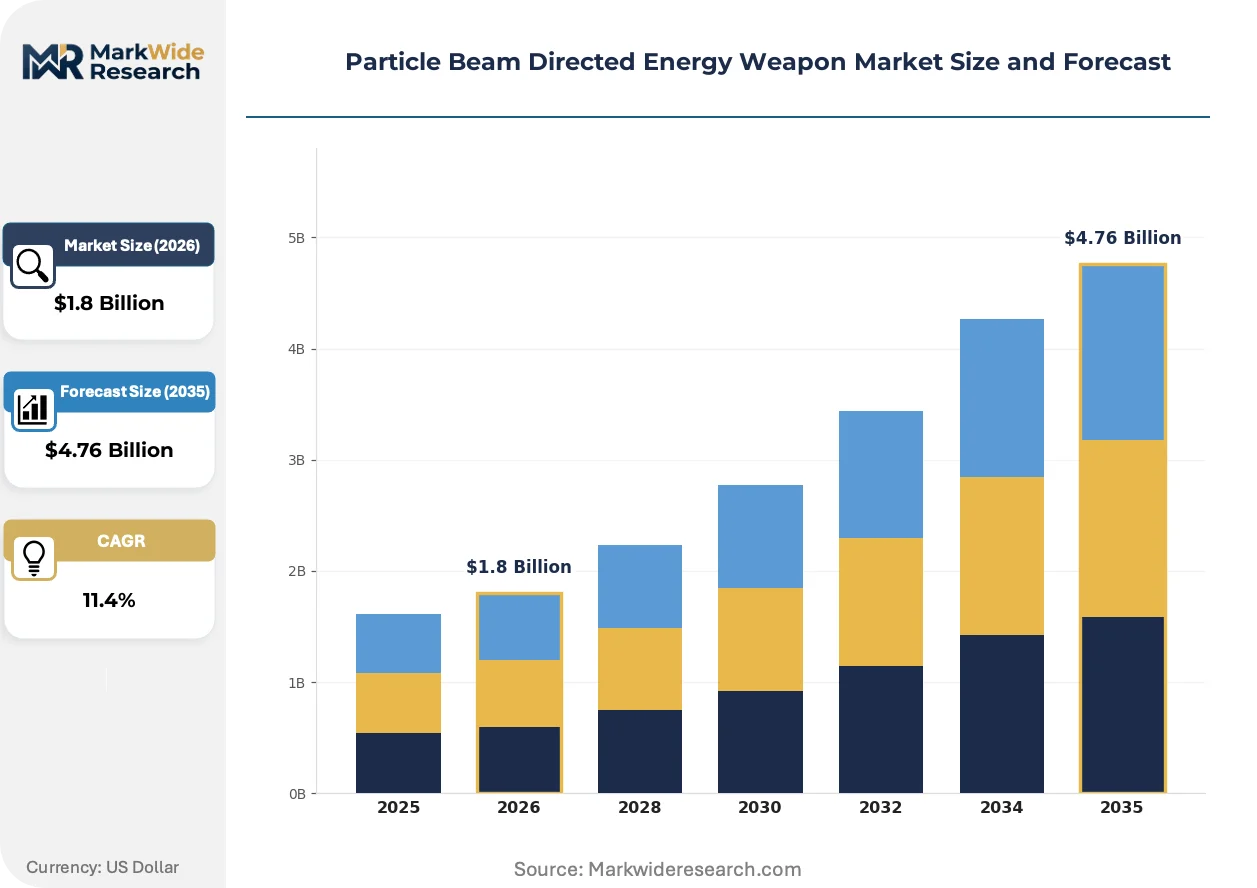
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Charged Particle Beam, Neutral Particle Beam, Laser-Induced Plasma, Microwaves Application: Military Defense, Space Operations, Missile Defense, Research Facilities End User: Government Agencies, Defense Contractors, Research Institutions, Private Sector Deployment: Ground-Based Systems, Sea-Based Systems, Airborne Platforms, Mobile Units |
| Companies Covered | Lockheed Martin Corporation, Raytheon Technologies, Northrop Grumman Corporation, The Boeing Company, BAE Systems, L3Harris Technologies, Thales Group, Leonardo S.p.A, Elbit Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Particle Beam Directed Energy Weapon Market Emerging Trajectories
Beam generation architectures are fragmenting into specialized subsystem supply chains, with magnetic lensing, pulsed power, and target acquisition modules developing independent vendor ecosystems and qualification standards.
Solid-state modulator technology is decomposing conventional Marx generator architectures in pulsed power subsystems. Naval surface warfare commands are specifying silicon carbide switchgear for shipboard installations. This compression of power conditioning mass is decomposing the historical 200-ton floor for tactical particle beam platforms.
NATO standardization agreements are hardening interoperability requirements for allied platform integration. Member state procurement offices must now demonstrate cross-compatible fire control interfaces before accessing pooled R&D funding. German and Japanese defense ministries are accelerating national certification programs to meet these framework deadlines.
Defense procurement offices are consolidating subsystem awards into single-prime, fixed-price vehicles. Historically fragmented accelerator, power, and targeting contracts are compressing into integrated system procurements. This bundling is most visible in U.S. Missile Defense Agency budget lines, where separate technology maturation programs are merging into operational system demonstrations.
Particle Beam Directed Energy Weapon Market Segmentation
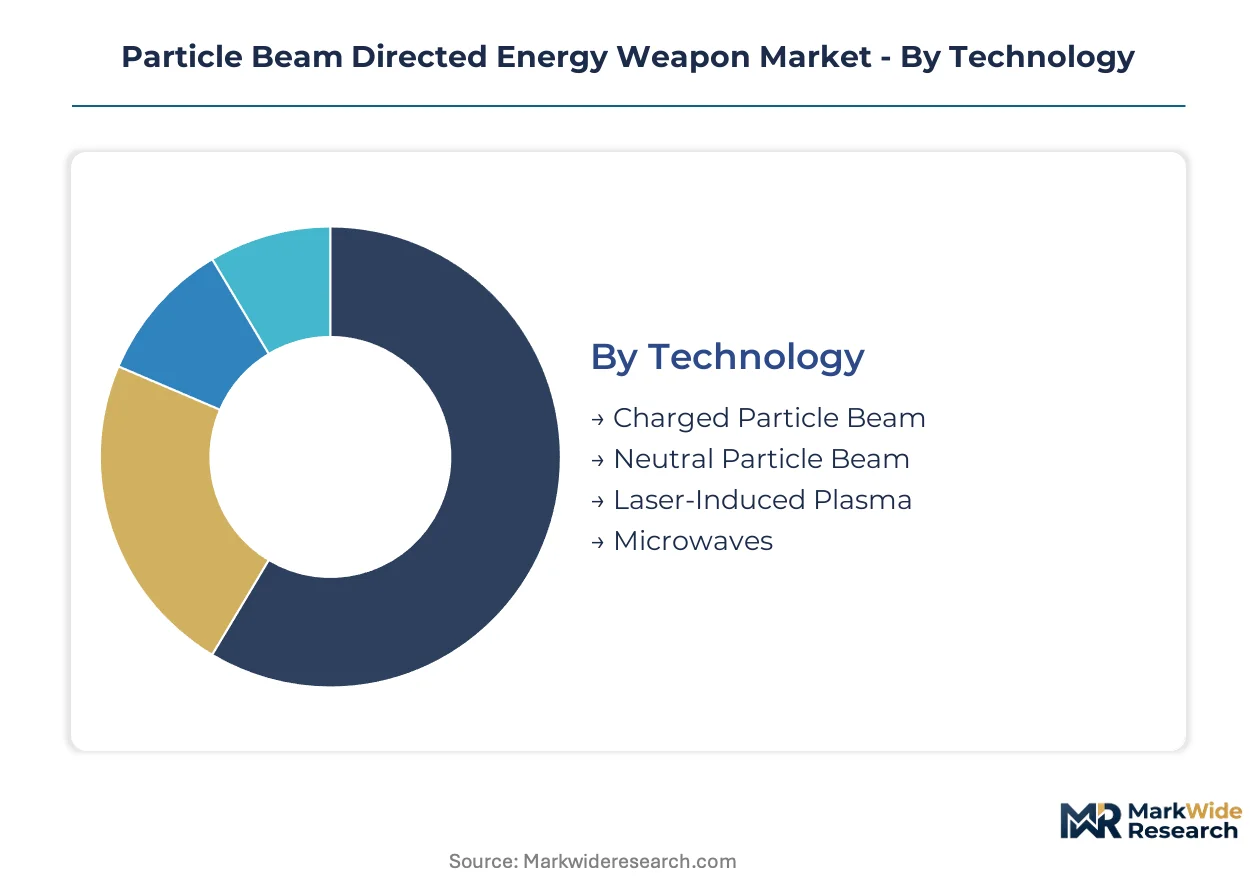
Segmentation in the particle beam directed energy weapon market reveals how procurement budgets fragment across competing technical architectures. Defense primes must align subsystem development with specific deployment constraints rather than pursuing universal platform solutions.
Technology:
Neutral particle beam architectures face the most intense substitution pressure from mature charged particle systems, while microwave hybrids threaten both categories in layered defense configurations.
- Charged Particle Beam:Accelerates ions or electrons through linear radio-frequency cavities, producing directed energy streams with established power-handling infrastructure. Procurement concentrates in U.S. ground-based missile defense installations where atmospheric attenuation below 30 km remains acceptable. Mature magnet technology and proven pulsed power subsystems sustain prime-tier contractor preference despite operational altitude limits.
- Neutral Particle Beam:Neutralizes accelerated hydrogen atoms through charge-exchange cells, enabling exoatmospheric propagation without magnetic deflection by Earth's field. Japan's METI coordinates bilateral test-range protocols with U.S. agencies, pulling forward R&D budgets for satellite defense applications where charged beams fail. Space-based deployment concepts drive the steepest investment trajectory despite cryogenic infrastructure penalties.
- Laser-Induced Plasma:Generates particle bursts through high-intensity laser-target interaction, offering compact sources without accelerator footprint. Research institutions in Germany evaluate plasma jet collimation for close-range defense scenarios.
- Microwaves:Delivers electromagnetic energy through directed high-power radio-frequency emission, competing for layered defense budgets against particle architectures. Naval surface warfare commands specify silicon carbide switchgear for shipboard installations.
Charged particle beam systems anchor the volume base while neutral particle beam architectures gain share at the steepest rate.
Application:
Cost tier stratification separates strategic national programs from tactical procurement, with missile defense commanding premium budgets and research facilities operating on constrained capital cycles.
- Military Defense:Encompasses tactical engagement of hardened ground targets and area denial missions requiring sustained beam dwell times. NATO standardization agreements mandate cross-compatible fire control interfaces, concentrating awards among cleared defense contractors with ISO 9001 certification.
- Missile Defense:Targets ballistic reentry vehicles and hypersonic glide vehicles at standoff distances exceeding conventional kinetic interceptors. The U.S. Missile Defense Agency merges separate technology maturation programs into operational system demonstrations, compressing historically fragmented contracts.
- Space Operations:Addresses satellite defense and orbital asset protection through exoatmospheric beam propagation. Japanese and Australian defense white papers cite explicit counter-satellite procurement mandates.
- Research Facilities:Supports fundamental beam physics, target effects modeling, and subsystem validation at national laboratories. Accelerator physicist scarcity at five U.S. facilities constrains program staffing.
Missile defense applications absorb the dominant procurement share while space operations climb the fastest.
End User:
Customer type determines contracting vehicle structure, with government agencies consolidating awards and private sector participation limited to component supply.
- Government Agencies:The U.S. Missile Defense Agency and Japan's METI coordinate test-range protocols, controlling demonstration schedules and pooled R&D funding access. Fixed-price vehicle consolidation excludes subsystem vendors lacking AS9100 traceability.
- Defense Contractors:Lockheed Martin Corporation leverages captive pulsed power R&D Northrop Grumman Corporation anchors naval integration; Raytheon Technologies competes on hybrid architectures. Three integrated primes dominate prime-tier competitions.
- Research Institutions:National laboratories supply accelerator physicist pipelines and validate beam propagation physics. Workforce concentration at five U.S. facilities constrains program scaling.
- Private Sector:Japanese and German specialty manufacturers concentrate superconducting magnet supply, forcing 18-24 month procurement delays without qualified second sources.
Government agencies anchor the volume base while defense contractors capture share at the steepest rate.
Deployment:
Platform mobility requirements fragment supply chains, with fixed installations tolerating heavy accelerator footprints and mobile units demanding cryogenic system miniaturization.
- Ground-Based Systems:Fixed installations accommodate 200-ton accelerator floors with dedicated liquid helium infrastructure. Qatar and United States helium spot market volatility constrains operational tempo.
- Sea-Based Systems:Naval combatants integrate particle beams through shipboard power distribution and magnetic lensing stabilization. Silicon carbide switchgear compression enables tactical platform integration.
- Airborne Platforms:High-altitude unmanned carriers above 20 km bypass atmospheric scattering losses. Niobium-tin magnet performance gains shrink accelerator footprints below 40-ton transport thresholds.
- Mobile Units:Tactical vehicle integration demands superconducting magnet miniaturization and reduced cryogenic consumption. German defense ministries accelerate national certification programs for NATO interoperability deadlines.
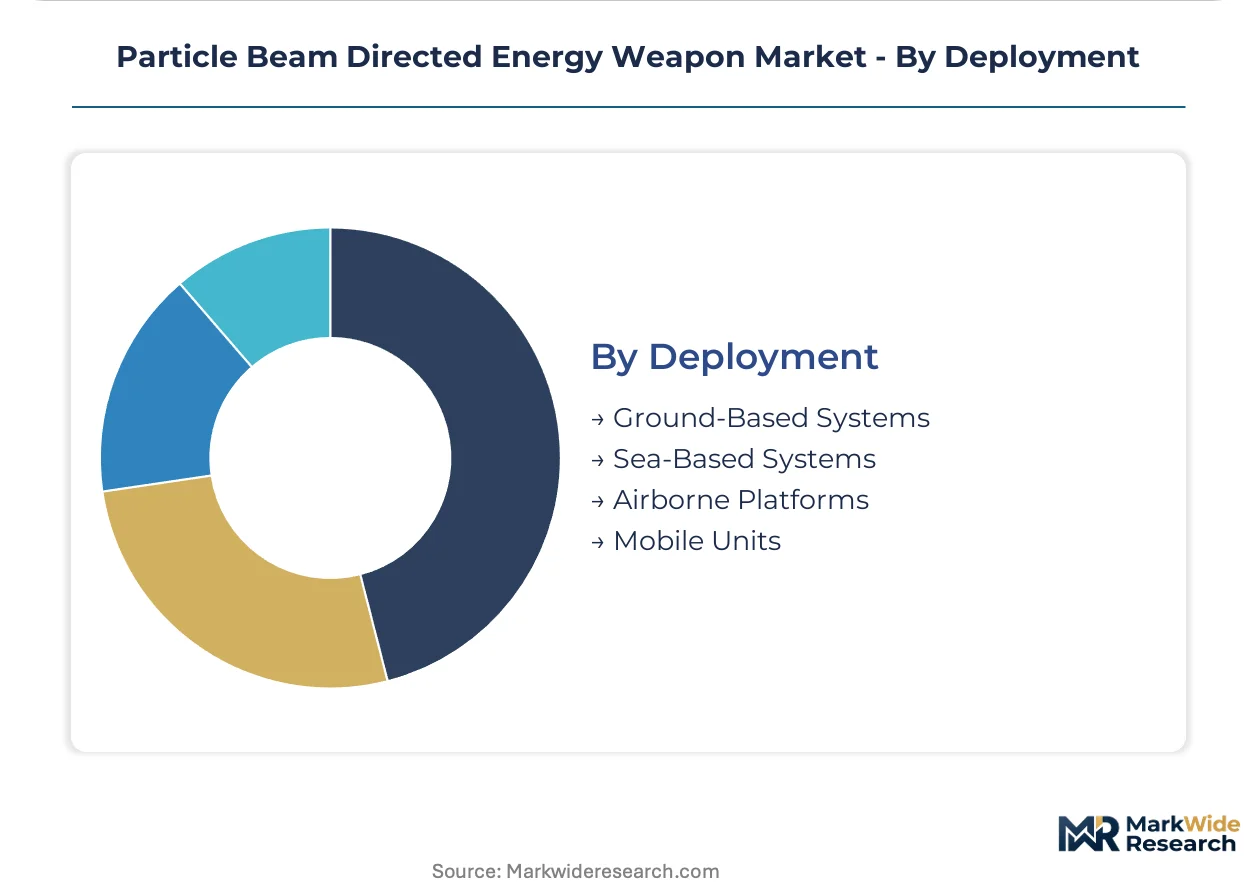
Ground-based systems anchor the volume base while airborne platforms gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices in NATO member states and select Asia-Pacific allies concentrate the buyer archetype, with national missile defense agencies controlling demonstration schedules and pooled R&D funding access.
United States
The U.S. Missile Defense Agency merges separate technology maturation programs into operational system demonstrations, compressing historically fragmented contracts. ISO 9001 defense contractor certification rotates as the primary gate for program eligibility. Albuquerque and Livermore host accelerator physicist pipelines at national laboratories, constraining program scaling as workforce demand outstrips supply.
Japan
Japan's METI coordinates bilateral test-range protocols with U.S. agencies, pulling forward R&D budgets for satellite defense applications. Defense white papers explicitly cite counter-satellite procurement mandates, creating acquisition mandates outside U.S. budget cycles. Japanese specialty manufacturers concentrate superconducting magnet supply, forcing defense primes to qualify second-source vendors or absorb procurement delays.
Germany
German defense ministries accelerate national certification programs to meet NATO interoperability framework deadlines. The country's national defense procurement office consolidates subsystem awards into single-prime, fixed-price vehicles. Bavaria and North Rhine-Westphalia anchor superconducting magnet research clusters, with Fraunhofer institutes evaluating niobium-tin performance gains for accelerator miniaturization.
Australia
Australian defense white papers cite explicit counter-satellite requirements, creating procurement mandates tied to PLA threat response. The country's national defense regulator governs interoperability requirements for allied platform integration. Canberra and Adelaide concentrate naval combat systems integration expertise, with shipboard power distribution programs specifying silicon carbide switchgear for particle beam installations.
United Kingdom
UK defense procurement offices participate in NATO standardization agreements governing cross-compatible fire control interfaces. The country's national defense ministry controls access to pooled R&D funding through interoperability demonstration requirements. Scotland and Southwest England host BAE Systems integration facilities, anchoring naval directed-energy programs through shipboard combat systems divisions.
Particle Beam Directed Energy Weapon Market Vendor Landscape
Player mix skews toward integrated defense primes with captive pulsed power R&D and established AS9100 traceability. Three contractors dominate prime-tier competitions, with subsystem vendors excluded from eligibility by ISO 9001 certification barriers. Strategic archetypes include captive technology developers, naval integration specialists, and hybrid architecture competitors. Competitive moves concentrate on fixed-price vehicle consolidation and second-source magnet vendor qualification to compress accelerator subsystem lead times.
Among U.S.-based integrated primes, Lockheed Martin Corporation, Northrop Grumman Corporation, and Raytheon Technologies occupy positions within the prime-tier contractor set. Lockheed Martin represents the captive pulsed power R&D archetype, Northrop Grumman anchors naval directed-energy integration, and Raytheon exemplifies hybrid microwave-particle architecture competition. These three entities sit within the cleared defense contractor pool eligible for merged operational system demonstrations, with their positioning reflecting the market's consolidation around integrated system procurements rather than fragmented subsystem awards.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Raytheon Technologies |
| Northrop Grumman Corporation |
| The Boeing Company |
| BAE Systems |
| L3Harris Technologies |
| Thales Group |
| Leonardo S.p.A |
| Elbit Systems |
| Others |
Supply Flow & Price Mechanics
Fixed-price vehicle consolidation with helium spot indexation locks in procurement visibility for defense primes while exposing lifecycle costs to Qatar and United States supply volatility. This contract structure concentrates pricing power among integrated system vendors who absorb cryogenic infrastructure penalties upfront.
Pricing Analysis
Cost-plus contracts with liquid helium spot-price indexation dominate procurement structures, transferring commodity volatility risk to government agencies while guaranteeing prime-tier margins. Price differentiation separates ISO 9001-certified integrated systems from subsystem components lacking AS9100 traceability. Pricing pressure stems from superconducting magnet supply concentration in Japan and Germany, forcing 18-24 month procurement delays or premium qualification costs. Research institutions exhibit highest price sensitivity due to constrained capital cycles, while missile defense agencies demonstrate lowest sensitivity given mission-critical procurement mandates.
Supply Chain Analysis
Strategic stockpiling of niobium-tin superconducting magnets and liquid helium reserves characterizes inventory preferences, contrasting with just-in-time approaches in conventional defense electronics. Supply concentrates in Japanese and German specialty manufacturers for superconducting magnets, with Qatar and the United States anchoring helium extraction. Raw material dependencies include niobium-tin alloys, high-purity helium, and radiation-hardened silicon carbide substrates. Single-source vulnerability in magnet supply chains constitutes the dominant structural risk. Distribution runs through prime-tier defense contractors with cleared facility access, excluding uncertified subsystem vendors from direct government contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where cryogenic infrastructure maintenance and accelerator physicist staffing contracts expand faster than hardware procurement. Recurring revenue layers from operational support agreements now exceed initial system acquisition value in total contract lifetime.
For Market Incumbents: Secure captive pulsed power R&D capabilities through backward integration into solid-state modulator production, insulating against silicon carbide switchgear supply volatility. Lock in exclusive accelerator physicist pipelines at national laboratories through endowed research chairs, constraining competitor staffing. Neutral beam architectures threaten charged particle system incumbents; defend through hybrid microwave-particle bundled offerings that capture layered defense budgets. For New Entrants and Emerging Players: Differentiate on cryogenic system miniaturization for airborne platform integration, where niobium-tin magnet performance gains shrink accelerator footprints below tactical vehicle thresholds. Target Australian and Japanese defense procurement offices outside U.S. budget cycles, where PLA threat response creates independent acquisition mandates. Pursue qualified second-source magnet vendor status to compress 18-24 month lead times plaguing established supply chains. For Investors and Strategic Acquirers: Capital is best deployed toward subsystem specialists with AS9100 traceability and ISO 9001 certification pathways, positioned for prime-tier contract consolidation. Long-term viability hinges on exoatmospheric neutral beam deployment maturation and space-based platform proliferation. Watch U.S. Missile Defense Agency budget line mergers as the inflection signal—operational system demonstrations replacing fragmented technology maturation programs indicate procurement velocity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Second-Source Magnet Vendor Qualification | Compresses accelerator subsystem lead times constrained by Japanese and German supply concentration. |
| Cryogenic Infrastructure Miniaturization | Enables tactical vehicle integration previously restricted to 200-ton fixed installations. |
| Hybrid Microwave-Particle Architecture Development | Captures bundled system awards from layered missile defense commands at Northrop Grumman and Raytheon. |
| Accelerator Physicist Pipeline Endowment | Secures workforce access at five U.S. national laboratories where talent scarcity constrains scaling. |
| NATO Interoperability Certification Acceleration | Unlocks pooled R&D funding access for German and Japanese defense ministries meeting framework deadlines. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with defense procurement officers, accelerator physicists at national laboratories, and shipboard combat systems engineers; and secondary validation through U.S. Missile Defense Agency budget justifications, NATO standardization agreement texts, and METI bilateral protocol filings. Bottom-up triangulation across subsystem vendor qualification records and top-down reconciliation against prime-tier contract awards anchored market sizing.
Across the projection horizon, the analytical framework modeled technology segmentation by beam architecture, deployment platform mobility tiers, and application mission profiles including missile defense and space operations. CAGRs derived from procurement timeline compression observed in merged operational system demonstrations and superconducting magnet miniaturization benchmarks. Industry-specific inputs incorporated helium spot market volatility curves and accelerator physicist pipeline graduation rates.
Material uncertainties—superconducting magnet supply chain disruption, cryogenic infrastructure cost inflation, and exoatmospheric lethality validation failures—sit outside the modeled envelope. Forecasts reflect documented assumptions regarding NATO interoperability framework adherence and bilateral test-range protocol continuity. Revision becomes warranted when neutral particle beam space-to-ground effectiveness demonstrations cross operational deployment thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Intercontinental Ballistic Missile Market
Weapons and Ammunition
Missile Launching Systems Market
Weapons and Ammunition
Asia-Pacific Nuclear Bombs and Missiles Market
Weapons and Ammunition
Asia-Pacific Cruise Missile Market
Weapons and Ammunition
Mortar Ammunition Market
Weapons and Ammunition
Middle East and Africa Ammunition Market
Weapons and Ammunition
Global Artillery Systems Market
Weapons and Ammunition
Global Submarine Launched Missile Market
Weapons and Ammunition
Shotgun and Rifles Market
Weapons and Ammunition
Weapon Mounts Market
Weapons and Ammunition
Hypersonic Missile Market
Weapons and Ammunition
Ballistic Missile Market
Weapons and Ammunition
Ammunition Belt Market
Weapons and Ammunition
Military Fire Control Systems Market
Weapons and Ammunition
Middle East and North Africa Perforating Gun Market
Weapons and Ammunition
Military Fuze Market