
 France Rotor Blade Market | 2026-2036
France Rotor Blade Market Size, Share, and Industry Trends Forecast 2026-2036
France Rotor Blade Market Foresight
France is fragmenting its rotor blade supply base across multiple coastal manufacturing zones. Siemens Gamesa Renewable Energy SA anchors blade assembly at its Le Havre facility, leveraging port infrastructure for offshore logistics. LM Wind Power competes through specialized composite molding capabilities serving both wind and aerospace derivative markets. Vestas Wind Systems A/S sustains regional service density with blade repair networks spanning northern and western France.
A rotor blade is an aerodynamic lifting surface engineered from fiberglass-reinforced polymer or carbon fiber composite, typically spanning 40 to 120 meters in wind applications, designed to convert kinetic airflow into rotational mechanical energy driving a generator or transmission system. Composite blades dominate installed capacity due to fatigue resistance and specific strength advantages, while carbon fiber variants capture premium aerospace and next-generation wind segments where weight reduction justifies material cost premiums. Metal blades retain niche positions in helicopter tail rotors and certain defense applications where impact tolerance outweighs mass penalties.
France's national energy regulator and environmental permitting authorities enforce offshore wind farm approval timelines that directly shape blade procurement scheduling and localization requirements. The country's civil aviation authority and EU-derived CE marking protocols govern helicopter and drone blade airworthiness certification, creating dual compliance pathways for suppliers serving both energy and aerospace end users. Stakeholders must track how France's implementation of the EU Green Deal industrial plan reallocates domestic manufacturing incentives between blade production and upstream composite material supply.
Market Dynamics
The France rotor blade market is being fundamentally restructured by the Ministry of Ecological Transition's tightening domestic content requirements for offshore wind tenders, which are forcing supply chain relocalization away from established Iberian manufacturing corridors toward Atlantic port clusters.
Growth Catalysts
- EU Green Deal industrial plan:France's implementation reallocates manufacturing incentives toward composite material supply chains, directly subsidizing blade mold tooling and resin formulation capacity expansion.
- Offshore wind tender regime:The Ministry of Ecological Transition mandates escalating local content thresholds that compel developers to source blades from Saint-Nazaire corridor facilities rather than import from Denmark or Spain.
- Blade replacement cycles:Normandy and Brittany onshore operators are accelerating decommissioning schedules for 2000s-era 40-50 meter blades, creating predictable demand for 70-90 meter composite replacements.
Market Restraints
- Epoxy resin price volatility:Petrochemical feedstock fluctuations and Baltic Sea shipping disruptions transmit directly into blade laminate cost structures, compressing molders' margin buffers.
- Carbon fiber supply concentration:Precursor production clusters in Japan and the United States create import dependency for next-generation lightweight blade variants targeting floating offshore platforms.
- CE marking airworthiness dual-track:France's civil aviation authority maintains divergent certification timelines for helicopter blade derivatives versus wind applications, extending product qualification cycles.
Strategic Opportunities
- Floating offshore wind:France's Mediterranean and Atlantic deep-water lease zones require 100+ meter blade architectures that domestic molders can capture before Iberian competitors scale equivalent capacity.
- Aerospace composite convergence:LM Wind Power and adjacent Airbus Atlantic facilities enable technology spillover from A350 wing programs into wind blade spar cap designs.
- Port of Le Havre logistics integration:Direct heavy-lift quayside access allows complete blade assembly adjacent to offshore installation vessel loading, eliminating road transport constraints that bottleneck Spanish competitors.
Industry Challenges
- Composite technician scarcity:Brittany and Normandy lack sufficient trained laminators and infusion specialists to staff expanded molding lines, forcing wage competition with aerospace sector recruiters.
- Blade repair certification bottlenecks:Vestas and Siemens Gamesa service networks face extended approval timelines from Bureau Veritas for non-destructive testing protocols, delaying warranty claim resolution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Rotor Blade Market |
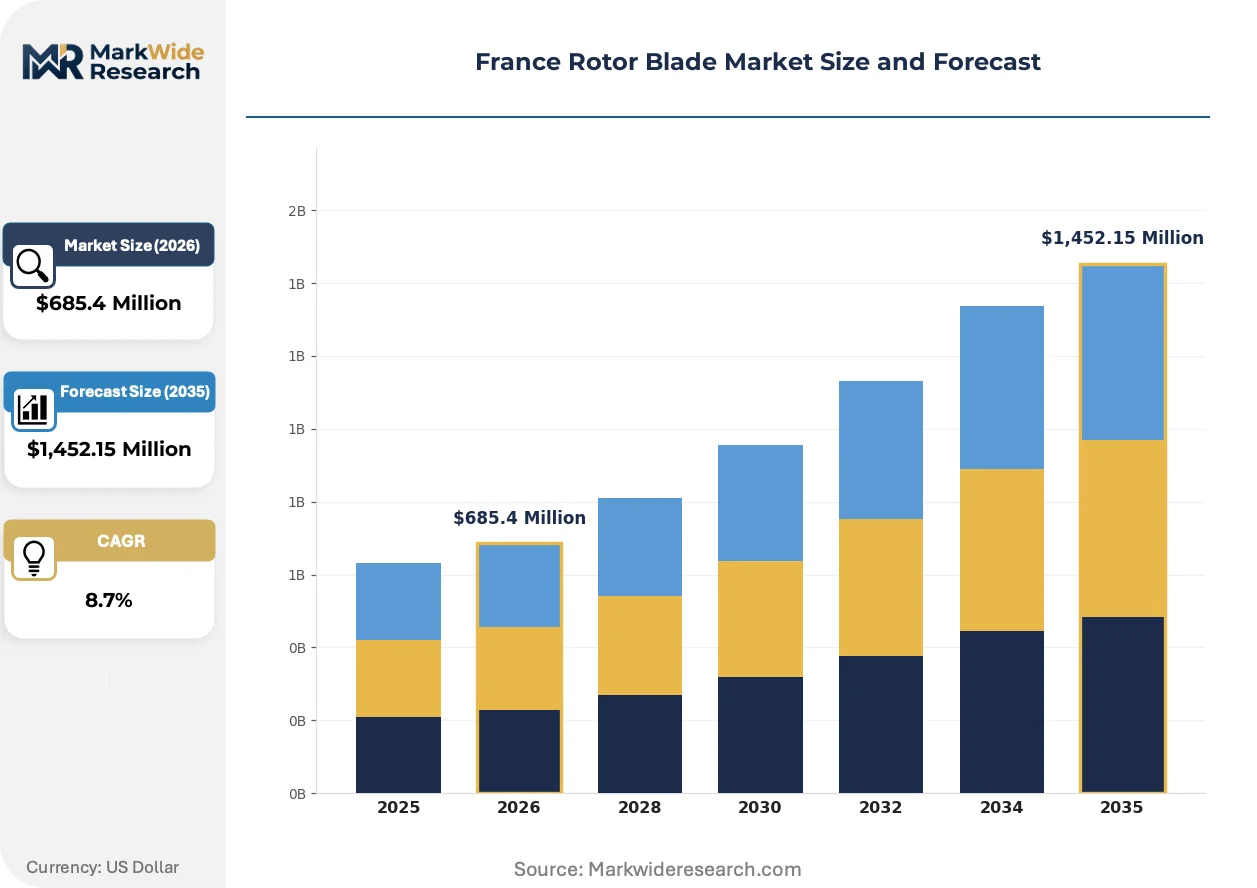
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Blades, Metal Blades, Wooden Blades, Hybrid Blades, Carbon Fiber Blades Application: Wind Turbines, Helicopters, Drones, Aviation Equipment, Renewable Energy Systems Material: Fiberglass, Aluminum Alloy, Titanium, Polymer Matrix, Kevlar End User: Renewable Energy Operators, Aerospace Manufacturers, Defense Contractors, Agricultural Services, Research Institutions |
| Companies Covered | Nordex SE, Siemens Gamesa Renewable Energy SA, Vestas Wind Systems A/S, Suzlon Energy Limited, LM Wind Power, Enercon GmbH, Airbus Helicopters, Safran Helicopter Engines, GE Renewable Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Rotor Blade Market Shifts & Advancements
Digital engineering workflows and advanced materials are compressing blade development cycles while regulatory pressure on recyclability forces redesign of end-of-life composite architectures.
Thermoplastic resin systems are virtualizing traditional epoxy-based manufacturing by enabling automated fiber placement and in-situ welding of blade segments. Offshore developers in the Saint-Nazaire corridor are piloting these systems for 90-meter spar caps. The technology is virtualizing labor-intensive hand layup processes that previously constrained production scaling.
The EU Green Deal industrial plan's carbon border adjustment mechanism is reshaping raw material sourcing economics for French molders. Imported carbon fiber from third countries now carries embedded emissions penalties that domestic epoxy formulation from Fos-sur-Mer avoids. Blade suppliers serving floating offshore projects are accelerating partnerships with Portuguese precursor recyclers to secure lower-carbon feedstock certification.
Service unbundling is fragmenting traditional OEM maintenance contracts. Independent blade inspection specialists using drone-mounted lidar are displacing Vestas and Siemens Gamesa scheduled service agreements at Brittany onshore farms. This pattern concentrates in aging 2005-2015 installed capacity where operators seek to decouple hardware procurement from lifetime service commitments.
France Rotor Blade Market Segmentation
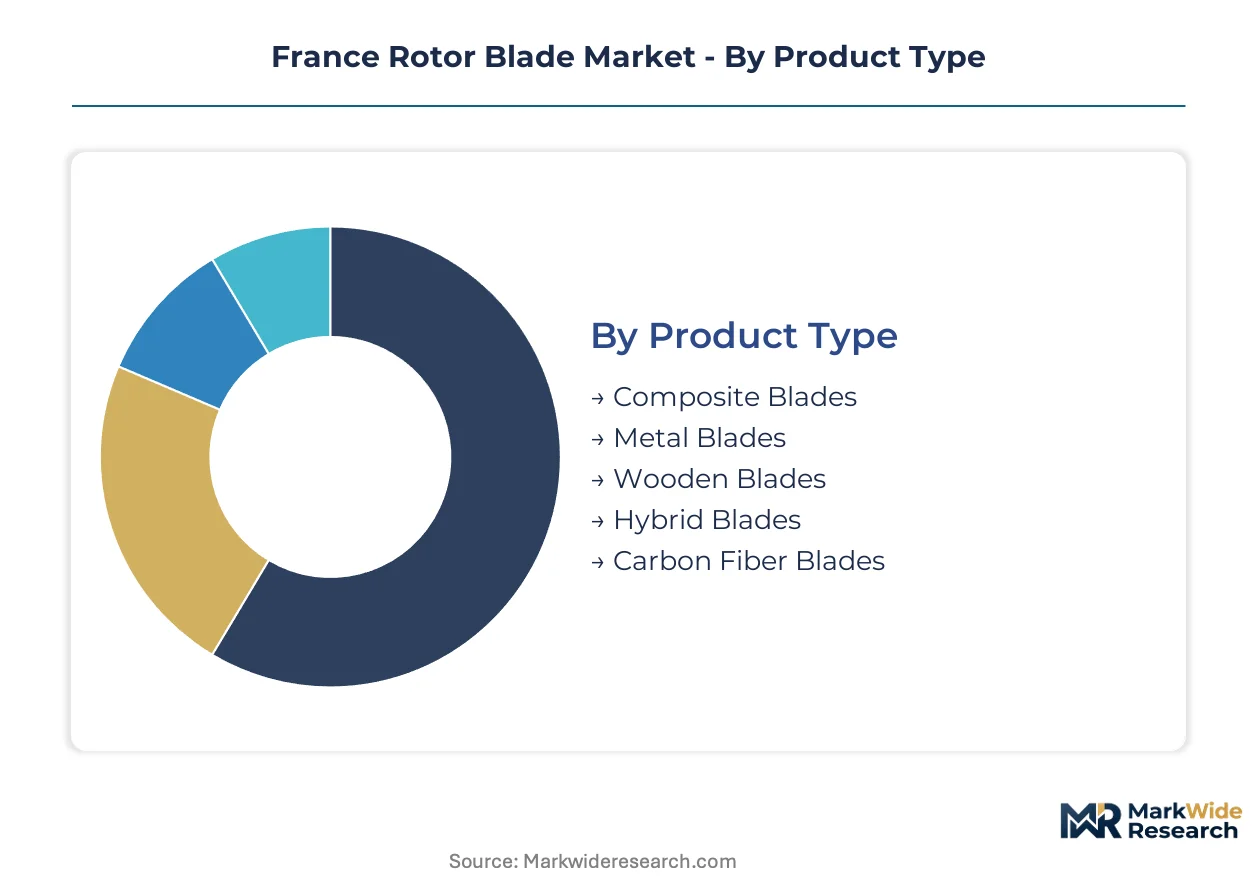
Rotor blade segmentation in France reveals divergent replacement cycles across energy and aerospace verticals. Material composition and certification requirements create stark differences in procurement frequency between offshore wind farms and defense helicopter programs.
Product Type:
Composite blades turn over fastest in offshore wind replacement programs, while metal variants persist for decades in defense applications. Cycle time variance spans 15-25 years for wind composites versus 30-40 years for aerospace metal architectures.
- Composite Blades:Fiberglass-reinforced polymer laminates dominate Saint-Nazaire corridor production for 70-120 meter offshore units. Brittany and Normandy wind farm operators source these for accelerated blade replacement cycles driven by 2000s-era decommissioning schedules.
- Metal Blades:Aluminum and titanium alloys serve helicopter tail rotors and defense applications where impact tolerance outweighs mass penalties. French defense contractors specify these for naval aviation programs with extended service intervals.
- Wooden Blades:Laminated timber constructions retain niche positions in heritage windmill restoration and small-scale agricultural pumping systems.
- Hybrid Blades:Metal-composite hybrid spar caps combine aluminum leading edges with fiberglass trailing sections for specialized drone applications.
- Carbon Fiber Blades:Prepreg carbon fiber variants target floating offshore platforms and next-generation aerospace derivatives where weight reduction justifies material cost premiums.
Composite blades anchor the volume base while carbon fiber variants gain share at the steepest rate.
Application:
Cost tier separation distinguishes capital-intensive offshore wind installations from lower-unit-cost drone fleets. Procurement patterns split between multi-million euro turbine blades and serialized thousand-euro unmanned aerial system components.
- Wind Turbines:Onshore units in Normandy and offshore arrays at Saint-Nazaire drive demand for 70-120 meter composite architectures. The Ministry of Ecological Transition's domestic content mandates concentrate procurement through Le Havre and Saint-Nazaire assembly corridors.
- Helicopters:Airbus Atlantic and Dassault Aviation programs specify metal-composite hybrid main and tail rotors with Bureau Veritas airworthiness certification. Defense variants face extended qualification timelines under France's civil aviation authority protocols.
- Drones:Lightweight carbon fiber and polymer matrix blades serve commercial inspection and agricultural spraying fleets with 2-5 year replacement cycles.
- Aviation Equipment:Auxiliary propulsion and cooling fan blades for regional aircraft programs leverage composite molding capabilities adjacent to Airbus Atlantic facilities.
- Renewable Energy Systems:Small wind and hydrokinetic turbine blades overlap with marine current energy prototypes tested in Brittany coastal zones.
Wind turbine applications command the highest unit values while drone segments expand most quickly through fleet scaling.
Material:
Supply concentration varies sharply between domestically formulated epoxy resins and import-dependent carbon fiber precursors. Geography of precursor production determines lead time and carbon border adjustment exposure under EU Green Deal mechanisms.
- Fiberglass:E-glass and S-glass reinforcements from Saint-Gobain facilities supply the bulk of wind blade laminate structures with established domestic supply chains.
- Aluminum Alloy:Aerospace-grade 7075 and 2024 series serve helicopter rotor hubs and leading edge erosion shields.
- Titanium:Beta and alpha-beta alloys from Aubert & Duval provide high-cycle fatigue resistance for naval aviation tail rotor components.
- Polymer Matrix:Epoxy formulations from Fos-sur-Mer petrochemical clusters avoid carbon border adjustment penalties versus imported alternatives.
- Kevlar:Aramid fiber hybrid laminates reinforce leading edge protection and ballistic-tolerant drone architectures for defense applications.
Fiberglass anchors the volume base while polymer matrix systems climb the fastest through thermoplastic resin substitution.
End User:
Customer type determines contract structure, with renewable energy operators favoring long-term service agreements and defense contractors requiring discrete project-based procurement. Margin profiles diverge between serialized production and specialized low-volume manufacture.
- Renewable Energy Operators:EDF Renewables and independent wind farm owners in Brittany and Normandy drive blade replacement demand through 15-20 year asset management cycles. Procurement bundles hardware with Bureau Veritas-certified inspection protocols.
- Aerospace Manufacturers:Airbus Atlantic and Safran Helicopter Engines programs require CE-marked and civil aviation authority-certified components with full traceability documentation.
- Defense Contractors:Naval Group and Dassault Aviation specify impact-tolerant metal and hybrid architectures with classified performance parameters.
- Agricultural Services:Vineyard and cereal crop spraying cooperatives in Champagne and Bordeaux regions source standardized drone blade replacements.
- Research Institutions:ONERA and CNRS laboratories procure experimental blade geometries for aerodynamic and aeroelastic testing programs.
Renewable energy operators anchor the volume base while agricultural services gain share at the steepest rate through drone fleet densification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANSM and the Ministry of Ecological Transition anchor regulatory oversight across France's rotor blade manufacturing corridors, with domestic content mandates reshaping procurement flows toward Atlantic port clusters.
Normandy
Onshore wind farm operators in Normandy accelerate blade replacement programs for aging 2000s-era turbines. The Ministry of Ecological Transition enforces decommissioning timelines that synchronize with CE marking protocols for new composite installations. Le Havre hosts Siemens Gamesa assembly lines serving offshore logistics corridors.
Brittany
Brittany's coastal wind farms drive demand for 70-90 meter composite blade replacements. Bureau Veritas certification requirements extend approval timelines for non-destructive testing protocols. Saint-Brieuc and Brest anchor blade repair networks competing with OEM service contracts.
Pays de la Loire
The Saint-Nazaire offshore wind assembly corridor concentrates next-generation blade manufacturing capacity. Domestic content thresholds under the EU Green Deal industrial plan redirect procurement from Iberian suppliers. The Port of Saint-Nazaire enables direct heavy-lift quayside loading for installation vessels.
Hauts-de-France
Wind farm operators in northern coastal zones source blade replacements through logistics networks spanning the English Channel. CNIL data governance protocols shape digital inspection tool deployment for drone-based maintenance. Dunkirk and Calais serve as secondary import gateways for carbon fiber precursor materials.
Nouvelle-Aquitaine
Land-based wind installations in southwestern France require periodic blade refurbishment under extended asset management cycles. Regional environmental permitting authorities coordinate with national energy regulators on repowering schedules. Bordeaux and La Rochelle support composite technician training programs addressing labor scarcity.
France Rotor Blade Market Competitive Landscape
Integrated turbine OEMs and specialized blade fabricators split the market into distinct capability tiers. Market structure reflects moderate consolidation around port-adjacent manufacturing assets, with entry barriers rising from domestic content mandates and specialized composite labor requirements. Three archetypes dominate: vertically integrated wind turbine suppliers, independent blade specialists with aerospace adjacencies, and regional service networks capturing maintenance unbundling trends. Competitive intensity centers on capacity expansion in Atlantic corridors and strategic partnerships securing carbon fiber supply.
Among integrated European turbine suppliers, Siemens Gamesa Renewable Energy SA and Vestas Wind Systems A/S occupy positions anchoring offshore wind procurement channels through French port facilities. LM Wind Power represents the independent specialist archetype, sitting within composite manufacturing networks that bridge wind energy and aerospace derivative markets. These three entities exemplify how regulatory localization requirements favor established players with existing Atlantic corridor infrastructure over import-dependent competitors.
| Leading Market Players |
|---|
| Nordex SE |
| Siemens Gamesa Renewable Energy SA |
| Vestas Wind Systems A/S |
| Suzlon Energy Limited |
| LM Wind Power |
| Enercon GmbH |
| Airbus Helicopters |
| Safran Helicopter Engines |
| GE Renewable Energy |
| Others |
Supply & Pricing Matrix
The Port of Saint-Nazaire heavy-lift corridor transmits logistics cost differentials directly into blade procurement premiums, with Atlantic port access separating domestic molders from Iberian competitors facing road transport constraints. This freight geography concentrates supply-side pricing power among Le Havre and Saint-Nazaire adjacent facilities while compressing margins for import-dependent distributors.
Pricing Analysis
Geographic price spreads of 12-18% separate Saint-Nazaire corridor deliveries from Spanish-imported equivalents after domestic content mandates took effect. Contract-based long-term offtake agreements dominate offshore wind procurement, with price differentiation resting on Bureau Veritas certification tier and bundled inspection service depth. Cost compression in standard-grade composite segments is intensifying due to epoxy resin feedstock volatility. Independent repair specialists exhibit highest price sensitivity, while EDF Renewables maintains lowest sensitivity through captive service agreements.
Supply Chain Analysis
Contract manufacturing capacity concentrates at Siemens Gamesa's Le Havre facility and LM Wind Power's Atlantic molding operations, with no significant third-party blade foundry presence in France. Raw material sourcing draws from German epoxy resin formulators, Japanese carbon fiber precursor suppliers, and Saint-Gobain's domestic fiberglass operations. Single-source vulnerability persists for aerospace-grade carbon fiber imports subject to EU carbon border adjustment penalties. Distribution runs through port-adjacent assembly corridors with direct quayside loading to offshore installation vessels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's rotor blade market sits in early-cycle expansion as floating offshore wind lease activations accelerate adoption beyond established onshore replacement demand. The Ministry of Ecological Transition's escalating domestic content thresholds create structural tailwinds for Atlantic corridor capacity.
For Market Incumbents: Harden supply security through backward integration into Fos-sur-Mer epoxy formulation capacity, eliminating carbon border adjustment exposure on imported resin systems. Secure exclusive Bureau Veritas certification pathways for thermoplastic spar cap architectures before Iberian competitors scale equivalent qualifications. Lock in long-term carbon fiber supply agreements with Portuguese precursor recyclers to defend margin buffers against Japanese supply concentration.
For New Entrants and Emerging Players: Pursue drone blade manufacturing white space in Nouvelle-Aquitaine, where agricultural spraying cooperatives drive 2-5 year replacement cycles with minimal incumbent service bundling. Target independent inspection services unbundling from Vestas and Siemens Gamesa maintenance contracts at aging Brittany onshore farms. Lead with drone-mounted lidar deployment partnerships as the go-to-market angle.
For Investors and Strategic Acquirers: Specialized composite molders with aerospace adjacencies represent the most defensible acquisition archetype, capturing technology spillover from Airbus Atlantic wing programs into wind blade spar cap designs. Long-term viability rests on dual-use manufacturing flexibility across energy and aerospace certification pathways. Watch for inflection when floating offshore project financings reach final investment decision, signaling 100+ meter blade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Resin Transition | Enables automated fiber placement at Saint-Nazaire facilities, reducing labor-intensive hand layup bottlenecks. |
| Carbon Fiber Precursor Recycling Partnership | Secures lower-carbon feedstock certification under EU Green Deal border adjustment mechanisms for floating offshore projects. |
| Port of Le Havre Logistics Integration | Eliminates road transport constraints through direct heavy-lift quayside access for complete blade assembly. |
| Composite Technician Training Expansion | Addresses Brittany and Normandy labor scarcity forcing wage competition with aerospace sector recruiters. |
| Drone-Based Inspection Service Launch | Captures maintenance unbundling trends displacing OEM scheduled service agreements at aging onshore farms. |
Research Methodology
The analysis maps onshore replacement cycles, offshore tender pipelines, and aerospace derivative demand, each validated through composite plant managers, EPC contractor procurement leads, wind farm asset directors, and Bureau Veritas certification engineers. Primary fieldwork combined structured interviews with secondary validation against customs trade records, EU Green Deal implementation filings, and Saint-Nazaire port authority cargo manifests. Bottom-up blade unit forecasting triangulated against top-down energy capacity expansion targets from the Ministry of Ecological Transition.
Assumption sets held fixed the domestic content threshold escalation schedule while varying epoxy resin price trajectories and carbon fiber import tariff scenarios across the projection horizon. Segmentation dimensions modeled include blade material architecture, application vertical, end-user contract structure, and regional manufacturing corridor. CAGRs derived from unit demand build-ups applied to average selling price estimates, with forecast inputs incorporating decommissioning schedules for 2000s-era turbines and floating offshore lease activation timelines.
Sensitivities concentrate around Ministry of Ecological Transition tender timing delays, Baltic Sea shipping disruptions affecting epoxy feedstock, and Bureau Veritas certification backlog extensions. Forecasts embed assumptions on thermoplastic resin adoption rates and Portuguese precursor recycler capacity scaling. Quarterly review of offshore wind final investment decisions and carbon fiber spot price indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Commercial Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Aerospace and Defense C-Class Parts Market
Aircraft and Aerospace Components
Advanced Turbine Blade Design Market
Aircraft and Aerospace Components
Thrust Vector Control Market
Aircraft and Aerospace Components
Europe Military Aviation Market
Aircraft and Aerospace Components
Global Aerospace Wiring Harness Market
Aircraft and Aerospace Components
Composite Wing-to-Body Fairing Structures for Wide-Body Aircraft Market
Aircraft and Aerospace Components
Aerostructure Equipment Market
Aircraft and Aerospace Components
Multi-Foil Rotors Market
Aircraft and Aerospace Components
Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Aviation Electro Optical Systems Market
Aircraft and Aerospace Components
Composite Flap Track Fairing Systems for Drag Reduction Market
Aircraft and Aerospace Components
Europe Rotor Blade Market
Aircraft and Aerospace Components
Aerospace Nuts Market
Aircraft and Aerospace Components
Cold Gas Thrusters Market
Aircraft and Aerospace Components
Aerostructures Market