
 Global E Bomb Market | 2026-2036
Global E Bomb Market Size, Share, and Industry Trends Forecast 2026-2036
Global E Bomb Market Analysis
Defense procurement from government agencies is rebalancing toward electromagnetic pulse and radio frequency weapon systems as traditional kinetic munitions face supply chain constraints. Lockheed Martin leverages its directed-energy portfolio to sustain long-term contracts with the US Department of Defense. BAE Systems anchors European demand through its electronic warfare programs. RTX Corporation differentiates via integrated radar-kill chain technologies.
An electromagnetic bomb generates a burst of electromagnetic energy designed to disable electronic circuits, communication networks, and power distribution systems without structural destruction, typically producing field strengths exceeding thousands of volts per meter across a defined radius. Military Operations applications dominate current procurement volumes, while Cyber Warfare represents the fastest-growing segment as state actors prioritize non-kinetic disruption capabilities. Aerial Deployment systems command premium pricing due to platform integration complexity, whereas Ground-Based Launch configurations occupy the volume base across NATO-aligned forces.
The US Department of Defense shapes procurement through NNSA stockpile stewardship requirements and congressional directed-energy appropriations, while China's SAMR and MIIT coordinate civilian-military fusion standards for electromagnetic compatibility testing. The EU's dual-use export control framework and the Wassenaar Arrangement constrain technology transfer pathways for radio frequency weapon components. Stakeholders must monitor evolving classification thresholds that determine whether electromagnetic pulse systems fall under munitions or electronic warfare export licensing regimes.
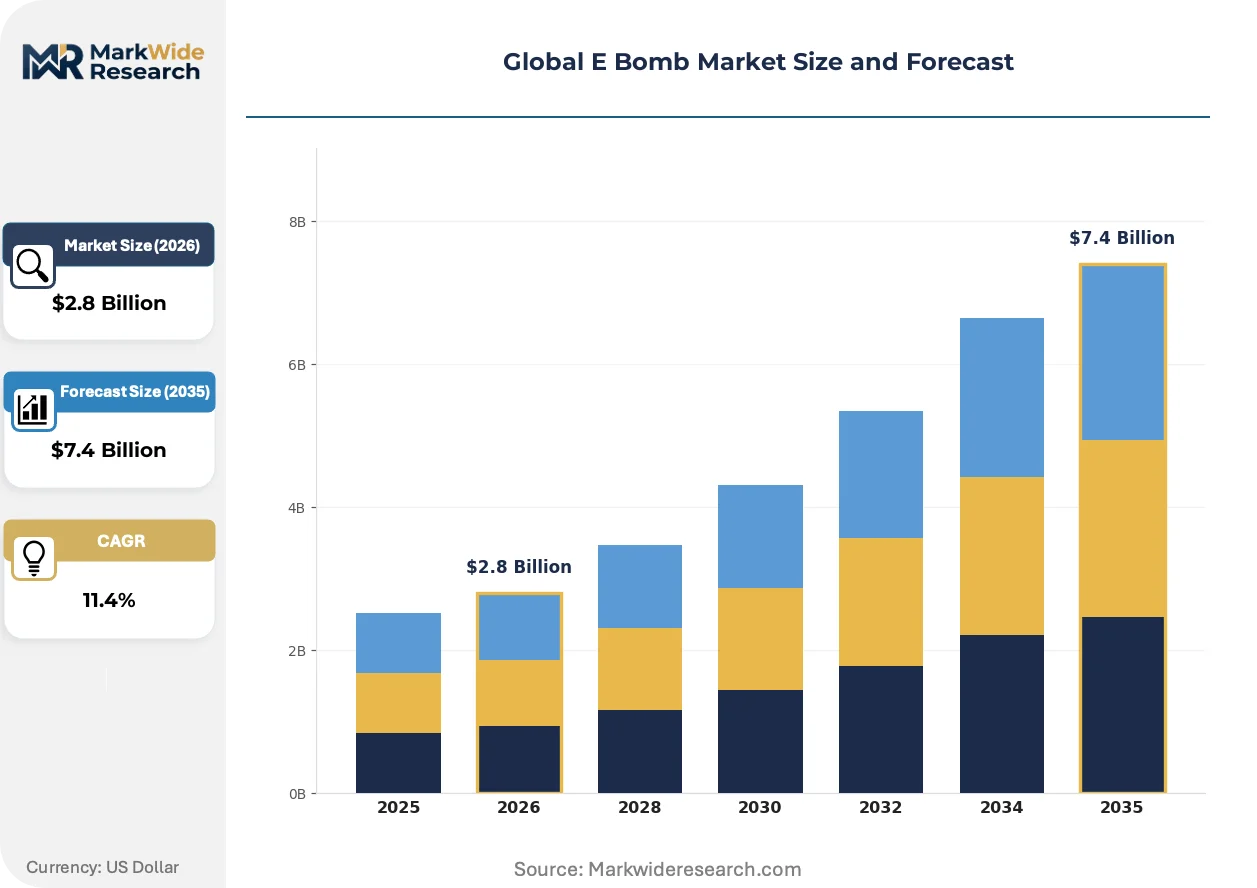
Market Dynamics
The US Department of Defense's congressional directed-energy appropriations are rebalancing procurement away from kinetic munitions toward electromagnetic pulse systems, compressing supplier qualification timelines and fragmenting contract awards across specialized electronic warfare vendors.
Growth Catalysts
- Civilian-Military Fusion Standards:China's SAMR and MIIT coordinate electromagnetic compatibility testing protocols that accelerate domestic supplier certification cycles and reduce platform integration costs for state-owned defense enterprises.
- Non-Kinetic Warfare Doctrine:NATO-aligned forces prioritize electronic attack capabilities over explosive ordnance, creating sustained demand for radio frequency weapons that disable infrastructure without physical destruction.
- Directed-Energy Funding Streams:US congressional appropriations through NNSA stockpile stewardship requirements channel capital into high-power microwave source development and pulse-forming network manufacturing.
Market Restraints
- Export Control Friction:The Wassenaar Arrangement and EU dual-use framework impose licensing delays on radio frequency weapon components, constraining cross-border technology transfer for gallium nitride high-power amplifiers.
- Platform Integration Complexity:Aerial deployment systems require extensive electromagnetic interference hardening and airframe modification, extending qualification cycles and elevating non-recurring engineering costs for prime contractors.
- Power Density Limitations:Current Marx generator and flux compression generator architectures face thermal management constraints that cap effective radiated power for man-portable configurations.
Strategic Opportunities
- Cyber Warfare Convergence:State actors in Israel and the United States pursue integrated electromagnetic-cyber attack capabilities, opening procurement channels for systems that bridge physical destruction and network infiltration.
- Ground-Based Volume Expansion:NATO's eastern flank members seek fixed-site electromagnetic pulse installations for critical infrastructure protection, creating demand clusters outside traditional aerial platform markets.
- Standardization Tailwinds:IEC and ISO initiatives on electromagnetic environment effects testing promise harmonized certification pathways that reduce duplicate qualification costs for multi-national defense suppliers.
Industry Challenges
- Specialized Workforce Scarcity:High-power electromagnetics engineering and pulsed power physics expertise concentrates within national laboratories and a limited cohort of defense primes, constraining supplier base expansion.
- Classification-Induced Information Asymmetry:Program-level electromagnetic weapon specifications often reside within compartmentalized security envelopes, complicating requirements definition and technical proposal preparation for qualified bidders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global E Bomb Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic Pulse, Radio Frequency Weapon, Non-Lethal Disruption Device, Power Distribution Interference Application: Military Operations, Cyber Warfare, Defense Strategies, Infrastructure Protection Delivery Mode: Aerial Deployment, Ground-Based Launch, Maritime Delivery, Tactical Use End User: Government Agencies, Military Contractors, Defense Groups, Security Organizations |
| Companies Covered | Lockheed Martin Corporation, The Boeing Company, BAE Systems plc, RTX Corporation, Northrop Grumman Corporation, General Dynamics Corporation, Textron Inc, L3Harris Technologies, Denel SOC Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global E Bomb Market Emerging Trajectories
Directed-energy system architectures are rewriting competitive positioning across the electromagnetic weapons value chain, as solid-state radio frequency sources displace legacy vacuum tube technologies and software-defined waveform generation enables mission-specific pulse tailoring.
Solid-state gallium nitride power amplifiers are rewriting the economics of high-power microwave systems by enabling compact airborne platforms previously restricted to ground-based installations. US Air Force Research Laboratory programs are accelerating transition of these devices from laboratory demonstration to operational testing. The shift is compressing supplier margins for traveling wave tube manufacturers while elevating semiconductor foundry capacity allocation as a strategic chokepoint.
The EU's dual-use export control framework revision is tightening technology transfer pathways for radio frequency weapon subcomponents, particularly gallium arsenide and gallium nitride epitaxial wafers. European prime contractors face extended end-user verification timelines for sales to non-NATO partners. Israeli and South Korean suppliers are responding by deepening domestic compound semiconductor fabrication capabilities to circumvent licensing dependencies.
Defense procurement offices are consolidating electromagnetic weapon requirements into multi-year indefinite-delivery contracts with technical refresh clauses, displacing traditional single-program milestone awards. This contractual evolution favors suppliers with sustained research and development pipelines over point-solution vendors. The United States and China exhibit the most pronounced shift toward this model, with China's state-owned defense conglomerates internalizing supply chains to match this procurement rhythm.
Global E Bomb Market Segmentation
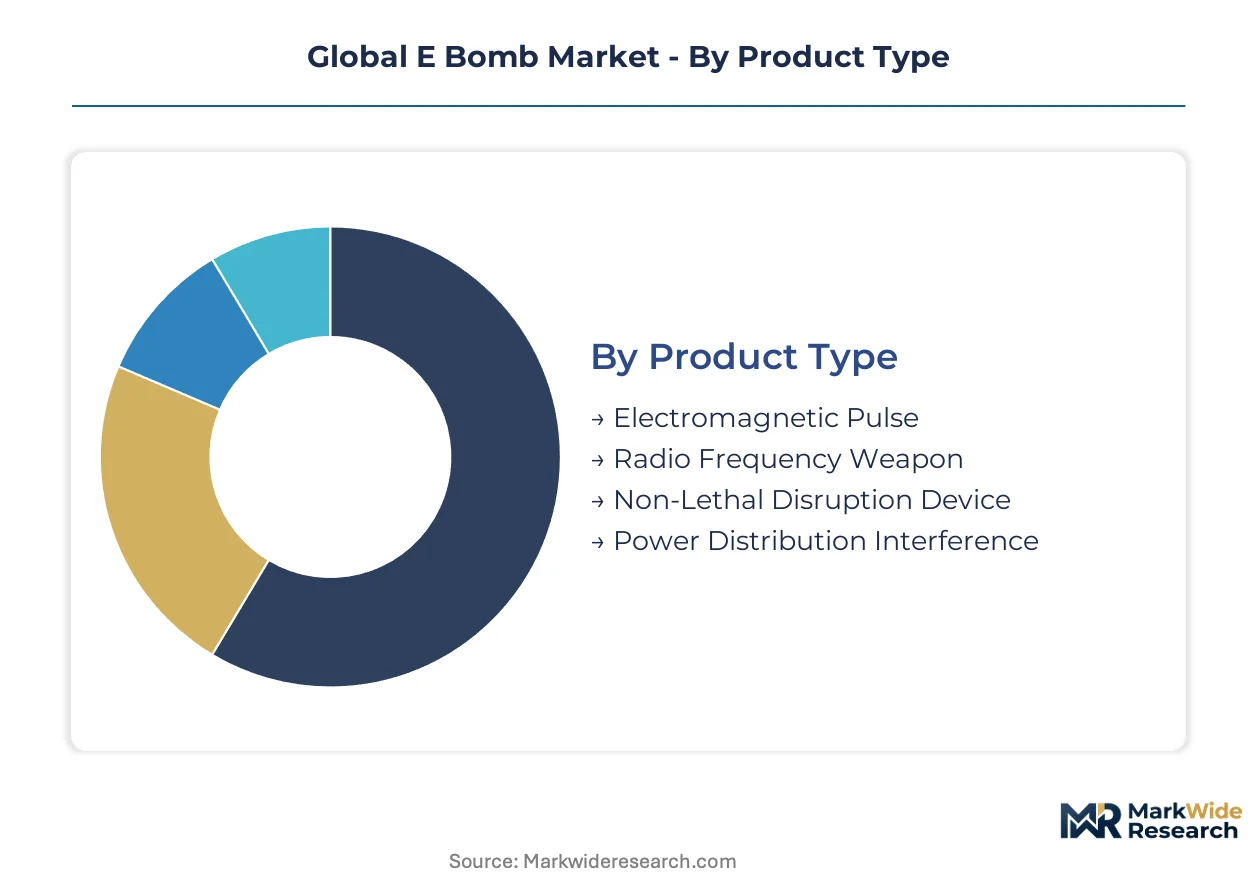
Electromagnetic weapon procurement splits along integration depth lines—standalone systems for strategic infrastructure protection versus embedded modules for platform-agnostic deployment. Understanding these boundaries clarifies where defense primes invest non-recurring engineering versus where specialized vendors capture recurring component demand.
Product Type:
Standalone pulse generators require hardened enclosures and dedicated power conditioning, while embedded radio frequency modules integrate into existing electronic warfare suites with minimal platform modification.
- Electromagnetic Pulse:High-power microwave sources producing field strengths exceeding thousands of volts per meter across defined radii. Procurement concentrates in United States and Chinese strategic deterrent programs, driven by congressional appropriations for stockpile stewardship and civilian-military fusion standardization.
- Radio Frequency Weapon:Directional energy systems targeting specific electronic vulnerabilities through tailored waveform generation. Israeli and United States defense groups prioritize these for integrated electromagnetic-cyber attack capabilities, compressing supplier qualification timelines for gallium nitride amplifier vendors.
- Non-Lethal Disruption Device:Lower-power configurations for perimeter security and crowd control applications.
- Power Distribution Interference:Grid-scale systems targeting electrical infrastructure without physical destruction.
Volume placements concentrate in Electromagnetic Pulse systems; the faster expansion belongs to Radio Frequency Weapon configurations.
Application:
Cost tiers separate capital-intensive strategic programs from tactical systems with shorter procurement cycles and lower technical barriers to entry.
- Military Operations:Platform-integrated electronic attack capabilities for kinetic suppression and air defense degradation. NATO-aligned forces and Chinese People's Liberation Army units drive procurement, prioritizing non-kinetic disruption over explosive ordnance to circumvent supply chain constraints affecting traditional munitions.
- Cyber Warfare:Convergent systems bridging physical electromagnetic effects with network infiltration payloads. United States Cyber Command and Israeli military intelligence services anchor demand, seeking capabilities that disable hardware while preserving data exfiltration pathways.
- Defense Strategies:Doctrine development and wargaming support for electromagnetic combat scenarios.
- Infrastructure Protection:Fixed-site installations guarding critical facilities against adversary electromagnetic attack.
Volume placements concentrate in Military Operations; Cyber Warfare exhibits the steepest expansion trajectory as state actors prioritize dual-domain attack capabilities.
Delivery Mode:
Platform integration complexity creates margin differentiation—aerial systems command premium pricing for airframe modification and electromagnetic interference hardening, while ground configurations compete on unit cost and rapid deployment.
- Aerial Deployment:Cruise missile, unmanned aerial vehicle, and manned aircraft integration requiring extensive airframe modification and flight certification. United States Air Force Research Laboratory programs and Chinese aerospace conglomerates dominate procurement, absorbing elevated non-recurring engineering costs for operational testing.
- Ground-Based Launch:Mobile and fixed-site configurations serving volume demand across NATO's eastern flank members. Polish and Romanian defense ministries seek these for critical infrastructure protection, creating demand clusters outside traditional aerial platform markets.
- Maritime Delivery:Ship-mounted and submarine-launch systems for naval electronic warfare.
- Tactical Use:Man-portable configurations constrained by thermal management and power density limitations.
Volume placements concentrate in Ground-Based Launch; Maritime Delivery is gaining share fastest as naval electronic warfare budgets expand.
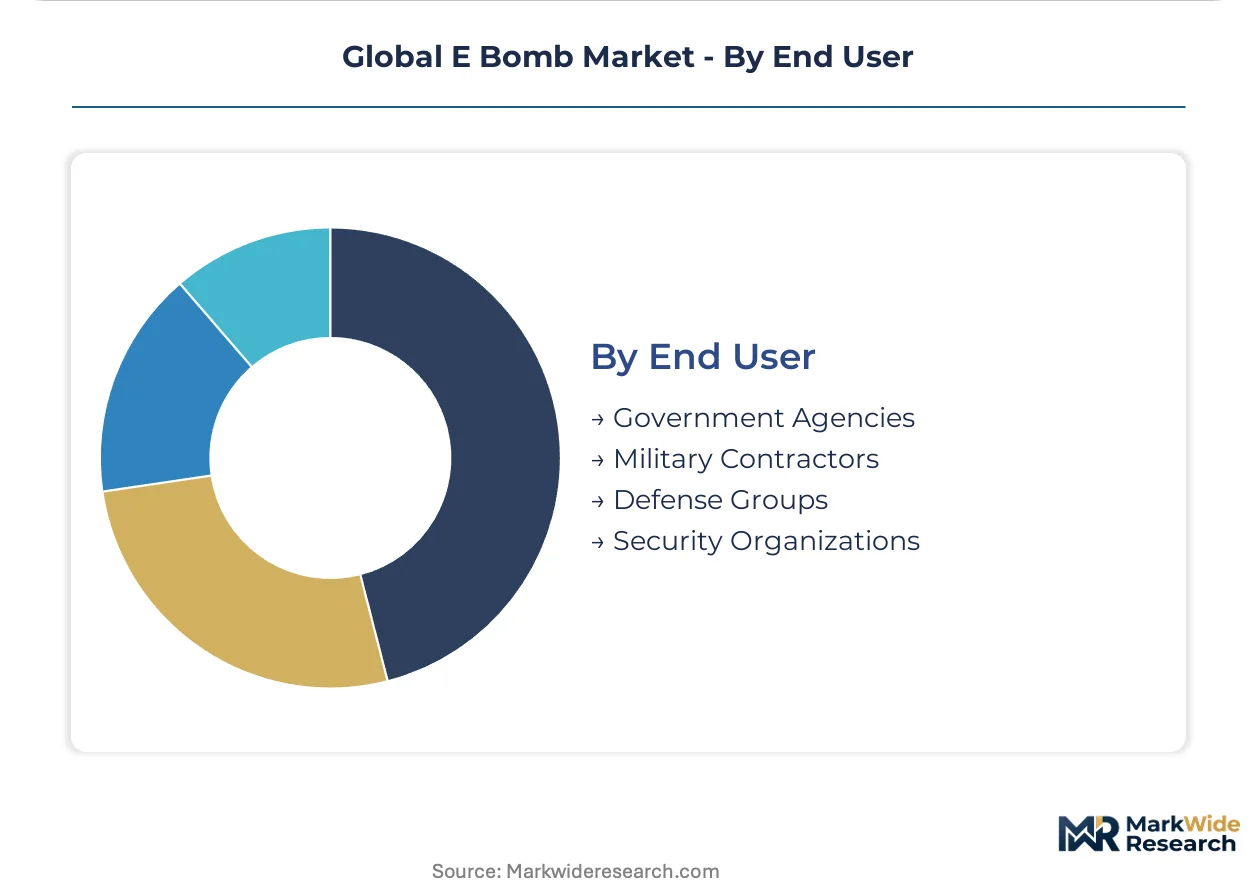
End User:
Customer type determines contracting structure—government agencies drive multi-year indefinite-delivery awards with technical refresh clauses, while military contractors compete for sub-tier component supply with shorter cycle times.
- Government Agencies:National laboratories, defense ministries, and intelligence services defining requirements and funding development. United States Department of Defense and China's State Administration for Market Regulation coordinate procurement through congressional appropriations and civilian-military fusion frameworks respectively.
- Military Contractors:Prime and sub-tier suppliers executing platform integration and manufacturing. Lockheed Martin and BAE Systems anchor this segment through sustained research pipelines matching multi-year contracting rhythms.
- Defense Groups:Multi-national consortiums and alliance structures pooling procurement resources.
- Security Organizations:Non-military government security services with constrained budgets and rapid deployment requirements.
Volume placements concentrate in Government Agencies; Military Contractors are expanding most quickly as supply chain consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense production concentrates in the United States and China, while procurement demand spreads across NATO-aligned forces and Middle Eastern defense ministries seeking electromagnetic pulse capabilities.
United States
Congressional directed-energy appropriations through NNSA stockpile stewardship requirements channel capital into high-power microwave development. The Department of Defense compresses supplier qualification timelines for electromagnetic pulse systems. Albuquerque and Livermore national laboratories anchor research clusters where pulse-forming network manufacturing scales toward operational testing.
China
Civilian-military fusion standards from SAMR and MIIT accelerate domestic supplier certification for state-owned defense enterprises. The People's Liberation Army prioritizes electromagnetic compatibility testing protocols for platform integration. Beijing and Chengdu host concentrated research activity where aerospace conglomerates internalize gallium nitride amplifier supply chains.
Israel
Military intelligence services anchor procurement for integrated electromagnetic-cyber attack capabilities bridging physical destruction and network infiltration. The national defense establishment channels funding toward non-kinetic disruption systems. Tel Aviv and Haifa clusters concentrate specialized workforce expertise in high-power electromagnetics engineering and pulsed power physics.
United Kingdom
BAE Systems anchors European demand through sustained electronic warfare program pipelines matching multi-year contracting rhythms. The Ministry of Defence aligns procurement with NATO non-kinetic warfare doctrine prioritizing electronic attack over explosive ordnance. Bristol and Lancashire house concentrated manufacturing activity where prime contractors execute platform integration for aerial deployment systems.
Poland
The defense ministry seeks fixed-site electromagnetic pulse installations for critical infrastructure protection along NATO's eastern flank. National procurement channels prioritize ground-based launch configurations for rapid deployment requirements. Warsaw and Wrocław clusters emerge as demand centers outside traditional aerial platform markets, absorbing volume placements for mobile configurations.
Global E Bomb Market Vendor Landscape
Top-tier vendors anchor multi-year indefinite-delivery contracts with technical refresh clauses, while specialized electronic warfare suppliers compete for sub-tier component awards with shorter cycle times. The supplier base concentrates among defense primes with sustained research pipelines and semiconductor foundries controlling gallium nitride epitaxial wafer capacity. Two strategic archetypes dominate: integrated platform-weapon system houses and compound semiconductor fabrication specialists. Competitive moves center on supply chain consolidation through captive semiconductor production and backward integration into pulsed power component manufacturing.
Among United States-based defense primes, Lockheed Martin Corporation, RTX Corporation, and Northrop Grumman Corporation occupy positions exemplifying the integrated platform-weapon system archetype. These entities represent sustained research and development pipelines matching multi-year contracting rhythms. Lockheed Martin anchors directed-energy portfolio positioning through long-term Department of Defense relationships. RTX Corporation sits within the radar-kill chain integration tier. Northrop Grumman exemplifies the electronic attack systems specialization vector where mission-specific pulse tailoring capabilities concentrate.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| The Boeing Company |
| BAE Systems plc |
| RTX Corporation |
| Northrop Grumman Corporation |
| General Dynamics Corporation |
| Textron Inc |
| L3Harris Technologies |
| Denel SOC Ltd |
| Others |
Supply Flow & Price Mechanics
EU dual-use export control framework revisions gate qualified supply for gallium nitride high-power amplifiers while reserving premium-tier pricing access for vendors with captive epitaxial wafer fabrication. Compliance certification with Wassenaar Arrangement licensing thresholds separates standard component suppliers from systems integrators commanding technical refresh contract premiums.
Pricing Analysis
Margin tightening in aerial deployment systems reflects airframe modification non-recurring engineering cost absorption by prime contractors. Project-based pricing dominates electromagnetic pulse procurement, with differentiation driven by IEC electromagnetic environment effects certification tier and after-sales technical refresh bundling. Cost-down pressure on ground-based launch configurations accelerates as NATO eastern flank members consolidate volume awards. Government agencies exhibit lowest price sensitivity due to multi-year indefinite-delivery contracting authority, while security organizations face highest budget constraints.
Supply Chain Analysis
Domestic-content mandates from China's MIIT and SAMR reshape sourcing patterns for civilian-military fusion standards compliance, forcing foreign suppliers into joint venture structures. Supply concentrates in the United States, China, and Israel for pulse-forming network manufacturing, drawing from gallium nitride epitaxial wafers, Marx generator capacitors, and flux compression generator components. Single-source vulnerability in compound semiconductor foundry capacity poses structural risk. Distribution runs through defense primes executing platform integration and national laboratories channeling research-to-production transition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state gallium nitride power amplifiers are displacing vacuum tube traveling wave tubes across high-power microwave architectures, compressing supplier margins for legacy technology holders while elevating semiconductor fabrication capacity as the decisive competitive chokepoint.
For Market Incumbents: Deepen captive gallium nitride epitaxial wafer production to circumvent EU dual-use licensing dependencies and secure technical refresh contract positioning. Acquire specialized pulsed power physics workforce clusters in Albuquerque and Livermore to defend against compound semiconductor fabrication specialists encroaching on systems integration. Prioritize backward integration into Marx generator component manufacturing. For New Entrants and Emerging Players: Launch via direct contracting with Poland and Romania defense ministries for ground-based launch configurations, bypassing aerial platform qualification barriers. Target cyber warfare convergence applications as the most penetrable segment, where electromagnetic-cyber attack capability gaps create procurement channel openings. Pursue gallium nitride amplifier sub-tier supply to prime contractors as the fastest qualification pathway. For Investors and Strategic Acquirers: US Air Force Research Laboratory solid-state transition program acceleration is the leading indicator that semiconductor fabrication capacity allocation will determine long-term vendor viability. Position acquisition screening toward compound semiconductor foundries with defense-qualified processes and electromagnetic compatibility testing certification. Watch for IEC electromagnetic environment effects standardization harmonization as the signal for multi-national contract scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Gallium Nitride Fabrication | Secures supply autonomy against EU dual-use licensing constraints for radio frequency weapon exports. |
| Electromagnetic-Cyber Convergence Development | Opens procurement channels with US Cyber Command and Israeli military intelligence services. |
| Ground-Based Launch Configuration Expansion | Captures NATO eastern flank demand clusters outside traditional aerial platform markets. |
| IEC Standardization Pre-Compliance Investment | Reduces duplicate qualification costs for multi-national defense suppliers across member states. |
| Pulsed Power Physics Workforce Acquisition | Addresses specialized expertise scarcity concentrated in national laboratory clusters. |
Methodological Framework
Congressional appropriation records, Wassenaar Arrangement licensing databases, and SEC 10-K defense segment disclosures formed the secondary backbone for market sizing. Primary interviews with directed-energy program officers, electromagnetic compatibility testing engineers, and defense procurement contract specialists validated segment assumptions. Bottom-up triangulation across product type, application, and delivery mode dimensions converged with top-down congressional funding flow analysis.
Historical trendline analysis of NNSA stockpile stewardship appropriations and civilian-military fusion budget allocations established baseline growth patterns across the projection horizon. The analytical framework modeled electromagnetic pulse systems, radio frequency weapons, non-lethal disruption devices, and power distribution interference configurations by military operations, cyber warfare, defense strategies, and infrastructure protection applications. CAGRs derived from procurement cycle compression rates and platform integration qualification timelines. Forecast inputs incorporated directed-energy funding stream continuity and compound semiconductor fabrication capacity expansion trajectories.
The model assumes a particular technology adoption path favoring solid-state gallium nitride architectures; alternative pathways for vacuum tube traveling wave tube retention would alter the outlook for incumbent supplier margins. Forecasts reflect assumptions regarding congressional appropriation continuity and export control framework stability. Alternative electromagnetic weapon classification thresholds or civilian-military fusion standardization delays would revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Small and Medium Caliber Ammunition Market
Weapons and Ammunition
Weapon Mounts Market
Weapons and Ammunition
Military Fire Control Systems Market
Weapons and Ammunition
Shotgun Shell Market
Weapons and Ammunition
Command Fuzes Market
Weapons and Ammunition
Weapons and Ammunition Market
Weapons and Ammunition
Programmable Ammunition Market
Weapons and Ammunition
Particle Beam Directed Energy Weapon Market
Weapons and Ammunition
Nuclear Bomb Market
Weapons and Ammunition
Missile Launching Systems Market
Weapons and Ammunition
Non Lethal Projectiles Market
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Next-Generation Assault Rifles Market
Weapons and Ammunition
North America Small Arms Market
Weapons and Ammunition
Precision Guided Munition Market
Weapons and Ammunition
APAC Ballistic Missile Market