
 Global Rockets and Missiles Market | 2026-2036
Global Rockets and Missiles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rockets and Missiles Market Outlook
Software-defined guidance and targeting architectures is restructuring what defense contractors deliver to military buyers. Lockheed Martin Corporation leverages its vertically integrated production of hypersonic glide bodies to sustain program margins across multiple Pentagon contracts. RTX Corporation anchors its position through captive solid-rocket motor manufacturing that insulates supply from propellant shortages. Northrop Grumman Corporation dominates space launch integration by controlling both booster production and satellite bus assembly.
Rockets and missiles are self-propelled aerospace vehicles incorporating warheads, guidance systems, and propulsion subsystems designed to deliver payloads across atmospheric or exoatmospheric trajectories with specified circular error probable. Solid propellant configurations now lead tactical missile production due to simplified storage requirements and reduced launch-preparation intervals compared to liquid-fueled alternatives. Ballistic missiles concentrate the largest value pool among product types because intercontinental and medium-range systems command unit prices orders of magnitude above tactical alternatives. Defense applications absorb the majority of segment value, though commercial launch represents the fastest-expanding application category as satellite constellation operators proliferate.
Defense procurement in the United States operates under Federal Acquisition Regulation oversight with supplemental Missile Defense Agency technical standards, while European programs must satisfy NATO STANAG interoperability requirements and REACH chemical restrictions on propellant formulations. China's SAMR and military-civil fusion directives shape competitive access for foreign suppliers across Asia-Pacific programs. Stakeholders must monitor how export control regimes and domestic content mandates fragment supplier eligibility across national procurement pipelines.
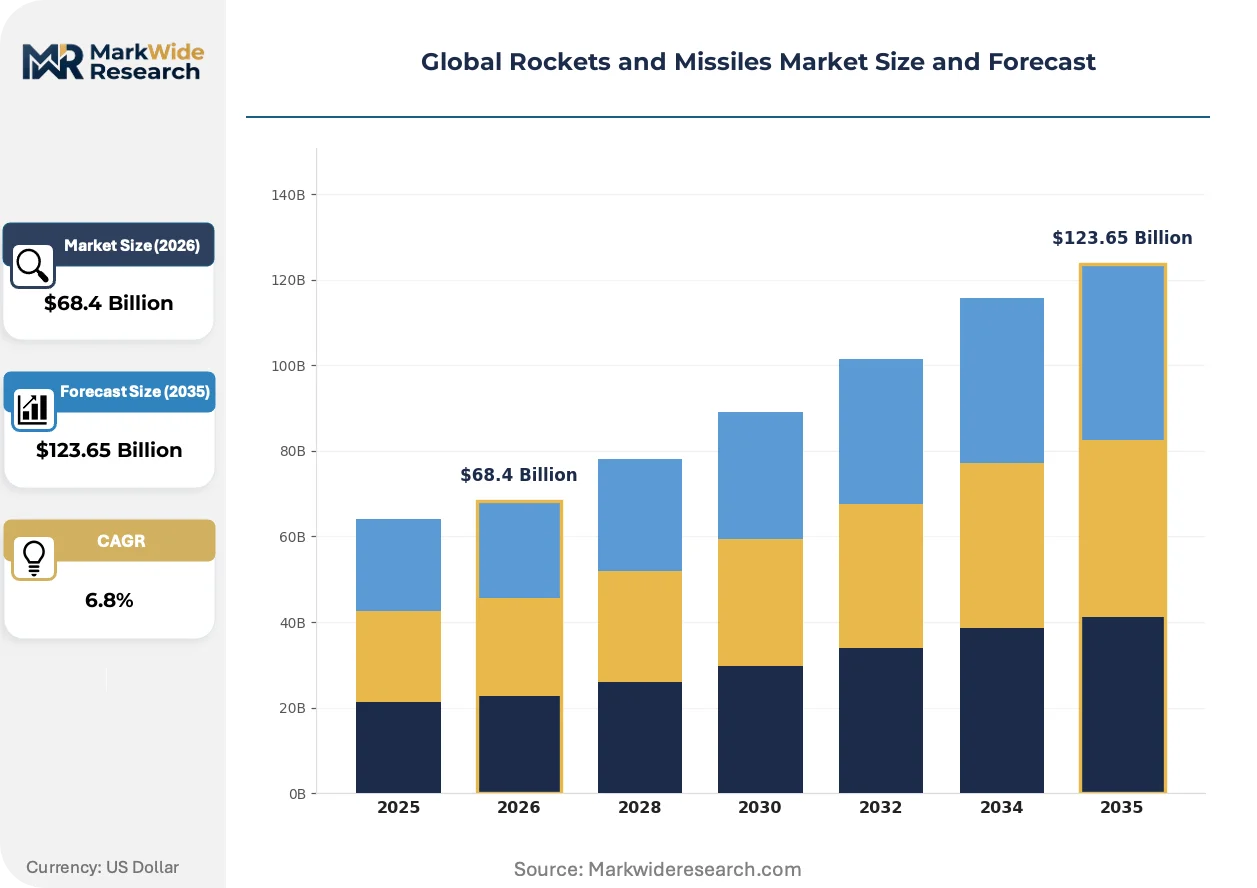
Market Dynamics
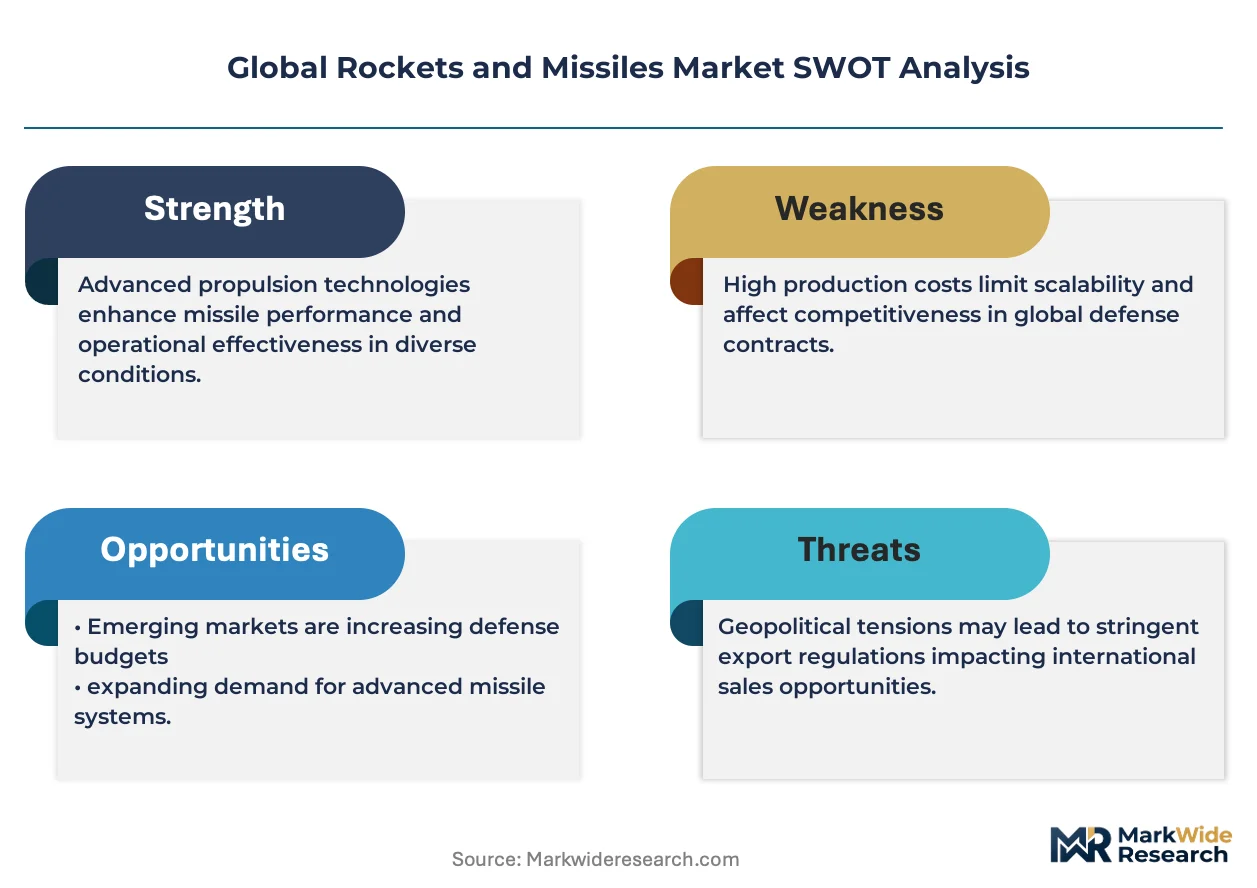
Solid propellant chemistry is displacing liquid-fueled architectures across tactical missile programs, compressing launch-preparation intervals and reshaping supplier qualification requirements for defense contractors.
Growth Catalysts
- Precision-Strike Procurement:NATO member states are expanding acquisition of guided munitions under collective defense modernization frameworks, with Poland and Germany accelerating multiyear framework agreements for long-range fires.
- Dual-Use Launch Infrastructure:Satellite constellation operators in the United States and China are absorbing excess solid-motor production capacity originally scaled for defense programs, creating cross-subsidy economics for propulsion suppliers.
- Indigenization Mandates:India's Defence Acquisition Procedure 2020 prioritizes domestic content thresholds for missile systems, channeling state capital into captive propellant synthesis and guidance electronics fabrication.
Market Restraints
- Ammonium Perchlorate Supply Concentration:North American suppliers control over eighty percent of global solid-oxidizer production, exposing missile manufacturers to single-source pricing volatility and force majeure risk.
- ITAR Export Control Friction:United States International Traffic in Arms Regulations impose licensing timelines exceeding eighteen months for subsystem transfers, fragmenting supplier eligibility across allied procurement pipelines.
- Hypersonic Thermal Protection Limits:Ceramic matrix composites for glide-body nosecones face yield-rate constraints below forty percent at volume, capping production scalability regardless of program funding.
Strategic Opportunities
- Commercial Launch Channel Expansion:Reusable booster recovery is creating aftermarket demand for solid-rocket motor refurbishment services, with SpaceX and Blue Origin establishing qualification protocols for third-party propulsion maintenance.
- Hypersonic Defense Architecture:United States Missile Defense Agency layered defense mandates are opening adjacent markets for interceptors with divert-and-attitude-control systems, extending addressable scope beyond strike applications.
- Green Propellant Transition:European Space Agency Clean Space initiative is funding ammonium dinitramide formulations to replace hydrazine derivatives, creating first-mover advantage for compliant chemistry suppliers.
Industry Challenges
- Systems Engineering Talent Scarcity:Guidance-navigation-control integration requires specialized expertise in Kalman filtering and sensor fusion, with defense contractors competing against commercial autonomy programs for the same finite labor pool.
- Range Certification Backlogs:United States Eastern and Western Range launch windows face eighteen-month scheduling queues, constraining flight-test velocity for new entrant missile programs regardless of technical readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rockets and Missiles Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballistic Missiles, Cruise Missiles, Space Launch Vehicles, Tactical Missiles Technology: Solid Propellant, Liquid Propellant, Hybrid Propellant, Air-Breathing Propellant Application: Defense, Space Exploration, Research, Commercial Launch End User: Governments, Military Organizations, Private Companies, Research Institutions |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, Northrop Grumman Corporation, Boeing, MBDA, BAE Systems, General Dynamics Corporation, Raytheon Technologies Corporation, KONGSBERG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rockets and Missiles Market Strategic Shifts
Software-defined architectures are penetrating guidance and targeting subsystems, enabling firmware updates post-deployment and compressing obsolescence cycles for fielded munitions across multiple defense ministries.
Multi-mode seekers combining radar with imaging infrared is rewriting engagement geometry for anti-ship applications. United States Navy Distributed Maritime Operations doctrine demands salvo-coordinated targeting across dispersed launch platforms. This capability is compressing the tradable space between standoff range and terminal accuracy that previously separated cruise from ballistic alternatives.
REACH chemical restrictions on perchlorate discharge are compelling European propellant manufacturers to reformulate binders and plasticizers. Germany's KBA and France's ANSM are coordinating transitional approval pathways for alternative oxidizer chemistries. Tactical missile programs with European supply chains face eighteen-to-twenty-four month qualification delays for compliant motor configurations.
Defense procurement offices are consolidating vendor pools through multi-year indefinite-delivery contracts, displacing transactional spot-buying for subsystems. United States Army Futures Command and United Kingdom Defence Equipment and Support are piloting this model for precision fires. Supplier selection in these programs now hinges on digital engineering maturity rather than unit-cost bidding.
Global Rockets and Missiles Market Segmentation
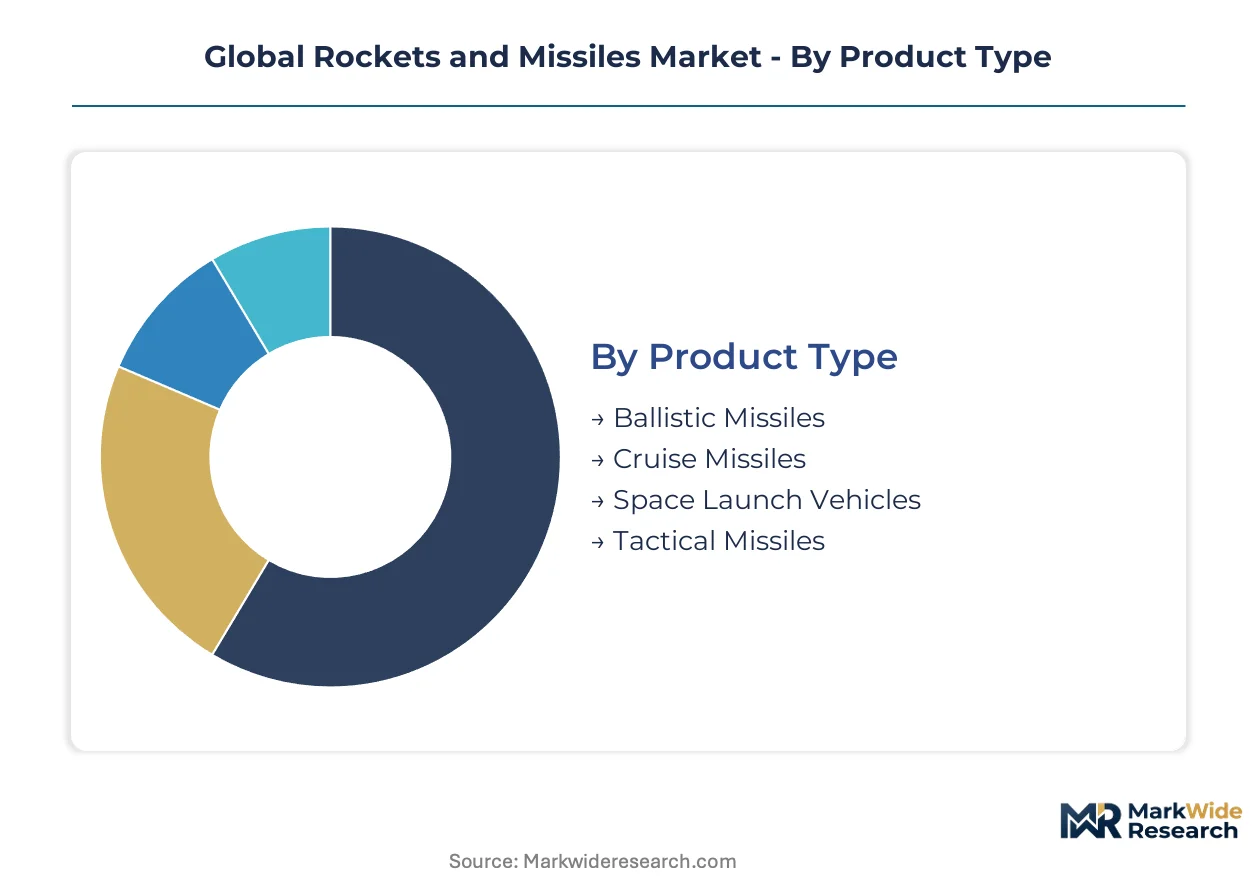
Segmentation in rockets and missiles reveals how procurement specialization fragments supplier economics. Defense ministries prioritize reliability and range. Commercial operators optimize cost-per-kilogram to orbit. Each segment commands distinct qualification protocols and margin structures.
Product Type:
Standardization dominates ballistic and cruise architectures where NATO STANAG interoperability governs interface specifications. Customization concentrates in tactical variants and dedicated space launch platforms where mission profiles vary by payload and trajectory requirements.
- Ballistic Missiles:These systems follow parabolic trajectories with exoatmospheric apogee and reentry vehicle separation. Demand concentrates in the United States, China, and India as these nations modernize intercontinental and medium-range deterrent arsenals under strategic stability frameworks. Unit economics favor solid propellant configurations for reduced launch-preparation intervals.
- Cruise Missiles:Air-breathing or turbine-powered systems sustain atmospheric flight through terrain-following guidance. Poland and Germany are accelerating multiyear framework agreements for long-range precision fires under NATO collective defense modernization. Multi-mode seekers combining radar with imaging infrared are compressing engagement geometry for anti-ship applications.
- Space Launch Vehicles:Expendable and partially reusable boosters deliver satellites to specified orbital inclinations. Reusable booster recovery is creating aftermarket demand for solid-rocket motor refurbishment services.
- Tactical Missiles:Short-to-medium range systems for battlefield engagement including anti-tank, anti-aircraft, and surface-to-surface roles. India's Defence Acquisition Procedure 2020 prioritizes domestic content thresholds for these systems.
Most installed capacity flows through Ballistic Missiles. Expansion is steepest in Space Launch Vehicles.
Technology:
Cost tier separation is pronounced: solid propellant commands premium pricing for tactical applications where storage simplicity justifies higher chemistry costs. Liquid systems retain volume leadership in heavy-lift launch where throttle control and restart capability offset complexity penalties.
- Solid Propellant:Composite formulations of ammonium perchlorate oxidizer, aluminum fuel, and hydroxyl-terminated polybutadiene binder enable storable, instant-launch readiness. United States Missile Defense Agency layered defense mandates are opening adjacent markets for interceptors with divert-and-attitude-control systems using solid propulsion. REACH chemical restrictions on perchlorate discharge are compelling European manufacturers to reformulate binders and plasticizers.
- Liquid Propellant:Cryogenic or storable liquid oxygen and hydrocarbon combinations deliver higher specific impulse for orbital insertion burns. China's SAMR and military-civil fusion directives shape competitive access for foreign suppliers across Asia-Pacific programs using liquid architectures.
- Hybrid Propellant:Combines solid fuel grain with liquid or gaseous oxidizer for throttle flexibility without full liquid complexity. European Space Agency Clean Space initiative is funding ammonium dinitramide formulations to replace hydrazine derivatives.
- Air-Breathing Propellant:Turbojet, ramjet, or scramjet engines ingest atmospheric oxygen for sustained cruise flight. Thermal protection limits for hypersonic glide bodies face yield-rate constraints below forty percent at volume.
Production gravity centers on Solid Propellant for defense applications. Steepest expansion trajectory belongs to Air-Breathing Propellant as hypersonic programs mature.
Application:
Customer type bifurcation is extreme: defense procurement operates under Federal Acquisition Regulation oversight with eighteen-month ITAR licensing timelines, while commercial launch faces range certification backlogs at United States Eastern and Western Ranges regardless of technical readiness.
- Defense:Integrated weapon systems with warheads, guidance, and propulsion subsystems designed to specified circular error probable. United States Army Futures Command and United Kingdom Defence Equipment and Support are piloting multi-year indefinite-delivery contracts displacing transactional spot-buying.
- Space Exploration:Scientific payload delivery beyond low Earth orbit including lunar, planetary, and deep-space missions. NASA and ESA programs dominate demand concentration.
- Research:Suborbital sounding rockets and technology demonstration vehicles for atmospheric science and subsystem validation. Universities and national laboratories anchor procurement.
- Commercial Launch:Satellite constellation deployment and hosted payload services. Satellite constellation operators in the United States and China are absorbing excess solid-motor production capacity originally scaled for defense programs.
Defense absorbs the majority of segment value. Commercial Launch is gaining share fastest as constellation operators proliferate.
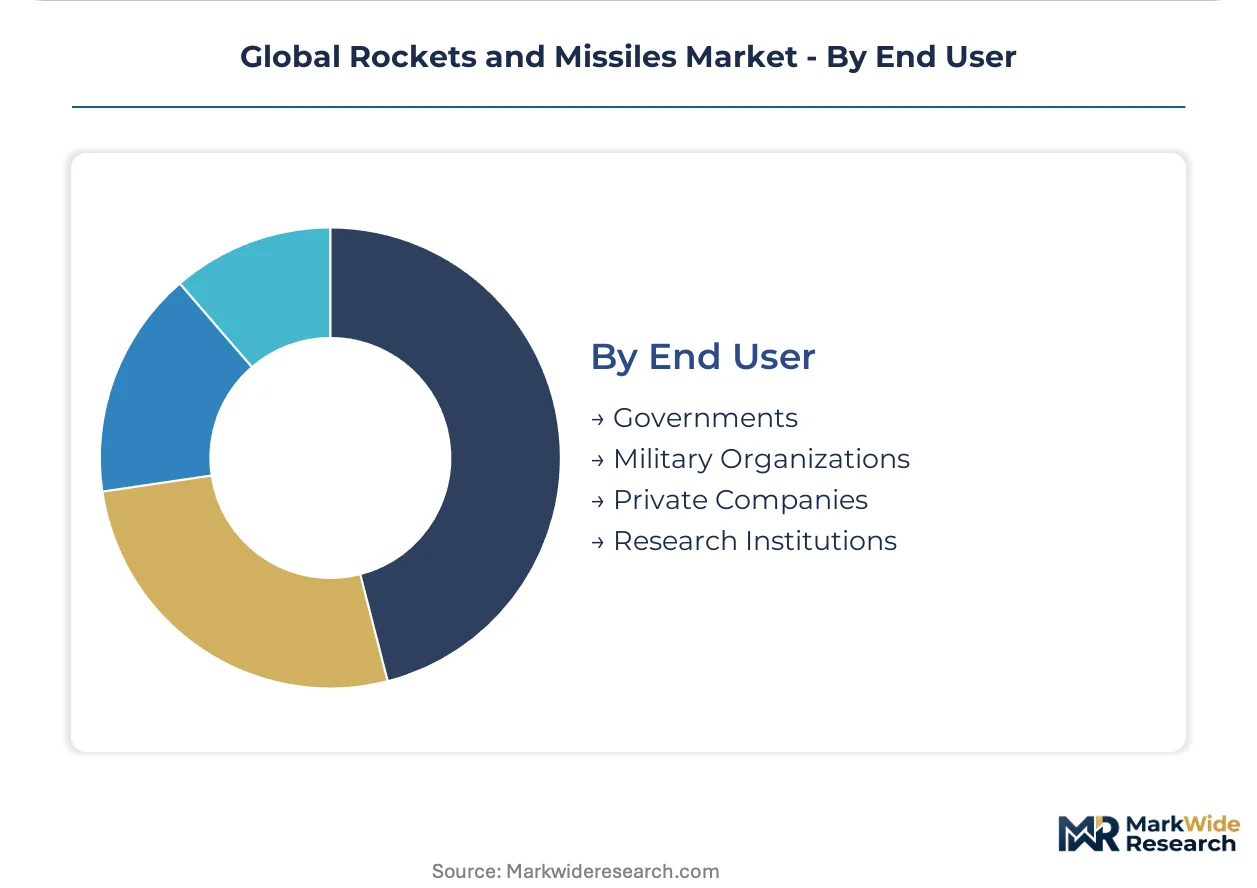
End User:
Procurement authority concentration varies sharply: military organizations consolidate through framework agreements while private companies fragment across spot-buy and dedicated launch contracts. Research institutions occupy intermediate volume with specialized qualification requirements.
- Governments:National space agencies and defense ministries with sovereign launch capability requirements. Federal Acquisition Regulation oversight and Missile Defense Agency technical standards govern United States procurement.
- Military Organizations:Service branches with theater-specific mission requirements and interoperability mandates. NATO STANAG requirements shape European program specifications.
- Private Companies:Satellite operators, launch service providers, and emerging space infrastructure developers. SpaceX and Blue Origin are establishing qualification protocols for third-party propulsion maintenance.
- Research Institutions:Universities, national laboratories, and international scientific consortia. Range certification backlogs constrain flight-test velocity regardless of technical readiness.
Military Organizations channel the largest procurement volumes. Private Companies are expanding most quickly as commercial launch capacity democratizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's military-civil fusion directives accelerate indigenous propulsion programs while the United States maintains Federal Acquisition Regulation oversight of precision-strike procurement. India channels state capital into domestic content thresholds as European NATO members confront REACH chemical restrictions on solid-oxidizer formulations.
United States
Pentagon multi-year indefinite-delivery contracts for precision fires and Missile Defense Agency interceptor mandates drive procurement volume. Federal Acquisition Regulation oversight combines with eighteen-month ITAR licensing timelines that fragment supplier eligibility. Huntsville, Alabama anchors solid-rocket motor production clusters where captive propellant synthesis insulates defense contractors from ammonium perchlorate supply volatility.
China
Indigenous launch and defense programs absorb state-directed investment under SAMR technical standard-setting and military-civil fusion policy integration. The country's national aerospace regulator coordinates dual-use infrastructure development across state-owned defense conglomerates. Xian and Shanghai metropolitan clusters concentrate booster integration facilities where liquid and solid propellant architectures serve both commercial constellation deployment and strategic deterrent modernization.
India
Defence Acquisition Procedure 2020 prioritizes domestic content thresholds for tactical missile systems and short-range battlefield engagement platforms. The central defense procurement authority channels state capital into captive propellant synthesis and guidance electronics fabrication. Hyderabad and Bengaluru anchor emerging propulsion and avionics clusters where public-private partnerships accelerate indigenous seeker and divert-attitude-control subsystem qualification.
Germany
NATO STANAG interoperability requirements shape long-range precision fires procurement alongside Poland under collective defense modernization frameworks. KBA coordinates transitional approval pathways for REACH-compliant propellant formulations that replace perchlorate oxidizers. Bavaria and Baden-Württemberg concentrate subsystem engineering clusters where German defense contractors reformulate binders and plasticizers to satisfy eighteen-to-twenty-four month motor qualification delays.
Poland
Multiyear framework agreements for long-range fires accelerate under NATO collective defense commitments and regional deterrence posture enhancement. The country's national defense procurement office consolidates vendor pools through multi-year contracts displacing transactional spot-buying. Warsaw and Pomeranian Voivodeship clusters concentrate emerging precision-strike integration facilities where Polish defense modernization absorbs excess European solid-motor production capacity.
Global Rockets and Missiles Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with defense primes commanding integrated system delivery while subsystem suppliers compete on digital engineering maturity. The vendor base concentrates around vertically integrated propulsion houses and satellite bus integrators rather than fragmented component specialists. Three archetypes dominate: captive solid-motor manufacturers, hypersonic glide body integrators, and space launch platform specialists. M&A activity targets guidance-navigation-control talent pools, while strategic partnerships secure ammonium perchlorate supply commitments against single-source pricing volatility.
Within the integrated defense prime tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify vertically structured competitors with in-house production of strategic subsystems. RTX Corporation occupies a position among captive propulsion manufacturers that control critical supply chain nodes. These three entities represent the dominant competitive archetypes: system integrators with backward integration into hypersonic bodies, satellite bus assembly, and solid-rocket motor manufacturing respectively.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| Northrop Grumman Corporation |
| Boeing |
| MBDA |
| BAE Systems |
| General Dynamics Corporation |
| Raytheon Technologies Corporation |
| KONGSBERG |
| Others |
Value Chain & Pricing Dynamics
Kalman filtering specialists concentrated in Huntsville, Alabama and Hyderabad, India drive labor-cost spreads that separate premium guidance-system integrators from economy-tier subsystem vendors. Systems engineering talent scarcity across these clusters compresses pricing flexibility for defense contractors competing against commercial autonomy programs.
Pricing Analysis
Capacity additions in Poland and Germany are reshaping price floors for NATO-compliant precision fires as multiyear framework agreements consolidate vendor pools. Three-tier pricing structure across ITAR-restricted, NATO STANAG-certified, and domestic-content tiers differentiates by regulatory compliance burden rather than unit performance. Cost compression in European REACH-compliant propellant formulations is intensifying because eighteen-to-twenty-four month qualification delays extend supplier switching costs. Military procurement offices show lowest price sensitivity due to mission-critical reliability mandates, while research institutions face tightest budget constraints.
Supply Chain Analysis
Freight costs for ammonium perchlorate solid oxidizer shipments from North American suppliers to European and Asian manufacturing clusters have become a material cost driver under single-source concentration. Production gravity centers on the United States, China, and India for solid propellant architectures, with Germany and Poland emerging for NATO-compliant reformulation. Supply chains draw from aluminum fuel suppliers, hydroxyl-terminated polybutadiene binder manufacturers, and ceramic matrix composite fabricators for thermal protection. Single-source vulnerability in North American solid-oxidizer production exposes missile manufacturers to force majeure risk. Distribution runs through defense prime integrators with captive propulsion divisions rather than independent component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's Defence Acquisition Procedure 2020 domestic content thresholds offer cost advantages against United States ITAR licensing timelines that exceed eighteen months for equivalent subsystem transfers.
For Market Incumbents: To counter emerging solid-motor capacity in India and Poland, Lockheed Martin Corporation and RTX Corporation should deepen backward integration into ammonium perchlorate synthesis and accelerate digital engineering maturity certifications for United States Army Futures Command multi-year indefinite-delivery contracts. Captive propellant production insulates margins from supply volatility. For New Entrants and Emerging Players: Launch via third-party propulsion maintenance services for reusable booster recovery protocols that SpaceX and Blue Origin are establishing, targeting the commercial launch segment where satellite constellation operators absorb excess solid-motor capacity. White-space concentration sits with green propellant transition programs under European Space Agency Clean Space initiative funding. For Investors and Strategic Acquirers: Defense prime integrators with hypersonic glide body capabilities are the most active acquirer in this space, seeking guidance-navigation-control talent pools that defense contractors and commercial autonomy programs compete to secure. Long-term viability hinges on positioning against layered Missile Defense Agency interceptor mandates. Watch for yield-rate breakthroughs in ceramic matrix composite nosecone production as inflection signal for hypersonic program scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Solid-Motor Manufacturing | RTX Corporation insulates supply from ammonium perchlorate shortages through vertical production control. |
| Hypersonic Glide Body Integration | Lockheed Martin sustains program margins across multiple Pentagon contracts via in-house production. |
| Green Propellant Reformulation | German KBA and French ANSM coordination creates first-mover advantage for REACH-compliant chemistry suppliers. |
| Multi-Year Indefinite-Delivery Contracts | United Kingdom Defence Equipment and Support consolidates vendor pools through digital engineering maturity selection. |
| Reusable Booster Refurbishment Services | SpaceX qualification protocols open aftermarket demand for third-party solid-rocket motor maintenance. |
Study Parameters
Bottom-up defense procurement modeling reconciled against top-down solid-motor production capacity tracking forms the analytical core of this study. Primary interviews with Pentagon program officers, Missile Defense Agency technical directors, European defense procurement officials at NATO member ministries, and commercial launch operators at satellite constellation companies combined with secondary validation from Federal Acquisition Regulation filings, NATO STANAG documentation, SAMR technical standards, and Defence Acquisition Procedure 2020 policy texts. Triangulation across these sources ensures segmentation integrity for ballistic, cruise, tactical, and space launch vehicle categories.
Historical trendline analysis of precision-strike procurement cycles and dual-use launch infrastructure utilization rates informed the projection framework. Segmentation dimensions modeled include propulsion technology architecture, application category across defense and commercial launch, and end-user procurement authority concentration. CAGRs derived from fitted growth curves reflect underlying drivers of NATO collective defense modernization, military-civil fusion policy integration, and indigenization mandate enforcement. Industry-specific forecast inputs incorporate range certification backlog constraints and ITAR licensing timeline friction.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ammonium perchlorate supply disruption or hypersonic thermal protection yield-rate stagnation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Missile Launching Systems Market
Weapons and Ammunition
Electromagnetic Weapons Market
Weapons and Ammunition
Electrical Weapon Market
Weapons and Ammunition
Military Fuze Market
Weapons and Ammunition
Smart Weapons Market
Weapons and Ammunition
Global Submarine Launched Missile Market
Weapons and Ammunition
Cruise Missile Market
Weapons and Ammunition
Close-In Weapon Systems Market
Weapons and Ammunition
North America Ammunition Market
Weapons and Ammunition
Global Multiple Launch Rocket Systems Market
Weapons and Ammunition
Recoilless Rifle Market
Weapons and Ammunition
Decoy Flares Market
Weapons and Ammunition
Asia-Pacific Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Southeast Asia, Middle-East and Africa Small Arms and Ammunition Market
Weapons and Ammunition
Large Caliber Ammunition Market
Weapons and Ammunition
Explosives for Civil Uses Market