
 North America Nuclear Bombs and Missiles Market | 2026-2036
North America Nuclear Bombs and Missiles Market Size, Share, and Industry Trends Forecast 2026-2036
North America Nuclear Bombs and Missiles Market Analytics
A shift from sole-source to multi-source contracting for propulsion subsystems is restructuring supplier relationships across the North American nuclear weapons industrial base. Lockheed Martin Corporation dominates strategic missile integration through its dominance of the Navy's Trident program. RTX Corporation sustains long-range precision guidance capabilities across multiple delivery platforms. Northrop Grumman Corporation anchors the airborne leg through its specialization in cruise missile systems and next-generation bomber payloads.
Nuclear bombs and missiles encompass thermonuclear warheads and precision-guided delivery vehicles engineered to specific yield-to-weight ratios, with plutonium pits and boosted primaries requiring exacting metallurgical control. These systems serve deterrence posture maintenance and strategic force projection for national security architectures. Intercontinental ballistic missiles command the largest capital allocation within the product type dimension due to silo infrastructure and ground-based strategic deterrent replacement cycles. Submarine-launched ballistic missiles represent the fastest-growing deployment category as the Columbia-class program accelerates. Advanced targeting systems within the technology dimension concentrate margin pools through software-defined seeker architectures and hardened electronics.
The U.S. Department of Energy's National Nuclear Security Administration governs warhead life extension programs, while the Department of Defense's Missile Defense Agency shapes interceptor and countermeasures development priorities. Canadian participation through NORAD modernization commitments introduces bilateral coordination requirements for continental defense architectures. Stakeholders must track how the U.S. Nuclear Regulatory Commission's evolving materials security protocols and the Pentagon's software supply chain mandates reshape component sourcing eligibility and facility certification timelines.
Market Dynamics
The Columbia-class submarine program is concentrating capital allocation toward next-generation ballistic missile delivery platforms, restructuring supplier relationships across the North American nuclear weapons industrial base.
Growth Catalysts
- National Defense Authorization Act modernization mandates:Congressional appropriations for the nuclear triad refresh are sustaining multi-year procurement cycles for intercontinental ballistic missiles and submarine-launched systems.
- Plutonium pit production expansion:The Department of Energy's Savannah River Site and Los Alamos National Laboratory are scaling metallurgical capacity to meet warhead life extension program requirements.
- NORAD continental defense coordination:Canadian commitments to aerospace warning and control modernization are creating bilateral demand for integrated command-and-control architectures.
Market Restraints
- Plutonium-239 supply concentration:Weapons-grade fissile material stockpiles remain concentrated at limited Department of Energy sites, creating single-point vulnerability in the pit production pipeline.
- Specialized workforce scarcity:The American nuclear weapons complex faces critical shortages of certified metallurgists, nuclear engineers, and security-cleared technicians with Q-level clearances.
- Environmental compliance friction:The Environmental Protection Agency's hazardous waste remediation requirements at legacy production facilities are extending site certification timelines and constraining expansion options.
Strategic Opportunities
- Canadian Arctic defense infrastructure:NORAD modernization commitments are opening procurement channels for hardened communication systems and northern warning radar upgrades.
- Software-defined seeker architectures:Convergence of machine learning algorithms with radiation-hardened electronics is enabling precision guidance improvements without hardware redesign cycles.
- Multi-source propulsion contracting:The shift away from sole-source supplier relationships for missile motor segments is creating entry points for qualified aerospace subcontractors.
Industry Challenges
- Security clearance pipeline constraints:The Department of Defense's personnel vetting backlog is delaying workforce onboarding and compressing program schedules across the industrial base.
- Legacy system integration complexity:Minuteman III replacement programs must maintain interoperability with existing silo infrastructure and command networks during phased transitions.
- Software supply chain attestation:Pentagon mandates for software bill of materials compliance are forcing subsystem vendors to requalify existing codebases and documentation practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Nuclear Bombs and Missiles Market |
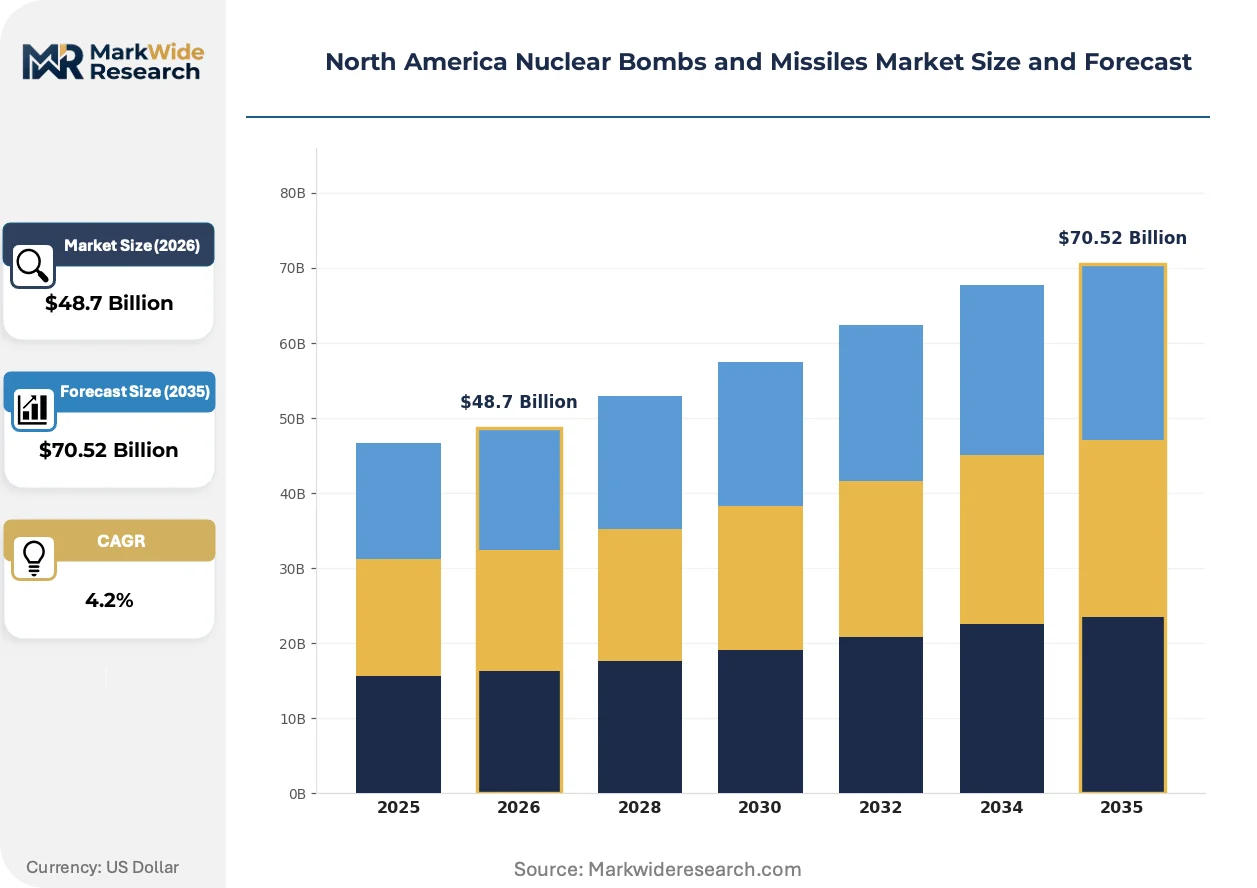
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $70.52 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intercontinental Ballistic Missiles, Submarine-Launched Ballistic Missiles, Tactical Nuclear Weapons, Air-Launched Cruise Missiles End User: Military, Defense Contractors, Government Agencies, Research Institutions Technology: Guided Weapons, Unmanned Systems, Nuclear Propulsion, Advanced Targeting Systems Deployment: Land-Based, Sea-Based, Air-Based, Underground Silos |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, Northrop Grumman Corporation, Boeing, BAE Systems, General Dynamics, Aerojet Rocketdyne, L3Harris Technologies, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Nuclear Bombs and Missiles Market Evolving Landscape
Digital engineering practices are compressing development cycles for nuclear delivery systems while hardened electronics architectures are extending operational lifespans in radiation environments.
Modular warhead designs are overtaking fixed-yield configurations across Navy strategic programs. The National Nuclear Security Administration is prioritizing adaptable secondary architectures that permit yield modulation without full weapon redesign. This flexibility is compressing the number of distinct warhead types the complex must sustain while maintaining deterrent coverage.
The Department of Energy's 80-50 plutonium pit production directive is reshaping supplier qualification requirements. Industrial facilities must demonstrate surge capacity for 80 pits annually by 2030, with 50 pits as sustained steady-state output. Prime contractors are responding by qualifying secondary machining vendors and expanding hot cell automation investments.
Consolidated prime contracting is displacing fragmented subsystem procurement across Air Force strategic systems. The Ground-Based Strategic Deterrent program has concentrated integration responsibility with single prime contractors for missile, command-and-control, and launch control center segments. This concentration is visible most acutely in Wyoming, Montana, and North Dakota, where silo infrastructure replacement is synchronizing with new missile fielding schedules.
North America Nuclear Bombs and Missiles Market Segmentation
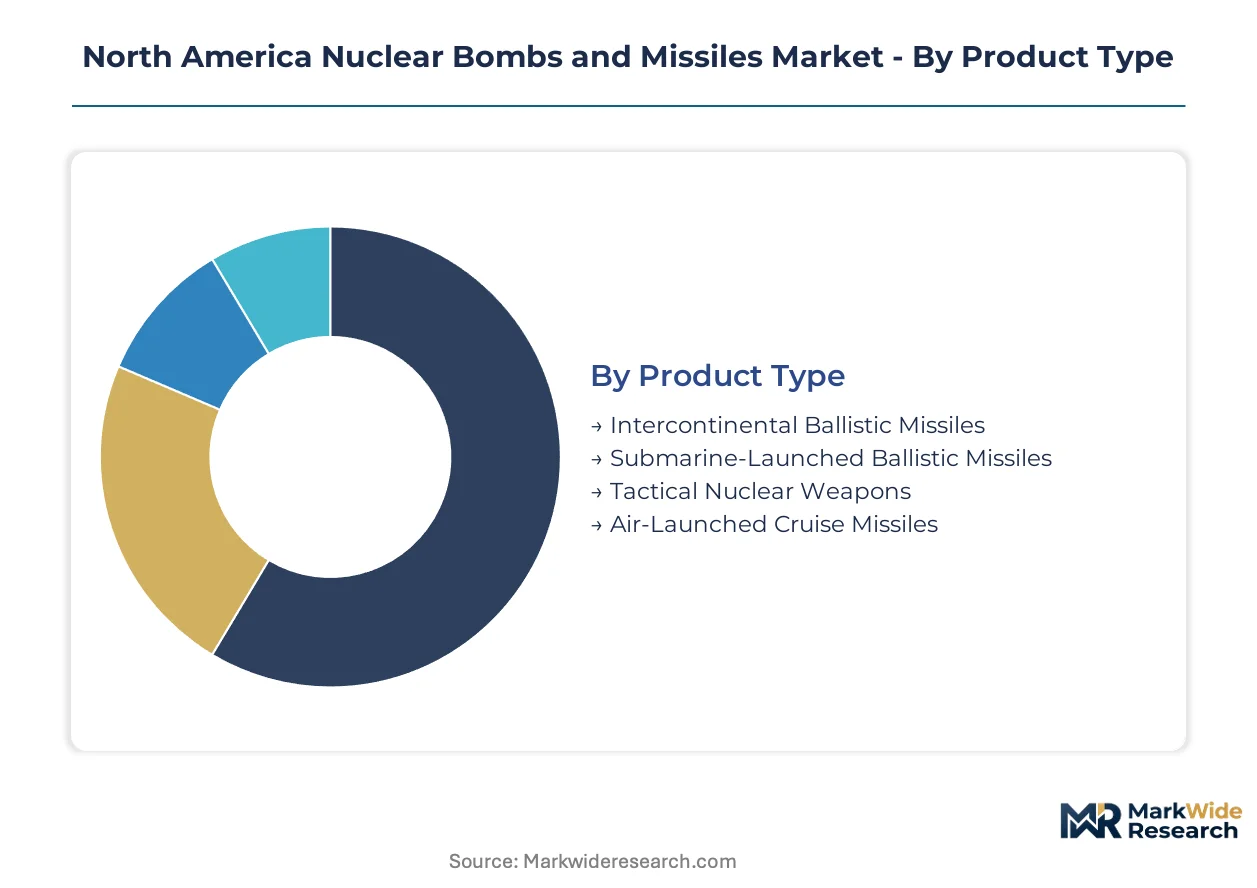
Segmentation in the North America nuclear weapons industrial base reveals how capital allocation patterns diverge across delivery platforms, institutional buyers, and operational environments. Procurement cycles, security clearance requirements, and infrastructure dependencies create distinct competitive dynamics within each category.
Product Type:
Defense planners differentiate procurement budgets by platform survivability, response time requirements, and basing mode vulnerability.
- Intercontinental Ballistic Missiles:Silo-based strategic systems with hardened command links and fixed-site infrastructure. The U.S. Air Force's Ground-Based Strategic Deterrent program is redirecting capital toward Wyoming, Montana, and North Dakota replacement cycles.
- Submarine-Launched Ballistic Missiles:Sea-based deterrent platforms engineered for continuous at-sea presence and second-strike assurance. The Navy's Columbia-class program is accelerating demand across the Atlantic and Pacific submarine construction yards.
- Tactical Nuclear Weapons:Theater-range systems with variable yield configurations for regional deterrence missions.
- Air-Launched Cruise Missiles:Standoff delivery vehicles integrated with bomber fleet modernization timelines.
Intercontinental ballistic missiles lead volumes today; submarine-launched ballistic missiles are gaining share fastest.
End User:
Institutional buyers vary in contracting authority, security classification levels, and technical specification authority.
- Military:Uniformed services with operational command requirements and field deployment responsibilities. The Department of Defense's Strategic Command concentrates demand for integrated deterrence architectures across U.S. Northern Command jurisdictions.
- Defense Contractors:Prime and subsystem vendors executing design-build contracts under National Nuclear Security Administration oversight.
- Government Agencies:Civilian departments with policy, regulatory, or intelligence functions.
- Research Institutions:National laboratories and university-affiliated centers with weapons physics and materials science mandates.
Military end users dominate current procurement; defense contractors are expanding their share through consolidated prime contracting models.
Technology:
Technology segments separate by hardware-software integration depth and radiation environment tolerance requirements.
- Guided Weapons:Precision navigation and terminal guidance subsystems with inertial measurement units and stellar reference packages. The Missile Defense Agency's interceptor programs are driving hardened electronics demand.
- Advanced Targeting Systems:Sensor fusion architectures combining multi-spectral seekers with machine-learning track algorithms. Software-defined seeker designs are compressing hardware refresh cycles across Air Force strategic programs.
- Unmanned Systems:Autonomous delivery platforms with reduced crew exposure profiles.
- Nuclear Propulsion:Reactor and thermal management systems for extended-range submarine operations.
Guided weapons anchor current technology spending; advanced targeting systems show the steepest expansion trajectory.
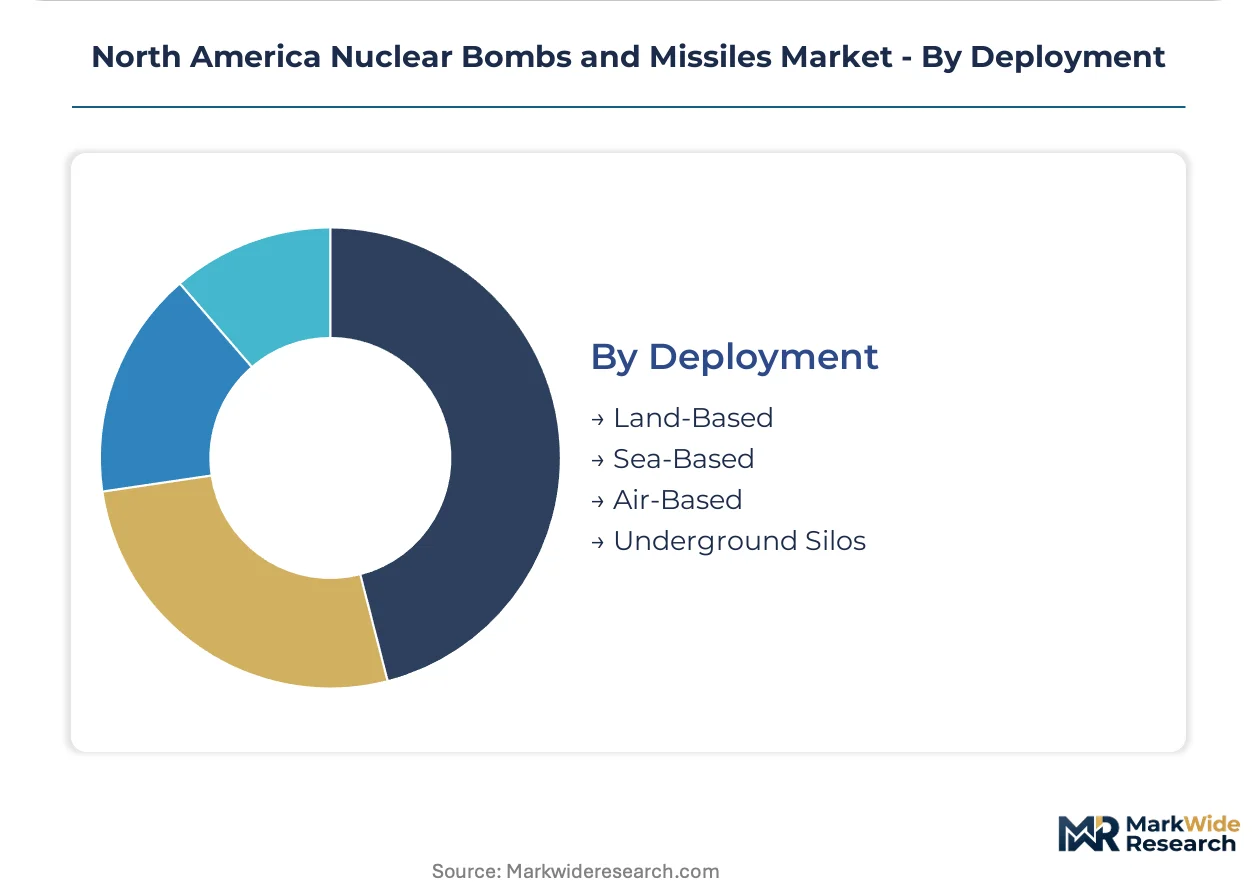
Deployment:
Deployment modes reflect geographic basing constraints, survivability trade-offs, and command-and-control architecture requirements.
- Sea-Based:Submarine platforms operating from Kitsap, Kings Bay, and future Atlantic homeports. The Columbia-class construction schedule is synchronizing with Ohio-class retirement timelines.
- Land-Based:Fixed-site missile fields and mobile launcher systems across the continental United States. Silo infrastructure replacement in the northern tier states is extending construction seasons.
- Air-Based:Bomber fleet integration with next-generation stealth platform deliveries.
- Underground Silos:Hardened vertical storage with blast-resistant command capsules.
Sea-based deployment commands the largest capital allocation; land-based systems are climbing fastest through modernization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pantex Plant-Amarillo complex anchors North American warhead assembly capacity. The nuclear weapons industrial base concentrates around Department of Energy sites and Navy submarine construction yards. Canadian NORAD commitments and U.S. triad modernization are reshaping bilateral procurement flows.
United States
Ground-Based Strategic Deterrent fielding in Wyoming, Montana, and North Dakota is driving silo infrastructure replacement cycles. The National Nuclear Security Administration's 80-50 pit production directive mandates surge capacity at Los Alamos National Laboratory and Savannah River Site. Seattle-Bremerton submarine construction clusters are synchronizing Columbia-class hull deliveries with Ohio-class retirement schedules.
Canada
NORAD modernization commitments are generating demand for northern warning radar upgrades and hardened Arctic communication systems. The Department of National Defence's continental defense policy framework aligns procurement with U.S. Strategic Command requirements. Ottawa-Gatineau defense corridors are coordinating aerospace warning integration with Cheyenne Mountain operations.
Mexico
Industrial security protocols under the Secretariat of National Defense govern dual-use component transit for U.S. aerospace supply chains. The Mexican Space Agency's satellite navigation partnerships create peripheral demand for precision guidance subsystem testing. Baja California manufacturing clusters support radiation-hardened electronics packaging for cross-border defense contractors.
North America Nuclear Bombs and Missiles Market Competitive Landscape
Global majors compete with regional champions across prime contracting tiers in the North America nuclear bombs and missiles market. The industrial base exhibits consolidated prime contracting with fragmented subsystem supply, where three to five integrators dominate strategic platform awards while specialized vendors populate propulsion and guidance tiers. Strategic archetypes include full-spectrum prime integrators, propulsion subsystem specialists, and radiation-hardened electronics suppliers. Competitive dynamics center on multi-source contracting transitions and digital engineering qualification races.
Within the prime integrator tier, Lockheed Martin Corporation and Northrop Grumman Corporation occupy positions as archetypal strategic systems architects, while RTX Corporation exemplifies the precision guidance specialist archetype. These entities anchor supplier relationship restructuring as the Department of Defense shifts from sole-source to competitive propulsion contracting. Their positioning reflects the market's concentration around Navy submarine programs and Air Force ground-based deterrent replacement cycles.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| Northrop Grumman Corporation |
| Boeing |
| BAE Systems |
| General Dynamics |
| Aerojet Rocketdyne |
| L3Harris Technologies |
| Honeywell International |
| Others |
Value Network & Pricing Analysis
The Department of Defense's shift from sole-source to multi-source contracting for propulsion subsystems is forcing subsystem vendors to absorb qualification costs upfront while compressing margins across the nuclear weapons industrial base. This procurement preference restructuring concentrates pricing power with prime integrators who can spread compliance investments across multi-year National Defense Authorization Act appropriations.
Pricing Analysis
Input-cost pass-through from weapons-grade plutonium-239 stockpile management and certified metallurgist labor scarcity shapes contract economics across the nuclear weapons complex. Three-tier pricing structure across life-extension programs, new production lots, and surge-capacity options differentiates bids based on security clearance infrastructure and hot cell automation levels. Pricing pressure stems from the Environmental Protection Agency's hazardous waste remediation requirements extending site certification timelines. Tier 2 subsystem vendors show highest price sensitivity due to concentrated buyer power at the prime integrator level.
Supply Chain Analysis
Dual-sourcing requirements for missile motor segments mandated by the Missile Defense Agency are fragmenting propulsion supplier relationships previously concentrated with single vendors. The supply chain draws from the United States, Canada, and Mexico for radiation-hardened electronics packaging and precision machining capacity. Critical inputs include plutonium pits, tritium reservoirs, and radiation-hardened semiconductors. Single-source vulnerability persists at the weapons-grade fissile material tier where Department of Energy site concentration creates chokepoints. Distribution runs through prime contractor integration facilities at Pantex, Los Alamos, and Savannah River with direct government offtake contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between U.S. Department of Energy site labor costs and Canadian NORAD infrastructure commitments offers procurement cost differentials for hardened communication systems and northern warning radar segments.
For Market Incumbents: Acquire Q-level cleared workforce pipelines and hot cell automation assets to offset certified technician scarcity compressing program schedules. Consolidate propulsion subsystem vendors under long-term qualification agreements to defend against multi-source contracting fragmentation. Prioritize backward integration into plutonium pit production capacity at Los Alamos and Savannah River to secure supply chain positioning ahead of the 80-50 directive surge requirements. For New Entrants and Emerging Players: Digital engineering qualification races for software-defined seeker architectures offer entry points without legacy hardware redesign cycles. Target Canadian Arctic defense infrastructure commitments for hardened communication systems where bilateral coordination requirements create procurement channels outside prime integrator concentration. Pursue aerospace subcontractor status through radiation-hardened electronics packaging specialization for cross-border defense contractors operating in Baja California clusters. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier subsystem vendors holding dual-use aerospace certifications and Q-level facility clearances. The five-to-ten-year viability window favors entities positioned for plutonium pit production expansion and Columbia-class submarine construction synchronization. Monitor Department of Energy site certification timeline deviations as the inflection indicator for capacity-constrained pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Propulsion Contracting | Fragments sole-source supplier relationships across Navy Trident and Air Force GBSD programs. |
| Plutonium Pit Production Expansion | Reshapes supplier qualification requirements at Los Alamos National Laboratory and Savannah River Site. |
| Digital Engineering Qualification | Compresses development cycles for software-defined seeker architectures in radiation-hardened electronics. |
| NORAD Arctic Infrastructure Commitment | Opens bilateral procurement channels for Canadian northern warning radar and hardened communications. |
| Security Clearance Pipeline Investment | Addresses Department of Defense personnel vetting backlog constraining workforce onboarding timelines. |
Research Methodology
Bottom-up defense contractor procurement tracking reconciled against top-down Department of Energy site capacity monitoring forms the analytical core of this study. Primary interviews with strategic systems program managers, National Nuclear Security Administration procurement officers, submarine construction yard planners, and radiation-hardened electronics vendors combined with secondary validation against SEC 10-K filings, Department of Defense budget justification documents, and Congressional Research Service triad modernization reports.
Historical trendline analysis across nuclear weapons complex capital allocation patterns established baseline growth trajectories. Segmentation modeling spanned delivery platform type, end-user contracting authority, technology integration depth, and deployment mode basing constraints across the analysis window. CAGRs derived from procurement cycle synchronization with Ohio-class retirement and Columbia-class fielding schedules, plutonium pit production ramp assumptions, and NORAD modernization commitment flows.
The model assumes a particular technology adoption path for modular warhead designs and software-defined guidance; alternative pathways for adaptable secondary architectures or machine-learning seeker integration would alter the outlook. Deviation in Department of Energy site certification timelines or Congressional appropriation continuity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Small Arms Market
Weapons and Ammunition
Command Fuzes Market
Weapons and Ammunition
North America Weapon Night Sight Market
Weapons and Ammunition
Manned Anti-Tank Guided Missile System Market
Weapons and Ammunition
Small Caliber Ammunition Market
Weapons and Ammunition
Military Airborne Laser Market
Weapons and Ammunition
Ballistic Protection Market
Weapons and Ammunition
Military Fuze Market
Weapons and Ammunition
Shotgun and Rifles Market
Weapons and Ammunition
Europe Cruise Missile Market
Weapons and Ammunition
Military Helmet Market
Weapons and Ammunition
Smoke Grenade Market
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Precision Guided Munition Market
Weapons and Ammunition
Supersonic and Hypersonic Weapons Market
Weapons and Ammunition
Intercontinental Ballistic Missile Market