
 Advanced Aerial Mobility Market | 2026-2036
Advanced Aerial Mobility Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Aerial Mobility Market Analysis
The capital-intensity divergence between well-funded incumbents and venture-stage entrants is redrawing competitive boundaries in advanced aerial mobility. Airbus S.A.S. leverages its aerospace manufacturing scale to sustain certification programs across multiple vehicle architectures. Joby Aviation anchors its position through extensive flight-test hours and FAA type-certification progress. Lilium GmbH differentiates via its proprietary ducted-electric-thrust approach for regional passenger routes.
Advanced aerial mobility encompasses crewed and uncrewed electric aircraft systems capable of vertical or short-field operations, typically featuring distributed electric propulsion with power densities exceeding 5 kW/kg and redundant flight-control architectures. These vehicles serve urban congestion relief, time-critical logistics, and emergency response missions where surface infrastructure proves limiting. Hybrid product configurations currently attract the deepest engineering investment, as they reconcile range anxiety with operational flexibility better than pure multirotor designs. Electric propulsion technology leads patent filings, yet autonomous navigation systems carry the highest margin potential once regulatory frameworks mature. Urban air mobility applications dominate public visibility, though cargo transport segments show faster near-term deployment timelines.
The FAA's powered-lift rulemaking and EASA's SC-VTOL certification framework jointly shape vehicle design standards and pilot-training requirements across the Atlantic. China's CAAC issues type certificates under GB standards that accelerate domestic eVTOL commercialization while limiting foreign market access. Stakeholders must monitor which regulator's certification precedent achieves bilateral recognition first, as this will determine manufacturing-location strategy and fleet-export potential.
Market Dynamics
The FAA's powered-lift rulemaking is compressing certification timelines and forcing vehicle architectures toward unified pilot-training standards that accommodate both helicopter and fixed-wing operational profiles.
Growth Catalysts
- Healthcare Logistics:Medical cargo drones are displacing ground-based emergency transport for time-critical pharmaceuticals and organ delivery across congested urban corridors.
- EASA SC-VTOL Framework:The European certification pathway is accelerating type-approval reciprocity discussions with the FAA, reducing dual-certification burdens for manufacturers targeting transatlantic operations.
- Battery Energy Density:Solid-state lithium-metal cells exceeding 400 Wh/kg are extending electric aircraft range envelopes and enabling regional passenger routes previously reserved for combustion-powered alternatives.
Market Restraints
- Critical Mineral Concentration:Cobalt and lithium processing capacity concentrates in China, exposing non-Chinese OEMs to supply disruption and geopolitical pricing volatility.
- Airspace Integration Friction:ATM system modernization lags behind vehicle certification, creating operational bottlenecks in high-density corridors where UTM infrastructure remains fragmented.
- Pilot Pipeline Constraints:The powered-lift rating requires dual helicopter and airplane certification foundations, extending training duration and limiting qualified instructor availability.
Strategic Opportunities
- German Urban Clusters:Munich and Stuttgart anchor Europe's densest eVTOL manufacturing ecosystem, offering established aerospace supply chains and EASA proximity for accelerated validation.
- Autonomous Navigation Convergence:Sensor fusion combining lidar, radar, and computer vision is enabling reduced-crew operations that compress operating costs below piloted-service thresholds.
- US IRA Clean Aviation Credits:Federal tax incentives for zero-emission aircraft production are offsetting certification program capital intensity for domestic final-assembly facilities.
Industry Challenges
- Systems Engineering Talent Scarcity:Distributed electric propulsion requires rare cross-disciplinary expertise spanning aerospace structures, high-voltage power electronics, and flight-control software.
- Type-Certification Capital Burden:Full FAA Part 25 or Part 135 validation demands sustained flight-test programs consuming engineering resources across multi-year timelines.
- Vertiport Infrastructure Coordination:Real estate acquisition, electrical grid upgrades, and municipal zoning approvals create site-specific deployment friction unrelated to vehicle readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Aerial Mobility Market |
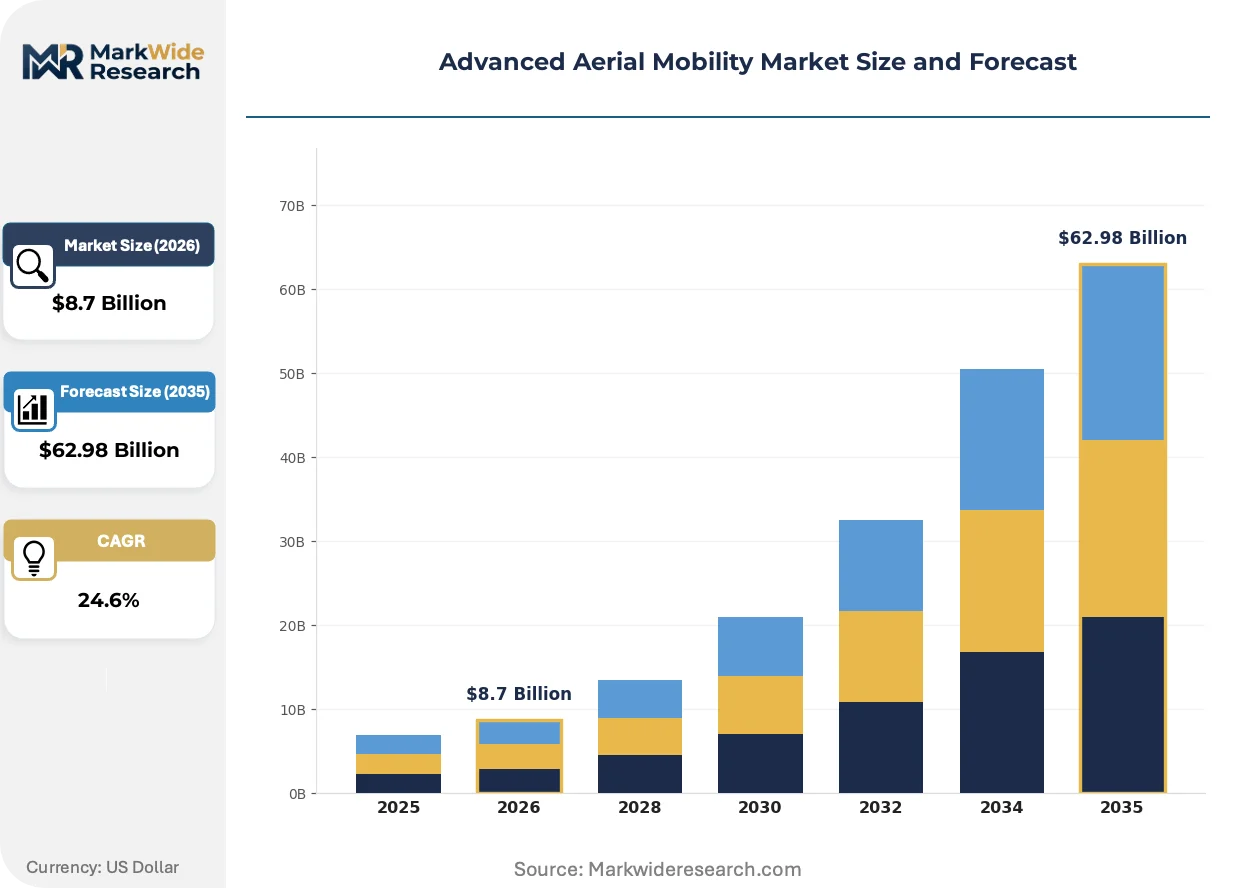
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Takeoff, Multirotor, Fixed Wing, Hybrid Technology: Electric Propulsion, Autonomous Navigation, Communication Systems, UAV Software Application: Urban Air Mobility, Cargo Transport, Surveillance, Emergency Services End User: Logistics Providers, Government Agencies, Private Corporations, Healthcare Services |
| Companies Covered | Airbus S.A.S., The Boeing Company, Lilium GmbH, Joby Aviation, Archer Aviation, Volocopter GmbH, Bell Textron Inc., Guangzhou EHang Intelligent Technology Co., Ltd., Hyundai Motor Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Aerial Mobility Market Emerging Trajectories
Hybrid-electric propulsion architectures are redrawing performance trade-offs between range and operational flexibility. Regulatory frameworks on both sides of the Atlantic are converging toward unified powered-lift standards. End-users are redefining service models around time-certain delivery rather than asset ownership.
Distributed electric propulsion with tilting ducted fans is displacing conventional helicopter rotor systems in regional passenger applications. Air ambulance operators in Germany and the United Arab Emirates are evaluating these configurations for inter-city medical transport. The shift is compressing direct operating costs and expanding route viability to airports lacking heliport infrastructure.
The FAA's Special Federal Aviation Regulation for powered-lift operations is mandating unified pilot type ratings that bridge helicopter and airplane privileges. This regulatory architecture is forcing training device manufacturers to develop novel simulation platforms capable of replicating thrust-vectoring transitions. OEMs targeting US commercial entry are restructuring flight-test programs to generate dual-purpose data supporting both type certification and training curriculum validation.
Hospital networks and logistics integrators are consolidating procurement authority under centralized fleet-management contracts rather than point-to-point charter arrangements. The shift is displacing traditional air-taxi brokers with vertically integrated operators offering guaranteed availability and predictable unit economics. This pattern is most visible in the United States, where healthcare systems in Texas and Florida are piloting multi-year service agreements with emerging advanced aerial mobility providers.
Advanced Aerial Mobility Market Segmentation
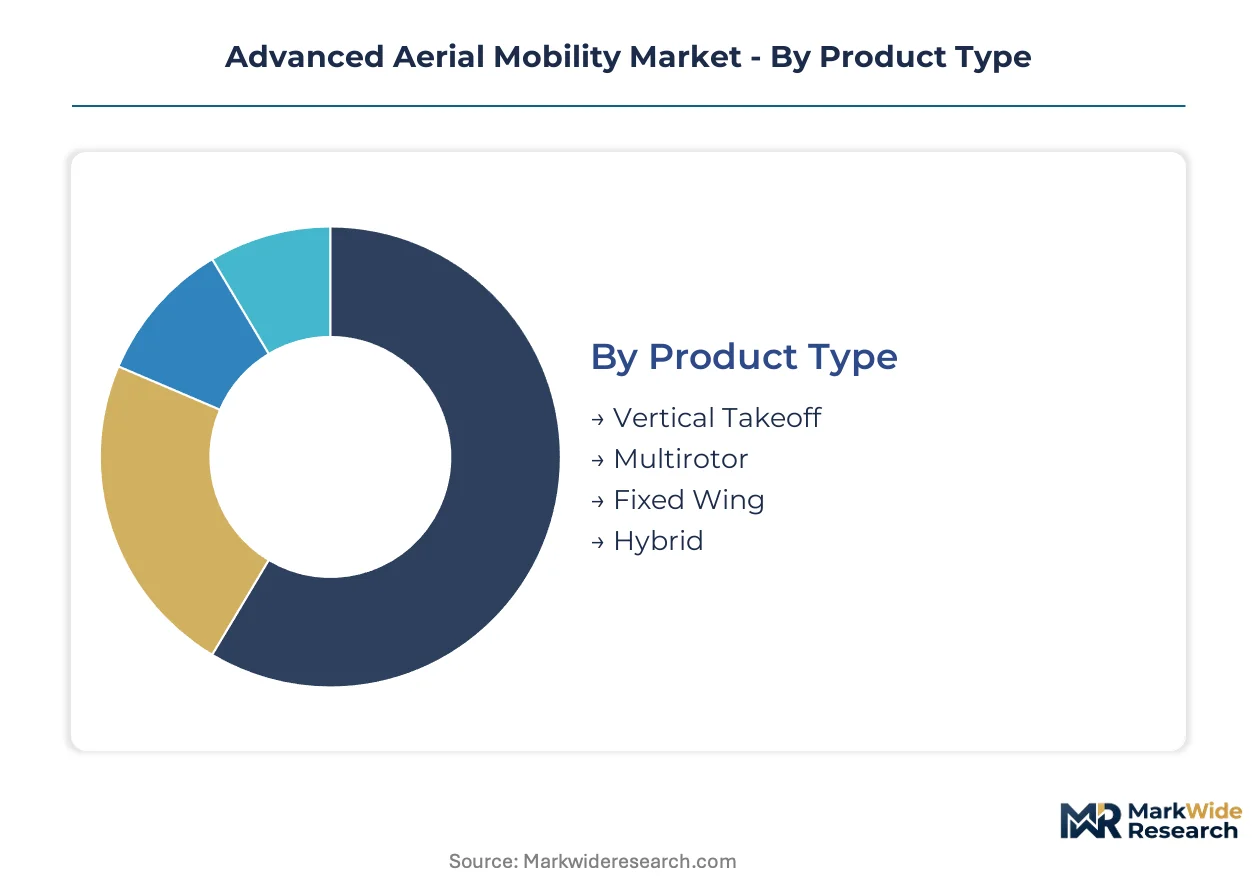
Vehicle architecture and propulsion technology determine certification pathways and operational economics in advanced aerial mobility. Channel strategy diverges sharply between passenger services requiring vertiport infrastructure and cargo applications leveraging existing logistics networks.
Product Type:
Channel mix splits between direct OEM sales to fleet operators and lease-to-service arrangements for passenger-carrying configurations. Cargo-focused architectures flow through logistics integrators with established ground-handling relationships.
- Vertical Takeoff:Tilt-rotor and vectored-thrust designs transition between hover and wing-borne flight. Demand concentrates in Germany and the United Arab Emirates for inter-city medical transport where heliport infrastructure is sparse.
- Multirotor:Distributed electric propulsion with fixed rotors dominates last-mile cargo and surveillance applications. Logistics providers in Texas and Florida are consolidating procurement under multi-year fleet-management contracts for pharmaceutical delivery.
- Fixed Wing:Conventional runway-dependent designs serve regional routes with superior aerodynamic efficiency. These configurations attract limited engineering investment as hybrid alternatives capture development budgets.
- Hybrid:Combines vertical lift capability with cruise-efficient fixed-wing flight. The architecture reconciles range limitations of pure-electric designs with operational flexibility demands from emergency services operators.
Multirotor systems dominate installed base. Hybrid configurations are where expansion concentrates.
Technology:
Cost tiering separates mature electric drivetrains from emerging autonomous systems carrying premium development overhead. Volume production concentrates in power electronics while software layers capture margin expansion.
- Electric Propulsion:Distributed motor architectures with power densities exceeding 5 kW/kg enable redundant flight control. Solid-state lithium-metal cells are extending range envelopes for regional passenger routes previously reserved for combustion alternatives.
- Autonomous Navigation:Sensor fusion combining lidar, radar, and computer vision enables reduced-crew operations. The technology carries the highest margin potential once FAA and EASA regulatory frameworks mature for beyond-visual-line-of-sight certification.
- Communication Systems:Command-and-control links with encrypted data transmission for air-ground coordination. These subsystems face integration friction where UTM infrastructure remains fragmented in high-density corridors.
- UAV Software:Flight-control algorithms and fleet-management platforms. Healthcare networks are piloting centralized procurement authority under vertically integrated operators offering guaranteed availability.
Electric propulsion dominates installed base. Autonomous navigation is climbing the fastest.
Application:
Customer type stratification separates time-critical emergency buyers from cost-optimizing cargo operators. Maturity curves diverge with surveillance deployments preceding passenger certification.
- Urban Air Mobility:Crewed passenger services connecting metropolitan centers and airports. Public visibility outpaces near-term deployment as vertiport infrastructure coordination creates site-specific friction unrelated to vehicle readiness.
- Cargo Transport:Uncrewed pharmaceutical and organ delivery displacing ground-based emergency transport. Medical cargo drones show faster deployment timelines than passenger applications across congested urban corridors.
- Surveillance:Persistent aerial monitoring for infrastructure and border security. Government agencies in Germany anchor procurement through established aerospace supply chains near EASA validation facilities.
- Emergency Services:Air ambulance and rapid-response medical evacuation. Operators in the United Arab Emirates are evaluating ducted-electric-thrust configurations for inter-city transport.
Cargo transport dominates installed base. Urban air mobility is gaining share fastest.
End User:
Margin structure varies by procurement sophistication, with healthcare systems consolidating authority versus fragmented government acquisition. Supply concentration in aerospace manufacturing clusters shapes vendor selection.
- Logistics Providers:Integrators seeking time-certain delivery guarantees rather than asset ownership. These buyers are displacing traditional air-taxi brokers with multi-year service agreements.
- Government Agencies:Defense and civilian authorities with mission-critical reliability requirements. Procurement flows through specialized channels with extended qualification timelines.
- Private Corporations:Energy and infrastructure operators deploying surveillance and executive transport. Demand concentrates where municipal zoning approvals align with electrical grid upgrade schedules.
- Healthcare Services:Hospital networks and emergency medical systems. This segment is expanding most quickly as air ambulances and medical cargo drones gain traction in the United States and Germany.
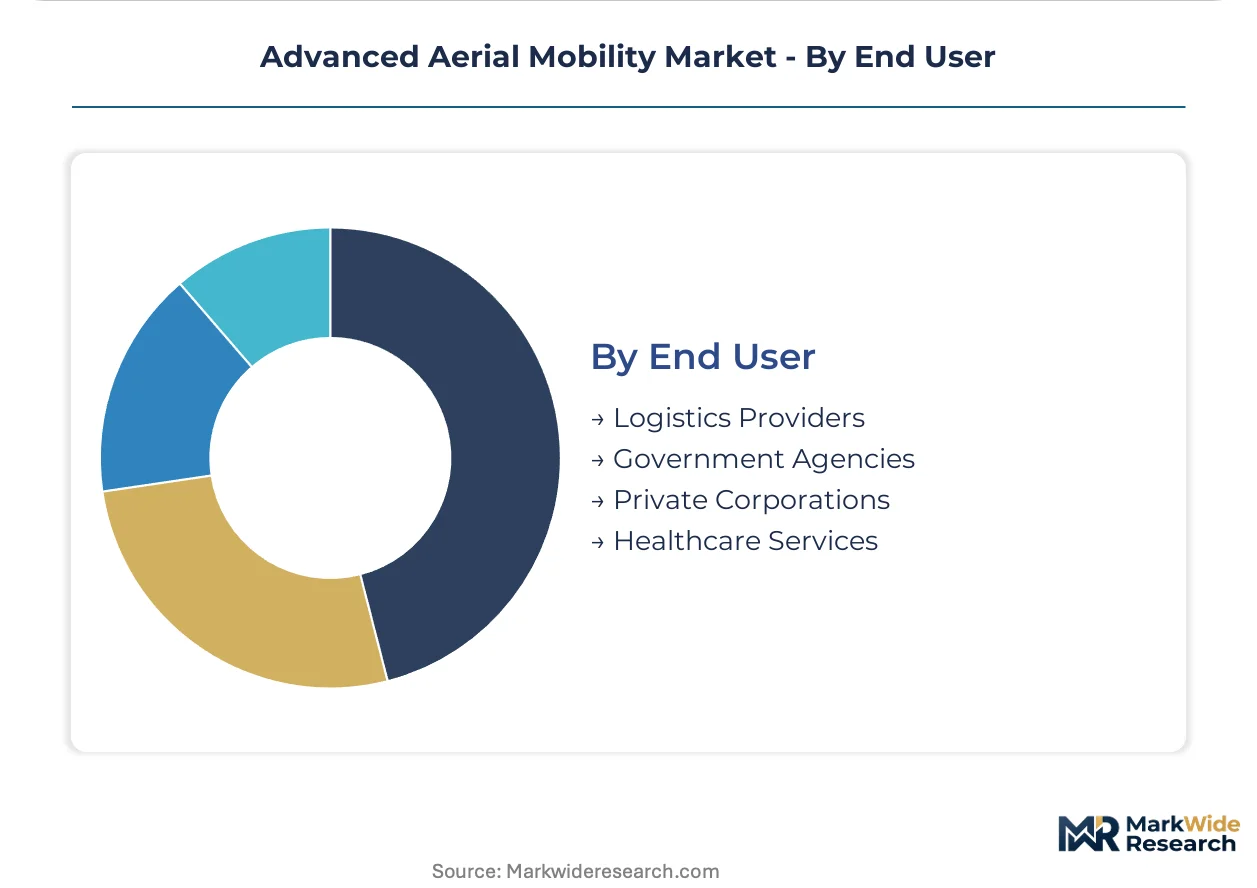
Logistics providers dominate installed base. Healthcare services represent where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's aerospace clusters while certification costs burden newer entrants in the United Arab Emirates. This asymmetry shapes manufacturing-location decisions and fleet-export strategies across the advanced aerial mobility sector.
United States
Healthcare networks in Texas and Florida are consolidating procurement under multi-year service agreements for air ambulance and medical cargo drone fleets. The FAA's Part 135 certification pathway for powered-lift aircraft compresses operational timelines while mandating unified pilot-training standards. Joby Aviation anchors flight-test activity in California, generating dual-purpose data for type certification and training curriculum validation.
Germany
Munich and Stuttgart host Europe's densest eVTOL manufacturing ecosystem, with Volocopter and Lilium anchoring regional passenger route development. EASA's SC-VTOL certification framework accelerates type-approval reciprocity discussions with transatlantic regulators. Air ambulance operators in Bavaria are evaluating ducted-electric-thrust configurations for inter-city medical transport where heliport infrastructure remains sparse.
China
Domestic eVTOL commercialization accelerates under CAAC type certificates issued via GB standards that limit foreign market access. Critical mineral processing capacity for cobalt and lithium concentrates supply chains, exposing non-Chinese OEMs to geopolitical pricing volatility. Guangzhou anchors intelligent technology development for uncrewed cargo applications in congested urban corridors.
United Arab Emirates
Emergency services operators are evaluating advanced aerial mobility configurations for rapid-response medical evacuation across emirate networks. The country's aviation regulator coordinates with EASA validation precedents to reduce dual-certification burdens for fleet entry. Dubai's logistics integrators are piloting centralized fleet-management contracts displacing traditional air-taxi brokerage models.
Japan
METI programs channel public-private investment toward urban air mobility infrastructure coordination in dense metropolitan corridors. The country's national aviation regulator monitors FAA powered-lift rulemaking for bilateral recognition opportunities. Osaka-based manufacturing clusters are developing simulation platforms for thrust-vectoring transition training mandated by emerging pilot-rating standards.
Advanced Aerial Mobility Market Vendor Landscape
Concentration sits with aerospace incumbents leveraging manufacturing scale against venture-stage entrants absorbing multi-year certification costs. The vendor base stratifies across three tiers: legacy airframe manufacturers with established regulatory relationships, pure-play eVTOL developers accumulating flight-test hours, and intelligent technology platforms specializing in autonomous navigation. Dominant competitive moves include strategic partnerships for vertiport infrastructure coordination and technology licensing agreements spanning propulsion architectures.
Within the pure-play developer tier, Joby Aviation and Archer Aviation exemplify the flight-test-hour accumulation strategy required for FAA type-certification progress. Lilium GmbH occupies a position among regional-route specialists pursuing proprietary ducted-electric-thrust approaches. Among aerospace incumbents, Airbus S.A.S. and The Boeing Company represent the manufacturing-scale archetype sustaining certification programs across multiple vehicle architectures simultaneously.
| Leading Market Players |
|---|
| Airbus S.A.S. |
| The Boeing Company |
| Lilium GmbH |
| Joby Aviation |
| Archer Aviation |
| Volocopter GmbH |
| Bell Textron Inc. |
| Guangzhou EHang Intelligent Technology Co., Ltd. |
| Hyundai Motor Company |
| Others |
Supply Flow & Price Mechanics
Solid-state lithium-metal cell adoption is displacing conventional lithium-ion pack architectures, simultaneously shifting procurement geography toward East Asian cathode refiners and compressing unit cost curves for electric propulsion systems. This substitution dynamic redistributes pricing power from vehicle integrators toward cell chemistry specialists while exposing non-Chinese OEMs to geopolitical input volatility.
Pricing Analysis
The customization-premium spread separates configured-to-order aircraft from standard fleet configurations, with EASA SC-VTOL certification tier and power density grade serving as primary price differentiation drivers. Subscription-based service contracts dominate passenger applications while per-unit transactional pricing prevails in cargo drone procurement. Cost compression in multirotor segments is intensifying due to power electronics commoditization, with logistics providers exhibiting highest price sensitivity and emergency services operators showing lowest.
Supply Chain Analysis
Cobalt hydroxide transit through the Strait of Malacca underwrites cathode precursor availability for non-Chinese cell manufacturers, creating a logistics chokepoint that concentrates supply risk. Critical mineral processing draws from China, Australia, and the Democratic Republic of Congo, with lithium carbonate and cobalt sulfate serving as anchor inputs. Single-source vulnerability in rare-earth magnet supply threatens motor manufacturing scale. Distribution runs through tier-one aerospace integrators and specialized logistics providers with vertiport ground-handling capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced aerial mobility represents a fragmentation opportunity as healthcare procurement consolidation creates tiered service niches spanning emergency response, scheduled inter-city transport, and pharmaceutical logistics.
For Market Incumbents: Secure EASA-FAA certification reciprocity pathways to reduce dual-validation burdens for transatlantic fleet deployment. Anchor manufacturing scale in established aerospace clusters near regulatory validation facilities, using backward integration into power electronics to defend margins against emerging pure-play developers accumulating flight-test hours. For New Entrants and Emerging Players: Lead with medical cargo drone applications in Texas and Florida healthcare networks, where multi-year fleet-management contracts displace traditional air-taxi brokerage. Target surveillance deployments for government agencies in Germany as the most penetrable near-term segment, using lease-to-service arrangements rather than asset-sale models to compress customer acquisition friction. For Investors and Strategic Acquirers: The market sits at a certification-ramp phase that favors vertically integrated developers with sustained flight-test programs and regulatory relationship depth. Long-term viability hinges on autonomous navigation technology maturation for beyond-visual-line-of-sight operations. Watch FAA powered-lift rulemaking bilateral recognition progress as the inflection signal determining manufacturing-location strategy and fleet-export potential.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | FAA Part 135 validation compresses operational entry timelines for powered-lift configurations. |
| Vertiport Infrastructure Partnership | Municipal zoning coordination with electrical grid upgrades reduces site-specific deployment friction. |
| Autonomous Navigation Development | Sensor fusion capabilities enable reduced-crew operations that compress operating cost thresholds. |
| Healthcare System Integration | Hospital network procurement consolidation creates multi-year service agreement opportunities. |
| Supply Chain Localization | Domestic cell manufacturing mitigates cobalt and lithium processing concentration risk. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with eVTOL program directors, FAA certification leads, hospital procurement managers, and vertiport infrastructure developers. Secondary validation drew from FAA docket filings, EASA SC-VTOL consultation papers, SEC S-1 disclosures from publicly traded developers, and customs data on lithium-ion cell imports. Bottom-up fleet deployment projections were triangulated against top-down addressable market sizing across passenger and cargo applications.
Across the analysis window, the forecasting framework modeled vehicle architecture, propulsion technology, application segment, and end-user procurement sophistication as core segmentation dimensions. CAGRs were derived from deployment trajectory analysis weighted by certification milestone achievement and infrastructure readiness indicators. Forecast inputs incorporated battery energy density improvement curves and regulatory framework maturation timelines without specifying year-bound milestones.
Underlying assumptions cover certification timeline adherence and critical mineral supply continuity, with deviation risk concentrated in airspace integration delays and pilot pipeline constraints. Practitioners should keep alternative scenarios live as FAA-EASA reciprocity negotiations and solid-state cell manufacturing scale-up evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
Flying Taxi Market
Air Mobility
Advanced Air Mobility Market
Air Mobility
Asia-Pacific Military Aviation Market
Air Mobility
Urban Air Mobility (UAM) Market
Air Mobility
Hang Glider Market
Air Mobility
Offshore Helicopter Services Market
Air Mobility
Air Transport USM Market
Air Mobility
Global Aerodynamics Market
Air Mobility
Parabolic Flight Tourism Market
Air Mobility
Helicopter-Based Transportation Market
Air Mobility
Global Aerial Firefighting Market
Air Mobility
Middle East and Africa General Aviation Market
Air Mobility
Airborne Pods Market
Air Mobility
China Chartered Air Transport Market
Air Mobility
Flying Motorbikes Market
Air Mobility
Global Flying Cars Market