
 Customized Avionic Systems Market | 2026-2036
Customized Avionic Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Customized Avionic Systems Market Outlook
Silicon carbide power modules are shifting thermal management economics in customized avionic systems, replacing legacy silicon-based architectures in high-density flight control computers. Honeywell International Inc. leverages its proprietary integrated modular avionics architecture to sustain long-term military contracts. BAE Systems PLC anchors European defense programs with sovereign-certified mission systems. Thales Group competes through differentiated fly-by-wire platforms for rotary-wing applications.
Customized avionic systems comprise purpose-built electronic hardware and software subsystems engineered to aircraft-specific mission profiles, typically operating across temperature extremes from -55°C to +125°C per DO-160G environmental categories, with primary purpose being safe command, navigation, communication, and surveillance under autonomous or piloted flight regimes. Flight control systems occupy the largest value pool given fly-by-wire retrofit cycles and new platform development, while avionics as a service represents the fastest-expanding technology segment as operators seek to convert capital expenditure to operational expenditure models. Communication systems retain mature, stable margins in the business aviation retrofit channel.
The FAA enforces DO-178C and DO-254 standards that dictate software and hardware assurance levels for civil certified systems, while the EASA CS-25 certification framework governs European large-aircraft installations, and the U.S. Department of Defense imposes MIL-STD-1553 and MIL-STD-1760 interface requirements that shape military product roadmaps. These overlapping compliance regimes force suppliers to maintain parallel certification competencies, raising barriers for non-specialized entrants. Stakeholders must evaluate whether to absorb certification costs in-house or partner with established qualification holders as platform-specific contracts fragment across OEM and aftermarket channels.
Market Dynamics
Silicon carbide power modules are compressing thermal budgets in flight control computers, forcing legacy silicon suppliers to recertify architectures or cede high-density slots to compound-semiconductor specialists.
Growth Catalysts
- FAA NextGen mandate:Air navigation modernization compresses retrofit timelines for communication and surveillance suites across US commercial fleets.
- Military mission-tailoring:Defense primes demand platform-specific avionics configurations for next-generation fighter and rotary-wing programs.
- Texas-Arizona-California corridor concentration:Tier-one integrators cluster around these aerospace hubs, accelerating supplier qualification cycles.
Market Restraints
- DO-178C certification cost structure:Software assurance documentation consumes 40-60% of development budgets for civil-certified systems.
- Silicon carbide substrate supply concentration:Wafer fabrication capacity concentrates among three global suppliers, creating input bottleneck risk.
- MIL-STD-1553 legacy interface persistence:Military platforms extend obsolete bus architectures, fragmenting R&D across parallel product lines.
Strategic Opportunities
- Avionics-as-a-service conversion:Business aviation operators shift capital expenditure to operational expenditure models through subscription-based flight management.
- Rotary-wing fly-by-wire penetration:Helicopter platforms lag fixed-wing in flight control modernization, creating retrofit white space.
- DO-254 hardware acceleration:Complex electronic hardware certification tools automate verification workflows for custom FPGA-based mission computers.
Industry Challenges
- DO-178C/D-254 parallel competency maintenance:Suppliers must sustain dual software and hardware certification teams as civil-military contract mix fragments.
- Legacy MIL-STD-1760 weapon interface integration:New stores management computers must bridge obsolete 1553B backplanes while hosting modern Ethernet payloads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Customized Avionic Systems Market |
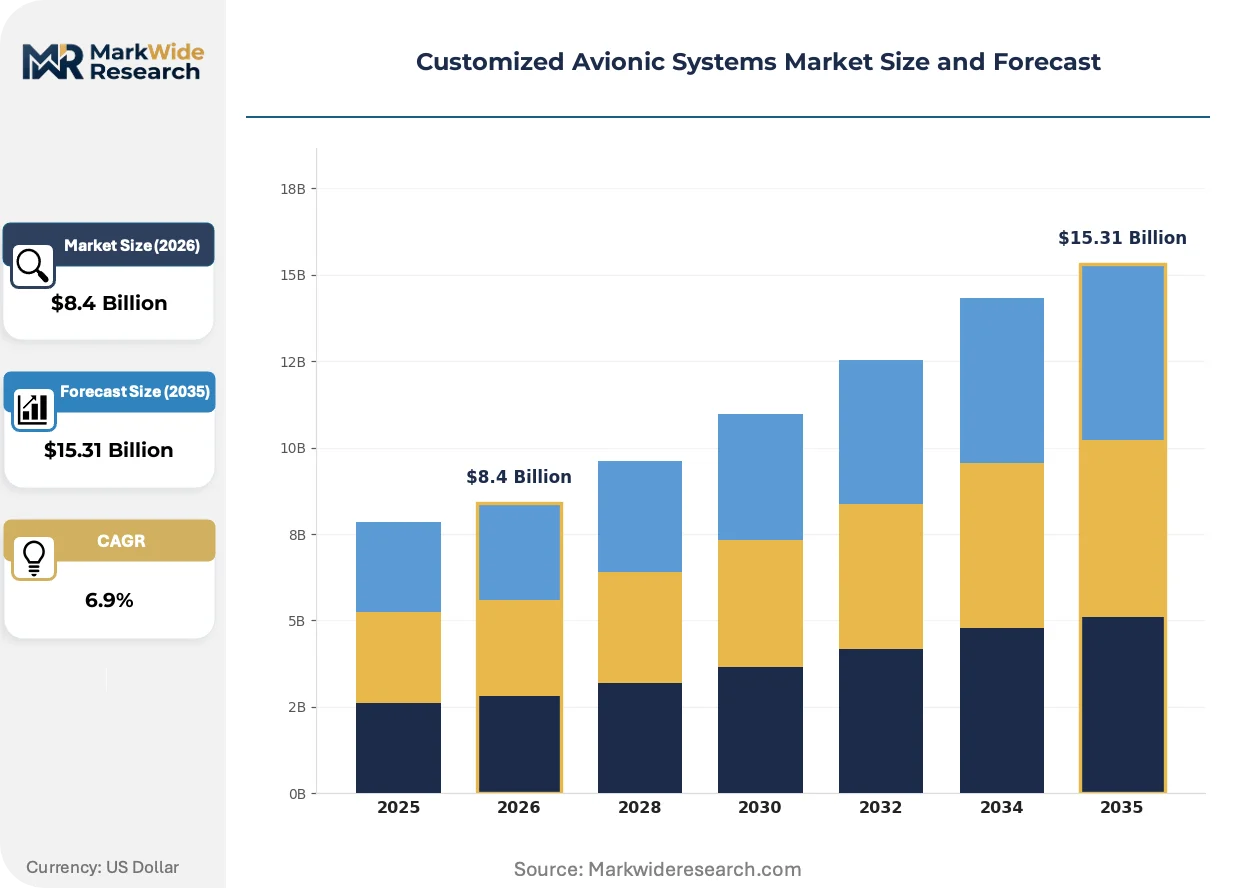
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.31 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Control Systems, Navigation Systems, Communication Systems, Surveillance Systems End User: Commercial Aviation, Military Aviation, UAVs, Business Aviation Technology: Digital Systems, Analog Systems, Hybrid Systems, Avionics as a Service Application: In-Flight Operations, Ground Operations, Maintenance, Training |
| Companies Covered | L3Harris Technologies Inc., BAE Systems PLC, Honeywell International Inc., Elbit Systems Ltd., Safran, RTX Corporation, General Electric Company, Meggitt PLC, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Customized Avionic Systems Market Strategic Shifts
Compound-semiconductor power electronics and modular open systems architectures are converging to redefine thermal and software integration boundaries in defense and commercial aviation.
Gallium nitride and silicon carbide wide-bandgap semiconductors is rewriting thermal management economics in high-density flight control computers. Military primes are accelerating adoption for next-generation fighter avionics bays. This transition compresses cooling system mass and enables previously impossible processing density in confined airframe volumes.
EASA CS-25 certification harmonization with FAA Part 25 is creating unified approval pathways for large-aircraft customized installations. European integrators now pursue simultaneous US-European certification to capture cross-Atlantic retrofit contracts. Business aviation operators in Switzerland and the United Kingdom are leveraging this convergence to accelerate fleet modernization timelines.
Platform-specific contracting is fragmenting supplier relationships across OEM and aftermarket channels. Tier-one integrators now bypass distribution partners for direct subsystem procurement from specialized avionics houses. This pattern concentrates most visibly in Arizona and California, where defense primes maintain captive engineering offices at key supplier facilities.
Customized Avionic Systems Market Segmentation
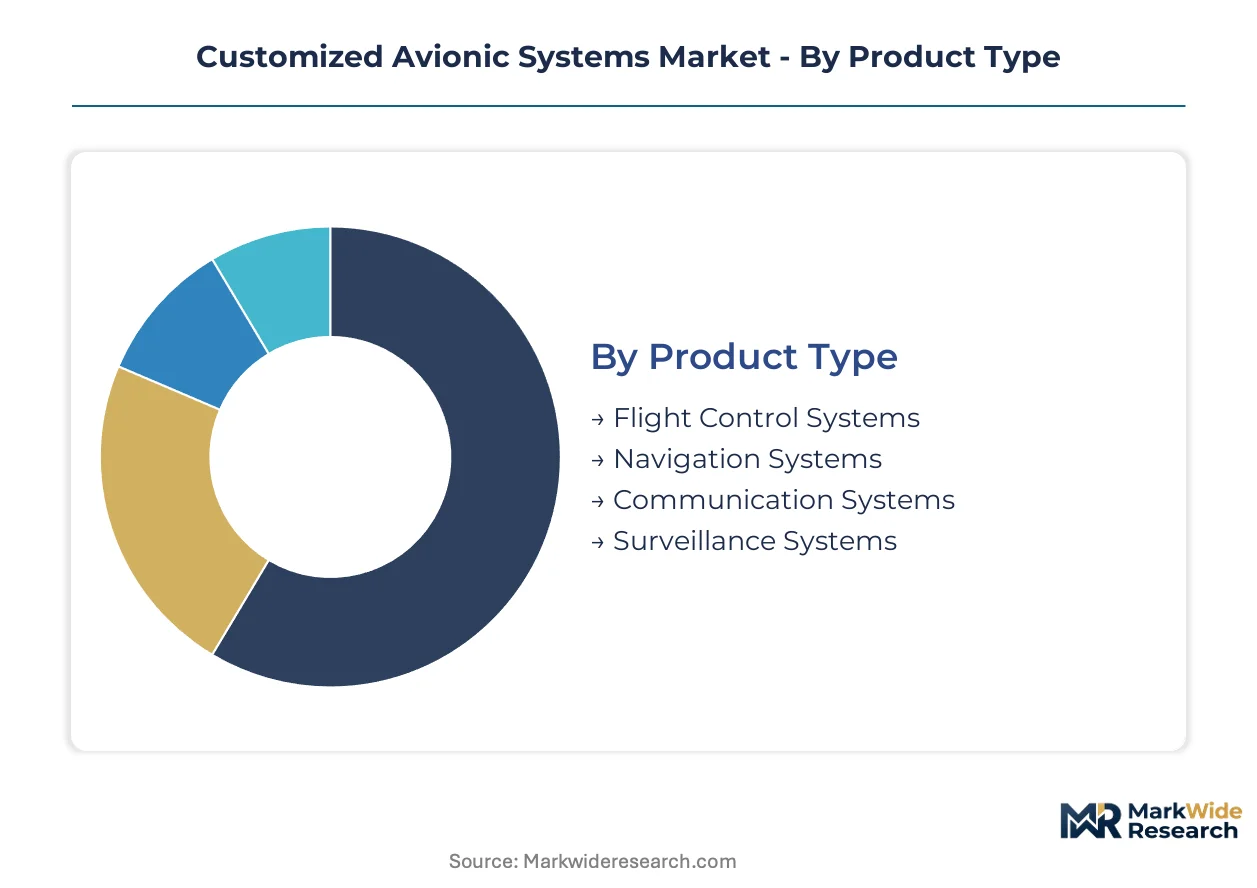
Segmentation in customized avionic systems reveals how capital allocation, certification requirements, and mission specificity fragment procurement patterns across hardware and service categories. Each dimension exposes distinct margin structures and supplier qualification barriers that shape competitive positioning.
Product Type:
Flight control systems demand the heaviest upfront engineering investment given DO-178C software assurance and redundant hardware architectures required for safety-critical functions.
- Flight Control Systems:These comprise fly-by-wire computers, actuator control electronics, and sensor fusion processors operating across -55°C to +125°C extremes. Military aviation procurement in the United States concentrates demand for platform-specific configurations as next-generation fighter programs accelerate development cycles.
- Navigation Systems:Inertial reference units, GPS receivers, and multi-sensor positioning modules integrate satellite and terrain-referenced guidance. Commercial aviation retrofit demand in the United States is compressing timelines as FAA NextGen mandates drive fleet-wide upgrades.
- Communication Systems:VHF, UHF, and satellite datalink transceivers with software-defined radio architectures.
- Surveillance Systems:Traffic alert, terrain awareness, and weather radar processors with integrated display generation.
Flight control systems absorb the bulk of installed capacity; avionics as a service is expanding most quickly through subscription-based flight management conversions.
End User:
Defense primes impose the most stringent qualification requirements, forcing suppliers to sustain MIL-STD-1553 and MIL-STD-1760 competencies alongside civil certification tracks.
- Commercial Aviation:Scheduled air carriers operating Part 121 fleets demand FAA-certified integrated modular avionics with predictable upgrade paths. United States-based carriers are consolidating supplier relationships around Texas-Arizona-California corridor integrators to compress qualification cycles.
- Military Aviation:Defense platforms require mission-tailored configurations with sovereign-certified mission systems and anti-tamper protections. European programs anchored by BAE Systems and Thales Group sustain parallel product lines for fighter and rotary-wing applications.
- UAVs:Uncrewed platforms with size-weight-power-constrained payloads and autonomous decision architectures.
- Business Aviation:Fractional ownership and charter operators seeking operational expenditure flexibility through avionics-as-a-service models.
Commercial aviation dominates absolute unit volume; UAVs are gaining share fastest as autonomous platform development accelerates across defense and commercial applications.
Technology:
Analog architectures retain installed base persistence in legacy military platforms, fragmenting R&D budgets across obsolete and modern product lines.
- Digital Systems:Integrated modular avionics with partitioned software stacks on shared processing hardware. Silicon carbide power modules are displacing legacy silicon in high-density flight control computers as thermal budgets compress.
- Hybrid Systems:Mixed-signal architectures bridging analog sensors with digital processing for cost-sensitive retrofits.
- Analog Systems:Discrete component architectures in legacy military platforms with extended service life requirements.
- Avionics as a Service:Cloud-connected flight management with subscription-based feature activation and over-the-air updates.
Digital systems command the largest development footprint; avionics as a service is climbing the fastest as operators convert capital expenditure to operational expenditure models.
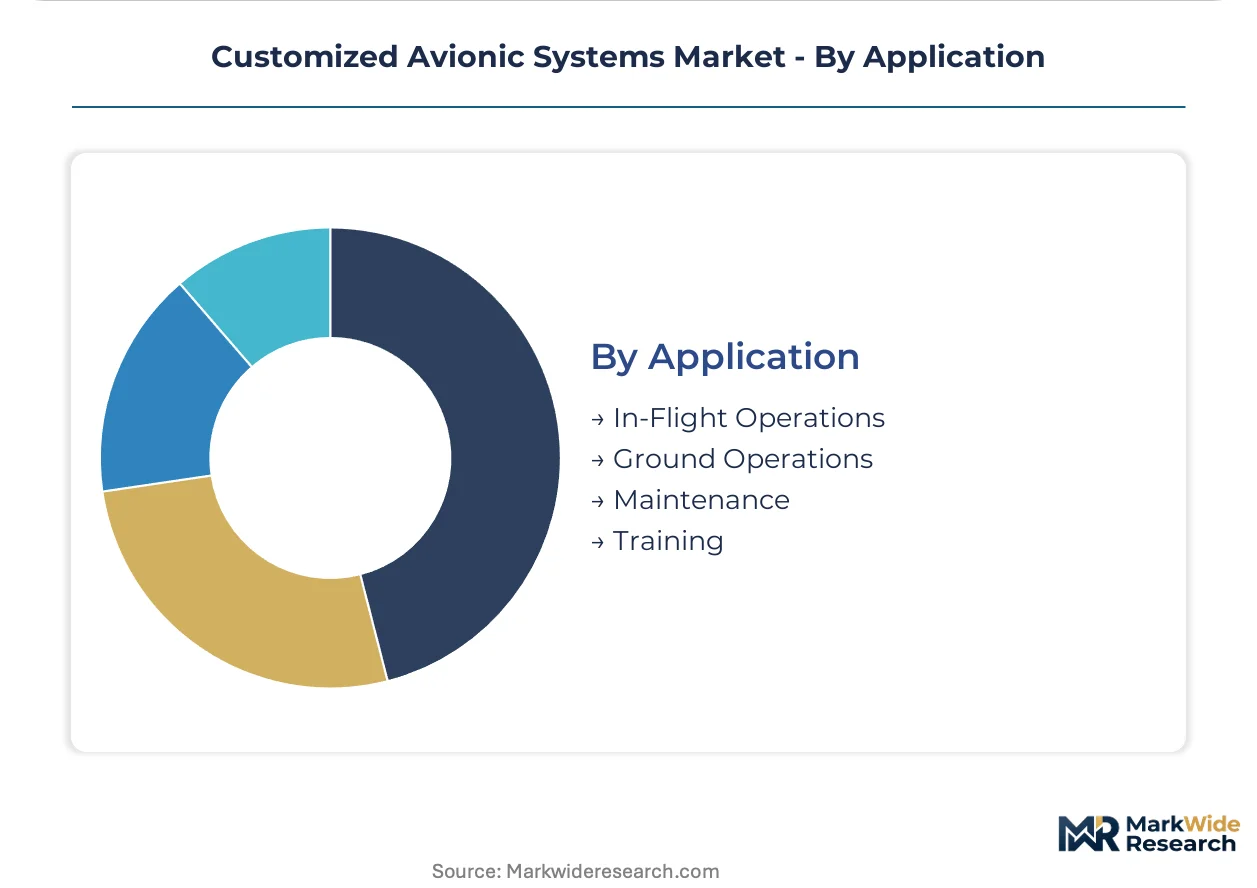
Application:
In-flight operations concentrate value capture given safety-critical certification requirements and continuous operational dependency.
- In-Flight Operations:Real-time command, navigation, communication, and surveillance functions with DO-178C Level A assurance for catastrophic failure conditions.
- Ground Operations:Pre-flight planning, dispatch, and ground-based augmentation systems with lower assurance requirements.
- Maintenance:Built-in test equipment and prognostic health monitoring with diagnostic data logging.
- Training:Synthetic environment replication for pilot and maintainer qualification with simulated fault injection.
In-flight operations anchor supplier revenue; training applications are expanding most quickly as synthetic environments reduce live-flight qualification costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense primes in the United States concentrate procurement of mission-tailored avionics suites, while European sovereign certification requirements sustain parallel supply chains across the Atlantic. The FAA's NextGen mandate and EASA's CS-25 harmonization are compressing retrofit timelines in both markets. Supplier qualification cycles accelerate where tier-one integrators cluster around aerospace corridors.
United States
Next-generation fighter programs and rotary-wing modernization drive procurement of platform-specific flight control computers. The FAA enforces DO-178C software assurance standards that consume 40-60% of development budgets for civil-certified systems. Texas, Arizona, and California host dense concentrations of defense primes and tier-one integrators, with direct subsystem procurement bypassing traditional distribution channels.
United Kingdom
Sovereign defense programs sustain demand for mission-certified avionics with anti-tamper protections. BAE Systems anchors domestic supply chains for fighter and naval aviation applications. The UK Civil Aviation Authority aligns certification pathways with EASA frameworks to capture cross-Atlantic retrofit contracts, particularly from business aviation operators in Switzerland and the Middle East.
France
Thales Group competes through differentiated fly-by-wire platforms for rotary-wing applications, addressing a segment where helicopter flight control modernization lags fixed-wing penetration. EASA CS-25 certification governs large-aircraft installations, with French integrators pursuing simultaneous US-European approval to accelerate fleet modernization timelines for business aviation operators.
Germany
Industrial and defense electronics specialists supply MIL-STD-1553 and MIL-STD-1760 interface components for European military platforms. The country's automotive semiconductor expertise transfers into silicon carbide power module development for high-density flight control computers. Bavaria and Baden-Württemberg host precision electronics manufacturing clusters serving adjacent aerospace supply chains.
Israel
Uncrewed platform development accelerates demand for size-weight-power-constrained avionic payloads with autonomous decision architectures. Elbit Systems exemplifies the specialist tier integrating mission computers and sensor fusion processors. Domestic defense procurement prioritizes sovereign-certified systems, with export orientation toward Asia-Pacific and Latin American UAV programs.
Customized Avionic Systems Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with defense primes consolidating around long-term platform-specific contracts while commercial aviation fragments across retrofit channels. The market structures into three tiers: integrated primes with captive avionics divisions, specialized subsystem houses with dual civil-military certification competencies, and compound-semiconductor power electronics entrants displacing legacy silicon suppliers. Competitive moves concentrate on M&A to absorb certification capabilities and strategic partnerships to bridge obsolete MIL-STD-1553 interfaces with modern Ethernet architectures.
Among defense-anchored integrators, L3Harris Technologies Inc., BAE Systems PLC, and Honeywell International Inc. exemplify contrasting archetypes. L3Harris occupies a position within the mission systems specialist tier, BAE Systems anchors European sovereign programs through platform-specific contracting, and Honeywell represents the integrated prime model leveraging proprietary modular architectures to sustain military relationships. Each sits within distinct competitive vectors—specialist agility, regional certification sovereignty, and scale-driven integrated supply—rather than direct segment overlap.
| Leading Market Players |
|---|
| L3Harris Technologies Inc. |
| BAE Systems PLC |
| Honeywell International Inc. |
| Elbit Systems Ltd. |
| Safran |
| RTX Corporation |
| General Electric Company |
| Meggitt PLC |
| Thales Group |
| Others |
Value Chain & Pricing Dynamics
Silicon carbide substrate fabrication is consolidating manufacturing economics and supplier power in customized avionic systems, compressing thermal management costs while concentrating wafer supply among three global producers. This dual compression of cost structures and input availability is reshaping how flight control computer vendors negotiate component contracts and price platform-specific configurations.
Pricing Analysis
Volume concentrates in flight control retrofits while margins cluster in avionics-as-a-service subscriptions. Three-tier pricing structure across DO-178C Level A certified, Level B qualified, and non-certified commercial tiers separates military primes from business aviation operators. Cost compression in silicon carbide power modules is intensifying because compound-semiconductor specialists undercut legacy silicon suppliers on thermal density metrics. Defense primes show least price sensitivity given sovereign certification requirements; fractional ownership operators in business aviation exhibit highest sensitivity as they convert capital expenditure to operational expenditure models.
Supply Chain Analysis
Specialized aerospace electronics manufacturing clusters in Texas, Arizona, and California face tightening availability of DO-178C certified software engineers and MIL-STD-1553 systems architects. Wafer fabrication concentrates in Japan, Germany, and the United States for silicon carbide substrates; flight control computer assembly draws from these same corridors. Single-source vulnerability runs through concentrated compound-semiconductor foundry capacity. Distribution runs through direct subsystem procurement from tier-one integrators bypassing traditional channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
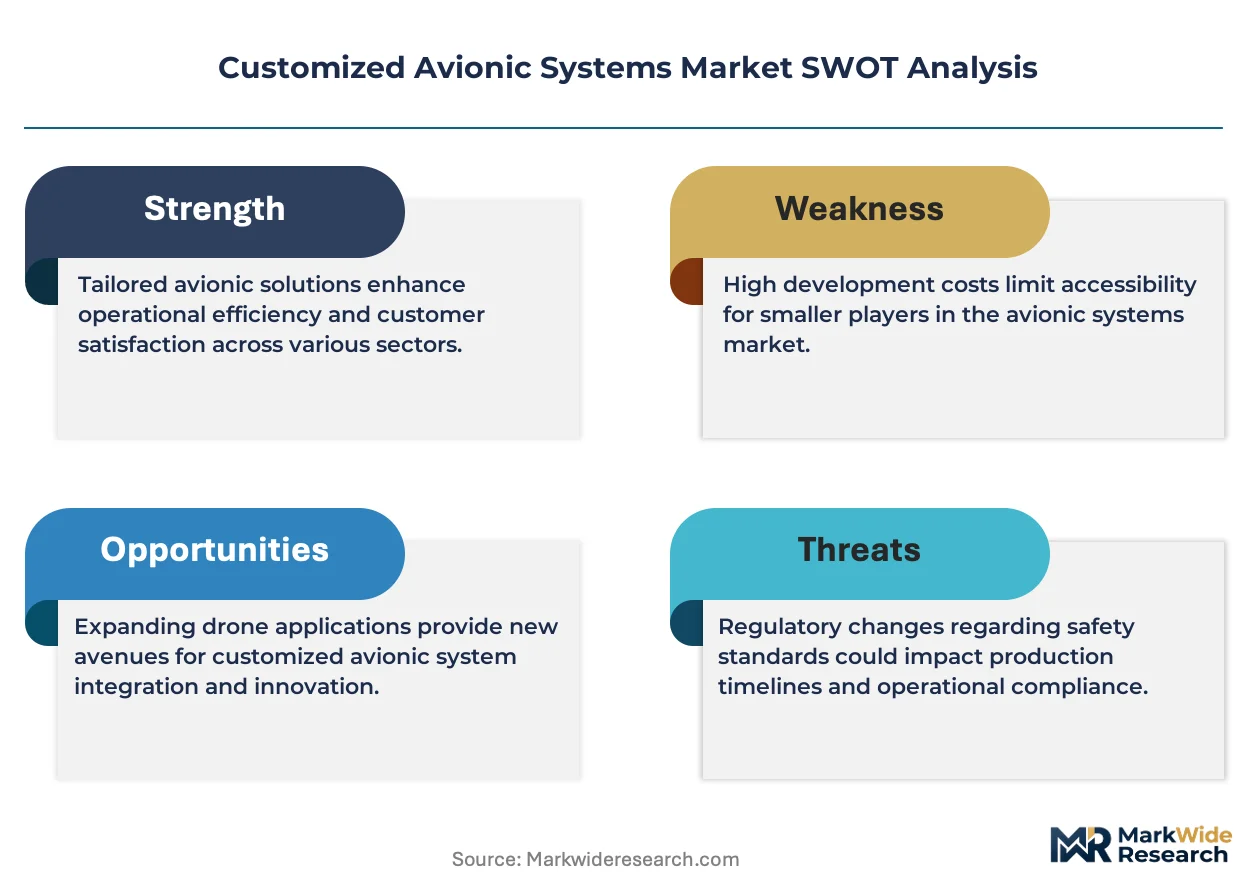
Customized avionic systems function as a cost-of-compliance market where FAA DO-178C and EASA CS-25 certification requirements erect structural barriers that protect incumbent qualification holders from commoditization pressure.
For Market Incumbents: Hedge silicon carbide supply exposure through qualification partnerships with compound-semiconductor foundries in Japan and Germany. Absorb DO-254 hardware certification capabilities in-house rather than outsourcing verification workflows, as FPGA-based mission computer demand accelerates. Consolidate position in rotary-wing fly-by-wire platforms where helicopter modernization lags fixed-wing penetration and pricing power remains intact. For New Entrants and Emerging Players: Enter via avionics-as-a-service subscription models targeting business aviation operators seeking operational expenditure flexibility over capital-intensive ownership. Rotary-wing fly-by-wire retrofits offer the most penetrable white space given Thales Group's current dominance and limited specialist competition. Pursue partnership pathways with Arizona and California-based tier-one integrators to compress supplier qualification cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by defense primes seeking dual civil-military certification competencies. Long-term viability favors specialized subsystem houses maintaining parallel DO-178C and MIL-STD-1553 capabilities over pure-play commercial vendors vulnerable to FAA mandate cyclicality. Watch silicon carbide substrate supply allocation decisions as inflection indicator for thermal management technology winners.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Capability Acquisition | Absorbing DO-178C software assurance teams compresses development timelines for civil-military dual-use contracts. |
| Compound-Semiconductor Supply Agreement | Long-term silicon carbide wafer offtake secures thermal density advantages in next-generation flight control computers. |
| Rotary-Wing Platform Specialization | Differentiated fly-by-wire architectures for helicopter applications exploit retrofit white space in lagging modernization cycles. |
| Avionics-as-a-Service Platform Launch | Subscription-based flight management converts business aviation capital expenditure to recurring operational expenditure revenue. |
| Direct Procurement Channel Establishment | Bypassing distribution partners for subsystem sales to Texas-Arizona-California integrators accelerates supplier qualification. |
Study Parameters
Multi-period observation of FAA NextGen retrofit timelines, EASA CS-25 certification harmonization progress, and defense prime procurement patterns anchored the trend analysis, supplemented by interviews with avionics program managers, DO-178C certification leads, flight control systems engineers, and tier-one integrator procurement directors. Secondary validation drew from FAA certification databases, EASA type certificate records, MIL-STD-1553 interface specifications, and defense contract award disclosures. Bottom-up segment sizing triangulated against top-down aerospace electronics expenditure estimates.
Segment-weighting across product type, end user, technology, and application dimensions shaped the analytical framework over the projection horizon. Flight control systems, navigation systems, communication systems, and surveillance systems carried distinct certification cost assumptions. CAGRs derived from platform-specific contracting velocity, retrofit cycle compression, and avionics-as-a-service adoption curves. Forecast inputs included silicon carbide power module penetration rates and rotary-wing fly-by-wire modernization lag.
Forecast precision tightens around the base case; tail outcomes carry wider variance under silicon carbide supply disruption or FAA certification timeline extension scenarios. Forecasts reflect documented assumptions about defense procurement continuity and EASA-FAA harmonization progress. A small set of triggers—compound-semiconductor foundry allocation shifts, MIL-STD-1553 legacy interface retirement decisions, and business aviation subscription conversion velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Global Commercial Avionics Systems Market
Avionics
Military Aircraft Avionics Market
Avionics
Aircraft Computers Market
Avionics
Asia-Pacific Aircraft Avionics Market
Avionics
Commercial Electronic Flight Bag Market
Avionics
Aerospace Avionics Market
Avionics
Avionics LRU Repair and Test Services Market
Avionics
Autonomous Aircraft Flight Management Computers Market
Avionics
Military Avionic Systems Market
Avionics
Display for Avionics Application Market
Avionics
Europe Military Aircraft Communication Avionics Market
Avionics
Global Helicopter Avionics Market
Avionics
Commercial Aircraft Electronic Flight Bag (EFB) Systems Market
Avionics
North America Military Aircraft Communication Avionics Market
Avionics
Middle East Commercial Aircraft in-Flight Entertainment System Market
Avionics
Europe Commercial Aircraft in-Flight Entertainment System Market