
 Asia-Pacific Medium and Large Caliber Ammunition Market | 2026-2036
Asia-Pacific Medium and Large Caliber Ammunition Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Medium and Large Caliber Ammunition Market Outlook
The EU Green Deal's defense industrial decarbonization guidelines is restructuring procurement criteria across NATO-aligned Asia-Pacific militaries, compelling ammunition suppliers to reformulate propellant chemistries and reduce lifecycle emissions. Hanwha Corporation leverages its integrated explosives-to-assembly pipeline to dominate South Korean naval artillery supply. Poongsan Corporation anchors regional mortar round exports through its propellant casting expertise. Rheinmetall AG competes on precision-fuzed 155mm shell technology for Australian and Indonesian land forces.
Medium and large caliber ammunition encompasses projectiles, propellant charges, and fuzing systems designed for rifled and smoothbore weapons firing munitions of 20mm diameter and above, with brass or steel cartridge cases, nitrocellulose-based propellants, and point-detonating or proximity fuzes serving anti-armor, area suppression, and precision-strike missions. Artillery shells in 155mm caliber sustain the largest revenue pool given NATO-standard interoperability and replacement cycles for aging stockpiles, while tank ammunition differentiates through depleted uranium and tungsten penetrator formulations against reactive armor threats. Propellant segments occupy thinner margins but control supply security for vertically integrated primes.
India's Defence Acquisition Procedure, Australia's Sovereign Guided Weapons and Explosive Ordnance Enterprise, and South Korea's Defense Acquisition Program Administration collectively shape market access through local-content thresholds, offset mandates, and foreign-ownership ceilings on sensitive explosive manufacturing. Australia's explosive ordnance safety regulator enforces strict insensitive munitions standards that filter supplier eligibility for Pacific partner nations. Stakeholders must monitor how bilateral security compacts between Japan, Australia, and India redirect procurement flows away from traditional European supply lines toward regional co-production frameworks.
Market Dynamics
Naval modernization programs across Southeast Asian littoral states are compressing procurement cycles for shipboard artillery systems, while India's Defence Acquisition Procedure reforms are accelerating indigenization mandates that reshape supplier eligibility for medium and large caliber ammunition.
Growth Catalysts
- Defence Acquisition Procedure 2020:India's revised offset thresholds and local-content mandates are channeling foreign original equipment manufacturers toward joint ventures with state-owned ordnance factories, expanding domestic shell and propellant capacity.
- Sovereign munitions initiatives:Australia's Guided Weapons and Explosive Ordnance Enterprise is consolidating fragmented explosive ordnance procurement under a single national framework, generating sustained demand for 155mm artillery and naval gun ammunition.
- Insensitive munitions standards:Australia's explosive ordnance safety regulator is mandating IM-compliant formulations for Pacific partner nations, creating technical barriers that favor suppliers with advanced propellant chemistry capabilities.
Market Restraints
- Nitrocellulose supply concentration:Global propellant precursor production clusters in China and Eastern Europe, exposing Asia-Pacific assemblers to raw material disruption risks from trade policy friction.
- Foreign ownership ceilings:South Korea's Defense Acquisition Program Administration restricts equity participation in sensitive explosive manufacturing, limiting technology transfer depth for multinational primes.
- Depleted uranium substitution costs:Environmental liability frameworks in Australia and Japan are forcing tungsten penetrator adoption for anti-armor rounds, elevating unit production costs against legacy uranium formulations.
Strategic Opportunities
- Indonesian naval artillery expansion:The Tentara Nasional Indonesia-Angkatan Laut is procuring new frigate classes with 76mm and 127mm gun systems, opening procurement windows for precision-fuzed naval rounds.
- Japan-Australia-India trilateral co-production:Emerging bilateral security compacts are redirecting supply chains toward regional manufacturing frameworks, displacing traditional European sourcing for Pacific partner nations.
- PLI scheme alignment:India's Production Linked Incentive schemes for defense manufacturing are subsidizing greenfield explosive ordnance facilities, lowering capital barriers for domestic entrants.
Industry Challenges
- Propellant chemist scarcity:Specialized expertise in nitrocellulose formulation and casting operations is concentrated in aging workforces at state-owned facilities across the region, constraining capacity expansion timelines.
- Insensitive munitions certification delays:Australia's regulator enforces multi-year qualification protocols for IM-compliant fuzing systems, extending product development cycles for new market entrants.
- Legacy system integration:Vietnam and Philippines forces operate mixed NATO and Soviet-caliber inventories, complicating logistics and forcing suppliers to maintain parallel production lines for non-standard ammunition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Medium and Large Caliber Ammunition Market |
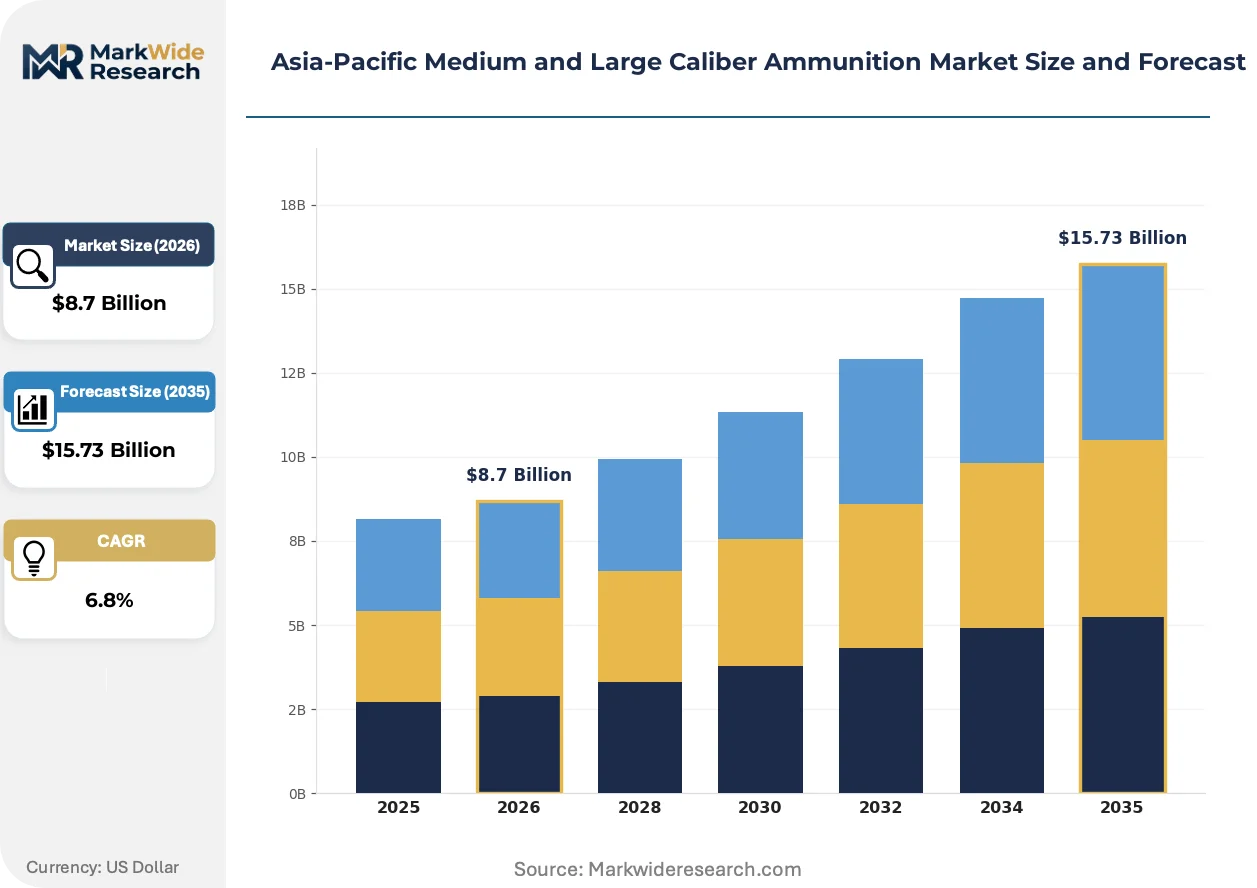
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artillery Shells, Mortar Rounds, Tank Ammunition, Propellant End User: Military, Law Enforcement, Defense Contractors, Private Security Caliber Size: 20mm, 40mm, 105mm, 155mm Distribution Channel: Direct Sales, Online Retail, Distributors, Manufacturers |
| Companies Covered | Munitions India Limited, Hanwha Corporation, Poongsan Corporation, Rheinmetall AG, Singapore Technologies Engineering Ltd, Bharat Electronics Limited, China South Industries Group Co Ltd, Kalyani Strategic Systems Limited, BAE Systems plc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Medium and Large Caliber Ammunition Market Strategic Shifts
Precision-guided artillery technology and environmentally reformulated propellants are converging to redefine performance benchmarks, while procurement centralization is compressing supplier margins and consolidating contract volumes toward vertically integrated primes.
Modular charge systems with combustible cartridge cases are absorbing incremental R&D investment from South Korean and Australian ordnance programs. Naval gunnery divisions are adopting these configurations to reduce magazine stowage weight and accelerate loading cycles. The technology is absorbing market share from traditional brass-cased ammunition in shipboard applications, compressing revenue pools for legacy cartridge case suppliers.
The EU Green Deal's defense industrial decarbonization guidelines are restructuring procurement criteria across NATO-aligned Asia-Pacific militaries. Ammunition suppliers must now document lifecycle emissions from precursor chemicals through demilitarization. Australian and Japanese land forces are most affected, inserting carbon-footprint clauses into tender evaluations that disadvantage producers without green chemistry capabilities.
Consolidated national procurement frameworks are displacing fragmented service-level purchasing across the region. Australia's single enterprise model for explosive ordnance is being studied by New Zealand and Singapore defense ministries as a template. This behavioral shift is most visible in Canberra's capital territory, where multi-year munitions stockpile contracts now bundle artillery, mortar, and naval ammunition under unified vendor management.
Asia-Pacific Medium and Large Caliber Ammunition Market Segmentation
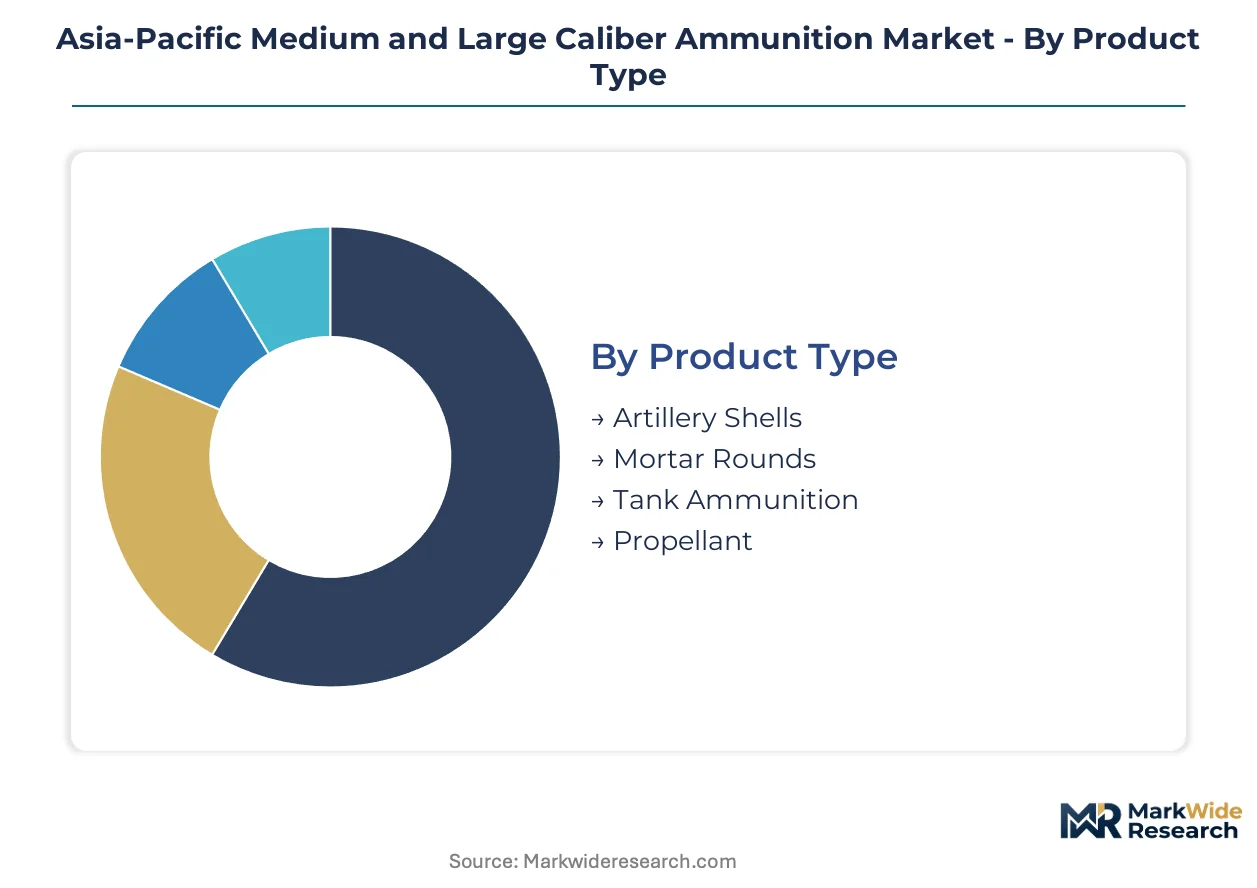
Segmentation in the Asia-Pacific medium and large caliber ammunition market reveals how procurement centralization, caliber standardization, and distribution security reshape supplier positioning across national defense frameworks. Understanding these divides exposes where technology leadership concentrates and where new entrants face barriers.
Product Type:
Caliber specification and mission profile determine manufacturing complexity, propellant chemistry requirements, and qualification timelines for each product category.
- Artillery Shells:Steel or forged alloy projectiles paired with brass cartridge cases or modular combustible charges, designed for rifled howitzers and naval guns. India's ordnance modernization programs and Australia's sovereign munitions initiatives concentrate demand for NATO-standard 155mm precision-fuzed rounds, with insensitive munitions compliance filtering supplier eligibility.
- Mortar Rounds:Fin-stabilized projectiles with variable propellant increments for high-angle fire, requiring specialized casting expertise for incremental charge systems. Southeast Asian littoral states expanding marine infantry capabilities drive procurement for 81mm and 120mm systems, though regional production capacity remains concentrated at state-owned facilities.
- Tank Ammunition:Sub-caliber penetrators with depleted uranium or tungsten cores against reactive armor threats, encased in combustible semi-combustible cartridge configurations.
- Propellant:Nitrocellulose-based formulations with stabilizers and deterrent coatings, controlling burn rates for consistent muzzle velocities.
Mature deployment sits with artillery shells. Newer deployment is concentrated in propellant chemistry upgrades for insensitive munitions compliance.
End User:
Customer type dictates security clearance requirements, contract duration, and technical specification rigor across the procurement lifecycle.
- Military:National armed forces with multi-year stockpile contracts, technical acceptance protocols, and offset mandates under India's Defence Acquisition Procedure and South Korea's Defense Acquisition Program Administration. Australia's Guided Weapons and Explosive Ordnance Enterprise consolidates demand under unified vendor management, compressing supplier margins toward vertically integrated primes.
- Defense Contractors:Prime integrators subcontracting ammunition for platform-integrated weapon systems, requiring traceable supply chains and export license coordination.
- Law Enforcement:Specialized tactical units with limited volume requirements and accelerated procurement cycles for less-lethal and breaching applications.
- Private Security:Maritime protection and critical infrastructure operators with restricted access to military-grade calibers and fuzing technologies.
Military procurement absorbs the dominant contract volume. Defense contractors represent the steepest expansion trajectory as platform integrators deepen backward integration into ammunition supply.
Caliber Size:
Standardization alliances and legacy system inventories fragment demand across incompatible technical specifications.
- 155mm:NATO-standard artillery caliber dominating land force procurement, with interoperability requirements forcing common ballistic profiles and fuzing interfaces. Australia's stockpile modernization and Indonesian army expansion sustain the largest revenue concentration, though propellant temperature sensitivity remains a performance constraint in tropical climates.
- 105mm:Legacy light artillery and tank gun caliber persisting in Southeast Asian inventories with mixed NATO and Soviet lineage, complicating logistics for non-standard ammunition.
- 40mm:Automatic grenade launcher and naval close-in weapon system caliber, with Southeast Asian naval modernization accelerating orders for shipboard applications.
- 20mm:Aircraft cannon and light naval gun caliber with declining land force relevance outside airborne platforms.
155mm deployment dominates procurement budgets. 40mm naval applications are climbing the fastest as littoral states expand frigate and patrol vessel construction.
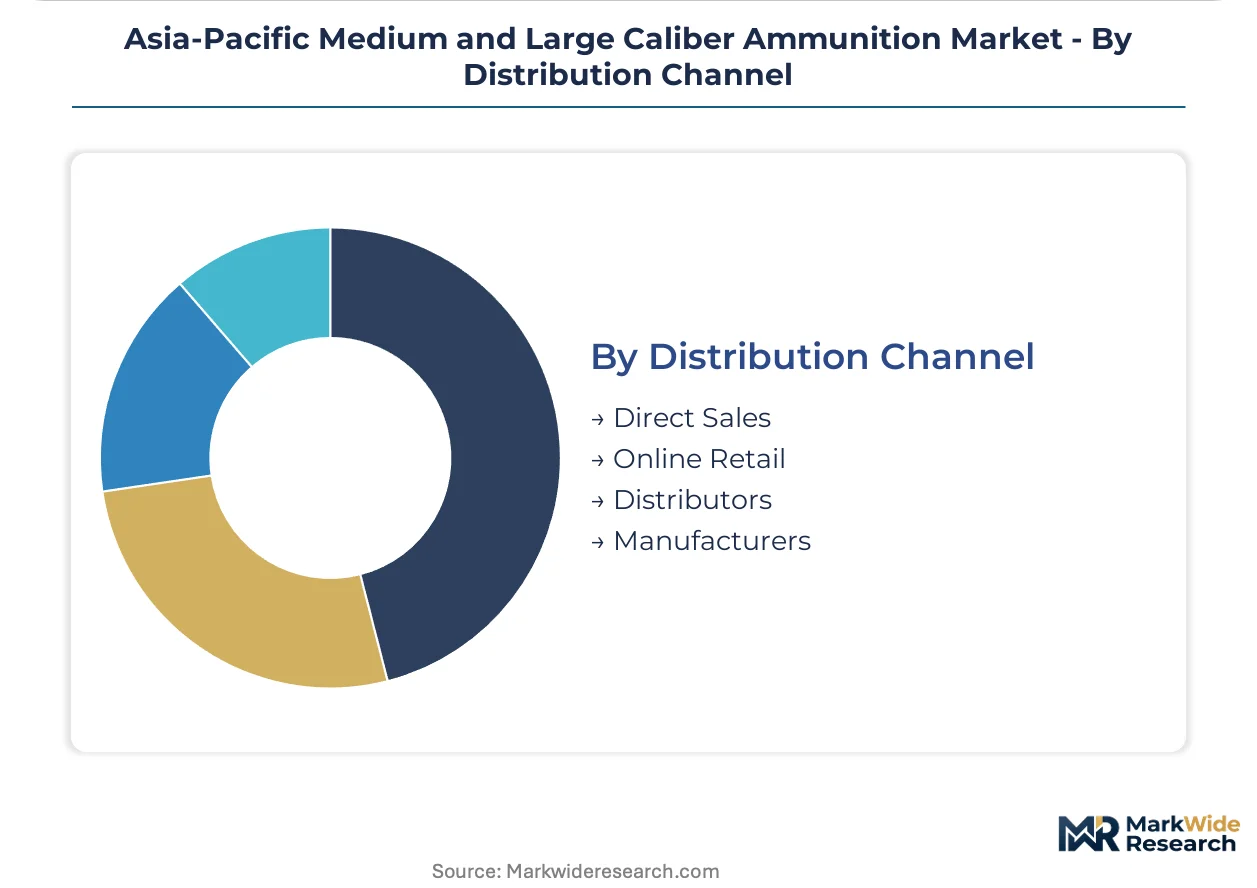
Distribution Channel:
Channel structure reflects security classification, order scale, and national sovereignty requirements across the region.
- Direct Sales:Government-to-government or prime-to-military contracts with classified specifications, multi-year delivery schedules, and local-content mandates. India's offset thresholds and South Korea's foreign ownership ceilings channel foreign original equipment manufacturers toward joint ventures, reshaping direct sales eligibility.
- Distributors:Authorized intermediaries handling non-sensitive calibers and training ammunition for law enforcement and allied partner nations.
- Manufacturers:Captive production at state-owned ordnance factories with limited external channel dependency.
- Online Retail:Restricted to inert replicas, demilitarized components, and technical documentation with no operational ammunition availability.
Direct sales capture military-grade volume. Distributor networks are gaining share fastest as Pacific partner nations seek procurement flexibility outside bilateral government frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors regional ammunition innovation through Hanwha Corporation's integrated explosives-to-assembly pipeline, while procurement reforms across Southeast Asian navies compress order cycles for naval gun systems.
India
Ordnance modernization programs drive demand for 155mm artillery shells and indigenous propellant capacity. The Defence Acquisition Procedure 2020 channels foreign manufacturers toward joint ventures with state-owned factories under local-content mandates. The Pune-Ambarnath industrial corridor concentrates shell forging and filling operations where private sector entrants are establishing greenfield explosive ordnance facilities.
South Korea
Naval artillery supply contracts dominate procurement volumes for 76mm and 127mm precision-fuzed rounds. The Defense Acquisition Program Administration enforces foreign ownership ceilings on sensitive explosive manufacturing that limit technology transfer depth. The Changwon-Seongju defense cluster houses propellant casting and modular charge system production where insensitive munitions R&D is accelerating.
Australia
The Sovereign Guided Weapons and Explosive Ordnance Enterprise consolidates fragmented procurement under unified national management. Australia's explosive ordnance safety regulator mandates multi-year qualification protocols for IM-compliant formulations that filter supplier eligibility. The Benalla-Mulwala corridor hosts the country's primary propellant and filling infrastructure where stockpile modernization contracts are bundling artillery and naval ammunition.
Indonesia
The Tentara Nasional Indonesia-Angkatan Laut is procuring new frigate classes with 76mm and 127mm gun systems, opening procurement windows for precision-fuzed naval rounds. National offset requirements under defense procurement law steer foreign suppliers toward local partnership structures. The Surabaya naval industrial zone concentrates shipboard weapons integration where ammunition logistics capabilities are expanding to support expanded fleet operations.
Japan
Environmental liability frameworks are forcing tungsten penetrator adoption for anti-armor rounds, elevating unit production costs against legacy depleted uranium formulations. METI coordinates industrial policy for propellant chemistry reformulation to meet decarbonization guidelines. The Nagoya-Osaka manufacturing belt houses precision machining capacity where trilateral co-production discussions with Australia and India are redirecting supply chain planning.
Asia-Pacific Medium and Large Caliber Ammunition Market Competitive Environment
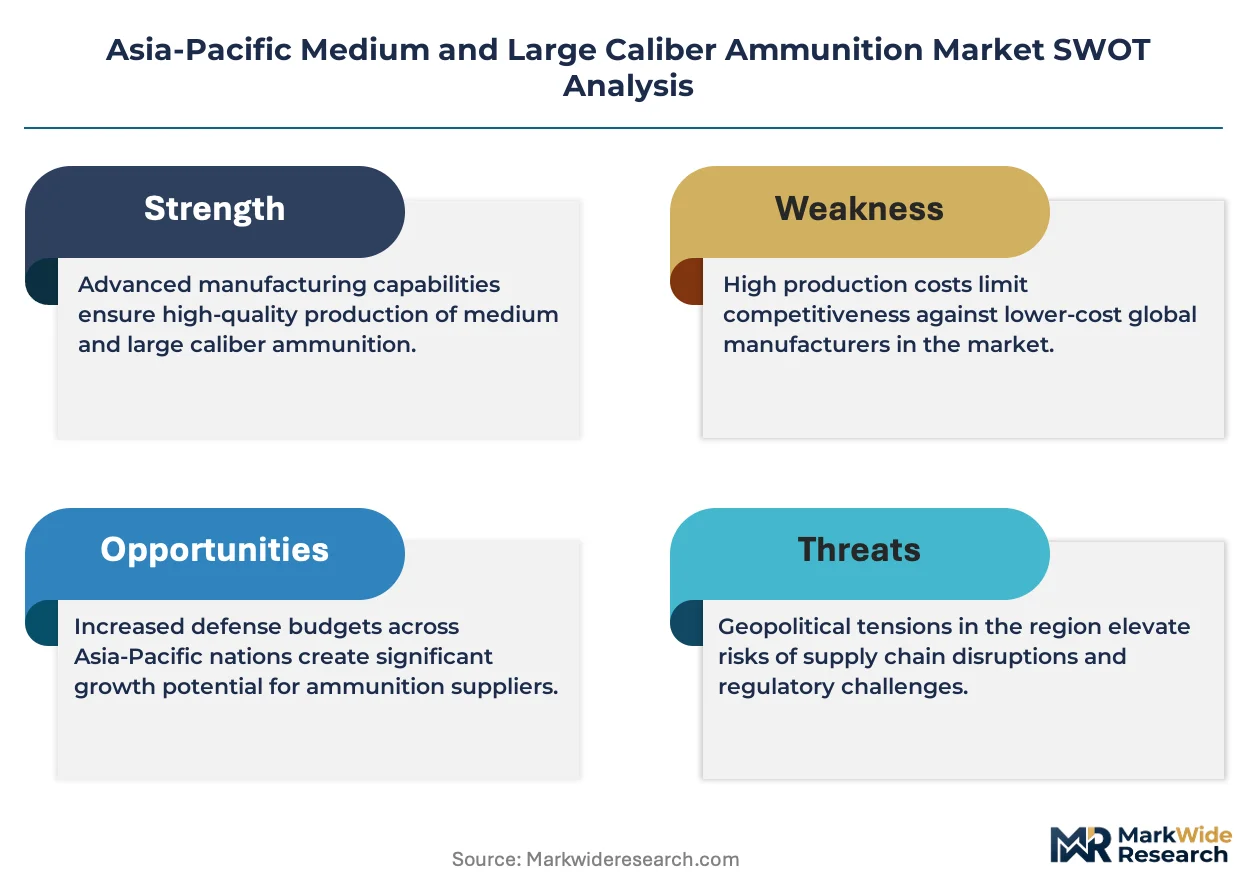
Premium-margin players sit above commodity-margin players across propellant chemistry capability and insensitive munitions certification depth. The vendor base stratifies between integrated primes with captive explosives supply and assembly-only contractors exposed to nitrocellulose price volatility. Three archetypes dominate: state-owned ordnance factories with guaranteed domestic offtake, diversified conglomerates with backward integration into propellant production, and foreign specialists competing on precision-fuzed technology. Capacity expansion and strategic partnerships constitute the dominant competitive moves as regional procurement centralization compresses contract volumes toward fewer suppliers.
Within the integrated prime tier, Hanwha Corporation and Poongsan Corporation anchor South Korean supply security through in-house explosives production. Rheinmetall AG occupies a position exemplifying foreign precision-technology competition for Australian and Indonesian land force contracts. Munitions India Limited represents the state-owned archetype where Defence Acquisition Procedure reforms are opening joint venture pathways for private sector participation. These three entities illustrate how geography and ownership structure determine market access under tightening local-content regimes.
| Leading Market Players |
|---|
| Munitions India Limited |
| Hanwha Corporation |
| Poongsan Corporation |
| Rheinmetall AG |
| Singapore Technologies Engineering Ltd |
| Bharat Electronics Limited |
| China South Industries Group Co Ltd |
| Kalyani Strategic Systems Limited |
| BAE Systems plc |
| Others |
Value Chain & Pricing Dynamics
Australia's Guided Weapons and Explosive Ordnance Enterprise and India's Defence Acquisition Procedure reforms concentrate procurement authority in national-level buyers, compressing supplier margins toward long-term contract pricing with local-content premiums. This buyer concentration forces ammunition primes to absorb nitrocellulose cost volatility through captive propellant production or risk disqualification under offset mandates.
Pricing Analysis
Value-based pricing anchored to insensitive munitions certification depth and precision-fuzing performance separates premium suppliers from commodity assemblers. Three-tier pricing structure across IM-certified, NATO-standard, and legacy-grade ammunition reflects qualification timeline differentials and safety compliance investment. Cost compression in standard 155mm artillery shells is intensifying as India's PLI subsidies attract domestic entrants, while Australian naval gun contracts sustain pricing power for IM-compliant precision rounds. Defense contractors integrating ammunition into platform systems exhibit lowest price sensitivity; law enforcement and training ammunition buyers face steepest budget constraints.
Supply Chain Analysis
Propellant chemist scarcity in South Korea's Changwon-Seongju cluster and India's Pune-Ambarnath corridor constrains capacity expansion timelines for nitrocellulose formulation. Supply concentrates in China and Eastern Europe for raw nitrocellulose, South Korea for modular charge systems, and Australia for IM-compliant filling operations. Raw material dependencies on cotton cellulose feedstock, nitric acid, and stabilizer chemicals expose assemblers to commodity price swings. Single-source vulnerability in Chinese precursor supply creates tariff exposure risks. Distribution runs through government-to-government direct sales for military-grade contracts, with authorized distributors handling law enforcement and allied partner procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized propellant chemistry expertise functions as the binding capacity constraint across Asia-Pacific ordnance programs, insulating certified suppliers from price erosion while excluding uncertified competitors from tender eligibility.
For Market Incumbents: Lock in backward integration into nitrocellulose production or secure long-term precursor supply agreements before India's PLI scheme floods domestic capacity. Invest in IM certification depth at Australian and Japanese regulators to defend margin position against European precision-fuzing specialists. Capture joint venture equity in India's state-owned ordnance factory partnerships to preserve market access under local-content mandates. For New Entrants and Emerging Players: Digital-channel defense procurement platforms in Southeast Asian littoral states offer lower barrier entry points than bilateral government frameworks dominated by integrated primes. Target Indonesian naval artillery expansion and Philippine coast guard modernization as penetrable segments with less stringent IM compliance requirements. Pursue subcontractor positioning under Rheinmetall or Hanwha prime contracts to build qualification track records before direct tendering. For Investors and Strategic Acquirers: The window for entry favors propellant-chemistry specialists with existing IM certification and aging workforce succession risk. Long-term viability hinges on 5-10 year stockpile modernization cycles across Australia, India, and Indonesia. Watch for Australian regulator approval of tungsten penetrator formulations as inflection indicator for environmental liability framework adoption across Japan and South Korea.| Strategic Initiative | Industry Significance |
|---|---|
| IM Certification Investment | Australian regulator approval unlocks Pacific partner nation tender eligibility for precision-fuzed suppliers. |
| Joint Venture Formation | India's Defence Acquisition Procedure channels foreign OEMs toward state-owned factory partnerships with equity caps. |
| Backward Integration | Captive nitrocellulose production insulates margins from Chinese precursor supply disruption risks. |
| Naval Artillery Expansion | Indonesian frigate procurement opens 76mm and 127mm precision-fuzed round demand windows. |
| Green Chemistry Transition | EU Green Deal decarbonization guidelines force propellant reformulation for NATO-aligned Asia-Pacific militaries. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with ordnance factory executives, defense procurement officers, propellant chemists, and naval weapons integration specialists. Defense Acquisition Procedure documentation, Australian explosive ordnance safety regulator protocols, and South Korean Defense Acquisition Program Administration filings provided policy framework validation. Customs records on nitrocellulose precursor trade flows and national stockpile budget appropriations furnished demand-side calibration. Bottom-up capacity assessments at Changwon-Seongju, Pune-Ambarnath, and Benalla-Mulwala industrial corridors were triangulated against top-down procurement contract value aggregation.
Segment-level modeling operated at product type, end user, caliber size, and distribution channel granularity across the projection horizon. Artillery shell, mortar round, tank ammunition, and propellant categories were modeled separately with caliber-specific qualification timeline assumptions. Military, defense contractor, law enforcement, and private security end users carried distinct contract duration and security clearance parameters. CAGRs were derived from contract award velocity analysis and stockpile modernization schedule alignment with platform procurement cycles. Nitrocellulose supply concentration risk and IM compliance diffusion rates served as industry-specific forecast modifiers.
The model holds under stable bilateral security compact commitments and continued local-content mandate enforcement; deviation in trade policy friction severity or propellant chemist workforce availability would shift capacity expansion timelines and pricing power distribution. Material deviation in Chinese nitrocellulose export restrictions or Australian IM certification protocol acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Supersonic and Hypersonic Weapons Market
Weapons and Ammunition
Global Shoulder-Fired Weapons Market
Weapons and Ammunition
Global Multiple Launch Rocket Systems Market
Weapons and Ammunition
Nuclear Bomb Market
Weapons and Ammunition
Asia-Pacific Nuclear Bombs and Missiles Market
Weapons and Ammunition
Airborne Weapon System Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
Detonator Market
Weapons and Ammunition
France Nuclear Bombs and Missiles Market
Weapons and Ammunition
Weapon Mounts Market
Weapons and Ammunition
Electrical Weapon Market
Weapons and Ammunition
Nuclear Bombs and Missiles Market
Weapons and Ammunition
Space Weapons Market
Weapons and Ammunition
Small Caliber Ammunition Market
Weapons and Ammunition
Small Arms Market
Weapons and Ammunition
Smart Weapons Market