
 Global Semiconductor Packaging and Assembly Equipment Market | 2026-2036
Global Semiconductor Packaging and Assembly Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semiconductor Packaging and Assembly Equipment Market Analysis
The buyer landscape for semiconductor packaging and assembly equipment is broadening beyond traditional integrated device manufacturers toward fabless AI chip designers and outsourced semiconductor assembly and test providers. ASM Pacific Technology leverages its dominant position in die attach and wire bonding systems across Greater China. Applied Materials sustains technology leadership in advanced packaging deposition and etch tools. Kulicke & Soffa Industries specializes in ball bonding and wedge bonding platforms for automotive-grade reliability requirements.
Semiconductor packaging and assembly equipment encompasses capital machinery used to encapsulate, interconnect, and test bare silicon dies into functional electronic components, operating at micron-scale precision with throughput rates exceeding 20,000 units per hour for high-volume consumer applications. Flip chip and advanced packaging technologies command premium pricing as chiplet-based architectures displace monolithic designs in data center processors. Wire bonding remains the volume anchor in automotive and industrial end-user segments where cost sensitivity and proven reliability standards persist. Testing equipment captures disproportionate margin pools as heterogeneous integration multiplies defect-detection complexity.
The US Department of Commerce export controls on advanced packaging equipment to China intersect with South Korea's K-Chips Act subsidies and Japan's METI semiconductor revitalization strategy, fragmenting procurement compliance requirements across supplier jurisdictions. REACH and RoHS frameworks in Europe restrict lead-based solder materials and halogenated flame retardants in packaging chemistries, compelling equipment retrofits and process qualification cycles. Stakeholders must monitor how bilateral technology transfer restrictions reshape the geographic deployment of advanced packaging capacity without triggering supply chain discontinuities.
Market Dynamics
Heterogeneous integration architectures are forcing equipment vendors to retool for chiplet-based assembly workflows, compressing qualification cycles while expanding addressable precision requirements. This structural shift reconfigures capital allocation across die attach, lithography, and testing subsystems.
Growth Catalysts
- EU Chips Act capital allocation:Subsidized fab construction in Germany and France is generating pull-through demand for advanced packaging lines. Equipment vendors are pre-qualifying deposition tools for these greenfield sites.
- AI accelerator heterogeneous integration:Fabless designers in Taiwan and South Korea are commissioning fan-out panel-level packaging capacity. Die-to-wafer bonding throughput requirements have doubled.
- Automotive functional safety mandates:ISO 26262 certification is expanding wire bonding demand for power modules. Tier-1 suppliers are qualifying second-source assembly equipment.
Market Restraints
- Neon gas supply concentration:Ukrainian-sourced noble gases remain critical for excimer laser annealing. Disruption risks elevate input cost volatility for lithography-adjacent packaging tools.
- US export control friction:Commerce Department licensing requirements for advanced packaging equipment to China are fragmenting supplier compliance architectures. Vendors face jurisdiction-specific product variants.
- Copper pillar interconnect limitations:Fine-pitch scaling beyond 40 micrometers encounters electromigration barriers in high-current AI accelerators. Alternative metallurgies remain unqualified.
Strategic Opportunities
- India PLI scheme assembly incentives:Domestic packaging capacity subsidies are attracting OSAT investment in Gujarat and Karnataka. Equipment vendors can establish localized service footprints.
- Photonics-electronics convergence:Co-packaged optical I/O modules require hybrid bonding and passive alignment capabilities. Data center interconnect demand is creating new tool categories.
- Japan METI semiconductor revitalization:Subsidized advanced packaging R&D consortia in Tsukuba are accelerating glass substrate and embedded die technologies. Collaboration frameworks reduce customer acquisition costs.
Industry Challenges
- Process engineer scarcity:Heterogeneous integration requires expertise spanning front-end lithography and back-end assembly. Universities in Taiwan and South Korea are expanding packaging-specific curricula.
- Multi-vendor integration complexity:Chiplet assembly lines combine tools from deposition, bonding, and testing specialists. Interface standardization gaps extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semiconductor Packaging and Assembly Equipment Market |
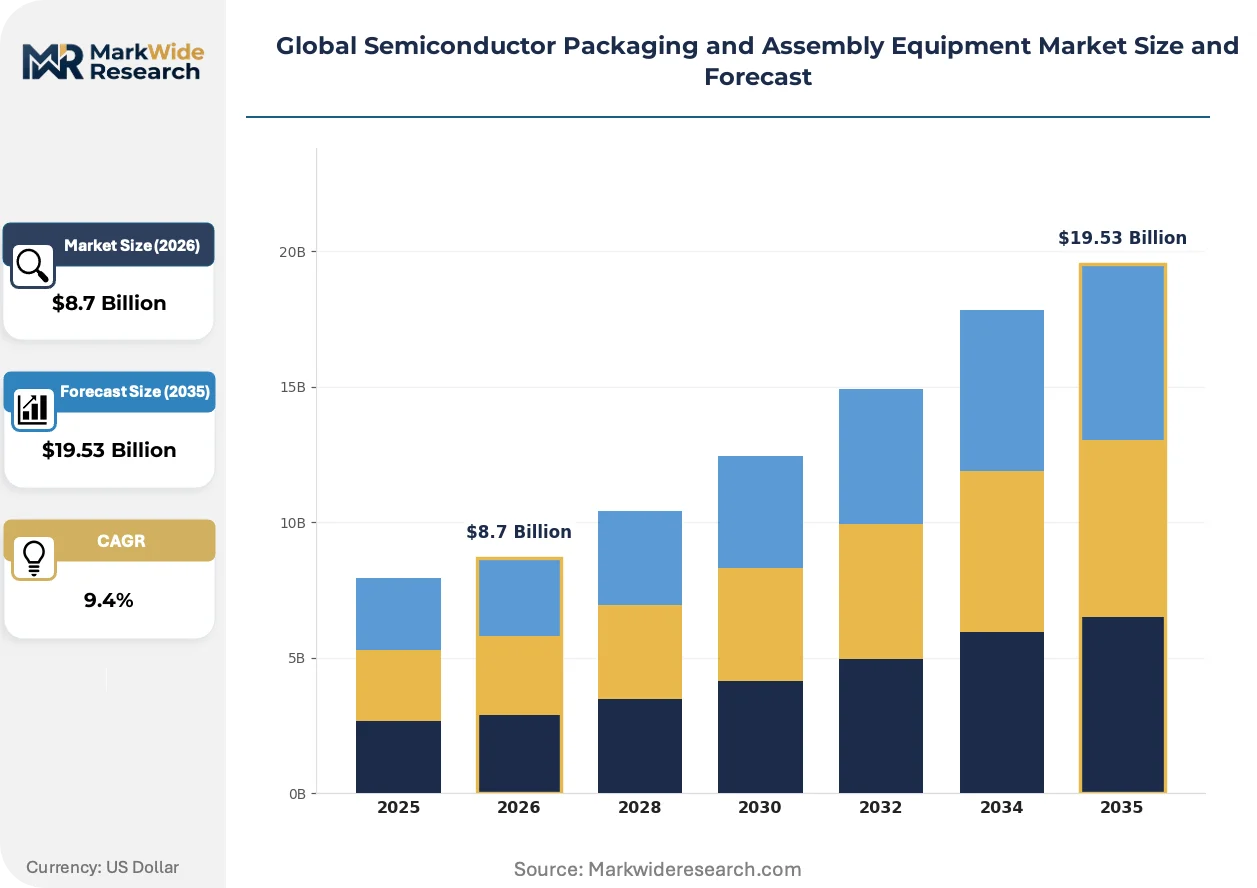
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Testing Equipment, Assembly Machines, Packaging Tools, Inspection Systems Technology: Die Attach, Wire Bonding, Flip Chip, Advanced Packaging End User: Consumer Electronics, Automotive, Telecommunications, Industrial Deployment: On-Premise, Cloud-Based, Hybrid, Remote |
| Companies Covered | ASM Pacific Technology, Applied Materials, Tokyo Electron Limited, Veeco Instruments, Besi, Kulicke & Soffa Industries, Disco Corporation, Lam Research Corporation, SUSS MicroTec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semiconductor Packaging and Assembly Equipment Market Emerging Trajectories
Equipment architectures are converging around panel-level processing formats and in-situ metrology integration, compressing the traditional separation between front-end precision and back-end throughput paradigms.
Hybrid bonding is electrifying sub-10 micrometer interconnect scaling for 3D memory and logic stacking. Samsung and SK Hynix are qualifying die-to-wafer bonders for HBM4 production ramps. This technology is electrifying capital intensity in the bonding equipment segment as thermocompression tools displace traditional flip chip methods.
REACH substance restrictions are compelling lead-free solder material transitions across European packaging facilities. ECHA authorization requirements for novel interconnect chemistries are extending process qualification timelines. Automotive module suppliers in Germany are accelerating non-conductive paste adoption to preempt regulatory non-compliance.
Consolidated procurement through OSAT-led equipment specification consortia is displacing individual IDM vendor selection. ASE Group and Amkor are issuing unified technical requirements for multi-vendor line integration. This pattern concentrates most visibly in Taiwan's Hsinchu corridor where packaging capacity expansion is coordinated through industry association frameworks.
Global Semiconductor Packaging and Assembly Equipment Market Segmentation
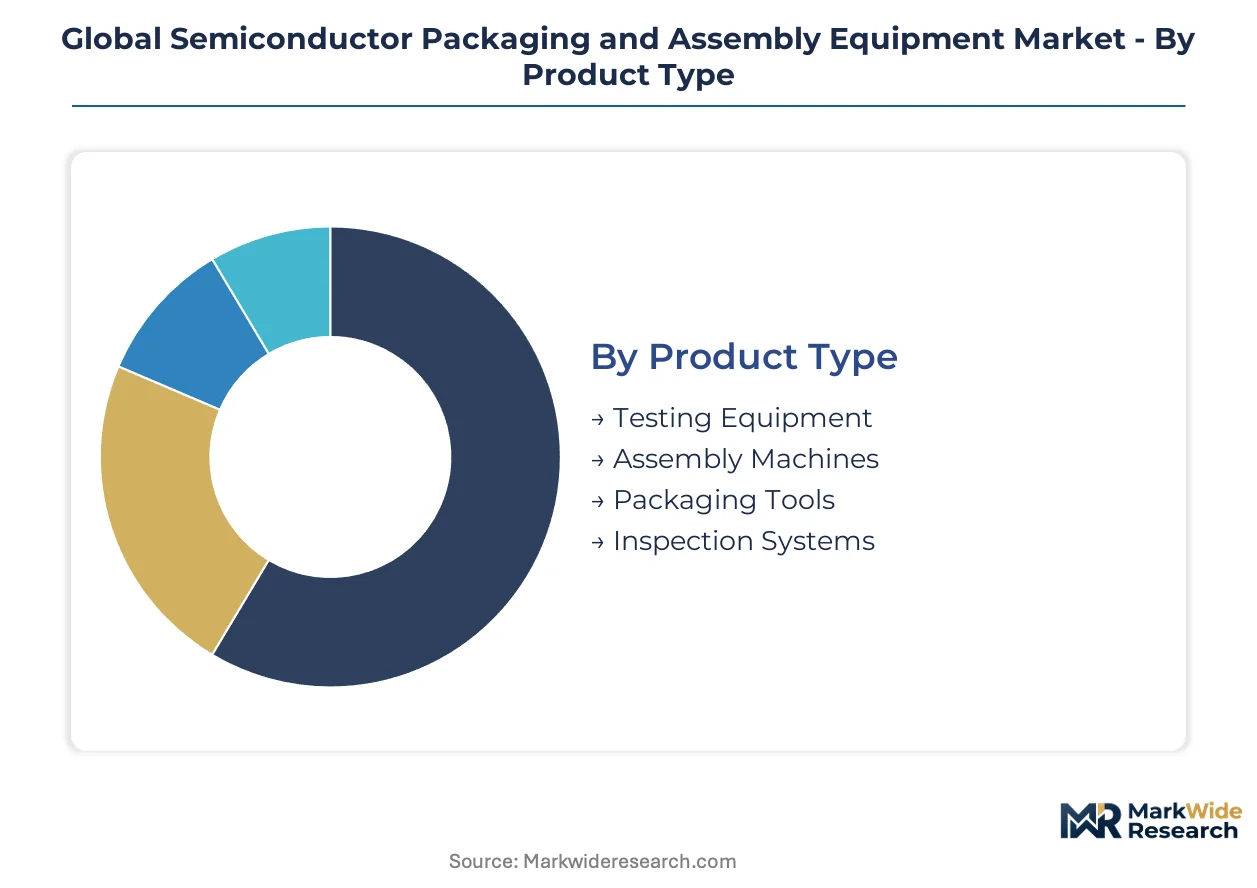
Equipment segmentation in semiconductor packaging reveals how capital allocation splits between precision-critical testing systems and high-throughput assembly machinery. Technology choices increasingly determine factory layout as heterogeneous integration reconfigures traditional back-end workflows.
Product Type:
Supply concentration in deposition and lithography-adjacent tools elevates certain equipment categories above others in procurement priority lists.
- Testing Equipment:Systems performing electrical, thermal, and optical validation at micron-scale precision. Demand concentrates in Taiwan's Hsinchu corridor where ASE Group and Amkor are expanding heterogeneous integration lines; defect detection complexity multiplies with chiplet architectures.
- Assembly Machines:Die attach, wire bonding, and flip chip placement systems operating at throughput rates exceeding 20,000 units per hour. Automotive module production in Germany's Saxony cluster is pulling thermocompression bonders for ISO 26262-qualified power electronics.
- Packaging Tools:Encapsulation, molding, and singulation equipment for final component formation. Japan's METI-subsidized consortia in Tsukuba are qualifying glass substrate handling systems.
- Inspection Systems:Automated optical and X-ray verification platforms for process control. South Korea's Yongin complex is deploying in-situ metrology for panel-level fan-out production.
Testing equipment absorbs the bulk of installed capacity; advanced packaging tools are expanding most quickly.
Technology:
Cost tier stratification separates legacy interconnect methods from premium bonding platforms commanding 3-4x capital intensity per unit throughput.
- Die Attach:Precision placement systems for bare die positioning with sub-micron accuracy. AI accelerator packaging in South Korea is driving die-to-wafer bonding throughput requirements upward.
- Wire Bonding:Thermosonic and ultrasonic interconnect systems using gold, copper, or aluminum wire. Automotive power modules in Germany maintain volume demand for ball and wedge bonding platforms.
- Flip Chip:Solder bump and copper pillar interconnect technologies for high-I/O density applications. Data center processors are displacing wire bonding in high-performance compute packaging.
- Advanced Packaging:Fan-out wafer-level, fan-out panel-level, and 2.5D/3D integration platforms. Taiwan's OSAT consortium specifications are standardizing multi-vendor line integration for these technologies.
Wire bonding retains the largest installed base; hybrid bonding within advanced packaging is climbing the fastest.
End User:
Application-driven specifications fragment equipment requirements across reliability grades and throughput mandates.
- Consumer Electronics:High-volume packaging for smartphones, wearables, and personal computing devices. Cost sensitivity in this segment perpetuates wire bonding dominance for mid-range applications.
- Automotive:Functional safety-critical modules for power electronics and sensor systems. ISO 26262 certification requirements in Germany are expanding demand for automotive-grade assembly equipment.
- Telecommunications:Baseband processors, RF modules, and optical transceivers for network infrastructure. Co-packaged optical I/O development is creating hybrid bonding demand in this segment.
- Industrial:Motor drives, power supplies, and automation controllers with extended temperature ranges. Proven reliability standards here sustain older packaging technology adoption.
Consumer electronics commands the greatest equipment installed base; automotive applications are gaining share fastest.
Deployment:
Maturity gradients separate established on-premise factory models from emerging cloud-connected equipment architectures.
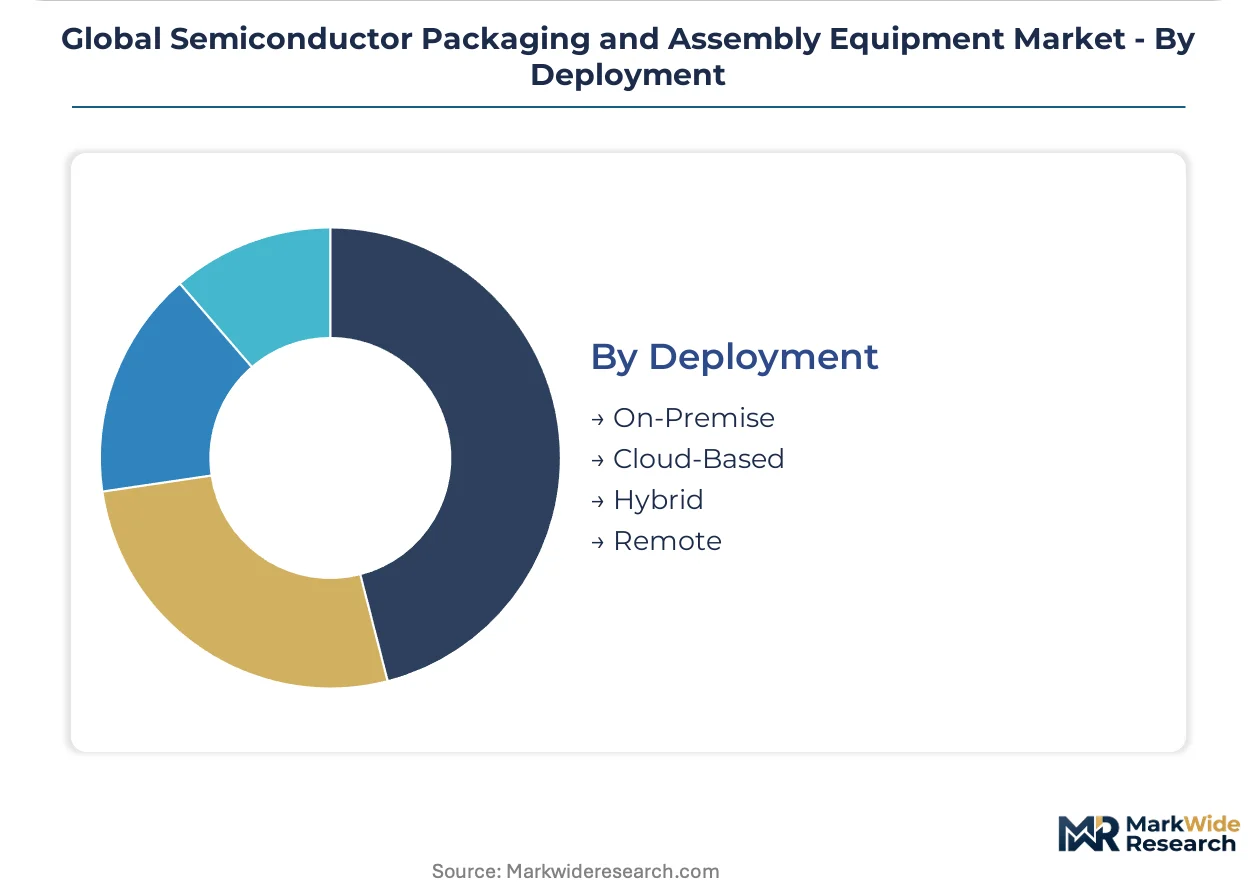
- On-Premise:Traditional capital equipment installation within fabrication and OSAT facilities. Taiwan and South Korea's packaging clusters operate predominantly on this model.
- Cloud-Based:Remote equipment monitoring, predictive maintenance, and process optimization via centralized data platforms. Japan's METI consortia are piloting these architectures.
- Hybrid:Local process control with cloud-based analytics and vendor remote support. Germany's greenfield packaging lines are specifying this deployment mode.
- Remote:Fully vendor-managed equipment operation with customer oversight. This model remains nascent in semiconductor packaging due to IP sensitivity.
On-premise deployment holds the overwhelming majority of installed systems; hybrid configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates in three fabrication clusters where capital expenditure cycles now diverge under competing subsidy regimes. Taiwan and South Korea anchor advanced packaging capacity expansion. China's domestic equipment substitution accelerates under technology access constraints.
Taiwan
Heterogeneous integration lines at ASE Group and Amkor are commissioning die-to-wafer bonders for AI accelerator packaging. The National Development Council coordinates capacity expansion through Hsinchu Science Park infrastructure subsidies. Kaohsiung's emerging packaging corridor is attracting thermocompression equipment for panel-level fan-out production.
South Korea
SK Hynix and Samsung are qualifying hybrid bonding tools for HBM4 memory stacking ramps. The K-Chips Act directs fiscal support toward Yongin semiconductor complex packaging R&D. Seoul's equipment specification consortia are standardizing multi-vendor line integration protocols for chiplet architectures.
China
Domestic OSATs are retrofitting wire bonding capacity for automotive power modules under import substitution mandates. MIIT localization targets for deposition and etch tools are compressing qualification timelines for indigenous suppliers. Shanghai's Zhangjiang Hi-Tech Park is consolidating advanced packaging equipment procurement for memory and logic devices.
Germany
Saxony's power electronics cluster is expanding thermocompression bonder installations for ISO 26262-qualified automotive modules. The EU Chips Act capital allocation is greenlighting Dresden-area packaging line construction with REACH-compliant process chemistries. Bavarian automotive tier-1 suppliers are qualifying second-source assembly equipment for silicon carbide power modules.
Japan
Tsukuba's METI-subsidized R&D consortia are accelerating glass substrate and embedded die technology qualification. Equipment vendors are collaborating with national research institutes on hybrid bonding process development. Kyushu's legacy packaging facilities are upgrading inspection systems for heterogeneous integration defect detection.
Global Semiconductor Packaging and Assembly Equipment Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue panel-level packaging and co-packaged optical integration niches. The vendor base stratifies across three tiers: diversified capital equipment conglomerates with deposition-to-test portfolios; bonding and assembly specialists with automotive-grade certification depth; and regional equipment fabricators serving cost-sensitive wire bonding replacement demand. Dominant competitive moves include strategic partnerships for multi-vendor line integration and geographic expansion through localized service footprints in subsidy-active jurisdictions.
Within the diversified conglomerate tier, Applied Materials and Lam Research Corporation exemplify capital intensity concentration across deposition, etch, and advanced packaging tool categories. ASM Pacific Technology anchors the bonding and assembly specialist archetype with Greater China market presence. Tokyo Electron Limited occupies a position bridging front-end precision and back-end throughput equipment architectures.
| Leading Market Players |
|---|
| ASM Pacific Technology |
| Applied Materials |
| Tokyo Electron Limited |
| Veeco Instruments |
| Besi |
| Kulicke & Soffa Industries |
| Disco Corporation |
| Lam Research Corporation |
| SUSS MicroTec |
| Others |
Supply Flow & Price Mechanics
REACH substance restrictions in Europe gate qualified supply for deposition and bonding tools while segmenting pricing tiers between legacy wire bonding and advanced hybrid bonding platforms. Buyers seeking ISO 26262-certified automotive-grade equipment face extended qualification timelines that compress margin pools for vendors unable to demonstrate compliance documentation.
Pricing Analysis
Volume-margin splits separate high-throughput wire bonding systems from premium hybrid bonding platforms commanding elevated capital intensity per unit throughput. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with automotive module suppliers in Germany exhibiting lowest price sensitivity due to functional safety mandates. Cost compression in standard-tier die attach equipment is intensifying because OSAT procurement consortia are consolidating vendor specifications. Consumer electronics packaging lines in Taiwan demonstrate highest price sensitivity, perpetuating wire bonding dominance for mid-range smartphone applications.
Supply Chain Analysis
Dual-sourcing requirements from ASE Group and Amkor mandate multi-supplier qualification for thermocompression bonders and inspection systems across Taiwan, South Korea, and Japan. Equipment fabrication draws from precision motion control components in Germany, laser systems in the United States, and ceramic structural elements from Japanese suppliers. Single-source vulnerability concentrates in excimer laser annealing equipment dependent on Ukrainian-sourced neon gas. Distribution runs through direct vendor relationships with OSAT facilities and IDM captive packaging lines, with localized service footprints increasingly specified in subsidy-active jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as heterogeneous integration complexity forces sub-scale bonding specialists into acquisition targets or exit. Process engineer scarcity and multi-vendor integration failures are accelerating attrition among equipment vendors lacking deposition-to-test portfolios.
For Market Incumbents: Deepen backward integration into precision motion control subsystems to reduce exposure to German component supply constraints. Expand captive service footprints in India's Gujarat and Karnataka corridors ahead of PLI scheme capacity ramps. Defensive consolidation moves should prioritize acquiring inspection system specialists as defect detection complexity multiplies with chiplet architectures.
For New Entrants and Emerging Players: Photonics-electronics convergence tools for co-packaged optical I/O modules offer a technology-first wedge into data center interconnect demand. White-space targets concentrate in glass substrate handling systems for Japan's METI-subsidized Tsukuba consortia and panel-level fan-out equipment for Kaohsiung's emerging packaging corridor. Go-to-market positioning should emphasize collaboration frameworks with national research institutes to reduce customer acquisition costs.
For Investors and Strategic Acquirers: OSAT issuance of unified multi-vendor line integration specifications is the leading indicator that bonding equipment consolidation will accelerate within the next investment horizon. Acquisition targets should profile mid-cap assembly specialists with automotive-grade certification depth and established presence in Taiwan's Hsinchu corridor. Watch for hybrid bonding tool qualification announcements from SK Hynix and Samsung as inflection signals for HBM4 production ramps.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Vendor Line Integration Partnership | ASE Group and Amkor specifications are standardizing equipment interoperability requirements. |
| Automotive Certification Investment | ISO 26262 qualification opens German power electronics procurement to second-source vendors. |
| Hybrid Bonding Technology Licensing | Samsung and SK Hynix HBM4 ramps are electrifying sub-10 micrometer interconnect capital intensity. |
| Localized Service Footprint Expansion | India PLI scheme subsidies in Gujarat are attracting OSAT investment requiring on-site support. |
| Glass Substrate R&D Consortium | Japan METI Tsukuba funding accelerates embedded die technology qualification timelines. |
Methodological Framework
SEC 10-K filings, equipment vendor technical documentation, and national subsidy program disclosures formed the secondary backbone for this analysis. Primary interviews with OSAT procurement directors, IDM packaging engineers, and equipment vendor sales executives combined with secondary validation through trade flow data and fab construction announcements. Bottom-up capacity installation tracking and top-down capital expenditure triangulation anchored market sizing across the projection horizon.
Historical trendline analysis of equipment shipment patterns informed the analytical framework across the analysis window, with segmentation modeling across product type, technology node, end-user application, and deployment architecture. CAGRs were derived from regression analysis of capital intensity per wafer-start equivalent and technology transition velocity. Forecast inputs incorporated MIIT localization targets for Chinese domestic equipment substitution and EU Chips Act capital allocation schedules for greenfield packaging lines.
Several conditions sit outside the modeled scope, including bilateral technology transfer restriction modifications, noble gas supply disruption scenarios, and unanticipated metallurgy qualification failures for copper pillar alternatives. Deviation in US Commerce Department licensing enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Multichip Package Market
Semiconductor Packaging
Memory Packaging Market
Semiconductor Packaging
Microtube Box Market
Semiconductor Packaging
3D IC Packaging Market
Semiconductor Packaging
NOR-Based Multi-Chip Packages Market
Semiconductor Packaging
Semiconductor Wafer Tape Market
Semiconductor Packaging
Through Silicon via (TSV) Packaging Market
Semiconductor Packaging
Ceramic IC Packages Market
Semiconductor Packaging
Asia Pacific LED Packaging Market
Semiconductor Packaging
Semiconductor Solder Flux Market
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market
Semiconductor Packaging
Advanced Semiconductor Packaging Market
Semiconductor Packaging
Semiconductor and IC Packaging Materials Market
Semiconductor Packaging
ESD Stackable Boxes Market
Semiconductor Packaging
Global Semiconductor Seals Market
Semiconductor Packaging
Quad-Flat-No-Lead Packaging (QFN) Market